
 Global Embryo Incubator Market | 2026-2036
Global Embryo Incubator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Embryo Incubator Market Foresight
Remote diagnostics and predictive maintenance subscriptions is realigning how embryo incubator vendors monetize hardware placements. Vitrolife leverages its software-enabled service contracts to extend customer lifetime value across European fertility networks. Thermo Fisher Scientific anchors North American demand through integrated consumables and instrument bundles. Esco Medical competes in Asia-Pacific with localized calibration and field service capabilities.
An embryo incubator is a controlled-environment chamber maintaining temperature at 37°C, CO2 concentration at 5-6%, and humidity above 95% to support in vitro embryo development during assisted reproductive procedures. The device employs infrared gas sensors and heated-air jackets to prevent thermal fluctuation that compromises blastocyst viability. Time-lapse incubators with automated imaging now command premium positioning by enabling continuous morphokinetic assessment without culture disturbance. Multi-chamber designs dominate high-throughput fertility clinics where parallel patient cycles require isolated environmental control. Portable incubators for inter-laboratory embryo transport represent the fastest-expanding segment as cross-border reproductive care networks proliferate.
FDA 510(k) clearance pathways and EMA Medical Device Regulation classifications shape product development timelines and commercialization scope for manufacturers. ISO 13485 quality management and WHO laboratory standards further dictate design validation protocols for instruments deployed in human IVF applications. Stakeholders must monitor evolving reimbursement classifications for time-lapse monitoring as health technology assessment bodies in Germany, France, and the United Kingdom recalibrate coverage thresholds for add-on fertility services.
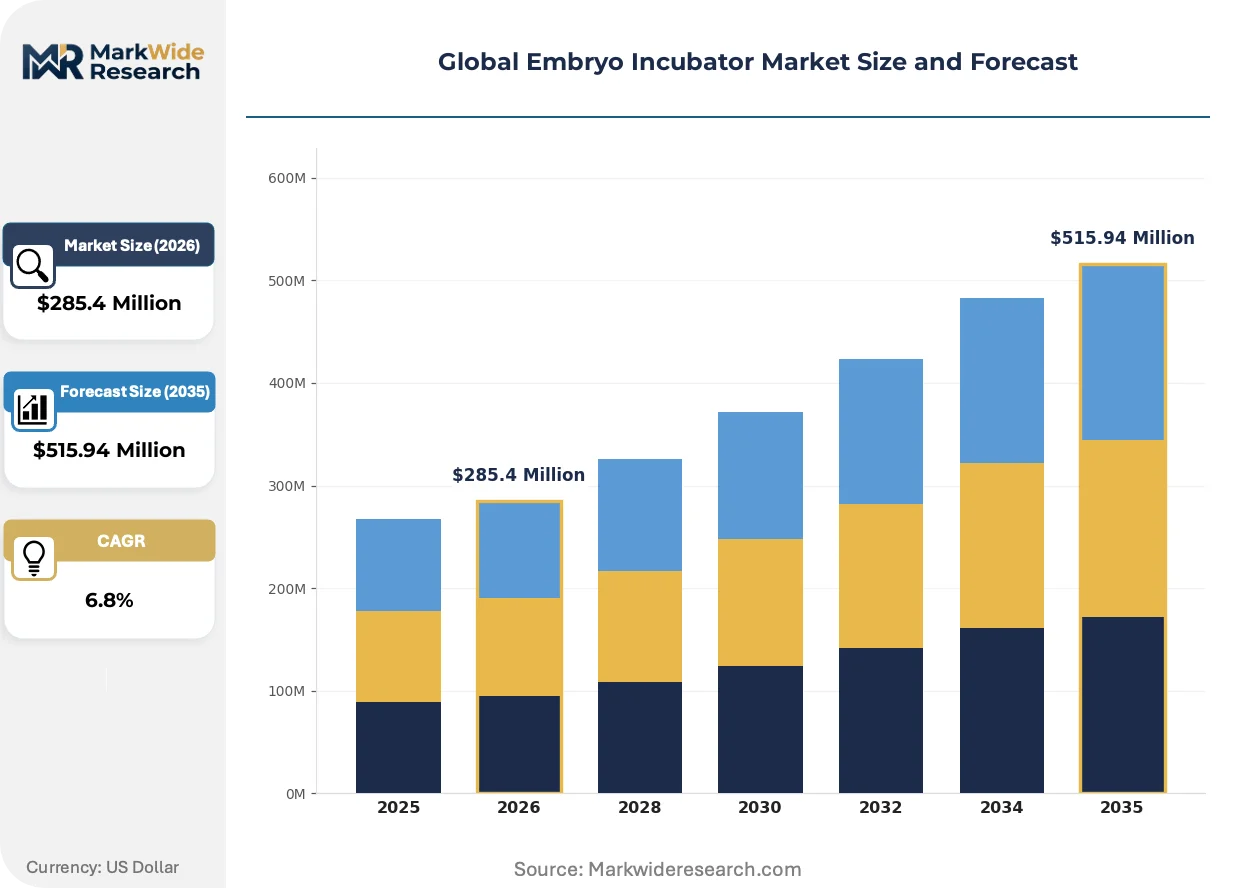
Market Dynamics
Time-lapse imaging modules with embedded AI morphokinetic scoring are compressing replacement cycles for conventional incubators across fertility networks. This hardware-software convergence forces capital planning shifts at clinics previously anchored to decade-long depreciation schedules.
Growth Catalysts
- EMA Medical Device Regulation harmonization:Streamlined CE marking pathways accelerate cross-border product registration, enabling faster rollout of multi-chamber systems in Spain, Italy, and Germany.
- Cross-border reproductive care networks:Portable incubators for inter-laboratory embryo transport unlock revenue streams from medical tourism corridors linking Czech Republic, Cyprus, and Greece.
- Time-lapse morphokinetic assessment:Automated continuous imaging eliminates manual embryo checks, reducing culture disturbance while generating proprietary datasets for viability algorithms.
Market Restraints
- Precision sensor supply concentration:Infrared CO2 sensor fabrication concentrates among German and Japanese component specialists, exposing lead-time vulnerability.
- ISO 13485 certification timeline:Design validation protocols for human IVF applications extend product development cycles by 18-24 months versus general laboratory equipment.
- Disposable culture media bundling:Integrated consumables contracts lock clinics into single-vendor ecosystems, raising switching costs and limiting price negotiation leverage.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives attract incubator assembly operations targeting cost-sensitive South Asian fertility centers.
- Remote diagnostics subscriptions:Predictive maintenance software layers transform one-time hardware sales into recurring revenue across European clinic networks.
- WHO laboratory standards adoption:Emerging-market fertility centers in Brazil and Mexico upgrade to internationally certified equipment to attract medical tourists.
Industry Challenges
- Embryologist training pipelines:Specialized expertise in time-lapse image interpretation and AI-assisted scoring lags behind installation rates at high-throughput clinics.
- Legacy incubator integration:Retrofitting existing culture rooms with networked monitoring systems requires HVAC reconfiguration and validation downtime.
- Health technology assessment divergence:Reimbursement bodies in France, Germany, and the United Kingdom apply inconsistent evidentiary thresholds for time-lapse monitoring add-ons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Embryo Incubator Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Incubators, Multi-chamber Incubators, Time-lapse Incubators, CO2 Incubators, Portable Incubators Technology: Optical Tracking, Microfluidics, Gas Regulation, Temperature Control, Automated Imaging Application: In Vitro Fertilization, Animal Breeding, Stem Cell Research, Genetic Testing, Cryopreservation End User: Fertility Clinics, Research Laboratories, Veterinary Hospitals, Academic Institutions, Biotechnology Firms |
| Companies Covered | Cook Medical, Merck KGaA, Esco Medical, The Baker Company, IVFtech ApS, Vitrolife, Thermo Fisher Scientific, PHC Corporation, Genea Biomedx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Embryo Incubator Market Shifts & Advancements
Embedded intelligence and connectivity layers are redefining how embryo incubators generate value beyond environmental control. Hardware vendors now compete on data architecture and algorithmic prediction capabilities rather than chamber specifications alone.
Gas-permeable culture dishes with integrated RFID tracking are overtaking standard petri dishes in premium clinic segments. These consumables enable automated chain-of-custody logging and eliminate manual embryo identification errors. High-throughput fertility centers in Denmark and the Netherlands now specify RFID-enabled workflows in procurement tenders, compressing demand for non-trackable alternatives.
EU Medical Device Regulation (MDR) Class IIa reclassification is elevating clinical evidence requirements for software-enabled incubators. Manufacturers must now submit post-market surveillance data and algorithm validation studies alongside technical documentation. German notified bodies have issued the first MDR certificates for time-lapse systems, establishing precedent that slower-moving competitors must match.
Subscription-based service unbundling is fragmenting traditional capital equipment sales. Fertility networks in the United Kingdom now lease incubator capacity with per-cycle pricing rather than purchasing outright, transferring obsolescence risk to vendors. This model compresses vendor cash conversion cycles while locking in long-term consumables commitments from clinic chains seeking balance-sheet flexibility.
Global Embryo Incubator Market Segmentation
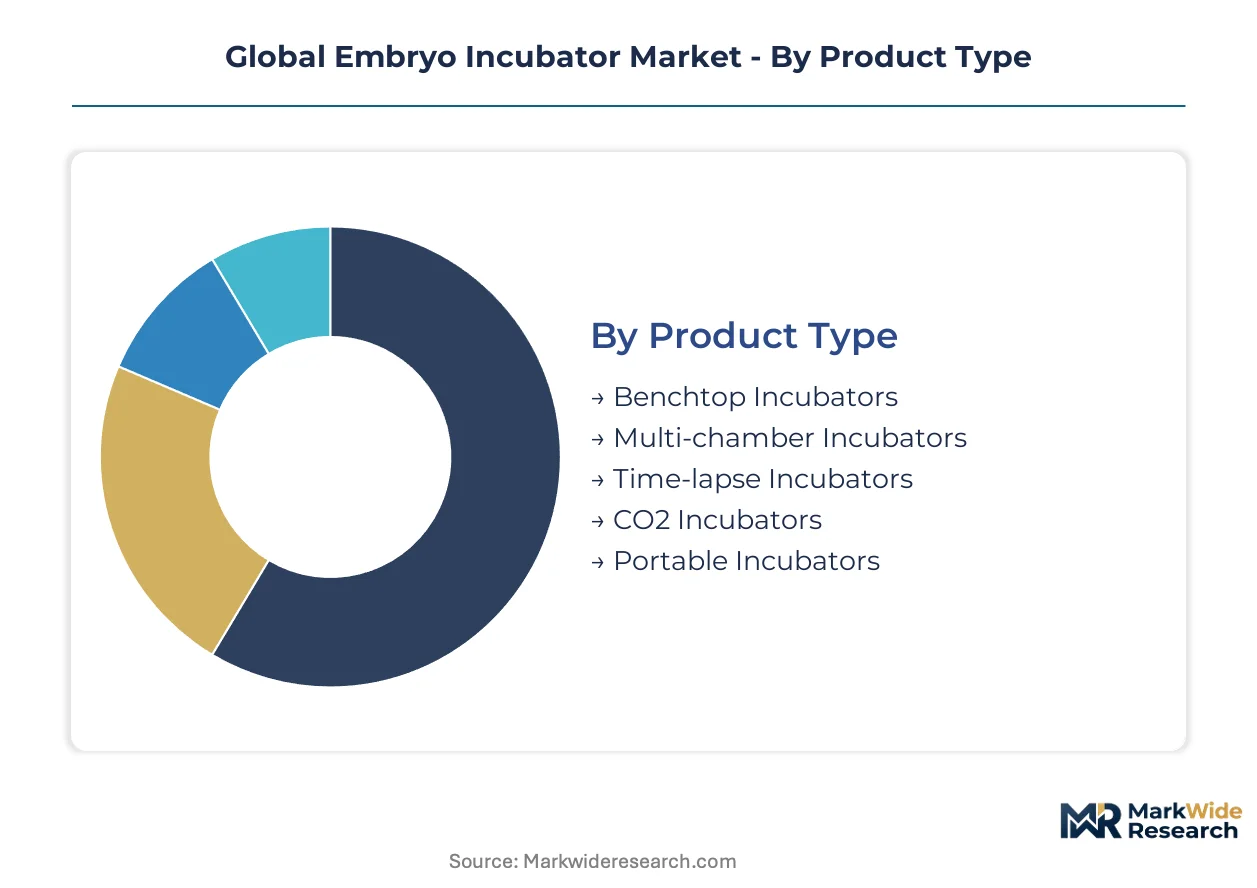
Embryo incubator purchasing decisions split across clinical throughput requirements, research precision demands, and portability constraints. Each segment carries distinct certification burdens and service attachment rates that reshape vendor profitability.
Product Type:
Customization intensity varies from standardized benchtop units to fully configured multi-chamber installations with integrated imaging stacks.
- Time-lapse Incubators:Continuous morphokinetic imaging chambers capture embryo development at 10-20 minute intervals without culture disturbance. Danish and Dutch fertility networks now specify these systems in procurement tenders, compressing demand for conventional alternatives as automated viability scoring reduces embryologist labor.
- Multi-chamber Incubators:Isolated environmental zones enable parallel patient cycles with independent CO2 and temperature regulation. High-throughput clinics in Spain and Germany favor these configurations under EMA Medical Device Regulation harmonization, though HVAC revalidation requirements extend installation timelines.
- Benchtop Incubators:Compact single-chamber designs serve low-volume laboratories with basic temperature and gas control.
- CO2 Incubators:Standard heated-air jacket systems dominate legacy installations requiring manual embryo checks.
- Portable Incubators:Battery-powered transport units maintain thermal stability during inter-laboratory embryo movement across Czech Republic-Cyprus-Greece medical tourism corridors.
Most installed capacity flows through Multi-chamber Incubators. Expansion is steepest in Time-lapse Incubators.
Technology:
Technology selection tracks the shift from passive environmental maintenance to active data generation and predictive intervention.
- Automated Imaging:Embedded camera arrays with AI-assisted morphokinetic scoring transform hardware into diagnostic platforms. German notified bodies have issued the first EU MDR Class IIa certificates for these software-enabled systems, establishing clinical evidence thresholds that slower competitors must match.
- Optical Tracking:Non-invasive time-lapse microscopy eliminates manual embryo identification errors while generating proprietary datasets for viability algorithms. Research laboratories in the Netherlands prioritize optical systems for stem cell lineage tracing applications.
- Gas Regulation:Infrared CO2 sensor arrays with automated calibration maintain 5-6% concentration stability.
- Temperature Control:Heated-air jacket and direct heat technologies prevent thermal fluctuation compromising blastocyst viability.
- Microfluidics:Chip-based culture environments enable precise media perfusion for research-grade embryo manipulation.
Automated Imaging commands the highest attach rates in new installations. Microfluidics is gaining share fastest in academic research contracts.
Application:
Application mix reflects divergent regulatory pathways between clinical human IVF and research or veterinary use cases.
- In Vitro Fertilization:Human reproductive applications demand ISO 13485 certification and WHO laboratory standard compliance for instruments deployed in clinical settings. Fertility clinics in Italy and Germany face tightening capacity constraints from aging demographics and expanded reimbursement coverage.
- Stem Cell Research:Embryonic stem cell derivation requires precise environmental control for undifferentiated lineage maintenance. Academic institutions in Denmark specify time-lapse monitoring for longitudinal developmental studies.
- Animal Breeding:Veterinary applications face lighter regulatory burdens but require species-specific temperature and gas calibration protocols.
- Genetic Testing:Preimplantation genetic screening applications prioritize rapid embryo biopsy access with minimal culture disturbance.
- Cryopreservation:Vitrification and warming protocols demand precise thermal ramping capabilities for embryo survival.
IVF applications absorb the majority of premium system placements. Stem Cell Research shows the steepest technology upgrade trajectory as funding concentrates in EU and North American centers.
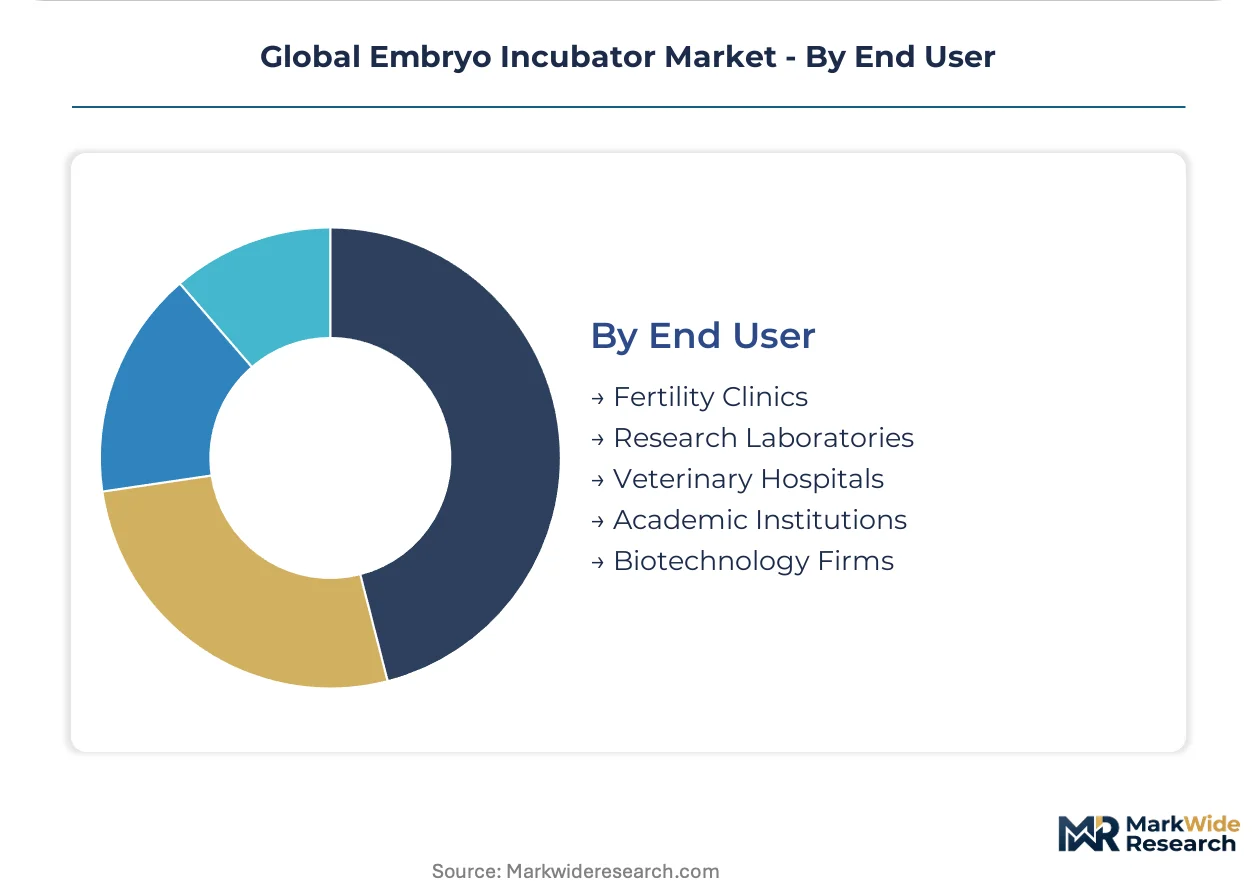
End User:
End user categories separate fee-for-service clinical operations from grant-funded research and agricultural breeding programs.
- Fertility Clinics:Specialized reproductive centers purchase integrated instrument-consumable bundles under long-term service contracts. UK clinic chains now lease incubator capacity with per-cycle pricing rather than capital purchase, transferring obsolescence risk to vendors.
- Biotechnology Firms:Cell therapy developers require GMP-compliant incubation systems for regulatory submission batches. These users prioritize audit trails and batch documentation over throughput metrics.
- Research Laboratories:Academic centers balance specification flexibility against budget constraints, often accepting longer validation timelines.
- Veterinary Hospitals:Equine and livestock breeding operations demand ruggedized field-portable units for on-farm embryo collection.
- Academic Institutions:University-based programs emphasize multi-user access protocols and training curriculum integration.
Fertility Clinics represent the dominant revenue concentration. Biotechnology Firms are expanding procurement fastest as cell therapy pipelines mature toward commercial manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys more time-lapse incubators per fertility clinic than Spain, yet Spanish centers report steeper installation growth curves under streamlined EMA Medical Device Regulation pathways.
United States
FDA 510(k) clearance pathways shape product development timelines for manufacturers targeting the largest IVF market outside Europe. Reimbursement fragmentation across state Medicaid programs and private insurers creates uneven access to time-lapse monitoring add-ons. Boston and San Francisco research clusters drive demand for multi-chamber systems with integrated stem cell research capabilities.
Germany
Aging demographics and expanded statutory health insurance coverage for IVF cycles tighten capacity at specialized reproductive centers in Berlin and Munich. EMA Medical Device Regulation harmonization accelerates CE marking for multi-chamber systems, though HVAC revalidation requirements extend installation timelines. German notified bodies issued the first MDR Class IIa certificates for software-enabled incubators.
Spain
Medical tourism corridors from Northern Europe funnel patients to Barcelona and Madrid fertility networks, driving portable incubator demand for inter-laboratory embryo transport. EMA directives enable faster cross-border product registration than legacy national pathways. Spanish clinics lead Southern Europe in time-lapse morphokinetic assessment adoption.
India
PLI scheme incentives for medical device manufacturing attract incubator assembly operations targeting cost-sensitive South Asian fertility centers. CDSCO regulatory pathways remain fragmented across state-level import licensing. Mumbai and Delhi-NCR fertility networks upgrade from basic CO2 incubators to time-lapse systems as private equity consolidates clinic chains.
Denmark
Public healthcare procurement tenders now specify RFID-enabled workflows and automated imaging capabilities, compressing demand for non-trackable alternatives. Copenhagen and Aarhus academic medical centers integrate time-lapse systems into longitudinal embryonic stem cell research programs. Danish fertility networks operate at higher cycle volumes per embryologist than European peers.
Global Embryo Incubator Market Competitive Landscape
Top-tier vendors anchor premium-tier positioning through software-enabled service contracts, while mid-tier specialists compete on localized field service and calibration capabilities. The vendor base stratifies across integrated life science conglomerates, dedicated reproductive technology specialists, and regional fabrication houses. Three archetypes dominate: instrument-consumable bundlers, predictive maintenance platform operators, and portable transport unit specialists. M&A activity concentrates on AI morphokinetic scoring acquisitions, while geographic expansion targets India's PLI scheme zones and Middle Eastern medical tourism hubs.
Within the integrated conglomerate tier, Thermo Fisher Scientific and Merck KGaA exemplify instrument-consumable bundling strategies that lock clinic networks into long-term ecosystems. Among dedicated reproductive technology specialists, Vitrolife and Esco Medical occupy positions shaped by software service attachment rates and regional field service density. Cook Medical represents the mid-tier archetype where FDA clearance expertise and gynecological device cross-selling anchor market presence.
| Leading Market Players |
|---|
| Cook Medical |
| Merck KGaA |
| Esco Medical |
| The Baker Company |
| IVFtech ApS |
| Vitrolife |
| Thermo Fisher Scientific |
| PHC Corporation |
| Genea Biomedx |
| Others |
Supply & Pricing Matrix
Time-lapse imaging module integration is simultaneously elevating R&D amortization burdens and concentrating procurement leverage among German and Japanese sensor specialists. This hardware-software convergence forces manufacturers to absorb upstream component volatility while clinics demand predictable per-cycle economics.
Pricing Analysis
Capacity additions in India under the PLI scheme are reshaping price floors for benchtop and mid-tier systems across South Asian fertility networks. Three-tier pricing structure across premium, standard, and economy levels separates time-lapse AI-enabled platforms from multi-chamber conventional units and basic CO2 incubators. Price differentiation rests on ISO 13485 certification tier and embedded service contract duration. Cost compression in standard-tier hardware is intensifying because Indian assembly operations displace European fabrication for cost-sensitive clinic chains. Public healthcare procurement in Denmark and the Netherlands demonstrates lowest price sensitivity; standalone fertility clinics in emerging markets exhibit highest.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese infrared CO2 sensor fabrication, where two component specialists anchor global production. Assembly operations concentrate in Germany, the United States, and Singapore for finished systems; plastic consumables mold in China and Malaysia. Raw material dependencies span medical-grade stainless steel, precision optical glass, and platinum temperature sensors. Tariff exposure on Chinese-sourced electronics assemblies threatens margin stability for vendors with limited regional sourcing diversification. Distribution runs through direct sales teams for premium systems and specialized medical device distributors for mid-tier configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded software service layers are expanding addressable margin per installation as clinics shift from capital purchase to subscription models. This recurring revenue transition rewards vendors with validated predictive maintenance algorithms and consumables bundling depth.
For Market Incumbents: Hedge against AI scoring commoditization by deepening captive supply of RFID-enabled culture dishes and gas-permeable consumables. Lock clinic networks into decade-long service contracts with hardware refresh guarantees. Prioritize M&A targeting morphokinetic algorithm specialists before German notified bodies elevate MDR Class IIa evidence thresholds further. For New Entrants and Emerging Players: Direct-to-fertility-clinic digital sales channels bypass entrenched distributor relationships that Thermo Fisher Scientific and Merck KGaA anchor. Target portable incubator demand along Czech Republic-Cyprus-Greece medical tourism corridors where inter-laboratory transport infrastructure remains underdeveloped. Lead with calibration-as-a-service offerings that offset capital purchase barriers for mid-tier clinic chains. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier specialists with FDA 510(k) clearance expertise but limited software service attachment. Five-to-ten year viability favors vendors with demonstrated algorithm validation studies and post-market surveillance infrastructure under EU MDR. Monitor German health technology assessment body rulings on time-lapse monitoring reimbursement as the critical inflection signal for premium-tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Pathway | German notified body precedent establishes clinical evidence thresholds competitors must match for software-enabled systems. |
| Remote Diagnostics Platform Development | Predictive maintenance subscriptions transform hardware sales into recurring revenue across European clinic networks. |
| RFID-Enabled Consumables Integration | Gas-permeable culture dishes with automated chain-of-custody logging eliminate manual embryo identification errors. |
| Per-Cycle Leasing Model Deployment | UK clinic chains transfer obsolescence risk to vendors while locking in long-term consumables commitments. |
| India PLI Scheme Manufacturing Footprint | Domestic assembly operations target cost-sensitive South Asian fertility centers with compressed delivery timelines. |
Research Methodology
Direct dialogue with fertility clinic directors, embryology laboratory heads, biomedical equipment procurement managers, and GPO contracts specialists grounded qualitative findings in operational reality. Secondary validation drew from FDA 510(k) clearances, EMA MDR submission databases, hospital procurement tender records, and WHO laboratory standards documentation. Bottom-up installation data across 12 countries triangulated against top-down vendor revenue segmentation.
Top-down macroeconomic drivers and bottom-up clinic capacity expansion plans converged across the analysis window. Segmentation dimensions modeled include product type, technology tier, application setting, and end-user category alongside regional regulatory cluster differentiation. CAGRs derived from installed base growth rates and average selling price trajectories. Forecast inputs incorporated IVF cycle volume projections and reimbursement policy evolution in Germany, France, and the United Kingdom.
The model assumes a particular technology adoption path; alternative pathways for AI-assisted morphokinetic scoring would alter the outlook if health technology assessment bodies reject evidentiary submissions. Forecasts reflect assumptions regarding EMA MDR implementation timelines and IVF reimbursement stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Blood Purification Equipment Market
Medical Equipment
Hospital Stretchers Market
Medical Equipment
Global Optometry Equipment Market
Medical Equipment
Global Latex Medical Gloves Market
Medical Equipment
Urodynamic Equipment and Consumables Market
Medical Equipment
Clinical Microscopes Market
Medical Equipment
Cryochambers Market
Medical Equipment
Tanning Units Market
Medical Equipment
Dialyzer Reprocessing Machines and Concentrates Market
Medical Equipment
Autopsy Saw Market
Medical Equipment
Medical X-Ray Generators Market
Medical Equipment
Automated Dialysis Concentrated Production Systems Market
Medical Equipment
Healthcare Simulators Market
Medical Equipment
Benchtop Platelet Agitator Market
Medical Equipment
Operating Table Market
Medical Equipment
Chile Radiotherapy Market