
 Global Latex Medical Gloves Market | 2026-2036
Global Latex Medical Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Global Latex Medical Gloves Market Foresight
Subscription-based inventory management and automated replenishment software is restructuring how hospitals procure latex medical gloves, shifting volume commitments from spot purchasing to multi-year service contracts. Top Glove Corporation Bhd leverages integrated dipping lines and captive natural rubber supply to sustain cost leadership across powder-free and sterile segments. Hartalega Holdings Berhad anchors its position through proprietary nitrile-latex hybrid technology, while Kossan Rubber Industries Bhd differentiates via specialized dental and veterinary glove portfolios with enhanced tactile sensitivity specifications.
Latex medical gloves are disposable hand protection devices manufactured from natural rubber latex through coagulant dipping processes, typically measuring 4-8 mil in thickness and designed to provide barrier protection against bloodborne pathogens and chemical exposure in clinical settings. Powder-free variants now dominate hospital procurement due to reduced Type I hypersensitivity reactions and alignment with Joint Commission patient safety standards. Surgical application segments command premium pricing through sterilization validation and extended cuff designs, while examination-grade volumes scale through diagnostic center networks and dental laboratory contracts. E-commerce distribution channels are capturing share from traditional medical distributors among smaller clinic accounts seeking transparent unit economics.
FDA enforcement of banned powdered glove rules and EMA Medical Device Regulation conformity assessments are elevating compliance costs for manufacturers without certified quality management systems. Malaysia's Department of Standards and ISO 13485 certification requirements shape export eligibility for glove producers serving OECD healthcare systems. Buyers must monitor evolving FDA guidance on latex protein labeling thresholds and EU Green Deal procurement criteria affecting single-use medical device sustainability scores.
Market Dynamics
Malaysian manufacturing corridors now control over 60% of global latex glove output, creating supply-side leverage that restructures procurement negotiations for North American and European hospital networks.
Growth Catalysts
- FDA Powdered Glove Ban:The 2017 prohibition on powdered surgeon's and patient examination gloves eliminated allergen-heavy inventory, forcing hospital systems toward powder-free alternatives and expanding addressable demand for compliant manufacturers.
- Post-Pandemic Infection Control Protocols:Surgical departments across hospital networks are expanding glove procurement programs to address standardized barrier protection mandates in operating theaters and emergency departments.
- Natural Rubber Latex Dipping Automation:Coagulant dipping line robotics are reducing defect rates in sterile surgical glove production while compressing batch cycle times for high-volume examination-grade output.
Market Restraints
- Natural Rubber Price Volatility:Latex concentrate input costs fluctuate with Malaysian Ringgit exchange rates and regional weather patterns affecting Hevea brasiliensis tapping schedules.
- Single-Source Geography Risk:Three Malaysian producers dominate sterile and powder-free capacity, creating concentration vulnerability for buyers dependent on Strait of Malacca shipping lanes.
- Nitrile Substitution Pressure:Synthetic nitrile alternatives are capturing share in examination-grade segments where tactile sensitivity requirements are less stringent than surgical applications.
Strategic Opportunities
- Vietnamese Manufacturing Expansion:Greenfield glove production facilities outside Malaysia's saturated industrial zones offer tariff diversification and proximity to ASEAN healthcare demand growth.
- Veterinary and Dental Specialty Gloves:Enhanced tactile sensitivity specifications for animal handling and orthodontic procedures command premium pricing above standard examination grades.
- EU Green Deal Procurement Criteria:Sustainability scoring mechanisms for single-use medical devices create first-mover advantage for manufacturers with certified carbon footprint reduction programs.
Industry Challenges
- ISO 13485 Certification Timelines:Medical device quality management system audits require 12-18 month validation cycles that delay market entry for new production facilities.
- Legacy ERP Integration with Automated Replenishment:Hospital procurement systems struggle to synchronize multi-year service contract data with real-time inventory management platforms.
- Skilled Dipping Line Technician Shortage:Coagulant chemistry expertise and thickness control specialization are scarce in emerging manufacturing geographies outside Malaysia.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Latex Medical Gloves Market |
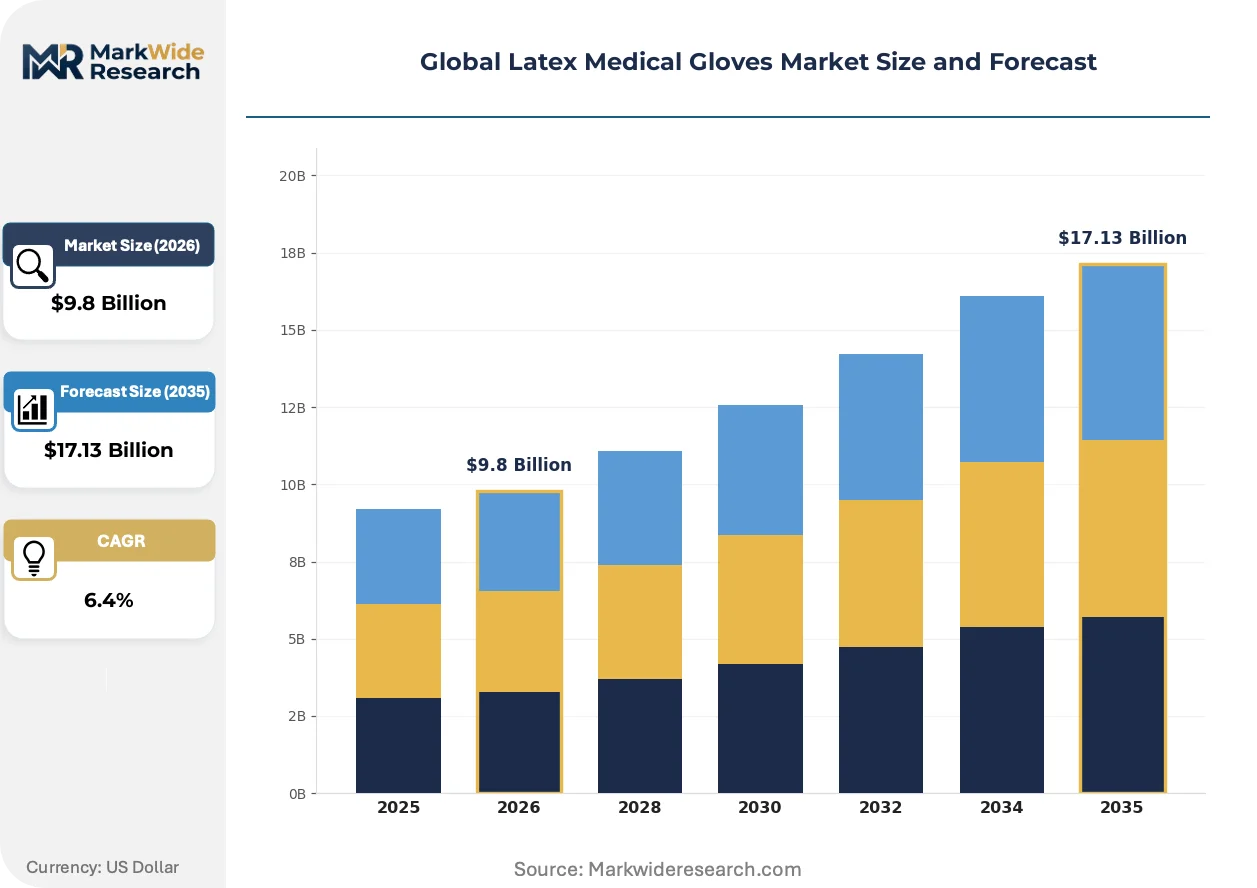
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered, Powder-Free, Sterile, Non-Sterile Application: Surgical Procedures, Diagnostic, Examination, Dental, Veterinary End User: Hospitals, Clinics, Diagnostic Centers, Dental Laboratories Distribution Channel: Hospital Pharmacies, E-Commerce, Medical Distributors, Retail Pharmacies |
| Companies Covered | Top Glove Corporation Bhd, Hartalega Holdings Berhad, Kossan Rubber Industries Bhd, Supermax Corporation Berhad, Ansell Ltd, Cardinal Health, McKesson Medical-Surgical Inc., B. Braun SE, Dynarex Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Latex Medical Gloves Market Shifts & Advancements
Material science breakthroughs and procurement platform digitization are converging to compress traditional distributor margins while elevating barrier performance specifications across clinical settings.
Chlorination surface treatment technology is rewriting the competitive hierarchy in powder-free latex segments. This chemical process eliminates residual surface proteins and reduces surface friction without cornstarch lubricants. Major hospital networks in Germany and the United States are specifying chlorinated surfaces for all surgical glove tenders. The technology is compressing price premiums between mid-tier and premium sterile grades.
EMA Medical Device Regulation conformity assessments are elevating compliance documentation burdens for non-EU manufacturers. The 2021 MDR transition requires updated clinical evaluation reports and post-market surveillance systems for all latex gloves entering EU distribution. Sterile surgical glove importers bear the heaviest audit burden, with notified body queue times extending certification cycles.
Subscription-based inventory management platforms are displacing spot purchasing among mid-sized clinic networks. These software systems aggregate consumption data across multiple facilities to automate replenishment triggers and consolidate volume commitments. The shift is most visible in United States ambulatory surgery centers seeking transparent unit economics without distributor markups.
Global Latex Medical Gloves Market Segmentation
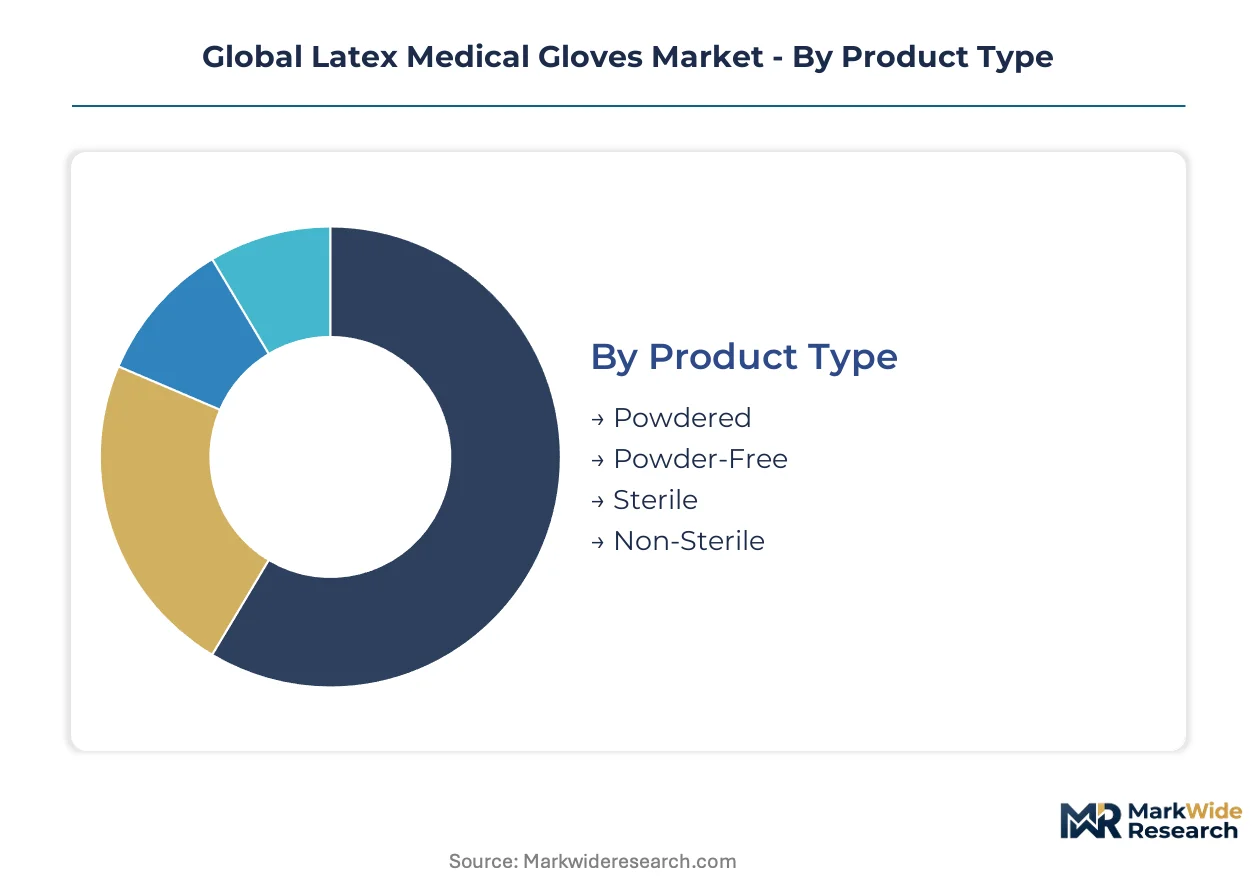
Latex medical gloves serve heterogeneous clinical environments with divergent performance specifications and procurement protocols. Segmentation reveals how powder-free formulations and surgical-grade sterilization create tiered value pools that manufacturers exploit through differentiated production assets.
Product Type:
Customization intensity varies sharply across this category, from commodity examination grades to validated sterile surgical lines requiring dedicated dipping corridors and gamma irradiation capacity.
- Powdered:Cornstarch-lubricated surfaces historically dominated high-throughput examination applications. FDA's 2017 prohibition eliminated this segment from US hospital procurement, relegating residual demand to veterinary and industrial markets outside OECD regulatory jurisdictions.
- Powder-Free:Chlorinated or polymer-coated surfaces eliminate Type I hypersensitivity risks while maintaining donning efficiency. German hospital networks and US academic medical centers specify these formulations exclusively, compressing price premiums through volume standardization.
- Sterile:Individual packaging with gamma irradiation or ethylene oxide validation supports operating theater protocols. Extended cuff designs and anatomical curvature specifications command dedicated production lines with ISO 13485-certified quality systems.
- Non-Sterile:Bulk-packaged examination grades serve diagnostic phlebotomy and general patient contact where aseptic field maintenance is unnecessary.
Most installed capacity flows through powder-free lines. Expansion is steepest in sterile surgical segments as hospital networks consolidate supplier relationships around full-procedure coverage.
Application:
Volume scale inversely correlates with performance stringency across clinical use cases, creating margin stratification that rewards specialized manufacturing competence.
- Surgical Procedures:Sterile latex gloves with thickness tolerances of 4-8 mil and textured fingertip surfaces enable precision instrument handling in operating theaters. FDA 510(k) clearance and extended cuff barriers against fluid exposure support premium positioning in cardiac and orthopedic surgery suites.
- Diagnostic:High-frequency phlebotomy and specimen collection drive consumption velocity in laboratory networks. Powder-free chlorinated surfaces reduce latex protein transfer during repetitive glove changes.
- Examination:General patient contact protocols in emergency departments and inpatient wards generate baseline volume demand with minimal specification differentiation.
- Dental:Enhanced tactile sensitivity specifications for periodontal probing and orthodontic wire manipulation command specialized cuff designs and reduced palm thickness profiles.
- Veterinary:Animal handling applications prioritize puncture resistance and extended gauntlet lengths for large-specimen procedures.
Diagnostic and examination applications absorb the highest unit volumes. Dental specialty lines are gaining share fastest as ambulatory oral surgery centers expand procurement autonomy.
End User:
Procurement sophistication separates institutional buyers with automated replenishment systems from smaller accounts dependent on distributor relationships.
- Hospitals:Integrated delivery networks negotiate multi-year service contracts with Malaysian manufacturers, leveraging consumption data analytics to compress unit costs across surgical and examination grades simultaneously.
- Clinics:Independent physician practices and urgent care facilities purchase through group purchasing organizations or direct e-commerce channels, prioritizing transparent pricing over technical specification depth.
- Diagnostic Centers:High-throughput phlebotomy and imaging facilities require rapid inventory turnover with just-in-time delivery commitments.
- Dental Laboratories:Specialized orthodontic and prosthetic manufacturing operations source enhanced tactile sensitivity grades for precision wax modeling and ceramic handling.
Hospital networks concentrate procurement leverage. Clinic segment expansion is accelerating most quickly as retail health and telemedicine referral networks proliferate.
Distribution Channel:
Channel selection reflects buyer scale and technical support requirements, with digital platforms disrupting traditional medical distributor relationships among mid-sized accounts.
- Hospital Pharmacies:Captive supply chain operations within integrated delivery networks manage sterile inventory with lot tracking and expiration monitoring systems.
- E-Commerce:Direct manufacturer portals and medical supply marketplaces serve ambulatory surgery centers and independent clinics seeking price transparency without distributor markups.
- Medical Distributors:Cardinal Health and McKesson maintain field sales organizations for technical consultation on sterilization validation and regulatory compliance documentation.
- Retail Pharmacies:CVS and Walgreens capture consumer-directed demand for home healthcare and first-aid applications with limited clinical specification requirements.
Medical distributors retain sterile surgical volume. E-commerce channels are climbing the fastest as procurement digitization penetrates mid-tier clinic networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage drives production migration toward jurisdictions with lower compliance costs and established quality certification infrastructure. Malaysian manufacturers exploit ISO 13485 audit density and FDA pre-clearance history to maintain cost leadership against emerging competitors.
United States
Hospital procurement consolidation and ambulatory surgery center expansion sustain powder-free sterile demand. FDA enforcement of the 2017 powdered glove ban eliminated non-compliant inventory from distribution channels. Midwest integrated delivery networks in Illinois and Ohio negotiate multi-year service contracts with Malaysian suppliers.
Germany
EMA Medical Device Regulation conformity assessments elevate documentation burdens for sterile surgical glove importers. University hospital networks in Bavaria and North Rhine-Westphalia specify chlorinated powder-free surfaces exclusively. The country's national pharmaceutical regulator maintains strict post-market surveillance requirements for latex protein labeling.
Malaysia
Captive natural rubber supply and concentrated dipping line automation sustain sixty percent of global sterile capacity. The Department of Standards enforces export eligibility criteria aligned with OECD healthcare system procurement rules. Industrial corridors in Selangor and Perak host integrated manufacturing facilities serving North American and European buyers.
China
Domestic hospital network expansion and diagnostic center proliferation drive examination-grade consumption velocity. NMPA medical device registration requirements shape import substitution patterns for powder-free formulations. Yangtze River Delta manufacturing clusters are developing chlorination surface treatment capabilities for surgical-grade output.
Vietnam
Greenfield glove production facilities offer tariff diversification and proximity to ASEAN healthcare demand growth. The country's national standards body is aligning quality management certification with ISO 13485 requirements. Industrial zones near Ho Chi Minh City attract Malaysian capital seeking capacity expansion outside saturated Malaysian corridors.
Global Latex Medical Gloves Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with sterile surgical lines concentrating around quality-certified producers while examination grades fragment across price-competitive fabricators. Malaysian-incorporated entities with captive rubber supply anchor the premium tier through integrated dipping corridor control. Three strategic archetypes dominate: vertically integrated natural rubber processors, nitrile-latex hybrid technology specialists, and veterinary-dental niche specification developers. Competitive moves center on multi-year hospital service contract capture and Vietnamese manufacturing footprint expansion.
Within the Malaysian-anchored tier, Top Glove Corporation Bhd, Hartalega Holdings Berhad, and Kossan Rubber Industries Bhd exemplify distinct strategic positioning. Top Glove occupies a position representing scale-driven cost leadership through integrated supply chain control. Hartalega sits within the technology-differentiated segment through proprietary material science capabilities. Kossan exemplifies niche specialization targeting tactile-sensitive applications outside standard hospital procurement. These three entities collectively represent the production concentration that restructures buyer negotiation dynamics across developed market healthcare systems.
| Leading Market Players |
|---|
| Top Glove Corporation Bhd |
| Hartalega Holdings Berhad |
| Kossan Rubber Industries Bhd |
| Supermax Corporation Berhad |
| Ansell Ltd |
| Cardinal Health |
| McKesson Medical-Surgical Inc. |
| B. Braun SE |
| Dynarex Corp. |
| Others |
Supply & Pricing Matrix
Latex concentrate futures on the Malaysian Rubber Exchange anchor cost structures across sterile and examination-grade tiers, with Ringgit volatility cascading through coagulant dipping operations into three-tier pricing stratification that separates gamma-irradiated surgical lines from bulk-packaged diagnostic grades.
Pricing Analysis
Distributor margins compress as e-commerce platforms capture mid-sized clinic accounts seeking transparent unit economics. Subscription-based procurement contracts now dominate hospital network purchasing, with price differentiation driven by ISO 13485 certification tier and sterilization validation depth. Cost compression in examination-grade segments intensifies due to nitrile substitution pressure. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers with multi-year service contracts show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Malaysian concentrated dipping corridors in Selangor and Perak, where Top Glove, Hartalega, and Kossan control sixty percent of global sterile capacity. Raw material dependencies center on Hevea brasiliensis latex concentrate, chlorination chemicals, and gamma irradiation equipment. Tariff exposure runs through Strait of Malacca shipping lanes subject to regional trade policy shifts. Distribution runs through integrated delivery networks with automated replenishment systems, medical distributors with field sales organizations, and direct manufacturer portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The latex medical gloves market functions as a regulatory compounder, with FDA's 2017 powdered glove ban permanently eliminating non-compliant inventory and expanding addressable demand for powder-free alternatives across hospital procurement programs.
For Market Incumbents: Extend sterile surgical line capacity through Vietnamese greenfield facilities to diversify tariff exposure beyond Malaysian corridors. Deepen backward integration into captive natural rubber supply to defend margin position against latex price volatility. Prioritize chlorination surface treatment R&D to maintain technology differentiation as nitrile-latex hybrid formats mature. For New Entrants and Emerging Players: The price-point gap between premium sterile surgical grades and economy examination lines offers entry opportunity through specialized dental and veterinary portfolios with enhanced tactile sensitivity specifications. Target ASEAN diagnostic center networks with just-in-time delivery commitments and simplified regulatory pathways. Pursue direct e-commerce distribution to bypass entrenched medical distributor relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with Vietnamese manufacturing facilities holding ISO 13485 certification alignment and proximity to regional healthcare demand growth. Five-to-ten year viability favors producers with chlorination technology capabilities and hospital system contract anchoring. Watch FDA guidance evolution on latex protein labeling thresholds as inflection signal for compliance cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Vietnamese Manufacturing Expansion | Greenfield facilities in Ho Chi Minh City industrial zones diversify tariff exposure beyond Malaysian corridors. |
| Chlorination Technology Investment | Surface treatment capabilities eliminate residual proteins while meeting German hospital network tender specifications. |
| ISO 13485 Certification Acceleration | Quality management system validation compresses audit timelines for EU MDR conformity assessment entry. |
| Subscription Platform Development | Automated replenishment software captures ambulatory surgery center procurement digitization momentum. |
| Veterinary-Dental Portfolio Extension | Specialized tactile sensitivity grades command premium positioning outside commoditized examination segments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, GPO contracts specialists, biomedical engineers, and Malaysian dipping line operations directors with secondary validation against FDA 510(k) filings, EMA MDR submission databases, hospital procurement contract registries, and Malaysian Rubber Exchange price indices. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Segment-weighting approaches distributed value across powder-free, sterile, and non-sterile product tiers; surgical, diagnostic, examination, dental, and veterinary applications; and hospital, clinic, diagnostic center, and dental laboratory end users. CAGRs derived from elasticity-adjusted consumption models incorporating natural rubber price cycles and regulatory compliance cost trajectories. Forecast inputs included Malaysian Ringgit exchange rate assumptions and EU Green Deal procurement criteria adoption curves.
The model assumes a particular technology adoption path; alternative pathways for nitrile-latex hybrid formats would alter the outlook. Forecasts reflect assumptions on FDA enforcement continuity and EMA MDR audit queue durations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical Thawing Systems Market
Medical Equipment
Brazil Massage Equipment Market
Medical Equipment
Global Medical Lifting Slings Market
Medical Equipment
Terminal Sterilization Market
Medical Equipment
Global Steam Autoclaves Market
Medical Equipment
Defibrillator Analyzers Market
Medical Equipment
Global Surgical Table Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
Global Medical Equipment Cooling Market
Medical Equipment
US Radiotherapy Market
Medical Equipment
Medical Carts and Workstations Market
Medical Equipment
Chile Radiotherapy Market
Medical Equipment
Medical Device and Equipment Tags Market
Medical Equipment
Global Cardiopulmonary Stress Testing Systems Market
Medical Equipment
Spinal Surgery Tables Market
Medical Equipment
Electron Beam Linear Accelerators Market