
 Aircraft Control Surface Market | 2026-2036
Aircraft Control Surface Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Control Surface Market Analysis
Commercial aviation is decoupling from military procurement as the dominant demand pillar for control surface fabrication. Spirit AeroSystems sustains one of the largest independent aerostructures footprints in Wichita, Kansas, supplying major assemblies across Boeing platforms. Safran dominates European actuation and flight control systems through its specialized electromechanical portfolio. Airbus SE leverages its vertically integrated Hamburg and Toulouse facilities to control upstream supply of wing and empennage components.
Aircraft control surfaces are movable aerodynamic devices—ailerons, elevators, rudders, and flaps—typically manufactured from aluminum alloys or carbon-fiber-reinforced polymer composites, with hydraulic or electromechanical actuation systems enabling pitch, roll, and yaw authority. These surfaces must withstand cyclic loading exceeding 100,000 flight hours while maintaining precise deflection tolerances under extreme temperature and pressure differentials. Composite materials are capturing expanded share as airframers pursue weight reduction targets, though aluminum retains cost advantages in high-volume narrow-body programs. Electric actuation technology is displacing legacy hydraulic architectures in next-generation designs, redrawing supplier capability requirements and qualification barriers.
FAA Part 25 airworthiness standards and EASA CS-25 certification frameworks govern structural integrity, flutter margins, and damage tolerance for transport-category aircraft control surfaces, directly shaping R&D allocation and testing protocols. The EU Green Deal emissions trajectory and ICAO carbon offset requirements are pressing OEMs toward lighter, more efficient flight control architectures. Stakeholders must weigh composite qualification timelines against electric actuation reliability benchmarks as platform development cycles compress.
Market Dynamics
Electric actuation architectures are forcing a wholesale supplier base reconfiguration as hydraulic system incumbents face capability obsolescence and electromechanical specialists capture platform design wins on next-generation narrow-body programs.
Growth Catalysts
- FAA Part 25 flutter suppression mandates:Stricter airworthiness directives for damage tolerance and fatigue life are accelerating composite material adoption across transport-category flight control surfaces.
- Narrow-body fleet modernization:Airlines retiring aging aircraft are placing substantial orders for fuel-efficient single-aisle jets, concentrating demand for lightweight control surface assemblies.
- Electromechanical actuation:Power-by-wire systems are eliminating centralized hydraulic infrastructure, reducing weight and maintenance burden on new platform designs.
Market Restraints
- Carbon fiber prepreg cost volatility:Aerospace-grade composite raw material prices fluctuate with energy and acrylonitrile feedstock markets, compressing margin on fixed-price contracts.
- Supplier concentration in Wichita and Everett:Boeing-centric production clusters create geographic risk exposure for tier-two fabricators dependent on single-platform demand.
- Legacy hydraulic qualification inertia:Decades of in-service reliability data for centralized hydraulic architectures create certification pathway advantages that slow electric actuation penetration.
Strategic Opportunities
- EU Green Deal aviation emissions trajectory:Carbon-neutral flight mandates are creating preference for thermoplastic composites and additive manufacturing in control surface production.
- Urban air mobility platforms:Electric vertical takeoff aircraft require distributed flight control surfaces with ultra-lightweight electromechanical actuation at scale volumes.
- Aftermarket service unbundling:Airlines are separating control surface overhaul from OEM maintenance programs, opening independent MRO channel access for specialized repair stations.
Industry Challenges
- Electromechanical systems engineering talent scarcity:The convergence of aerospace mechanical design with power electronics expertise exceeds current workforce supply, elongating hiring cycles for qualified engineers.
- Dual certification pathway complexity:Simultaneous FAA and EASA qualification for new materials requires redundant testing protocols, extending program timelines and capital lockup.
- Legacy fleet hydraulic spares commitment:Long-tail support obligations for in-service aircraft constrain R&D reallocation toward electric architectures despite strategic priority.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Control Surface Market |
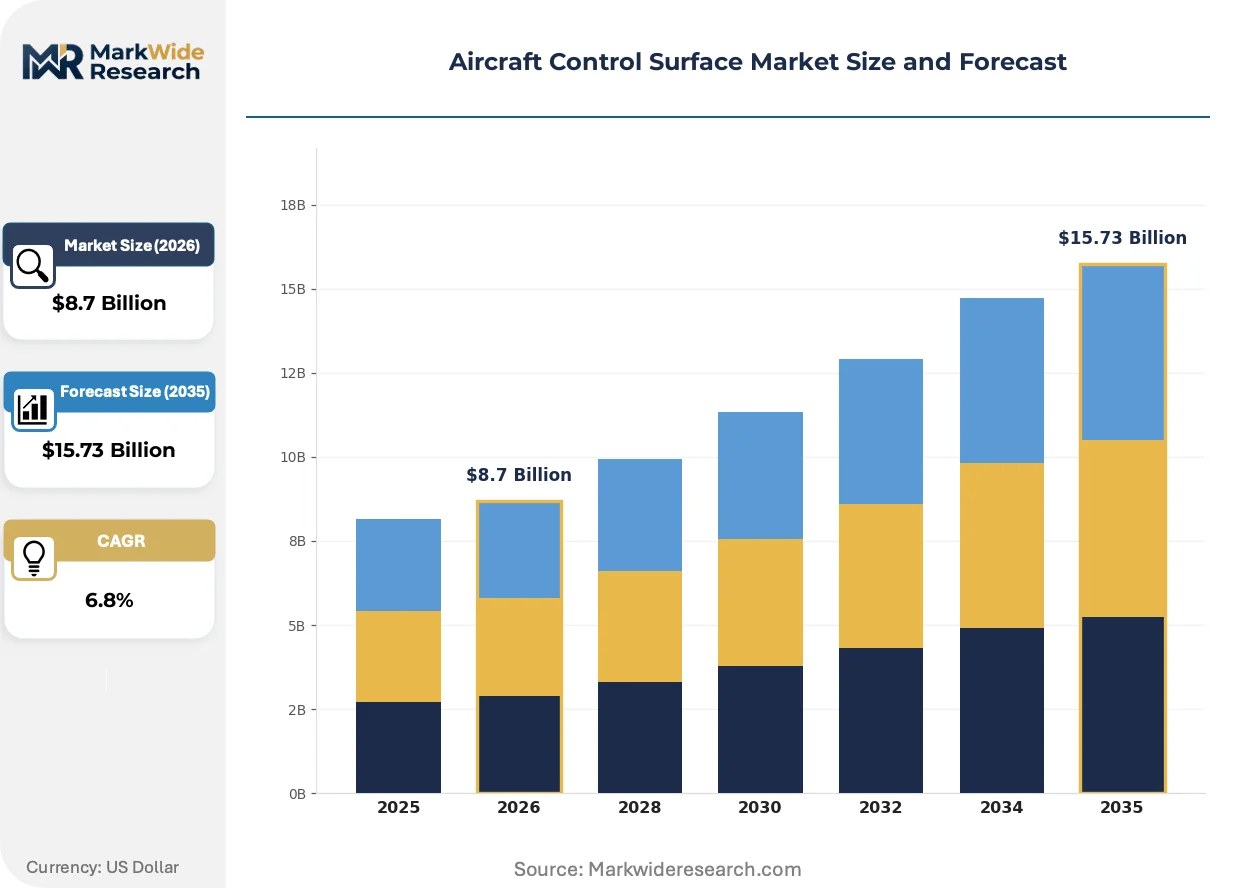
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Ailerons, Elevators, Rudders, Flaps Material: Aluminum, Composite, Steel, Titanium End User: Civil Aviation, Military Aviation, Commercial Aerospace, Private Aircraft Technology: Hydraulic Systems, Fly-by-Wire, Mechanical Linkages, Electric Actuation |
| Companies Covered | Triumph Group, Inc., Magellan Aerospace Corporation, Strata Manufacturing PJSC, The Boeing Company, Airbus SE, Spirit AeroSystems, Moog Inc., Safran, GKN Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Control Surface Market Emerging Trajectories
Flight control surface engineering is converging on three vectors: intelligent material systems, regulatory-driven sustainability mandates, and compressed procurement cycles that favor vertically integrated suppliers with captive composite and actuation capabilities.
Fly-by-wire distributed actuation is automating surface control authority through embedded electromechanical actuators replacing centralized hydraulic power distribution. Airbus and Boeing next-generation programs are specifying power-by-wire architectures for primary flight controls. This automation is compressing supplier qualification timelines as electromechanical capability becomes a gating factor for platform participation.
EASA CS-25 damage tolerance amendments and FAA harmonization efforts are tightening certification requirements for composite control surface repair and inspection protocols. Manufacturers must now demonstrate flaw growth characteristics under realistic environmental exposure rather than idealized laboratory conditions. European narrow-body programs are responding with thermoplastic resin systems enabling weldable repairs and reduced scrap rates.
Airline procurement organizations are consolidating supplier relationships through multi-platform frame agreements that bundle control surfaces with adjacent aerostructures. Long-term sole-source contracts are displacing competitive bidding on individual shipsets, concentrating volume with tier-one integrators. This concentration is most visible in United States carrier fleets where fleet commonality drives preference for Boeing-aligned supply chains.
Aircraft Control Surface Market Segmentation
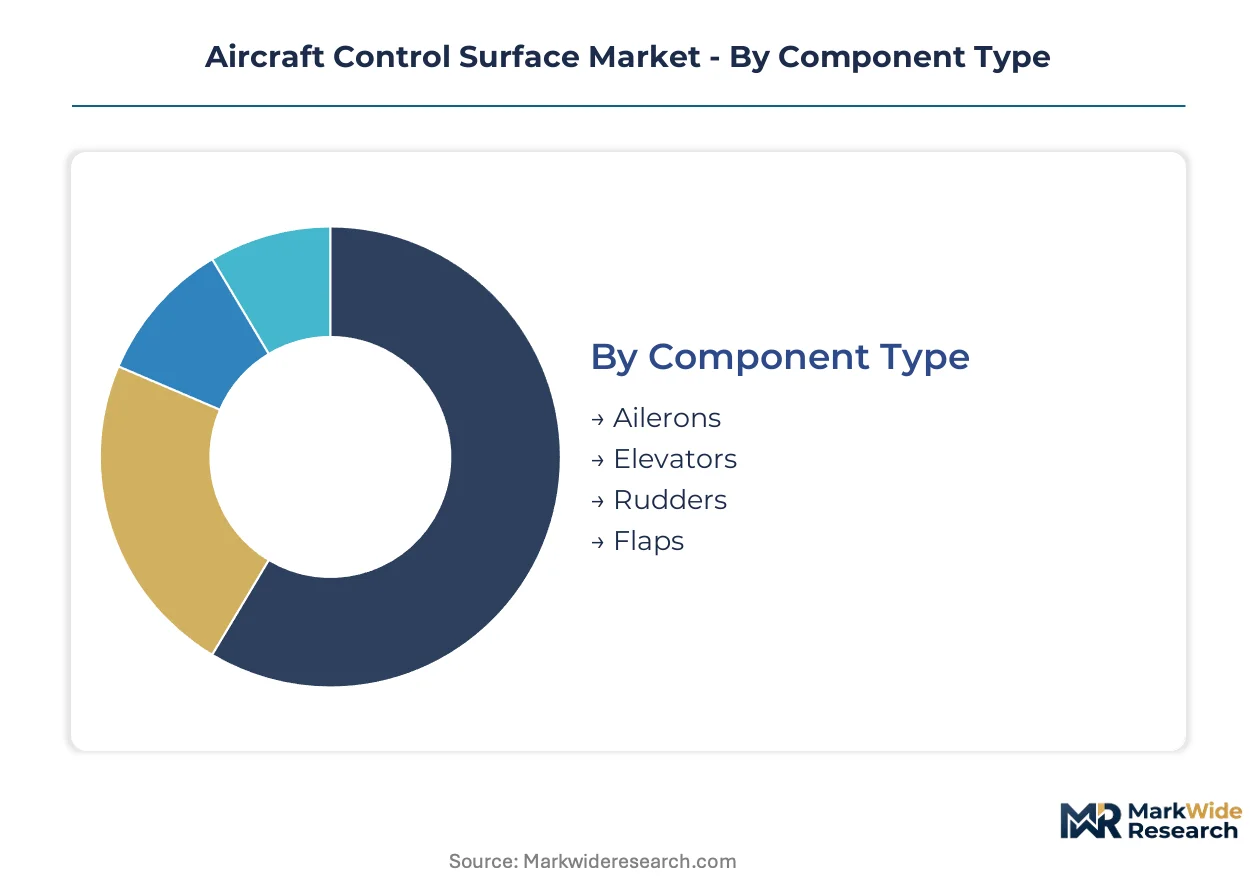
Control surface procurement patterns diverge sharply across material systems and actuation architectures, with supplier capability portfolios determining platform access. Segmentation reveals where engineering investment concentrates and which qualification pathways gate market participation.
Component Type:
Supply concentration clusters around primary flight control surfaces where failure modes demand redundant actuation and damage-tolerant design.
- Flaps:High-lift devices spanning inboard wing sections, typically constructed from aluminum ribs and skins with composite trailing edges. Demand concentrates on narrow-body programs in the United States as airlines prioritize fuel-efficient takeoff and landing performance. FAA Part 25 high-lift device certification timelines shape supplier selection.
- Ailerons:Outboard wing surfaces governing roll authority, increasingly fabricated from carbon-fiber-reinforced polymer to minimize control reversal under asymmetric loading. European OEM specifications favor electromechanical actuation integration, compressing qualification cycles for Wichita-based fabricators.
- Elevators:Pitch control surfaces on horizontal stabilizers, subject to highest aerodynamic loading and flutter margin requirements.
- Rudders:Vertical stabilizer surfaces providing yaw authority, with directional stability mandates driving oversized designs on twin-engine transports.
Today's leader: Flaps. Tomorrow's challenger: Ailerons.
Material:
Cost tier stratification separates legacy aluminum programs from composite platforms pursuing weight reduction targets.
- Composite:Carbon-fiber-reinforced polymer and thermoplastic resin systems enabling 15-20% weight savings over metallic alternatives. Commercial aerospace OEMs in France and Germany specify thermoplastic weldability for repair protocols under EASA CS-25 damage tolerance amendments. Acrylonitrile feedstock volatility constrains margin on fixed-price narrow-body contracts.
- Aluminum:7xxx-series alloys and lithium-aluminum compositions retaining cost advantages in high-volume production, with established supply chains from Kansas and Washington state fabricators. Military aviation procurement sustains demand where impact damage tolerance outweighs weight optimization.
- Titanium:High-strength corrosion-resistant alloys for hinge fittings and actuator attachment points in severe environments.
- Steel:Ultra-high-strength alloys for actuator housings and primary load paths requiring fatigue resistance.
Composite platforms command premium positioning. Aluminum retains volume dominance.
End User:
Customer type determines specification stringency and aftermarket service bundling.
- Commercial Aerospace:Airline and lessor procurement of transport-category aircraft, with fleet commonality driving sole-source frame agreements. United States carrier narrow-body modernization sustains demand concentration in Boeing-aligned supply chains. Power-by-wire specifications are displacing hydraulic architectures on next-generation platforms.
- Civil Aviation:General aviation and regional turboprop operators, with cost-sensitive procurement favoring mechanical linkages and aluminum construction. FAA Part 23 certification pathways enable faster market entry for new suppliers.
- Military Aviation:Defense procurement with stealth and survivability specifications, including radar-absorbing treatments and battle damage tolerance.
- Private Aircraft:Owner-flown and corporate aviation, with customization preferences fragmenting supplier relationships.
Commercial aerospace captures engineering priority. Military aviation sustains specialized capability.
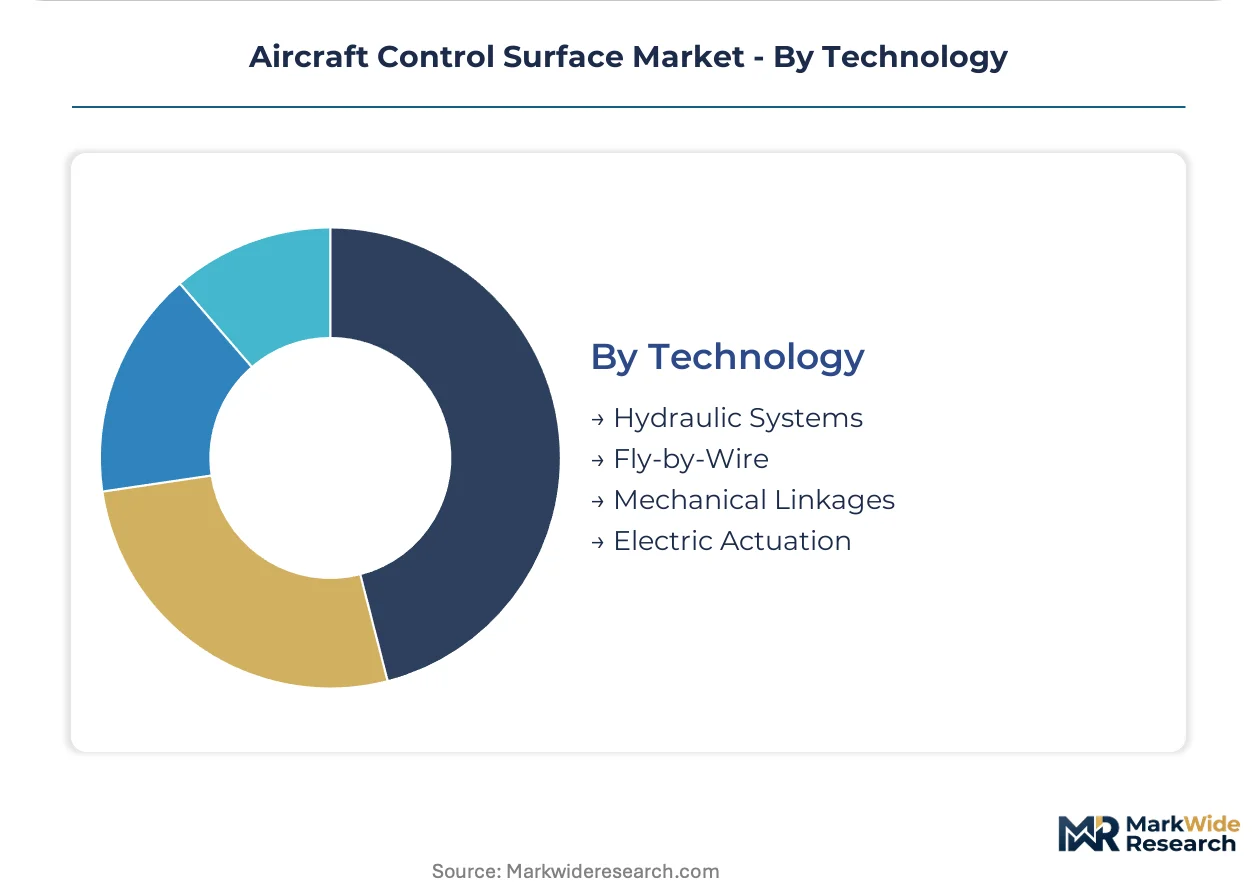
Technology:
Technology maturity curves separate qualified in-service architectures from developmental systems facing certification inertia.
- Electric Actuation:Distributed electromechanical actuators eliminating centralized hydraulic infrastructure, with power electronics integration demanding new supplier competencies. Airbus and Boeing next-generation programs specify these architectures for primary flight controls, redrawing tier-one qualification requirements.
- Fly-by-Wire:Digital flight control computers translating pilot inputs to surface commands, with triple-redundant channel architectures standard on transport-category aircraft. EASA and FAA harmonization efforts on software certification shape development timelines.
- Hydraulic Systems:Centralized 3000-5000 psi power distribution with decades of in-service reliability data, sustaining aftermarket spares commitments despite strategic displacement.
- Mechanical Linkages:Direct cable and pushrod connections for backup authority and general aviation cost structures.
Electric actuation is climbing the fastest. Hydraulic systems anchor installed base revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redistributing control surface fabrication toward jurisdictions with streamlined FAA-EASA dual-certification pathways and established aerospace labor pools, while cost-of-compliance gaps between mature and emerging production clusters shape supplier migration patterns.
United States
Boeing's narrow-body production surge drives demand concentration in Washington state and Kansas manufacturing corridors. FAA Part 25 airworthiness standards govern flutter suppression and damage tolerance protocols for all transport-category assemblies. Wichita-based fabricators anchor the country's largest independent aerostructures cluster, supplying major flight control assemblies across commercial platforms.
France
Airbus SE's vertically integrated Toulouse and Hamburg facilities control upstream supply of wing and empennage components for European narrow-body programs. EASA CS-25 certification frameworks mandate thermoplastic composite repair protocols under recent damage tolerance amendments. The country's southwestern aerospace belt concentrates electromechanical actuation engineering talent for next-generation power-by-wire architectures.
Germany
Premium-tier supplier engineering for composite primary structures sustains demand in Bavaria and Hamburg metropolitan production zones. EU Green Deal aviation emissions trajectories press OEMs toward lighter flight control architectures with reduced carbon intensity. Hamburg's aerospace corridor specializes in thermoplastic resin systems enabling weldable repairs and manufacturing scrap reduction.
United Kingdom
Heritage aerospace engineering capabilities in the Midlands and Southwest England sustain specialized flight control surface fabrication for military and commercial platforms. CAA alignment with EASA post-Brexit maintains certification pathway access for dual-qualified suppliers. Bristol and Broughton industrial clusters concentrate composite wing assembly expertise for transatlantic platform programs.
Japan
Composite materials research partnerships between METI-supported institutes and tier-one suppliers advance thermoplastic applications for next-generation regional aircraft. JIS standards harmonization with FAA-EASA protocols reduces requalification burden for export-oriented fabricators. Nagoya aerospace production complexes supply carbon-fiber-reinforced polymer assemblies to Boeing and Airbus extended supply chains.
Aircraft Control Surface Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with tier-one integrators capturing sole-source frame agreements while independent fabricators compete for shipset allocations on platform-specific programs. The supplier base concentrates around three strategic archetypes: vertically integrated OEMs with captive aerostructures divisions, independent tier-one aerostructures integrators with multi-platform qualifications, and specialized electromechanical actuation houses with power-by-wire capabilities. Dominant competitive moves include backward integration into composite prepreg manufacturing and strategic partnerships securing long-term sole-source positions on next-generation narrow-body development programs.
Among North American-based fabricators, Spirit AeroSystems represents the independent tier-one archetype with concentrated narrow-body exposure, while Triumph Group exemplifies diversified aerostructures capability spanning multiple OEM platforms. Moog Inc. occupies a specialized position within the electromechanical actuation tier, anchoring power-by-wire qualification pathways for flight control systems. European competition clusters around Safran and GKN Aerospace, with the former dominating actuation technology integration and the latter representing composite primary structures expertise. These named entities illustrate how supplier capability portfolios—rather than scale alone—determine platform access in an increasingly consolidated procurement environment.
| Leading Market Players |
|---|
| Triumph Group, Inc. |
| Magellan Aerospace Corporation |
| Strata Manufacturing PJSC |
| The Boeing Company |
| Airbus SE |
| Spirit AeroSystems |
| Moog Inc. |
| Safran |
| GKN Aerospace |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up aerostructures specialists have consolidated Wichita and Kansas fabrication assets, concentrating pricing power among tier-one integrators while compressing margin for component suppliers locked into long-term Boeing shipset agreements. This ownership pattern tightens supply discipline as portfolio companies prioritize EBITDA stability over market-share expansion, feeding cost pressure downstream to aluminum and composite raw material tiers.
Pricing Analysis
Direct-to-OEM contract structures dominate, with frame agreements bundling control surfaces across multiple platforms at volume-scaled unit economics. Price differentiation rests on EASA CS-25 certification tier and thermoplastic weldability credentials, with European-qualified suppliers commanding premiums over FAA-only qualified fabricators. Cost compression in aluminum-intensive narrow-body programs is intensifying because airlines prioritize fuel-efficiency ROI over premium composite specifications. Regional turboprop operators exhibit highest price sensitivity, while flagship carrier fleet procurement teams accept premium positioning for power-by-wire architectures.
Supply Chain Analysis
Refurbishment flows for in-service hydraulic actuators are extending component life cycles, delaying aftermarket revenue capture for electromechanical specialists while sustaining legacy spares demand. Manufacturing concentrates in the United States, France, and Germany, with carbon fiber prepreg, aerospace-grade aluminum, and electromechanical actuation systems as critical inputs. Single-source vulnerability around acrylonitrile feedstock exposes composite fabricators to energy market volatility. Distribution runs through OEM-integrated tier-one suppliers rather than independent channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Aircraft Control Surface Market compounds steadily as narrow-body fleet modernization sustains replacement demand across multi-decade aircraft life cycles.
For Market Incumbents: Deploy backward integration into carbon fiber prepreg manufacturing to defend margin against acrylonitrile cost volatility. Capture sole-source positions on next-generation electric actuation platforms before qualification windows close, as electromechanical engineering talent scarcity raises barriers for late entrants.
For New Entrants and Emerging Players: Tier-two MRO repair stations offer the most penetrable channel for aftermarket control surface overhaul, as airlines unbundle maintenance from OEM programs. Target FAA Part 23 certification pathways for general aviation mechanical linkages, where barrier-to-entry costs remain manageable and incumbent presence thins.
For Investors and Strategic Acquirers: Tier-one aerostructures integrators with multi-platform qualifications are the most active acquirer in this space, rolling up specialized composite fabricators and electromechanical actuation houses. Watch for electric vertical takeoff aircraft program announcements as inflection indicators for distributed flight control surface demand at scale volumes.
| Strategic Initiative | Industry Significance |
|---|---|
| Power-by-Wire Platform Qualification | Airbus and Boeing next-generation programs are specifying electromechanical architectures for primary flight controls. |
| Thermoplastic Composite Manufacturing Scale-Up | EASA CS-25 damage tolerance amendments favor weldable repair protocols that reduce scrap rates. |
| Aftermarket MRO Channel Development | Airlines separating control surface overhaul from OEM maintenance programs opens independent repair station access. |
| Electromechanical Engineering Talent Acquisition | Power electronics and aerospace mechanical design convergence exceeds current workforce supply. |
| Dual FAA-EASA Certification Investment | Simultaneous qualification for new materials requires redundant testing protocols that elongate program timelines. |
Methodological Framework
Direct dialogue with aerostructures procurement directors, flight control system engineers, MRO operations managers, and composite manufacturing executives grounded qualitative findings. Secondary validation drew from FAA airworthiness directive filings, EASA certification databases, Boeing and Airbus supplier disclosure documents, and aerospace trade customs records. Bottom-up platform demand modeling and top-down OEM production forecasts were triangulated to constrain estimate variance.
Segmented outputs across the projection horizon reflect component type, material system, actuation technology, and end-user category dimensions. CAGRs were derived from fitted growth curves against historical narrow-body delivery patterns and fleet replacement schedules. Forecast inputs incorporated power-by-wire adoption curves, thermoplastic qualification timelines, and airline fleet modernization capital deployment.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electric actuation reliability maturation and composite raw material cost trajectories. Practitioners should monitor EASA-FAA harmonization progress on software certification and urban air mobility platform development milestones for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Europe Commercial Aircraft Market
Aircraft
Aircraft Flight Control System Market
Aircraft
Europe Business Jet Market
Aircraft
Aircraft Cargo Winches Market
Aircraft
Aircraft Lavatory System Market
Aircraft
Aircraft Elevator Market
Aircraft
Tandem Rotor Helicopter Market
Aircraft
Fixed Wing Aircraft Rivets Market
Aircraft
Europe Helicopters Market
Aircraft
Aircraft Ailerons Market
Aircraft
Aircraft Landing Gear Market
Aircraft
Helicopter Lighting Market
Aircraft
Global Aircraft Design and Engineering Market
Aircraft
Anti Rolling Gyro (ARG) Market
Aircraft
Aircraft Windshield Wiper and Washer System Market
Aircraft
Aero Wing Market