
 Maritime Patrol Aircraft Market | 2026-2036
Maritime Patrol Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Maritime Patrol Aircraft Market Analysis
European airframe integrators is decoupling from legacy turboprop supply chains as next-generation maritime patrol programs demand jet-powered endurance and open-architecture mission systems. Boeing leverages its P-8 Poseidon production line to dominate NATO-aligned Pacific basing agreements. Leonardo S.p.A. sustains Atlantic corridor market share through deep specialization in sonobuoy-delivery platforms and undersea surveillance integration. Saab AB differentiates in the Nordic-Baltic theater with compact, ice-operable variants tailored to archipelago environments.
Maritime patrol aircraft are fixed-wing, rotary-wing, unmanned, or hybrid aerial platforms engineered for surface and subsurface surveillance, typically integrating radar, magnetic anomaly detection, electro-optical/infrared sensors, and acoustic processors to achieve mission endurance exceeding twelve hours over open ocean. Their primary purpose centers on exclusive economic zone enforcement, anti-submarine warfare, search-and-rescue coordination, and illegal trafficking interdiction. Fixed-wing platforms anchor current procurement volumes due to fuel efficiency and sensor payload capacity, while UAV segments represent the fastest-expanding structural category as operators seek reduced crew-risk profiles for persistent littoral monitoring. Extended-range operational configurations concentrate margin pools where signals intelligence suites and satellite communications backhaul command premium integration contracts.
The US Navy's NAVAIR certification standards, EASA's military derivative airworthiness protocols, and NATO's Allied Tactical Publication interoperability mandates collectively shape airframe eligibility and sensor integration roadmaps for cross-coalition operations. The US FAA coordinates civilian airspace deconfliction rules that constrain unmanned platform routing near commercial corridors. Stakeholders must monitor how sovereign data-localization laws and encrypted datalink standards fragment previously unified procurement specifications across allied defense frameworks.
Market Dynamics
Jet-powered endurance requirements are forcing turboprop-dependent integrators to requalify supply chains around commercial narrowbody platforms, compressing development timelines and fragmenting previously consolidated vendor bases.
Growth Catalysts
- Exclusive Economic Zone expansion:Coastal states including Indonesia and Vietnam are widening sovereign maritime zones, triggering fleet recapitalization for persistent surveillance coverage.
- NATO Allied Tactical Publication interoperability mandates:Cross-coalition certification standards accelerate procurement alignment among member navies seeking joint operational compatibility.
- Acoustic processing advances:Real-time sonobuoy signal analysis is shortening detection-to-engagement cycles, compelling sensor suite upgrades across aging patrol fleets.
Market Restraints
- Airframe supply concentration:Commercial derivative platforms rely on Boeing and Airbus backlogs, exposing defense procurement to civilian production priority conflicts.
- Magnetic anomaly detection material scarcity:Rare-earth component sourcing from concentrated Asian refiners creates sensor production bottlenecks.
- Crew training pipeline limitations:Multi-mission operator certification timelines stretch eighteen to twenty-four months, constraining fleet utilization rates.
Strategic Opportunities
- Unmanned persistent littoral monitoring:UAV segments offer reduced crew-risk profiles for archipelago nations including the Philippines and Malaysia.
- Signals intelligence integration:ELINT/SIGINT suite retrofits on existing P-3 and Atlantique 2 airframes extend service life without full replacement.
- US FAA civilian airspace deconfliction rule evolution:Proposed beyond-visual-line-of-sight corridors for unmanned platforms unlock coastal routing previously restricted.
Industry Challenges
- Open-architecture mission system integration:Legacy proprietary avionics from Lockheed Martin and Thales resist modular sensor swap-outs, complicating mid-life upgrades.
- Airworthiness certification divergence:EASA military derivative protocols and US NAVAIR standards impose conflicting electromagnetic compatibility test regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maritime Patrol Aircraft Market |
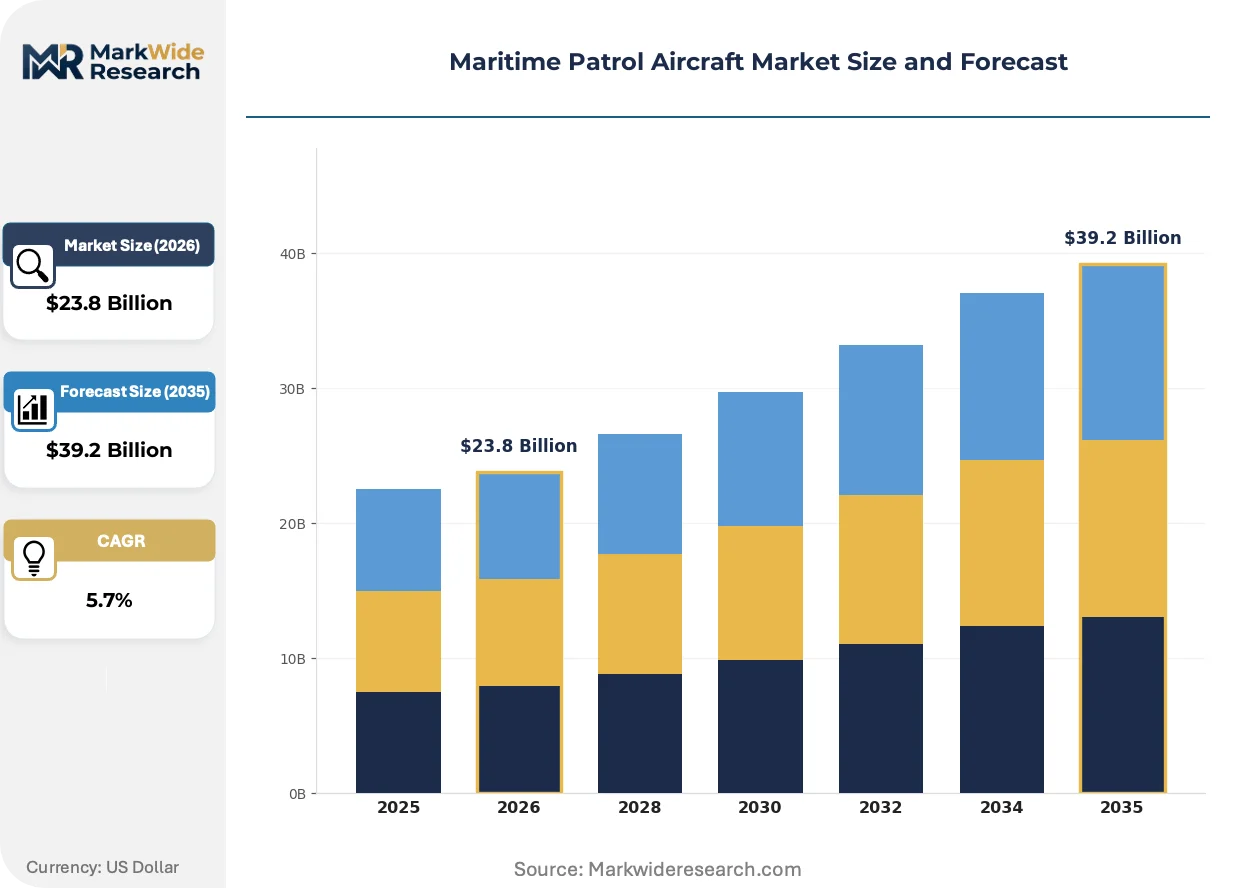
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $39.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Fixed-Wing, Rotary-Wing, UAV, Hybrid Operational Range: Short-Range, Medium-Range, Long-Range, Extended-Range End User: Military, Coast Guard, Customs, Civilian Operators Technology: Radar Systems, Sensor Arrays, Communication Systems, Surveillance Equipment |
| Companies Covered | Boeing, Lockheed Martin Corporation, Leonardo S.p.A., Airbus, Northrop Grumman Corporation, BAE Systems plc, Dassault Aviation, Embraer, Saab AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maritime Patrol Aircraft Market Emerging Trajectories
Synthetic aperture radar and artificial intelligence are fusing into unified detection pipelines, collapsing the historical separation between surface surveillance and subsurface tracking workflows.
Satellite communications backhaul is converging with tactical datalink architectures, enabling real-time sensor fusion across distributed patrol aircraft. Naval operators in the Indo-Pacific are adopting this architecture fastest, compressing command-to-shooter timelines from hours to minutes. Platform integrators now bid combined airframe-constellation packages rather than standalone aircraft.
EU F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon-based cooling systems in avionics thermal management. European integrators including Leonardo and Saab are accelerating solid-state cooling retrofits to maintain fleet availability. This regulatory pressure disproportionately affects legacy turboprop platforms with less electrical generation capacity.
Buyer concentration among coastal defense forces is consolidating procurement into multi-aircraft framework agreements with decade-long sustainment捆绑. Traditional single-aircraft competitions are disappearing in favor of fleet-level performance contracts. Australia and Japan exemplify this shift through their respective P-8A and Kawasaki P-1 acquisition structures.
Maritime Patrol Aircraft Market Segmentation
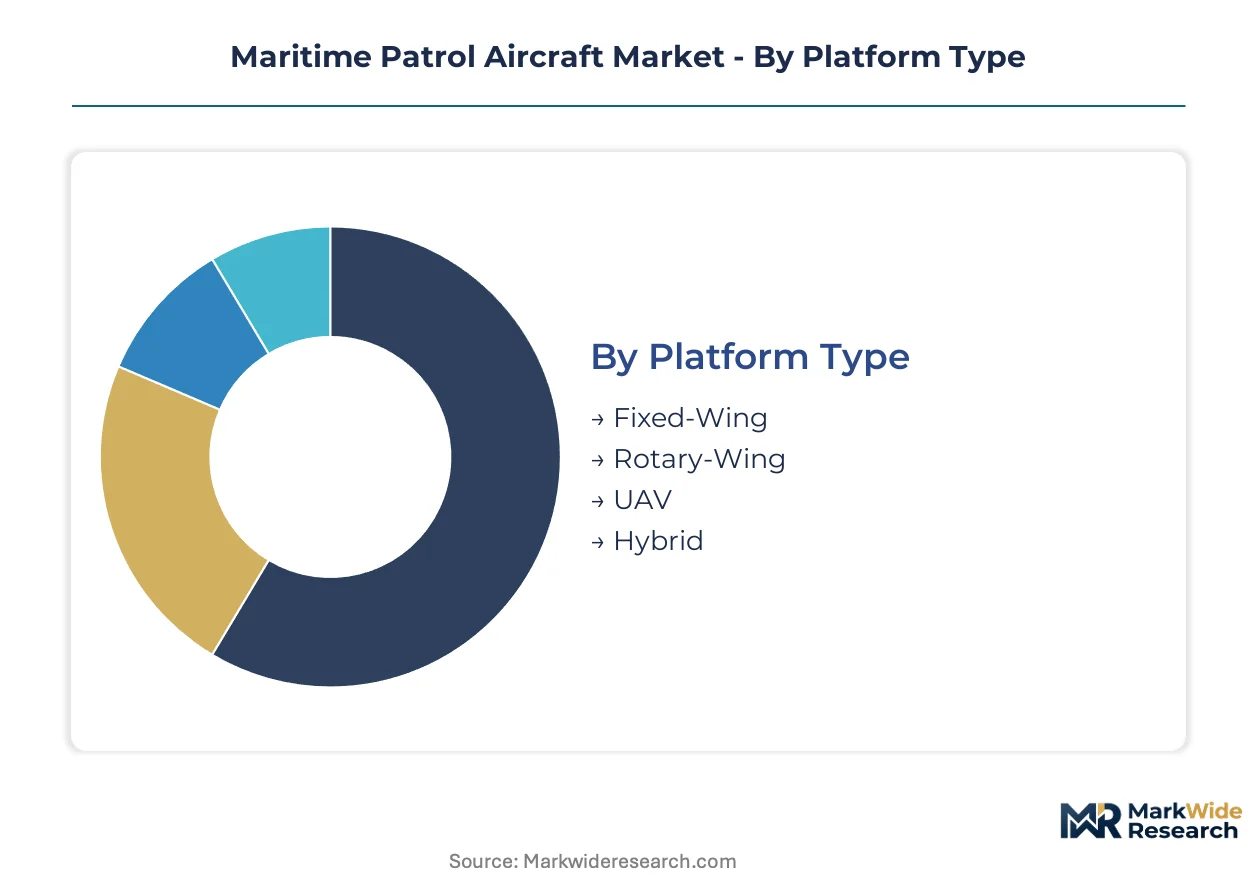
Maritime patrol aircraft procurement diverges sharply across platform architectures and operational envelopes, with buyer priorities shifting from raw endurance to sensor density and crew-risk mitigation. Segment boundaries increasingly blur as hybrid propulsion and unmanned systems reshape traditional categorization frameworks.
Platform Type:
Defense ministries weigh fuel efficiency against sensor payload capacity when selecting airframe architectures, with mission duration requirements often overriding acquisition cost considerations.
- Fixed-Wing:Turbofan and turboprop configurations dominate current fleet inventories, delivering twelve-to-eighteen-hour endurance with magnetic anomaly detection booms and multiple hardpoints for sonobuoy dispensers. Demand concentrates among NATO-aligned Pacific operators requiring high-altitude surface surveillance over contested Exclusive Economic Zones, though supply chain exposure to Boeing and Airbus commercial backlogs creates procurement delays.
- UAV:Unmanned platforms eliminate crew-risk constraints for persistent littoral monitoring, with beyond-visual-line-of-sight certification progress unlocking coastal routing previously restricted by FAA deconfliction rules. Archipelago nations including the Philippines and Malaysia are expanding procurement fastest as sovereign maritime zones widen.
- Rotary-Wing:Helicopter-based patrol serves coastal defense forces requiring vertical takeoff from ship decks or austere forward bases, sacrificing endurance for operational flexibility.
- Hybrid:Tiltrotor and compound helicopter designs merge rotary-wing accessibility with fixed-wing transit speeds, though development timelines lag pure unmanned alternatives.
Volume sits with Fixed-Wing platforms; growth tilts toward UAV configurations.
Operational Range:
Mission radius determines sensor suite density and crew complement, with premium margins clustering at endurance extremes where signals intelligence integration commands premium pricing.
- Extended-Range:Configurations exceeding fifteen hours aloft incorporate satellite communications backhaul and ELINT/SIGINT suites for real-time command-to-shooter compression, with Australia and Japan structuring decade-long fleet-level performance contracts around these specifications.
- Long-Range:Eight-to-twelve-hour missions anchor Indo-Pacific littoral state procurement, balancing sensor payload against airframe availability constraints.
- Medium-Range:Regional Exclusive Economic Zone enforcement drives European coast guard acquisition, with EASA military derivative airworthiness protocols shaping integration roadmaps.
- Short-Range:Harbor security and near-shore interdiction missions favor rapid-response configurations with reduced crew certification timelines.
Extended-Range configurations capture premium integration contracts; Medium-Range platforms dominate unit volume.
End User:
Institutional procurement authority shapes capability prioritization, with military operators emphasizing anti-submarine warfare while civilian agencies optimize for trafficking interdiction cost efficiency.
- Military:Naval aviation commands dominate fleet recapitalization, integrating acoustic processing advances and synthetic aperture radar for subsurface tracking workflows.
- Coast Guard:Search-and-rescue coordination and illegal trafficking interdiction drive sensor investments in electro-optical/infrared suites.
- Customs:Revenue protection missions prioritize cost-per-flight-hour metrics over combat system redundancy.
- Civilian Operators:Fisheries enforcement and environmental monitoring agencies adopt de-militarized platforms with reduced electromagnetic signature requirements.
Military procurement anchors development funding; Coast Guard demand is expanding most quickly as maritime law enforcement jurisdictions proliferate.
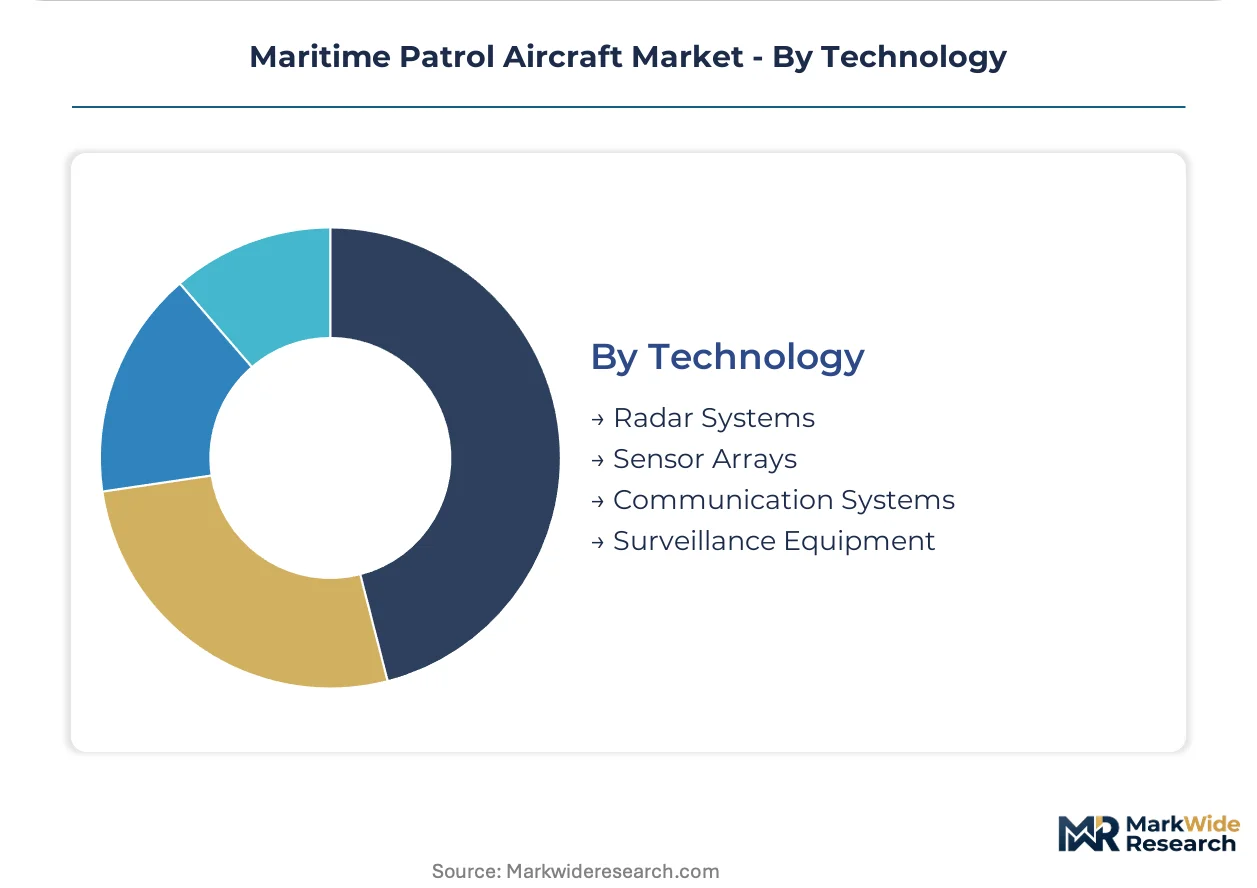
Technology:
Sensor fusion architectures now determine platform competitiveness more than airframe performance, with open-architecture mandates forcing legacy proprietary avionics toward modular swap-out compatibility.
- Radar Systems:Synthetic aperture and inverse synthetic aperture configurations provide surface target discrimination through weather and darkness, with artificial intelligence collapsing detection-to-classification timelines.
- Sensor Arrays:Magnetic anomaly detection and acoustic processor integration enable subsurface contact tracking, though rare-earth component sourcing from concentrated Asian refiners creates production bottlenecks.
- Communication Systems:Tactical datalink and satellite backhaul convergence enables distributed patrol aircraft coordination.
- Surveillance Equipment:Electro-optical/infrared turrets support visual identification and search-and-rescue operations.
Radar Systems command the largest integration contract values; Sensor Arrays face supply concentration constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare-earth refining clusters in Jiangxi and Inner Mongolia anchor magnetic anomaly detection supply chains, while Boeing's Renton production lines and Leonardo's Grottaglie final assembly facilities shape Atlantic-Pacific procurement corridors.
United States
NAVAIR certification standards and Pacific fleet recapitalization drive P-8 Poseidon procurement through 2035. The FAA coordinates civilian airspace deconfliction rules constraining unmanned platform routing near commercial corridors. Seattle-Tacoma aerospace clusters concentrate final assembly and sensor integration contracts for NATO-aligned operators.
Japan
Coast Guard fleet expansion and contested Exclusive Economic Zone enforcement accelerate Kawasaki P-1 acquisitions under decade-long performance contracts. METI defense production guidelines shape local content requirements for acoustic processor subsystems. Komaki-Nagoya industrial corridors host final assembly lines serving Indo-Pacific littoral surveillance demand.
Germany
EASA military derivative airworthiness protocols and NATO Allied Tactical Publication interoperability mandates accelerate cross-coalition certification alignment. The KBA coordinates electromagnetic compatibility test regimes for open-architecture mission system integration. Hamburg-Bremen aerospace clusters specialize in sonobuoy-delivery platform retrofits for Atlantic corridor patrol fleets.
Australia
Extended-range operational configurations and satellite communications backhaul integration command premium fleet-level contracts for P-8A squadrons. The TGA coordinates airworthiness certification for signals intelligence suite modifications. Adelaide-Edinburgh defense precincts concentrate sustainment infrastructure for southern hemisphere patrol coverage.
United Kingdom
Anti-submarine warfare sensor upgrades and acoustic processing advances compel P-8 Poseidon base establishment at RAF Lossiemouth. The UK Ministry of Defence mandates encrypted datalink standards for cross-coalition operations. Scottish aerospace clusters specialize in undersea surveillance integration for Nordic-Baltic theater coordination.
Maritime Patrol Aircraft Market Vendor Landscape
Global majors compete with regional champions across airframe architecture and sensor integration depth, producing a tiered structure where commercial-derivative platforms dominate volume while specialized turboprop variants retain niche coastal defense positions. Consolidation concentrates around Boeing-Airbus narrowbody backlogs, yet fragmentation persists in unmanned segments and ice-operable variants. Three archetypes populate the vendor map: commercial-airframe integrators leveraging civilian production lines, defense-specialist platforms optimized for acoustic processing, and emerging unmanned system houses. Dominant competitive moves include framework agreement consolidation into decade-long sustainment bundles and vertical integration into rare-earth magnet supply chains.
Within the commercial-airframe integrator tier, Boeing exemplifies scale-driven positioning through P-8 Poseidon production leverage, while Leonardo S.p.A. occupies a regional champion role specializing in Atlantic corridor sonobuoy-delivery platforms. Saab AB represents the compact-variant archetype, anchoring Nordic-Baltic demand for ice-operable configurations tailored to archipelago environments.
| Leading Market Players |
|---|
| Boeing |
| Lockheed Martin Corporation |
| Leonardo S.p.A. |
| Airbus |
| Northrop Grumman Corporation |
| BAE Systems plc |
| Dassault Aviation |
| Embraer |
| Saab AB |
| Others |
Supply Flow & Price Mechanics
Jet-powered platform transitions from legacy turboprop architectures are simultaneously compressing unit production economics and concentrating airframe sourcing around Boeing and Airbus commercial backlogs, reshaping how defense procurement budgets absorb civilian production priority conflicts.
Pricing Analysis
Extended-range fleet-level performance contracts bundle decade-long sustainment commitments with initial platform acquisition, unbundling traditional single-aircraft competitions into lifecycle-cost frameworks. Three-tier pricing structure across premium, standard, and economy levels separates NATO-interoperable configurations from coast-guard-optimized variants and de-militarized civilian patrol specifications. Price differentiation hinges on signals intelligence suite integration depth and encrypted datalink certification tiers. Pricing pressure stems from crew training pipeline bottlenecks stretching eighteen to twenty-four months, constraining fleet utilization rates and compressing per-airframe revenue recognition timelines. Coast Guard agencies exhibit highest price sensitivity due to cost-per-flight-hour procurement mandates, while naval aviation commands prioritize mission system density over unit acquisition cost.
Supply Chain Analysis
METI defense production guidelines in Japan and similar domestic-content mandates across Indo-Pacific littoral states are reshaping acoustic processor subsystem sourcing toward local industrial corridors. Magnetic anomaly detection supply chains draw from rare-earth refining clusters in Jiangxi and Inner Mongolia, tethering sensor production to concentrated Asian refiners. Boeing's Renton production lines and Leonardo's Grottaglie final assembly facilities anchor Atlantic-Pacific procurement corridors, with commercial narrowbody backlogs creating single-source vulnerability for defense airframe procurement. Distribution runs through government-to-government framework agreements rather than open commercial tendering, with sovereign data-localization laws fragmenting previously unified procurement specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EASA military derivative airworthiness protocols and US NAVAIR certification standards impose conflicting electromagnetic compatibility test regimes, erecting regulatory moats that disadvantage non-aligned integrators.
For Market Incumbents: Cement position through captive supply of rare-earth magnet components and accelerated solid-state cooling retrofits compliant with EU F-Gas Regulation phase-down schedules. Lock in decade-long sustainment捆绑 with Australia and Japan before open-architecture mission system mandates commoditize sensor integration margins. Threat vectors include unmanned platform houses disrupting persistent littoral monitoring segments with reduced crew-risk value propositions. For New Entrants and Emerging Players: Direct-to-defense procurement platforms bypassing traditional prime contractor hierarchies offer lower customer acquisition cost entry into coast guard segments in the Philippines and Malaysia. Target archipelago nations widening sovereign maritime zones where UAV beyond-visual-line-of-sight certification progress unlocks coastal routing previously restricted by FAA deconfliction rules. White-space concentrates in ice-operable compact variants for Nordic-Baltic theater requirements where Saab AB currently anchors demand. For Investors and Strategic Acquirers: Exit pathways concentrate in defense-specialist platform houses with acoustic processing depth and established NATO Allied Tactical Publication interoperability credentials. Long-term viability favors integrators with backward integration into sonobuoy-delivery platform manufacturing and satellite communications backhaul constellation partnerships. Watch for FAA beyond-visual-line-of-sight corridor rule finalization as inflection indicator unlocking unmanned segment addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Open-Architecture Mission System Certification | Modular sensor swap-out compatibility unlocks mid-life upgrade revenue streams for P-3 and Atlantique 2 operators. |
| Rare-Earth Magnet Supply Agreement | Captive sourcing from Jiangxi refiners insulates magnetic anomaly detection production against export restriction volatility. |
| Satellite Constellation Partnership | Combined airframe-constellation packages compress command-to-shooter timelines for Indo-Pacific naval operators. |
| Ice-Operable Variant Development | Archipelago-specific configurations capture Nordic-Baltic demand outside Boeing-Airbus narrowbody supply concentration. |
| Crew Training Pipeline Expansion | Accelerated multi-mission operator certification addresses eighteen-to-twenty-four-month constraint on fleet utilization rates. |
Methodological Framework
Independent corroboration across naval aviation procurement officers, acoustic processing subsystem engineers, and coast guard fleet planners underwrites the qualitative findings in this study. Primary interviews with sonobuoy-delivery platform integrators, magnetic anomaly detection sensor specialists, and satellite communications backhaul providers combined with secondary validation from NATO Allied Tactical Publication documentation, EASA military derivative airworthiness protocol filings, and FAA civilian airspace deconfliction rule dockets. Bottom-up triangulation across platform-type procurement volumes and top-down validation through defense budget appropriation analysis ensure cross-verified demand quantification.
Comparable-period anchoring to historical fleet recapitalization cycles and acoustic processing upgrade waves established the forecast window baseline. The analytical framework segments demand across fixed-wing, UAV, rotary-wing, and hybrid platform architectures, with operational range tiers and end-user institutional categories modeled throughout the projection horizon. CAGRs derive from elasticity-adjusted procurement projections incorporating anti-submarine warfare sensor upgrade timelines and Exclusive Economic Zone expansion patterns across littoral states.
Inputs from NAVAIR certification databases and EASA military derivative protocol registries were available through the study window; gaps in classified signals intelligence suite specification disclosures introduce uncertainty bands around extended-range configuration pricing estimates. Forecasts reflect documented assumptions regarding FAA beyond-visual-line-of-sight rule evolution and EU F-Gas Regulation enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Tilt Rotor Aircraft Market
Aircraft
Latin America Commercial Aircraft Market
Aircraft
Global Aircraft Towbars Market
Aircraft
Asia-Pacific Aircraft Manufacturing Market
Aircraft
Aircraft Strut Market
Aircraft
Asia-Pacific Commercial Aircraft Market
Aircraft
Commercial Turboprop Aircrafts Market
Aircraft
Experimental Amateur-Built (E-AB) Aircraft Market
Aircraft
Turboprop Aircraft Market
Aircraft
Belly Fairing Modifications for Freighter and Combi Aircraft Market
Aircraft
Aircraft Cargo Winches Market
Aircraft
Autonomous Aircraft Propulsion Systems Market
Aircraft
Aircraft Landing Gear Market
Aircraft
Middle East and Africa Aviation Market
Aircraft
Global Aircraft Tugs Market
Aircraft
Europe Military Helicopters Market