
 US Aircraft Windshield Wiper and Washer System Market | 2026-2036
US Aircraft Windshield Wiper and Washer System Market Size, Share, and Industry Trends Forecast 2026-2036
US Aircraft Windshield Wiper and Washer System Market Insights
US aerospace component manufacturing is realigning around higher OEM build rates and aftermarket refurbishment cycles. Collins Aerospace leverages its integrated flight-deck portfolio to sustain long-term supply agreements with domestic airframers. Honeywell International Inc. anchors the military aviation segment through hardened wiper systems designed for tactical rotorcraft environments. Parker Hannifin Corporation differentiates via hydraulic pump assemblies that occupy critical positions in regional jet platforms.
Aircraft windshield wiper and washer systems integrate motorized arm assemblies, fluid reservoirs, and control interfaces to maintain pilot visibility during precipitation, ice, and contaminated runway conditions. These systems typically operate at sweep speeds of 30-45 cycles per minute and withstand aerodynamic loads exceeding 300 knots across flat-pane and curved windscreen geometries. Wiper Systems dominate installed base value due to recurring blade replacement schedules, while Electro-Mechanical technology captures expanding share as carriers retire pneumatic infrastructure. Commercial Aviation generates the deepest margin pools among end users, though Military Aviation sustains premium pricing through hardened specification requirements.
FAA airworthiness directives govern field performance and replacement intervals for all US-registered aircraft visibility equipment. EPA regulations on de-icing fluid composition constrain washer system chemistry and disposal protocols for MRO facilities. The Department of Defense MIL-STD-810H framework shapes environmental testing for military wiper platforms. Stakeholders must weigh aftermarket parts proliferation against OEM captive supply strategies as fleet renewal accelerates.
Market Dynamics
Electro-mechanical actuator architectures are displacing pneumatic wiper systems across US commercial fleets, driven by FAA visibility standard updates and carrier demands for reduced maintenance intervals. This technology transition concentrates procurement decisions around integrated flight-deck suppliers capable of delivering certified electro-mechanical platforms at OEM build rates.
Growth Catalysts
- FAA Airworthiness Directives:Updated visibility equipment mandates require fleet-wide wiper system retrofits, generating sustained aftermarket demand from regional and major carriers operating aging narrow-body aircraft.
- Southeast Manufacturing Clusters:Boeing and Airbus final assembly lines in South Carolina and Alabama concentrate OEM procurement volumes, creating localized supply chain density for component manufacturers.
- Electro-Mechanical Technology:Solid-state actuator designs eliminate pneumatic infrastructure, reducing weight and maintenance while enabling precise sweep control across variable flight profiles.
Market Restraints
- Specialized Elastomer Supply:Aerospace-grade wiper blade compounds depend on fluoroelastomer feedstocks subject to price volatility and limited domestic sourcing.
- Certification Timeline Friction:FAA supplemental type certificate processes for wiper system modifications extend 18-24 months, delaying revenue recognition for retrofit programs.
- Electro-Mechanical Substitution:Pneumatic system installed base depreciation accelerates as carriers prioritize electro-mechanical platforms, stranding legacy inventory and repair capabilities.
Strategic Opportunities
- Military Aviation Hardening:Department of Defense MIL-STD-810H environmental testing requirements create premium pricing tiers for tactical rotorcraft wiper platforms with extended operational envelopes.
- Fluid Chemistry Innovation:EPA de-icing fluid disposal regulations constrain washer system formulations, opening white space for biodegradable concentrate solutions compatible with existing reservoir architectures.
- Regional Jet Electrification:Emerging electric-hybrid propulsion platforms in the 76-seat category require lightweight electro-mechanical wiper systems absent pneumatic bleed air infrastructure.
Industry Challenges
- Electro-Mechanical Engineering Talent:Domestic aerospace actuator design expertise concentrates at legacy suppliers, constraining workforce mobility for emerging competitors.
- Flight-Deck Integration Complexity:Wiper control interfaces must synchronize with modern avionics suites, extending software validation cycles and certification documentation burdens.
- Legacy Fleet Support Obligations:Pneumatic system technical data packages degrade as original equipment manufacturers sunset support, forcing MRO facilities to reverse-engineer replacement components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Aircraft Windshield Wiper and Washer System Market |
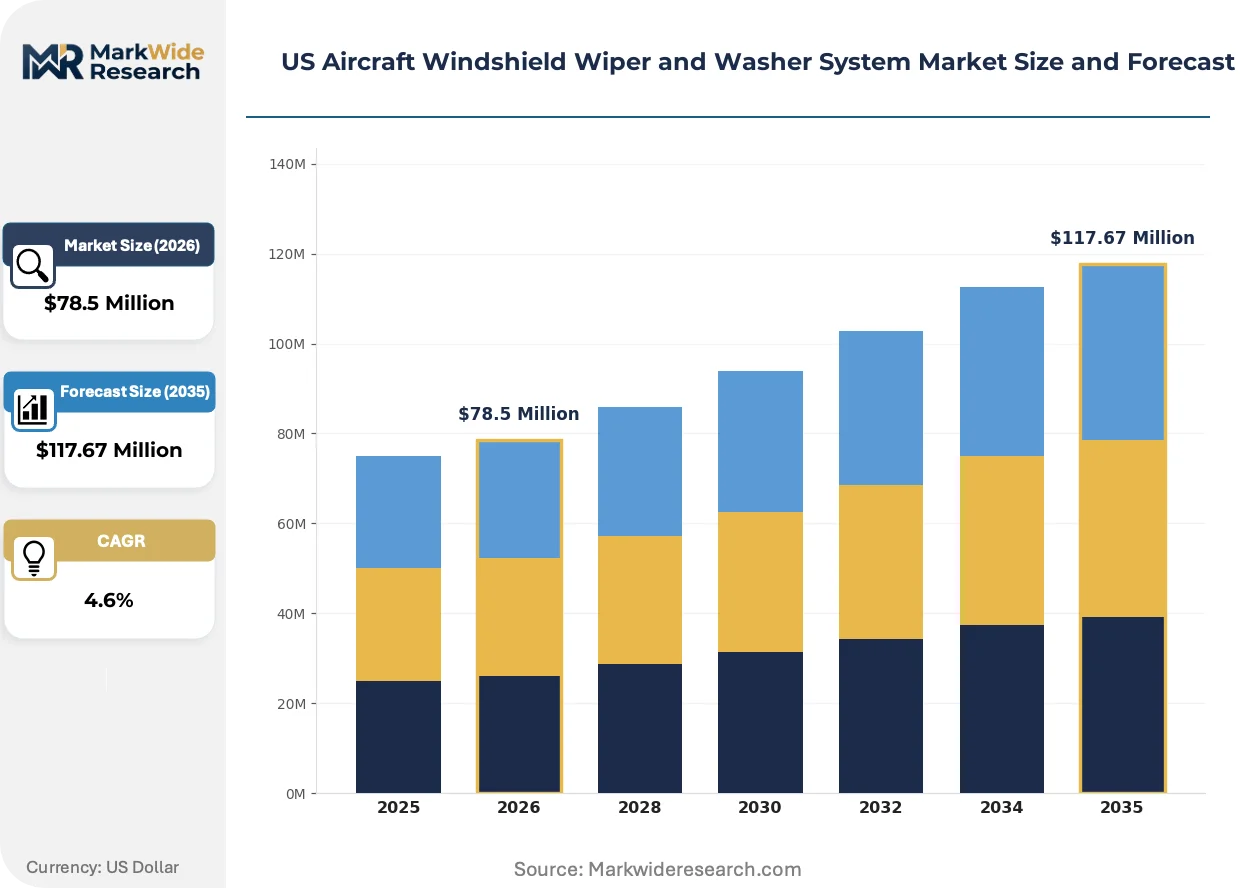
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $117.67 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wiper Systems, Washer Systems, Control Units, Pump Assemblies Technology: Mechanical, Electro-Mechanical, Hydraulic, Pneumatic End User: Commercial Aviation, Military Aviation, Private Jets, Rotorcraft Installation Type: OEM, Aftermarket, Retrofit, Custom Design |
| Companies Covered | Collins Aerospace, RTX Corporation, Honeywell International Inc., Eaton Corporation, Safran SA, Parker Hannifin Corporation, GKN Aerospace, Liebherr-Aerospace, Ametek Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Aircraft Windshield Wiper and Washer System Market Trends and Innovations
Active technology convergence between electro-mechanical actuation and integrated sensor feedback is redefining wiper system performance benchmarks. Regulatory chemistry constraints and procurement model evolution complete the tripartite pressure reshaping supplier positioning.
Brushless DC motor architectures with integrated position sensing are expanding into commercial aviation platforms previously served by pneumatic rotary actuators. Major US carriers retrofitting narrow-body fleets prioritize these systems for their reduced part count and predictive maintenance telemetry. The technology is expanding into regional jet OEM specifications as weight reduction targets harden.
FAA airworthiness directives governing visibility equipment replacement intervals now incorporate specific electro-mechanical performance thresholds absent from legacy pneumatic standards. Compliance documentation requirements have intensified, favoring suppliers with established certification engineering departments. Military Aviation segments respond through accelerated MIL-STD-810H test program completion to maintain program access.
Carrier procurement departments now unbundle wiper blade consumables from system-level contracts, creating direct aftermarket channels independent of OEM captive supply agreements. This disintermediation compresses margin pools for integrated system suppliers while opening volume opportunities for specialized blade manufacturers. The Southeast maintenance hub concentration around Atlanta and Miami renders this shift most visible in domestic fleet operations.
US Aircraft Windshield Wiper and Washer System Market Segmentation
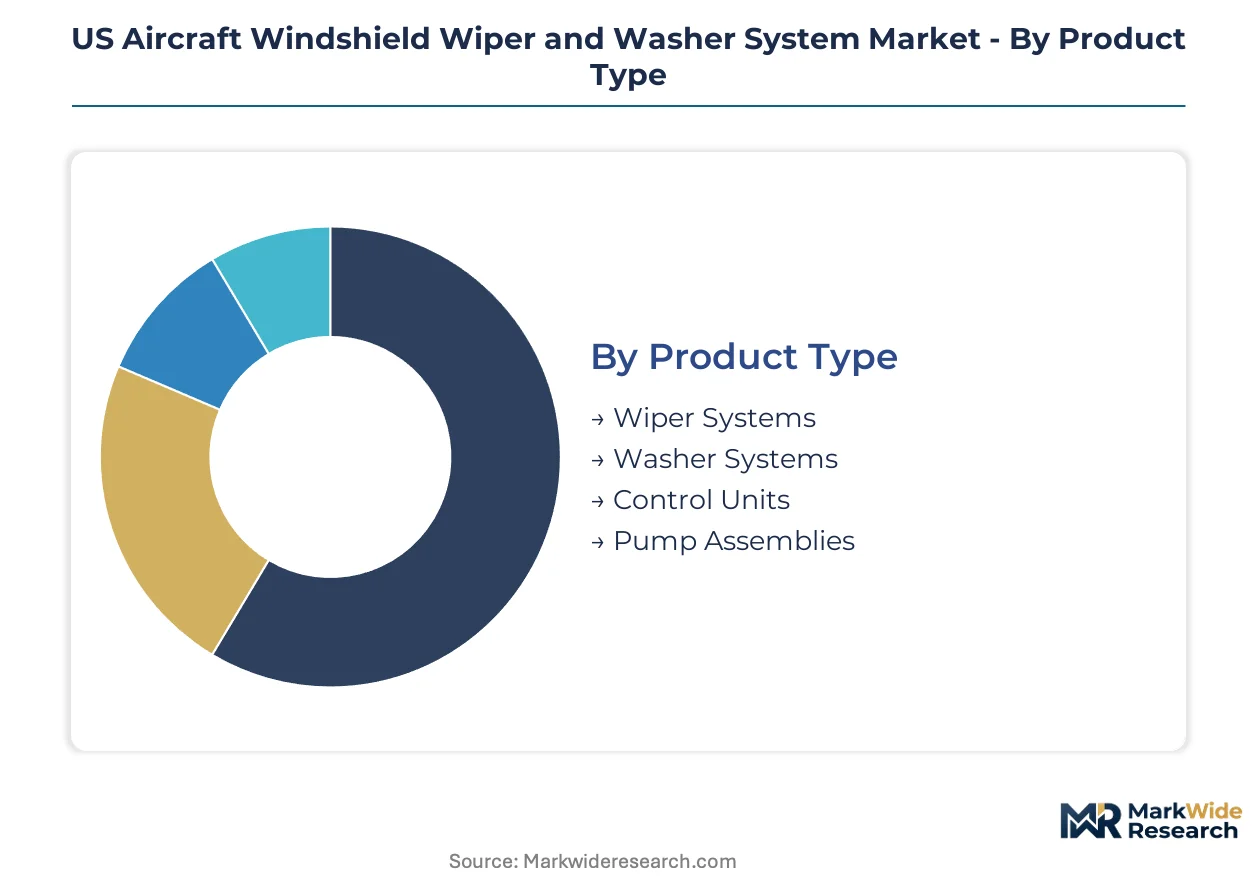
US aircraft windshield wiper and washer system procurement splits sharply between high-volume OEM contracts and premium aftermarket retrofits. Fleet renewal cycles and FAA mandate compliance create divergent margin profiles across product categories. Technology transitions and installation timing further stratify supplier positioning.
Product Type:
Wiper Systems dominate installed base value through recurring blade replacement, while Control Units capture premium pricing from avionics integration complexity.
- Wiper Systems:Motorized arm assemblies with sweep speeds of 30-45 cycles per minute withstand aerodynamic loads exceeding 300 knots. Demand concentrates at Southeast maintenance hubs around Atlanta and Miami where regional carrier blade replacement schedules drive volume procurement.
- Control Units:Electronic interfaces synchronize wiper operation with flight-deck avionics suites and environmental sensors. Procurement from Boeing and Airbus final assembly lines in South Carolina and Alabama favors suppliers with integrated certification engineering capabilities.
- Washer Systems:Fluid reservoirs and distribution manifolds deliver de-icing solutions under EPA disposal constraints.
- Pump Assemblies:Hydraulic and electric pump units occupy critical positions in regional jet platforms.
Mature deployment sits with Wiper Systems. Newer deployment is concentrated in Control Units.
Technology:
Cost tier stratification separates legacy pneumatic infrastructure from electro-mechanical platforms commanding OEM specification.
- Electro-Mechanical:Brushless DC motor architectures with integrated position sensing eliminate pneumatic infrastructure weight while enabling predictive maintenance telemetry. Major US carriers retrofitting narrow-body fleets prioritize these systems for reduced part count and precise sweep control across variable flight profiles.
- Pneumatic:Rotary actuator designs dependent on engine bleed air face accelerated depreciation as carriers prioritize electro-mechanical platforms. Legacy technical data packages degrade as original manufacturers sunset support, forcing MRO facilities to reverse-engineer replacement components.
- Mechanical:Basic linkage-driven systems persist in light general aviation applications.
- Hydraulic:Pump-driven assemblies serve specialized military rotorcraft requirements.
Electro-Mechanical platforms are expanding most quickly. Pneumatic systems face steepest contraction.
End User:
Application differentiation creates margin separation between commercial fleet volume and military specification premium.
- Commercial Aviation:Narrow-body and wide-body fleet operators generate the deepest margin pools through OEM build rate contracts and sustained aftermarket blade consumption. FAA airworthiness directive compliance mandates drive retrofit demand from aging aircraft populations.
- Military Aviation:Tactical rotorcraft and fixed-wing platforms sustain premium pricing through MIL-STD-810H hardened specifications with extended operational envelopes. Department of Defense procurement prioritizes environmental testing completion for program access.
- Private Jets:Business aircraft operators balance customization requirements with certification timeline constraints.
- Rotorcraft:Helicopter platforms demand specialized swept-area geometries and vibration-resistant mounting.
Volume concentration sits with Commercial Aviation. Premium pricing is concentrated in Military Aviation.
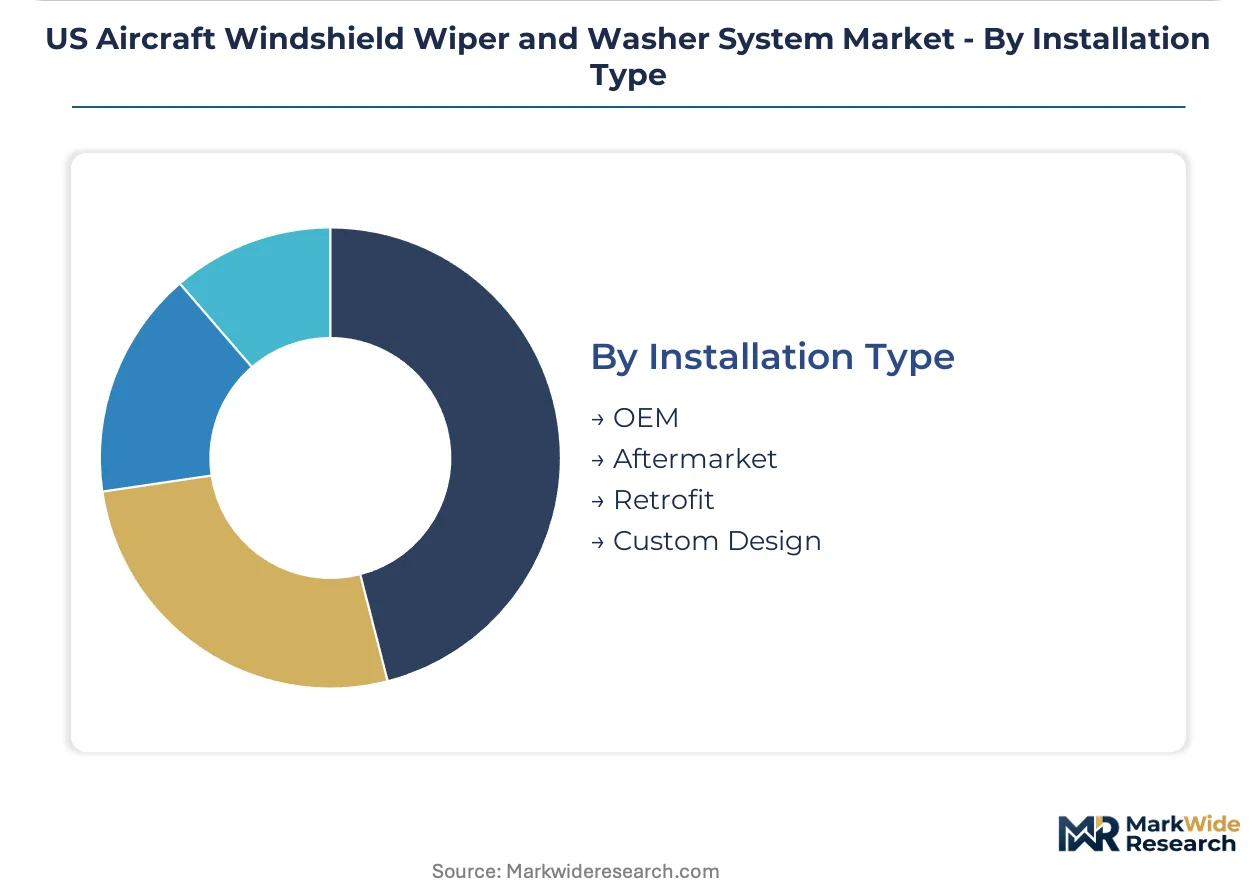
Installation Type:
Customer type stratification separates captive OEM supply agreements from independent aftermarket channels.
- OEM:Factory installation at Boeing and Airbus final assembly lines locks in long-term supply agreements with integrated flight-deck suppliers. Southeast manufacturing clusters concentrate procurement decisions around certified electro-mechanical platforms meeting build rate requirements.
- Aftermarket:Unbundled wiper blade consumables now move through direct channels independent of system-level contracts, compressing margins for integrated suppliers while opening volume opportunities for specialized blade manufacturers.
- Retrofit:Fleet-wide wiper system modifications face 18-24 month FAA supplemental type certificate timelines.
- Custom Design:Specialized applications require dedicated certification engineering resources.
Procurement scale sits with OEM. Channel disintermediation is concentrated in Aftermarket.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fluoroelastomer feedstock availability concentrates in the Gulf Coast petrochemical corridor, anchoring domestic wiper blade compound manufacturing. Southeast assembly operations draw component suppliers into tight geographic clusters around major airframer facilities.
Southeast
Boeing's Charleston facility and Airbus Mobile drive OEM procurement volumes for electro-mechanical wiper systems. FAA airworthiness directives mandate fleet-wide visibility equipment upgrades, concentrating retrofit demand at Atlanta and Miami maintenance hubs. Component manufacturers locate within 200-mile radii of final assembly lines to meet just-in-time delivery requirements.
Southwest
Texas hosts specialized elastomer blending operations serving aerospace sealant and wiper blade producers. EPA disposal regulations for de-icing fluids shape washer system chemistry development at Dallas-Fort Worth engineering centers. Parker Hannifin maintains hydraulic pump assembly capacity in the region for regional jet platforms.
Midwest
Ohio and Michigan aerospace clusters sustain legacy pneumatic system technical support for aging narrow-body fleets. Department of Defense procurement channels route through Wright-Patterson Air Force Base for MIL-STD-810H hardened rotorcraft platforms. Reverse-engineering capabilities concentrate at Cleveland and Cincinnati MRO facilities as OEMs sunset legacy data packages.
West Coast
California's flight-deck avionics integration expertise supports control unit software validation cycles. Honeywell anchors military aviation development through hardened wiper platforms designed for tactical environments. Seattle-area engineering talent pools feed electro-mechanical actuator design requirements for next-generation narrow-body specifications.
Northeast
Connecticut and Massachusetts defense contractors capture premium pricing for military specification wiper systems. Collins Aerospace leverages integrated flight-deck portfolios from headquarters operations in the region. FAA certification engineering departments cluster around Washington-Boston corridor, accelerating supplemental type certificate timelines for retrofit programs.
US Aircraft Windshield Wiper and Washer System Market Competitive Landscape
Global majors compete with regional champions across integrated flight-deck portfolios and specialized component supply. The market structure consolidates around three dominant suppliers with captive OEM relationships, while mid-tier fabricators compete for aftermarket blade and consumable volumes. Strategic archetypes separate integrated system suppliers, specialized component manufacturers, and diversified industrial conglomerates. Competitive moves concentrate on backward integration into elastomer compounding and strategic partnerships for electro-mechanical actuator technology licensing.
Within the integrated system supplier tier, Collins Aerospace and Honeywell International Inc. exemplify archetypes combining flight-deck portfolios with long-term OEM agreements. RTX Corporation occupies a position spanning both commercial and military aviation segments through diversified aerospace holdings. These three entities anchor competitive positioning around certification engineering capabilities and Southeast manufacturing proximity to final assembly lines.
| Leading Market Players |
|---|
| Collins Aerospace |
| RTX Corporation |
| Honeywell International Inc. |
| Eaton Corporation |
| Safran SA |
| Parker Hannifin Corporation |
| GKN Aerospace |
| Liebherr-Aerospace |
| Ametek Inc. |
| Others |
Pricing and Supply Chain Analysis
Family-owned elastomer compounders in the Gulf Coast petrochemical corridor anchor domestic wiper blade production, translating captive fluoroelastomer supply into pricing discipline that resists commoditization pressure from Asian imports. Their long-term offtake agreements with Boeing and Airbus final assembly lines in South Carolina and Alabama lock in volume commitments that insulate margin structures from spot-market volatility in aerospace-grade rubber feedstocks.
Pricing Analysis
Warranty-bundled electro-mechanical systems command premium positioning against unbundled blade consumables that carriers now source through direct aftermarket channels. Three-tier pricing structure across OEM specification, retrofit certification, and maintenance-grade tiers reflects FAA supplemental type certificate investment recovery timelines. Cost compression in the aftermarket blade tier is intensifying because carrier procurement departments disaggregate consumables from system-level contracts. Regional carriers operating aging narrow-body fleets exhibit highest price sensitivity, while military aviation programs sustain lowest sensitivity due to MIL-STD-810H hardened specification requirements.
Supply Chain Analysis
Single-source vulnerability sits with Japanese fluoroelastomer producers supplying aerospace sealant and wiper blade compounders in Texas and Louisiana. Domestic manufacturing draws from Gulf Coast petrochemical feedstocks, South Carolina electro-mechanical actuator fabrication, and Ohio legacy pneumatic component remanufacturing. Tariff exposure on imported elastomer precursors threatens margin stability for mid-tier blade fabricators lacking backward integration into compounding operations. Distribution runs through captive OEM supply agreements at Boeing Charleston and Airbus Mobile, supplemented by independent aftermarket channels radiating from Atlanta and Miami maintenance hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluoroelastomer compounding capacity constraints prop pricing power for integrated suppliers, as domestic feedstock availability limits production scale-up for emerging competitors. Electro-mechanical actuator engineering talent scarcity reinforces incumbent positioning through the projection horizon.
For Market Incumbents: Acquire specialized elastomer blending operations in the Gulf Coast corridor to secure captive fluoroelastomer supply against Japanese import dependency. Consolidate electro-mechanical actuator design talent pools in Seattle and California to defend against emerging flight-deck integrators. Threat substitution from Chinese electro-mechanical platforms intensifies pricing pressure in the aftermarket tier, requiring certification investment in FAA engineering departments along the Washington-Boston corridor as a defensive lever. For New Entrants and Emerging Players: Capture unbundled wiper blade volume in the Southeast maintenance hub corridor around Atlanta and Miami, where carrier disintermediation of system-level contracts creates direct channel access. Target military aviation rotorcraft specifications as the most penetrable premium segment, given MIL-STD-810H testing completion bottlenecks at legacy suppliers. Go-to-market execution should anchor on biodegradable de-icing fluid concentrate formulations compatible with existing washer system reservoir architectures. For Investors and Strategic Acquirers: FAA supplemental type certificate backlog clearance rates at the 18-month threshold is the leading indicator that aftermarket retrofit demand acceleration is materializing. Long-term viability frames around electro-mechanical platform conversion completion across the narrow-body fleet, with acquisition focus on mid-tier elastomer compounders possessing Gulf Coast manufacturing footprints. Watch electro-mechanical engineering hire rates at Collins Aerospace and Honeywell as the signal for incumbent capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Compounding | Secures fluoroelastomer supply against Japanese import tariff exposure for Gulf Coast compounders. |
| Electro-Mechanical Actuator Certification Investment | Accelerates FAA supplemental type certificate timelines for retrofit program access at Southeast carriers. |
| Biodegradable Fluid Chemistry Development | Addresses EPA de-icing fluid disposal constraints for MRO facilities in Dallas-Fort Worth engineering clusters. |
| Military Aviation Hardening Program Completion | Unlocks MIL-STD-810H premium pricing tiers for tactical rotorcraft platforms at Wright-Patterson procurement channels. |
| Aftermarket Channel Disintermediation | Captures unbundled blade volume through direct carrier relationships independent of OEM captive supply agreements. |
Research Methodology
Multi-period observation of FAA airworthiness directive issuance patterns, electro-mechanical retrofit adoption curves, and Southeast manufacturing cluster employment data anchored the trend analysis, supplemented by interviews with airline fleet engineering directors, MRO facility procurement managers, elastomer compounder operations heads, and flight-deck avionics integration specialists. Secondary validation drew from FAA certification databases, Department of Defense procurement filings, EPA de-icing fluid compliance records, and Bureau of Labor Statistics aerospace employment series. Bottom-up carrier fleet data triangulated against top-down OEM build rate projections.
Input-output matrices modeled electro-mechanical system penetration against pneumatic installed base depreciation across the projection horizon. Segmentation dimensions spanned product type, technology architecture, end-user application, and installation channel. CAGRs derived from fitted adoption curves incorporating FAA mandate compliance timelines and carrier capital expenditure cycle phasing. Industry-specific forecast inputs included fluoroelastomer feedstock price indices and electro-mechanical engineering wage inflation in Seattle and California talent markets.
The model holds under steady FAA regulatory enforcement and intact Japanese elastomer supply relationships; deviation in trade policy or accelerated domestic compounding capacity buildout would shift volume and value trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Asia-Pacific Helicopters Market
Aircraft
Global Helicopter Market
Aircraft
Aircraft Leasing and Rental Market
Aircraft
Aircraft Wheels Brakes Market
Aircraft
Single-Seat Gyrocopter Market
Aircraft
Europe Business Jet Market
Aircraft
Electric VTOL (Evtol) Aircraft Market
Aircraft
Aircraft Radome Market
Aircraft
Aircraft Cables Market
Aircraft
Two-Seater Ultralight Helicopters Market
Aircraft
Aircraft Door Market
Aircraft
Experimental Amateur-Built (E-AB) Aircraft Market
Aircraft
Aircraft Band Clamps Market
Aircraft
Aircraft Wheels Market
Aircraft
Aircraft Mounts Market
Aircraft
Tanker Aircraft Market