
 Small Evtol Aircraft Market | 2026-2036
Small Evtol Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Small Evtol Aircraft Market Insights
FAA Part 135 air carrier certification is reorganizing which developers can transition from prototype to revenue service. Joby Aviation leverages extensive flight test data to anchor its position in piloted passenger operations. Beta Technologies specializes in charging infrastructure integration alongside its aircraft development. EHang Holdings Ltd. competes through autonomous certification pathways that bypass pilot labor constraints entirely.
Small eVTOL aircraft are electric vertical take-off and landing vehicles with distributed electric propulsion, typically spanning 6-12 rotors and carrying 1-6 passengers or equivalent cargo payloads up to approximately 450 kg. These aircraft eliminate runway dependency through vectored thrust or lift-plus-cruise architectures, enabling point-to-point operations in dense urban environments. Passenger configurations currently dominate development pipelines, though cargo applications for last-mile delivery are attracting logistics capital due to simpler autonomy requirements and reduced certification burden. Hybrid electric propulsion systems occupy a transitional niche where battery energy density falls short of mission requirements, particularly in markets with limited ground charging infrastructure.
FAA type certification under 14 CFR Part 23 and EASA SC-VTOL frameworks govern airworthiness standards, while EU AI Act provisions increasingly shape autonomous flight control validation requirements. The FAA's Integration Pilot Program and EASA's design-driven regulation create divergent compliance pathways that fragment development roadmaps. Stakeholders must monitor which regulatory jurisdiction captures the first high-volume operational approvals, as this will determine manufacturing location decisions and supply chain clustering for the next decade of production scaling.
Market Dynamics
Solid-state battery chemistry is displacing lithium-ion architectures as the dominant energy storage paradigm, compressing development timelines and forcing airframe redesigns around new thermal management envelopes.
Growth Catalysts
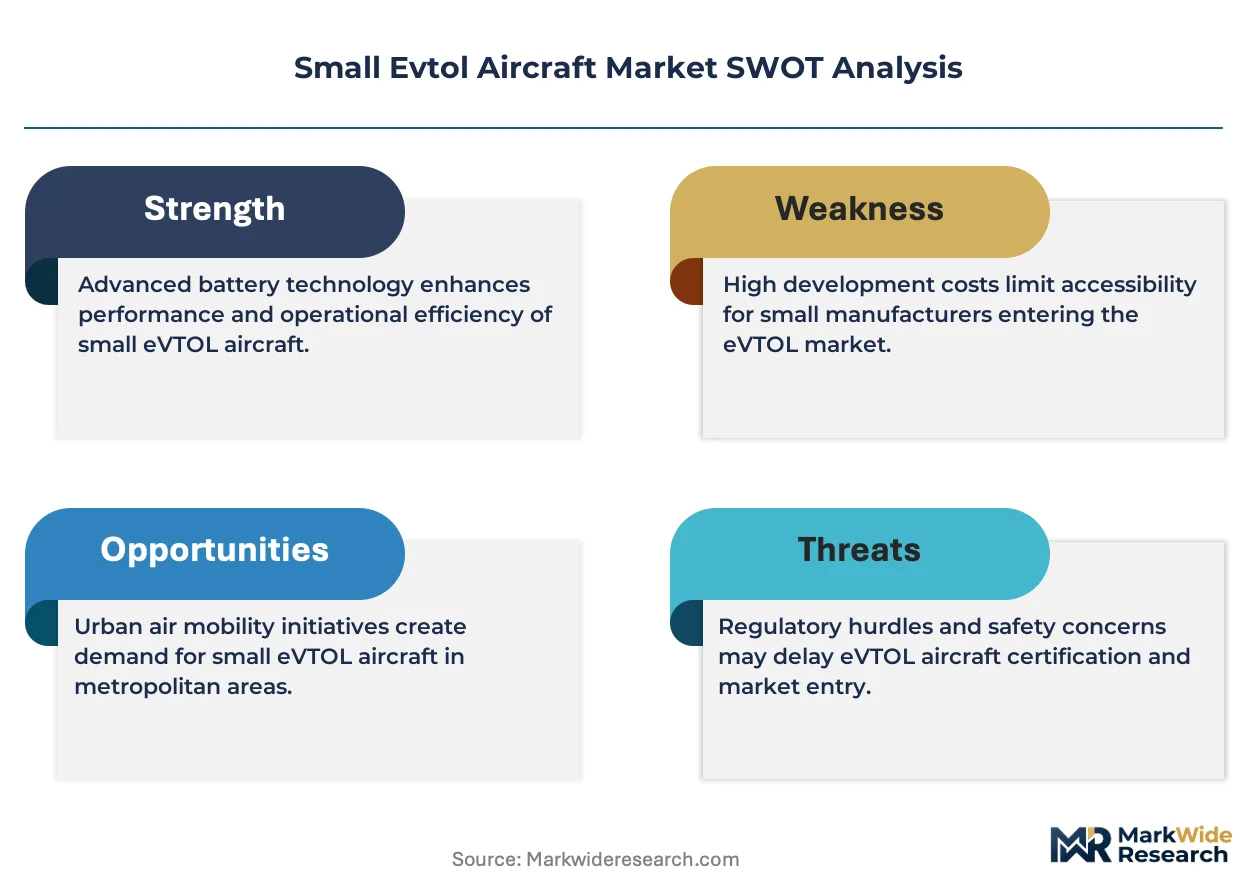
- FAA Part 135 Certification Pathways:Air carrier operating certificates for on-demand passenger service are unlocking revenue models beyond demonstration flights. Urban air mobility operators in the United States are securing these approvals ahead of European counterparts.
- Silicon-anode cell manufacturing:Energy density improvements from solid-state silicon-anode configurations are extending mission ranges to 150 nautical miles. Battery pack suppliers are scaling production lines dedicated to aviation-grade cells.
- Vertiport infrastructure deployment:Ground charging and passenger handling facilities are clustering around Dallas, Los Angeles, and Miami metropolitan areas. Real estate developers are securing FAA facility design approvals for multi-site networks.
Market Restraints
- Lithium supply concentration:Cathode precursor processing capacity concentrates in China, creating raw material vulnerability for non-Chinese airframe assemblers. Alternative sourcing from Chilean and Australian spodumene deposits remains underdeveloped.
- Copper conductor pricing volatility:Distributed electric propulsion architectures require substantial high-purity copper for motor windings and power distribution. Mining output constraints are amplifying input cost uncertainty.
- 14 CFR Part 23 airworthiness timelines:FAA type certification for novel propulsion configurations averages 5-7 years, compressing investor return horizons and limiting late-stage development funding.
Strategic Opportunities
- UAE urban air mobility corridors:Dubai's RTA vertiport masterplan and Abu Dhabi's regulatory sandbox are creating concentrated demand for piloted passenger services. The General Civil Aviation Authority is streamlining foreign operator approvals.
- Last-mile cargo substitution:E-commerce fulfillment networks are evaluating eVTOL replacement for van-based delivery in congested megacities. Autonomy requirements simplify compared to passenger certification.
- EU AI Act autonomous flight validation:Machine learning-based flight control systems are gaining regulatory recognition pathways separate from traditional deterministic software assurance. This bifurcation favors developers with AI-native architectures.
Industry Challenges
- Flight test engineer scarcity:Experienced rotary-wing test pilots with electric propulsion expertise are concentrated at legacy helicopter manufacturers. Training pipelines have not scaled to match development program demand.
- Battery thermal runaway containment:Aviation-grade battery management systems require redundant fault isolation architectures. Certification credit for automotive-derived designs remains contested by FAA certification teams.
- Ground infrastructure interoperability:Charging connector standards fragment between CCS-based automotive adaptations and aviation-specific high-voltage architectures. Fleet operators face stranded asset risk from early standard bets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Evtol Aircraft Market |
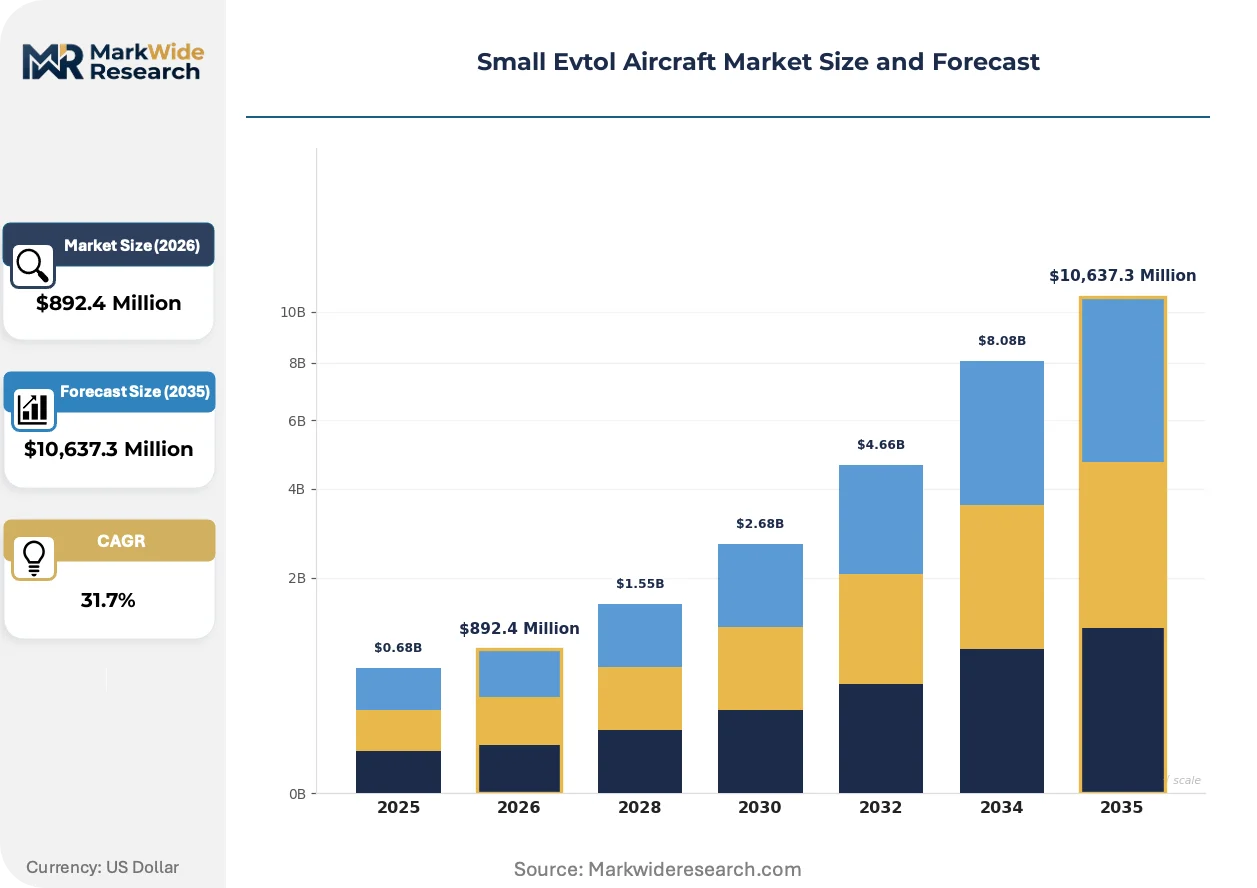
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $10,637.3 Million |
| CAGR (2026 – 2036) | 31.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger, Cargo, Surveillance, Emergency Response, Training Propulsion: Electric, Hybrid Electric, Hydrogen Fuel Cell, Turboelectric, Battery Powered Application: Urban Air Mobility, Last-Mile Delivery, Aerial Mapping, Public Safety, Infrastructure Inspection End User: Air Taxi Operators, Logistics Companies, Government Agencies, Research Institutions, Private Owners |
| Companies Covered | Joby Aviation, Beta Technologies, EHang Holdings Ltd., Airbus SE, Volocopter, Archer Aviation, Lilium, Vertical Aerospace, Embraer SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Evtol Aircraft Market Trends and Innovations
Distributed electric propulsion architectures are forcing fundamental reconsideration of airframe design paradigms, with vectored thrust configurations displacing conventional wing-borne lift for short-haul missions.
Silicon-carbide power electronics are displacing silicon IGBT modules in motor controllers, enabling switching frequencies above 50 kHz that reduce motor weight and acoustic signature. Tier 1 suppliers are converting automotive inverter production lines for aviation volumes. The structural consequence is compressing powertrain development cycles from 48 months to 24 months for derivative aircraft programs.
EASA's design-driven regulation for SC-VTOL category aircraft is creating parallel certification pathways to FAA Part 23 frameworks, fragmenting development roadmaps for multinational programs. European developers are leveraging this regulatory divergence to front-load autonomous flight control validation. The segment most affected is piloted passenger operations, where dual-certification strategies are extending timelines by 18-24 months.
Vertiport ground handling contracts are consolidating procurement decisions for fleet operators, with fixed-base operators capturing gate allocation rights before aircraft certification completion. Charter brokers and fractional ownership platforms are displacing direct airline sales as the primary channel for early commercial capacity. This channel shift is most visible in Florida and Texas, where Part 135 operator partnerships are pre-positioning for 2026 service entry.
Small Evtol Aircraft Market Segmentation
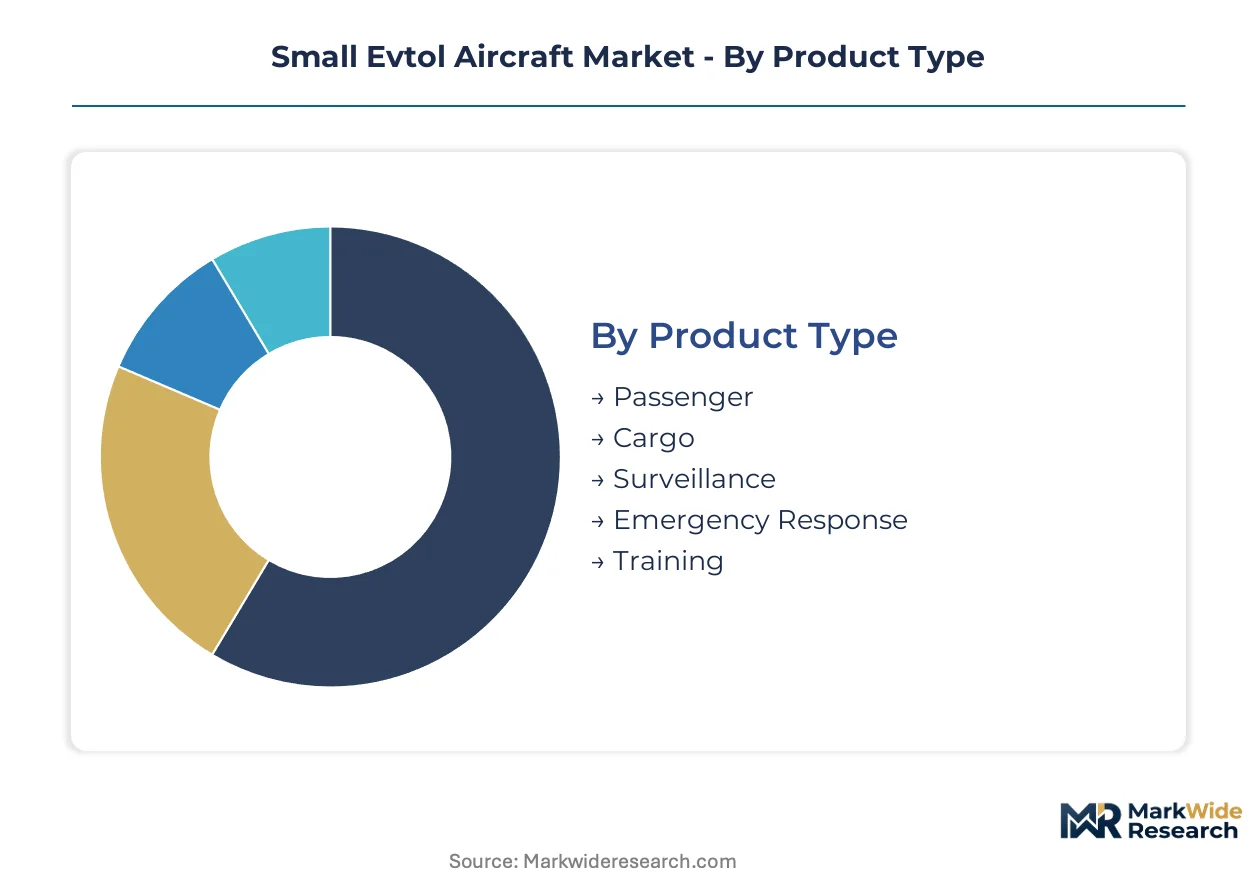
Segmentation in the small eVTOL market reveals how certification pathways, energy storage trade-offs, and operational economics fragment addressable demand across radically different buyer profiles and mission profiles.
Product Type:
Passenger configurations dominate United States development pipelines where Part 135 air carrier certification unlocks revenue service, while cargo variants find stronger traction in European and Middle Eastern markets prioritizing autonomy-first deployment.
- Passenger:Piloted configurations carrying 1-6 occupants account for the majority of FAA type certification applications currently under review. Dallas and Los Angeles metropolitan clusters are pre-positioning vertiport infrastructure specifically for air taxi services.
- Cargo:Payload capacities up to 450 kg with reduced autonomy requirements attract logistics capital seeking last-mile substitution in congested megacities. Simpler certification pathways under EASA SC-VTOL frameworks accelerate European deployment timelines relative to passenger equivalents.
- Surveillance:Persistent loiter requirements favor hybrid electric architectures where battery density falls short of endurance needs.
- Emergency Response:Medical evacuation and disaster relief applications prioritize rapid deployment over energy efficiency in early procurement decisions.
- Training:Flight school adoption remains nascent pending standardized type ratings and simulator certification.
Passenger configurations hold the largest share; momentum sits with cargo as autonomy requirements simplify regulatory pathways.
Propulsion:
Energy storage chemistry and thermal management capabilities determine which architectures can serve extended missions without ground infrastructure dependency.
- Electric:Pure battery configurations using silicon-anode solid-state cells are extending mission ranges toward 150 nautical miles. Aviation-grade cell production lines are scaling in South Korea and Japan to serve this demand.
- Hybrid Electric:Combustion range extenders address markets with limited vertiport charging density, particularly in Australian and Canadian operations spanning dispersed population centers.
- Hydrogen Fuel Cell:Proton exchange membrane systems offer theoretical energy density advantages for regional connectivity missions exceeding current battery limits.
- Turboelectric:Gas turbine generators driving distributed electric motors occupy a transitional niche where mature turbine supply chains offset battery supply constraints.
- Battery Powered:Conventional lithium-ion architectures face displacement as thermal runaway containment requirements drive adoption of solid-state alternatives.
Electric architectures dominate current development; hybrid configurations are climbing the fastest as infrastructure deployment lags fleet commitments.
Application:
Mission profile determines whether vectored thrust or lift-plus-cruise architectures deliver optimal operating economics.
- Urban Air Mobility:Point-to-point passenger transport in dense metropolitan environments favors distributed electric propulsion with minimal noise signatures. FAA Part 135 operator partnerships in Florida and Texas are concentrating early commercial deployment.
- Last-Mile Delivery:E-commerce fulfillment networks evaluate eVTOL substitution for van-based delivery where ground congestion imposes severe time penalties.
- Aerial Mapping:Survey and photogrammetry applications prioritize hover stability and payload flexibility over speed or range.
- Public Safety:Law enforcement and fire service procurement emphasizes rapid response capability with minimal pilot training transition from rotary-wing backgrounds.
- Infrastructure Inspection:Power line and pipeline surveillance missions favor extended loiter with precision station-keeping.
Urban air mobility captures the largest development investment; last-mile delivery is gaining share fastest as autonomy validation progresses.
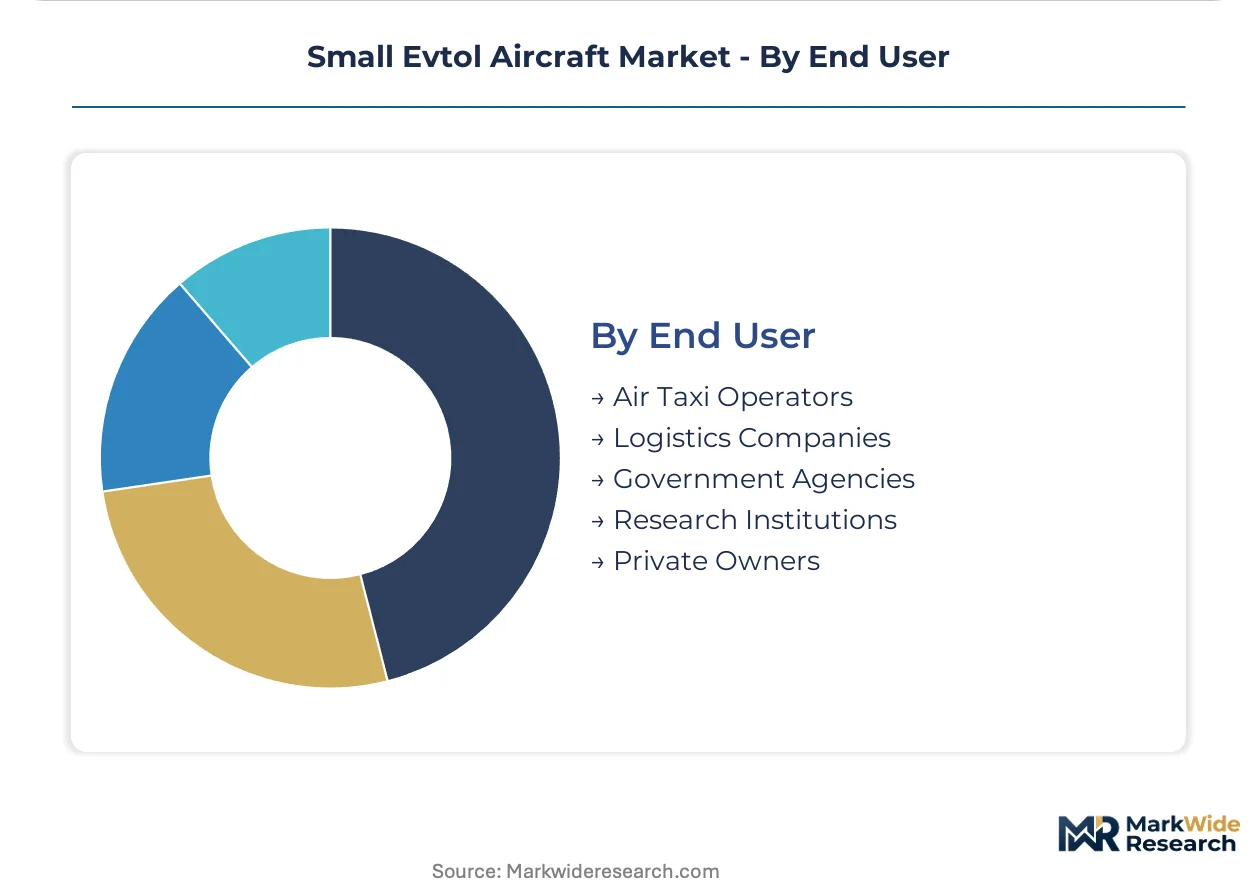
End User:
Procurement authority and capital access determine which buyer categories can absorb extended certification timelines and infrastructure co-investment requirements.
- Air Taxi Operators:Part 135 certificate holders with vertiport ground handling contracts are consolidating fleet procurement decisions ahead of individual aircraft certification. Charter brokers in Miami and Dallas are capturing gate allocation rights.
- Logistics Companies:E-commerce fulfillment networks with existing last-mile density evaluate cargo variants for congestion relief in specific metropolitan corridors.
- Government Agencies:Public safety and emergency response procurement follows separate acquisition pathways with modified airworthiness requirements.
- Research Institutions:Flight test and autonomy validation programs supply early revenue to developers before commercial certification completion.
- Private Owners:Fractional ownership platforms are displacing direct sales for high-net-worth individuals seeking access without operational burden.
Air taxi operators hold the largest committed order volume; logistics companies show the steepest expansion trajectory as cargo certification pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Air taxi operators and vertiport developers cluster in jurisdictions with compressed FAA Part 135 certification timelines. Fleet commitments concentrate where ground infrastructure investment precedes aircraft service entry.
United States
Dallas and Los Angeles metropolitan areas host the densest vertiport development clusters. FAA Part 135 air carrier certificates unlock revenue service for piloted passenger operations ahead of European counterparts. Miami and Texas urban corridors are pre-positioning ground handling contracts before 2026 service entry.
Germany
EASA SC-VTOL design-driven regulation accelerates autonomous flight control validation separate from FAA pathways. Lilium and Volocopter anchor development activity around Munich and Stuttgart aerospace clusters. The country's automotive supply base is converting power electronics production for aviation-grade silicon-carbide inverters.
China
EHang Holdings Ltd. pursues autonomous certification pathways that bypass pilot labor constraints entirely. The Civil Aviation Administration of China has issued type certificates for crewless passenger operations ahead of Western regulators. Shenzhen and Guangzhou manufacturing corridors supply distributed electric propulsion components to regional programs.
United Arab Emirates
Dubai's RTA vertiport masterplan and Abu Dhabi's regulatory sandbox create concentrated demand for piloted services. The General Civil Aviation Authority streamlines foreign operator approvals faster than EASA or FAA timelines. Dubai South logistics corridor is securing multi-site gate allocation rights ahead of fleet deliveries.
United Kingdom
Vertical Aerospace anchors development around Bristol aerospace engineering concentration. The UK CAA is negotiating bilateral recognition agreements with FAA and EASA to avoid dual-certification delays. London metropolitan airspace planning restricts early routes to outer borough corridors.
Small Evtol Aircraft Market Competitive Landscape
Player mix skews toward venture-backed airframe developers with automotive supply chain partnerships. Concentration remains moderate as certification timelines prevent early winner-take-all dynamics. Two strategic archetypes dominate: piloted passenger specialists leveraging extensive flight test data, and autonomy-first developers pursuing crewless certification pathways. Competitive moves center on vertiport ground handling contract capture and battery supply agreements with aviation-grade cell manufacturers.
Among US-based developers, Joby Aviation and Beta Technologies exemplify the piloted passenger archetype with infrastructure-integrated strategies. EHang Holdings Ltd. represents the autonomy-first pathway with regulatory approval in Chinese jurisdiction. Archer Aviation occupies a position between these vectors with hybrid certification timing. Each anchors distinct competitive positioning around certification jurisdiction selection and operational model design.
| Leading Market Players |
|---|
| Joby Aviation |
| Beta Technologies |
| EHang Holdings Ltd. |
| Airbus SE |
| Volocopter |
| Archer Aviation |
| Lilium |
| Vertical Aerospace |
| Embraer SA |
| Others |
Pricing and Supply Chain Analysis
Aviation-grade battery cell lead times stretching 18-24 months compress pricing power for airframe assemblers while amplifying cost pass-through to fleet operators, binding supply chain structure directly to contract terms.
Pricing Analysis
Cost-plus contracts indexed to copper and lithium carbonate benchmarks dominate procurement between battery pack suppliers and airframe developers. Pricing stratifies across FAA Part 135-certified configurations, EASA SC-VTOL autonomous pathways, and pre-certification development units. Cost compression in early commercial tiers intensifies as silicon-anode solid-state cells achieve aviation-grade scale. Logistics companies exhibit highest price sensitivity due to cargo variant commoditization, while air taxi operators absorb premiums for piloted passenger certification priority.
Supply Chain Analysis
Port congestion along Shanghai-to-Long Beach trade lanes elevates inbound logistics costs for power electronics and motor controller assemblies. Cathode precursor processing concentrates in China, South Korea, and Japan, drawing from Chilean and Australian spodumene deposits. Copper conductor sourcing rests on mining output constraints in Peru and Chile. Single-source vulnerability in solid-state electrolyte suppliers threatens production scaling. Distribution runs through Tier 1 aerospace integrators with automotive supply chain partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as certification pathway divergence between FAA Part 135 and EASA SC-VTOL frameworks creates distinct competitive arenas for specialized developers.
For Market Incumbents: Consolidate vertiport ground handling contract capture in Dallas and Miami metropolitan clusters to lock in gate allocation ahead of fleet deliveries. Deepen backward integration into aviation-grade battery cell supply through dedicated production line commitments with South Korean and Japanese manufacturers. Autonomous certification fast-tracks from EHang and Chinese regulators threaten piloted passenger specialists; defend through FAA flight test data accumulation and Part 135 operator exclusivity arrangements. For New Entrants and Emerging Players: EASA SC-VTOL autonomous validation fast-tracks offer regulatory arbitrage against FAA Part 23 timelines. White-space targets concentrate in UAE urban air mobility corridors where Dubai RTA vertiport masterplan streamlines foreign operator approvals. Last-mile cargo substitution in congested European megacities presents the most penetrable segment given simpler autonomy requirements. Go-to-market angle: partner with e-commerce fulfillment networks for pilot programs ahead of type certification completion. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid-state battery integration programs as thermal management and fault isolation architectures demand specialized engineering talent. Long-term viability over the next decade hinges on regulatory jurisdiction capture rather than airframe design differentiation. Acquisition target archetype: developers with aviation-grade battery management system validation and existing vertiport operator partnerships. Signal to watch: bilateral recognition agreements between FAA, EASA, and CAAC that collapse dual-certification delays.| Strategic Initiative | Industry Significance |
|---|---|
| FAA Part 135 Certification Investment | Air carrier operating certificates unlock revenue service ahead of autonomous pathway competitors. |
| Aviation-Grade Battery Supply Agreement | Dedicated cell production lines with South Korean and Japanese suppliers secure thermal management certification credit. |
| Vertiport Infrastructure Partnership | Ground handling contracts in Dallas and Miami metropolitan clusters capture gate allocation before fleet entry. |
| Autonomous Flight Control Validation | EU AI Act machine learning recognition pathways separate from deterministic software assurance favor AI-native architectures. |
| Silicon-Carbide Power Electronics Integration | Tier 1 automotive supplier partnerships compress motor controller development cycles from 48 to 24 months. |
Research Methodology
Operator-level perspectives from Part 135 certificate holders, vertiport developers, battery pack suppliers, and FAA certification teams anchored the qualitative base. Primary interviews with urban air mobility fleet planners, electric propulsion engineers, and ground infrastructure investors combined with secondary validation against FAA type certification filings, EASA SC-VTOL design-driven regulation updates, and aviation-grade cell production announcements from South Korean and Japanese manufacturers. Bottom-up aircraft delivery forecasts triangulated against top-down urban air mobility addressable demand estimates.
Sensitivity analysis framed volume and value outputs across the projection horizon, modeling propulsion architecture segmentation by energy storage chemistry, application segmentation by mission profile, and end-user segmentation by procurement authority. CAGRs derived from fleet commitment trajectories, certification timeline probability-weighting, and infrastructure deployment pacing. Forecast inputs incorporated solid-state battery energy density improvement curves and vertiport ground charging standard adoption rates.
The analysis sits within stated boundaries; outcomes outside FAA Part 135 timeline compression, EASA autonomous validation acceleration, or solid-state cell manufacturing scale would require recalibration. Forecasts reflect documented assumptions regarding regulatory jurisdiction capture and battery supply chain regionalization. Certification timeline extensions, raw material export restrictions, or ground infrastructure interoperability failures could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Nacelle Systems Market
Aircraft
Air Deflector Market
Aircraft
Global Aircraft Heat Exchanger Market
Aircraft
Vietnam Business Jets and Helicopters Market
Aircraft
Asia-Pacific Attack Helicopter Market
Aircraft
North America Military Helicopters Market
Aircraft
Australia Aviation Market
Aircraft
Latin America Business Jet Market
Aircraft
Aviation Crew Management System Market
Aircraft
Light and Very Light Jets Market
Aircraft
Aeronautical Wind Tunnel Market
Aircraft
Ultra-Light Aircraft Market
Aircraft
Commercial Aircraft in-Seat Power System Market
Aircraft
Southeast Asia Business Jet Market
Aircraft
Helicopter Flight Control Systems Market
Aircraft
Asia-Pacific Aircraft Manufacturing Market