
 Drone Turbojet Engine Market | 2026-2036
Drone Turbojet Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Turbojet Engine Market Insights
AS9100D certification is rotating the competitive landscape, filtering out suppliers lacking aerospace-quality management systems. Raytheon Technologies leverages its defense prime status to sustain integrated turbojet-avionics programs. UAV Engines Ltd. anchors the European supplier base with specialized small-engine manufacturing. PBS Velka Bites differentiates through precision-machined compressor stages for micro-turbojet applications.
A drone turbojet engine is a gas turbine propulsion system employing a single-spool or dual-spool compressor-turbine arrangement, typically generating thrust below 1,500 Newtons, with pressure ratios ranging from 3:1 to 8:1 and turbine inlet temperatures exceeding 900°C, purpose-built for unmanned aerial vehicles requiring high-speed dash capability or high-altitude endurance. Micro Turbojet systems occupy the volume tier for hand-launched tactical platforms where SWAP-C constraints dominate design trade-offs. Single-Spool architectures lead in unit economics for target drone applications, while Ceramic Matrix Composite hot-section components represent the fastest-growing technology segment as operating temperatures push material limits. Tactical Reconnaissance applications command premium pricing due to mission-critical reliability requirements and low-procurement-volume economics.
FAA airworthiness standards for unmanned systems above 55 pounds, EASA special condition frameworks for certified drone operations, and ISO 21384-3 unmanned aircraft system operational standards collectively govern market access and product qualification pathways. Defense agencies in the United States, United Kingdom, and Turkey enforce military-specific environmental qualification protocols that extend development cycles but create durable supplier relationships. Stakeholders must monitor evolving type-certification boundaries between experimental military platforms and commercially certifiable cargo delivery architectures.
Market Dynamics
AS9100D certification requirements are filtering supplier eligibility for defense procurement contracts, compressing the vendor base while elevating aerospace-quality management systems as a non-negotiable entry ticket for military turbojet programs.
Growth Catalysts
- Beyond-visual-line-of-sight waivers:FAA Part 107 expansions are unlocking commercial turbojet-powered cargo routes and infrastructure inspection missions across the United States.
- Ceramic Matrix Composites:Hot-section material advances are pushing turbine inlet temperatures past 900°C, enabling higher thrust-to-weight ratios in micro-turbojet architectures.
- NATO unmanned surveillance procurement:Member state defense budgets are accelerating adoption of high-speed reconnaissance platforms requiring compact gas turbine propulsion.
Market Restraints
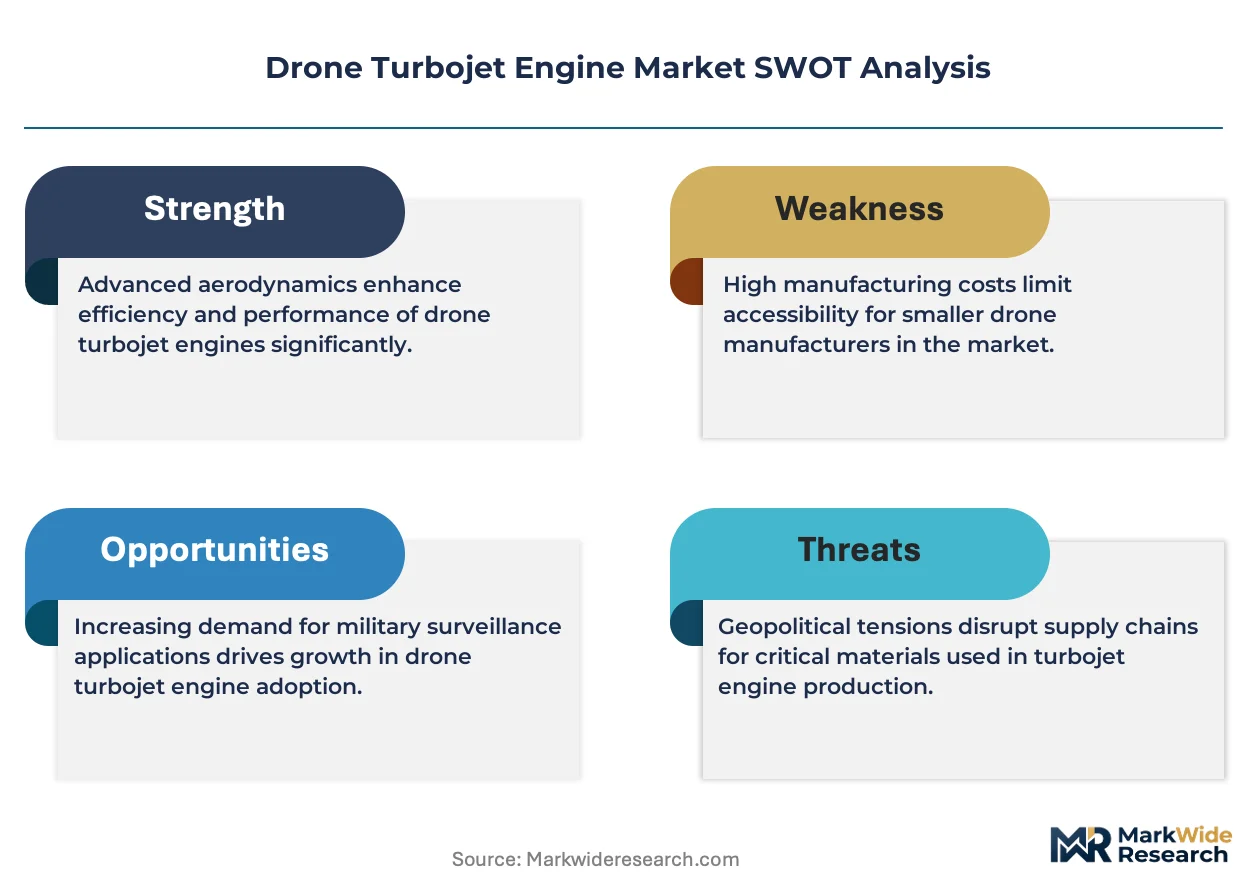
- Specialized alloy supply concentration:Nickel-based superalloy feedstock for turbine blades concentrates among a handful of European and North American foundries, creating input vulnerability.
- Extended military qualification cycles:United States, United Kingdom, and Turkish environmental testing protocols stretch development timelines by 18-36 months compared to commercial aviation standards.
- Electric propulsion substitution:Battery-powered ducted fan systems are capturing hand-launched tactical segments where endurance requirements fall below two hours.
Strategic Opportunities
- High-altitude pseudo-satellite platforms:Stratospheric endurance drones represent an emerging application requiring regenerative turbojet-electric hybrid cycles.
- EASA special condition frameworks:Certified drone operation pathways in Europe are creating first-mover advantage for turbojet systems meeting type-certification boundaries.
- Additive manufacturing convergence:Laser powder bed fusion combined with topology optimization is enabling single-piece turbine wheel geometries previously impossible to machine.
Industry Challenges
- Turbomachinery aerodynamics expertise scarcity:Specialized compressor design talent pools concentrate within legacy gas turbine OEMs, constraining startup propulsion houses.
- AS9100D certification capital intensity:Quality management system implementation demands dedicated metrology labs and traceable supply chain documentation infrastructure.
- Military-commercial certification boundary ambiguity:Stakeholders face uncertainty navigating type-certification pathways for dual-use architectures serving both defense and cargo delivery markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Turbojet Engine Market |
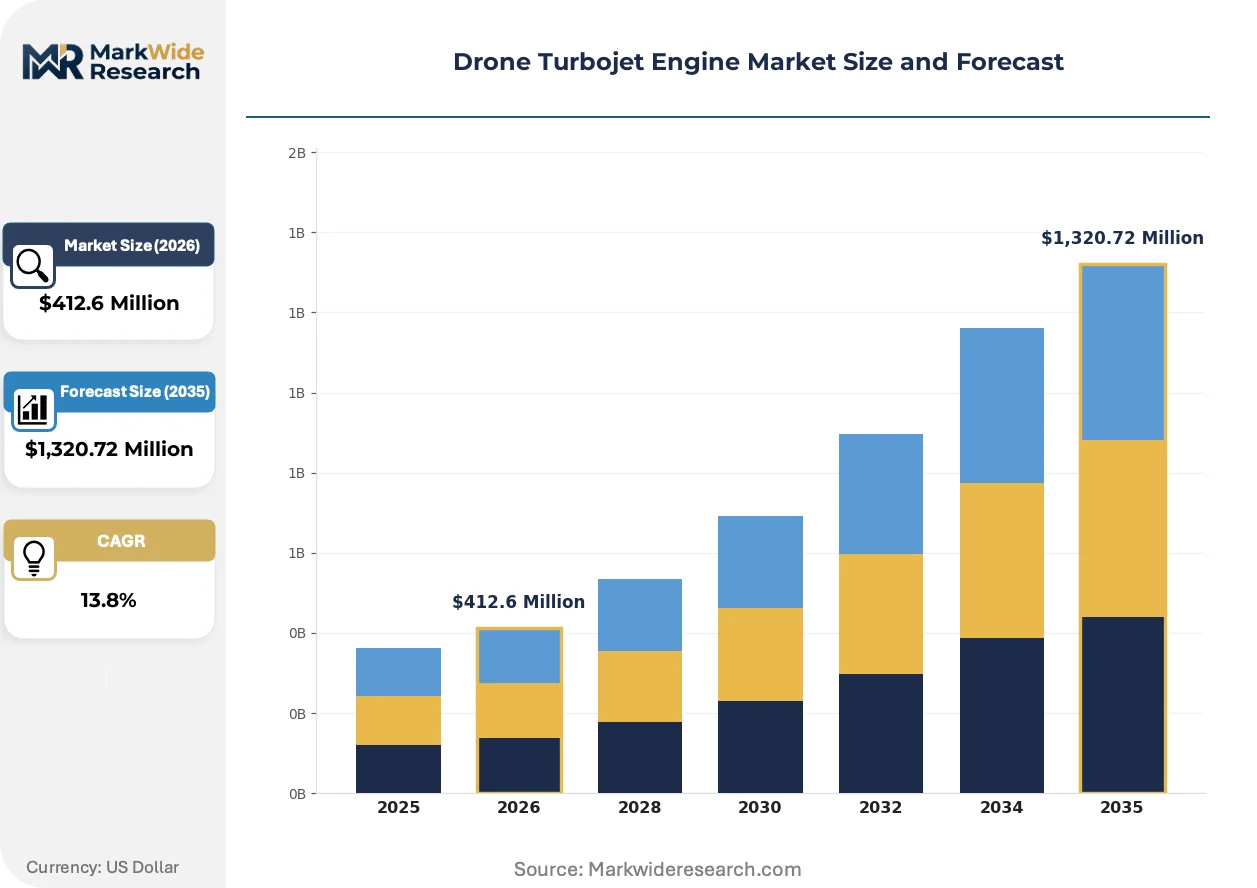
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,320.72 Million |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micro Turbojet, Small Turbojet, Medium Turbojet, High-Performance Turbojet Technology: Afterburner, Variable Cycle, Dual-Spool, Single-Spool, Ceramic Matrix Composite Application: Unmanned Surveillance, Target Drones, Cargo Delivery, Tactical Reconnaissance End User: Defense Agencies, Aerospace Manufacturers, Research Institutions, Private Drone Operators |
| Companies Covered | Raytheon Technologies, UAV Engines Ltd., Tusas Engine Industries, Accurate Automation, TEI, PBS Velka Bites, Suter Industries, Northwest UAV, Kratos Defense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Turbojet Engine Market Trends and Innovations
Ceramic Matrix Composites are displacing conventional superalloys in hot-section components, while regulatory frameworks bifurcate between experimental military platforms and commercially certifiable systems. Procurement behavior is compressing supplier qualification timelines.
Ceramic Matrix Composite turbine vanes and combustor liners tolerate operating temperatures 150-200°C above nickel-alloy limits without active cooling. Defense primes and emerging UAV propulsion houses are adopting CMC inserts for micro-turbojets below 1,500 Newtons thrust. This thermal margin is displacing conventional cooled-metal architectures in next-generation endurance platforms where fuel efficiency dictates mission economics.
EASA special condition frameworks for certified drone operations are mandating fault-tolerant control systems and redundant fuel architectures previously reserved for manned aviation. The industrial consequence is a qualification cost barrier favoring established aerospace suppliers with existing Part 21 design organization approvals. Commercial cargo delivery architectures in Germany and France are responding by partnering with defense-qualified turbojet vendors rather than developing in-house propulsion capabilities.
Defense agencies are compressing supplier qualification cycles through modular airworthiness approaches that separate engine certification from airframe integration. This unbundling disrupts traditional prime-contractor lock-in and enables engine specialists to bid directly on propulsion subsystem contracts. The United States and Turkey exhibit the most visible adoption of this procurement model, with program offices accepting engine-level AS9100D certification as sufficient for tactical platform integration.
Drone Turbojet Engine Market Segmentation
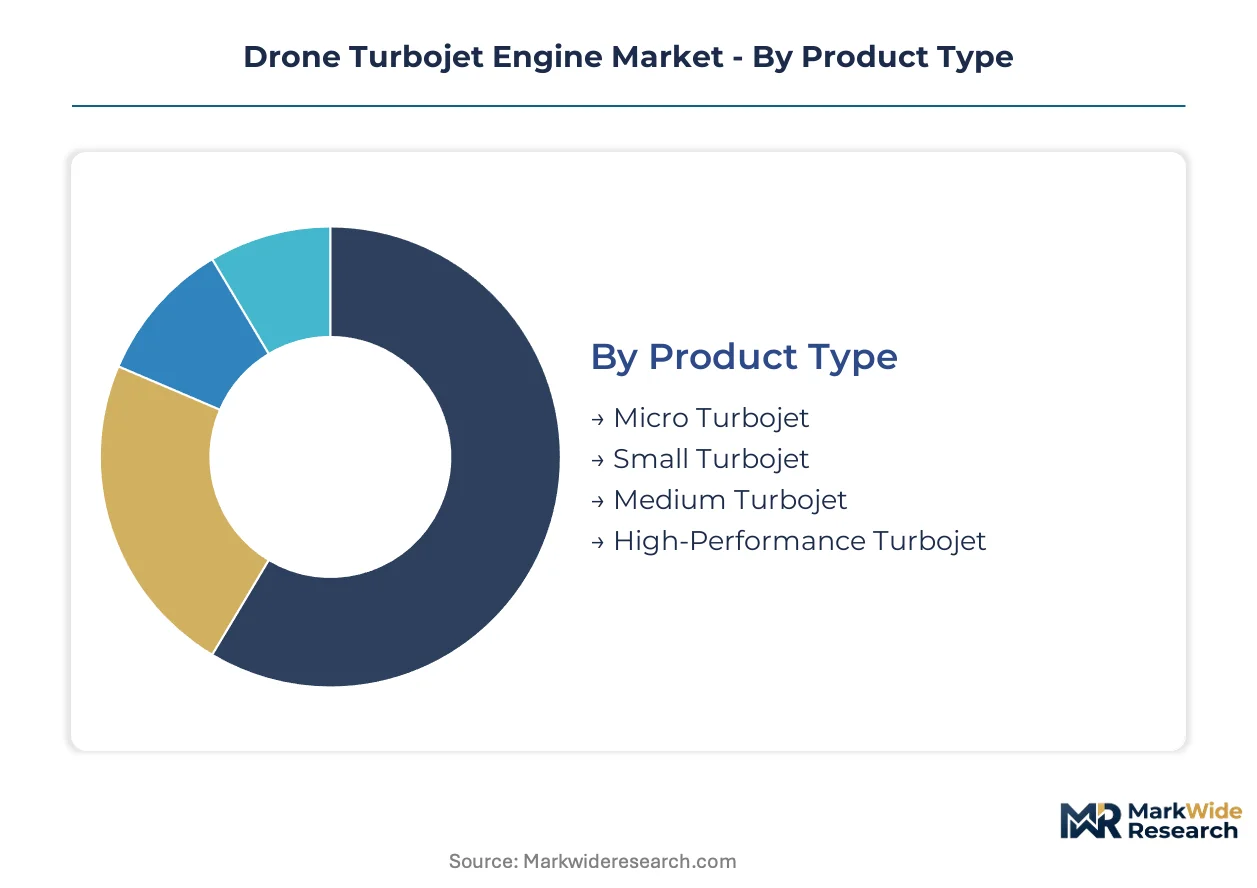
Drone turbojet engine segmentation reveals distinct procurement patterns across thrust classes and mission profiles. Defense agencies prioritize qualification-tested architectures while commercial operators chase SWAP-C optimized platforms for beyond-visual-line-of-sight routes.
Product Type:
Micro Turbojet systems dominate domestic hand-launched tactical programs in Turkey and the United Kingdom, while Medium and High-Performance variants drive export-led defense contracts to NATO member states.
- Micro Turbojet:These sub-500 Newton thrust systems employ single-stage centrifugal compressors and uncooled turbine wheels. Hand-launched tactical platforms in the United States absorb volume here, constrained by two-hour endurance limits against electric alternatives.
- Small Turbojet:Generating 500-1,000 Newtons, these engines balance pressure ratios between 4:1 and 6:1 with axial-centrifugal hybrid compressors. Target drone manufacturers in the United Kingdom concentrate procurement where unit economics favor single-spool simplicity over fuel efficiency.
- Medium Turbojet:1,000-1,500 Newton thrust class serves high-altitude endurance platforms with dual-spool architectures. Defense R&D spending in the United States sustains development here.
- High-Performance Turbojet:Exceeding 1,500 Newtons with pressure ratios above 7:1, these systems incorporate variable geometry stators. Export restrictions limit deployment outside NATO procurement channels.
Small Turbojet holds the largest share; momentum sits with Micro Turbojet as electric substitution pressures the tactical segment.
Technology:
Cost tier stratification separates legacy metal architectures from premium CMC-enabled systems commanding 40-60% thrust-to-weight premiums.
- Afterburner:Reheat augmentation for dash phases adds 30-50% thrust penalty in fuel consumption. Limited to High-Performance Turbojet integrations for supersonic target drones.
- Variable Cycle:Mode-switching between high-thrust and high-efficiency operating lines. Complex actuation systems restrict adoption to defense-funded programs in the United States with extended development timelines.
- Dual-Spool:Separate high-pressure and low-pressure spools optimize compressor matching across flight envelopes. Ceramic Matrix Composite hot-section inserts are climbing the fastest in this architecture class as turbine inlet temperatures push past 900°C.
- Single-Spool:One rotating assembly minimizes part count and maintenance burden. Dominates target drone applications where acquisition cost outweighs fuel burn penalties.
- Ceramic Matrix Composite:Silicon carbide fiber-reinforced matrices tolerate 150-200°C thermal margins above nickel superalloys. Qualification cycles with the FAA and military environmental protocols in the United States and Turkey extend adoption timelines.
Single-Spool dominates unit volume; Ceramic Matrix Composite commands the steepest expansion trajectory as operating temperatures climb.
Application:
Customer type bifurcation separates mission-critical defense specifications from commercial cargo operators navigating EASA special condition frameworks.
- Unmanned Surveillance:Persistent orbital platforms demand 8-12 hour endurance with loiter-efficient throttle response. NATO member state procurement in Germany and France concentrates here, requiring AS9100D-certified propulsion subsystems.
- Target Drones:Expendable platforms prioritize unit production cost over fuel efficiency. Single-spool Micro Turbojet architectures from suppliers in the United Kingdom satisfy volume requirements.
- Cargo Delivery:Beyond-visual-line-of-sight waivers from the FAA unlock commercial routes in the United States. Payload-range requirements favor Medium Turbojet thrust classes with fault-tolerant fuel systems.
- Tactical Reconnaissance:High-speed dash capability above 400 knots distinguishes this segment. Premium pricing reflects low procurement volumes and military-specific environmental qualification protocols.
Unmanned Surveillance captures the largest revenue pool; Cargo Delivery is gaining share fastest as FAA Part 107 expansions accelerate.
End User:
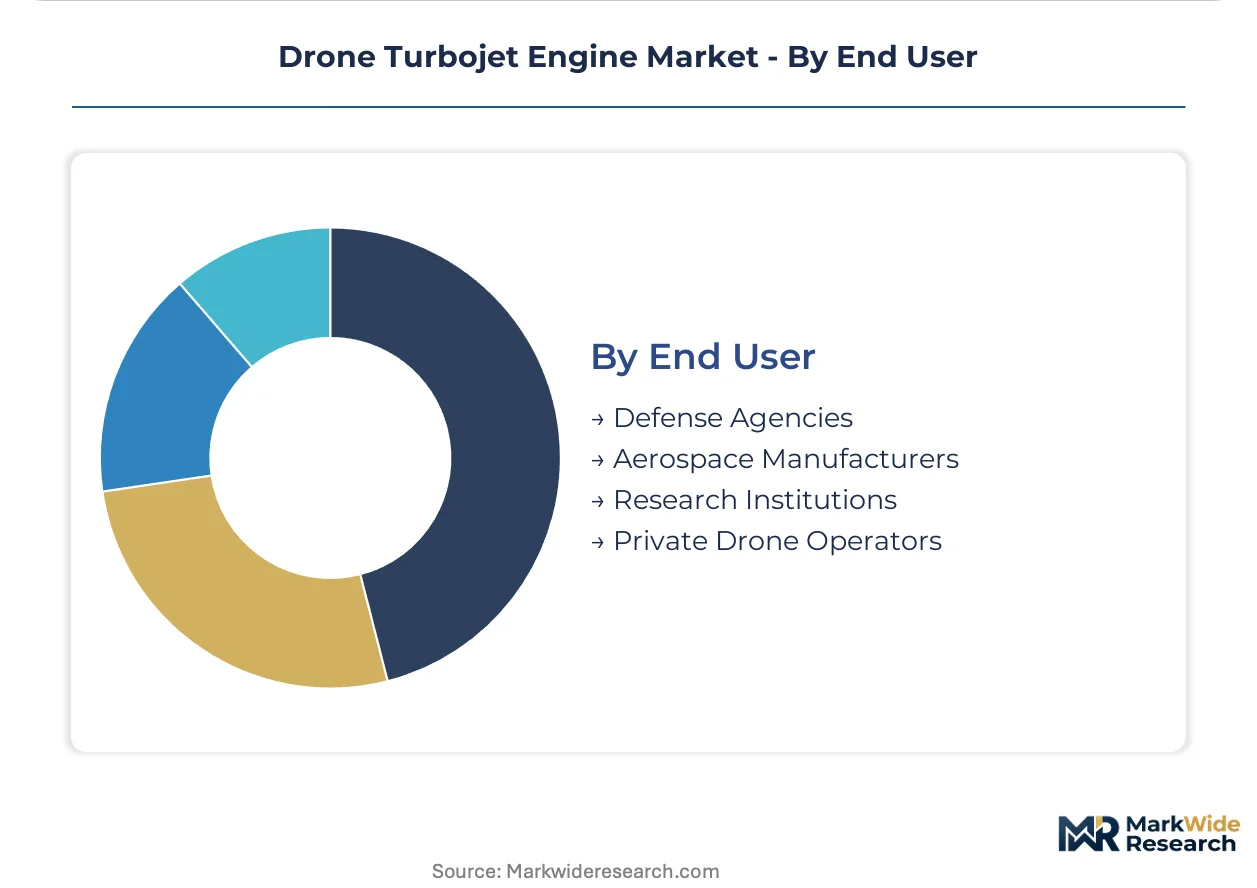
Supply concentration concentrates with defense primes and captive engine houses, while research institutions and private operators fragment procurement across boutique suppliers.
- Defense Agencies:The United States Department of Defense, United Kingdom Ministry of Defence, and Turkish Defense Ministry enforce military-specific environmental testing protocols. These 18-36 month qualification cycles create durable supplier relationships with AS9100D-certified vendors.
- Aerospace Manufacturers:Raytheon Technologies and tier-one primes integrate turbojet-avionics programs in-house. Modular airworthiness approaches in the United States now permit direct engine-level contracting.
- Research Institutions:Universities and national laboratories prototype additive-manufactured turbine wheels. Small-batch procurement lacks volume to justify dedicated production lines.
- Private Drone Operators:Commercial cargo ventures in Germany and France partner with defense-qualified vendors rather than developing proprietary propulsion. EASA special condition frameworks mandate redundant architectures that elevate qualification costs.
Defense Agencies command the largest share; Private Drone Operators are climbing fastest as certified cargo pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices and commercial cargo operators concentrate order flow in jurisdictions with mature aerospace certification infrastructure and permissive beyond-visual-line-of-sight regulatory frameworks.
United States
FAA Part 107 waiver expansions are unlocking commercial turbojet-powered cargo routes across Texas and Arizona test corridors. The Department of Defense sustains R&D spending through DARPA and service laboratories concentrated in California and Virginia. Modular airworthiness approaches now permit engine-level AS9100D certification as sufficient for tactical platform integration.
Turkey
Turkish Defense Ministry procurement programs are accelerating adoption of high-speed reconnaissance platforms requiring compact gas turbine propulsion. Military-specific environmental testing protocols stretch development timelines but create durable supplier relationships with certified vendors. Ankara-based engine houses and Izmir aerospace clusters anchor domestic manufacturing capacity for hand-launched tactical systems.
Germany
EASA special condition frameworks for certified drone operations are mandating fault-tolerant control systems previously reserved for manned aviation. Commercial cargo delivery architectures in Bavaria and Baden-Württemberg partner with defense-qualified turbojet vendors rather than developing proprietary propulsion. Munich-area primes integrate turbojet-avionics programs for NATO export markets.
United Kingdom
Ministry of Defence target drone programs concentrate procurement on single-spool architectures where unit economics favor simplicity over fuel efficiency. UAV Engines Ltd. anchors the domestic supplier base with specialized small-engine manufacturing in Staffordshire. AS9100D certification requirements filter supplier eligibility for defense contracts, compressing the vendor base.
France
Persistent orbital platforms for unmanned surveillance demand 8-12 hour endurance with loiter-efficient throttle response from defense primes in the Île-de-France region. EASA type-certification boundaries favor established aerospace suppliers with existing Part 21 design organization approvals. Toulouse-area clusters concentrate systems integration expertise for stratospheric endurance applications.
Drone Turbojet Engine Market Competitive Landscape
Player mix skews toward defense-integrated primes and specialized engine houses with aerospace-quality certifications. Market structure concentrates around vendors possessing AS9100D credentials and military environmental qualification experience. Two strategic archetypes dominate: captive propulsion divisions of defense primes, and independent specialists focused on micro-turbojet architectures. Competitive moves center on modular airworthiness partnerships and ceramic matrix composite technology licensing.
Within the defense-integrated tier, Raytheon Technologies and Kratos Defense represent prime-contractor propulsion strategies leveraging existing military relationships. Among European specialists, UAV Engines Ltd. and PBS Velka Bites occupy positions as qualified suppliers to NATO procurement channels. Tusas Engine Industries anchors the Turkish supplier base with domestic manufacturing credentials. These named entities exemplify the bifurcation between scale-driven defense primes and boutique engine houses competing on qualification speed.
| Leading Market Players |
|---|
| Raytheon Technologies |
| UAV Engines Ltd. |
| Tusas Engine Industries |
| Accurate Automation |
| TEI |
| PBS Velka Bites |
| Suter Industries |
| Northwest UAV |
| Kratos Defense |
| Others |
Pricing and Supply Chain Analysis
AS9100D certification gates both supplier qualification and price differentiation simultaneously, compressing the vendor base into aerospace-quality management tiers while elevating certified architectures above uncertified alternatives in military procurement channels. Defense agencies in the United States and Turkey pay premiums for environmental qualification completion, whereas commercial cargo operators in Germany negotiate on fault-tolerant system bundling.
Pricing Analysis
Cost-plus contracts with nickel-based superalloy indexation dominate defense procurement, insulating foundries from raw material volatility while passing through alloy feedstock swings to prime contractors. Pricing stratifies across AS9100D-certified premium tiers, single-spool standard architectures, and expendable economy tiers for target drones. Cost compression in the tactical segment intensifies because electric propulsion substitutes erode turbojet volumes below 500 Newtons. Target drone manufacturers exhibit highest price sensitivity; tactical reconnaissance platforms show lowest sensitivity due to mission-critical reliability requirements.
Supply Chain Analysis
Strait of Hormuz transit vulnerability concentrates nickel superalloy feedstock dependence on European and North American foundries, with turbine blade casting capacity clustering in the United States, United Kingdom, and Germany. Compressor machining draws from precision aerospace clusters in the Czech Republic and Turkey. Single-source vulnerability runs through specialized alloy suppliers qualified to military environmental protocols. Distribution runs through defense prime captive channels and direct engine-level contracting under modular airworthiness approaches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from electric substitution pressure in tactical segments, with cyclical rebound tied to FAA Part 107 waiver expansions unlocking commercial cargo route economics.
For Market Incumbents: Compound defensive positioning by deepening ceramic matrix composite licensing partnerships and accelerating additive manufacturing qualification for turbine wheel geometries. Electric propulsion substitution in hand-launched platforms demands counter-moves through hybrid-electric architecture development. Vertical integration into nickel superalloy casting capacity insulates against foundry concentration risk. For New Entrants and Emerging Players: Lead with stratospheric endurance platforms where regenerative turbojet-electric cycles face limited incumbent lock-in. High-altitude pseudo-satellite applications in the United States represent the most penetrable white-space segment. Partner with defense-qualified vendors for EASA special condition certification rather than pursuing proprietary propulsion development. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across ceramic matrix composite hot-section manufacturing as turbine inlet temperatures push past 900°C. Long-term viability favors acquisition targets possessing AS9100D credentials and military environmental qualification experience with completed Turkish or United States defense programs. Watch FAA type-certification boundary clarity for dual-use cargo-defense architectures as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Matrix Composite Licensing | Silicon carbide fiber technology transfers enable 150-200°C thermal margins above nickel superalloys. |
| Additive Manufacturing Qualification | Laser powder bed fusion of single-piece turbine wheels reduces part count for micro-turbojet architectures. |
| Modular Airworthiness Partnership | Engine-level AS9100D certification unbundles propulsion from airframe integration in United States procurement. |
| Hybrid-Electric Architecture Development | Regenerative cycles address stratospheric endurance requirements for pseudo-satellite platforms. |
| Defense Prime Channel Integration | Direct contracting with Raytheon Technologies and Kratos Defense locks in tactical platform order flow. |
Research Methodology
Desk research of FAA Part 107 waiver filings, DARPA program announcements, and EASA special condition frameworks preceded structured interviews with turbojet propulsion engineers, defense procurement officers, and ceramic matrix composite materials scientists. Secondary validation drew from Department of Defense budget justifications, NATO procurement databases, and AS9100D registrar records. Bottom-up segment sizing triangulated against top-down defense R&D spending allocation models.
Variance decomposition across thrust class, technology architecture, and application mission profile shaped the analytical framework over the projection horizon. Modeled dimensions included product type segmentation, Ceramic Matrix Composite penetration rates, and end-user procurement channel concentration. CAGRs derived from segment-level volume build-ups validated against macro defense spending and commercial cargo route expansion assumptions. Forecast inputs incorporated nickel superalloy price trajectories and electric propulsion substitution elasticity estimates.
The analysis sits within stated boundaries; outcomes outside sustained FAA waiver expansion or ceramic matrix composite qualification acceleration would require recalibration. Forecasts reflect documented assumptions regarding defense budget continuity and EASA type-certification pathway clarity. Practitioners should keep alternative scenarios live as electric propulsion energy density improvements and military procurement cycle timing evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Airship Market
Aircraft
Asia-Pacific Aircraft Windshield Wiper and Washer System Market
Aircraft
Europe Turboprop Aircraft Market
Aircraft
Asia-Pacific Turboprop Aircraft Market
Aircraft
Ultra-Light Aircraft Market
Aircraft
Aircraft Door Market
Aircraft
Helicopter Flight Control Systems Market
Aircraft
Air Speed Indicator Market
Aircraft
Asia-Pacific Helicopters Market
Aircraft
Global Helicopter Market
Aircraft
Winglets Market
Aircraft
Evtol (Electric Vertical Takeoff and Landing) Airplane Market
Aircraft
South Korea Aerospace and Defense Market
Aircraft
Civil Helicopter Market
Aircraft
Japan Aircraft Windshield Wiper and Washer System Market
Aircraft
India Aviation Market