
 Africa Space Propulsion System Market | 2026-2036
Africa Space Propulsion System Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Space Propulsion System Market Analytics
Software-defined thrust vectoring is pivoting what African space programs purchase, shifting capital expenditure from fixed hardware to upgradable control architectures. Safran SA leverages its electric propulsion heritage to compete for satellite bus contracts with Nigeria and Egypt. Astrofica Technologies anchors its position through indigenous thruster manufacturing in Addis Ababa. Panafric Space specializes in cold gas systems for university-led CubeSat missions across East Africa.
A space propulsion system generates thrust through controlled expulsion of propellant mass to alter spacecraft velocity, attitude, or orbital parameters, typically achieving specific impulse values from seconds for cold gas systems to thousands of seconds for gridded ion thrusters. Chemical propulsion retains dominance in launch vehicle main stages due to its high thrust-to-weight ratio, while electric propulsion segments capture expanding margin pools from geostationary satellite station-keeping contracts. Government agencies constitute the primary end user category, absorbing systems through national space program budgets rather than commercial procurement channels.
Nigeria's National Space Research and Development Agency and South Africa's National Regulator for Compulsory Specifications shape product standards for propellant handling and launch site safety across the continent. Egypt's Egyptian Space Agency coordinates with the country's military technical regulator to define defense satellite propulsion requirements. Stakeholders must monitor how harmonization between national space laws and the African Union's nascent space policy framework affects cross-border component trade and technology transfer licensing.
Market Dynamics
Software-defined thrust vectoring is compressing capital cycles across African space programs, forcing procurement offices to reallocate budgets from fixed hardware toward upgradable control architectures that extend satellite operational lifespans without physical retrofit.
Growth Catalysts
- Earth observation constellations:Government agencies in Nigeria and South Africa are procuring propulsion systems for national security and agricultural monitoring satellites, creating sustained demand for station-keeping thrusters.
- African Union space policy harmonization:The continental framework is reducing cross-border component trade barriers, enabling Egyptian and Ethiopian manufacturers to supply thruster subsystems to West African satellite programs.
- Green propellant formulations:Advances in ammonium dinitramide-based monopropellants are displacing hydrazine across university-led CubeSat missions, lowering handling costs and launch site insurance premiums.
Market Restraints
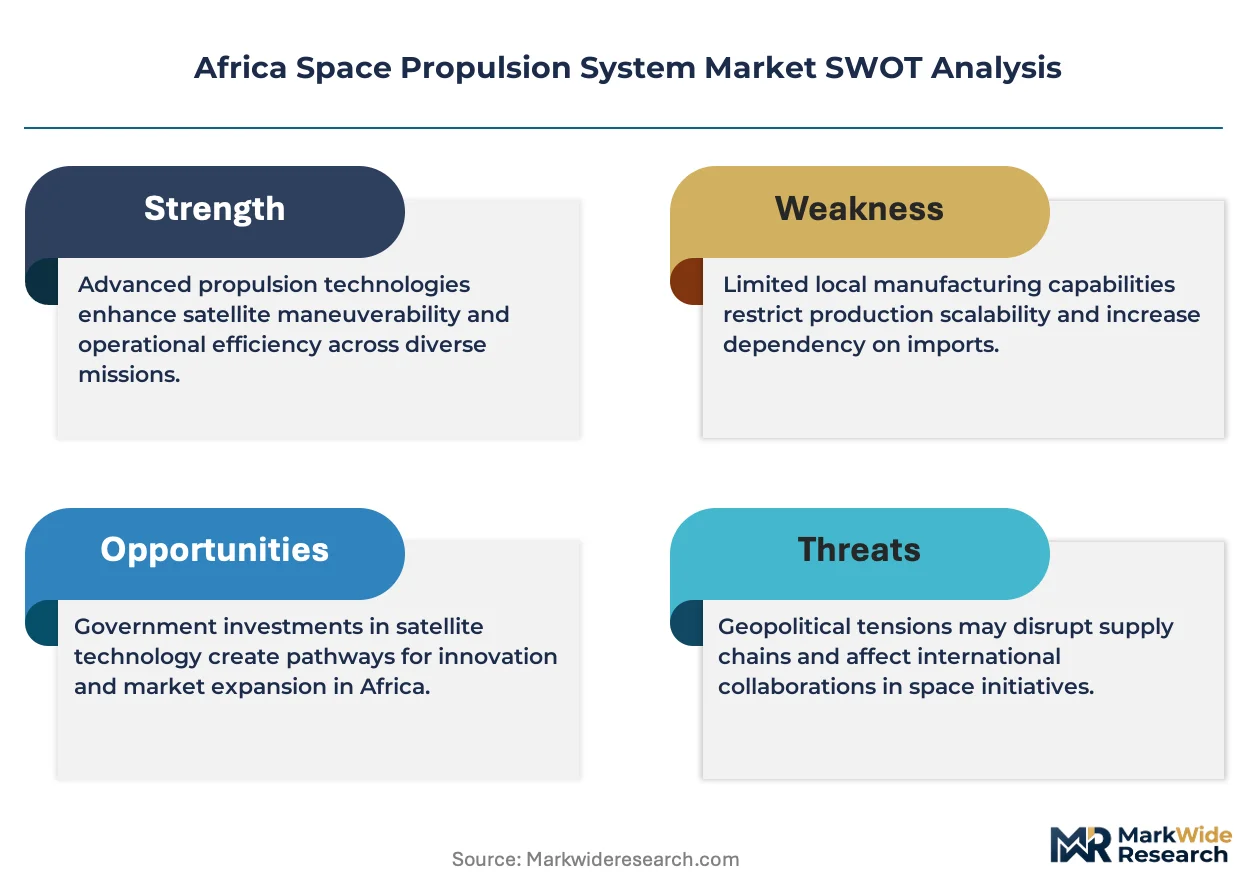
- Propellant supply concentration:Hydrazine and high-test peroxide imports depend on European and Asian chemical suppliers, exposing programs to currency volatility and shipping delays through the Cape of Good Hope route.
- Launch site infrastructure gaps:No African territory operates an orbital launch facility with integrated propellant loading capabilities, forcing satellite operators to ship fueled spacecraft to French Guiana or Kazakhstan.
- Technical workforce scarcity:Cryogenic system engineering and plasma physics expertise concentrates in South Africa and Egypt, leaving East and West African programs dependent on foreign contractors for electric propulsion integration.
Strategic Opportunities
- CubeSat propulsion standardization:The absence of continental interface standards for 1U-3U satellite thrusters creates first-mover advantage for indigenous manufacturers establishing de facto specifications.
- Defense satellite acceleration:Egypt's military technical regulator is expanding classified procurement channels for dual-use propulsion systems, opening parallel demand streams beyond civilian space agency budgets.
- Additive manufacturing convergence:Titanium alloy 3D printing and topology optimization software are collapsing thruster component lead times from months to weeks for Nairobi and Addis Ababa production facilities.
Industry Challenges
- Propulsion system qualification timelines:Thermal vacuum testing and vibration qualification for African-built thrusters require access to European Space Agency facilities in the Netherlands, creating 18-24 month certification bottlenecks.
- Technology transfer licensing complexity:French and Russian export control frameworks restrict gridded ion thruster know-how, forcing Nigerian and Algerian programs to develop Hall-effect alternatives from open literature.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Space Propulsion System Market |
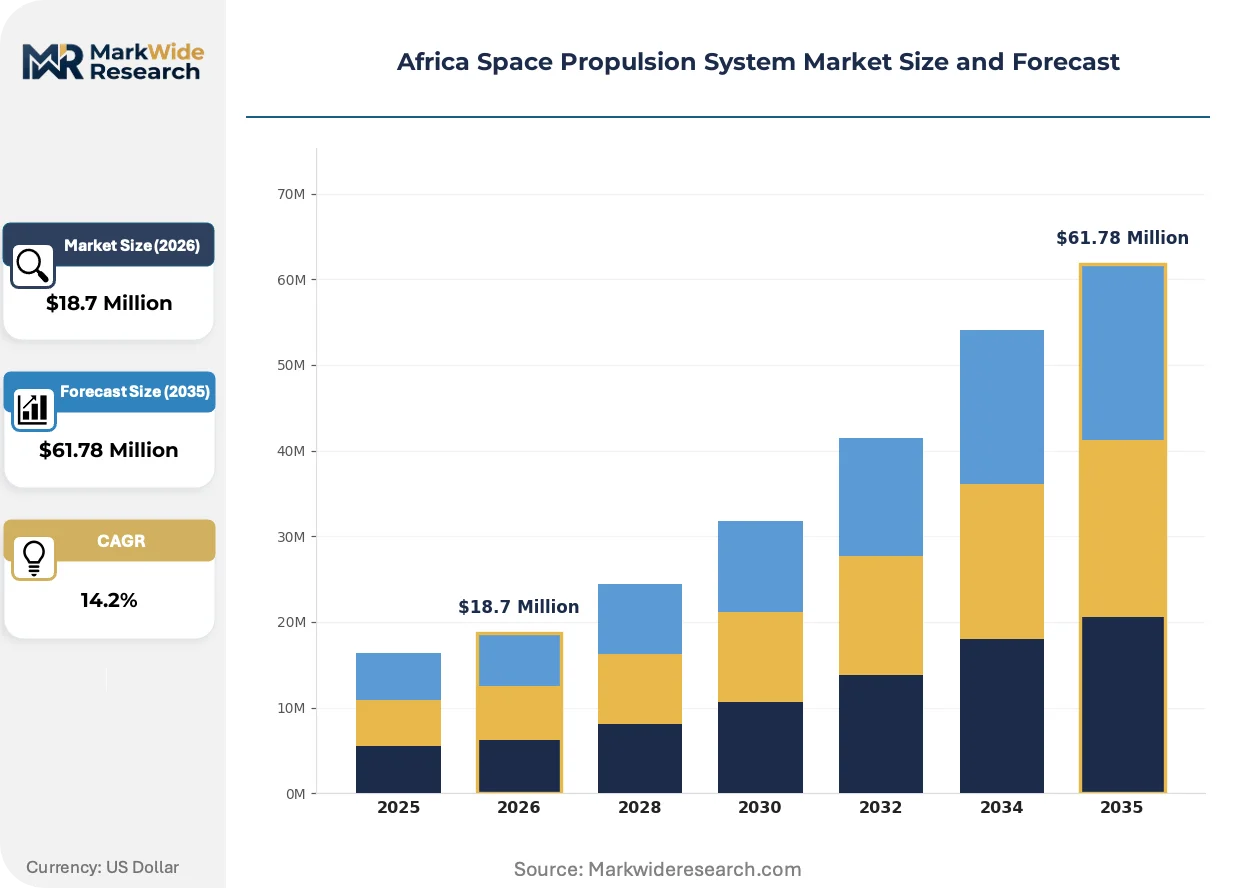
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $61.78 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Chemical Propulsion, Electric Propulsion, Hybrid Propulsion, Cold Gas Propulsion Application: Satellite Launch, Interplanetary Missions, Orbital Maneuvering, Space Exploration End User: Government Agencies, Private Companies, Research Institutions, Defense Organizations Component: Thrusters, Propellant Tanks, Control Systems, Nozzles |
| Companies Covered | Northrop Grumman Corporation, Safran SA, Space Exploration Technologies Corp, IHI Corporation, L3Harris Technologies, Inc., Astrofica Technologies, Panafric Space, Angel Technology, African Geospace, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Space Propulsion System Market Evolving Landscape
Thrust vector control architectures are migrating from analog hydraulic actuators to software-defined electric motor systems, compressing subsystem mass and enabling in-orbit reprogramming that extends mission flexibility without hardware replacement.
Monopropellant thruster designs using low-toxicity LMP-103S are consolidating market share among university and research satellite operators who lack hydrazine handling licenses. Nigeria's National Space Research and Development Agency has adopted this chemistry for its next-generation Earth observation bus. The shift is consolidating procurement patterns around pre-packaged, qualified thruster modules rather than custom-built systems.
South Africa's National Regulator for Compulsory Specifications is drafting continent-first standards for propellant storage and transport safety, modeled partially on European REACH chemical handling protocols. The regulations will mandate secondary containment and automated leak detection for all ground-based propellant facilities. Satellite operators in Cape Town and Pretoria are pre-emptively retrofitting existing infrastructure to avoid operational interruptions when enforcement begins.
University-led CubeSat programs are displacing traditional prime contractor relationships with direct component sourcing from specialized thruster manufacturers. East African engineering faculties in Kenya and Uganda now procure cold gas systems through online technical marketplaces rather than national space agency intermediaries. This channel fragmentation is most visible in Nairobi, where Astrofica Technologies maintains direct sales relationships with fifteen academic institutions across four countries.
Africa Space Propulsion System Market Segmentation
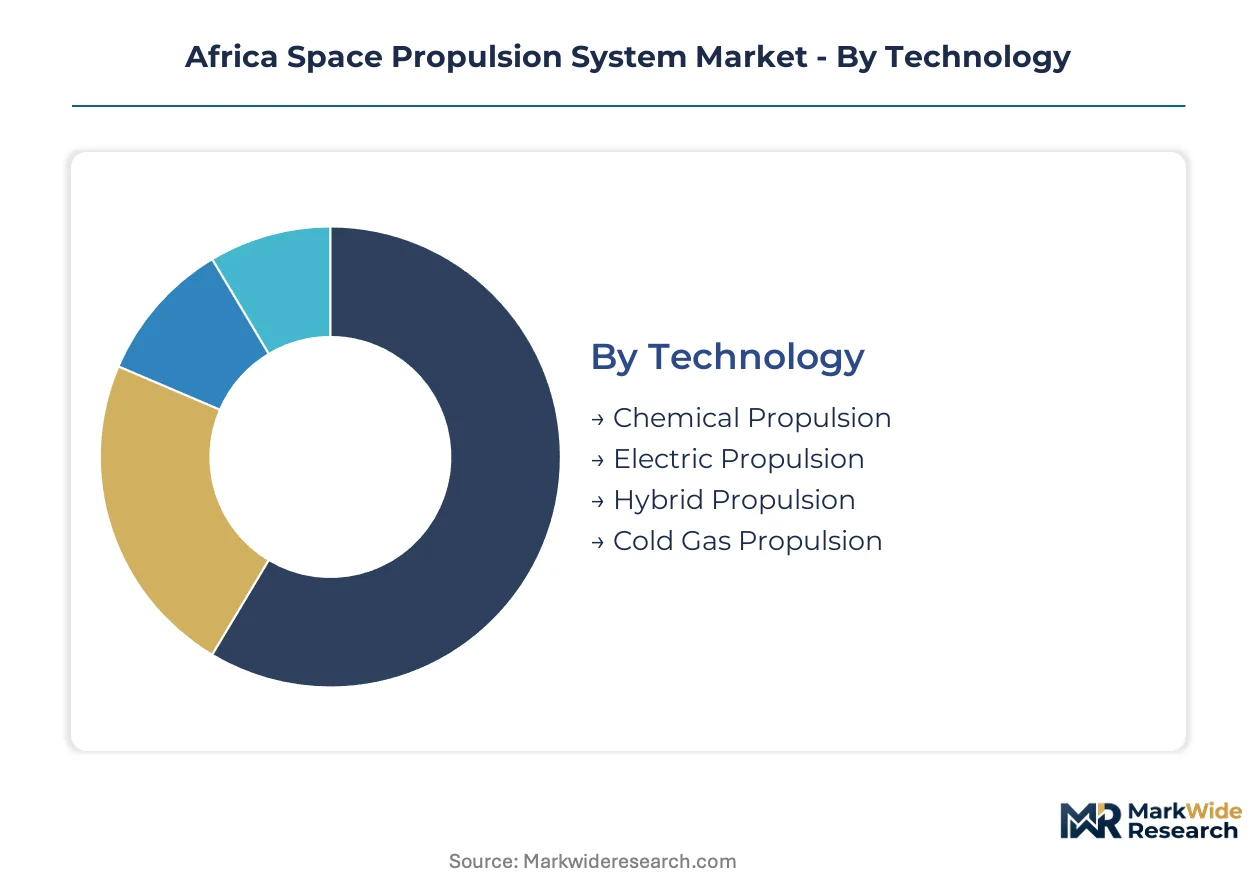
Propulsion system procurement across African space programs fragments along technical maturity curves and institutional risk appetites. Chemical systems dominate near-term launch manifests while electric alternatives capture long-duration mission budgets. Understanding where each segment concentrates purchasing authority reveals which technology pathways national agencies will fund.
Technology:
Customization intensity spans from fully configurable chemical stacks to standardized electric thruster modules that agencies procure off-catalog.
- Chemical Propulsion:Bi-propellant and monopropellant systems using hydrazine or green alternatives deliver high thrust-to-weight ratios essential for orbital insertion burns. Nigeria's National Space Research and Development Agency procures these systems for Earth observation satellites requiring rapid altitude changes. Handling infrastructure costs and propellant toxicity licensing constrain adoption outside South Africa and Egypt.
- Electric Propulsion:Gridded ion and Hall-effect thrusters achieve specific impulse values exceeding chemical alternatives by an order of magnitude, enabling station-keeping with minimal propellant mass. Egyptian and Algerian programs are developing indigenous Hall-effect variants to circumvent French export controls on gridded ion technology. Satellite operators prioritize these systems for geostationary communications platforms.
- Hybrid Propulsion:Combines solid fuel grains with liquid oxidizers, offering throttle flexibility absent in pure solid systems. South African testing facilities evaluate hybrid configurations for suborbital sounding rockets.
- Cold Gas Propulsion:Compressed nitrogen or argon systems provide precise attitude control for CubeSat missions. University programs in Kenya and Uganda source these through direct manufacturer relationships bypassing national procurement channels.
Most installed capacity flows through Chemical Propulsion. Expansion is steepest in Electric Propulsion.
Application:
Cost tiering separates capital-intensive launch services from operational maneuvering contracts that agencies fund through recurring budgets.
- Satellite Launch:Main stage and upper stage propulsion for orbital insertion dominates procurement volumes. Government agencies in Nigeria and South Africa fund national security and agricultural monitoring constellations. Launch service contracts bundle propulsion with vehicle integration, concentrating purchasing power with prime contractors.
- Orbital Maneuvering:Station-keeping, de-orbit, and collision avoidance burns sustain demand for low-thrust, high-efficiency systems. Egyptian Space Agency specifications mandate orbital maneuvering capability for all domestically manufactured satellites. Electric propulsion adoption is climbing fastest in this application.
- Interplanetary Missions:Deep-space trajectory correction and planetary orbit insertion require multi-year propulsion reliability. No African agency has funded independent interplanetary capability, though South African research institutions participate in international consortium missions.
- Space Exploration:Crewed spacecraft and sample return missions demand human-rated propulsion with abort capabilities. This application remains aspirational for African programs lacking launch vehicle infrastructure.
Current procurement concentrates in Satellite Launch. Orbital Maneuvering is gaining share fastest as on-orbit satellite populations expand.
End User:
Customer type determines contracting mechanisms, with government agencies using sovereign procurement frameworks while private operators negotiate commercial terms.
- Government Agencies:National space programs in Nigeria, South Africa, Egypt, and Ethiopia absorb systems through sovereign budgets rather than commercial channels. Procurement frameworks emphasize technology transfer and local manufacturing requirements. These agencies specify propulsion performance standards that cascade to subsystem suppliers.
- Defense Organizations:Egypt's military technical regulator operates classified procurement channels for dual-use satellite propulsion. Defense budgets bypass civilian space agency oversight, creating parallel demand streams with distinct security clearance requirements.
- Research Institutions:Universities in Kenya, Uganda, and Ghana source CubeSat propulsion through direct manufacturer relationships. Funding constraints favor cold gas and green monopropellant systems over hydrazine alternatives.
- Private Companies:Commercial satellite operators in South Africa and Nigeria procure propulsion as part of turnkey satellite bus contracts. Market presence remains limited by absence of indigenous launch infrastructure.
Government Agencies command the largest installed base. Defense Organizations are expanding procurement most quickly.
Component:
Supply concentration varies from commoditized propellant tanks to specialized thruster assemblies requiring qualification testing.
- Thrusters:Combustion chambers, injectors, and expansion nozzles constitute the highest-value subsystem. Additive manufacturing is collapsing lead times for titanium alloy thruster bodies at Nairobi and Addis Ababa production facilities. Thermal vacuum qualification remains a bottleneck requiring European Space Agency facility access.
- Propellant Tanks:Titanium or composite overwrapped pressure vessels store propellant and pressurant gases. Tank design interfaces directly with thruster feed system architecture, creating specification dependencies.
- Control Systems:Valves, regulators, and software-defined thrust vectoring electronics manage propellant flow and engine orientation. Migration from hydraulic to electric actuation is compressing subsystem mass and enabling in-orbit reprogramming.
- Nozzles:Expansion geometries optimize exhaust velocity for specific impulse targets. Regeneratively cooled designs dominate high-thrust chemical applications while radiatively cooled alternatives serve electric propulsion.
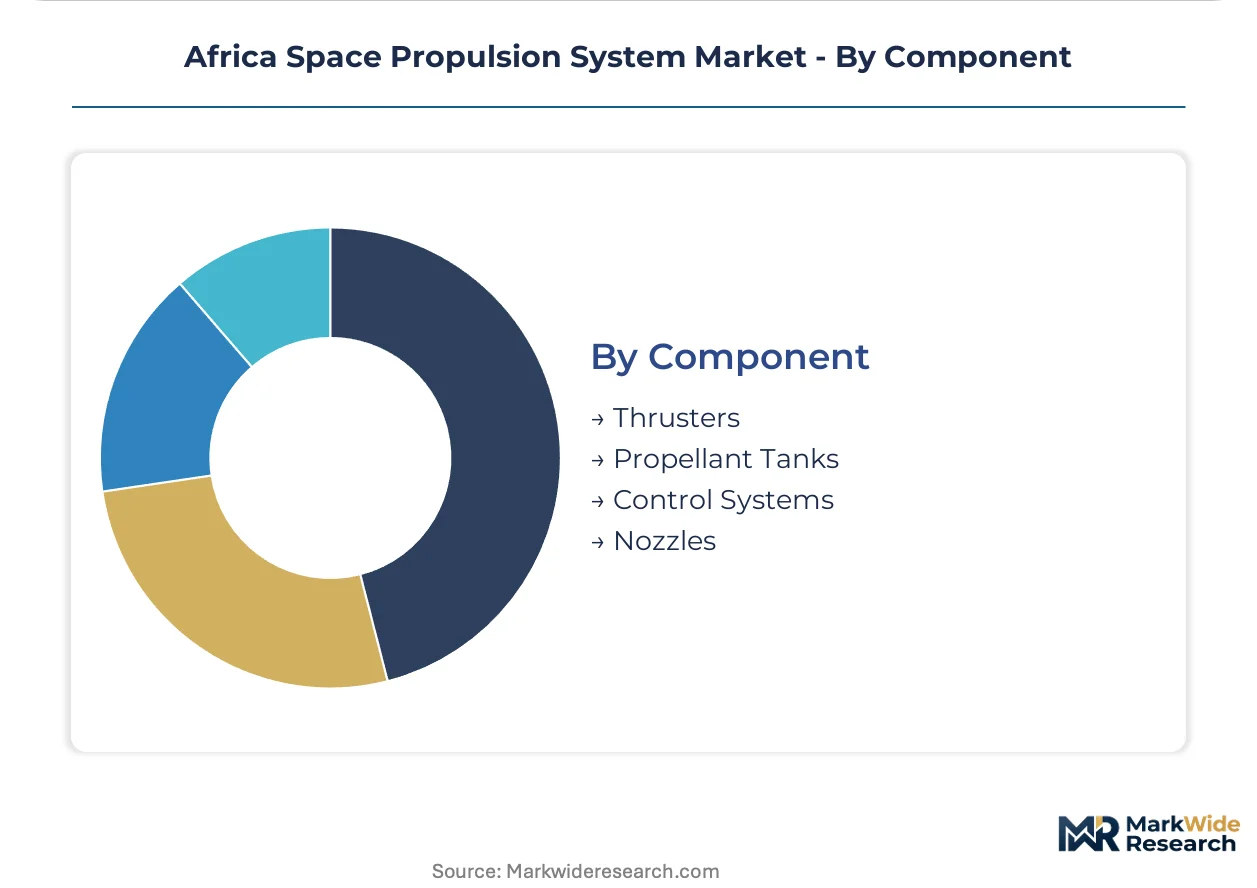
Thrusters absorb the largest share of component spending. Control Systems are climbing fastest as software-defined architectures displace fixed hardware.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nigeria's procurement frameworks concentrate demand in West Africa while South Africa's testing infrastructure anchors Southern African capability development, creating divergent investment patterns across the continent.
Nigeria
The National Space Research and Development Agency drives procurement for Earth observation constellations used in national security and agricultural monitoring. The agency's adoption of LMP-103S green monopropellant chemistry for next-generation satellite buses shapes subsystem specifications across West African programs. Abuja hosts the primary coordination hub where technology transfer requirements cascade to international suppliers.
South Africa
The National Regulator for Compulsory Specifications drafts continent-first propellant storage and transport safety standards modeled on European REACH protocols. Cape Town and Pretoria satellite operators pre-emptively retrofit ground infrastructure to comply with forthcoming secondary containment mandates. Cryogenic system engineering expertise concentrates here, leaving neighboring programs dependent on South African technical labor.
Egypt
The Egyptian Space Agency coordinates with military technical regulators to define defense satellite propulsion requirements through classified procurement channels. Hall-effect thruster development programs circumvent French export controls on gridded ion technology by building indigenous alternatives from open literature. Cairo anchors both civilian and parallel defense demand streams.
Ethiopia
Astrofica Technologies maintains indigenous thruster manufacturing operations in Addis Ababa, supplying cold gas and monopropellant systems to university-led CubeSat programs across East Africa. The facility leverages additive manufacturing to collapse titanium alloy component lead times from months to weeks. Direct sales relationships with fifteen academic institutions in four countries bypass traditional national procurement intermediaries.
Kenya
University engineering faculties in Nairobi procure CubeSat propulsion through online technical marketplaces rather than space agency channels, fragmenting traditional prime contractor relationships. Research institutions favor cold gas systems over hydrazine alternatives due to funding constraints and handling license limitations. This demand pattern concentrates in the capital's academic corridor.
Africa Space Propulsion System Market Competitive Landscape
Top-tier vendors anchor defense and geostationary satellite contracts, while indigenous manufacturers and university-focused specialists occupy emerging niches in CubeSat propulsion. The vendor base stratifies across three tiers: established aerospace conglomerates with electric propulsion heritage, regional manufacturers leveraging additive production, and academic-market cold gas specialists. Two dominant competitive moves are reshaping positioning: technology licensing partnerships to circumvent export controls, and backward integration into thruster component production to reduce European qualification bottlenecks.
Within the established aerospace tier, Northrop Grumman Corporation and Safran SA represent archetypes of electric propulsion heritage competing for satellite bus contracts with national space agencies. Among indigenous African manufacturers, Astrofica Technologies exemplifies the Addis Ababa-based production model, while Panafric Space occupies the university-market specialization niche serving East African CubeSat missions. Space Exploration Technologies Corp anchors the launch-integrated propulsion segment through bundled service offerings that reshape how government agencies procure orbital insertion capability.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Safran SA |
| Space Exploration Technologies Corp |
| IHI Corporation |
| L3Harris Technologies, Inc. |
| Astrofica Technologies |
| Panafric Space |
| Angel Technology |
| African Geospace |
| Others |
Value Network & Pricing Analysis
South Africa's REACH-modeled propellant storage and transport safety standards gate qualified supply access and premium-tier pricing for thruster systems across the continent. Satellite operators in Cape Town and Pretoria absorb compliance retrofit costs that filter through to end-user pricing, while East African university programs face exclusion from hydrazine-handling tiers entirely.
Pricing Analysis
Capacity additions in Addis Ababa and Nairobi are reshaping price floors for cold gas and green monopropellant thrusters. Three-tier pricing structure across ESA-qualified, nationally certified, and university-grade systems separates procurement channels. Price differentiation rests on thermal vacuum qualification status and local manufacturing content requirements. Cost compression in the university-grade tier is intensifying because direct manufacturer relationships bypass traditional agency markups. Government agencies in Nigeria and Egypt show lowest price sensitivity due to sovereign budget absorption; research institutions in Kenya and Uganda operate under severe funding constraints.
Supply Chain Analysis
Regional distribution centers in Johannesburg and Cairo anchor hub-and-spoke patterns for propellant and component logistics. Manufacturing concentrates in South Africa, Egypt, and Ethiopia; critical inputs draw from European chemical suppliers for hydrazine and ammonium dinitramide, Asian sources for titanium alloy feedstock, and domestic Addis Ababa facilities for 3D-printed thruster bodies. Single-source vulnerability pervades gridded ion thruster know-how restricted by French export controls. Distribution runs through national space agency procurement frameworks with limited commercial channel development.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa space propulsion market functions as a geographic-arbitrage play where Egyptian and Ethiopian manufacturers exploit lower labor and facility costs against South African regulatory compliance premiums.
For Market Incumbents: Deploy technology licensing partnerships to circumvent French and Russian export controls on electric propulsion know-how. Incumbents should anchor defense satellite contracts through Cairo's classified procurement channels while building captive qualification testing capacity to reduce 18-24 month ESA facility bottlenecks. The Hall-effect thruster substitution threat from indigenous Algerian and Egyptian programs demands accelerated R&D investment in next-generation gridded ion architectures. For New Entrants and Emerging Players: University procurement officers represent the most penetrable channel partner type for cold gas system penetration. New entrants should target Kenya's academic corridor where fifteen institutions across four countries source directly through online technical marketplaces. The white-space opportunity concentrates in standardized 1U-3U CubeSat thruster interfaces where no continental specifications yet exist. A green propellant handling certification bundled with thruster sales unlocks university budgets blocked by hydrazine licensing barriers. For Investors and Strategic Acquirers: Roll-up economics work for additive manufacturing specialists because titanium alloy 3D printing collapses component lead times from months to weeks without European qualification dependencies. Platform consolidation targets Nairobi and Addis Ababa production facilities with established direct sales relationships across East African academic markets. The inflection signal to watch is harmonization between national space laws and the African Union's continental policy framework, which would unlock cross-border component trade licensing.| Strategic Initiative | Industry Significance |
|---|---|
| Green Propellant Certification Program | Nigeria's NASRDA adoption of LMP-103S chemistry validates low-toxicity alternatives for Earth observation buses. |
| Additive Manufacturing Scale-Up | Astrofica Technologies' titanium alloy 3D printing in Addis Ababa compresses thruster body lead times dramatically. |
| Defense Procurement Channel Development | Egypt's military technical regulator operates parallel classified demand streams beyond civilian agency oversight. |
| University Direct Sales Network | Fifteen East African academic institutions now bypass national procurement intermediaries for CubeSat propulsion. |
| Indigenous Qualification Testing Investment | Thermal vacuum and vibration testing capacity would eliminate 18-24 month European Space Agency facility bottlenecks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured propulsion system procurement managers at Nigeria's NASRDA, Egyptian Space Agency technical directors, South African National Regulator for Compulsory Specifications officials, university engineering faculty in Nairobi and Kampala, and Addis Ababa-based manufacturing operations leads. Secondary validation drew from African Union space policy framework documents, national space legislation compilations, ESA technical standards databases, and customs records for propellant chemical imports. Bottom-up thruster production estimates and top-down satellite launch manifest projections were triangulated against sovereign budget appropriations.
Segment-weighting applied technology type, application mission profile, end-user procurement channel, and component subsystem value across the projection horizon. The analytical framework modeled chemical, electric, hybrid, and cold gas propulsion architectures against satellite launch, orbital maneuvering, and interplanetary mission applications. CAGRs were derived from procurement pipeline visibility and technology adoption curve positioning. Industry-specific inputs included Earth observation constellation funding commitments, green propellant regulatory transition timelines, and additive manufacturing capacity expansion announcements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to African Union space policy harmonization progress and export control regime evolution. Outputs reflect documented assumptions around sovereign budget continuity and technology transfer licensing pathways. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Management Solutions Market
Space
Deep Space Robotics Market
Space
Europe Space Logistics Market
Space
US Reusable Launch Vehicle Market
Space
Rocket Launchpad Market
Space
Orbital Spaceflight Market
Space
Electrically Powered Spacecraft Propulsion Market
Space
Germany Space Electronics Market
Space
Spain Space Electronics Market
Space
Space Colonization Market
Space
Near Space Robotics Market
Space
Spacecraft Market
Space
Deep Space Exploration Market
Space
US Space Launch Services Market
Space
Carrier Rocket Market
Space
Space Battery Market