
 Aircraft Anchoring System Market | 2026-2036
Aircraft Anchoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Anchoring System Market Analytics
The aircraft anchoring system market is consolidating around a widening gap between military-grade engineered systems and commoditized tie-down hardware for general aviation. Curtiss-Wright Corporation leverages its defense electronics heritage to dominate high-load arresting gear for carrier and expeditionary operations. Safran SA anchors its position through integrated landing-system portfolios that extend across European and Middle Eastern military customers. Runway Safe Group specializes in energy-absorbing foam arrestor systems, competing on certified safety performance rather than price.
An aircraft anchoring system comprises mechanical ground restraints, cable arrestors, and material-specific tie-down assemblies engineered to withstand dynamic aircraft loads ranging from light general aviation to heavy military transport categories. These systems secure parked aircraft against wind gusts, seismic events, or enemy action, and arrest runway overruns through friction or energy-dissipation mechanisms. Steel-ground-anchor configurations retain the largest installed base across permanent military installations, though composite mooring systems are gaining share where corrosion resistance and weight reduction matter. Temporary and mobile installation methods are expanding fastest among expeditionary military units and disaster-relief airfields where rapid deployment overrides longevity.
FAA regulations govern civil arresting system certification and load testing in the United States, while EASA's CS-25 airworthiness standards shape product requirements across European Union member states. Military procurement further channels demand through NAVAIR specifications in the United States and DEF STAN requirements in the United Kingdom, creating segmented compliance pathways that favor suppliers with dual-certification capabilities. Stakeholders must weigh defense budget cyclicality against the long replacement horizons of permanent airfield infrastructure when committing capital to capacity expansion or geographic diversification.
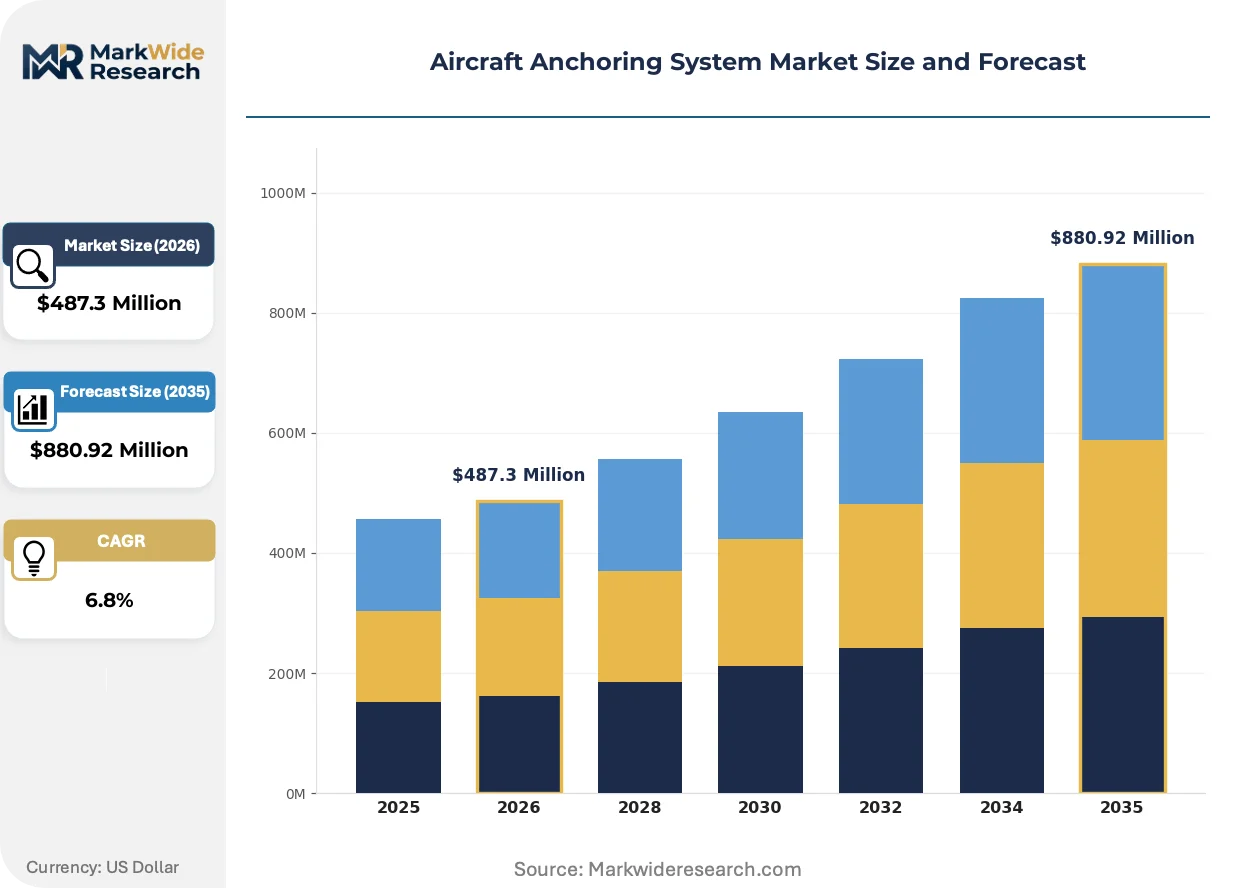
Market Dynamics
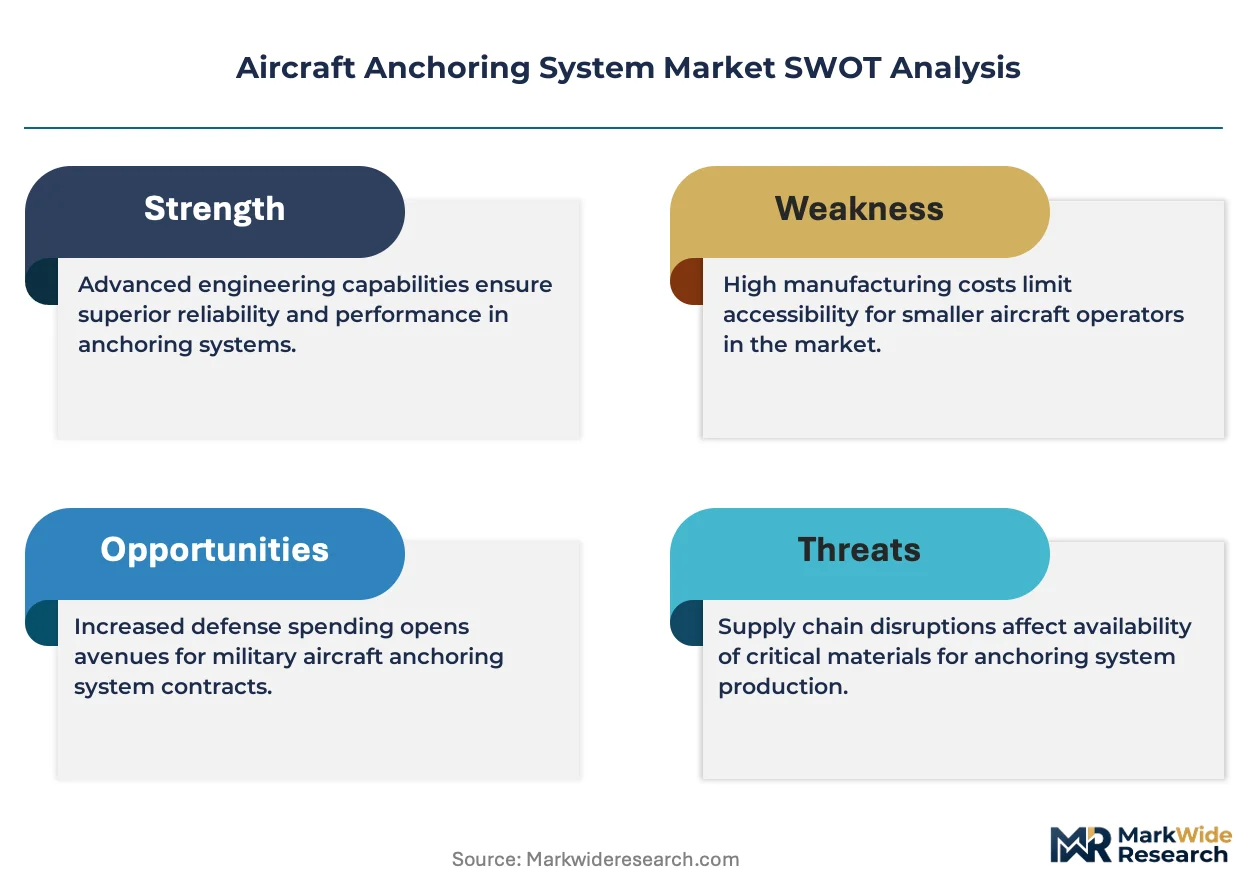
Military procurement cycles and FAA certification tightening are compressing supplier lead times while bifurcating demand between heavy-duty arresting gear and commoditized tie-down hardware.
Growth Catalysts
- NATO Defense Spending:Member states are accelerating orders for expeditionary mooring systems to support rapid-deployment airfield operations.
- FAA Material Standards:Updated load-testing requirements for arresting gear are forcing airfield operators into replacement cycles.
- Composite Materials:Corrosion-resistant anchor configurations are displacing steel installations in coastal and humid environments.
Market Restraints
- Steel Price Volatility:Input cost swings for high-grade alloy anchor components squeeze margins on fixed-price military contracts.
- Supplier Concentration:Certified arresting gear production clusters among three North American defense contractors.
- Technical Limitation:Energy-absorbing foam systems degrade under sustained UV exposure, limiting tropical deployment lifespans.
Strategic Opportunities
- Disaster-Relief Airfields:Temporary anchoring systems for humanitarian operations remain underpenetrated in Southeast Asian markets.
- EU Green Deal Incentives:Sustainable material mandates favor composite mooring suppliers with recycled-content certifications.
- Digital Load Monitoring:Sensor-embedded anchors converging with predictive maintenance platforms open aftermarket service revenue streams.
Industry Challenges
- Certification Timeline Compression:Dual FAA-EASA approval processes for new arrestor materials extend time-to-revenue by 18-24 months.
- Legacy System Integration:Modern energy-dissipating anchors must interface with 1970s-era runway infrastructure without full reconstruction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Anchoring System Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Anchors, Tie-Down Chains, Mooring Systems, Safety Straps Material: Aluminum, Steel, Composite, Nylon End User: Aviation Authorities, Airlines, Private Operators, Military Installation Method: Permanent, Semi-Permanent, Temporary, Mobile |
| Companies Covered | General Atomics Electromagnetic Systems, Runway Safe Group, SCAMA AB, A-Tech Inc., Curtiss-Wright Corporation, MacTaggart Scott, QinetiQ, Zodiac Aerospace, Safran SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Anchoring System Market Evolving Landscape
Active materials science and regulatory digitization are reshaping how anchoring systems are specified, tested, and deployed across military and commercial airfields.
Carbon-fiber-reinforced polymer anchors are integrating into expeditionary military kits where weight reduction and corrosion immunity override initial cost premiums. Marine Corps and special operations units are field-testing these configurations in Pacific theater exercises. The technology is integrating mobile airfield construction timelines from weeks to days, compressing competitive differentiation around rapid-deployment credentials.
EASA's CS-25 airworthiness standards are tightening documentation requirements for arresting system energy-absorption curves. Manufacturers must now submit digital twin simulations alongside physical load tests. European commercial airports and Middle Eastern hubs operating under EASA-equivalent bilateral agreements are accelerating procurement of certified simulation-capable suppliers.
Buyers are consolidating vendor relationships around integrated landing-system portfolios rather than standalone anchoring components. Middle Eastern military customers now specify single-source responsibility for arresting gear, lighting, and navigation aids. This bundling pattern concentrates contract awards among suppliers with full-runway capability, marginalizing specialized anchor-only manufacturers in Gulf Cooperation Council states.
Aircraft Anchoring System Market Segmentation
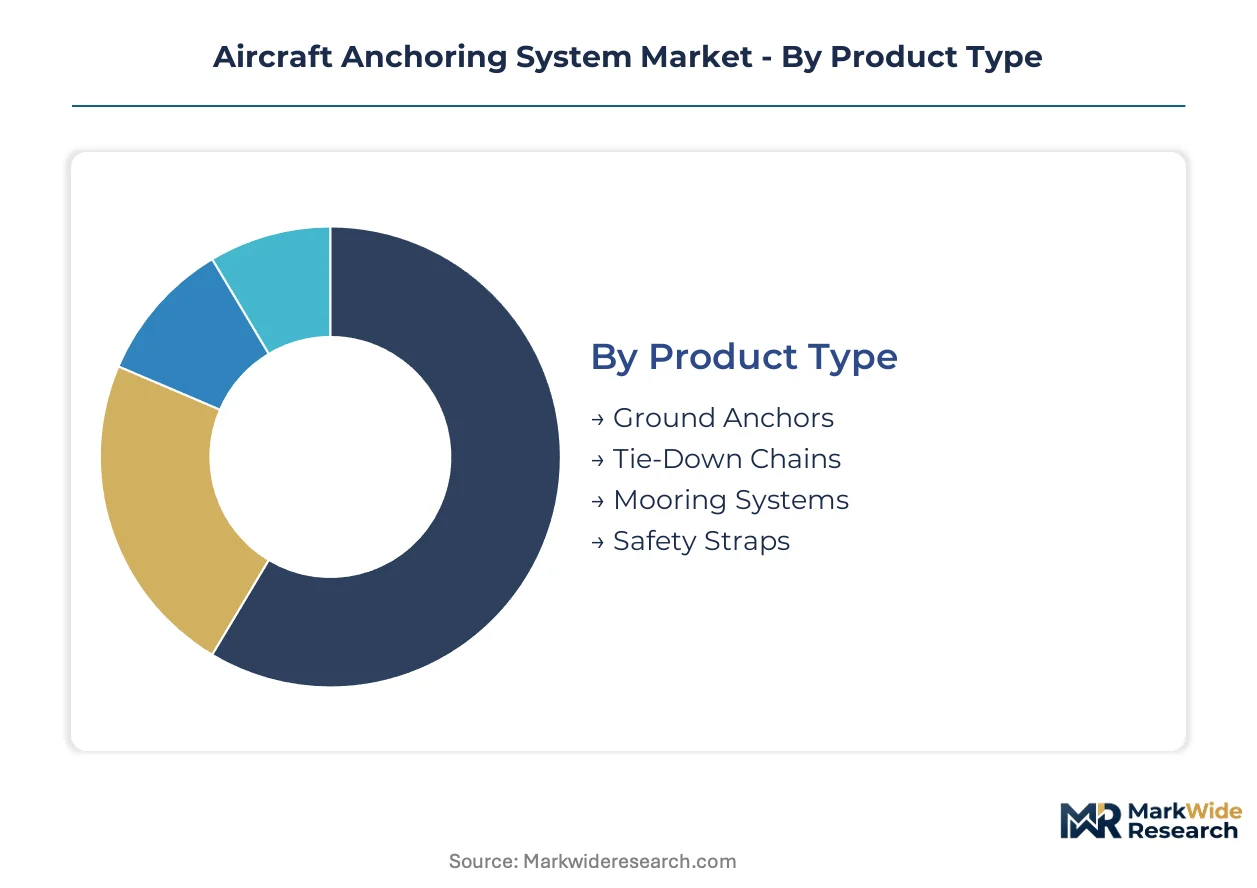
Aircraft anchoring systems fragment across four critical dimensions that determine procurement economics and operational deployment. Product type and material composition drive upfront capital outlays, while installation method dictates lifecycle flexibility for military expeditionary forces versus permanent commercial infrastructure.
Product Type:
Volume concentrates in commoditized hardware, while premium engineered systems capture defense procurement margins.
- Ground Anchors:Steel and composite subsurface fixtures engineered for lateral load resistance up to heavy transport categories. Demand clusters at permanent military installations in the United States and United Kingdom where NAVAIR and DEF STAN specifications mandate certified load ratings. FAA certification tightening on material fatigue testing is accelerating replacement cycles at aging commercial airfields.
- Mooring Systems:Integrated cable-and-anchor configurations for carrier decks and expeditionary airfields. Marine Corps Pacific theater exercises are field-testing carbon-fiber variants that compress mobile airfield construction timelines. NATO rapid-deployment doctrine favors these systems where runway overruns pose catastrophic risk.
- Tie-Down Chains:Standardized chain assemblies for general aviation parking aprons.
- Safety Straps:Synthetic webbing systems for light aircraft and helicopter securing.
Today's leader: Ground Anchors. Tomorrow's challenger: Mooring Systems.
Material:
Cost tiers separate legacy metal installations from next-generation composites commanding corrosion-resistance premiums.
- Steel:High-grade alloy anchors retaining the largest installed base across permanent military infrastructure. Price volatility in alloy inputs squeezes margins on fixed-price defense contracts, particularly for suppliers without backward integration into raw material sourcing.
- Composite:Carbon-fiber-reinforced polymer configurations displacing steel in coastal and humid environments. EU Green Deal sustainable material mandates favor suppliers with recycled-content certifications across European Union member states.
- Aluminum:Lightweight alternatives for general aviation tie-down hardware.
- Nylon:Synthetic webbing for temporary safety strap applications.
Steel dominates installed base. Composite gains share fastest where longevity commands premium pricing.
End User:
Customer type bifurcates between regulated procurement channels and discretionary general aviation spending.
- Military:Defense procurement programs across NATO members drive heavy-duty mooring system orders. NAVAIR specifications in the United States and DEF STAN requirements in the United Kingdom create segmented compliance pathways favoring dual-certification suppliers.
- Aviation Authorities:Regulatory bodies mandating arresting gear certification and airfield safety standards.
- Airlines:Commercial carriers replacing aging tie-down infrastructure during airport modernization cycles.
- Private Operators:General aviation and business jet owners purchasing commoditized hardware.
Military procurement anchors revenue stability. Aviation Authorities determine technology adoption timelines through regulatory mandates.
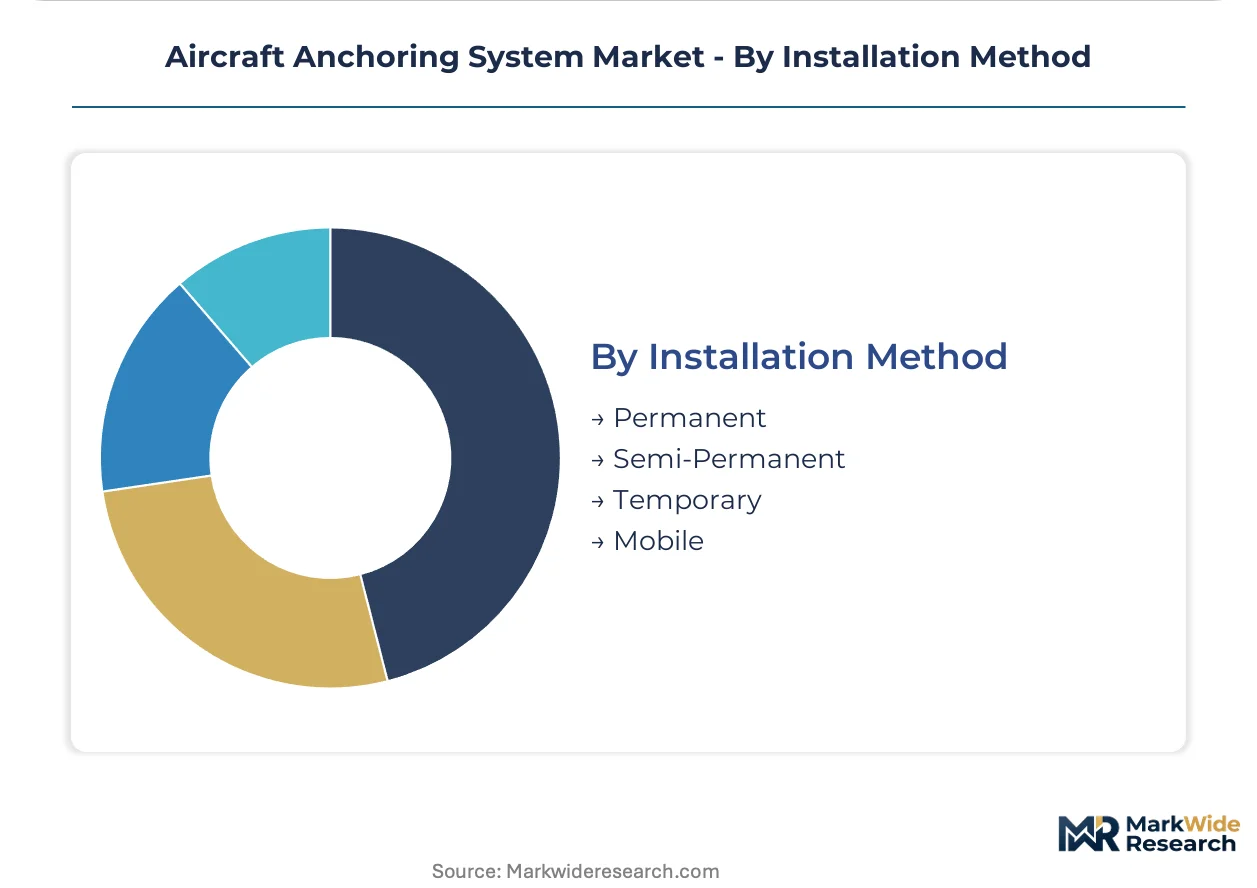
Installation Method:
Deployment flexibility separates permanent infrastructure investments from rapidly deployable expeditionary solutions.
- Temporary:Rapid-deployment kits for disaster-relief airfields and humanitarian operations. Southeast Asian markets remain underpenetrated for these configurations where seismic and typhoon response drives intermittent demand spikes.
- Mobile:Expeditionary systems for special operations units requiring runway construction in days rather than weeks. Pacific theater military exercises are validating composite mooring configurations that reduce transport weight.
- Permanent:Fixed installations at established military bases and commercial hubs.
- Semi-Permanent:Hybrid configurations for forward operating bases with medium-term deployment horizons.
Permanent methods hold installed base. Mobile and Temporary methods climb the fastest as expeditionary doctrine evolves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States outpaces Germany in defense procurement volume for heavy-duty mooring systems, while Japan's commercial airport modernization cycles run shorter than NATO replacement timelines. Demand clusters unevenly across mature defense infrastructure markets and emerging commercial hubs.
United States
NAVAIR specifications drive procurement for carrier-deck and expeditionary arresting gear across Marine Corps Pacific theater operations. FAA certification tightening on material fatigue testing accelerates replacement cycles at aging commercial airfields in the Southeast and Southwest. Defense contractors cluster around Washington DC-Northern Virginia corridor and San Diego shipbuilding complexes.
Germany
Bundeswehr rapid-deployment doctrine favors mobile mooring configurations for NATO forward airfield operations. EU Green Deal sustainable material mandates favor composite anchor suppliers with recycled-content certifications. Industrial concentration sits in Bavaria and Baden-Württemberg, where landing-system integrators serve both domestic and export military customers.
United Kingdom
DEF STAN requirements create segmented compliance pathways favoring dual-certification suppliers with FAA equivalency. Royal Air Force expeditionary operations in the Middle East drive temporary anchoring kit procurement. Manufacturing activity concentrates in Scotland and the Midlands, with QinetiQ anchoring defense research capabilities.
Japan
Ministry of Defense procurement emphasizes corrosion-resistant composite systems for coastal airbase installations. METI industrial standards shape domestic supplier qualification for arresting gear components. Industrial clusters in Aichi Prefecture and the Kanto region host precision manufacturers serving both JASDF and commercial export markets.
France
DGA defense procurement channels demand through Safran-anchored integrated landing-system portfolios. EASA CS-25 airworthiness standards tighten documentation requirements for arresting system energy-absorption curves. Aerospace manufacturing concentrates in Toulouse and the Île-de-France region, with export focus on Middle Eastern and African military customers.
Aircraft Anchoring System Market Competitive Landscape
Top-tier vendors anchor defense procurement channels, while specialized safety-system fabricators occupy certified niches. The market structures around three tiers: integrated landing-system conglomerates, defense-electronics heritage contractors, and specialized energy-absorption technology firms. Strategic archetypes include full-runway portfolio bundlers, rapid-deployment expeditionary specialists, and certified simulation-capable suppliers. Competitive moves concentrate on dual-certification capability building and composite material R&D partnerships.
Within the integrated-systems tier, Safran SA and Curtiss-Wright Corporation exemplify contrasting heritage models—European aerospace conglomerate versus American defense-electronics contractor. Runway Safe Group occupies a distinct position as a specialized energy-absorption technology firm competing on certified safety performance metrics rather than price. These three anchors represent the strategic spectrum: full-portfolio bundling, defense-heritage scale, and niche technology specialization.
| Leading Market Players |
|---|
| General Atomics Electromagnetic Systems |
| Runway Safe Group |
| SCAMA AB |
| A-Tech Inc. |
| Curtiss-Wright Corporation |
| MacTaggart Scott |
| QinetiQ |
| Zodiac Aerospace |
| Safran SA |
| Others |
Value Network & Pricing Analysis
EU Green Deal sustainable material mandates gate qualified supply and premium-tier pricing access, restricting certified composite anchor manufacturers while elevating price floors for corrosion-resistant mooring systems across European Union procurement channels.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for composite mooring configurations as Bavarian landing-system integrators expand production. Three-tier pricing structure across military-grade certified, commercial-standard, and general aviation commodity levels separates procurement tiers. Cost compression in steel-alloy ground anchors intensifies because high-grade input volatility squeezes fixed-price defense contract margins. General aviation private operators exhibit highest price sensitivity, while NATO military procurement shows lowest sensitivity due to mission-critical performance requirements.
Supply Chain Analysis
Regional distribution centers in Washington DC-Northern Virginia corridor and San Diego shipbuilding complexes anchor North American military procurement logistics. Manufacturing concentrates in United States, Germany, and France for defense-certified arresting gear. Raw material sourcing draws from high-grade alloy foundries, carbon-fiber composite suppliers, and energy-absorption foam chemical processors. Single-source vulnerability concentrates among three North American defense contractors holding FAA-EASA dual certification. Distribution runs through NAVAIR and DEF STAN specification channels toward permanent military installations and expeditionary field units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft anchoring system market functions as a stable compounder, with defense procurement cycles and regulatory replacement mandates delivering predictable revenue visibility across multi-year military and commercial airfield modernization programs.
For Market Incumbents: Deepen backward integration into carbon-fiber composite supply to offset steel price volatility and capture EU Green Deal certification premiums. Fortify dual FAA-EASA approval capabilities as certification timeline compression threatens revenue recognition for single-certified competitors. Prioritize sensor-embedded anchor R&D to anchor predictive maintenance service contracts against commoditization pressure in general aviation tie-down hardware. For New Entrants and Emerging Players: Begin with temporary anchoring kits for Southeast Asian disaster-relief airfields, where seismic and typhoon response drives intermittent demand spikes with limited incumbent presence. Target carbon-fiber expeditionary mooring configurations for Marine Corps Pacific theater validation programs as rapid-deployment doctrine accelerates. Pursue partnership-based go-to-market models with established landing-system integrators rather than direct certification investment. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized energy-absorption technology firms lacking full-runway portfolio bundling capability. Long-term viability over a five-to-ten year window rests on regulatory tightening accelerating replacement cycles and composite material share gains in coastal installations. Watch for FAA material fatigue testing rulemakings as inflection indicators for commercial airfield replacement demand timing.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | FAA-EASA approval capability compresses competitor time-to-revenue by 18-24 months. |
| Composite Material R&D Partnership | Carbon-fiber anchor development aligns with Marine Corps Pacific expeditionary requirements. |
| Predictive Maintenance Platform Integration | Sensor-embedded anchors open recurring service revenue streams beyond hardware sales. |
| Southeast Asian Distribution Buildout | Temporary anchoring kit penetration lags in typhoon-prone humanitarian response markets. |
| EU Green Deal Certification Program | Recycled-content composite credentials unlock premium procurement in Bundeswehr channels. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with NAVAIR procurement officers, DEF STAN compliance managers, airfield engineering directors, and composite materials R&D leads with secondary validation against FAA certification databases, EASA CS-25 airworthiness filings, NATO defense expenditure reports, and customs trade records for high-grade alloy imports. Bottom-up installation base modeling and top-down defense budget allocation analysis triangulated volume estimates.
Historical reference periods anchored the forecast window to observed replacement cycles across permanent military infrastructure and commercial airport modernization programs. Segmentation modeling spanned product type, material composition, end-user procurement channel, and installation method flexibility. CAGRs derived from regression against defense spending trajectories, regulatory mandate implementation timelines, and composite material cost curves. Industry-specific inputs included NAVAIR specification revision schedules and EASA digital twin documentation requirements.
Several conditions sit outside the modeled scope, including unannounced defense budget reallocations, breakthrough energy-absorption material discoveries, and geopolitical disruptions to alloy supply chains. Forecasts reflect documented assumptions around certification timeline stability and military expeditionary doctrine continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Crashworthy Aircraft Seats Market
Aircraft
Utility Aircraft Market
Aircraft
Helicopter Lighting Market
Aircraft
Aircraft Hangar Market
Aircraft
Air Deflector Market
Aircraft
Aircraft Control Surface Market
Aircraft
Middle-East and Africa Helicopters Market
Aircraft
Airplane Brackets Market
Aircraft
Europe Turboprop Aircraft Market
Aircraft
Civil Helicopter Market
Aircraft
Australia Aviation Market
Aircraft
Asia-Pacific Attack Helicopter Market
Aircraft
Aircraft Cargo Winches Market
Aircraft
South Korea Aerospace and Defense Market
Aircraft
Air Starter Market
Aircraft
Europe Freighter Aircraft Market