
 Smart Airport 3.0 Market | 2026-2036
Smart Airport 3.0 Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Airport 3.0 Market Analytics
Saudi Arabia is rewriting competitive dynamics across the Smart Airport 3.0 landscape through giga-project terminal developments at NEOM and King Salman International Airport. SITA leverages decades of aviation IT infrastructure dominance to anchor baggage handling automation across Gulf Cooperation Council hubs. Honeywell International Inc. sustains its position through integrated building management systems that control energy, fire safety, and passenger flow from unified command centers. Thales Group differentiates via biometric identity platforms that merge document verification with real-time threat detection.
Smart Airport 3.0 denotes the next-generation aviation ecosystem integrating artificial intelligence, Internet of Things architectures, and edge computing to achieve autonomous passenger processing, predictive asset maintenance, and dynamic resource allocation with sub-second latency requirements. Biometric Systems represent the most mature revenue pool, with fingerprint and facial recognition now standard at primary immigration checkpoints across tier-one hubs. IoT Sensors and AI-driven Systems capture the fastest expansion trajectory, as predictive runway condition monitoring and automated aircraft turnaround coordination deliver measurable reductions in ground time. Cloud-based Solutions remain the dominant integration architecture for greenfield airports, though edge computing deployments are accelerating where latency-sensitive applications such as autonomous baggage vehicles require localized processing.
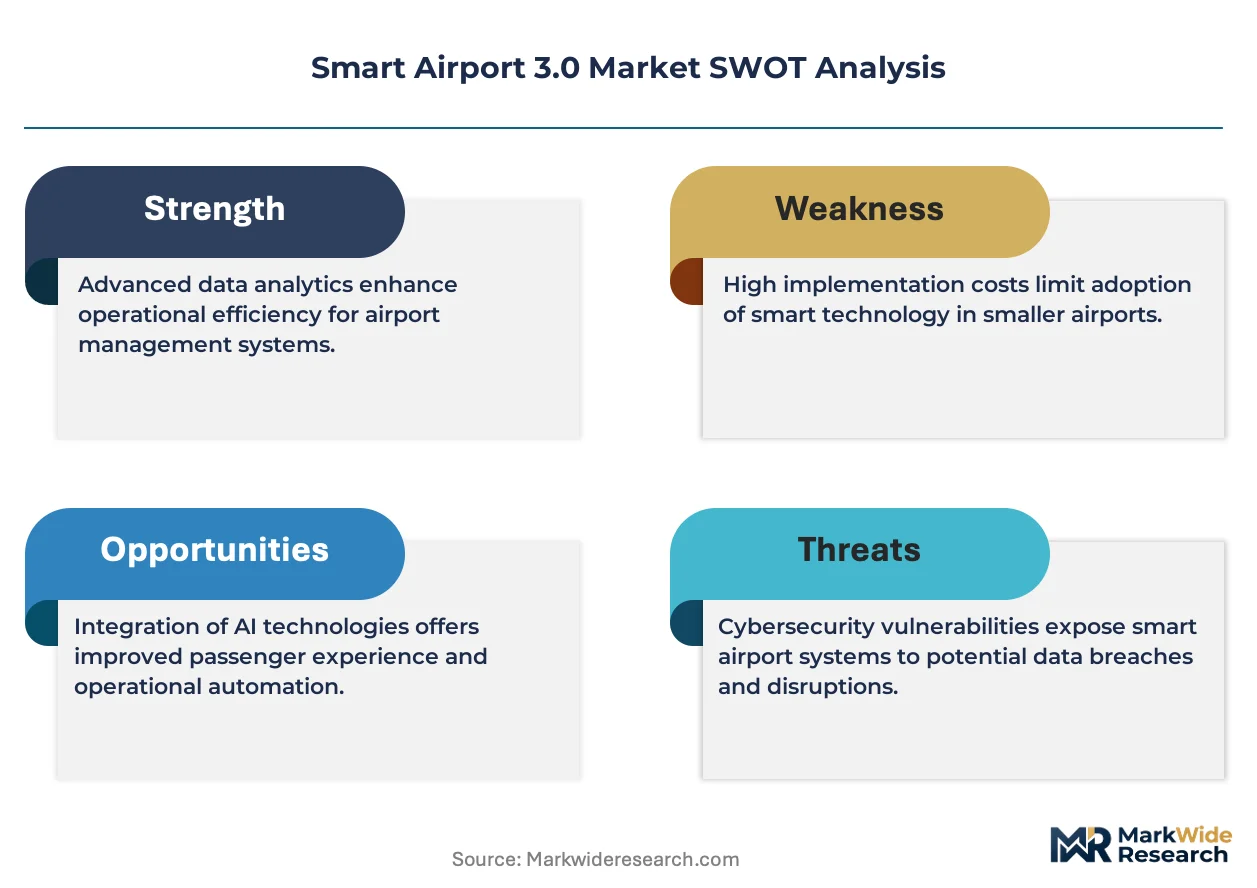
The Federal Aviation Administration mandates cybersecurity frameworks for airport operational networks under evolving critical infrastructure designations, while the EU AI Act imposes conformity assessments on biometric classification systems deployed at Schengen Area checkpoints. China's MIIT and GB standards govern data localization requirements for foreign technology vendors serving domestic hub expansions. Stakeholders must weigh regulatory fragmentation against standardization pressures as procurement decisions commit airports to decade-long technology lock-in periods.
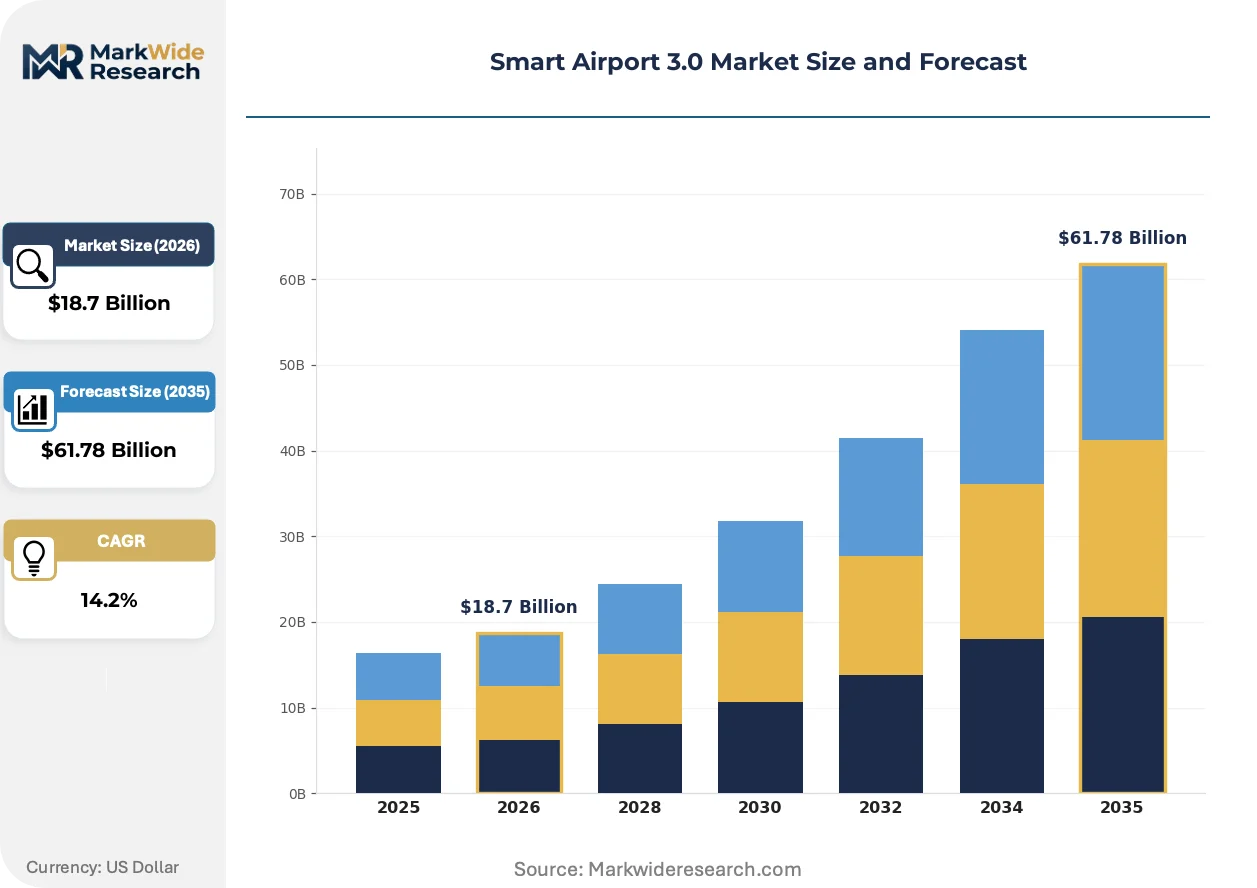
Market Dynamics
Biometric identity verification mandates from the EU AI Act and FAA cybersecurity directives are forcing simultaneous compliance investments across passenger processing, baggage handling, and airside operations. Airport operators face compressed procurement timelines as greenfield terminals in Saudi Arabia and retrofit programs in Europe demand synchronized technology rollouts.
Growth Catalysts
- EU AI Act Conformity Assessments:Mandatory algorithmic audits for biometric classification systems deployed at Schengen checkpoints are accelerating replacement of legacy fingerprint readers with privacy-preserving facial recognition platforms.
- NEOM and Red Sea Greenfield Construction:Saudi Arabia's giga-projects are embedding autonomous terminal operations from inception, eliminating retrofit costs that constrain brownfield airports elsewhere.
- Predictive Runway Monitoring:IoT sensor networks for real-time pavement condition assessment are reducing ground delays and aircraft turnaround times at tier-one hubs facing slot constraints.
Market Restraints
- Semiconductor Supply Concentration:Edge computing chipsets for autonomous baggage vehicles face procurement bottlenecks from concentrated foundry capacity in East Asia.
- GDPR Data Localization:Passenger biometric data storage requirements impose redundant infrastructure costs on multi-hub operators serving EU and non-EU routes simultaneously.
- Legacy System Interoperability:Proprietary protocols from 1990s-era building management systems resist API integration with modern AI-driven resource allocation platforms.
Strategic Opportunities
- India Greenfield Airport Expansion:Navi Mumbai and Jewar airports offer first-mover advantages for integrated biometric-IoT platforms without legacy debt.
- Carbon Border Adjustment Mechanisms:EU Green Deal compliance incentives favor energy-optimized building management systems that reduce Scope 2 emissions at connected terminals.
- Digital Twin Convergence:Real-time simulation of passenger flow, aircraft movement, and energy consumption is enabling scenario planning previously impossible with siloed operational data.
Industry Challenges
- Cybersecurity Certification Timelines:FAA critical infrastructure designations require multi-year authorization processes for operational technology vendors before deployment.
- Edge-AI Engineering Talent Scarcity:Sub-second latency requirements for autonomous ground vehicles demand specialized skill sets concentrated among aviation-specific system integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Airport 3.0 Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Biometric Systems, IoT Sensors, Automated Check-in, Wi-Fi Analytics End User: Airline Operators, Ground Handlers, Passengers, Airport Authorities Application: Security Screening, Baggage Handling, Passenger Flow Management, Flight Information Display Integration Level: Cloud-based Solutions, Edge Computing, Mobile Applications, AI-driven Systems |
| Companies Covered | SITA, Honeywell International Inc., Siemens AG, Thales Group, Huawei Technologies Co., Amadeus IT Group SA, Cisco Systems Inc., Raytheon Technologies Corporation, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Airport 3.0 Market Evolving Landscape
Artificial intelligence architectures are migrating from cloud-only deployments to hybrid edge-cloud configurations as latency requirements tighten for real-time passenger processing and autonomous vehicle coordination.
Computer vision platforms with embedded biometric matching engines are digitizing identity verification workflows at immigration checkpoints. Tier-one airports in Germany and Singapore are deploying these systems at primary inspection lanes. The technology is digitizing document verification from a sequential manual process into a continuous automated pipeline, compressing passenger processing times while reducing staffing ratios.
The EU AI Act's risk-based classification system imposes conformity assessment obligations on biometric identification systems deployed at Schengen Area entry points. Vendors must demonstrate algorithmic accuracy thresholds and bias mitigation protocols before market authorization. This regulatory architecture is accelerating procurement of certified platforms among EU hub operators while creating compliance barriers for uncertified competitors.
Airport authorities are unbundling long-term managed service contracts into modular component procurements for biometric hardware, software licenses, and operational support. This purchasing pattern is displacing single-vendor lock-in arrangements that dominated 2010s terminal modernization programs. The shift is most pronounced in Middle Eastern hubs where NEOM and King Salman International Airport projects evaluate subsystem vendors independently rather than through consolidated prime contractors.
Smart Airport 3.0 Market Segmentation
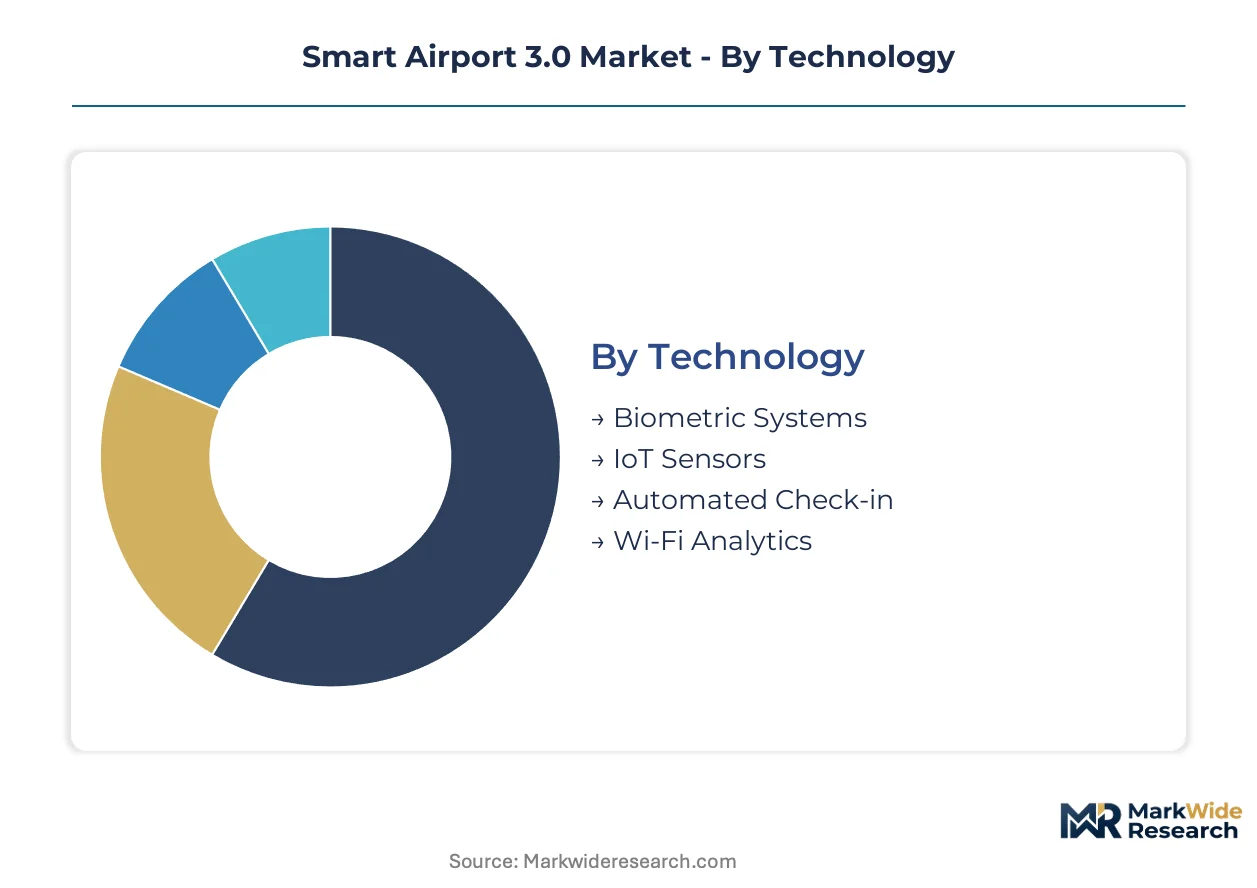
Smart Airport 3.0 deployments fragment across technology maturity curves, user workflows, and infrastructure integration depth. Procurement patterns diverge sharply between greenfield terminals embedding autonomous systems from inception and brownfield retrofits wrestling with legacy protocol constraints.
Technology:
After-sales service intensity varies dramatically across technology categories, with biometric platforms demanding continuous algorithm retraining and IoT networks requiring dense sensor calibration regimens.
- Biometric Systems:Fingerprint and facial recognition platforms with embedded liveness detection now standard at primary immigration checkpoints. Demand concentrates in Saudi Arabia's NEOM and Red Sea terminals where privacy-preserving architectures satisfy EU AI Act conformity requirements for Schengen-bound routes.
- IoT Sensors:Dense networks of pavement condition monitors, environmental probes, and asset trackers generating sub-second telemetry for predictive maintenance. Predictive runway monitoring applications at slot-constrained tier-one hubs are driving the steepest procurement acceleration.
- Automated Check-in:Self-service kiosks and mobile-enabled bag drops reducing counter staffing ratios.
- Wi-Fi Analytics:Passenger movement pattern extraction from network association data for flow optimization.
Biometric Systems holds the largest share; momentum sits with IoT Sensors.
End User:
Cost tier stratification separates enterprise-grade deployments by airport authorities from modular point solutions purchased by ground handlers.
- Airport Authorities:Integrated command centers unifying energy, safety, and passenger flow management across terminal footprints. Greenfield projects in Saudi Arabia and India are embedding full-stack autonomous operations without legacy debt.
- Airline Operators:Biometric boarding gates and self-service check-in ecosystems for loyalty program integration.
- Ground Handlers:Turnaround coordination platforms and automated baggage vehicle fleets.
- Passengers:Mobile applications for wayfinding, lounge access, and real-time flight updates.
Airport Authorities command the largest procurement volumes; climbing fastest are Ground Handlers modernizing under airline outsourcing pressure.
Application:
Application maturity correlates with measurable ROI visibility, with baggage handling automation delivering quantifiable turnaround reductions versus passenger flow management's softer efficiency gains.
- Security Screening:Computed tomography baggage scanners and automated threat detection algorithms replacing manual image analysis. FAA cybersecurity mandates for critical infrastructure networks are extending procurement timelines for new entrants.
- Baggage Handling:Autonomous vehicle fleets and RFID-tracked conveyor systems reducing mishandled baggage rates. IoT-enabled condition monitoring is expanding fastest at Middle Eastern hubs facing surging passenger volumes.
- Passenger Flow Management:Computer vision queue analytics and dynamic signage for congestion mitigation.
- Flight Information Display:LED and e-ink systems with centralized content management.
Security Screening absorbs the largest capital allocation; Baggage Handling is gaining share fastest through autonomous vehicle deployments.
Integration Level:
Supply concentration in East Asian foundries constrains edge computing chipset availability, privileging cloud-first architectures where latency requirements permit.
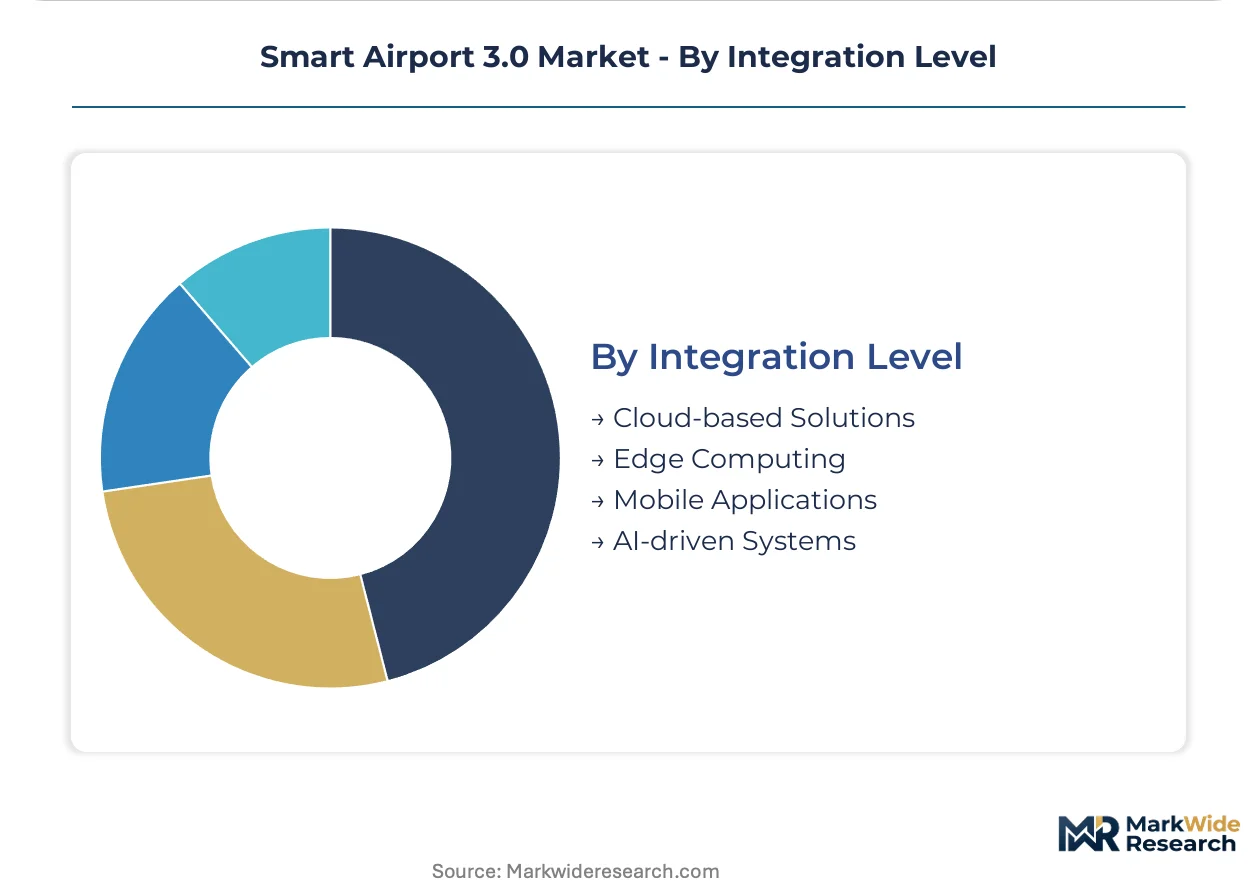
- Cloud-based Solutions:Centralized data lakes and SaaS operational platforms dominating greenfield airport procurement. Navi Mumbai and Jewar developments in India are specifying cloud-native stacks without on-premise legacy.
- Edge Computing:Localized processing nodes for sub-second latency in autonomous vehicle coordination and real-time biometric matching. Semiconductor supply bottlenecks are extending deployment timelines for baggage robot fleets.
- Mobile Applications:Passenger-facing iOS and Android platforms for contactless service delivery.
- AI-driven Systems:Predictive resource allocation and computer vision platforms requiring continuous model retraining.
Cloud-based Solutions holds the largest installed base; Edge Computing is expanding most quickly where autonomous operations mandate localized processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FAA anchors the regulatory framework in the United States, where critical infrastructure designations for airport operational networks mandate multi-year cybersecurity certification processes for technology vendors.
United States
Domestic carriers are retrofitting legacy terminals with biometric boarding gates and automated baggage handling systems to reduce ground delays. FAA cybersecurity directives require operational technology vendors to complete extensive authorization timelines before deployment. Dallas-Fort Worth International Airport is consolidating passenger flow management, energy systems, and fire safety controls into unified command centers.
Saudi Arabia
NEOM and King Salman International Airport projects are embedding fully autonomous terminal operations from inception without legacy system constraints. SFDA and national data governance frameworks govern biometric data handling for international route compliance. The Red Sea International Airport development is specifying privacy-preserving facial recognition architectures that satisfy EU AI Act requirements for Schengen-bound passengers.
Germany
Fraport and Munich Airport operators are replacing legacy fingerprint readers with certified biometric platforms to meet EU AI Act conformity assessment mandates. The KBA and federal data protection authorities enforce strict algorithmic audit requirements for passenger processing systems. Frankfurt Airport's primary inspection lanes are deploying computer vision platforms with embedded liveness detection for continuous automated identity verification.
India
Navi Mumbai and Jewar greenfield developments are specifying cloud-native technology stacks without on-premise legacy infrastructure. BIS standards and DGFT procurement guidelines favor integrated biometric-IoT platforms for new terminal construction. The Delhi Indira Gandhi International Airport expansion is implementing predictive runway condition monitoring through dense IoT sensor networks to reduce aircraft turnaround times.
Singapore
Changi Airport Group is deploying edge computing nodes for sub-second latency in autonomous baggage vehicle coordination and real-time biometric matching. The national cybersecurity agency mandates data localization protocols for passenger biometric information storage. The Changi East development is integrating digital twin simulations of passenger flow, aircraft movement, and energy consumption for scenario planning previously impossible with siloed data.
Smart Airport 3.0 Market Competitive Landscape
Capability concentration sits with specialized aviation IT infrastructure providers; scale advantage sits with diversified industrial conglomerates. The market structure tiers between legacy system integrators with decades of airport relationships and emerging technology vendors offering modular point solutions. Two strategic archetypes dominate: integrated platform providers delivering end-to-end command center solutions, and component specialists supplying biometric hardware or IoT sensor networks. Competitive moves center on unbundling long-term managed service contracts into modular procurements and forming strategic partnerships to bridge legacy protocol gaps.
Within the integrated platform tier, SITA leverages aviation-specific infrastructure dominance, while Honeywell International Inc. occupies a position exemplifying building management system consolidation. Thales Group represents the biometric identity specialization archetype, anchoring privacy-preserving architectures that satisfy multi-jurisdictional compliance requirements. These three entities collectively illustrate how competitive positioning stratifies between full-stack providers and subsystem specialists across greenfield and brownfield deployment contexts.
| Leading Market Players |
|---|
| SITA |
| Honeywell International Inc. |
| Siemens AG |
| Thales Group |
| Huawei Technologies Co. |
| Amadeus IT Group SA |
| Cisco Systems Inc. |
| Raytheon Technologies Corporation |
| IBM |
| Others |
Value Network & Pricing Analysis
Taipei-Hsinchu semiconductor corridor capacity allocation directly shapes downstream pricing power for edge computing chipsets deployed in autonomous baggage vehicle fleets. Foundry utilization rates at TSMC and UMC facilities cascade through aviation system integrators, compressing margins where sub-second latency requirements mandate localized processing nodes.
Pricing Analysis
Geographic price spreads between East Asian procurement and European deployment widen substantially for EU AI Act-certified biometric platforms versus uncertified alternatives. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels dominates procurement, with certification grade and after-sales algorithm retraining intensity as primary differentiation drivers. Cost compression in standard-tier edge computing modules is intensifying because concentrated foundry capacity constrains supply elasticity. Ground handlers and regional airport authorities exhibit highest price sensitivity, while tier-one hub operators in Saudi Arabia and Singapore prioritize performance guarantees over unit economics.
Supply Chain Analysis
Upstream feedstock for edge-AI chipsets draws from Taiwan, South Korea, and USA foundry networks, with advanced node wafers, high-bandwidth memory modules, and specialized packaging substrates as critical inputs. Single-source vulnerability concentrates in 5nm and below process nodes where TSMC holds dominant capacity. Distribution runs through aviation-specific system integrators rather than direct OEM relationships, with SITA and Honeywell anchoring procurement channels for terminal-wide deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized edge-AI engineering talent scarcity constrains deployment velocity for autonomous ground vehicle coordination, creating asymmetric returns for firms that secure captive capability pools ahead of Saudi greenfield completions.
For Market Incumbents: Pre-empt modular procurement unbundling by establishing independent subsystem certification for biometric hardware, software licenses, and operational support before NEOM and King Salman International Airport finalize vendor shortlists. Anchor relationships through backward integration into edge computing chipset allocation agreements with Taiwan foundries, securing supply priority as semiconductor bottlenecks extend deployment timelines for competitors. For New Entrants and Emerging Players: Pursue India's Navi Mumbai and Jewar greenfield developments as first-mover opportunities for cloud-native biometric-IoT platforms without legacy protocol integration burdens. Target ground handler modernization programs under airline outsourcing pressure, positioning predictive runway monitoring and autonomous baggage vehicle fleets as quantifiable turnaround reduction solutions with faster procurement cycles than airport authority enterprise sales. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors aviation-specific system integrators with established FAA cybersecurity authorization and EU AI Act conformity assessment track records over diversified industrial conglomerates lacking sector-specific certification velocity. Long-term viability hinges on regulatory moat depth rather than scale economics alone. Watch for inflection in edge computing chipset allocation priority shifts from consumer electronics to critical infrastructure designations.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Certification | Algorithmic audit completion unlocks Schengen checkpoint procurement for biometric platform vendors. |
| Edge Computing Chipset Allocation Agreement | Taiwan foundry priority status secures supply for autonomous vehicle fleets facing semiconductor bottlenecks. |
| Digital Twin Platform Integration | Real-time simulation of passenger flow and energy consumption differentiates command center offerings at tier-one hubs. |
| Greenfield Airport Partnership | Saudi Arabia NEOM and Red Sea projects embed autonomous operations without retrofit constraints. |
| Privacy-Preserving Biometric Architecture | GDPR-compliant facial recognition satisfies EU AI Act requirements for Schengen-bound international routes. |
Research Methodology
A standing panel of airport operations directors, aviation IT procurement leads, biometric system engineers, and ground handling fleet managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FAA cybersecurity directive filings, EU AI Act conformity assessment registers, Saudi SFDA data governance frameworks, Indian BIS standard publications, and customs records for edge computing chipset trade flows. Bottom-up deployment sizing triangulated against top-down terminal modernization budget allocations.
Scenario-bracketing framed optimistic, baseline, and constrained trajectories across the projection horizon. Segmentation dimensions modeled include technology maturity tier, end-user procurement authority, application ROI visibility, and integration architecture latency requirements. CAGRs derived from deployment pipeline velocity, regulatory authorization timelines, and foundry capacity expansion announcements. Industry-specific inputs incorporated biometric algorithm accuracy thresholds and IoT sensor network density specifications for predictive runway monitoring.
Macroeconomic conditions sit as an overlay; deviation in aviation passenger volume recovery, semiconductor capital expenditure cycles, or EU Green Deal compliance incentive timing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory authorization velocity and greenfield construction schedules. Quarterly review of foundry utilization rates, FAA cybersecurity certification queue depth, and Saudi giga-project milestone announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
North America Smart Airport Market
Airport Technologies
Middle-East and Africa Smart Airport Market
Airport Technologies
Airport Interactive Kiosk Market
Airport Technologies
Smart Baggage Handling System Market
Airport Technologies
Airport Information Display System Market
Airport Technologies
Bird Detection System for Airports Market
Airport Technologies
Asia-Pacific Smart Airport Market
Airport Technologies
Airport Information Systems Market
Airport Technologies
Advanced Airport Technologies Market
Airport Technologies
Airport Baggage Tracking Systems Market
Airport Technologies
Airport Smart Lighting Market
Airport Technologies
Air Traffic Smart Tower Solutions Market
Airport Technologies
Integrated Proximity and Taxiway Guidance Light Systems on Aircraft Exteriors Market
Airport Technologies
Europe Smart Airport Market
Airport Technologies
Middle-East and Africa Airport Ground Handling Systems Market
Airport Technologies
America Airport Ground Handling Systems Market