
 Asia-Pacific Freighter Aircraft Market | 2026-2036
Asia-Pacific Freighter Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Freighter Aircraft Market Outlook
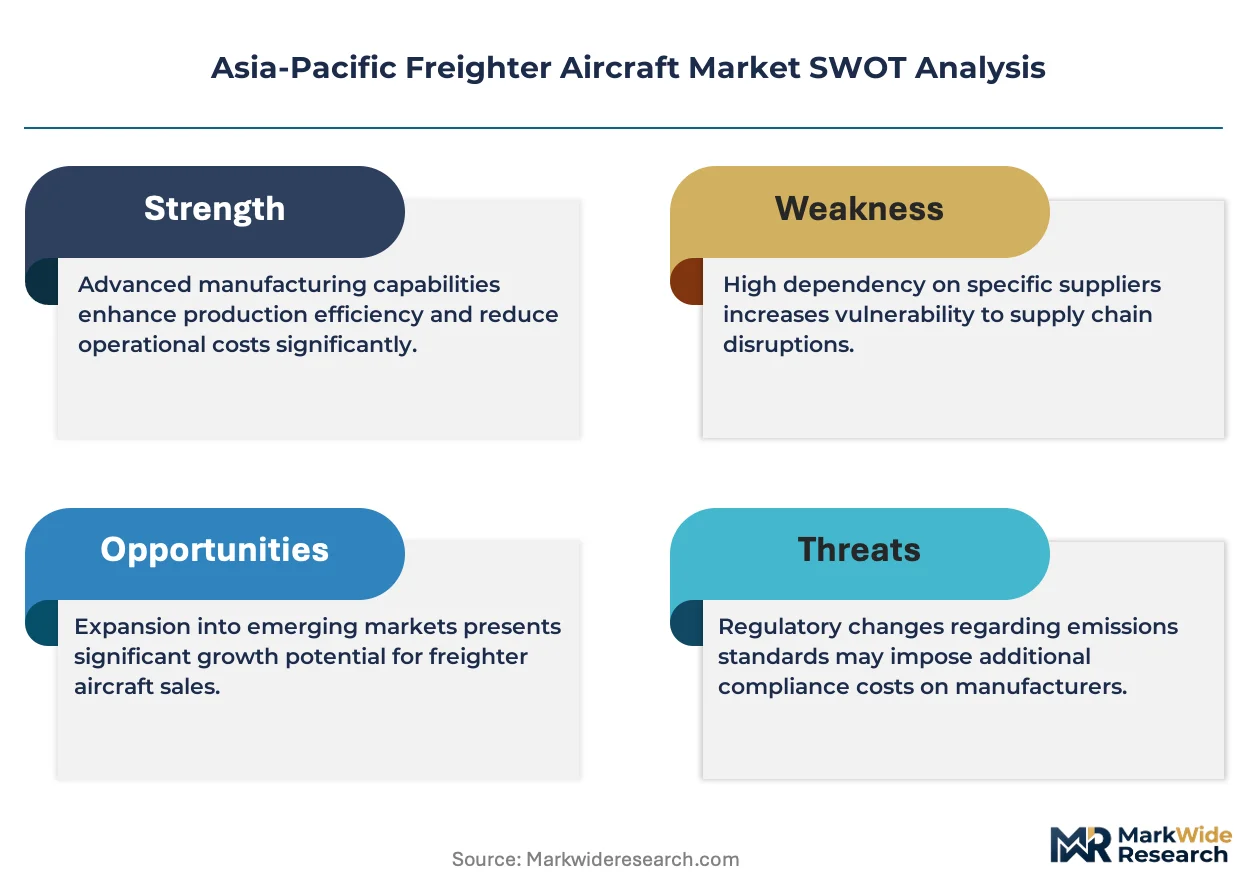
E-commerce fulfillment is shifting toward dedicated freighter networks across Southeast Asia and Oceania. Airbus SE leverages its A350F platform to compete in the above-60-ton payload segment, while The Boeing Company sustains dominance through 777-8F production commitments from regional cargo carriers. Singapore Technologies Engineering Ltd. anchors the passenger-to-freighter conversion ecosystem with heavy maintenance infrastructure at Changi.
Asia-Pacific freighter aircraft are fixed-wing cargo platforms engineered for palletized and containerized freight transport, typically operating at cruise altitudes with maximum takeoff weights exceeding 200 metric tons for widebody variants. Dedicated freighters command the largest installed base, though passenger-to-freighter conversions represent the fastest-growing value pool as feedstock from retiring A320ceo and 737-800 fleets expands. Turbofan engine technology leads new-build demand, while conventional powertrains still occupy the regional freighter retrofit segment where capital constraints persist.
China's CAAC enforces progressive noise and emissions standards that shape new aircraft certification timelines, while Australia's CASA mandates fatigue management protocols influencing conversion inspection intervals. Japan's MLIT coordinates bilateral landing rights that determine route density for payload capacity planning. Stakeholders must weigh China's COMAC C919 freighter derivative against established OEM delivery slots when forecasting fleet renewal cycles.
Market Dynamics
China's MIIT emissions standards and dual carbon goals are compressing conversion timelines for aging regional freighter fleets. Regional cargo carriers face simultaneous pressure to retire turboprop-powered feedstock aircraft and secure fuel-efficient turbofan replacements before 2030 compliance windows close.
Growth Catalysts
- E-commerce corridor densification:Dedicated freighter networks across Southeast Asia's manufacturing belts require palletized cargo capacity for same-day fulfillment. Indonesia's logistics providers are expanding narrowbody freighter operations to serve Java's industrial zones.
- MIIT fuel efficiency mandates:China's progressive emissions standards for commercial aviation are accelerating turbofan adoption. New-build freighter certification timelines now prioritize engines meeting Stage V noise requirements.
- Feedstock availability surge:Retiring A320ceo and 737-800 passenger fleets across India and Australia are expanding conversion-ready airframe pools. Singapore's heavy maintenance infrastructure anchors regional P2F modification capacity.
Market Restraints
- Turbofan engine supply concentration:Production slots for next-generation powerplants concentrate with two global OEMs, creating 18-24 month delivery backlogs for regional carriers.
- Composite airframe conversion limits:Carbon-fiber barrel construction on newer passenger jets restricts traditional cut-and-cap P2F modification techniques, limiting feedstock options for widebody conversion programs.
- Slot coordination complexity:Japan's MLIT bilateral landing rights negotiations create route density uncertainty, complicating payload capacity planning for Tokyo-Osaka freight corridors.
Strategic Opportunities
- Vietnam manufacturing belt penetration:Northern Vietnam's electronics assembly clusters lack dedicated freighter service. Hanoi-Ho Chi Minh City corridors present greenfield cargo network development potential.
- Sustainable aviation fuel infrastructure:Australia's CASA is coordinating SAF blending mandates with airport fuel system upgrades. Early-adopting carriers gain operational preference at Sydney and Melbourne cargo terminals.
- Digital freight matching platforms:Blockchain-enabled capacity exchanges are connecting fragmented Southeast Asian cargo demand with underutilized belly-hold and dedicated freighter space.
Industry Challenges
- Airframe engineering certification backlog:China's CAAC supplemental type certificate reviews for P2F conversions are extending beyond 14 months, delaying revenue service entry for modified aircraft.
- Specialized technician scarcity:Composite repair and avionics integration skills for next-generation freighter modifications concentrate in Singapore and Shanghai, creating recruitment competition across the region.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Freighter Aircraft Market |
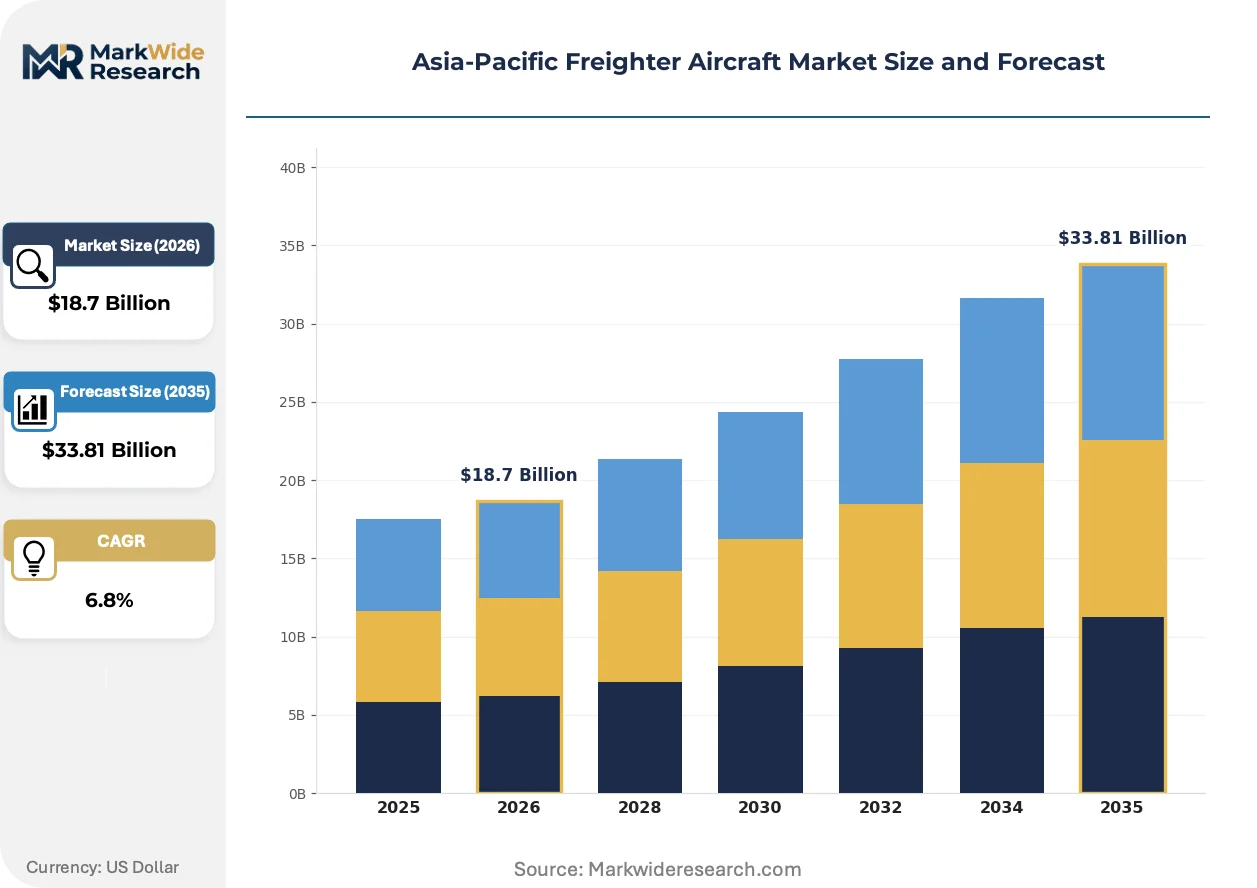
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Dedicated Freighters, Passenger-to-Freighter Conversions, Regional Freighters, Comb freighters End User: Cargo Airlines, E-Commerce Companies, Freight Forwarders, Logistics Providers Payload Capacity: Below 20 Tons, 20-40 Tons, 40-60 Tons, Above 60 Tons Technology: Conventional Engines, Turbofan Engines, Advanced Materials, Autonomous Systems |
| Companies Covered | Airbus SE, The Boeing Company, ATR, Singapore Technologies Engineering Ltd., Guangzhou Aircraft Maintenance Engineering Company Limited (GAMECO), Commercial Aircraft Corporation of China (COMAC), Israel Aerospace Industries, Mitsubishi Heavy Industries, Kawasaki Heavy Industries, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Freighter Aircraft Market Strategic Shifts
Autonomous ground handling systems and predictive maintenance algorithms are compressing turnaround times at Asia-Pacific cargo hubs. Digital twin technology for engine performance monitoring is spreading from major carriers to mid-tier operators.
Autonomous cargo loading systems are automating pallet positioning and restraint verification at Changi and Hong Kong terminals. Ground handlers at these facilities are deploying robotic guided vehicles for main-deck container movement, cutting loading cycle times by one-third. This technology is automating night-shift operations where skilled labor availability constrains throughput expansion.
China's MIIT is enforcing progressive noise and emissions standards that reshape freighter certification pathways. New aircraft must demonstrate 16% fuel efficiency improvements over baseline 2015 levels to receive domestic operating permits. Widebody freighter operators serving Yangtze River Delta manufacturing corridors are prioritizing engine upgrades to maintain route access.
Shippers are consolidating freight procurement through integrated logistics platforms that blend dedicated freighter, belly-hold, and multimodal capacity. Electronics manufacturers in India's Mumbai-Pune belt are bypassing traditional forwarder relationships to contract directly with airline cargo divisions. This behavioral shift concentrates volume commitments with carriers offering guaranteed block-space agreements.
Asia-Pacific Freighter Aircraft Market Segmentation
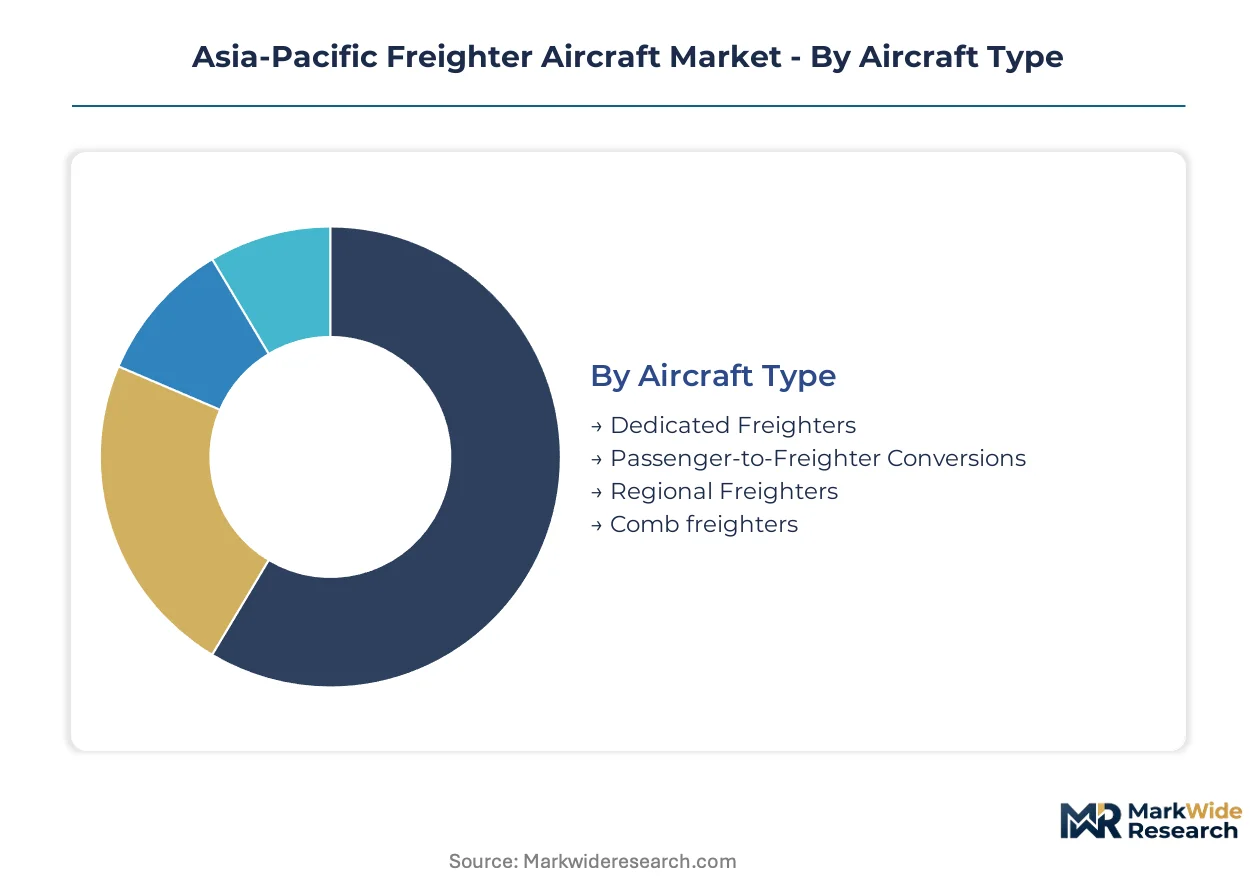
Freighter aircraft segmentation in Asia-Pacific reflects divergent operational economics across corridor densities and regulatory compliance windows. Payload capacity and propulsion technology choices determine fleet renewal priorities for carriers navigating China's MIIT emissions mandates and Indonesia's archipelago logistics demands.
Aircraft Type:
Standalone dedicated freighters dominate trunk routes, while embedded conversion programs extend asset lifecycles for regional operators managing capital constraints.
- Dedicated Freighters:Factory-built cargo platforms with reinforced floors and main-deck cargo doors engineered for 200+ metric ton MTOW operations. China's Yangtze River Delta electronics exporters favor these for guaranteed block-space contracts to North American destinations.
- Passenger-to-Freighter Conversions:Modified narrowbody airframes from retiring A320ceo and 737-800 fleets receive supplemental type certificates for palletized freight. Singapore Technologies Engineering Ltd. anchors regional modification capacity at Changi, though China's CAAC certification backlogs now exceed fourteen months.
- Regional Freighters:Turboprop and small jet platforms serving secondary airports with shorter runway constraints across Indonesia's Java corridor and the Philippines' Visayas archipelago.
- Comb Freighters:Mixed-configuration aircraft carrying palletized cargo on main deck with limited passenger capacity aft, deployed on thin routes where pure freighter economics fail.
Dedicated freighters lead volumes today; passenger-to-freighter conversions are gaining share fastest.
End User:
Procurement patterns split between asset-owning carriers seeking fleet control and platform-dependent intermediaries optimizing for variable capacity.
- Cargo Airlines:Dedicated operators like Cathay Pacific Cargo and Korean Air Cargo maintain owned freighter fleets for scheduled network density. These carriers prioritize above-60-ton payload platforms for transpacific corridor dominance.
- E-Commerce Companies:Alibaba's Cainiao and JD Logistics are acquiring narrowbody freighters for captive Southeast Asian fulfillment networks, bypassing traditional forwarder relationships.
- Freight Forwarders:Kuehne+Nagel and DHL Global Forwarding contract block-space agreements rather than own metal, concentrating volume commitments with turbofan-equipped carriers meeting sustainability disclosure requirements.
- Logistics Providers:Integrated operators like SF Holding combine owned freighters with belly-hold procurement across multimodal networks serving India's Mumbai-Pune manufacturing belt.
Cargo airlines retain the largest installed base; e-commerce companies are expanding fleet ownership most aggressively.
Payload Capacity:
Corridor density and cargo commodity mix dictate optimal payload tier selection for fleet planners.
- Below 20 Tons:Narrowbody and regional jet platforms serving feeder routes from Vietnam's northern electronics clusters to Hanoi hub operations. These aircraft face the steepest regulatory pressure under China's progressive noise standards.
- 20-40 Tons:Converted narrowbody workhorses dominate intra-ASEAN e-commerce fulfillment, with Indonesia's Lion Air Group expanding this segment for Java industrial zone coverage.
- 40-60 Tons:Widebody conversion candidates from A330 and 767 passenger retirements, positioned for Australia-Asia intermediate density corridors where CASA fatigue protocols influence inspection intervals.
- Above 60 Tons:Factory-built widebody platforms including 777-8F and A350F variants. Airbus SE competes in this segment against Boeing's established delivery slots with Asia-Pacific cargo carriers.
Above-60-ton platforms command premium pricing; below-20-ton segments face the most acute replacement pressure from emissions mandates.
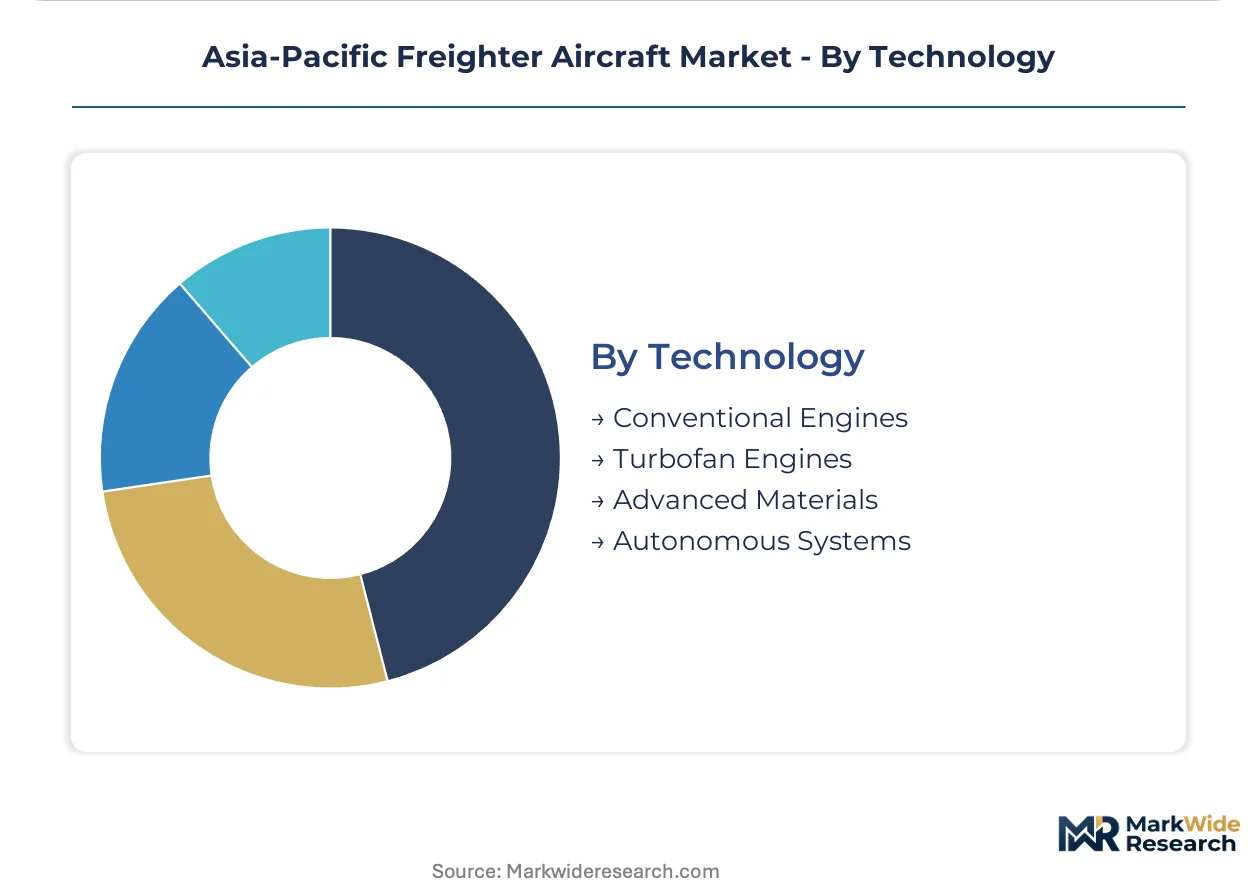
Technology:
Propulsion and materials choices determine compliance eligibility for China's domestic operating permits and Australia's SAF blending trajectory.
- Conventional Engines:Mature turbofan and turboprop powertrains from CFM56 and PW4000 families. These dominate the conversion feedstock pool but face progressive exclusion from MIIT-certified operations.
- Turbofan Engines:Next-generation powerplants including GE9X and Trent XWB variants delivering Stage V noise compliance and 16% fuel efficiency gains over 2015 baselines. Production backlogs now stretch eighteen to twenty-four months.
- Advanced Materials:Carbon-fiber reinforced structures reducing operating empty weight, though composite barrel construction complicates traditional cut-and-cap conversion techniques for newer airframes.
- Autonomous Systems:Ground-based robotic cargo handling and predictive maintenance algorithms compressing turnaround times at Changi and Hong Kong terminals.
Turbofan engines lead new-build demand; autonomous systems are penetrating ground operations most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta manufacturing corridors anchor freighter demand across the Asia-Pacific, with electronics exporters requiring guaranteed block-space capacity to North American destinations. China's MIIT emissions mandates and Indonesia's archipelago logistics requirements create divergent fleet renewal pressures across national markets.
China
Electronics manufacturers in Shanghai and Suzhou drive widebody freighter procurement for transpacific routes. MIIT's Stage V noise requirements and 16% fuel efficiency mandates compress conversion timelines for aging regional fleets. The Yangtze River Delta corridor concentrates demand for above-60-ton payload platforms serving guaranteed block-space contracts.
Japan
MLIT bilateral landing rights negotiations determine route density for Tokyo-Osaka freight corridors, complicating payload capacity planning for domestic carriers. Automotive parts exporters in Nagoya and semiconductor shippers in Kyushu require precision-scheduled narrowbody freighter services. Kansai International Airport anchors heavy maintenance infrastructure supporting regional conversion programs.
India
Pharmaceutical and automotive exporters in the Mumbai-Pune logistics belt are bypassing traditional forwarders to contract directly with airline cargo divisions. DGFT export incentive schemes accelerate dedicated freighter deployment for temperature-sensitive cargo. Bengaluru's electronics manufacturing clusters lack sufficient dedicated freighter service to European destinations.
Singapore
Changi Airport's heavy maintenance infrastructure anchors the regional passenger-to-freighter conversion ecosystem. CAAS coordinates SAF blending mandates with airport fuel system upgrades, creating operational preference for early-adopting carriers. The city-state's logistics providers are expanding narrowbody freighter operations to serve Vietnam's northern manufacturing zones.
Indonesia
Lion Air Group and other domestic carriers are expanding below-20-ton and 20-40-ton payload segments for Java industrial zone coverage. Archipelago geography necessitates turboprop and small jet platforms serving secondary airports with shorter runway constraints. Jakarta's Soekarno-Hatta International Airport faces slot coordination bottlenecks limiting night freighter expansion.
Asia-Pacific Freighter Aircraft Market Competitive Environment
Production slot accumulation dominates the current landscape as carriers secure delivery positions eighteen to twenty-four months ahead of fleet renewal deadlines. The market structures around three tiers: factory-built widebody OEMs, conversion specialists with heavy maintenance infrastructure, and emerging domestic manufacturers seeking certification pathways. Strategic archetypes include turbofan technology leaders, P2F modification anchors, and state-backed challengers. Competitive moves concentrate on securing feedstock airframe pools and expanding conversion hangar capacity.
Within the factory-built tier, Airbus SE and The Boeing Company exemplify divergent platform strategies for above-60-ton payload dominance. Singapore Technologies Engineering Ltd. anchors the conversion ecosystem through Changi-based heavy maintenance infrastructure. Commercial Aircraft Corporation of China represents the state-backed challenger archetype, with its C919 freighter derivative competing for domestic certification timelines against established delivery slots.
| Leading Market Players |
|---|
| Airbus SE |
| The Boeing Company |
| ATR |
| Singapore Technologies Engineering Ltd. |
| Guangzhou Aircraft Maintenance Engineering Company Limited (GAMECO) |
| Commercial Aircraft Corporation of China (COMAC) |
| Israel Aerospace Industries |
| Mitsubishi Heavy Industries |
| Kawasaki Heavy Industries |
| Others |
Value Chain & Pricing Dynamics
Turbofan engine production slot scarcity simultaneously inflates capital costs and concentrates supplier leverage among two global OEMs. China's MIIT emissions mandates compress conversion timelines, forcing regional carriers to accept premium pricing for Stage V-compliant powerplants or face route exclusion.
Pricing Analysis
Input-cost pass-through from engine OEMs dominates freighter aircraft pricing, with GE9X and Trent XWB production backlogs extending eighteen to twenty-four months. Three-tier pricing structure across premium turbofan new-builds, standard conversion programs, and economy-tier turboprop retrofits reflects certification grade and fuel efficiency performance. Cost compression in the below-20-ton segment is intensifying because China's progressive noise standards accelerate fleet retirement. E-commerce logistics providers show least price sensitivity due to captive network requirements, while regional freight forwarders face acute margin pressure.
Supply Chain Analysis
Composite airframe feedstock rests on Airbus and Boeing production schedules in France, Germany, and the United States, with carbon-fiber barrel construction complicating traditional cut-and-cap modification techniques. Specialized avionics integration and Stage V engine components draw from Japanese and South Korean precision manufacturing clusters. Single-source vulnerability concentrates in turbofan powerplant supply, where production capacity constraints create order backlogs. Distribution runs through heavy maintenance infrastructure at Singapore's Changi and China's Guangzhou, with conversion capacity determining regional feedstock absorption rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Asia-Pacific freighter aircraft hinges on turbofan technology premiums and conversion program efficiency gains as emissions mandates retire less efficient feedstock.
For Market Incumbents: Deepen vertical integration into passenger-to-freighter conversion capacity at Changi and Guangzhou to secure feedstock pools from retiring A320ceo and 737-800 fleets. Expand turbofan engine maintenance, repair, and overhaul capabilities to capture recurring revenue streams as China's MIIT mandates accelerate technology turnover. For New Entrants and Emerging Players: The price-point gap between premium widebody new-builds and economy-tier turboprop conversions creates white-space opportunity in Vietnam's northern electronics manufacturing belt and India's Bengaluru corridor. Target below-20-ton payload segments with turboprop platforms serving secondary airports across Indonesia's archipelago, leveraging direct contracts with electronics manufacturers bypassing traditional forwarder relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among conversion specialists with heavy maintenance infrastructure and established CAAC supplemental type certificate pathways. Acquisition focus should center on Singapore-based and Chinese modification facilities with proven feedstock access. Watch CAAC certification timeline compression as the inflection signal indicating regulatory capacity expansion and conversion revenue acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Passenger-to-Freighter Conversion Capacity Expansion | Captures retiring A320ceo and 737-800 feedstock pools across India and Australia. |
| Turbofan Engine Upgrade Programs | Ensures MIIT Stage V compliance and route access in Yangtze River Delta corridors. |
| Sustainable Aviation Fuel Infrastructure Investment | Positions early adopters for CASA blending mandates at Sydney and Melbourne terminals. |
| Digital Freight Matching Platform Development | Connects fragmented Southeast Asian cargo demand with underutilized belly-hold capacity. |
| Autonomous Ground Handling System Deployment | Compresses turnaround times at Changi and Hong Kong cargo terminals by one-third. |
Study Parameters
Coverage spans China, Japan, India, Singapore, and Indonesia, with primary inputs from each market's cargo airline fleet planners, heavy maintenance facility directors, and CAAC certification engineers. Secondary validation draws from MIIT emissions filings, CAAC supplemental type certificate databases, IATA cargo traffic statistics, and airline investor disclosures. Fleet planners at Cathay Pacific Cargo, Korean Air Cargo, and SF Holding provided operational economics perspectives. Bottom-up airframe demand modeling triangulates against top-down logistics sector growth projections.
Rate-of-change decomposition separates fleet replacement cycles from net capacity expansion across the projection horizon. Segmentation dimensions include aircraft type, payload capacity tier, propulsion technology, and end-user procurement pattern. CAGRs derive from logistics sector output correlations, e-commerce fulfillment density trajectories, and regulatory compliance window analysis. Forecast inputs incorporate MIIT emissions mandate phase-in schedules and feedstock availability from passenger fleet retirements.
Caveats apply where CAAC certification timeline extensions or turbofan engine production delays could materially shift the outlook. Forecasts reflect assumptions around bilateral landing rights stability and SAF infrastructure deployment pace. A small set of triggers—MIIT mandate acceleration, composite airframe conversion breakthroughs, and Vietnam manufacturing corridor densification—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Pushback Tugs Market
Aircraft
Japan Aerospace and Defense Market
Aircraft
Aircraft Exterior Mounts Market
Aircraft
Europe Freighter Aircraft Market
Aircraft
Afterburner Market
Aircraft
Japan Aviation Market
Aircraft
Strategic Bomber Market
Aircraft
Airplane Landing Gear Market
Aircraft
US Business Jet Market
Aircraft
Aircraft Strut Market
Aircraft
Amphibious Aircraft Market
Aircraft
Military Aircraft Market
Aircraft
Commercial Aircraft Lavatory System Market
Aircraft
Active Air Deflector Market
Aircraft
France Aviation Market
Aircraft
Middle-East and Africa Business Jet Market