
 Global Electric Drone Market | 2026-2036
Global Electric Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Drone Market Analysis
FAA Remote ID rules are repositioning the cost-of-entry calculus for commercial electric drone operators, forcing hardware retrofits and software stack upgrades across the US fleet. SZ DJI Technology Co. Ltd. leverages its Shenzhen manufacturing base to absorb compliance costs through vertical integration. AeroVironment Inc. anchors its defense and agricultural portfolios with ruggedized platforms built for contested electromagnetic environments. Skydio differentiates through autonomous flight stacks that navigate complex obstacle fields without GPS dependency.
Electric drones are unmanned aerial vehicles powered by battery-electric propulsion systems, typically employing lithium-polymer or lithium-ion cells driving brushless DC motors with thrust-to-weight ratios exceeding two-to-one for multi-rotor configurations. These systems execute aerial data collection, payload transport, and remote sensing missions across commercial and government applications. Multi-rotor architectures dominate consumer and light-commercial segments due to mechanical simplicity and vertical takeoff capability, while fixed-wing platforms sustain longer endurance missions in agricultural mapping and pipeline inspection where runway access or catapult launch is feasible. AI-powered flight control represents the fastest-growing technology segment as operators demand predictive maintenance and dynamic mission replanning without ground station tethering.
The European Union Aviation Safety Agency enforces CE marking and specific-category operational authorizations under EU Regulation 2019/947, while China's Civil Aviation Administration administers real-name registration and geo-fencing protocols through its UAS Traffic Management framework. These overlapping compliance regimes fragment certification pathways and inflate type-approval costs for manufacturers seeking cross-border sales. Stakeholders must monitor convergence between national U-space implementations and emerging detect-and-avoid mandates that will determine which platform architectures qualify for beyond-visual-line-of-sight operations at scale.
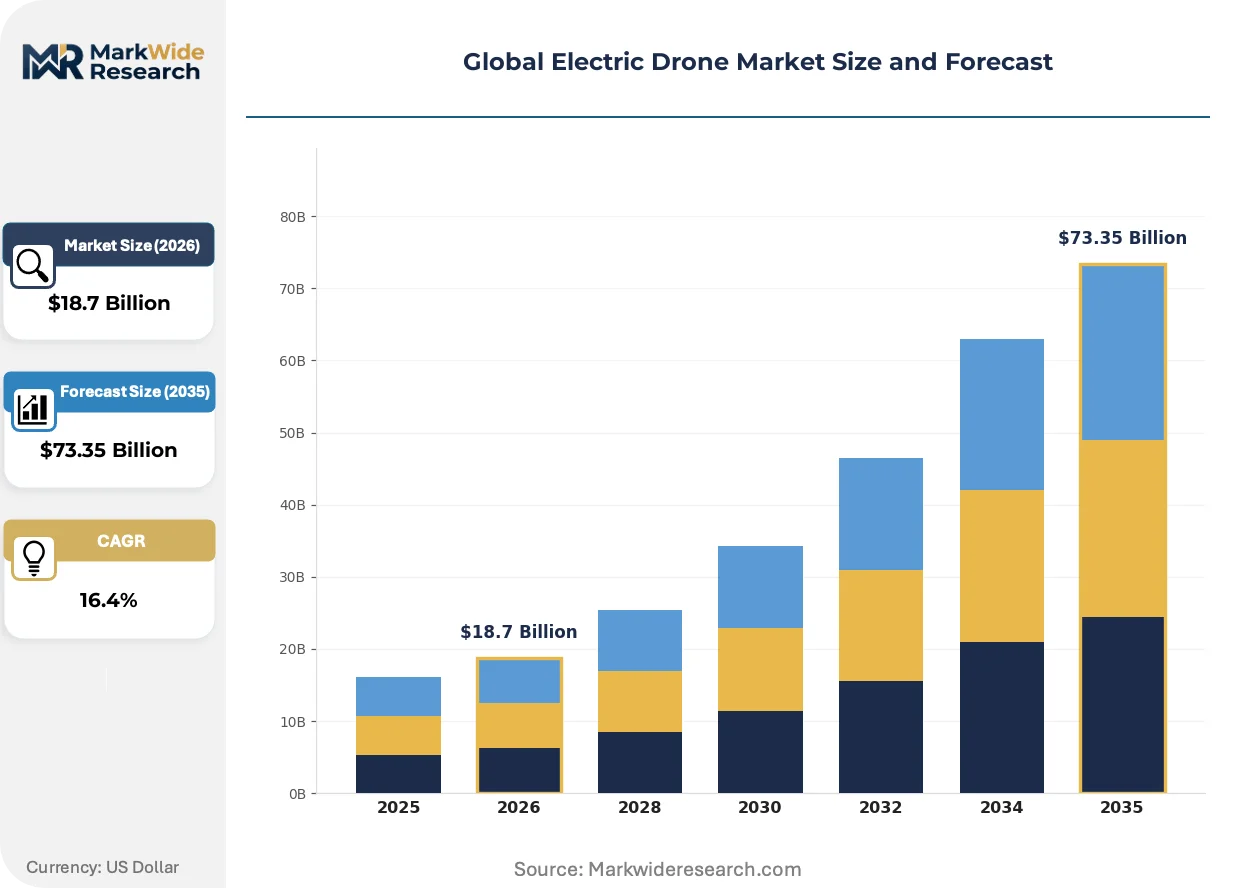
Market Dynamics
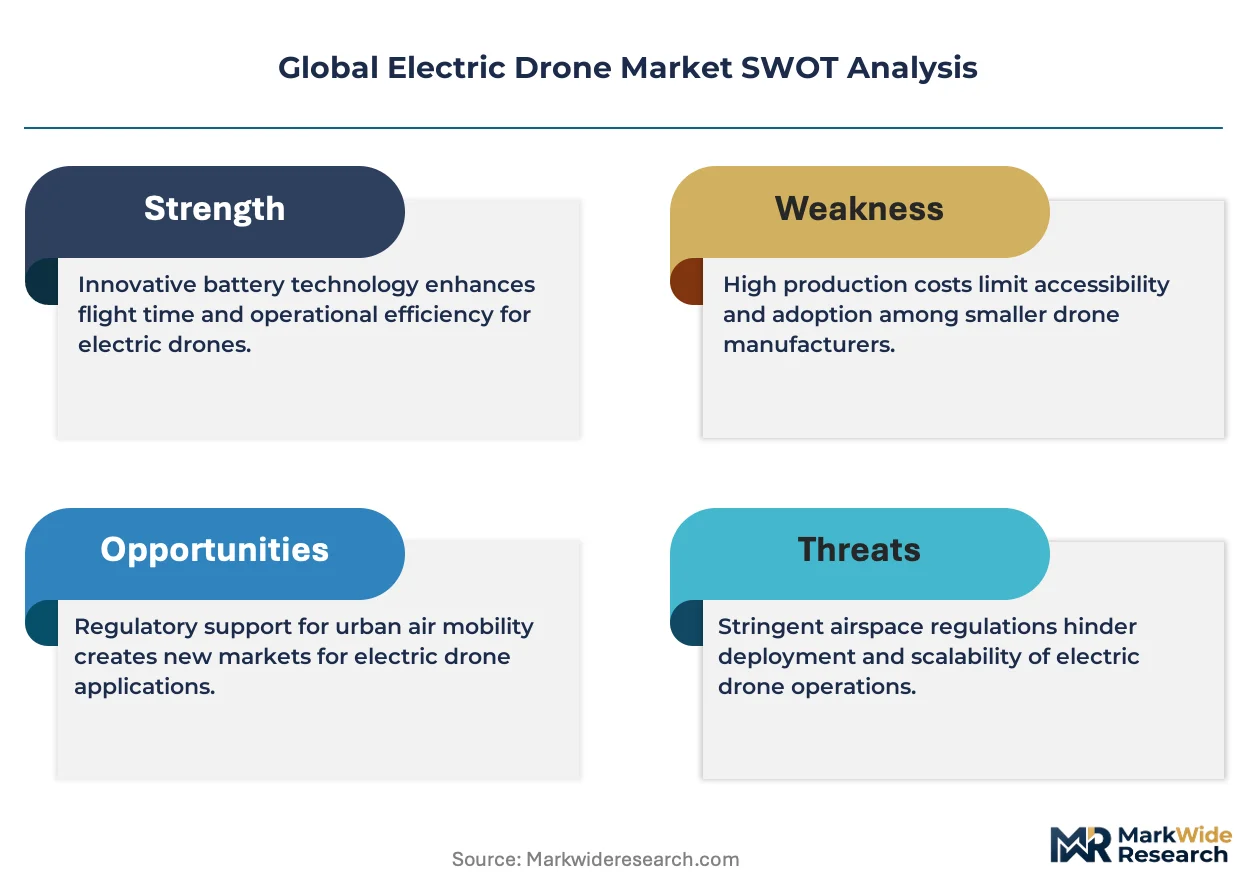
AI-powered flight control systems are compressing mission planning cycles and eliminating ground-station dependency, while Shenzhen's manufacturing cluster absorbs compliance costs through captive component supply.
Growth Catalysts
- EU U-space framework:The European Union Aviation Safety Agency's detect-and-avoid mandates are opening beyond-visual-line-of-sight corridors for commercial logistics operators.
- Precision agriculture:Brazilian commercial farms are deploying multi-spectral sensors for soil mapping and variable-rate input application.
- Lithium-polymer energy density:Cell chemistry advances are extending fixed-wing endurance past four hours for pipeline inspection missions.
Market Restraints
- Cobalt price volatility:Battery pack costs fluctuate with Democratic Republic of Congo mining output disruptions.
- Shenzhen supply concentration:Seventy percent of brushless motor production sits within fifty kilometers of one metropolitan cluster.
- FAA Remote ID retrofit burden:Hardware compliance mandates are stranding pre-2021 commercial fleets without broadcast modules.
Strategic Opportunities
- India agricultural extension:Subsidy programs under the PLI scheme are lowering acquisition barriers for cooperative farming collectives.
- Cellular command-and-control:5G network slicing is enabling real-time video relay without dedicated radio links.
- Swarm coordination algorithms:Distributed flight planning allows single operators to manage coordinated multi-vehicle missions.
Industry Challenges
- Autonomy software certification:No harmonized standard exists for validating machine-learning flight decisions in safety-critical airspace.
- Electromagnetic interference hardening:Defense and utility operators demand platforms that maintain navigation in GPS-denied environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Drone Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Multi-Rotor, Single Rotor, Hybrid Application: Agriculture, Surveillance, Delivery, Inspection End User: Aerospace, Construction, Energy, Logistics Technology: GPS, AI-Powered, LiDAR, 4G/5G |
| Companies Covered | SZ DJI Technology Co. Ltd., AeroVironment Inc., Parrot SA, Northrop Grumman Corporation, EHang, Yuneec International, Autel Robotics, Teledyne FLIR LLC, Skydio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Drone Market Emerging Trajectories
Autonomous navigation stacks are eliminating operator-to-vehicle ratios that have constrained fleet economics since commercialization began.
Computer-vision-based obstacle avoidance is rewriting mission profiles for infrastructure inspection. Power grid operators in Germany now fly turbine-close passes without pre-surveyed flight paths. The technology compresses pre-mission site preparation from days to hours.
China's Civil Aviation Administration is tightening geo-fencing protocols through its UAS Traffic Management framework. Manufacturers must pre-load no-fly coordinates at firmware level. Export-oriented Shenzhen producers are bifurcating product lines between domestic-locked and international-unlocked variants.
Utility procurement departments are unbundling hardware acquisition from pilot training and maintenance contracts. European transmission system operators now source platforms from one vendor and flight services from certified operator networks. This shift is visible most acutely in Nordic countries where state grid monopolies dominate capital allocation.
Global Electric Drone Market Segmentation
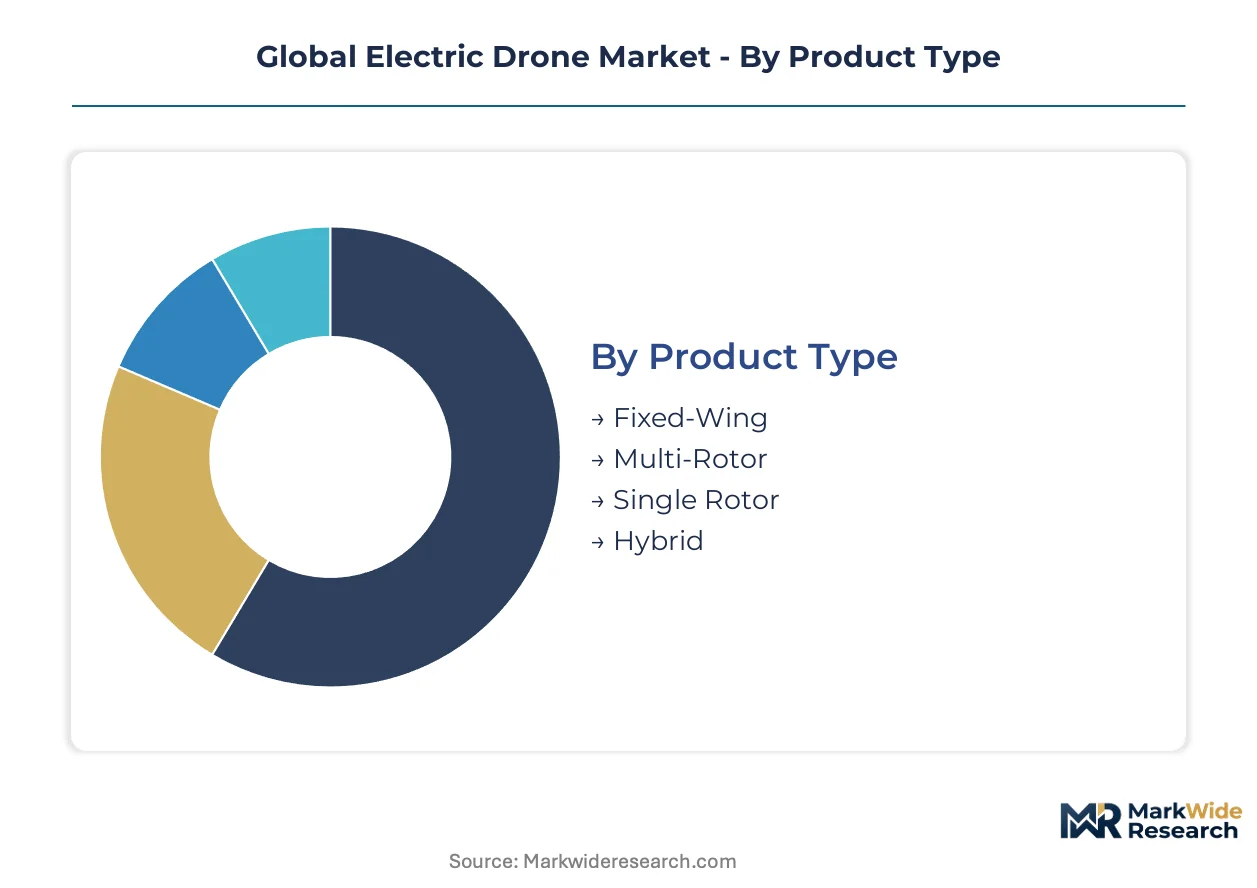
Electric drone procurement decisions hinge on certification pathways that vary dramatically across platform architectures. Operators must match segment-specific compliance burdens against mission requirements and fleet economics.
Product Type:
FAA Part 107 waivers and EASA specific-category authorizations impose divergent testing regimes on each airframe class, with multi-rotor platforms facing simplified type-approval in exchange for endurance limitations.
- Fixed-Wing:Catapult-launched or runway-dependent architectures achieve four-hour endurance through efficient lift-to-drag ratios and optimized propulsion layouts. Pipeline operators in Germany favor these platforms for linear infrastructure surveys where launch-site access exists.
- Multi-Rotor:Brushless DC motors driving three-to-eight rotor configurations dominate commercial procurement volumes due to vertical takeoff capability and mechanical redundancy. Brazilian precision agriculture deployments concentrate demand here for multi-spectral crop monitoring missions.
- Single Rotor:Helicopter-style platforms with swashplate mechanics offer payload efficiency for heavy-lift logistics trials.
- Hybrid:Tilt-rotor and fixed-wing transition designs merge endurance advantages with operational flexibility for beyond-visual-line-of-sight corridors.
Leading the category by volume: Multi-Rotor. Growing fastest: Hybrid.
Application:
End-use determines sensor payload integration, flight autonomy requirements, and operator certification tiers that segment procurement budgets.
- Agriculture:Variable-rate input application and soil mapping drive multi-spectral camera integration. Brazilian commercial farms anchor regional demand concentration for normalized difference vegetation index analytics.
- Surveillance:Thermal imaging and persistent loiter requirements shape defense and public safety procurement specifications. Border security agencies prioritize electromagnetic-hardened navigation for contested environments.
- Delivery:Last-mile logistics trials concentrate in China's Guangdong province where Shenzhen manufacturers test parachute and winch release mechanisms.
- Inspection:Power grid operators in Nordic countries unbundle hardware acquisition from flight services, sourcing platforms separately from certified operator networks.
Agriculture commands the largest installed base. Surveillance exhibits the steepest expansion trajectory as defense budgets reallocate toward unmanned systems.
End User:
Capital deployment cycles and maintenance capabilities diverge sharply between government procurement offices and commercial fleet operators.
- Aerospace:Subsystem testing and airframe prototyping drive demand for programmable flight controllers with open autopilot architectures.
- Construction:Progress monitoring and earthworks volumetrics require photogrammetry-grade camera stabilization.
- Energy:Transmission system operators in Germany and Nordic markets source turbine-close inspection platforms with computer-vision obstacle avoidance.
- Logistics:Warehouse inventory drones and last-mile delivery trials concentrate demand in China's Guangdong province.
Energy sector procurement leads by contract value. Logistics is climbing the fastest as 5G network slicing enables real-time command relay.
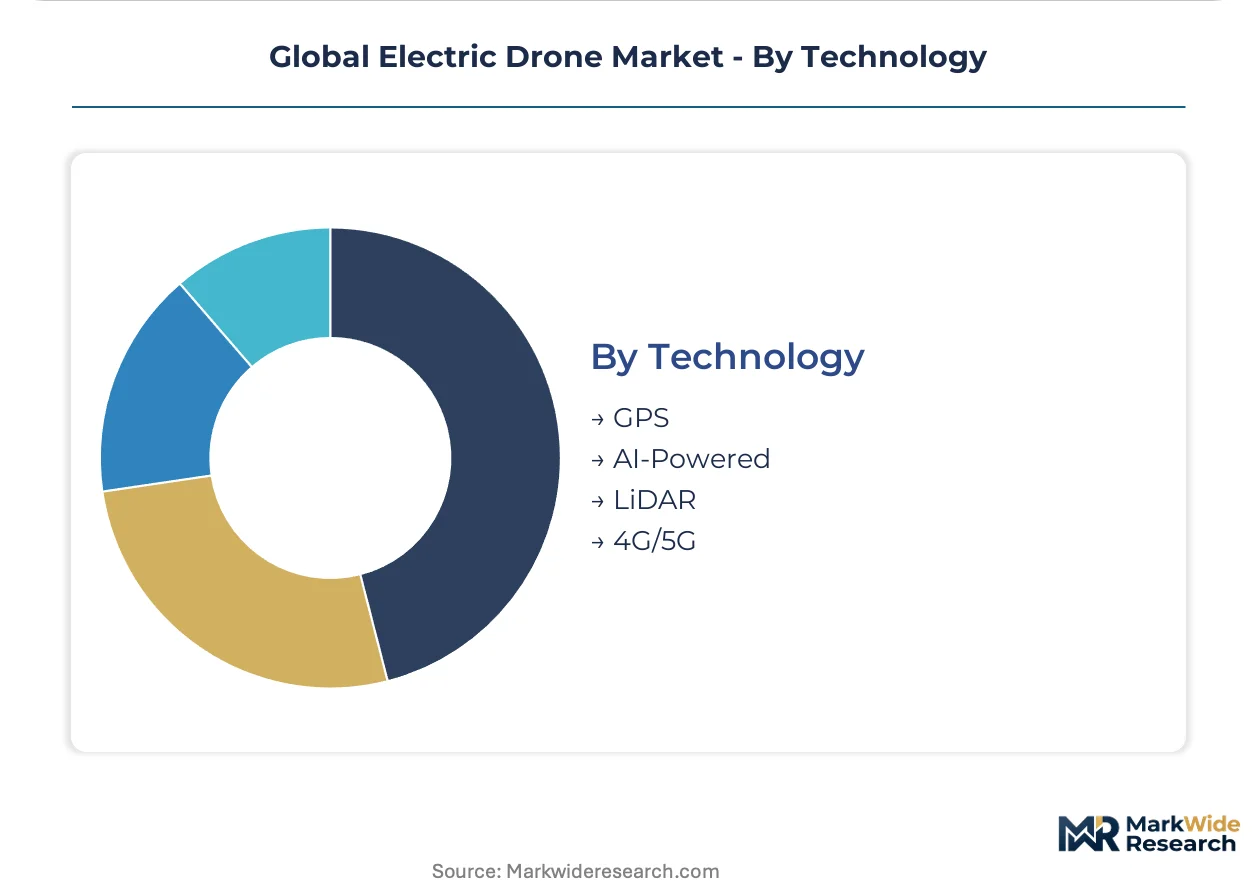
Technology:
Navigation and communications architectures determine regulatory compliance burdens and operational envelope limitations across mission profiles.
- GPS:Satellite-dependent positioning remains baseline for consumer and light-commercial segments despite vulnerability to jamming and spoofing in contested electromagnetic environments.
- AI-Powered:Predictive maintenance algorithms and dynamic mission replanning without ground-station tethering define the fastest-advancing capability tier. Skydio's autonomous flight stacks exemplify this segment's trajectory.
- LiDAR:Point-cloud generation for precision mapping commands premium pricing in surveying and forestry applications.
- 4G/5G:Cellular command-and-control links enable beyond-radio-range operations where network infrastructure permits.
GPS retains dominant share by unit volume. AI-Powered systems are gaining share fastest as operators eliminate ground-station dependency ratios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Guangdong province anchors global manufacturing concentration through Shenzhen's special economic zone status and dense component supplier networks. Tax incentives for high-technology enterprises have compressed production costs for battery-electric propulsion systems. The resulting ecosystem feeds downstream assembly operations across four continents.
United States
Defense procurement and agricultural automation drive commercial fleet expansion. FAA Remote ID mandates require hardware retrofits and software stack upgrades across existing commercial fleets. California's Bay Area hosts autonomy software developers while Texas energy corridors deploy inspection platforms for utility infrastructure.
China
Domestic logistics trials and export manufacturing dominate volume flows. CAAC geo-fencing protocols require firmware-locked no-fly coordinates for domestic market units. Shenzhen's fifty-kilometer manufacturing radius produces seventy percent of global brushless motor supply.
Germany
Power grid inspection and industrial surveying anchor enterprise demand. EASA specific-category authorizations under EU Regulation 2019/947 impose rigorous type-approval testing for beyond-visual-line-of-sight operations. Bavaria's industrial automation cluster integrates drone platforms into precision agriculture and infrastructure monitoring workflows.
Brazil
Commercial farm cooperatives deploy multi-spectral sensors for soil mapping and variable-rate input application. ANVISA coordinates with agricultural regulators on pesticide application certification for unmanned aerial platforms. São Paulo state's agribusiness corridor concentrates precision agriculture adoption among large-scale soybean and sugarcane producers.
India
Subsidy programs under the PLI scheme lower acquisition barriers for cooperative farming collectives. DGFT export promotion frameworks support component manufacturing scale-up. Karnataka's aerospace and defense corridor hosts subsystem testing facilities for flight controller validation.
Global Electric Drone Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. SZ DJI Technology Co. Ltd. anchors volume manufacturing through captive component supply in Shenzhen. Defense contractors maintain electromagnetic-hardened platform portfolios for contested environments. Autonomy software developers differentiate through GPS-independent navigation stacks. Strategic moves concentrate on backward integration into battery cell supply and geographic expansion through certification reciprocity agreements.
Within the vertically integrated tier, SZ DJI Technology Co. Ltd. exemplifies manufacturing scale advantages through upstream control over brushless motor and flight controller production. AeroVironment Inc. and Skydio occupy positions at the specialized-application end, with the former representing defense-electronics integration archetypes and the latter exemplifying autonomous navigation software differentiation. Parrot SA anchors European market presence through regulatory compliance specialization.
| Leading Market Players |
|---|
| SZ DJI Technology Co. Ltd. |
| AeroVironment Inc. |
| Parrot SA |
| Northrop Grumman Corporation |
| EHang |
| Yuneec International |
| Autel Robotics |
| Teledyne FLIR LLC |
| Skydio |
| Others |
Supply Flow & Price Mechanics
Shenzhen's embedded systems engineers concentrate within a fifty-kilometer radius, compressing firmware development costs and widening spreads between premium-certified and economy-tier platform pricing. Labor-cost differentials between this cluster and secondary assembly regions in Mexico and Eastern Europe translate directly into tiered acquisition costs for commercial operators.
Pricing Analysis
Lead-time premiums reward buyers securing production slots from Shenzhen's vertically integrated manufacturers, while spot inventory from distributors carries discounts tied to certification lag. Three-tier pricing structure across premium, standard, and economy levels stratifies by FAA Part 107 waiver status and EASA specific-category authorization. Pricing pressure stems from cobalt price volatility in battery pack assembly, eroding margins at the economy tier. Agricultural cooperatives in Brazil exhibit highest price sensitivity, while defense procurement offices in the United States absorb premium positioning for electromagnetic-hardened navigation.
Supply Chain Analysis
Certification gating through FAA Remote ID mandates and EASA detect-and-avoid protocols fragments supplier qualification pathways and inflates component traceability costs. Manufacturing concentrates in China, South Korea, and Germany, with brushless motor production anchored in Shenzhen's special economic zone. Raw material dependencies span lithium-cobalt oxide cathodes, rare-earth permanent magnets, and carbon-fiber composite airframes. Single-source vulnerability runs through Democratic Republic of Congo mining output for cobalt feedstock. Distribution runs through authorized dealer networks for commercial segments and direct government contracting for defense applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Electric Drone Market functions as a cost-of-compliance arena where FAA Remote ID mandates erect barrier-to-entry moats favoring incumbents with retrofit capital reserves.
For Market Incumbents: Acquire autonomous navigation software stacks to counter GPS-denied navigation threats from defense-electronics specialists. Secure captive lithium-polymer cell supply through backward integration into cathode material processing. Invest in EASA specific-category certification reciprocity to preempt European market access restrictions. For New Entrants and Emerging Players: Enter via India's PLI-subsidized agricultural extension programs where cooperative farming collectives face lowered acquisition barriers. Target precision agriculture applications in Brazil's São Paulo agribusiness corridor as the most penetrable segment. Deploy cellular command-and-control pilot programs leveraging 5G network slicing as the go-to-market wedge. For Investors and Strategic Acquirers: Re-rating potential sits with autonomy software developers given convergence between national U-space implementations and detect-and-avoid mandates opening beyond-visual-line-of-sight corridors. Long-term viability favors platforms with AI-powered flight control architectures decoupled from ground-station dependency. Watch for CAAC export license restrictions on firmware-unlocked variants as the inflection signal for supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Supply | Cathode material processing in Shenzhen absorbs cobalt price volatility exposure for premium platform tiers. |
| EASA Specific-Category Certification Investment | Beyond-visual-line-of-sight authorization unlocks German power grid inspection contracts for compliant operators. |
| Autonomous Navigation Stack Acquisition | Computer-vision obstacle avoidance eliminates pre-surveyed flight path requirements for infrastructure missions. |
| PLI Scheme Partnership in India | Subsidy alignment with Karnataka's aerospace corridor lowers unit economics for agricultural cooperative deployments. |
| 5G Network Slicing Pilot Deployment | Cellular command-and-control enables real-time video relay without dedicated radio link infrastructure. |
Methodological Framework
Multi-period observation of brushless motor production volumes, lithium-polymer cell pricing indices, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with flight controller firmware engineers, agricultural drone fleet operators, defense procurement officers, and EASA certification consultants. Secondary validation drew from FAA Remote ID compliance databases, CAAC UAS Traffic Management framework documents, SEC filings of listed component suppliers, and customs records of rare-earth magnet trade flows. Bottom-up platform shipment tallies triangulated against top-down addressable market sizing across the projection horizon.
Input-output matrices modeled unit economics across product type, application, end user, and technology segmentation dimensions, with additional granularity for certification pathway clusters. CAGRs were derived from regression analysis of historical shipment trajectories against driver variables including battery energy density improvements and regulatory mandate implementation schedules. Forecast inputs incorporated pipeline inspection mission expansion in German energy corridors and precision agriculture subsidy uptake in Brazilian commercial farm cooperatives.
Forecast precision tightens around the base case; tail outcomes carry wider variance under cobalt supply disruption scenarios or accelerated detect-and-avoid mandate harmonization. Model outputs reflect assumptions on lithium-ion cell chemistry cost curves and cross-border certification reciprocity timelines. A model refresh is warranted upon material change in FAA beyond-visual-line-of-sight waiver issuance velocity or CAAC export control tightening on firmware-unlocked variants.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Airborne Digital Battlefield Market
UAV
Asia-Pacific Tethered Drone Market
UAV
Unmanned Combat Aerial Vehicle Market
UAV
Autonomous Aircraft Cameras Market
UAV
Drone-As-A-Service Market
UAV
Drone Payload Market
UAV
Drone Data Management Market
UAV
Fuel Cell UAV Market
UAV
North America Tactical UAV Market
UAV
Global Smart Commercial Drones Market
UAV
Global Drone Light Shows Market
UAV
Electric Unmanned Aerial Vehicle Market
UAV
Miniature Drone Market
UAV
Global Drone Services Market
UAV
North America Small UAV Market
UAV
Global Aerial Survey Services Market