
 North America Aircraft Manufacturing Market | 2026-2036
North America Aircraft Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Aircraft Manufacturing Market Analytics
Mexico's aerospace corridor from Querétaro to Baja California is rewriting supply chain geography for North American aircraft manufacturing. The Boeing Company leverages its extensive Washington state production infrastructure for wide-body assembly. Lockheed Martin Corporation dominates military aircraft programs with sustained R&D intensity in stealth and autonomous systems. RTX Corporation anchors propulsion and avionics supply through differentiated engine architectures across commercial and defense platforms.
North America aircraft manufacturing encompasses the design, fabrication, assembly, and certification of fixed-wing and rotary-wing vehicles operating at altitudes up to approximately 45,000 feet, utilizing aluminum-lithium alloys, carbon fiber reinforced polymers, and titanium structures to achieve strength-to-weight ratios exceeding 200 kN·m/kg. The primary purpose spans commercial passenger transport, military mission execution, cargo logistics, and emerging urban air mobility services. Commercial aircraft commands the largest value pool among product types, though drones represent the fastest-expanding segment driven by defense and logistics applications. Aerospace materials technology leads margin capture due to composite formulation patents, while avionics systems compete on software-defined architecture integration.
The FAA enforces Part 25 airworthiness standards that dictate structural integrity and system redundancy for transport category aircraft, while EPA regulations constrain volatile organic compound emissions from coating and finishing operations. The U.S. Department of Defense procurement frameworks shape demand cycles through multi-year program commitments and foreign military sales authorizations. Stakeholders must monitor how FAA reauthorization priorities and defense budget appropriations recalibrate production schedules and certification timelines.
Market Dynamics
Defense procurement commitments from the U.S. Department of Defense sustain multi-year production backlogs, while FAA airworthiness certification timelines compress supplier delivery windows and reshape capital allocation across the manufacturing base.
Growth Catalysts
- Defense Procurement Frameworks:Multi-year program commitments from the U.S. Department of Defense generate predictable demand streams for military aircraft and sustain supplier ecosystem viability across the Southeast U.S. manufacturing corridor.
- Composite Material Patents:Carbon fiber reinforced polymer formulations with strength-to-weight ratios exceeding 200 kN·m/kg enable next-generation airframe designs that reduce fuel consumption and extend operational range.
- Mexico Aerospace Corridor:Supplier concentration from Querétaro to Baja California lowers component costs and shortens logistics lead times for final assembly operations in the United States.
Market Restraints
- Titanium Supply Concentration:Limited qualified suppliers for aerospace-grade titanium alloys create input cost volatility and single-source dependency risks for structural component manufacturers.
- FAA Part 25 Certification Friction:Airworthiness standards for transport category aircraft impose multi-year validation timelines that delay new platform introductions and freeze design iterations.
- EPA Emissions Constraints:Volatile organic compound regulations on coating and finishing operations restrict process flexibility and require capital-intensive abatement installations.
Strategic Opportunities
- Urban Air Mobility Services:Electric vertical takeoff and landing platforms open new addressable demand in metropolitan logistics and regional passenger transport below traditional airline thresholds.
- Software-Defined Avionics:Open architecture integration enables hardware-agnostic upgrades and creates recurring revenue streams through firmware subscriptions across installed commercial fleets.
- Canadian Defense Modernization:NORAD infrastructure investments and Arctic surveillance requirements generate incremental demand for patrol aircraft and northern logistics platforms.
Industry Challenges
- Specialized Workforce Scarcity:Shortages of certified composite technicians and avionics integration engineers constrain production rate ramp-ups and quality assurance throughput.
- Legacy System Integration Complexity:New digital manufacturing systems must interface with decades-old MRO databases and proprietary design archives without disrupting active production lines.
- Foreign Military Sales Authorization Delays:State Department export licensing timelines for defense platforms extend payment cycles and compress working capital efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Aircraft Manufacturing Market |
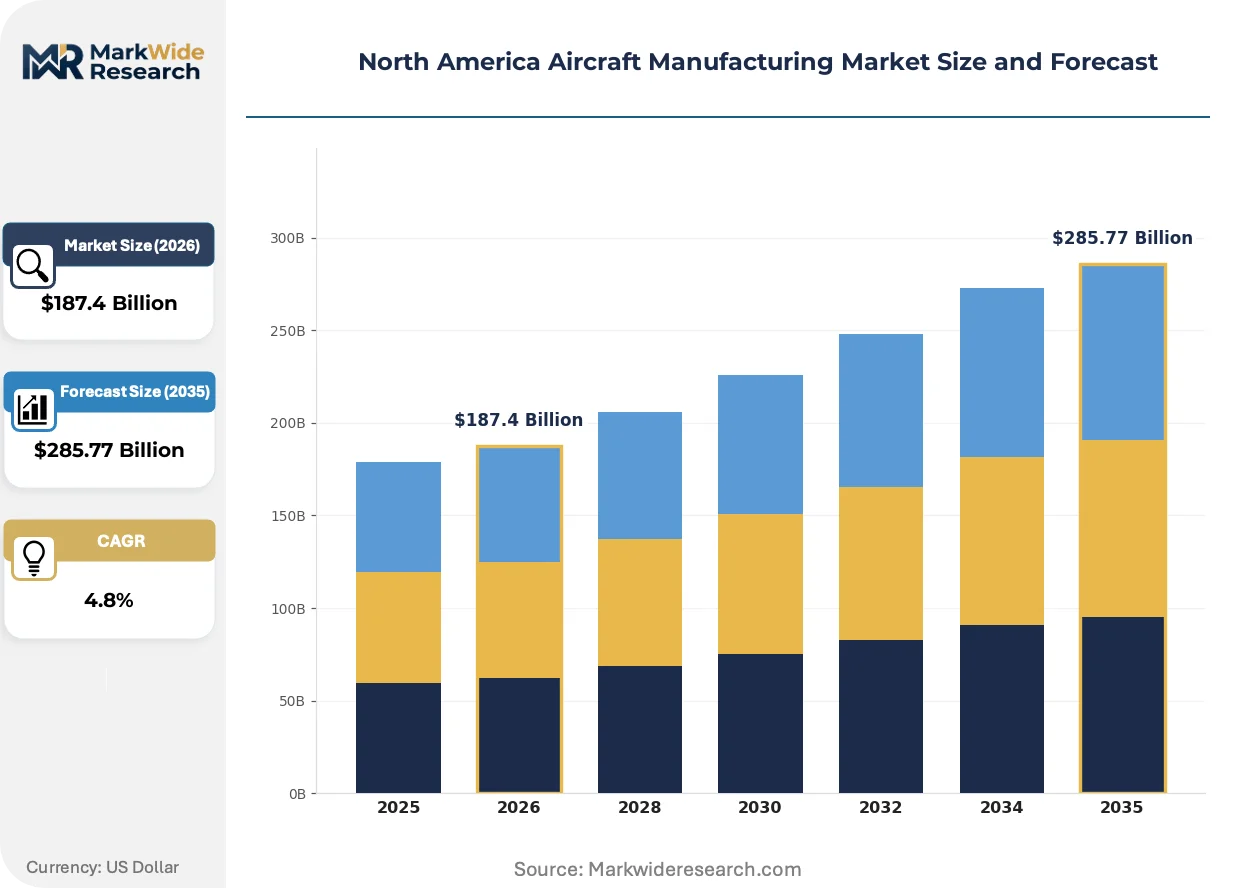
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Aircraft, Military Aircraft, Helicopters, Drones Technology: Aerospace Materials, Avionics, Propulsion Systems, Flight Control Systems End User: Airlines, Defense Departments, Charter Services, Maintenance Providers Service Type: Manufacturing, Maintenance, Overhaul, Support Services |
| Companies Covered | The Boeing Company, Airbus SE, Lockheed Martin Corporation, Textron Inc., Bombardier Inc., Northrop Grumman Corporation, General Dynamics Corporation, RTX Corporation, GE Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Aircraft Manufacturing Market Evolving Landscape
Digital thread architectures are collapsing the boundary between design engineering and shop-floor execution, compressing iteration cycles and enabling real-time quality feedback across dispersed supplier networks.
Digital twin technology is virtualizing physical aircraft systems into persistent software models that mirror structural stress, thermal load, and avionics performance throughout operational life. Airlines and defense operators are adopting these platforms for predictive maintenance scheduling and component life extension. This virtualization is compressing MRO turnaround times and shifting aftermarket value capture from parts replacement to data-driven intervention.
FAA reauthorization priorities are embedding cybersecurity requirements into airworthiness certification standards for connected aircraft systems. Manufacturers must now demonstrate resilience against intrusion vectors across flight control networks and passenger connectivity infrastructure. Commercial transport platforms with integrated internet-of-things architectures face the steepest compliance ramps and are accelerating investment in secure boot architectures.
After-sales service unbundling is fragmenting traditional OEM maintenance contracts into component-level subscriptions and performance-based availability guarantees. Regional airlines and cargo operators are adopting modular service tiers that separate line maintenance from heavy overhaul, driving third-party MRO network expansion. This pattern concentrates in the U.S. Southeast where hub-and-spoke logistics networks support rapid component exchange.
North America Aircraft Manufacturing Market Segmentation
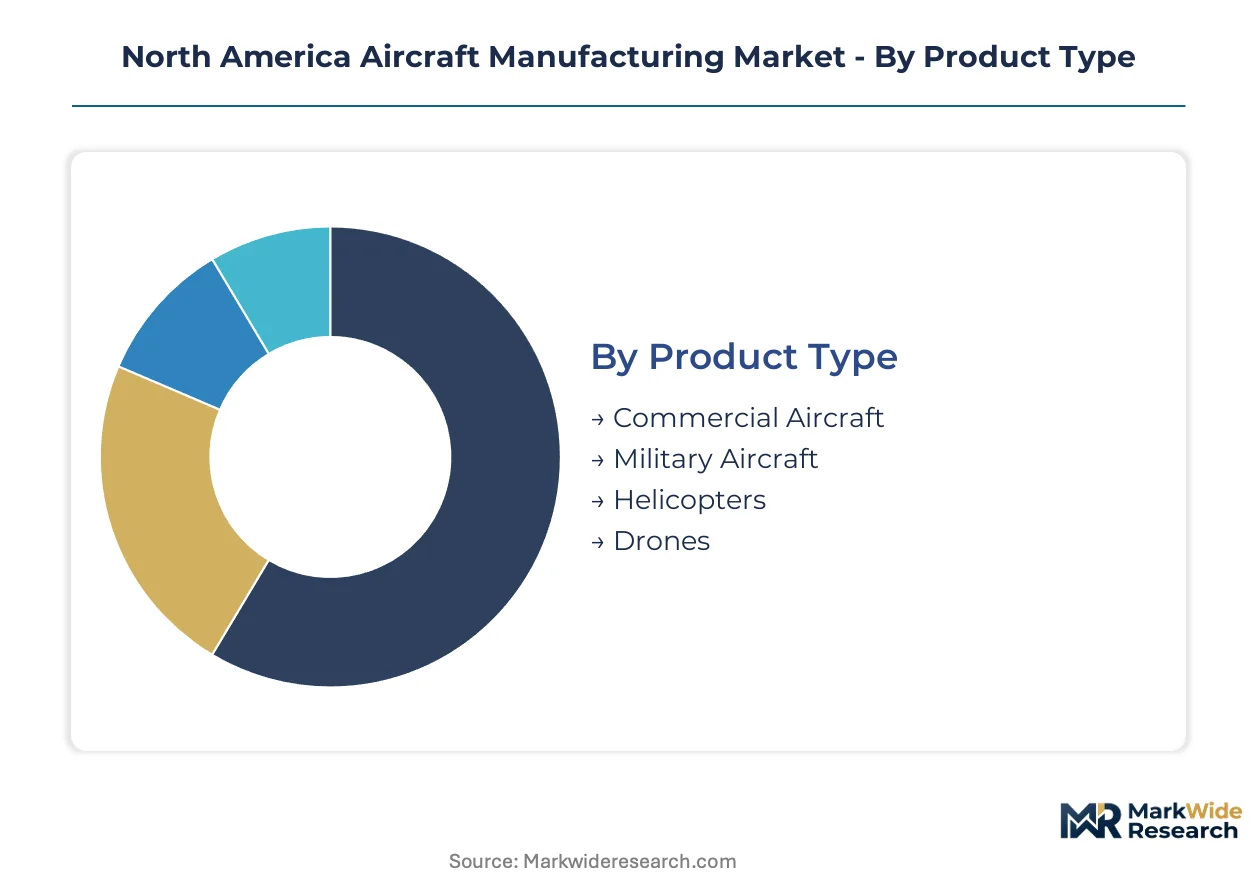
Segmentation in North American aircraft manufacturing reveals how capital allocation, regulatory exposure, and technology intensity diverge across product categories. Understanding these fault lines enables precise positioning against defense procurement cycles, FAA certification pathways, and aftermarket service demands.
Product Type:
Mature platforms dominate revenue concentration while emerging categories reshape competitive entry points.
- Commercial Aircraft:Wide-body and narrow-body platforms utilize aluminum-lithium alloys and carbon fiber reinforced polymers to achieve strength-to-weight ratios exceeding 200 kN·m/kg. U.S. Southeast assembly lines in South Carolina and Alabama anchor demand, though Boeing's Washington state infrastructure retains wide-body primacy.
- Military Aircraft:Stealth architectures and autonomous system integration drive R&D intensity through multi-year Department of Defense program commitments. Foreign military sales authorizations extend production backlogs while State Department licensing timelines compress working capital efficiency.
- Helicopters:Rotary-wing platforms serve offshore energy, emergency medical services, and military utility missions with specialized transmission and rotor system requirements.
- Drones:Electric vertical takeoff and landing systems and fixed-wing unmanned platforms represent the steepest expansion trajectory for defense reconnaissance and urban logistics applications.
Commercial aircraft handles the majority of throughput; drones is the fastest mover on share.
Technology:
Margin capture concentrates where patent protection intersects with certification barriers.
- Aerospace Materials:Composite formulation patents and titanium alloy processing expertise create defendable positions. EPA volatile organic compound regulations on coating operations constrain process flexibility and require capital-intensive abatement installations.
- Avionics:Software-defined architectures enable hardware-agnostic upgrades and recurring firmware subscription revenue across installed fleets. FAA cybersecurity requirements for connected aircraft systems now embed into Part 25 airworthiness standards.
- Propulsion Systems:Differentiated engine architectures span commercial turbofans and military afterburning designs, with RTX Corporation anchoring supply across both platforms.
- Flight Control Systems:Fly-by-wire and autonomous navigation modules integrate sensor fusion and redundancy management for transport category certification.
Aerospace materials commands the deepest margin pool; avionics is climbing the fastest on share.
End User:
Procurement authority and budget cyclicality determine contract structure and payment reliability.
- Airlines:Network carriers and low-cost operators drive narrow-body demand with fleet renewal cycles, while cargo operators prioritize wide-body conversion programs.
- Defense Departments:U.S. Department of Defense procurement frameworks generate predictable multi-year demand streams, with Canadian NORAD modernization adding Arctic surveillance platform requirements.
- Charter Services:Fractional ownership and on-demand operators sustain business jet and helicopter demand through utilization-based replacement economics.
- Maintenance Providers:Third-party MRO networks expand as after-sales service unbundling fragments traditional OEM contracts into component-level subscriptions.
Defense departments anchor volume commitment; maintenance providers is gaining share fastest.
Service Type:
Value chain position determines exposure to production cyclicality versus recurring revenue stability.
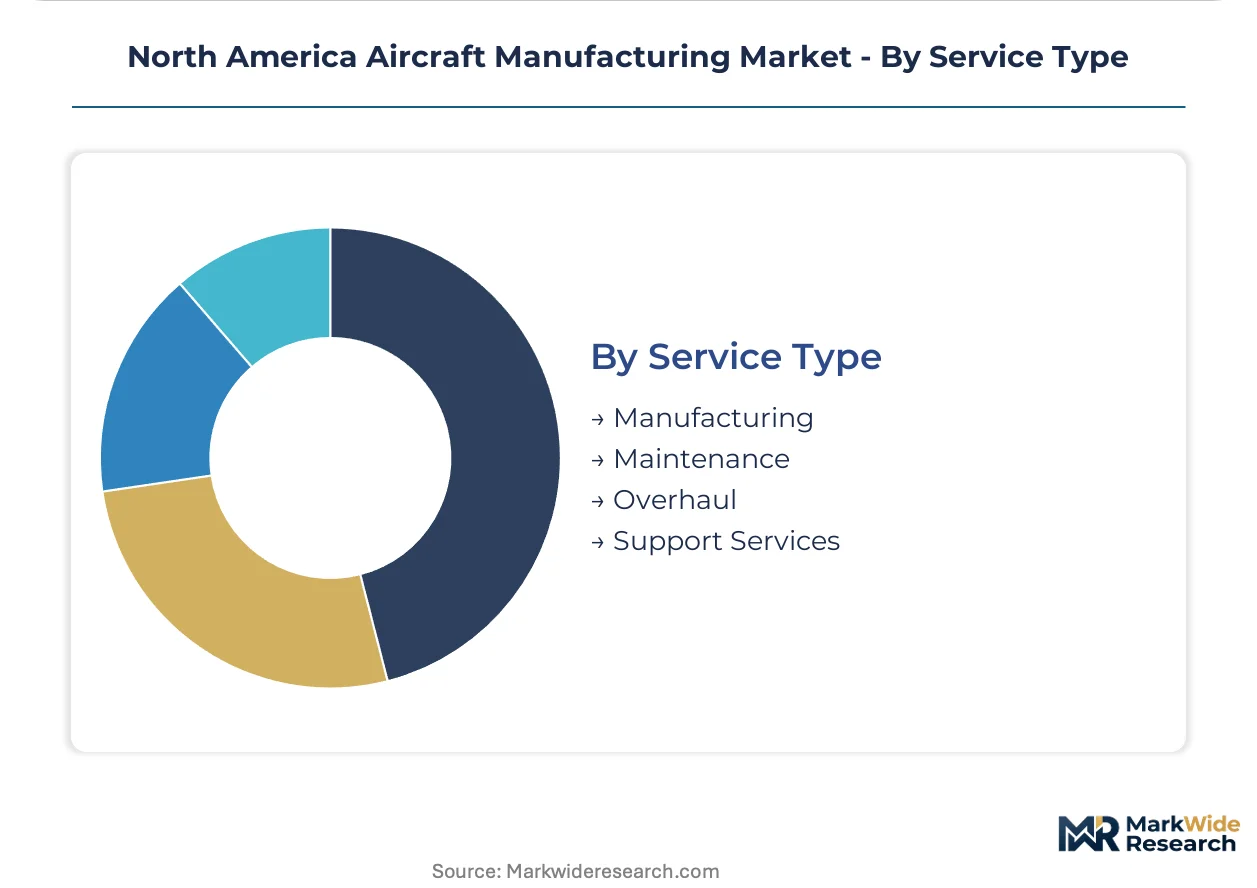
- Manufacturing:Final assembly and subsystem integration concentrate in the U.S. Southeast and Mexico's Querétaro-to-Baja California corridor, with digital thread architectures collapsing design-to-production iteration cycles.
- Maintenance:Line maintenance and heavy overhaul separate into modular service tiers, with regional airlines adopting performance-based availability guarantees.
- Overhaul:Component life extension through digital twin virtualization shifts value capture from parts replacement to data-driven intervention.
- Support Services:Technical documentation, training, and spare parts logistics sustain fleet operational readiness across multi-decade platform lifecycles.
Manufacturing handles the majority of throughput; support services is expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River inland waterway system and the Port of Long Beach container throughput anchor North American aerospace logistics, moving titanium feedstock and composite prepregs between extraction points and final assembly locations.
United States
Defense procurement commitments from the Pentagon sustain multi-year production backlogs for military aircraft platforms. FAA Part 25 airworthiness standards dictate structural integrity requirements that compress supplier certification timelines. Final assembly lines in South Carolina and Alabama anchor supplier ecosystems for commercial narrow-body production.
Canada
NORAD infrastructure investments and Arctic surveillance requirements generate incremental demand for patrol aircraft and northern logistics platforms. Canadian federal defense procurement frameworks coordinate with U.S. military specifications for interoperability. Quebec and Ontario host specialized aerostructures fabrication and flight test facilities serving transnational programs.
Mexico
Maquiladora operations along the Querétaro-to-Baja California corridor lower component costs and shorten logistics lead times for U.S. final assembly. Mexican federal economic development incentives target aerospace supplier clustering through specialized training institutes and duty-free import regimes. Tijuana and Mexicali concentrate precision machining operations for control surfaces and landing gear subassemblies.
North America Aircraft Manufacturing Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in propulsion, avionics, and aerostructures. The vendor base organizes into three tiers: full-airframe assemblers, major subsystem houses, and specialized materials processors. Dominant competitive moves include strategic partnerships for digital thread integration and selective backward integration into critical composite formulations.
Within the platform integrator tier, The Boeing Company and Lockheed Martin Corporation exemplify divergent strategic positioning—one anchored in commercial wide-body and narrow-body production, the other in stealth military architectures and autonomous systems. RTX Corporation occupies a position spanning both commercial and defense propulsion markets through differentiated engine architectures. These three entities represent the structural poles around which supplier ecosystems and certification pathways organize.
| Leading Market Players |
|---|
| The Boeing Company |
| Airbus SE |
| Lockheed Martin Corporation |
| Textron Inc. |
| Bombardier Inc. |
| Northrop Grumman Corporation |
| General Dynamics Corporation |
| RTX Corporation |
| GE Aerospace |
| Others |
Value Network & Pricing Analysis
Querétaro's precision machining cluster feeds carbon fiber reinforced polymer components into U.S. Southeast assembly lines, translating Mexican labor cost advantages into pricing leverage for tier-one suppliers bidding on Boeing and Lockheed Martin programs. This geographic arbitrage compresses margins for domestic fabricators while rewarding operators with cross-border logistics mastery and duty-free import credentials under maquiladora regimes.
Pricing Analysis
Volume-discount tiering structures separate defense procurement contracts from commercial airline fleet orders, with Pentagon multi-year program commitments commanding standard pricing and network carriers negotiating economy tiers based on delivery slot flexibility. Price differentiation rests on FAA Part 25 certification grade and after-sales service bundling, with cybersecurity-hardened avionics packages carrying premiums. Cost compression in narrow-body commercial tiers is intensifying because of Mexican supplier competition. Defense departments exhibit least price sensitivity; regional cargo operators show highest elasticity.
Supply Chain Analysis
Titanium sponge feedstock draws from U.S., Russian, and Japanese smelters, with aerospace-grade alloy processing concentrating in Ohio and Pennsylvania mills. Carbon fiber prepregs and aluminum-lithium alloys constitute critical input dependencies alongside rare earth elements for avionics magnetics. Single-source vulnerability for titanium alloys creates exposure to export restriction shocks. Distribution runs through Port of Long Beach container terminals and Mississippi River barge networks to final assembly corridors in South Carolina, Alabama, and Washington state.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America aircraft manufacturing is accelerating through FAA cybersecurity mandates for connected aircraft systems, creating compliance moats that favor incumbent platform integrators with certification infrastructure already embedded. This regulatory inflection compresses entry windows for unqualified competitors while expanding addressable demand for software-defined avionics retrofit programs.
For Market Incumbents: Harden supply chain resilience through backward integration into titanium alloy processing or captive carbon fiber formulation capacity, insulating against Russian feedstock disruption. Consolidate certification advantage by embedding FAA cybersecurity requirements into proprietary avionics architectures, creating switching costs for airlines and defense operators.
For New Entrants and Emerging Players: Establish a beachhead in urban air mobility electric vertical takeoff and landing platforms, where certification pathways remain unsettled and incumbent lock-in is weakest. Target Canadian Arctic surveillance and NORAD modernization programs as underpenetrated defense demand pools with interoperability requirements favoring new subsystem specialists. Lead with software-defined flight control modules that bypass hardware-legacy integration burdens.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors composite materials specialists with patent-protected formulation libraries and established EPA abatement compliance. Long-term viability across the projection horizon hinges on dual-use commercial-defense revenue diversification. Watch foreign military sales authorization velocity as the inflection signal for working capital efficiency and program backlog quality.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Thread Integration | Collapses design-to-production cycles for Boeing and Lockheed Martin supplier networks. |
| Composite Materials Patent Acquisition | Secures margin capture in carbon fiber reinforced polymer formulations above 200 kN·m/kg. |
| Mexico Corridor Capacity Expansion | Shortens logistics lead times from Querétaro to South Carolina final assembly. |
| Cybersecurity Certification Investment | Meets FAA Part 25 airworthiness standards for connected aircraft systems. |
| Urban Air Mobility Platform Development | Opens addressable demand in metropolitan logistics below traditional airline thresholds. |
Research Methodology
The analysis maps commercial aircraft, military platforms, helicopters, and drones, each validated through airframe program managers, avionics integration engineers, defense procurement officers, and FAA certification leads. Primary interview intelligence combined with secondary validation from SEC 10-K filings, Department of Defense budget justification documents, FAA type certificate databases, and aerospace trade flow data. Bottom-up platform production forecasts triangulate against top-down defense appropriation and airline capex cycle analysis.
Assumptions held fixed include FAA reauthorization timelines and EPA volatile organic compound enforcement intensity; variables stress-tested include titanium feedstock availability and foreign military sales authorization velocity. Segmentation modeling spans product type, technology category, end-user procurement authority, and service value chain position across the projection horizon. CAGRs derive from production rate ramp schedules, fleet renewal cycles, and emerging platform adoption curves with digital twin and software-defined avionics penetration as specific inputs.
Stress conditions across titanium supply disruption, FAA certification timeline extension, and defense budget sequestration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with revision triggers tied to named regulatory and procurement events. Cross-checking against Department of Defense Future Years Defense Program projections and airline fleet plan disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Europe Aviation Market
Aircraft
Military Rotorcraft Market
Aircraft
North America Helicopters Market
Aircraft
Freighter Aircraft Market
Aircraft
Airplane and Helicopter Hangar Doors Market
Aircraft
Global Business Jets Market
Aircraft
Aerospace Winglet System Market
Aircraft
Commercial Helicopter Market
Aircraft
Two-Seater Ultralight Helicopters Market
Aircraft
Commercial Aircraft Lavatory System Market
Aircraft
Small Evtol Aircraft Market
Aircraft
Active Air Deflector Market
Aircraft
Helicopter Lighting Market
Aircraft
Aircraft Wheels Market
Aircraft
Military Multirole Aircraft Market
Aircraft
America Freighter Aircraft Market