
 Tanker Aircraft Market | 2026-2036
Tanker Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Tanker Aircraft Market Analysis
Next-generation boom system specifications are redrawing competitive requirements for defense contractors. The Boeing Company leverages its KC-46 Pegasus production line to sustain Pentagon orders across multiple bases. Airbus SE anchors European supply through its A330 MRTT platform, which dominates NATO allied procurement. Lockheed Martin Corp. specializes in advanced mission systems integration for tanker derivatives of its strategic airlift portfolio.
Tanker aircraft are fixed-wing platforms designed to transfer aviation fuel to receiver aircraft during flight, typically operating at altitudes between 15,000 and 35,000 feet with transfer rates exceeding 1,200 gallons per minute through boom or hose-and-drogue architectures. Their primary purpose extends operational range of combat, surveillance, and transport aircraft without ground-based refueling infrastructure. Military tankers command the largest revenue share given sustained defense budgets and fleet recapitalization cycles, while hose-and-drogue technology leads in unit deployment due to compatibility with naval aviation and coalition partner aircraft. Wide body platforms concentrate margin pools through higher fuel offload capacity and multi-role conversion potential.
The FAA imposes airworthiness certification standards on commercial tanker modifications, while the EPA regulates emissions profiles for military and civil refueling platforms under evolving clean air mandates. The Department of Defense's MIL-STD-1553 data bus requirements shape avionics architecture for U.S. tanker programs, and NATO's air-to-air refueling interoperability standards dictate probe-and-drogue interface geometries for allied procurement. Stakeholders must monitor congressional appropriations committee markups for KC-Y next-generation tanker development and allied joint procurement frameworks to anticipate platform selection timelines.
Market Dynamics
Next-generation boom system specifications are redrawing competitive requirements for defense contractors, forcing manufacturers to requalify platforms under stricter FAA airworthiness directives while NATO allies accelerate fleet recapitalization timelines.
Growth Catalysts
- Extended-range fighter deployments:NATO member states are expanding aerial refueling fleets to support combat aircraft operating beyond traditional range envelopes, creating sustained platform demand across allied procurement frameworks.
- FAA certification modernization:Updated airworthiness directives for boom system certification are accelerating manufacturer compliance investments and filtering non-compliant suppliers from active procurement pools.
- Multi-role conversion architectures:Wide body platforms with higher fuel offload capacity and convertible mission systems are capturing margin pools through dual-use civil-military applications.
Market Restraints
- Specialized airframe supply concentration:Production of military-grade boom systems depends on a limited supplier base concentrated in North American and European defense corridors, creating single-source vulnerability.
- Prolonged certification timelines:FAA and EASA type certification processes for modified commercial tanker platforms extend development cycles by 18-36 months beyond original equipment schedules.
- Skilled technician scarcity:Licensed airframe and powerplant mechanics with boom system specialization command premium wages that compress contractor margins on sustainment contracts.
Strategic Opportunities
- Pacific theater basing gaps:The United States Air Force's dispersed operating concepts create demand for tanker-forward positioning in Guam, Australia, and Japan without permanent infrastructure investment.
- Hose-and-drogue naval compatibility:Carrier-based aviation requirements are expanding addressable market for probe-equipped refueling systems beyond traditional boom-dominated Air Force procurement.
- EU Green Deal compliance pathways:Sustainable aviation fuel integration mandates for military fleets are creating retrofit opportunities for engine and fuel system modifications on legacy tanker platforms.
Industry Challenges
- MIL-STD-1553 avionics integration:Legacy data bus architectures require specialized engineering talent that defense contractors compete for against commercial aerospace and autonomous systems sectors.
- Congressional appropriation volatility:KC-Y next-generation tanker development funding depends on annual defense authorization markups that create program timeline uncertainty for prime contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tanker Aircraft Market |
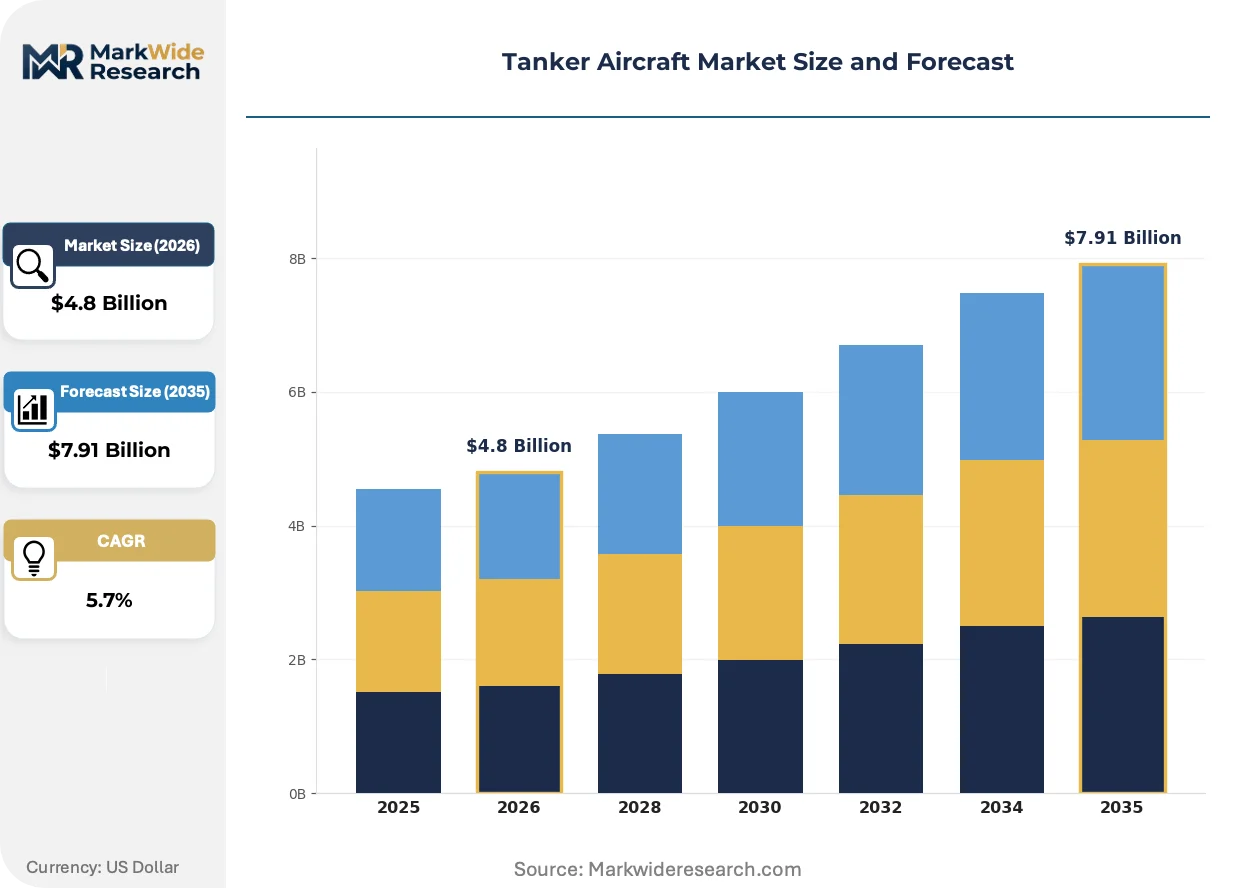
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wide Body, Narrow Body, Military Tankers, Commercial Tankers Technology: Fuselage Mount, Aerial Refueling Pods, Boom System, Hose-and-Drogue End User: Military Forces, Civil Aviation, Defense Contractors, Emergency Services Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity |
| Companies Covered | The Boeing Company, Airbus SE, Lockheed Martin Corp., Northrop Grumman Corp., United Aircraft Corp., BAE Systems Plc, Israel Aerospace Industries Ltd., RTX Corp., Embraer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tanker Aircraft Market Emerging Trajectories
Autonomous refueling technologies and digital mission systems are compressing crew requirements while coalition interoperability standards are mandating universal probe-and-drogue interface geometries across allied fleets.
Advanced boom control automation is fragmenting traditional operator-in-the-loop architectures. The Royal Australian Air Force and Japan Air Self-Defense Force are fielding reduced-crew tanker configurations for contested logistics scenarios. This capability compression is fragmenting labor cost structures and enabling smaller airframes to compete for missions previously requiring heavy tanker presence.
REACH chemical safety regulations and EU F-Gas restrictions are reshaping hydraulic fluid specifications for European-based tanker modifications. Industrial consequence includes reformulation of legacy fire-resistant fluids and retesting of seal compatibility across temperature envelopes. French and German defense procurement offices are now requiring full material disclosure documentation for all hydraulic subsystems in competitive tenders.
Outcome-based availability contracts are displacing traditional unit-acquisition-plus-spares procurement in allied defense ministries. The United Kingdom's Strategic Tanker Aircraft programme established payment-by-availability frameworks that defense contractors now replicate across NATO procurement. This model concentrates revenue risk with manufacturers while transferring operational readiness accountability from military operators to private sector platform managers.
Tanker Aircraft Market Segmentation
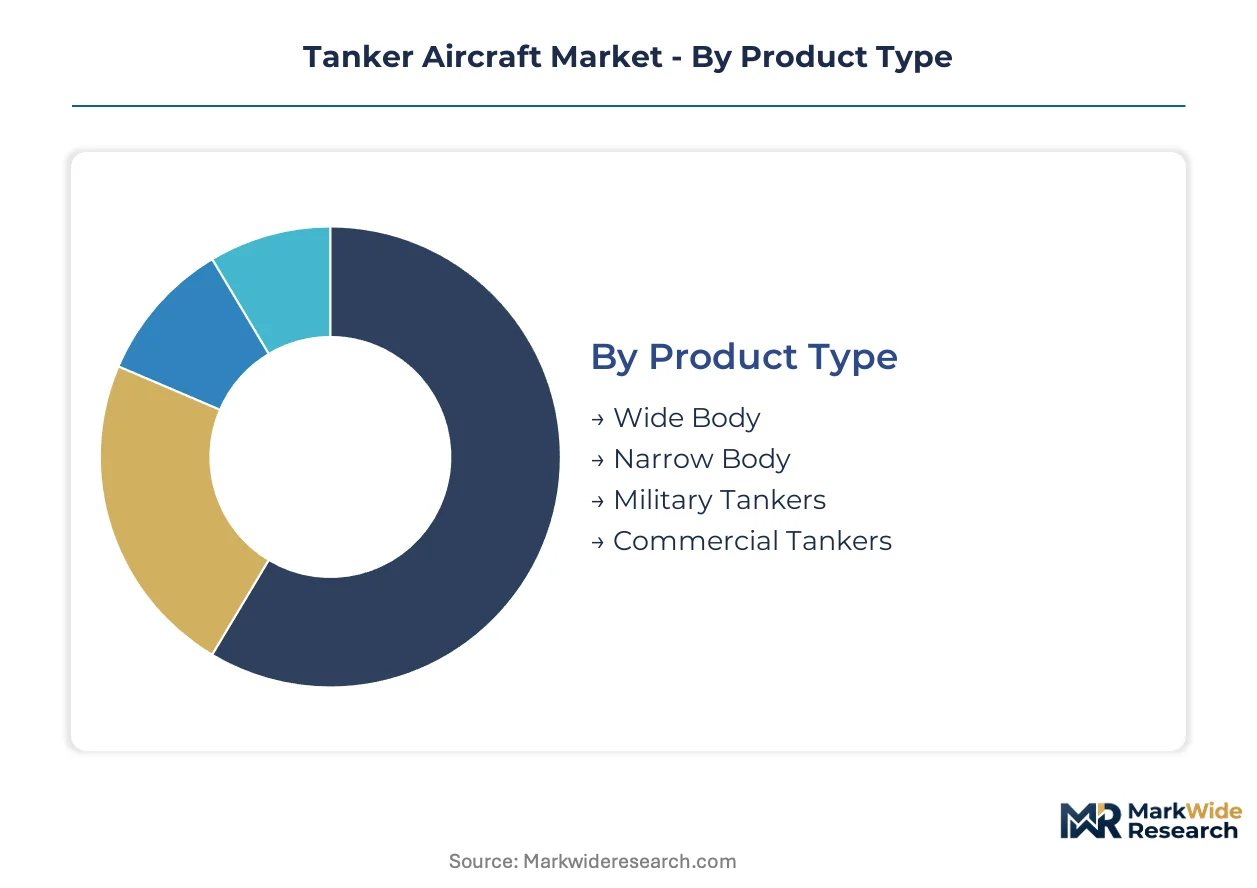
Tanker aircraft segmentation reveals divergent procurement patterns between sovereign defense programs and commercial aviation operators. Platform specifications vary sharply across military certification requirements, civilian airworthiness standards, and multi-role conversion architectures.
Product Type:
Domestic procurement in the United States concentrates on military-grade platforms, while European and Asia-Pacific demand flows through convertible wide-body derivatives with civil type certificates.
- Military Tankers:Purpose-built or heavily modified airframes meeting MIL-STD-1553 avionics requirements and STANAG 3447 refueling standards. Pentagon KC-46 and NATO A330 MRTT programs anchor demand in the United States, United Kingdom, and France, with fleet recapitalization cycles extending 25-30 years.
- Wide Body:Commercial derivatives such as Boeing 767 and Airbus A330 platforms converted for dual-use civil-military applications. Japan and Australia prioritize these for Pacific theater reach, leveraging existing maintenance infrastructure and pilot type ratings.
- Narrow Body:Single-aisle converted platforms serving regional tanker requirements and flight test programs. Israel and Singapore operate modified Boeing 707 and Gulfstream derivatives for specialized mission profiles.
- Commercial Tankers:Civil-registered tankers serving airline consortium fuel logistics and emergency response. Limited fleet presence concentrated in Scandinavian and North American cargo feeder operations.
Military Tankers command the established base. The steepest expansion runs through Wide Body platforms.
Technology:
Technology selection tracks customer fleet composition — boom systems dominate Air Force procurement while probe-equipped navies drive hose-and-drogue demand.
- Boom System:Rigid telescoping structures with fly-by-wire control enabling fuel transfer rates exceeding 1,200 gallons per minute. United States Air Force requirements and NATO interoperability mandates sustain demand, though FAA certification timelines for modified boom architectures extend 18-36 months.
- Hose-and-Drogue:Flexible refueling lines with stabilizing drogue baskets compatible with probe-equipped naval aircraft and coalition partners. Royal Australian Air Force and Japan Maritime Self-Defense Force procurement emphasizes probe compatibility for F-35B and F/A-18 operations.
- Aerial Refueling Pods:Wing-mounted units enabling simultaneous multi-point refueling on tanker derivatives. RAF Voyager and RAAF KC-30A configurations demonstrate pod-based flexibility for fighter-drone mixed formations.
- Fuselage Mount:Centerline installations on strategic airlift platforms such as C-130 and A400M derivatives. German and French air forces integrate these for tactical airlift-to-tanker role conversion.
Boom System technology anchors established defense procurement. The steepest technology expansion runs through Hose-and-Drogue configurations.
End User:
End-user concentration reflects sovereign budget cycles, with military forces commanding platform development and civil aviation accessing surplus or converted capacity.
- Military Forces:National air forces and naval aviation branches operating dedicated tanker fleets for power projection and homeland defense. United States, United Kingdom, and Saudi Arabia maintain the largest operational inventories, with procurement tied to defense authorization cycles.
- Civil Aviation:Airlines and cargo operators utilizing tanker-modified platforms for fuel logistics, flight testing, and specialized transport. Limited commercial segment concentrated in long-haul cargo corridors where fuel price arbitrage justifies dedicated tanker operations.
- Defense Contractors:Prime manufacturers and system integrators operating flight test tankers for new aircraft certification programs. Boeing, Airbus, and Lockheed Martin maintain captive tanker capacity for developmental flight testing.
- Emergency Services:National firefighting agencies and disaster response organizations adapting tanker platforms for water and retardant delivery. California and Australian state fire services operate modified military surplus tankers for aerial firefighting.
Military Forces command the established base. The steepest expansion runs through Emergency Services adaptation.
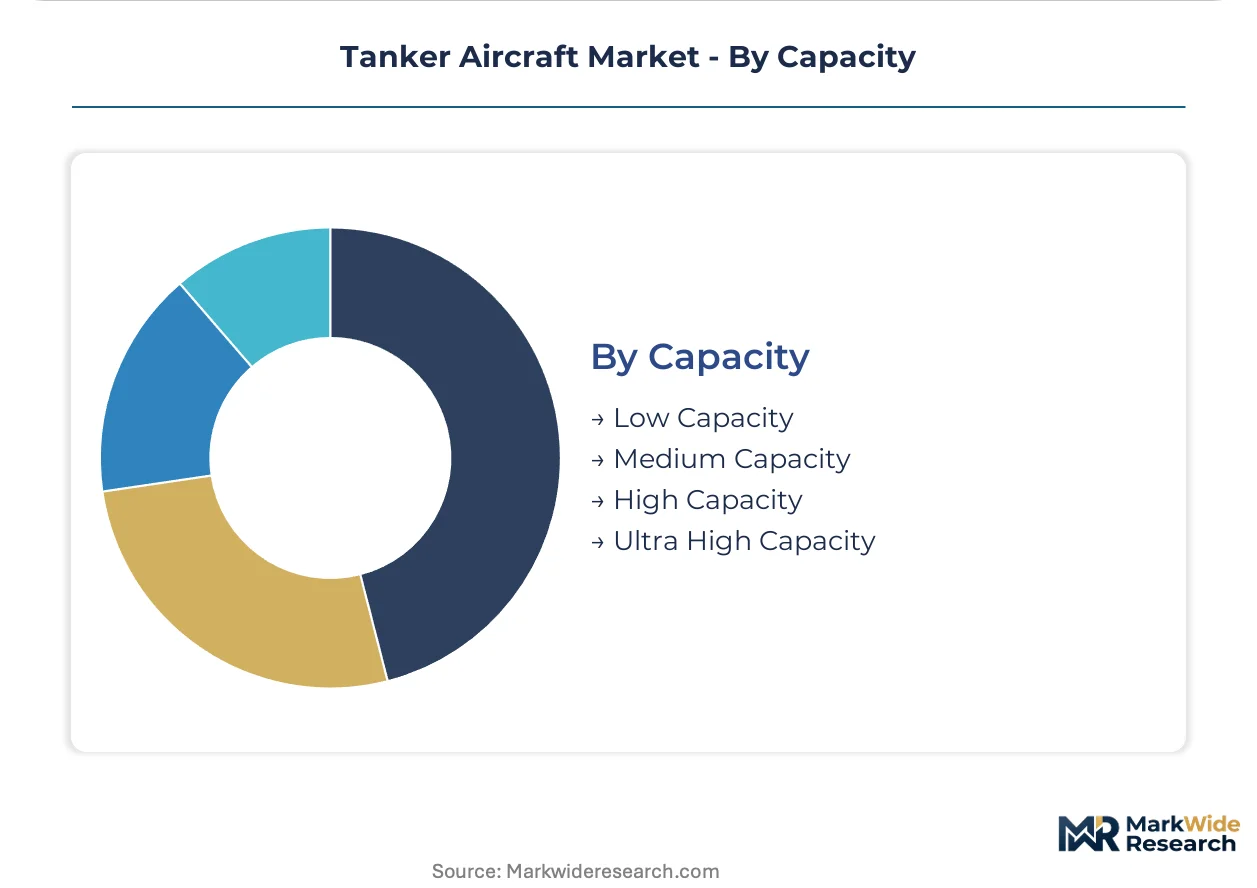
Capacity:
Capacity tiering aligns with mission radius requirements — high-capacity platforms serve intercontinental fighter escort while low-capacity units support tactical airlift conversion.
- High Capacity:Platforms exceeding 200,000 pounds fuel offload supporting strategic bomber and heavy transport escort. United States KC-10 and emerging KC-Y programs define this tier, with unit economics favoring dedicated heavy tankers over multi-point refueling networks.
- Ultra High Capacity:Specialized derivatives approaching 300,000 pounds offload for Pacific theater distributed operations. Proposed KC-Z concepts and commercial freighter conversions target this segment for China containment scenarios.
- Medium Capacity:100,000-200,000 pound offload platforms balancing range and basing flexibility. European A330 MRTT and Japanese KC-767 procurement clusters here, optimizing for regional power projection without heavy tanker infrastructure.
- Low Capacity:Under 100,000 pound offload for tactical airlift derivatives and expeditionary basing. Special Operations Command requirements and partner nation capacity building drive demand in this tier.
High Capacity platforms command the established base. The steepest expansion runs through Ultra High Capacity configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tanker aircraft trade flows reflect asymmetric defense industrial bases. The United States exports complete platforms and boom systems while importing specialized subcomponents from allied defense corridors. European and Asia-Pacific nations balance indigenous modification capacity with prime contractor technology licensing.
United States
Pentagon KC-46 and KC-Y programs drive sustained domestic production demand. The FAA's updated airworthiness directives for boom certification extend compliance timelines for modified commercial derivatives. Wichita, Kansas and Seattle, Washington anchor final assembly and flight test operations for strategic tanker platforms.
United Kingdom
The Strategic Tanker Aircraft programme established payment-by-availability contracting frameworks now replicated across NATO procurement. REACH chemical safety regulations reshape hydraulic fluid specifications for European-based modifications. Brize Norton in Oxfordshire concentrates RAF Voyager operations and maintenance infrastructure.
France
A330 MRTT procurement anchors French air force modernization alongside nuclear deterrence mission requirements. The EU Green Deal drives sustainable aviation fuel integration mandates for military fleet retrofits. Toulouse-Blagnac hosts Airbus final assembly lines serving domestic and export customers.
Japan
Pacific theater dispersed operating concepts create demand for tanker-forward positioning in Guam and Australia without permanent infrastructure. Japan Air Self-Defense Force procurement emphasizes probe-compatible systems for F-35B operations. Nagoya aerospace clusters support KC-767 modification and sustainment programs.
Australia
RAAF KC-30A operations demonstrate pod-based flexibility for fighter-drone mixed formations. Reduced-crew tanker configurations fielded for contested logistics scenarios compress labor cost structures. Amberley in Queensland concentrates regional tanker basing and coalition interoperability training.
Tanker Aircraft Market Vendor Landscape
Listed leaders compete with private specialists across platform development and mission systems integration. The supplier base concentrates around three prime contractors with captive airframe production and two tier-one system integrators with specialized boom architectures. Strategic archetypes include full-service platform developers, mission systems specialists, and regional modification houses. Competitive moves center on strategic partnerships for Pacific theater positioning and technology licensing for probe-drogue interoperability.
Within the full-service platform tier, The Boeing Company and Airbus SE occupy positions as anchor suppliers to Pentagon and NATO procurement frameworks respectively. Lockheed Martin Corp. sits within the mission systems specialization vector, anchoring avionics and data bus integration for tanker derivatives. These three entities exemplify the consolidated structure where airframe production and military certification capabilities create barriers to new entrant participation.
| Leading Market Players |
|---|
| The Boeing Company |
| Airbus SE |
| Lockheed Martin Corp. |
| Northrop Grumman Corp. |
| United Aircraft Corp. |
| BAE Systems Plc |
| Israel Aerospace Industries Ltd. |
| RTX Corp. |
| Embraer |
| Others |
Supply Flow & Price Mechanics
Sustainable aviation fuel mandates replacing conventional jet fuel specifications simultaneously redistribute modification center geography toward EU-certified facilities and compress margins on legacy platform sustainment contracts. Military procurement officers now face fuel system retrofit requirements that favor airframers with established European modification lines while penalizing North American suppliers lacking REACH-compliant fluid handling infrastructure.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for military tanker programs, with price differentiation tracking certification grade and volume scale across Pentagon and NATO procurement frameworks. Pricing pressure stems from congressional appropriation markups that compress development phase margins for KC-Y competitors. Defense contractors show least price sensitivity due to mission-critical requirements, while emergency services conversions exhibit highest sensitivity to airframe acquisition costs.
Supply Chain Analysis
Extended certification timelines stretching eighteen to thirty-six months beyond original equipment schedules strain inventory buffers for boom system manufacturers. Geographic supply concentration centers on the United States, France, and Germany for military-grade refueling architectures. Raw material dependencies include aerospace-grade aluminum alloys, specialized hydraulic fluids, and fly-by-wire control electronics. Single-source vulnerability pervades telescoping boom fabrication, where qualified suppliers remain concentrated in Wichita and Seattle aerospace clusters. Distribution runs through prime contractor direct-to-military channels with limited aftermarket parts intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous refueling drones present a credible substitute threat that incumbent platform developers must neutralize through crew-compression technology integration and contested logistics capability demonstration.
For Market Incumbents: Fortify boom system certification moats by accelerating FAA compliance investments ahead of updated airworthiness directive implementation. Deepen in-house production of fly-by-wire control electronics to offset skilled technician scarcity compressing sustainment margins. Lockheed Martin and Northrop Grumman autonomous systems divisions represent emerging competitive pressure requiring defensive patent positioning around reduced-crew architectures. For New Entrants and Emerging Players: Differentiate on hose-and-drogue pod modularity for naval aviation applications underserved by boom-dominated Air Force procurement. Target Pacific theater partner nations—Australia, Japan, Singapore—seeking probe-compatible systems for F-35B and F/A-18 operations without heavy tanker infrastructure. Pursue technology licensing from Airbus A330 MRTT program to bypass eighteen-month airworthiness certification barriers. For Investors and Strategic Acquirers: KC-Y next-generation tanker development funding authorization reshapes the acquisition landscape by concentrating program risk with prime contractors possessing established Pentagon relationships. Five-to-ten year viability favors platform developers with captive wide-body airframe production and multi-role conversion architectures. Monitor congressional defense appropriations committee markups as inflection indicator for program timeline certainty and contractor selection outcomes.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Boom Control Development | Boeing and Airbus compression of operator-in-the-loop requirements fragments labor cost structures for contested logistics. |
| Sustainable Aviation Fuel Integration | EU Green Deal mandates create retrofit revenue streams for engine and fuel system modifications on legacy KC-135 platforms. |
| Pacific Theater Basing Partnerships | Guam and Australia forward positioning agreements enable tanker presence without permanent infrastructure investment. |
| Payment-by-Availability Contracting | UK Strategic Tanker Aircraft programme frameworks transfer operational readiness accountability from RAF to private sector managers. |
| Probe-Drogue Interoperability Licensing | NATO STANAG 3447 standard adoption opens Japanese and Australian naval aviation procurement to qualified subsystem suppliers. |
Methodological Framework
Cross-validation between defense procurement officer interviews and FAA airworthiness directive filings anchors the qualitative findings on certification timeline compression. Primary fieldwork encompassed program managers at Boeing Defense, Space & Security, Airbus Military, and Lockheed Martin Aeronautics; procurement leads at United States Air Force Air Mobility Command and RAF Brize Norton; plus sustainment directors at Japanese Air Self-Defense Force Nagoya maintenance clusters. Secondary validation drew from Department of Defense budget justification materials, NATO air-to-air refueling interoperability standards documentation, EASA type certificate amendment records, and congressional defense appropriations committee markups. Bottom-up platform delivery forecasts triangulated against top-down defense budget allocation analysis.
Sensitivity analysis around KC-Y program authorization timing and sustainable aviation fuel mandate implementation pace frames the projection uncertainty envelope across the analysis window. Segmentation modeling tracked platform type, refueling technology architecture, end-user military versus civil classification, and fuel offload capacity tier. CAGRs derived from historical defense procurement cycle patterns and fleet recapitalization timeline analysis. Industry-specific forecast inputs included MIL-STD-1553 avionics integration lead times and REACH-compliant hydraulic fluid reformulation certification durations.
Material uncertainties — congressional funding volatility, autonomous refueling technology disruption timelines, and Pacific theater basing policy shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions on defense authorization continuity and allied joint procurement framework stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Water Bomber Market
Aircraft
Aircraft Container & Pallet Loader Market
Aircraft
Airplane Ailerons Market
Aircraft
Aircraft Cargo Container Market
Aircraft
Aircraft Wheels Brakes Market
Aircraft
Asia-Pacific Aircraft Windshield Wiper and Washer System Market
Aircraft
Japan Aerospace and Defense Market
Aircraft
Light Sport Aircraft (LSA) Market
Aircraft
Global Business Jets Market
Aircraft
Freighter Aircraft Market
Aircraft
Commercial Helicopter Market
Aircraft
US Aviation Market
Aircraft
Asia-Pacific Aircraft Manufacturing Market
Aircraft
North America Military Helicopters Market
Aircraft
Firefighting Aircraft Market
Aircraft
Aircraft Galley Systems Market