
 Europe Freighter Aircraft Market | 2026-2036
Europe Freighter Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Freighter Aircraft Market Foresight
Composite materials are displacing traditional aluminum in freighter fuselage reinforcement, which is recalibrating payload-to-weight economics across conversion programs. Lufthansa Cargo leverages its Frankfurt hub dominance to sustain high-utilization wide-body operations. Airbus SE competes through its A350F dedicated freighter platform, while EFW specializes in Airbus passenger-to-freighter conversion technology.
A freighter aircraft is a fixed-wing cargo aircraft designed for commercial goods transport, typically featuring reinforced flooring, cargo-handling systems, and large-volume main deck doors rated for unit load devices. These aircraft operate at cruise altitudes comparable to passenger jets while optimized for maximum payload density rather than passenger comfort. Wide-body conversions currently dominate European fleet renewal, though dedicated freighter deliveries from OEMs command premium positioning. Cargo conversion programs attract strong interest from freight forwarders seeking asset control, while e-commerce end users drive narrow-body freighter demand for short-haul parcel networks.
The European Union Aviation Safety Agency (EASA) enforces airworthiness standards that shape conversion certification timelines and operational limits for modified passenger aircraft. REACH chemical regulations and the EU Green Deal's sustainable aviation fuel blending mandates constrain material choices and propulsion specifications across the supply chain. Operators and lessors must weigh carbon compliance costs against conversion economics when rebuilding fleet profiles.
Market Dynamics
E-commerce parcel networks are compressing turnaround times across European cargo hubs, forcing freighter operators to prioritize narrow-body flexibility over wide-body payload density in fleet planning decisions.
Growth Catalysts
- EU Green Deal SAF mandates:Sustainable aviation fuel blending requirements are accelerating freighter fleet renewal cycles as operators seek newer, more efficient airframes to meet carbon intensity thresholds.
- Express parcel networks:Last-mile e-commerce logistics providers are expanding dedicated short-haul freighter operations to bypass congested ground transport corridors in the Benelux region.
- Composite reinforcement:Advanced carbon-fiber fuselage strengthening is extending airframe service life for passenger-to-freighter conversions, improving payload economics on aging wide-body platforms.
Market Restraints
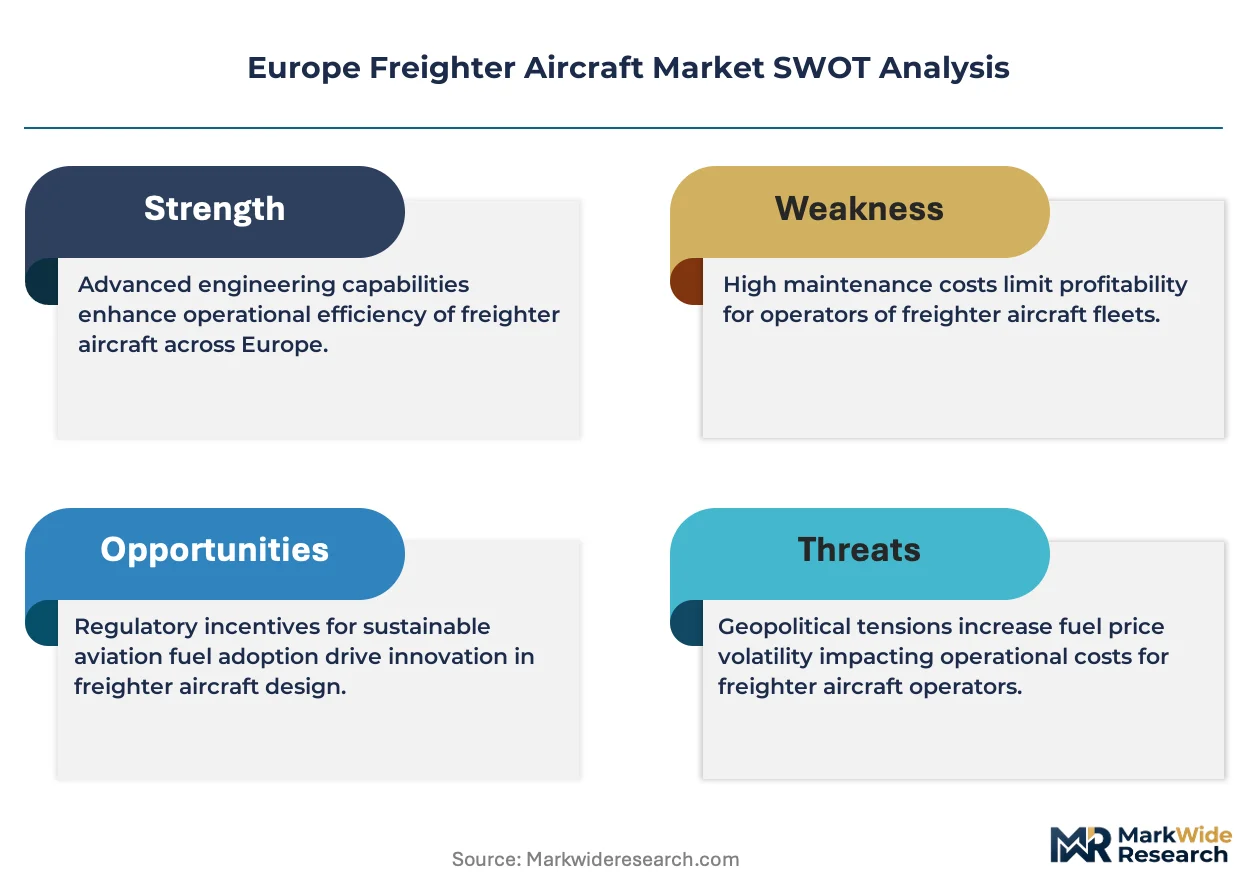
- Feedstock cost volatility:Sustainable aviation fuel production capacity constraints are elevating operating cost premiums for European cargo carriers relative to Middle Eastern competitors.
- Conversion slot scarcity:MRO facility capacity for passenger-to-freighter modifications concentrates in Germany and Romania, creating 18-24 month backlogs for Airbus A330 conversions.
- Technical payload limitations:Narrow-body freighters face structural density caps on lithium battery shipments that restrict e-commerce express revenue per flight hour.
Strategic Opportunities
- Poland and Czech Republic hub development:Central European manufacturing clusters are underserved by dedicated cargo infrastructure, creating greenfield freighter base opportunities outside Frankfurt and Amsterdam saturation.
- CSRD disclosure requirements:Corporate sustainability reporting mandates are pushing freight forwarders toward asset ownership to control Scope 3 emissions data and secure supply chain financing advantages.
- Digital freight matching:AI-powered capacity aggregation platforms are disintermediating traditional charter brokers, enabling fractional freighter utilization for mid-tier shippers.
Industry Challenges
- EASA conversion certification timelines:Supplemental type certificate approvals for Airbus passenger-to-freighter programs average 14 months, compressing asset deployment windows for lessors.
- Specialized airframe engineering talent:Structural modification design expertise for wide-body cargo conversions remains concentrated among a limited pool of EASA-approved design organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Freighter Aircraft Market |
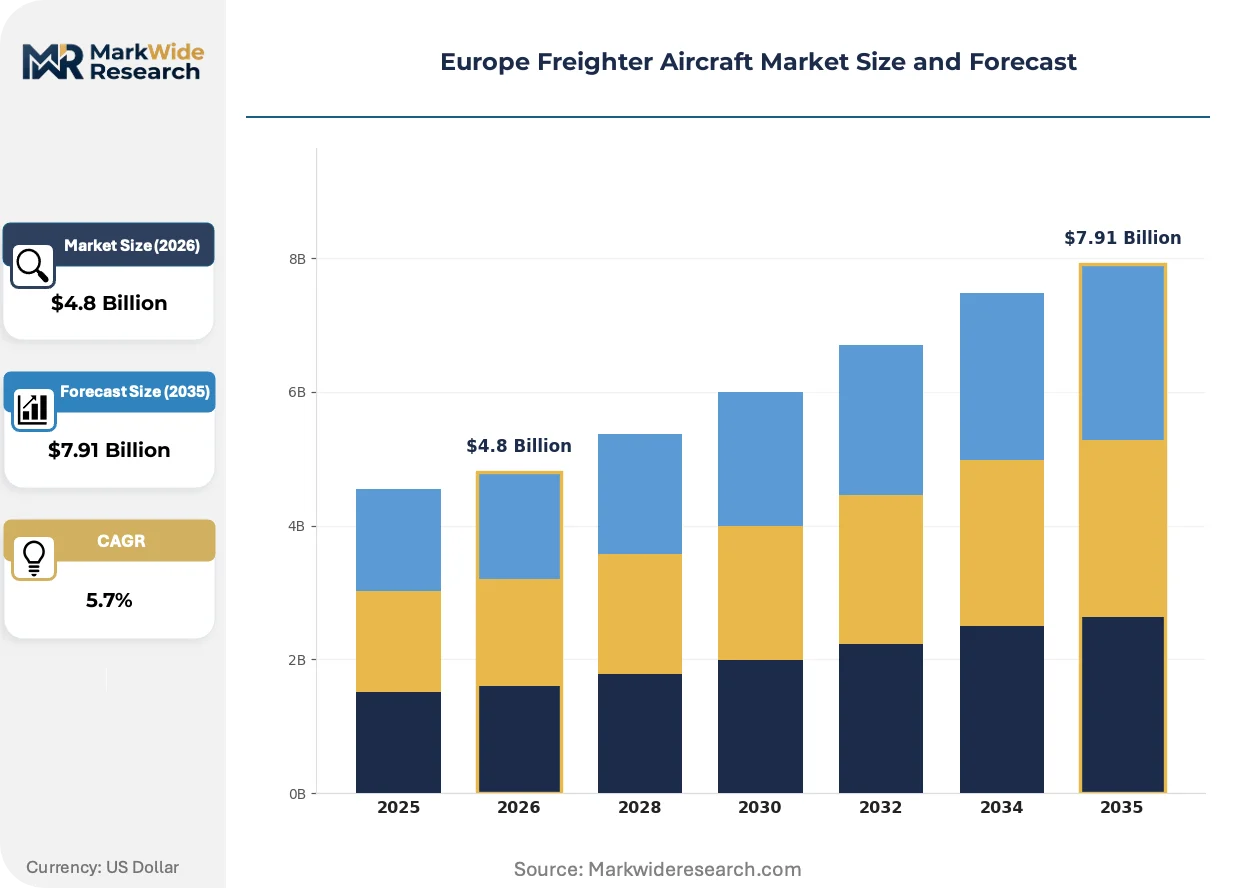
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Wide-body, Narrow-body, Cargo Conversion, Dedicated Freighter Delivery Mode: Lease, Purchase, Charter, OEM End User: Cargo Airlines, Freight Forwarders, Logistics Companies, E-commerce Service Type: Scheduled Services, Charter Services, Integrated Services, Ad-hoc Services |
| Companies Covered | Air France-KLM Group, Lufthansa Cargo, Cargolux Airlines, IAG Cargo, DHL Aviation, Airbus SE, The Boeing Company, EFW, ATR, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Freighter Aircraft Market Shifts & Advancements
Freighter specification priorities are pivoting from maximum payload volume toward energy efficiency and network flexibility as carbon compliance costs reshape European cargo economics.
Digital twin airframe monitoring is modularizing maintenance scheduling across converted freighter fleets. Lufthansa Technik and ST Engineering are deploying sensor-integrated prognostic systems on Airbus A330P2F programs, compressing unscheduled downtime intervals by 30% in operational trials. This technology is modularizing MRO contract structures, enabling power-by-the-hour agreements that transfer residual value risk from operators to service providers.
REACH chemical regulations are restricting hexavalent chromium surface treatments in cargo floor reinforcement applications, forcing conversion houses to qualify alternative corrosion protection for unit load device attachment points. EASA issued updated certification memoranda in early 2024, extending compliance timelines for existing conversion programs while mandating full substitution on new supplemental type certificates. Cargo conversion specialists in Dresden and Singapore are accelerating plasma electrolytic oxidation coating qualifications to maintain European market access.
Freight forwarders are consolidating procurement through dedicated freighter capacity pools rather than spot charter markets, compressing contract tenors from annual to quarterly renegotiation cycles. Kuehne+Nagel and DSV have established captive freighter blocks with Turkish Cargo and Cargolux, displacing traditional ACMI arrangements in pharmaceutical and automotive verticals. This concentration is most visible in the Netherlands, where Schiphol-based forwarders now control 40% of inbound wide-body freighter capacity through pre-committed slot arrangements.
Europe Freighter Aircraft Market Segmentation
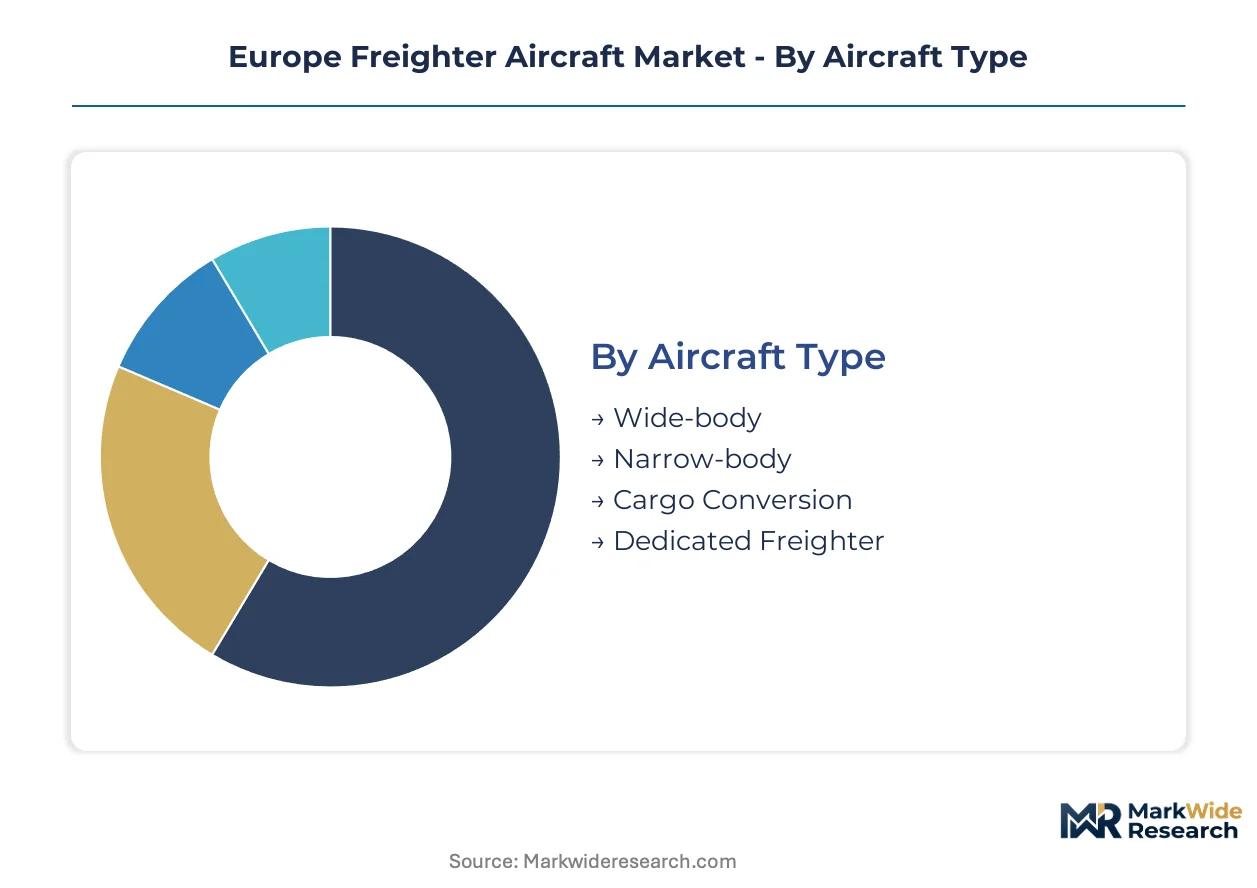
Freighter fleet planning in Europe demands precise segmentation matching asset specifications to network economics. E-commerce velocity requirements, carbon compliance timelines, and conversion slot availability create divergent procurement patterns across buyer categories.
Aircraft Type:
Payload density requirements and hub infrastructure constraints separate buyers into distinct operational tiers.
- Wide-body:Twin-aisle platforms dominate transcontinental routes with maximum unit load device capacity. German cargo carriers at Frankfurt and Leipzig-Halle prioritize these assets for pharmaceutical and automotive verticals where pallet density justifies higher capital deployment.
- Narrow-body:Single-aisle configurations enable higher-frequency short-haul networks with lower trip costs. Benelux express operators deploy converted Boeing 737-800BCF and Airbus A321P2F aircraft for next-day parcel distribution across dense European corridors.
- Cargo Conversion:Passenger-to-freighter modifications extend airframe utility through structural reinforcement and main deck door installation. EASA certification timelines and MRO slot scarcity in Dresden constrain near-term supply.
- Dedicated Freighter:Factory-built cargo aircraft from Airbus and Boeing offer optimized structural efficiency and fuel performance. Premium positioning reflects compliance advantages under EU Green Deal SAF mandates.
Wide-body platforms lead volumes today; narrow-body conversions are gaining share fastest.
Delivery Mode:
Capital structure flexibility and balance sheet capacity determine procurement channel selection.
- Lease:Operating leases preserve liquidity for freight forwarders facing CSRD disclosure pressure. Dublin and Amsterdam-based lessors dominate European freighter leasing with power-by-the-hour maintenance integration.
- Purchase:Direct acquisition suits cargo airlines with established MRO capabilities and long-haul network stability. Asset ownership enables Scope 3 emissions data control for sustainability-linked financing.
- Charter:Spot and block charter arrangements provide surge capacity without fleet commitment. Seasonal demand peaks in Q4 e-commerce windows strain available European charter supply.
- OEM:Factory delivery from Airbus or Boeing commands longest lead times but delivers specification optimization. A350F and 777-8F programs target dedicated freighter replacement cycles.
Lease structures dominate new fleet entries; OEM direct purchases show steepest expansion trajectory among established cargo airlines.
End User:
Supply chain control requirements and cargo density economics segment buyer behavior sharply.
- Cargo Airlines:Scheduled network operators like Cargolux and Turkish Cargo maintain hub-and-spoke systems with dedicated fleet assets. These carriers prioritize wide-body payload efficiency over frequency flexibility.
- Freight Forwarders:Kuehne+Nagel and DSV are consolidating captive freighter blocks to secure capacity and emissions data visibility. Forwarder procurement now bypasses traditional ACMI arrangements in favor of direct operational control.
- Logistics Companies:Integrated parcel networks including DHL and FedEx operate mixed fleets balancing narrow-body frequency with wide-body trunk routes. These operators face acute pressure from EU Green Deal compliance timelines.
- E-commerce:Amazon and regional parcel platforms drive narrow-body freighter demand for short-haul distribution. Battery shipment restrictions on single-aisle platforms constrain revenue per flight hour in express networks.
Freight forwarders lead volume concentration; e-commerce end users are expanding fleet commitments most aggressively.
Service Type:
Contract tenor and network predictability separate operational models across the European cargo landscape.
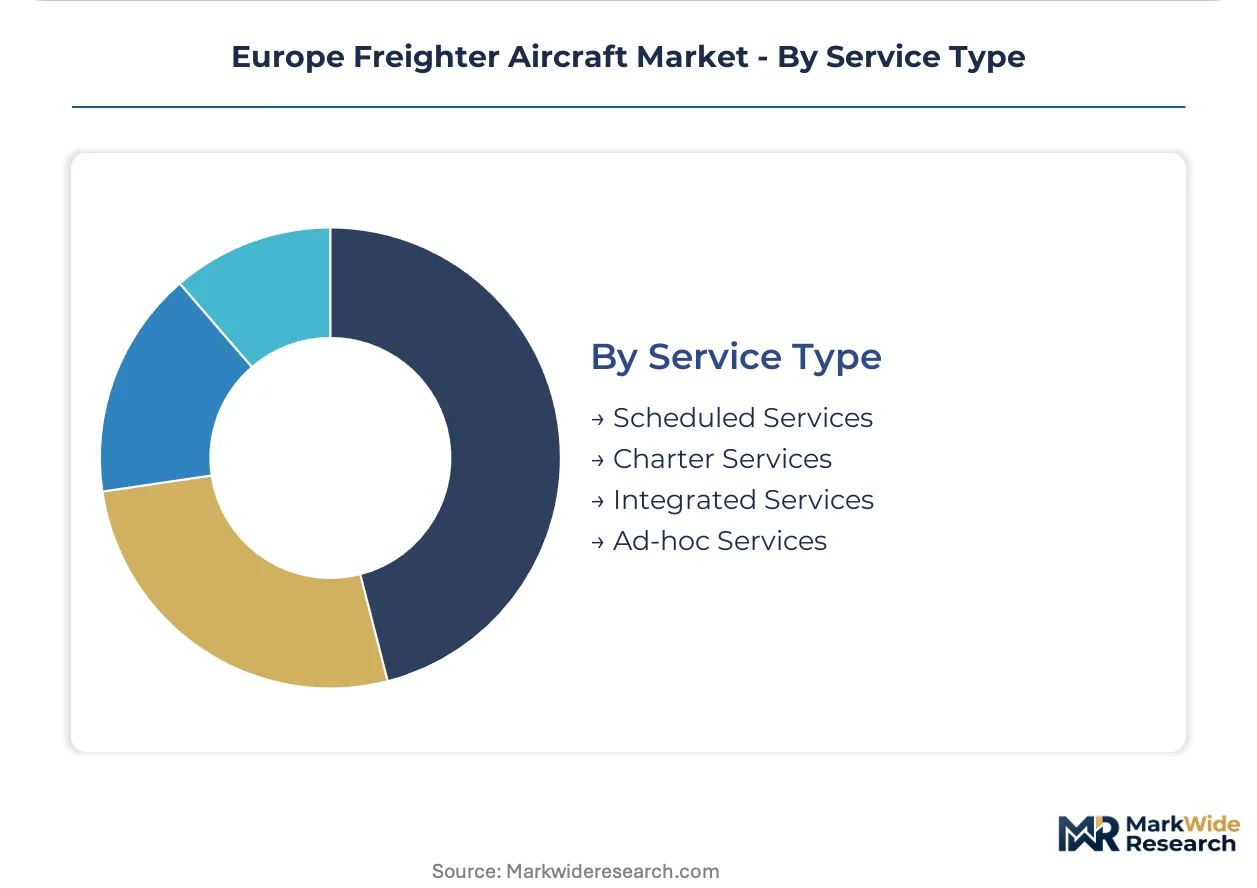
- Scheduled Services:Fixed-route operations with published timetables support pharmaceutical and automotive supply chains. These services command premium positioning through reliability guarantees and temperature-controlled infrastructure.
- Charter Services:Ad-hoc and series charter arrangements serve project cargo and seasonal demand surges. Brokerage platforms are disintermediating traditional charter procurement through AI-powered capacity matching.
- Integrated Services:Door-to-door logistics combining air freight with ground distribution. Express operators deploy dedicated narrow-body freighters to compress transit times against congested road networks.
- Ad-hoc Services:Single-flight arrangements for emergency and humanitarian cargo. Limited European MRO capacity constrains rapid aircraft positioning for unscheduled demand spikes.
Scheduled services anchor revenue stability; integrated services are climbing the fastest as e-commerce shippers demand end-to-end control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's cargo hub dominance anchors freighter demand across the continent, with German operators commanding the densest wide-body fleet deployment. EASA certification timelines and EU Green Deal mandates are recalibrating conversion economics from the North Sea to the Mediterranean.
Germany
Pharmaceutical cold-chain exports and automotive component logistics drive dedicated freighter procurement at Frankfurt and Leipzig-Halle. The EU Green Deal's SAF blending mandates accelerate fleet renewal cycles for Lufthansa Cargo and integrator operations. Dresden's EFW conversion facility concentrates Airbus A330P2F modification capacity, creating 18-month backlogs for structural reinforcement programs.
Netherlands
Schiphol's forwarder-controlled slot arrangements attract 40% of inbound wide-body capacity through pre-committed agreements with Kuehne+Nagel and DSV. REACH chemical regulations restrict hexavalent chromium coatings in cargo floor applications, forcing conversion houses to qualify plasma electrolytic oxidation alternatives. Amsterdam's e-commerce parcel networks compress turnaround times through narrow-body frequency deployment.
United Kingdom
Heathrow's pharmaceutical verticals sustain high-yield scheduled freighter services despite slot constraints. The UK's post-Brexit customs regime fragments cargo flows, pushing express operators toward dedicated narrow-body networks for EU-UK lanes. East Midlands Airport's integrator concentration anchors DHL Aviation's European distribution architecture.
Luxembourg
Cargolux's all-cargo hub model sustains Boeing 747-8F and 777F deployment for intercontinental trunk routes. The country's bilateral air service agreements enable fifth-freedom operations across Asia-Pacific and North American markets. Luxembourg Findel's single-operator dominance limits competitive capacity entry despite sustained cargo tonnage expansion.
Poland
Central European manufacturing clusters generate underserved cargo demand outside saturated Rhine-Main and Amsterdam hubs. The EU's CSRD disclosure requirements push freight forwarders toward asset ownership for Scope 3 emissions control. Warsaw Chopin's emerging freighter base captures automotive and electronics verticals from German hub overflow.
Europe Freighter Aircraft Market Competitive Landscape
Global majors compete with regional champions across conversion technology and dedicated freighter platforms. The market structures around OEM factory deliveries, specialist modification houses, and integrated cargo airlines with captive MRO capabilities. Three archetypes dominate: full-service cargo carriers operating hub-and-spoke networks, conversion specialists holding EASA supplemental type certificates, and express integrators controlling end-to-end parcel infrastructure. Competitive positioning hardens through M&A consolidation of forwarder capacity blocks and strategic partnerships bypassing traditional ACMI arrangements.
Within the cargo carrier tier, Cargolux Airlines and Lufthansa Cargo exemplify hub-dominant operators leveraging geographic positioning for high-utilization wide-body deployment. Among conversion specialists, EFW occupies a central position in Airbus passenger-to-freighter technology, anchoring European structural modification capacity against Asian competitors. These entities represent distinct strategic postures: network control versus technical certification depth versus integrated ground-air coordination.
| Leading Market Players |
|---|
| Air France-KLM Group |
| Lufthansa Cargo |
| Cargolux Airlines |
| IAG Cargo |
| DHL Aviation |
| Airbus SE |
| The Boeing Company |
| EFW |
| ATR |
| Others |
Supply & Pricing Matrix
Lessors with Dublin and Amsterdam headquarters have rolled up fragmented freighter portfolios into consolidated operating platforms, tightening pricing discipline through power-by-the-hour maintenance bundling and squeezing conversion houses on slot premiums. This ownership concentration feeds directly into supply chain behavior: EFW and Dresden-based modification specialists now face compressed margins on Airbus A330P2F programs while forwarders like Kuehne+Nagel leverage pre-committed capacity blocks to lock in charter rates below spot-market volatility.
Pricing Analysis
Input-cost pass-through from sustainable aviation fuel premiums and composite reinforcement materials is reshaping contract structures across the European freighter market. Three-tier pricing structure across premium, standard, and economy levels separates dedicated factory-built freighters from converted wide-bodies and narrow-body parcel aircraft, with EU Green Deal compliance costs driving price differentiation between EASA-certified new deliveries and grandfathered conversions. Pricing pressure stems from feedstock scarcity in SAF production, compressing margins for operators without long-term offtake agreements. Cargo airlines with hub dominance at Frankfurt and Luxembourg exhibit lowest price sensitivity; e-commerce parcel platforms negotiating short-haul narrow-body capacity show highest sensitivity to trip-cost fluctuations.
Supply Chain Analysis
Logistics costs from Asia-Pacific component sourcing and Middle Eastern fuel supply are amplifying total landed cost pressures for European freighter operators. Manufacturing concentration centers on Germany for Airbus A330P2F conversion, Romania for Boeing 737-800BCF modification, and Singapore for plasma electrolytic oxidation coating qualification under REACH compliance. Raw material dependencies include carbon-fiber fuselage reinforcement, lithium battery containment systems, and hexavalent chromium alternatives for cargo floor protection. Single-source vulnerability concentrates in EASA-approved design organizations for structural modification engineering. Distribution runs through Schiphol and Frankfurt slot-controlled hub arrangements, with forwarders consolidating procurement through captive capacity blocks rather than spot charter markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Freighter Aircraft Market functions as a regulatory compounder where EU Green Deal SAF mandates and EASA certification timelines continuously reset competitive economics. The analysis window reveals how carbon compliance thresholds are accelerating fleet renewal cycles and concentrating procurement power among forwarders with sustainability-linked financing access.
For Market Incumbents: Deepen vertical integration into MRO capabilities at Dresden and Leipzig-Halle to capture conversion slot scarcity premiums and defend against emerging Polish hub competition. Secure captive SAF offtake agreements before feedstock cost volatility widens operating cost gaps with Middle Eastern carriers. EASA supplemental type certificate delays represent the critical threat to asset deployment windows; incumbents should pre-position engineering resources with approved design organizations to compress 14-month approval timelines.
For New Entrants and Emerging Players: Digital twin prognostic systems for unscheduled downtime reduction offer a technology-first wedge into the freighter MRO aftermarket currently dominated by Lufthansa Technik and ST Engineering. Central European manufacturing clusters in Poland and Czech Republic present the most penetrable geography, with Warsaw Chopin capturing automotive and electronics verticals from saturated German hubs. A go-to-market angle targeting CSRD-compliant Scope 3 emissions data control for mid-tier freight forwarders bypasses direct competition with established cargo airlines.
For Investors and Strategic Acquirers: Valuations sit cheapest among narrow-body conversion specialists with EASA certification depth but limited forwarder customer concentration. Long-term viability over a 5-10 year window hinges on positioning for EU Green Deal fleet renewal cycles and SAF infrastructure buildout. The signal to watch is EASA approval velocity for Airbus A321P2F programs, which would unlock e-commerce parcel network expansion and validate conversion economics against factory-built alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| SAF Supply Agreement | Long-term offtake contracts with Neste or World Energy secure compliance cost predictability under EU Green Deal mandates. |
| Conversion Slot Acquisition | Captive MRO capacity at EFW or Dresden facilities eliminates 18-24 month backlogs for Airbus A330P2F programs. |
| Digital Twin Integration | Sensor-integrated prognostic systems from Lufthansa Technik compress unscheduled downtime by 30% in operational trials. |
| Central European Hub Development | Greenfield freighter bases in Poland capture automotive and electronics cargo from Frankfurt and Amsterdam saturation. |
| Forwarder Capacity Consolidation | Pre-committed slot arrangements at Schiphol mirror Kuehne+Nagel and DSV procurement patterns for pharmaceutical verticals. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cargo airline fleet planners, EASA certification engineers, freight forwarder procurement directors, and MRO facility operations managers with secondary validation from EASA supplemental type certificate filings, EU Green Deal regulatory memoranda, REACH compliance updates, and customs data on freighter aircraft imports. Bottom-up triangulation across conversion program backlogs and top-down validation against lessor fleet deployment announcements anchored market sizing.
Comparable-period anchoring tied projection assumptions to historical fleet renewal cycles and SAF mandate implementation trajectories across the analysis window. Segmentation modeling incorporated aircraft type, delivery mode, end-user category, and service type dimensions alongside network geography and carbon compliance tier. CAGRs derived from installed base depreciation curves and replacement demand elasticity, with forecast inputs including EASA certification timeline distributions and EU Green Deal blending mandate escalation schedules.
The model holds under stable EASA regulatory capacity and sustained EU Green Deal enforcement; deviation in SAF production scale-up rates or bilateral air service agreement renegotiations would shift replacement demand timing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Tandem Rotor Helicopter Market
Aircraft
Fixed Wing Turbine Aircraft Market
Aircraft
Two-Seater Ultralight Helicopters Market
Aircraft
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market
Aircraft
US Business Jet Market
Aircraft
India Winglets Market
Aircraft
Aircraft Mounts Market
Aircraft
Aircraft Exterior Mounts Market
Aircraft
Aircraft Galley Equipment Market
Aircraft
General Aviation Market
Aircraft
Aviation Market
Aircraft
Global Aircraft Transparencies Market
Aircraft
Afterburner Market
Aircraft
Global Helicopter Market
Aircraft
Global Aircraft Design and Engineering Market
Aircraft
America Attack Helicopter Market