
 Egg Replacement Ingredients Market | 2026-2036
Egg Replacement Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Egg Replacement Ingredients Market Intelligence
Formulation service revenue is tilting from commodity ingredient supply toward customized blend development and technical support. Cargill Incorporated leverages its global oilseed processing infrastructure to secure consistent plant-protein feedstock for egg replacer formulations. Kerry Group plc sustains competitive position through integrated taste and nutrition laboratories that co-develop texture systems with bakery clients. Ingredion Incorporated anchors its presence in the segment through specialty starch and clean-label texturizer portfolios designed for vegan baking applications.
Egg replacement ingredients comprise functional blends of plant-derived proteins, modified starches, lecithin-based emulsifiers, and hydrocolloid gums formulated to replicate the binding, leavening, and moisture-retention properties of hen eggs in food processing. These systems typically achieve foaming stability through controlled protein denaturation temperatures between 60°C and 85°C, enabling their deployment in industrial-scale cake and meringue production. Plant-based proteins command the largest share of product-type value pools due to their versatility across bakery and meat-analogue applications. Emulsifiers represent the fastest-expanding functional class as manufacturers seek to reduce dependency on egg-derived lecithin amid supply volatility. Baked goods applications absorb the greatest volume of egg replacement ingredients, though meat-analogue formulations are gaining share as extrusion technology advances.
The FDA governs egg replacement ingredient labeling under the Food Allergen Labeling and Consumer Protection Act, while USDA oversight applies to products entering federally inspected meat and poultry processing facilities. EFSA evaluates novel protein sources under the EU's novel food regulation, creating compliance pathways that determine market access timelines for emerging plant-protein isolates. Stakeholders must monitor evolving definitions of "egg-free" and "vegan" claims across jurisdictions, as classification inconsistencies between FDA guidance and EU member-state interpretations create formulation and packaging complexity that directly impacts regional go-to-market strategy.
Market Dynamics
Commercial bakeries are accelerating recipe reformulation as the EU Green Deal and F-Gas Regulation tighten ingredient provenance requirements, compressing formulation timelines and shifting procurement criteria toward verified low-carbon supply chains.
Growth Catalysts
- Clean-label mandates:The EU Green Deal incentivizes bakery manufacturers to eliminate synthetic additives, creating pull for plant-protein egg replacers with transparent supply chains.
- Extrusion technology maturation:Advanced twin-screw extrusion systems now enable meat-analogue producers to achieve fibrous textures previously requiring egg binders.
- German innovation clustering:Food technology hubs around Cologne and Hamburg concentrate R&D talent and pilot facilities, accelerating commercialization timelines for novel formulations.
Market Restraints
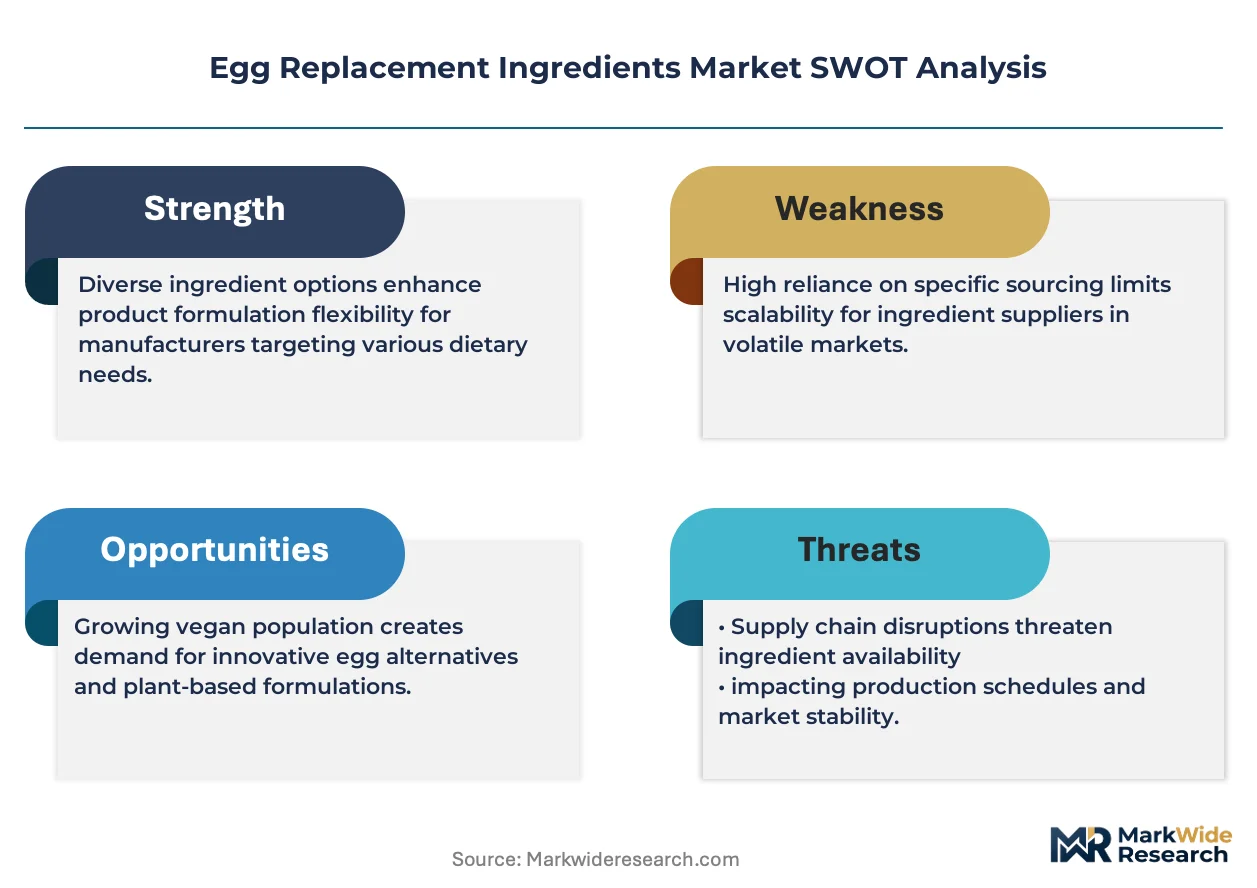
- Protein isolate cost volatility:Pea and fava bean protein prices fluctuate with agricultural yields and energy-intensive fractionation processes.
- Emulsifier supply concentration:Sunflower lecithin production clusters in Black Sea region processors, exposing formulators to geopolitical disruption risk.
- Foaming ceiling:Plant proteins denature across narrower temperature bands than ovalbumin, limiting application in high-ratio sponge cakes without compensatory hydrocolloid additions.
Strategic Opportunities
- US regulatory arbitrage:FDA allergen labeling rules lag EFSA novel food pathways, allowing faster market entry for fermented protein isolates.
- Precision fermentation convergence:Microbial protein production paired with enzymatic modification promises functional parity with egg whites at scale.
- Direct-to-manufacturer platforms:Digital ingredient marketplaces bypass traditional distributor markups for mid-sized bakery chains.
Industry Challenges
- Formulation chemist scarcity:Bakery science programs produce fewer specialists versed in both traditional rheology and plant-protein functionality.
- Clean-label certification timelines:EFSA novel food dossiers require 18-24 month safety evaluations, freezing product launch schedules.
- Legacy equipment retrofit costs:Existing sponge cake lines require viscosity and temperature recalibration to handle starch-thickened batters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egg Replacement Ingredients Market |
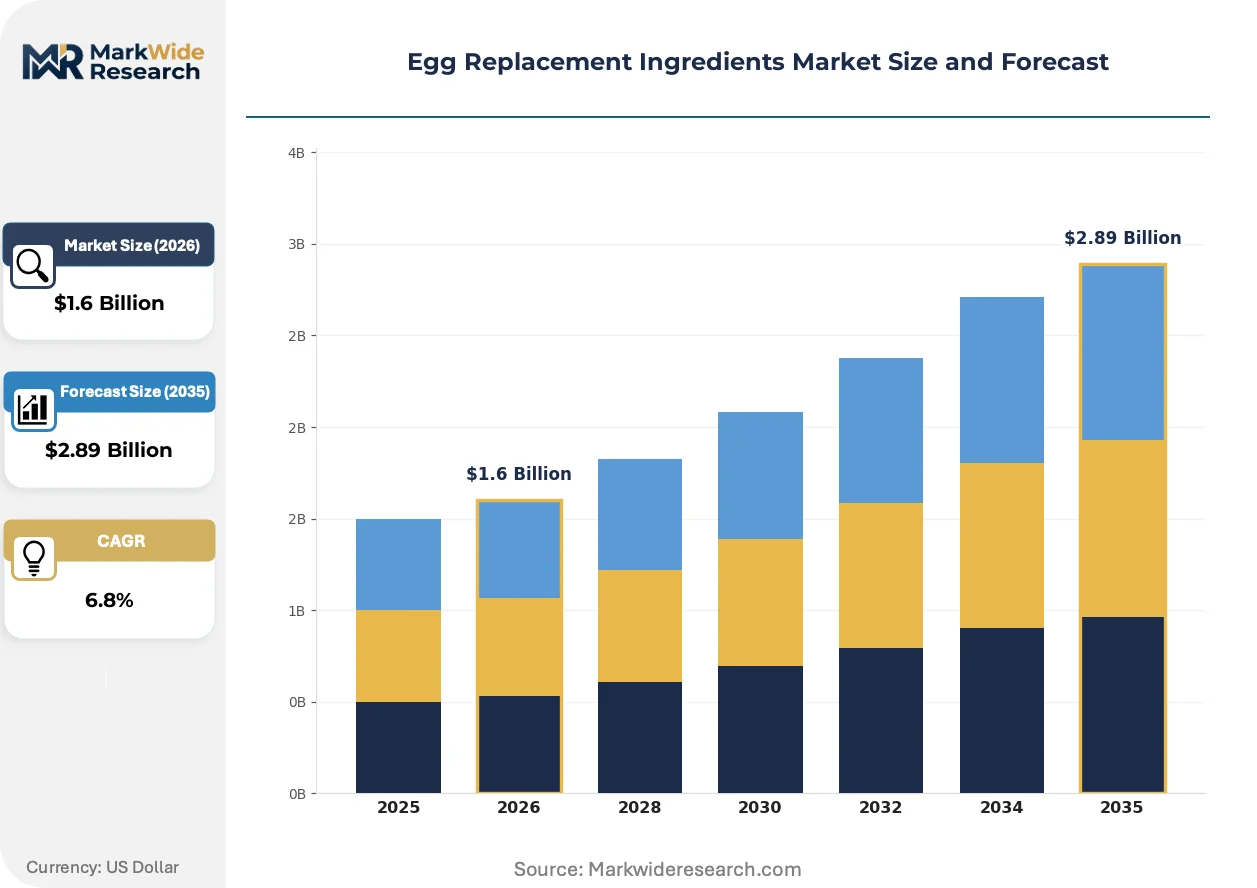
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $2.89 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-Based Proteins, Starches, Emulsifiers, Fibers, Gums, Flours Application: Baked Goods, Confectionery, Meat Analogues, Sauces & Dressings, Dairy Alternatives, Snacks End User: Commercial Bakeries, Food Processing Plants, Foodservice Providers, Household Consumers Distribution Channel: Supermarkets & Hypermarkets, Specialty Stores, Online Retailers, Wholesale Suppliers, Direct Sales |
| Companies Covered | Cargill Incorporated, Ingredion Incorporated, Kerry Group plc, Archer-Daniels-Midland Company, Tate & Lyle PLC, Corbion NV, Puratos Corporation, Glanbia PLC, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egg Replacement Ingredients Market Strategic Shifts & Innovations
Digital integration across formulation labs and production floors is compressing development cycles, while regulatory divergence between jurisdictions creates competitive openings for agile suppliers.
Enzymatic protein modification is digitizing the precision with which formulators control denaturation kinetics. Industrial bakeries in Germany and the Netherlands deploy real-time viscosity sensors to adjust shear rates during sponge cake mixing. This technology is digitizing quality consistency previously dependent on egg batch variability, reducing waste and enabling continuous rather than batch processing.
The F-Gas Regulation's phasedown of hydrofluorocarbon propellants intersects with bakery sector decarbonization targets. EFSA's expanded novel food evaluations now cover precision-fermented proteins, creating compliance bottlenecks that favor established ingredient houses with regulatory affairs infrastructure. European meat-analogue producers are responding by front-loading dossier submissions two years ahead of planned launches.
Ingredient procurement is consolidating through co-manufacturer networks rather than traditional distributor relationships. Mid-sized bakery chains now contract directly with blend houses for customized texture systems, disintermediating regional ingredient brokers. This pattern is most visible in the US Pacific Northwest and German Rhine-Ruhr corridor, where vertically integrated bakery groups negotiate multi-year supply agreements locking in plant-protein volumes.
Egg Replacement Ingredients Market Segmentation
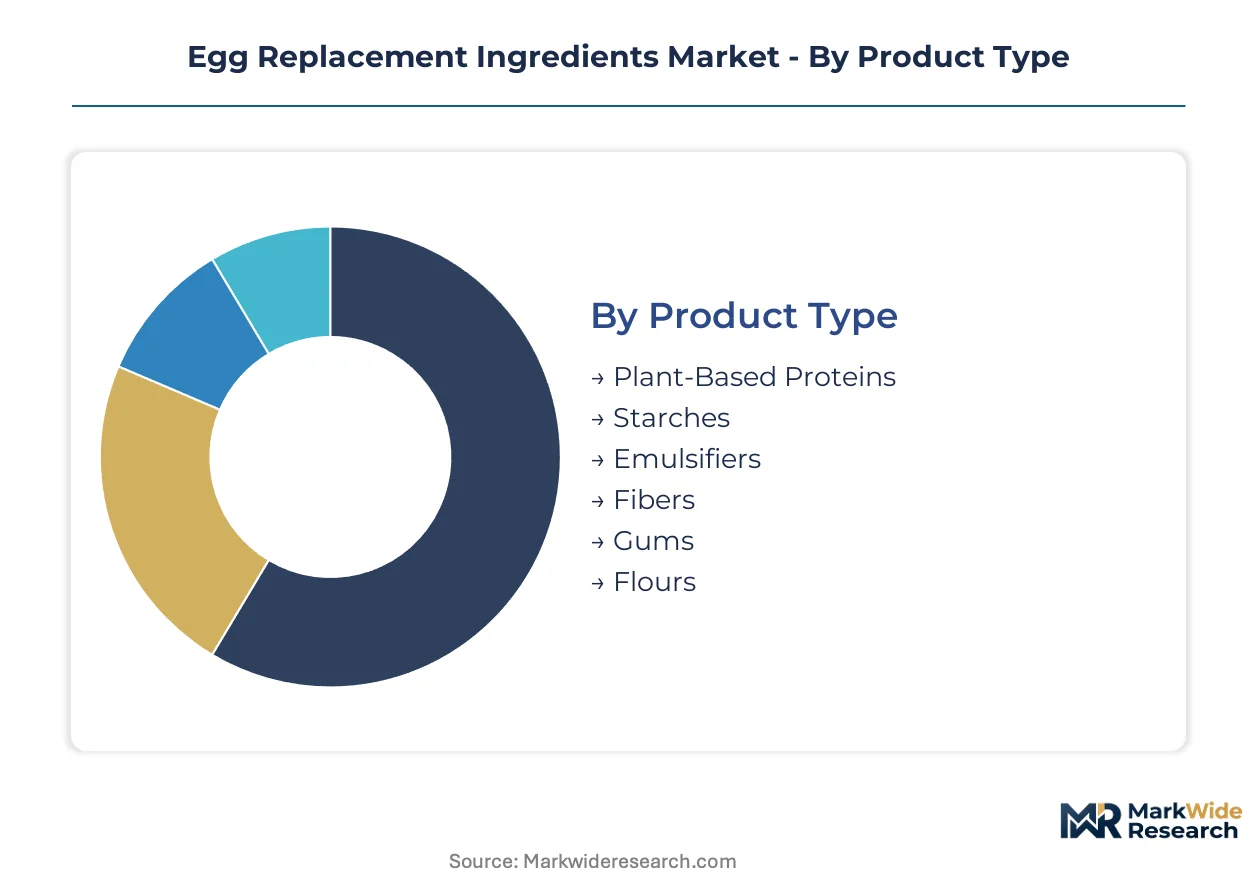
Egg replacement ingredients serve divergent functional requirements across protein systems, texture modifiers, and emulsification technologies. Segmentation reveals how formulation chemistry aligns with specific end-use constraints in bakery, meat-analogue, and sauce applications.
Product Type:
Plant-derived functional ingredients span a spectrum from high-protein isolates to polysaccharide texturizers, each addressing distinct binding, foaming, or moisture-retention challenges in industrial food production.
- Plant-Based Proteins:Pea, fava bean, and chickpea isolates provide gelation and emulsification through controlled denaturation between 60°C and 85°C. Commercial bakeries in Germany absorb the greatest volumes as they reformulate sponge cakes and meringues under EU Green Deal carbon-accounting pressures.
- Emulsifiers:Sunflower and rapeseed lecithin substitutes replicate egg-derived phospholipid functionality amid supply volatility. Meat-analogue producers in the Netherlands deploy these most aggressively as extrusion technology matures and eliminates egg binder dependencies.
- Starches:Modified potato and tapioca starches deliver viscosity and moisture retention in high-ratio cake systems.
- Fibers:Oat and citrus fibers contribute water-binding capacity in reduced-fat bakery applications.
- Gums:Xanthan and guar hydrocolloids stabilize foam structures and prevent syneresis in frozen desserts.
- Flours:Chickpea and lupin flours provide whole-system egg replacement in clean-label vegan baking.
Established volume favors plant-based proteins; emerging adoption favors emulsifiers.
Application:
Cost tier differentiation separates commodity-scale bakery deployment from premium-positioned meat-analogue and confectionery segments.
- Baked Goods:Cakes, cookies, and bread formulations represent the highest-volume deployment channel, with industrial lines requiring precise viscosity calibration for starch-thickened batters. German and Dutch commercial bakeries drive procurement as F-Gas Regulation compliance tightens ingredient provenance requirements.
- Meat Analogues:Extruded plant-based meats and seafood substitutes leverage binding and texturizing properties previously dependent on egg albumen. Advanced twin-screw extrusion systems in Cologne and Hamburg food technology hubs enable fibrous textures without traditional binders.
- Confectionery:Aerated candies and chocolate products require foaming stability and emulsification.
- Sauces & Dressings:Creamy emulsions rely on lecithin alternatives for stability and mouthfeel.
- Dairy Alternatives:Vegan mayonnaise and ice cream applications demand combined emulsification and foam stabilization.
- Snacks:Extruded and baked snack coatings utilize egg replacers for adhesion and browning control.
High-throughput bakery operations dominate current procurement volumes; meat-analogue applications are climbing the fastest as extrusion technology advances.
End User:
Customer type fragmentation separates specification-heavy industrial buyers from price-sensitive household segments.
- Commercial Bakeries:Large-scale operations with dedicated formulation chemists negotiate multi-year supply agreements for customized texture systems. Rhine-Ruhr corridor bakery groups in Germany concentrate procurement through direct blend-house contracts, disintermediating regional distributors.
- Food Processing Plants:Industrial manufacturers of meat analogues, sauces, and dairy alternatives require technical support and pilot-scale validation.
- Foodservice Providers:Restaurant chains and catering operations seek pre-hydrated or ready-to-use egg replacement blends.
- Household Consumers:Retail-packaged powders and liquid concentrates serve vegan home bakers through supermarket and online channels.
Direct procurement concentration favors commercial bakeries; emerging volume favors food processing plants as meat-analogue capacity expands.
Distribution Channel:
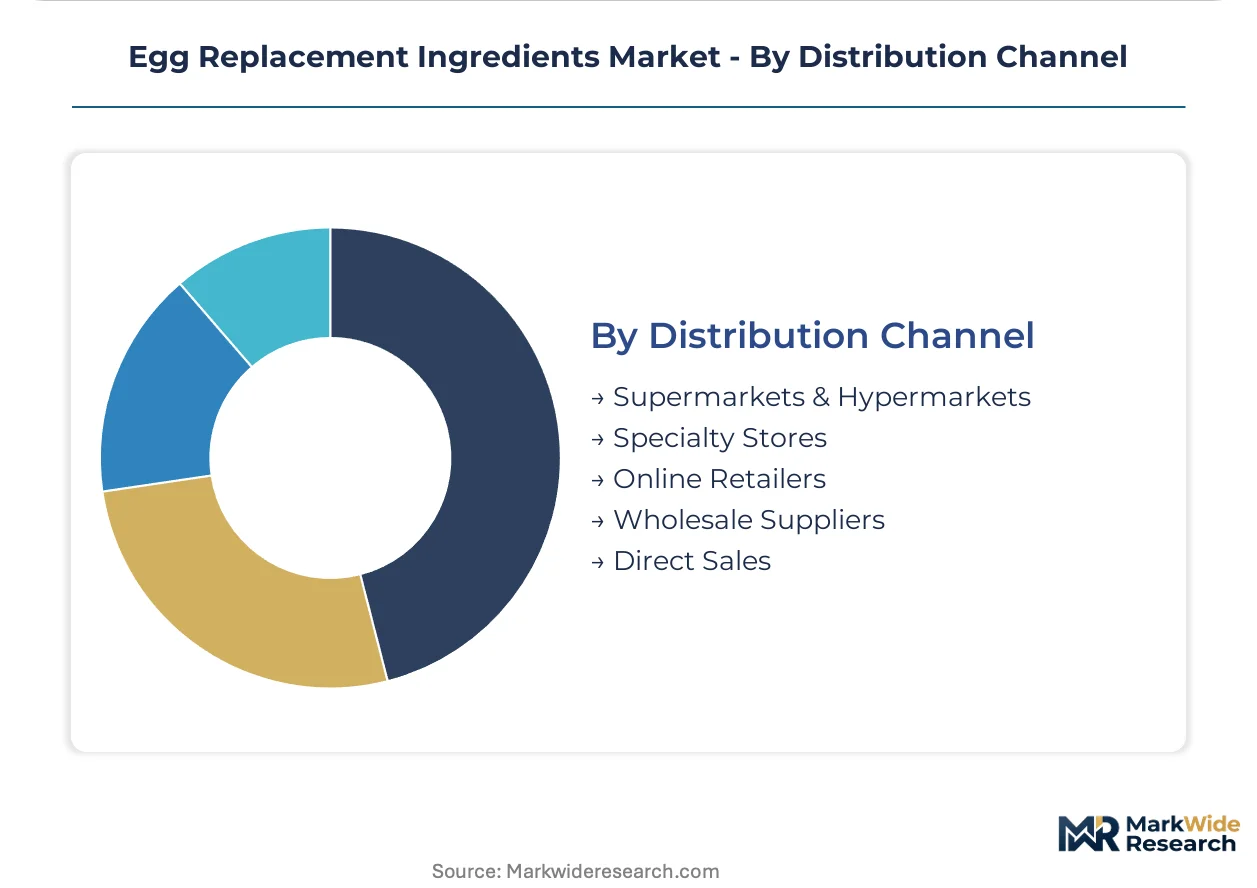
Supply concentration patterns separate consolidated wholesale and direct-sales volumes from fragmented retail endpoints.
- Wholesale Suppliers:Regional ingredient distributors serve mid-sized bakery chains with standard blends and technical documentation.
- Direct Sales:Blend houses and ingredient manufacturers contract directly with large bakery groups and food processors, locking in plant-protein volumes through multi-year agreements visible in the US Pacific Northwest and German industrial corridors.
- Supermarkets & Hypermarkets:Mass retail channels distribute consumer-ready egg replacement powders and liquids.
- Specialty Stores:Health food and vegan-focused retailers curate premium-positioned clean-label options.
- Online Retailers:E-commerce platforms enable direct-to-manufacturer ingredient marketplaces and household consumer access.
Procurement scale favors wholesale suppliers and direct sales; channel innovation favors online retailers as digital ingredient marketplaces mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the Netherlands exhibit the lowest price elasticity, absorbing premium plant-protein isolates under regulatory pressure. US commercial bakeries show higher elasticity, substituting toward modified starches when pea protein costs spike. Price-sensitive procurement dominates emerging markets where basic emulsifier blends suffice.
Germany
Commercial bakeries in the Rhine-Ruhr corridor drive concentrated demand for customized texture systems. The EU Green Deal and F-Gas Regulation mandate verified low-carbon supply chains, compressing formulation timelines. Cologne and Hamburg food technology hubs cluster R&D talent and pilot facilities, accelerating novel formulation commercialization.
United States
Industrial bakeries in the Pacific Northwest negotiate multi-year direct contracts with blend houses. FDA allergen labeling rules lag EFSA pathways, enabling faster market entry for fermented protein isolates. Mid-sized bakery chains disintermediate regional distributors through digital ingredient marketplaces.
Netherlands
Meat-analogue producers deploy advanced twin-screw extrusion systems to eliminate egg binder dependencies. EFSA novel food dossiers require 18-24 month safety evaluations, freezing some product launches. Rotterdam and Eindhoven processing corridors concentrate extrusion R&D and pilot-scale validation capacity.
France
Premium confectionery manufacturers sustain demand for high-foaming egg replacer systems. REACH compliance and evolving clean-label definitions create formulation complexity across EU member-state interpretations. Paris Basin food science institutes collaborate with ingredient houses on enzymatic protein modification protocols.
United Kingdom
Post-Brexit regulatory divergence from EU novel food pathways creates compliance arbitrage opportunities for domestic formulators. EMA and UK Food Standards Agency classification inconsistencies impact "vegan" claim packaging strategies. Greater Manchester and East Midlands industrial bakery clusters source increasingly from domestic blend houses.
Egg Replacement Ingredients Market Key Industry Players
Capability concentration sits with specialized texture-system developers; scale advantage sits with diversified agricultural processors. The market structure tiers between global ingredient conglomerates with oilseed processing infrastructure and regional blend houses offering technical support. Three archetypes dominate: integrated agricultural processors, specialty starch and hydrocolloid formulators, and precision-fermentation startups. Competitive moves center on backward integration into plant-protein fractionation and multi-year supply agreements locking in bakery chain volumes.
Among integrated agricultural processors, Cargill Incorporated and Archer-Daniels-Midland Company exemplify the scale-driven tier with captive oilseed supply chains. Kerry Group plc occupies a position within the formulation-services archetype, anchoring integrated taste and nutrition laboratory capabilities. These three represent distinct competitive vectors: upstream feedstock control, midstream processing scale, and downstream technical co-development with end-users.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Ingredion Incorporated |
| Kerry Group plc |
| Archer-Daniels-Midland Company |
| Tate & Lyle PLC |
| Corbion NV |
| Puratos Corporation |
| Glanbia PLC |
| DuPont |
| Others |
Cost & Logistics Intelligence
Black Sea sunflower lecithin concentration determines both premium-mid-economy pricing spreads and supply chain resilience architecture across egg replacement ingredient markets. Single-source dependency on Ukrainian and Russian processors compresses margins for formulators while amplifying procurement risk premiums in contract negotiations.
Pricing Analysis
Technical service contracts and formulation support drive lifetime value differentiation beyond commodity ingredient sales. Three-tier pricing structure across premium, standard, and economy levels separates patented enzyme-modified protein systems from basic starch blends and unbranded commodity isolates. Cost compression in standard-tier pea protein concentrates is intensifying because energy-intensive fractionation processes face natural gas price volatility. Mid-sized commercial bakeries in the US Pacific Northwest exhibit highest price elasticity, while German industrial bakery groups absorb premium isolates under EU Green Deal compliance mandates.
Supply Chain Analysis
Contract manufacturing capacity for specialized egg replacer blends concentrates with Corbion NV in the Netherlands, Puratos Corporation in Belgium, and regional blend houses across Germany's Rhine-Ruhr corridor. Raw material sourcing draws from Canadian yellow pea fractionation, French fava bean processing, and Black Sea sunflower crushing. Single-source vulnerability in lecithin supply creates acute exposure to geopolitical disruption. Distribution runs through direct sales agreements with large bakery groups, bypassing traditional regional distributors in concentrated procurement corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The egg replacement ingredients market sits at an early-cycle expansion phase where clean-label regulatory mandates and extrusion technology maturation accelerate adoption beyond traditional vegan niche positioning.
For Market Incumbents: Insulate formulation service revenue from commodity protein price volatility by locking multi-year technical support contracts with German and Dutch commercial bakery groups. Deepen backward integration into pea and fava bean fractionation capacity in Canada and France to secure feedstock against agricultural yield fluctuations. Patent-protected enzyme modification protocols represent the priority defensive moat against precision-fermentation entrants. For New Entrants and Emerging Players: Mid-sized meat-analogue producers in the Netherlands and US Pacific Northwest represent the most penetrable entry point for novel fermented protein isolates. Direct-to-manufacturer digital platforms bypass established distributor markups and accelerate customer acquisition cycles. Technical co-development partnerships with extrusion equipment manufacturers unlock pilot-scale validation credibility. For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors specialized texture-system developers with regulatory affairs infrastructure over undifferentiated commodity suppliers. Acquisition targets should demonstrate EFSA novel food dossier experience and established bakery chain validation partnerships. Quarterly tracking of precision-fermentation scale-up announcements and EFSA approval timelines signals inflection toward functional parity with egg whites.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Protein Fractionation | Captive supply of Canadian pea and French fava bean isolates secures margin control against agricultural volatility. |
| EFSA Novel Food Dossier Submission | Early filing locks competitive position ahead of 18-24 month safety evaluation timelines for emerging isolates. |
| Direct-to-Manufacturer Platform Launch | Digital ingredient marketplaces disintermediate regional distributors and compress customer acquisition costs. |
| Precision-Fermentation Scale-Up Partnership | Microbial protein production alliances promise functional parity with egg whites at industrial scale. |
| Multi-Year Supply Agreement with Bakery Chains | Volume commitments from German Rhine-Ruhr corridor groups lock in plant-protein offtake and utilization rates. |
Research Approach
A spread of perspectives from formulation chemists at commercial bakeries, procurement directors at meat-analogue producers, regulatory affairs specialists navigating EFSA pathways, and technical sales leads at ingredient blend houses converged on the working assumptions. Primary interview insights combined with secondary validation from EU novel food registration databases, FDA allergen labeling guidance documents, customs trade data on plant-protein imports, and SEC filings from diversified agricultural processors. Bottom-up volume modeling across application segments triangulated against top-down market sizing from industry association reports.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application viscosity requirement, end-user scale category, and regional regulatory cluster complexity. CAGRs derived from fitted growth curves applied to validated base-year estimates, with cross-reference to historical protein ingredient adoption patterns. Forecast inputs incorporated extrusion technology deployment rates and EFSA novel food approval velocity assumptions.
Practitioners should monitor EFSA dossier backlog accumulation, Black Sea logistics disruption indicators, and precision-fermentation commercialization announcements for early signals of forecast deviation. Quarterly review of pea protein spot price movements, bakery chain reformulation timelines, and clean-label certification adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Safflower Oil Market
Ingredients
North America and Europe Coconut Derivatives Market
Ingredients
Refined Coconut Oil Market
Ingredients
Asia-Pacific Food Coating Ingredients Market
Ingredients
Corn Steep Liquor Market
Ingredients
PHO Oils Market
Ingredients
Resistant Starch Market
Ingredients
Feed Premix Market
Ingredients
Tryptose Market
Ingredients
Icing Shortening Market
Ingredients
Torula Yeast Market
Ingredients
Europe Plant Protein Ingredients Market
Ingredients
North America Carrageenan Market
Ingredients
Wort Concentrate Market
Ingredients
Wheat Malt Market
Ingredients
Psyllium Products Market