
 Wort Concentrate Market | 2026-2036
Wort Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Wort Concentrate Market Analytics
Buyer concentration among mid-sized craft breweries is recalibrating procurement patterns across the wort concentrate supply base. Briess Malt & Ingredients leverages its North American malting infrastructure to secure long-term contracts with regional brewers. Muntons sustains competitive position through specialized liquid extract formulations tailored to small-batch operators. Döhler Natural Food and Beverage Ingredients anchors European demand by integrating wort concentrates into broader beverage ingredient portfolios.
Wort concentrate denotes a condensed malt-derived extract produced through controlled mashing, lautering, and evaporation, typically achieving solids content between 78% and 82% for syrups and 95% plus for powders. The substance functions primarily as a fermentable substrate in brewing and distillation, eliminating traditional mashing steps while standardizing sugar profiles. Liquid concentrate dominates volume flows due to lower reconstitution costs for industrial breweries, whereas powder formats command margin premiums from export-oriented food manufacturers seeking reduced freight weight. Baking and flavoring applications represent the fastest-expanding demand pool as savory flavor houses adopt malt-derived syrups for clean-label formulations.
The FDA's GRAS self-determination framework and the EPA's Clean Water Act discharge standards shape manufacturing compliance costs for US-based producers, while the EU's Food Safety Authority enforces strict acrylamide thresholds in thermally processed malt products. Germany's BfR and France's ANSES maintain divergent guidance on heavy metal limits in malt extracts, fragmenting certification requirements for cross-border suppliers. Stakeholders must monitor evolving alcohol excise classifications, as several jurisdictions reassess whether wort concentrate sales to homebrewers trigger beverage taxation rather than ingredient duties.
Market Dynamics
Procurement consolidation among mid-sized craft breweries is compressing supplier margins and forcing malt houses to reconfigure liquid extract production lines for smaller batch flexibility. The shift from in-house mashing to outsourced wort concentrate is redrawing competitive boundaries between traditional malters and beverage ingredient specialists.
Growth Catalysts
- EU Food Information to Consumers Regulation:Mandatory purity declarations for malt-derived ingredients are pushing breweries toward certified concentrate suppliers with verified supply chain documentation.
- Clean-label savory formulations:Flavor houses in the baking sector are adopting malt-derived syrups to replace artificial caramel colorings and synthetic flavor enhancers.
- Bavaria cluster density:Proximity to Weyermann Malting and regional distilleries creates logistical efficiencies that lower per-unit procurement costs for liquid concentrate buyers.
Market Restraints
- Barley price volatility:Input cost swings for malting-grade grain compress margins for producers locked into annual supply contracts with industrial breweries.
- German-French regulatory divergence:BfR and ANSES maintain conflicting heavy metal limits in malt extracts, fragmenting certification requirements for cross-border suppliers.
- All-grain homebrewing revival:Enthusiast brewers with access to affordable small-scale mashing equipment view concentrate as a quality compromise.
Strategic Opportunities
- Non-alcoholic beverage expansion:Malt-based soft drink producers in Germany represent an underpenetrated demand pool for standardized wort bases.
- Carbon footprint labeling:EU Green Deal disclosure requirements create first-mover advantage for concentrate producers with verified Scope 3 emissions data.
- E-commerce direct-to-homebrewer channels:Specialty retailers are building subscription models that bypass traditional foodservice distribution tiers.
Industry Challenges
- Acrylamide compliance testing:EFSA thresholds for thermally processed malt products require capital-intensive laboratory infrastructure that smaller producers struggle to fund.
- Legacy equipment incompatibility:Industrial breweries with fixed-ratio mashing systems face integration friction when blending concentrate with traditional wort streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wort Concentrate Market |
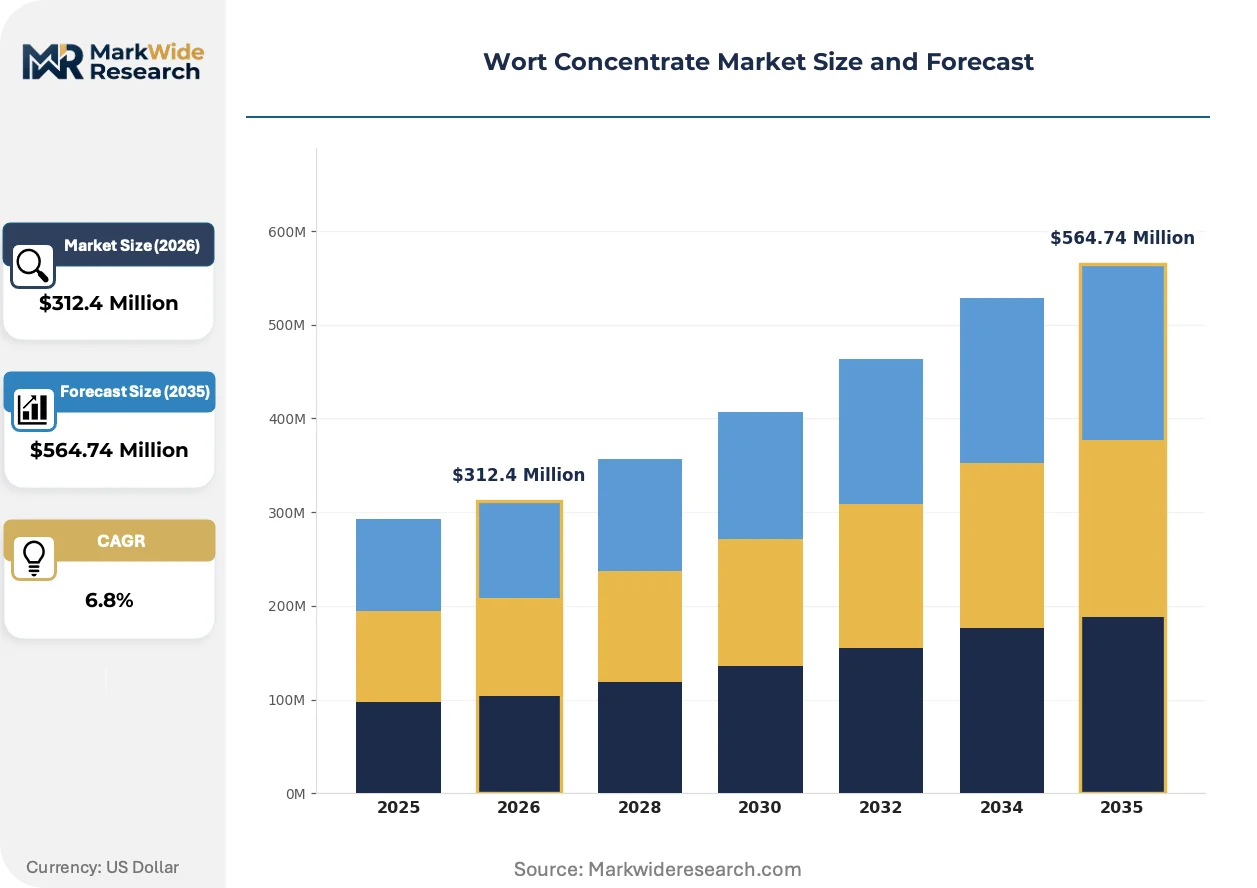
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Syrup, Granule Application: Brewing, Distillation, Baking, Flavoring End User: Breweries, Bakeries, Food Manufacturers, Homebrewers Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | Briess Malt & Ingredients, Muntons, Döhler Natural Food and Beverage Ingredients, Castle Malting, Weyermann Malting, Black Rock, Thomas Fawcett and Sons, Crisp Malt, Patagonia Malt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wort Concentrate Market Evolving Landscape
Membrane filtration and low-temperature evaporation technologies are redefining quality benchmarks for liquid concentrates. These advances are compressing the traditional trade-off between extract yield and flavor preservation that has constrained product development for decades.
Cross-flow microfiltration systems are overtaking conventional diatomaceous earth filtration in premium concentrate production. Bavarian craft distilleries are adopting these systems to retain volatile aromatic compounds previously lost to heat damage. The technology is enabling smaller production runs with batch-specific flavor profiles that command pricing premiums from regional breweries.
EPA Clean Water Act discharge standards are tightening effluent limits for malt processing facilities with direct discharge permits. Plants in water-stressed regions face capital decisions on closed-loop evaporation systems versus treatment infrastructure upgrades. Powder concentrate producers with thermal recovery systems are gaining operational flexibility under these constraints.
Consolidated buying cooperatives are displacing individual brewery procurement functions across the US craft sector. These pooled purchasing entities negotiate volume-tiered contracts that extract price concessions unavailable to standalone operators. The Pacific Northwest brewing cluster exhibits the most advanced cooperative structures, with shared storage and logistics reducing per-unit freight costs.
Wort Concentrate Market Segmentation
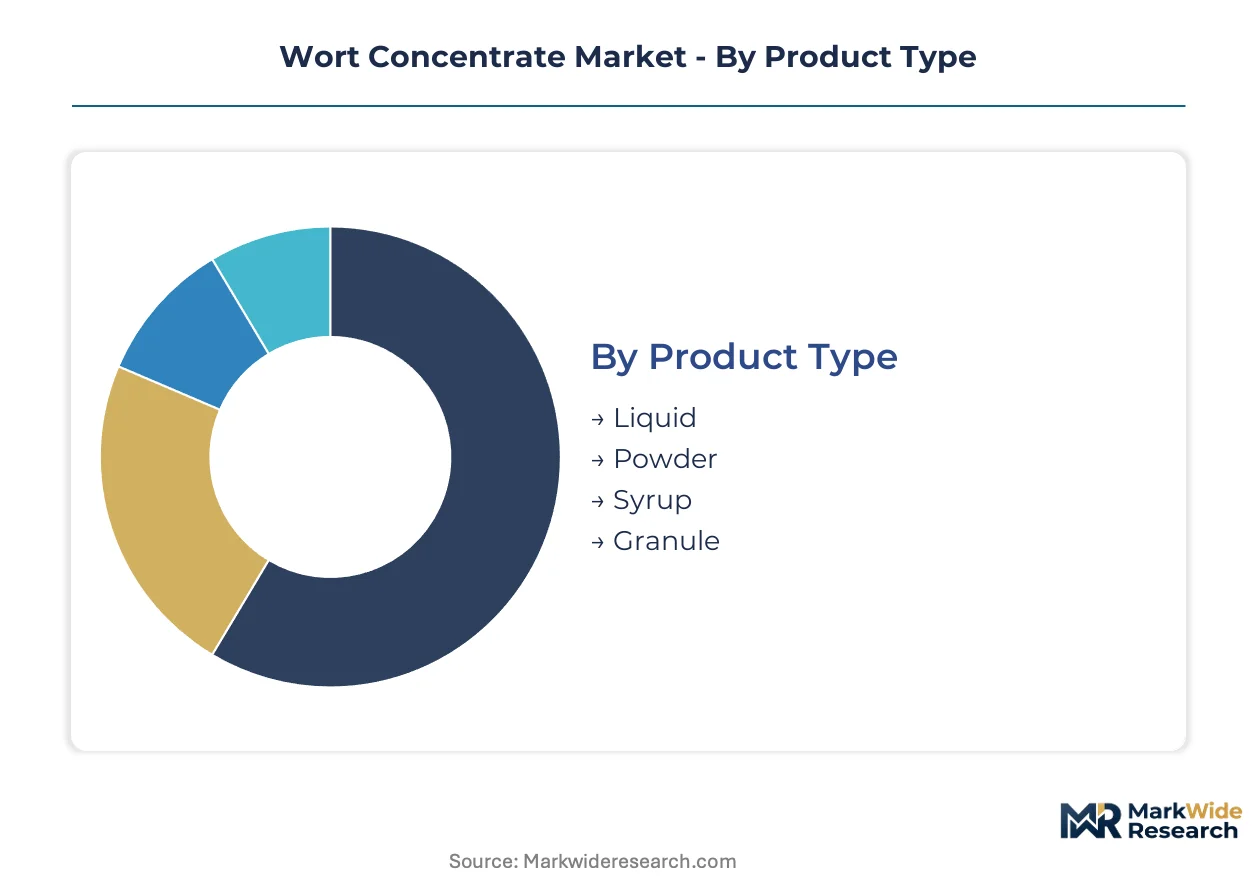
Wort concentrate segmentation reveals how production format, application intensity, and procurement channel reshape supplier economics. Each dimension carries distinct margin profiles and regulatory exposure that determine competitive positioning.
Product Type:
Upgrade cycles from legacy mashing infrastructure toward concentrate-based systems favor formats with lower reconstitution friction and extended shelf stability.
- Liquid:Achieves 78-82% solids content through controlled evaporation, preserving enzymatic activity for fermentation consistency. Demand concentrates in Germany's Bavaria region, where Weyermann Malting and regional craft distilleries anchor supply chain density and breweries prioritize batch-to-batch reproducibility over transport cost optimization.
- Powder:Exceeds 95% solids via spray-drying or drum-drying, slashing freight weight for export-oriented food manufacturers. Powder formats command margin premiums from baking sector buyers in France and the Netherlands seeking reduced logistics spend on intercontinental shipments.
- Syrup:Intermediate viscosity liquid with standardized Brix levels, suited for small-batch breweries lacking precision dosing equipment.
- Granule:Agglomerated powder form with enhanced flow properties, addressing caking issues in humid climates for tropical market distribution.
Liquid concentrate sits at the top of the volume ranking, with powder climbing the fastest as export-oriented food manufacturers seek freight optimization.
Application:
Cost tier differentiation separates commodity brewing substrates from premium flavoring ingredients with divergent certification requirements and margin structures.
- Brewing:Fermentable base for beer production, eliminating traditional mashing steps while standardizing sugar profiles. Procurement concentrates among mid-sized North American craft breweries expanding concentrate adoption to compress production cycle times.
- Distillation:Standardized wort base for whiskey and spirits production, prized for predictable alcohol yield. Bavarian craft distilleries adopting cross-flow microfiltration systems drive premium concentrate demand for volatile aromatic retention.
- Baking:Malt-derived syrups replace artificial caramel colorings in clean-label formulations. Flavor houses in the sector represent the fastest-expanding demand pool as savory applications adopt malt extracts.
- Flavoring:Concentrated malt extracts for beverage and savory flavor systems, requiring EFSA acrylamide compliance certification.
Brewing commands the dominant volume position, with baking gaining share fastest as clean-label reformulation accelerates across European savory applications.
End User:
Customer type fragmentation creates divergent service models, from technical support-intensive brewery partnerships to commodity transactions with food manufacturers.
- Breweries:Industrial and craft beer producers seeking fermentation consistency and production cycle compression. Consolidated buying cooperatives in the US Pacific Northwest are displacing individual procurement functions with pooled volume-tiered contracts.
- Bakeries:Artisan and industrial bread producers incorporating malt syrups for crust color and flavor modulation.
- Food Manufacturers:Savory flavor houses and beverage formulators requiring certified supply chain documentation under EU Food Information to Consumers Regulation.
- Homebrewers:Enthusiast segment with rising e-commerce subscription penetration, though all-grain revival among equipment-accessible hobbyists constrains concentrate appeal.
Breweries anchor volume concentration, with food manufacturers expanding most quickly as regulatory purity declarations tighten across EU member states.
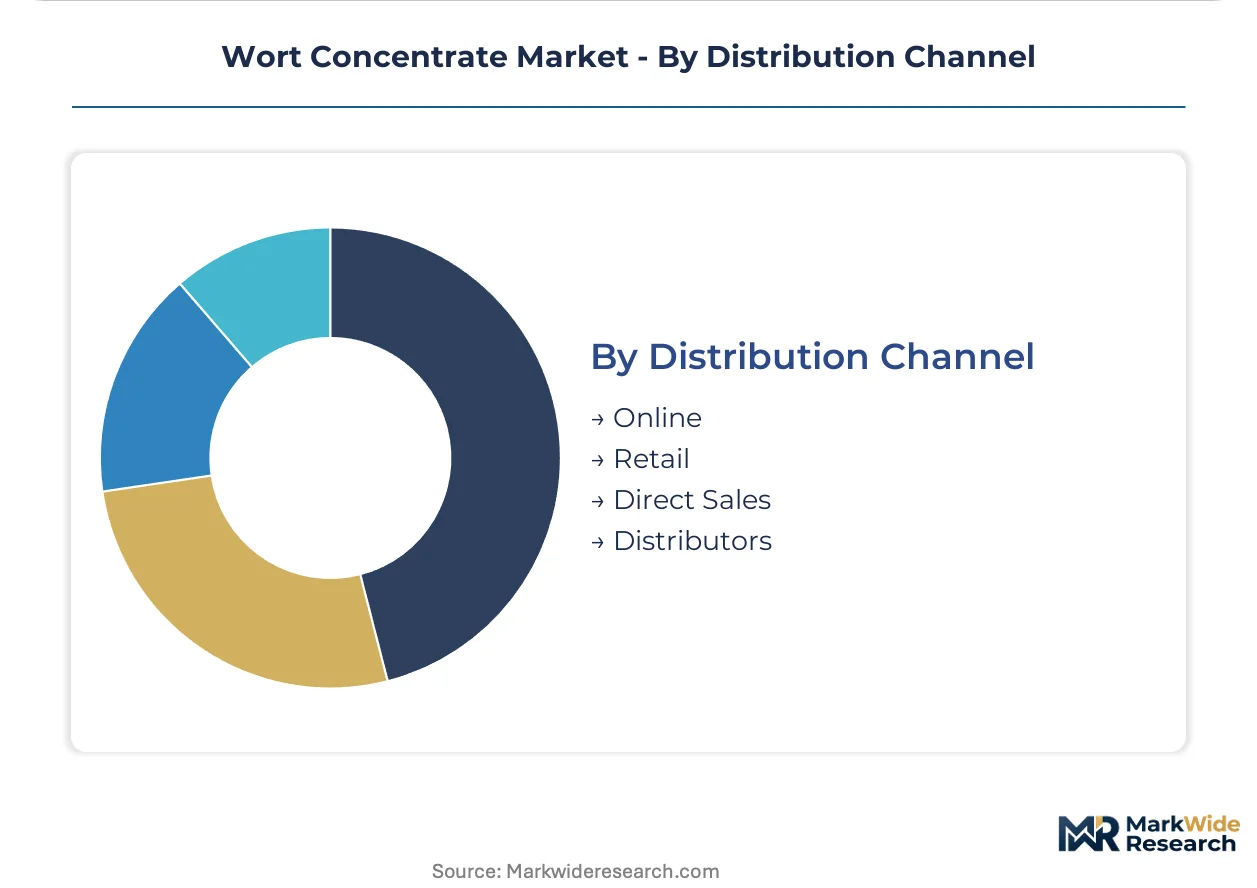
Distribution Channel:
Supply concentration in malt-processing clusters dictates channel efficiency, with direct sales advantaged in Bavaria and online channels penetrating fragmented homebrewer demand.
- Online:E-commerce direct-to-homebrewer channels built on subscription models that bypass traditional foodservice distribution tiers. Specialty retailers leverage this channel for geographic reach beyond established brewing clusters.
- Retail:Brick-and-mortar homebrew supply stores and food ingredient distributors serving small-batch operators.
- Direct Sales:Long-term contracts between malt houses and industrial breweries, exemplified by Briess Malt securing regional brewer commitments through North American malting infrastructure proximity.
- Distributors:Third-party logistics networks enabling cross-border concentrate movement, navigating German-French regulatory divergence on heavy metal limits.
Direct sales hold the volume lead, with online channels climbing fastest as subscription models capture homebrewer loyalty outside traditional distribution geography.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the densest concentration of wort concentrate production infrastructure, while the United States leads in craft brewery adoption rates for liquid extract systems.
Germany
Bavaria anchors European supply chain density through Weyermann Malting and clustered craft distilleries. The BfR enforces food contact material guidelines that tighten purity declarations for malt-derived ingredients. Regional producers adopting cross-flow microfiltration systems retain volatile aromatic compounds for premium concentrate batches.
United States
Mid-sized craft breweries across the Pacific Northwest and New England are consolidating procurement through buying cooperatives. The FDA's GRAS self-determination framework shapes manufacturing compliance costs for domestic producers. Briess Malt leverages North American malting infrastructure to secure long-term contracts with regional brewers in Wisconsin and surrounding states.
France
Flavor houses in the baking sector are adopting malt-derived syrups for clean-label savory formulations. ANSES maintains divergent heavy metal limits from German BfR standards, fragmenting certification requirements for cross-border suppliers. Industrial bread producers in Île-de-France incorporate malt extracts for crust color modulation.
United Kingdom
Specialty retailers are building e-commerce subscription models that bypass traditional foodservice distribution tiers. The UK Food Standards Agency aligns with EFSA acrylamide thresholds for thermally processed malt products. Thomas Fawcett and Sons anchors traditional malting heritage in Yorkshire while adapting liquid extract capabilities.
Belgium
Castle Malting serves export-oriented food manufacturers seeking reduced freight weight through powder concentrate formats. EU Food Information to Consumers Regulation mandates verified supply chain documentation for malt-derived ingredients. The Flemish brewing cluster generates logistical efficiencies for liquid concentrate buyers serving traditional lambic producers.
Wort Concentrate Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: integrated malting houses with captive concentrate production, beverage ingredient specialists with diversified extract portfolios, and regional craft maltsters with batch-flexible systems. Dominant competitive moves include backward integration into barley sourcing and technology licensing for low-temperature evaporation systems.
Within the integrated malting tier, Briess Malt & Ingredients and Muntons occupy positions exemplifying North American and European infrastructure scale respectively. Döhler Natural Food and Beverage Ingredients represents the diversified beverage ingredient archetype, anchoring European demand through integration of wort concentrates into broader formulation portfolios. Weyermann Malting and Castle Malting sit within the heritage maltster segment, leveraging geographic proximity to brewing clusters for logistical advantage.
| Leading Market Players |
|---|
| Briess Malt & Ingredients |
| Muntons |
| Döhler Natural Food and Beverage Ingredients |
| Castle Malting |
| Weyermann Malting |
| Black Rock |
| Thomas Fawcett and Sons |
| Crisp Malt |
| Patagonia Malt |
| Others |
Value Network & Pricing Analysis
Procurement consolidation among mid-sized craft breweries is compressing supplier margins and forcing malt houses to reconfigure liquid extract production lines for smaller batch flexibility. This buyer-side pressure is redrawing competitive boundaries between traditional malters and beverage ingredient specialists, with pricing power shifting toward volume-tiered cooperative contracts.
Pricing Analysis
Capacity additions in Germany's Bavaria region are reshaping price floors for premium liquid concentrates. Three-tier pricing structure across premium, standard, and economy levels separates cross-flow microfiltration batches from conventional evaporated syrups and commodity-grade powders. Cost compression in standard-tier liquid formats is intensifying because barley price volatility feeds directly into malt house margin structures. Small-batch craft breweries exhibit highest price sensitivity, while industrial food manufacturers purchasing powder concentrates for intercontinental shipment show lowest sensitivity due to freight-weight savings.
Supply Chain Analysis
Domestic-content mandates under EU Food Information to Consumers Regulation are reshaping sourcing patterns toward verified regional malt houses. Supply concentrates in Germany, the United States, and Belgium, with Bavarian clusters anchoring European liquid concentrate flows and Wisconsin-based malting infrastructure serving North American craft brewery demand. Raw material dependencies center on malting-grade barley, enzymatic processing aids, and food-grade packaging materials. Single-source vulnerability runs through concentrated barley sourcing regions exposed to climate-driven yield variability. Distribution runs through direct sales contracts for industrial breweries, supplemented by e-commerce subscription channels penetrating fragmented homebrewer demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wort concentrate market functions as a regulatory compounder, with EU Food Information to Consumers Regulation mandatory purity declarations driving brewery procurement toward certified suppliers with verified supply chain documentation.
For Market Incumbents: Lock in backward integration into barley sourcing to insulate margin structures from grain price volatility. Secure long-term contracts with consolidated buying cooperatives in the US Pacific Northwest before regional craft brewery procurement functions fully centralize. Cross-flow microfiltration certification investments differentiate premium concentrate batches from commodity competitors. For New Entrants and Emerging Players: Enter via non-alcoholic beverage expansion in Germany, where malt-based soft drink producers represent underpenetrated demand for standardized wort bases. Bavarian craft distilleries adopting aromatic-retention technologies offer the most penetrable premium segment. E-commerce direct-to-homebrewer subscription models bypass entrenched foodservice distribution tiers. For Investors and Strategic Acquirers: Asymmetric upside sits with batch-flexible regional craft maltsters possessing cross-flow microfiltration capabilities and proximity to brewing cluster density. Long-term viability hinges on carbon footprint labeling readiness under EU Green Deal disclosure requirements. Watch for Scope 3 emissions verification infrastructure deployment as inflection indicator for first-mover advantage capture.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Flow Microfiltration Adoption | Bavarian craft distilleries retain volatile aromatics previously lost to heat damage, commanding pricing premiums. |
| Backward Integration into Barley Sourcing | Malting houses secure captive supply of malting-grade grain against climate-driven yield variability. |
| Carbon Footprint Labeling Investment | Concentrate producers with verified Scope 3 data gain first-mover advantage under EU Green Deal requirements. |
| E-Commerce Subscription Channel Buildout | Specialty retailers capture homebrewer loyalty outside traditional Pacific Northwest and New England distribution geography. |
| Closed-Loop Evaporation System Deployment | Powder concentrate producers gain operational flexibility under EPA Clean Water Act discharge standards tightening. |
Research Methodology
Direct dialogue with malt house operations directors, craft brewery procurement managers, flavor house R&D directors, and beverage ingredient distribution channel partners grounded the qualitative foundation. Secondary validation drew from FDA GRAS determinations, EFSA acrylamide threshold documentation, EU Food Information to Consumers Regulation filings, and customs trade data on malt extract movements. Bottom-up volume modeling triangulated against top-down market sizing across product format, application intensity, and procurement channel dimensions.
Bottom-up demand aggregation by end-user segment and format type converged with top-down macroeconomic elasticity assumptions across the projection horizon. Segmentation dimensions modeled include liquid versus powder versus syrup versus granule formats, brewing versus distillation versus baking versus flavoring applications, and brewery versus food manufacturer versus homebrewer customer types. CAGRs were derived from segment-level growth rate blending weighted by base-year value shares. Industry-specific forecast inputs incorporated barley futures price trajectory assumptions and craft brewery formation rates by US census region.
Inputs from malt house financial disclosures and cooperative procurement entity contract structures were available through the study window; gaps in small-scale craft distillery concentrate adoption data introduce uncertainty bands around distillation application forecasts. Forecasts reflect documented assumptions on regulatory enforcement intensity and barley yield recovery patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Potato & Yam Derivatives Market
Ingredients
Milk Ingredients Market
Ingredients
Volatile Fatty Acids Market
Ingredients
France Protein Market
Ingredients
Textured Soy Protein Market
Ingredients
South America Vegetable Oil Market
Ingredients
Bran Market
Ingredients
Food Grade Hydrolyzed Casein Market
Ingredients
Dry Brewing Ingredients Market
Ingredients
Cacao Bean Market
Ingredients
Arrowroot Starch Market
Ingredients
Pea Flour Market
Ingredients
Low-Fat Cocoa Powder Market
Ingredients
PDO/PGI-Linked Mediterranean Ingredient Collections Market
Ingredients
Confectionery Ingredients Market
Ingredients
Wheat Germ Oil Market