
 Torula Yeast Market | 2026-2036
Torula Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Torula Yeast Market Analysis
Precision fermentation and cell-culture optimization is reconfiguring how torula yeast biomass achieves commercial scale and functional consistency. Lallemand Inc. leverages proprietary strain libraries to dominate North American supply chains for food-grade torula derivatives. Lesaffre Group anchors European production through integrated fermentation facilities that sustain cost advantages in yeast extract manufacturing. Angel Yeast Co. Ltd. competes aggressively on powder and flake formats, extending its footprint across Asian nutritional supplement channels.
Torula yeast denotes a non-Saccharomyces species, Candida utilis, cultivated on wood-derived sugars or agricultural residues, typically yielding 45-55% crude protein content with a balanced amino acid profile including lysine and threonine. Manufacturers deploy submerged aerobic fermentation at controlled pH and temperature to produce biomass for human food, animal nutrition, and pharmaceutical applications. Yeast extract and torula yeast powder command the deepest margin pools within product type segments, reflecting their concentration of nucleotides and glutamic acid for umami delivery. The animal feed ingredient application grows fastest structurally, as aquaculture and pet food formulators replace marine proteins with single-cell alternatives to address supply volatility and sustainability mandates.
FDA GRAS status and USDA organic certification govern human food applications in the United States, while the EU Novel Food Regulation and EFSA safety assessments shape market access for innovative torula-derived ingredients in Europe. These frameworks elevate compliance costs for new entrants but simultaneously validate premium positioning for established suppliers with documented toxicology dossiers. Stakeholders must monitor evolving protein-labeling standards and carbon-accounting requirements that will determine which fermentation platforms secure preferred procurement status across food and feed value chains.
Market Dynamics
Precision fermentation scale-up and EU decarbonization mandates are compressing production economics while redirecting capital toward bio-based protein platforms.
Growth Catalysts
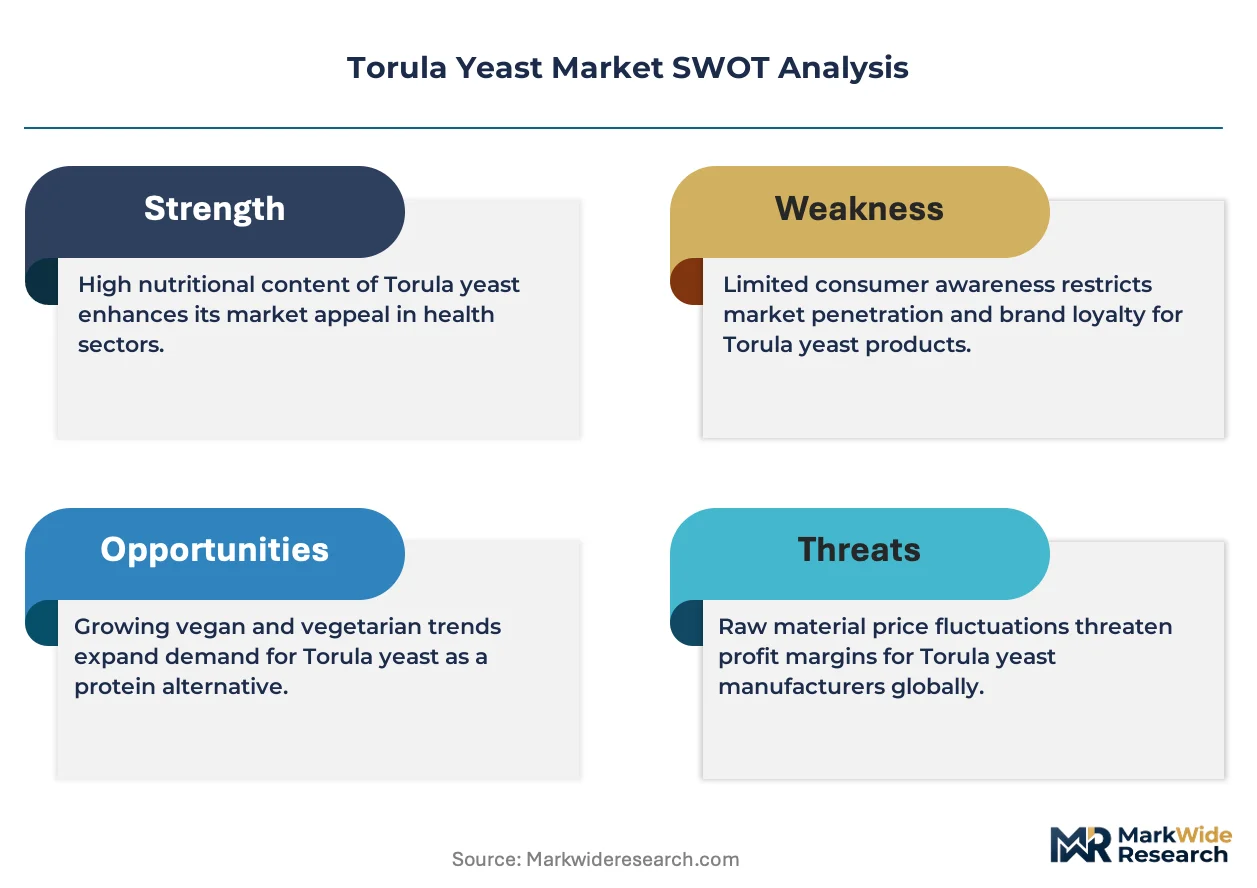
- EU F-Gas Regulation:European manufacturers face binding phase-down schedules for synthetic refrigerants, pushing fermentation facilities toward torula yeast as a lower-carbon protein input for food and feed applications.
- Aquafeed formulators:Salmon and shrimp producers in Norway and Chile are substituting fishmeal with single-cell proteins to mitigate marine supply volatility and meet ASC certification requirements.
- Wood-derived sugar platforms:Forestry residue valorization technologies in Scandinavia are unlocking feedstock cost advantages that improve torula yeast unit economics against soy and pea isolates.
Market Restraints
- Molasses price volatility:Cane and beet sugar byproduct costs fluctuate with agricultural commodity cycles, squeezing margin predictability for conventional fermentation operators.
- Strain IP concentration:Proprietary Candida utilis libraries remain concentrated among three North American and European suppliers, limiting new entrant access to high-yield phenotypes.
- Soy protein isolate substitution:Established oilseed processing infrastructure and farmer subsidy regimes in the US and Brazil sustain cost advantages for legacy plant proteins in mass-market feed.
Strategic Opportunities
- Clean-label flavor enhancers:German and French industrial bakeries are reformulating with torula-derived nucleotides to replace synthetic MSG while maintaining umami intensity.
- USDA organic certification pathways:USDA organic torula yeast commands 40-60% price premiums in human nutrition channels, creating margin expansion for compliant fermentation investments.
- Precision fermentation + AI strain optimization:Converging computational biology tools with continuous culture systems promises to compress development timelines for novel functional strains.
Industry Challenges
- Bioprocess engineering talent scarcity:Industrial-scale aerobic fermentation requires specialized metabolic engineering and downstream processing expertise that outpaces current graduate program output.
- EFSA Novel Food dossier timelines:European market access for innovative torula-derived ingredients requires 18-24 month safety assessments that delay revenue recognition.
- Legacy feed formulation integration:Animal nutritionists at major compounders require extensive retraining to optimize amino acid balancing with single-cell proteins versus conventional oilseed meals.
Report Scope
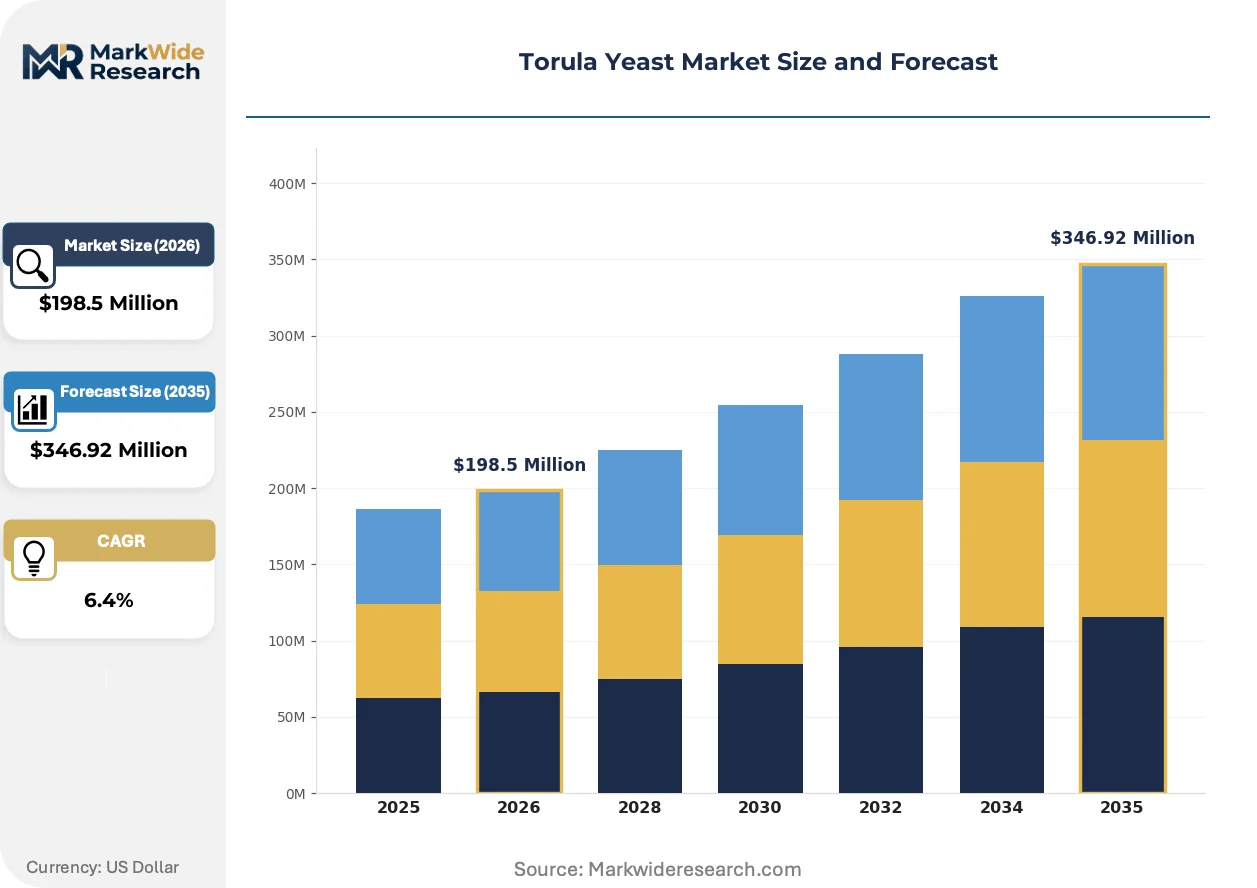
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Torula Yeast Market |
| Market Size in 2026 | $198.5 Million |
| Market Size in 2035 | $346.92 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Torula Yeast, Yeast Extract, Torula Yeast Powder, Torula Yeast Flakes End User: Food Industry, Animal Nutrition, Bakery, Pharmaceuticals Application: Flavor Enhancer, Nutritional Supplement, Animal Feed Ingredient, Food Preservative Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Lallemand Inc., Oriental Yeast Co. Ltd., Lesaffre Group, Archer Daniels Midland Company, Alltech Inc., Associated British Foods plc, Chr. Hansen A/S, Angel Yeast Co. Ltd., Koninklijke DSM N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Torula Yeast Market Emerging Trajectories
Bioprocessing architectures and regulatory frameworks are simultaneously evolving, compressing the gap between pilot-scale strain development and commercial biomass production.
Continuous fermentation with real-time metabolite monitoring is migrating from pharmaceutical monoclonal antibody production into commodity yeast biomass operations. Contract manufacturers serving pet food brands in the US Midwest are retrofitting stainless steel trains with perfusion capabilities that boost volumetric productivity threefold. This technology diffusion is compressing capital requirements for new market entrants while eroding the scale advantages of legacy batch facilities.
REACH registration requirements for novel fermentation inputs are tightening substance characterization obligations across European supply chains. ECHA's 2024 updated guidance on microbial biomass derivatives now demands expanded toxicology packages for proteins exceeding defined molecular weight thresholds. Human food ingredient suppliers are responding by front-loading safety studies to secure Article 95 listing ahead of competitor submissions.
Direct procurement relationships between pet food superbrands and fermentation operators are displacing traditional ingredient distributor networks. Mars Petcare and Nestlé Purina are establishing multi-year offtake agreements with torula yeast producers that specify carbon intensity thresholds and traceability protocols. This channel restructuring is most visible in North American markets where vertical consolidation in pet food manufacturing has concentrated buying power among four national formulators.
Torula Yeast Market Segmentation
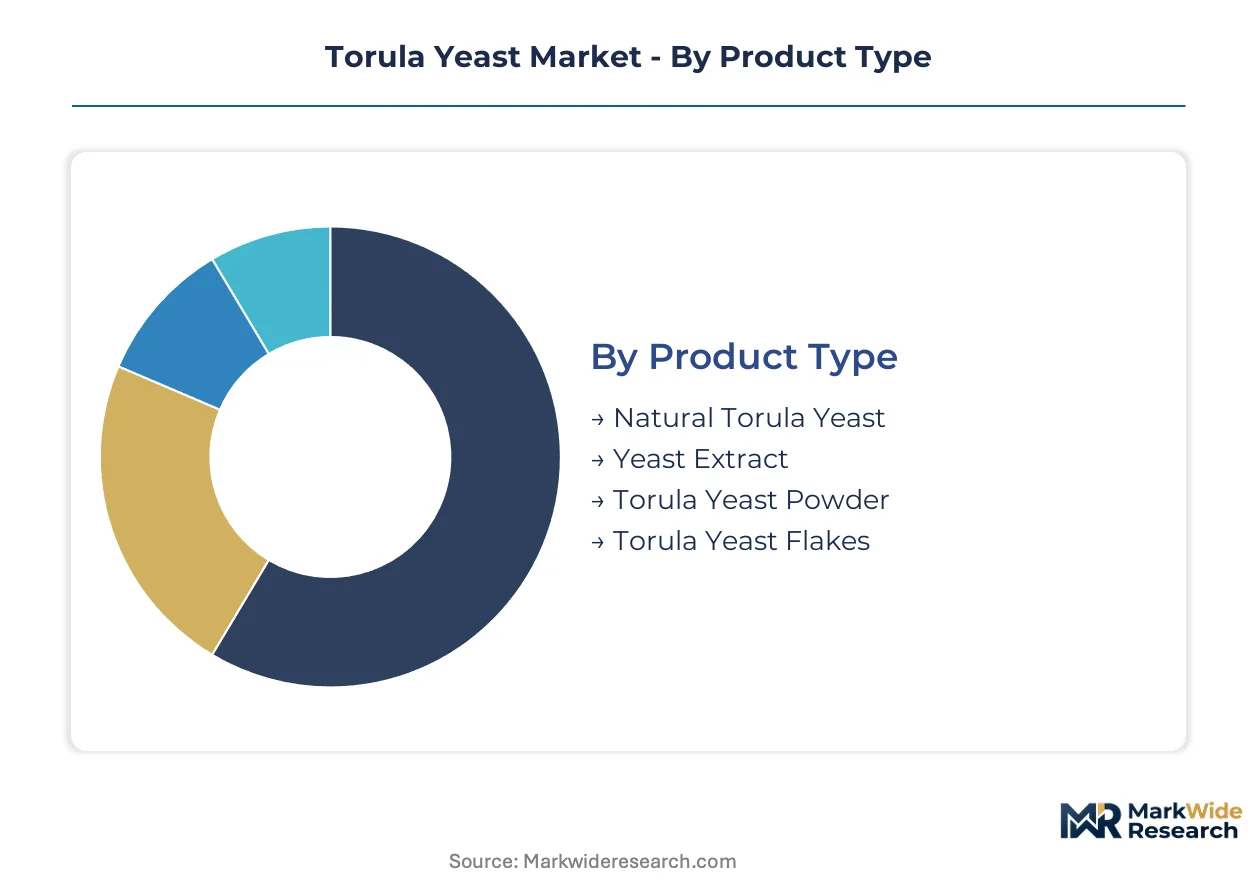
Torula yeast suppliers configure production lines around protein concentration, solubility profiles, and downstream processing intensity. Segmentation logic directly shapes margin architecture and regulatory pathway requirements across food, feed, and pharmaceutical channels.
Product Type:
Mature formats dominate current revenue, while emerging extraction technologies are redefining functional performance benchmarks.
- Yeast Extract:Concentrated nucleotide and glutamic acid content delivers clean-label umami functionality. Industrial bakeries in Germany and France reformulate with this extract to replace synthetic MSG while maintaining flavor intensity.
- Torula Yeast Powder:Spray-dried biomass with 45-55% crude protein serves nutritional supplement manufacturers. Powder commands premium positioning in Asian markets where protein fortification drives formulation decisions.
- Natural Torula Yeast:Minimally processed whole-cell biomass retains full vitamin B-complex and mineral content. Pet food formulators favor this format for its complete nutritional profile and digestibility claims.
- Torula Yeast Flakes:Debittered flake structures provide textural versatility for savory seasoning blends. Flake production requires specialized drying equipment that limits supplier participation.
Yeast extract handles the majority of throughput; torula yeast powder is expanding most quickly on share.
End User:
Customer sophistication varies sharply across sectors, with pharmaceutical buyers imposing the most stringent documentation requirements.
- Animal Nutrition:Aquafeed and pet food compounders substitute single-cell proteins for marine ingredients. Norwegian salmon producers and US pet food superbrands drive procurement volume through direct offtake agreements.
- Food Industry:Processed food manufacturers integrate torula-derived ingredients for protein fortification and flavor modulation. Clean-label positioning requirements accelerate adoption in premium product lines.
- Pharmaceuticals:Cell culture media and fermentation feedstock applications demand pharmaceutical-grade biomass. Suppliers must document strain lineage and absence of adventitious agents.
- Bakery:Artisan and industrial bakeries utilize torula yeast for dough conditioning and flavor enhancement. European clean-label mandates particularly favor nucleotide-rich extracts.
Animal nutrition absorbs the largest volume; food industry applications are climbing the fastest.
Application:
Functional role determines pricing architecture, with preservation applications commanding stability premiums over commodity feed uses.
- Flavor Enhancer:Nucleotide concentrates replace hydrolyzed vegetable proteins and synthetic additives. German industrial bakeries lead reformulation activity under EU clean-label pressures.
- Animal Feed Ingredient:Single-cell protein addresses fishmeal supply volatility in aquaculture. ASC certification requirements in Norway and Chile accelerate substitution timelines.
- Nutritional Supplement:High-protein biomass fortifies sports nutrition and senior nutrition products. Asian markets show strongest demand concentration for powder and capsule formats.
- Food Preservative:Natural antimicrobial peptides extend shelf life in clean-label applications. Preservation functionality remains underdeveloped relative to flavor and nutrition segments.
Animal feed ingredient moves the highest tonnage; flavor enhancer applications show steepest expansion trajectory.
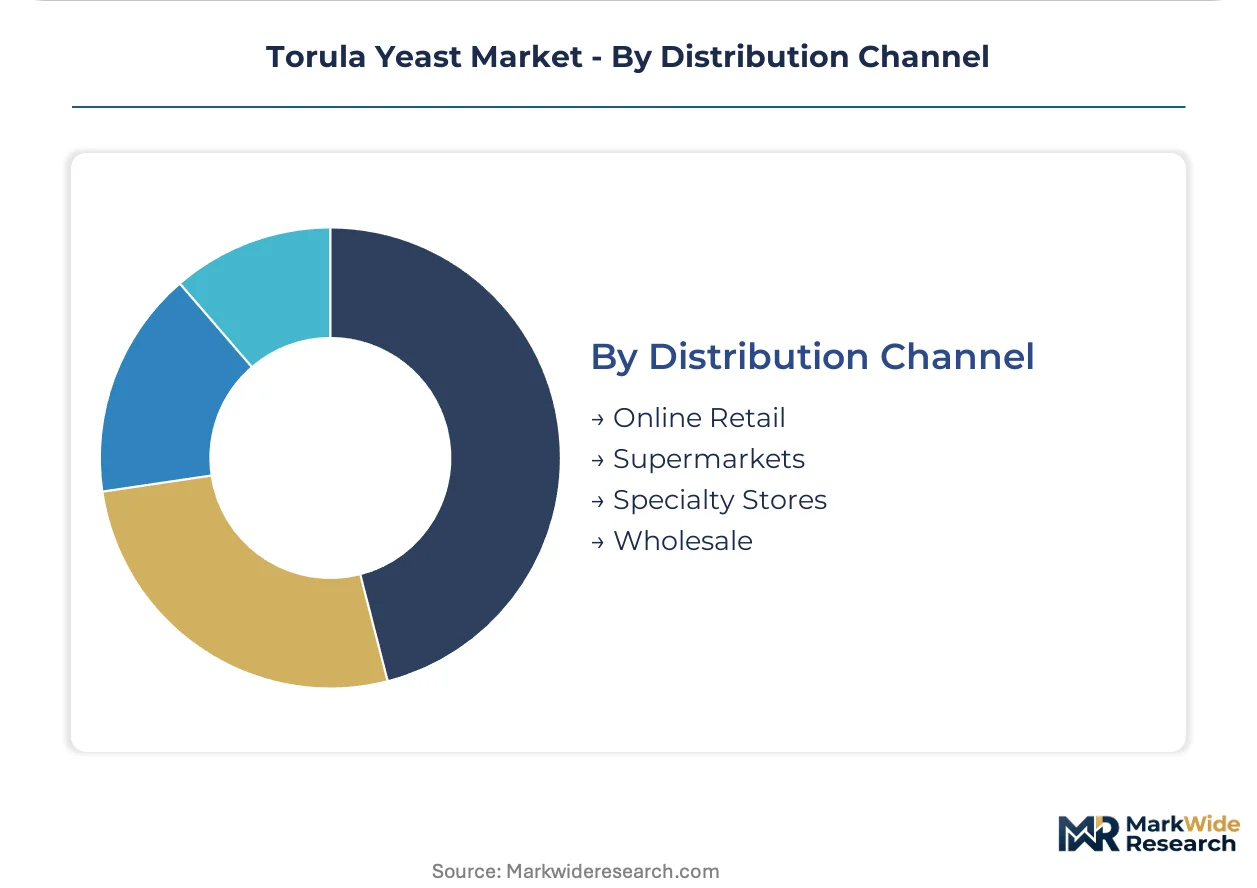
Distribution Channel:
Channel selection reflects buyer scale, technical support requirements, and traceability documentation needs.
- Wholesale:Bulk procurement by compound feed manufacturers and industrial food processors. Direct relationships with fermentation operators are displacing traditional distributor networks.
- Online Retail:E-commerce platforms serve small-scale food manufacturers and specialty pet food startups. Digital channels enable rapid sampling and technical documentation access.
- Specialty Stores:Health food retailers stock organic-certified torula yeast for human nutrition. USDA organic certification commands 40-60% price premiums in these channels.
- Supermarkets:Mass retail distribution remains limited to consumer-packaged yeast products. Private label expansion could reshape this channel.
Wholesale channels handle the majority of throughput; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German torula yeast exports supply industrial bakeries across France and the Netherlands, while Scandinavian producers ship biomass to Norwegian aquafeed compounders. Trade corridors link wood-sugar fermentation clusters to protein-deficient buyer geographies.
Germany
Industrial bakeries in Lower Saxony and Bavaria drive extract demand for clean-label reformulation. The EU F-Gas Regulation accelerates fermentation facility upgrades toward lower-carbon protein inputs. Berlin-Brandenburg hosts pilot-scale precision fermentation operations serving pharmaceutical-grade biomass requirements.
United States
Pet food superbrands in the Midwest source torula yeast directly through multi-year offtake agreements. FDA GRAS status and USDA organic certification govern human food applications, elevating compliance costs for new entrants. Wisconsin and Minnesota fermentation facilities supply powder formats to nutritional supplement distributors.
Norway
Salmon producers substitute fishmeal with single-cell proteins to meet ASC certification requirements. The country's national food safety authority enforces strict traceability protocols for aquafeed ingredients. Bergen and Trondheim anchor processing clusters where torula yeast integrates into marine protein replacement formulations.
China
Angel Yeast Co. Ltd. extends powder and flake distribution across Asian nutritional supplement channels. NMPA and GB standards regulate yeast-derived food additives with increasing stringency. Hubei province concentrates submerged fermentation capacity serving both domestic and export markets.
France
Lesaffre Group anchors European production through integrated fermentation facilities sustaining cost advantages in yeast extract manufacturing. ANSM oversees novel food ingredient assessments with timelines extending 18-24 months. The Grand Est region hosts downstream processing operations supplying industrial food manufacturers.
Torula Yeast Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Consolidation concentrates among North American and European suppliers with proprietary strain libraries, while Asian manufacturers compete aggressively on powder and flake formats. Three archetypes dominate: integrated fermentation operators with captive feedstock access, precision fermentation technology licensors, and contract biomass manufacturers serving private-label brands. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure carbon-accounting credentials for preferred procurement status.
Among the integrated fermentation operators, Lallemand Inc., Lesaffre Group, and Angel Yeast Co. Ltd. occupy positions representing distinct geographic and format specializations. Lallemand exemplifies the North American channel-control archetype through proprietary strain development. Lesaffre anchors European supply with integrated manufacturing infrastructure. Angel Yeast represents the Asian scale-driven specialist competing across powder and nutritional supplement segments.
| Leading Market Players |
|---|
| Lallemand Inc. |
| Oriental Yeast Co. Ltd. |
| Lesaffre Group |
| Archer Daniels Midland Company |
| Alltech Inc. |
| Associated British Foods plc |
| Chr. Hansen A/S |
| Angel Yeast Co. Ltd. |
| Koninklijke DSM N.V. |
| Others |
Supply Flow & Price Mechanics
Molasses price volatility determines both the spread between commodity and pharmaceutical-grade torula yeast pricing tiers and the geographic clustering of fermentation capacity near cane and beet processing zones. Buyers face contract renegotiation cycles that compress margin predictability across the value chain.
Pricing Analysis
Batch fermentation versus continuous culture systems creates a technology-generation pricing gap that separates legacy operators from precision fermentation adopters. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with USDA organic certification commanding substantial premiums. Pricing pressure stems from soy protein isolate substitution in mass-market feed applications. Animal nutrition compounders show highest price sensitivity; pharmaceutical-grade buyers demonstrate lowest elasticity due to documentation requirements.
Supply Chain Analysis
Extended payment terms from pet food superbrands reshape supplier financing structures across North American biomass producers. Supply concentrates in Germany, the United States, and China, with each hub drawing from distinct feedstock bases. Raw material dependencies center on wood-derived sugars, cane molasses, and agricultural residues. Single-source vulnerability runs through proprietary Candida utilis strain libraries held by three dominant suppliers. Distribution runs through direct procurement relationships that displace traditional ingredient distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation scale-up constitutes a high-growth disruption, with EU F-Gas Regulation mandates accelerating capital reallocation toward bio-based protein platforms.
For Market Incumbents: Harden proprietary strain IP through accelerated patent filings in high-yield phenotypes to defend against emerging precision fermentation specialists. Expand captive feedstock access via backward integration into Scandinavian wood-sugar platforms. This consolidates cost advantages against soy and pea isolate competitors. For New Entrants and Emerging Players: Pursue USDA organic certification pathways in human nutrition channels where price premiums support margin expansion. Target Asian nutritional supplement markets for powder format penetration. Establish direct technical support relationships with industrial bakeries seeking clean-label reformulation assistance. For Investors and Strategic Acquirers: EFSA Novel Food dossier timelines reshape the acquisition landscape by delaying revenue recognition for innovative torula-derived ingredients. Five-to-ten year viability hinges on carbon-accounting credentials securing preferred procurement status. Acquire contract biomass manufacturers with perfusion capabilities. Watch for ASC certification requirement expansion in aquaculture as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Continuous culture systems triple volumetric productivity for pet food biomass contracts. |
| Backward Integration into Feedstock | Scandinavian wood-sugar platforms unlock cost advantages against legacy molasses dependence. |
| USDA Organic Certification Investment | Certified biomass commands premium positioning in human nutrition distribution channels. |
| Direct Procurement Agreements | Mars Petcare and Nestlé Purina offtake contracts specify carbon intensity thresholds. |
| EFSA Safety Dossier Front-Loading | Early toxicology packages secure Article 95 listing ahead of competitor submissions. |
Methodological Framework
The analysis maps yeast extract, torula yeast powder, natural torula yeast, and torula yeast flakes segments, each validated through fermentation facility operators, pet food formulation executives, industrial bakery procurement managers, and pharmaceutical-grade biomass buyers. Primary interviews combined with secondary validation from FDA GRAS filings, EFSA Novel Food registers, ECHA REACH guidance updates, and USDA organic certification databases. Bottom-up capacity modeling and top-down demand triangulation cross-verify volume estimates.
Assumptions held fixed include current regulatory pathway timelines and prevailing feedstock cost structures, while strain yield improvements and carbon pricing mechanisms varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, end user, application, and distribution channel alongside regional production hub clustering. CAGRs derived from regression analysis against protein substitution elasticity and clean-label reformulation intensity.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity cycles, energy input costs, or trade tariff regimes would shift the trajectory. Forecasts reflect documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
United Kingdom Protein Market
Ingredients
Food Grade Hydrolyzed Casein Market
Ingredients
Global Personal Care Active Ingredients Market
Ingredients
Potato Fiber Market
Ingredients
South America Phytosterols Market
Ingredients
Sweet Almond Oil Market
Ingredients
Global Fresh Compressed Yeast Market
Ingredients
Citrus Fiber Market
Ingredients
Cocoa Powder Market
Ingredients
Caramel Ingredient Market
Ingredients
Animal-Derived Ingredients Market
Ingredients
Grapeseed Oil Market
Ingredients
Industrial Sugar Market
Ingredients
Plant Based Premix Market
Ingredients
Tannin Market
Ingredients
North America Whey Protein Ingredients Market