
 North America and Europe Coconut Derivatives Market | 2026-2036
North America and Europe Coconut Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Europe Coconut Derivatives Market Analytics
Asset-light contract manufacturing and third-party toll processing is reconfiguring capital deployment across the coconut derivatives supply chain. Vita Coco leverages direct-to-consumer channel control to sustain premium positioning in North American retail. Cargill anchors its competitive stance through backward integration into tropical sourcing networks. Barry Callebaut Group differentiates via specialized lipid fractionation capabilities for confectionery applications.
Coconut derivatives encompass refined and virgin oils, aqueous extracts, dehydrated flesh, and concentrated emulsions extracted from Cocos nucifera endosperm, typically containing 60-70% medium-chain triglycerides by oil weight and serving as functional ingredients across food, cosmetic, and energy applications. Coconut oil leads product-type revenue pools due to its ubiquity in frying, baking, and personal care formulations, while coconut milk posts the fastest application growth as barista-style beverages and dairy-free cooking bases expand shelf space. Nutraceuticals command margin premiums where MCT oil purity grades support ketogenic and sports nutrition positioning.
EMA food-contact guidelines, FDA GRAS determinations, and REACH chemical safety registrations collectively govern ingredient purity thresholds and label claims across the transatlantic trade corridor. These frameworks elevate compliance costs for smaller importers while creating certification barriers that favor established suppliers with dedicated regulatory affairs teams. Stakeholders must monitor evolving EU deforestation-free supply chain mandates and emerging state-level clean-label statutes in the United States to anticipate sourcing and documentation requirements.
Market Dynamics
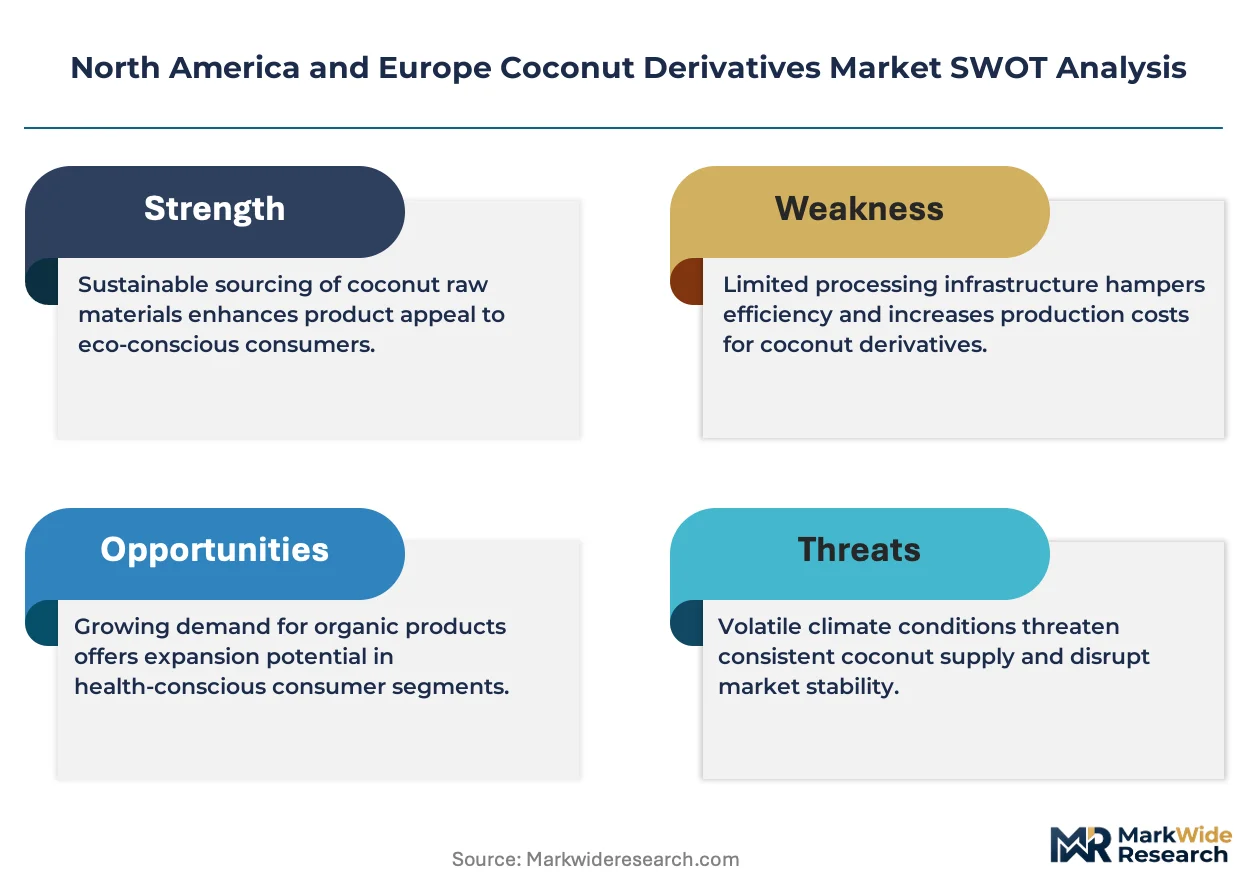
Clean-label procurement mandates from European retailers and US foodservice distributors are compressing formulation timelines while fragmenting supplier qualification pools across the transatlantic corridor.
Growth Catalysts
- Plant-based dairy substitution:Barista-format coconut milk demand from specialty coffee chains in Germany and the United States is pulling volume through foodservice procurement channels.
- REACH chemical safety registrations:ECHA compliance requirements for cosmetic-grade MCT oils are creating certification premiums that reward suppliers with dedicated regulatory affairs infrastructure.
- Ketogenic nutrition positioning:Sports nutrition formulators in the United States are specifying 95%+ purity MCT oil grades for powdered drink mixes and gel formats.
Market Restraints
- Raw material concentration:Crude coconut oil supply concentrates in Southeast Asian crushing facilities, exposing processors to freight rate volatility and port congestion at Rotterdam and Long Beach.
- Input cost volatility:Copra prices fluctuate with Philippine and Indonesian weather patterns, compressing margin predictability for European refiners operating on quarterly contracts.
- Substitution threat:Oat milk and pea protein isolates are displacing coconut derivatives in mid-tier dairy alternatives where cost sensitivity outweighs premium positioning.
Strategic Opportunities
- Underpenetrated geography:Eastern European markets including Poland and Romania show nascent clean-label adoption where coconut cream and milk powder formats can establish first-mover shelf presence.
- Regulatory tailwind:EU deforestation-free supply chain mandates scheduled for phased implementation create documentation barriers that favor established suppliers with traceable tropical sourcing networks.
- Emerging application:Solid lipid nanoparticle formulations in dermocosmetics are opening technical specifications for fractionated coconut waxes in French and German skincare manufacturing.
Industry Challenges
- Certification timeline compression:FDA GRAS self-affirmation pathways for novel coconut protein isolates require 18-24 month toxicology studies that delay product launch windows.
- Skill scarcity in lipid analytics:European refiners face recruitment gaps for gas chromatography specialists capable of validating MCT chain-length distribution per EFSA specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Europe Coconut Derivatives Market |
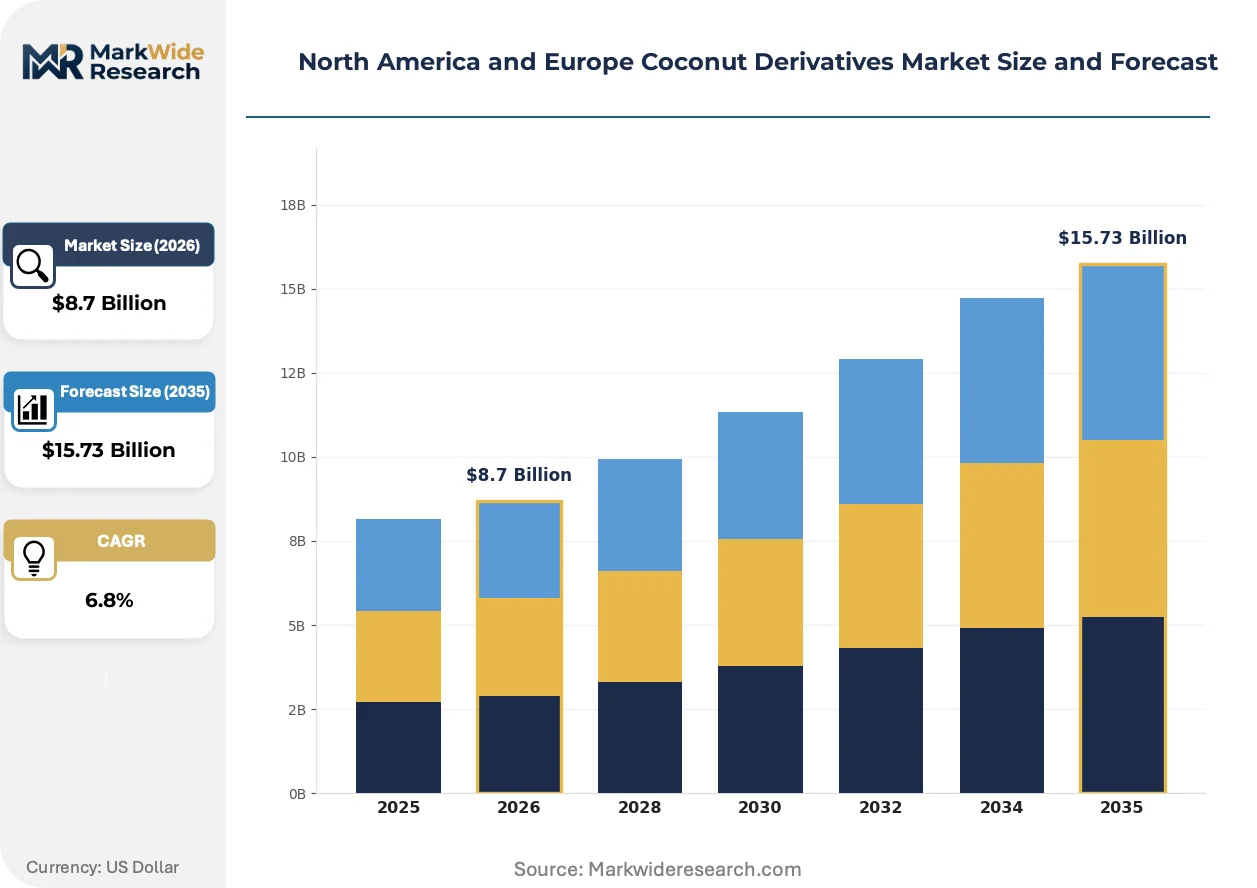
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut Oil, Coconut Milk, Desiccated Coconut, Coconut Cream Application: Food & Beverage, Cosmetics, Nutraceuticals, Biofuels End User: Food Manufacturers, Personal Care Brands, Health Product Retailers, Fuel Producers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Distributors |
| Companies Covered | Danone S.A., Celebes Coconut Corporation, Vita Coco, Barry Callebaut Group, Cargill, McCormick & Company, Axelum Resources, Fresh, Hain Celestial, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Europe Coconut Derivatives Market Evolving Landscape
Processing technology convergence and regulatory documentation requirements are elevating capital barriers while creating tiered competitive positions based on analytical capabilities and tropical sourcing control.
Cold-pressed virgin coconut oil extraction is hybridizing with supercritical CO2 fractionation to yield customized triglyceride profiles for pharmaceutical and nutraceutical applications. German and Dutch specialty oil processors are adopting these hybrid systems to serve contract manufacturing demand from sports nutrition brands. The technology is hybridizing product portfolios, enabling single facilities to switch between food-grade and cosmetic-grade outputs without dedicated production lines.
EU deforestation-free regulation (EUDR) due diligence obligations are reshaping documentation requirements for coconut kernel imports into Rotterdam and Hamburg. Operators must now maintain geolocation data and supplier risk assessments for every plantation source. Small-scale importers without dedicated compliance teams are exiting the market, consolidating procurement leverage among integrated processors with captive Southeast Asian supply bases.
Foodservice distributors in the United States are consolidating coconut milk and cream specifications under private-label programs that displace branded ingredient suppliers. National broadline distributors including Sysco and US Foods are specifying aseptic carton formats with extended ambient shelf life for their own-label barista products. This concentration is most visible in the Northeast and California markets where specialty coffee chain density supports volume commitments.
North America and Europe Coconut Derivatives Market Segmentation
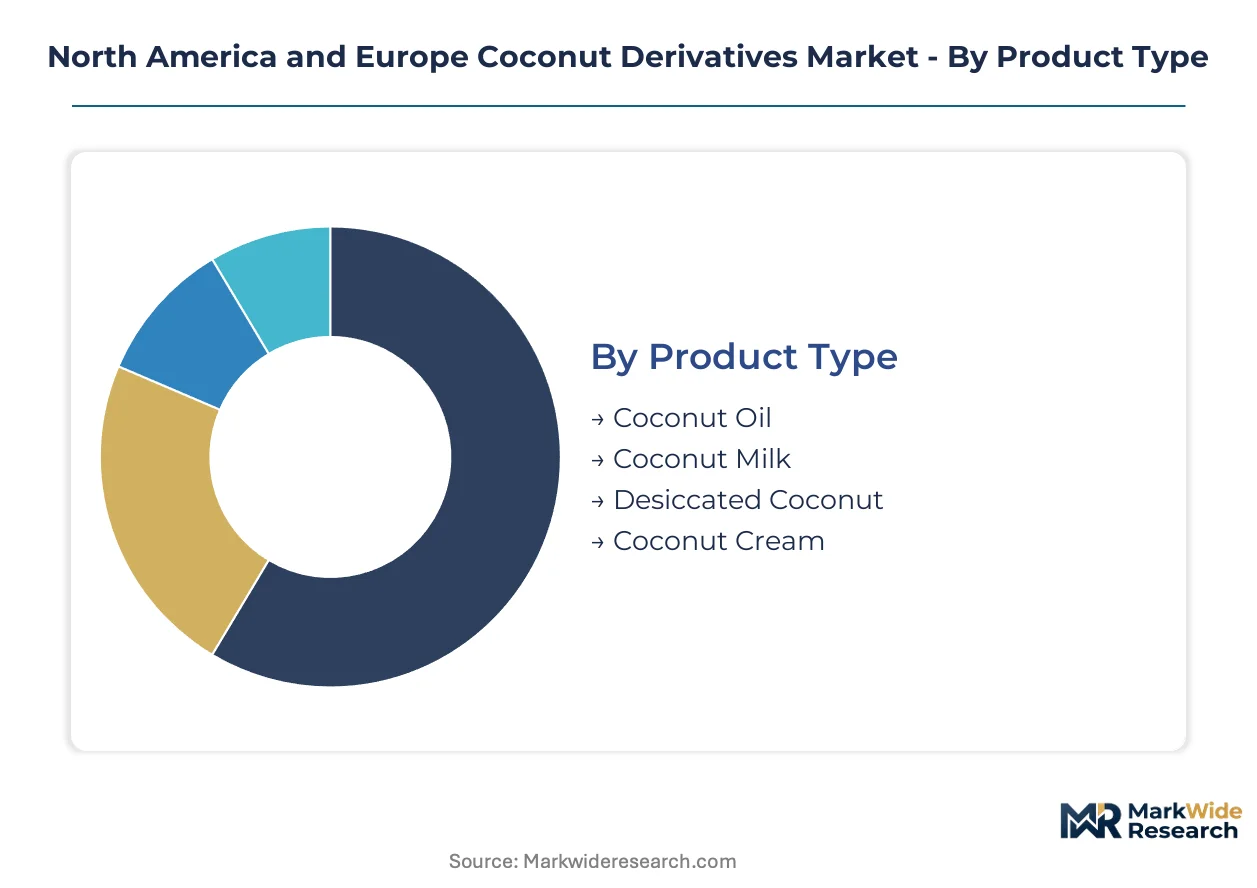
Coconut derivatives span distinct technical specifications and procurement rhythms that fragment competitive positioning across North America and Europe. Understanding segment turnover velocity and margin stratification reveals where capital deployment concentrates versus where new entrants find footholds.
Product Type:
Coconut oil commands the shortest production cycle from copra crushing to refined output, while fractionated MCT oils extend lead times through multi-stage molecular distillation. Virgin and cold-pressed grades introduce agricultural seasonality that compresses procurement windows for European refiners.
- Coconut Oil:Refined and virgin grades contain 60-70% medium-chain triglycerides by weight, serving frying, baking, and personal care formulation. German and US food manufacturers specify high-lauric acid variants for shelf-stable baked goods, though Philippine weather volatility disrupts quarterly contract pricing.
- Coconut Milk:Aqueous emulsions with 15-25% fat content anchor barista-format beverage demand from specialty coffee chains in Berlin and Los Angeles. Aseptic carton specifications with 12-month ambient stability are displacing canned formats in US foodservice procurement.
- Desiccated Coconut:Dehydrated endosperm flakes at 3% maximum moisture content supply industrial confectionery and bakery applications.
- Coconut Cream:Concentrated emulsions above 24% fat content target premium cooking bases and dairy-free dessert manufacturing in France and the United Kingdom.
Coconut oil anchors the volume base while coconut milk gains share at the steepest rate.
Application:
Margin tiers stratify sharply across applications, with pharmaceutical-grade MCT oils capturing certification premiums that commodity food oils cannot approach. REACH registration requirements for cosmetic applications create documentation barriers that favor established European processors over import traders.
- Food & Beverage:Plant-based dairy alternatives in Germany and the United States drive specification intensity for neutral-flavor coconut milks with protein stability under thermal processing. Clean-label mandates from retailers like Whole Foods and Edeka compress supplier qualification timelines.
- Cosmetics:Fractionated triglycerides serve emollient and carrier functions in dermocosmetic formulations, with French and German skincare manufacturers specifying caprylic-capric acid ratios per ECHA cosmetic ingredient guidelines.
- Nutraceuticals:95%+ purity MCT oil grades support ketogenic positioning in US sports nutrition powders and gels.
- Biofuels:Crude coconut oil feedstock for biodiesel transesterification faces competition from waste cooking oil collection in European renewable fuel mandates.
Food and beverage commands the revenue base while nutraceuticals expand most quickly on per-kilogram margin premiums.
End User:
Procurement sophistication varies dramatically across end-user categories, with multinational food manufacturers imposing traceability requirements that small health product retailers cannot operationalize. EUDR compliance deadlines are accelerating supplier consolidation toward integrated processors with captive Southeast Asian sourcing.
- Food Manufacturers:Industrial-scale buyers in the US Midwest and German Rhine-Ruhr corridor specify 20-tonne minimum order quantities with documented deforestation-free geolocation data per phased EU regulation.
- Personal Care Brands:Cosmetic houses in Paris and Hamburg demand certificate-of-analysis documentation for every lot, with gas chromatography validation of fatty acid distribution.
- Health Product Retailers:Direct-to-consumer brands and specialty supplement shops source smaller volumes with emphasis on organic and fair-trade certification marks.
- Fuel Producers:Renewable diesel refiners in the Netherlands and California evaluate coconut oil against tallow and used cooking oil on carbon intensity scoring under respective state and national fuel standards.
Food manufacturers dominate procurement volume while personal care brands drive specification complexity fastest.
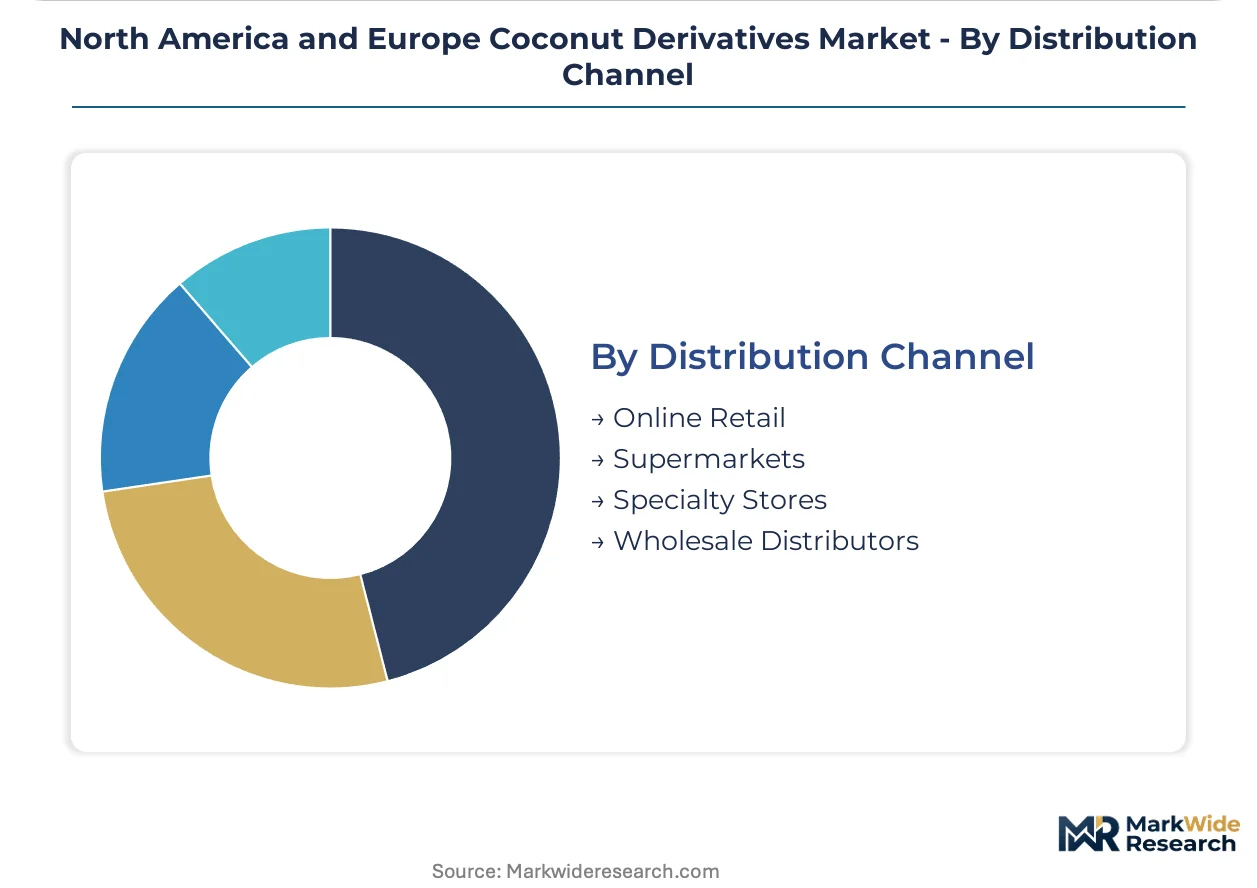
Distribution Channel:
Channel economics reflect handling requirements and shelf-life constraints that fragment logistics infrastructure. Ambient-stable formats enable mass retail penetration, while refrigerated and frozen grades concentrate in foodservice and specialty routes.
- Online Retail:Direct-to-consumer platforms capture premium virgin coconut oil and specialty MCT oil formats, with subscription models building recurring revenue for US-based wellness brands.
- Supermarkets:Mass retail chains in the United States and Germany consolidate shelf space under private-label coconut milk programs, displacing branded suppliers in the barista segment.
- Specialty Stores:Organic and natural product retailers stock cold-pressed and extra-virgin grades with origin storytelling for discerning household purchasers.
- Wholesale Distributors:Broadline foodservice operators including Sysco and US Foods specify aseptic coconut cream and milk for their own-label barista products in high-density specialty coffee markets.
Wholesale distributors anchor institutional volume while online retail climbs the fastest on premium-format traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU deforestation-free regulation mandates and FDA food-labeling standards in the United States are reshaping procurement documentation requirements across the transatlantic corridor. Germany and the United States concentrate clean-label ingredient demand as retailers intensify supplier qualification protocols.
United States
Specialty coffee chains in Los Angeles and New York Metro drive barista-format coconut milk procurement through foodservice channels. FDA GRAS self-affirmation pathways for novel protein isolates impose 18-24 month toxicology timelines that delay product launches. Midwest food manufacturers in Illinois and Ohio specify 20-tonne minimum orders with traceability documentation.
Germany
Berlin and Hamburg anchor European demand for neutral-flavor coconut milks with protein stability under thermal processing. REACH chemical safety registrations for cosmetic-grade MCT oils create certification premiums rewarding suppliers with dedicated regulatory affairs teams. The Rhine-Ruhr corridor hosts industrial-scale buyers imposing documented deforestation-free geolocation data requirements.
France
Paris-based cosmetic houses demand certificate-of-analysis documentation with gas chromatography validation of fatty acid distribution per ECHA guidelines. EMA food-contact guidelines govern ingredient purity thresholds for dermocosmetic formulations. The Provence-Alpes-Côte d'Azur region shows nascent solid lipid nanoparticle demand for fractionated coconut waxes in skincare manufacturing.
United Kingdom
London and Southeast England concentrate premium cooking base demand for coconut cream in dairy-free dessert manufacturing. Retailers like Whole Foods compress supplier qualification timelines through clean-label procurement mandates. The Midlands hosts confectionery manufacturers specifying high-lauric acid coconut oil variants for shelf-stable baked goods.
Netherlands
Rotterdam and Amsterdam serve as primary European entry points for Southeast Asian coconut kernel imports facing EUDR due diligence obligations. Dutch specialty oil processors adopt hybrid cold-pressed and supercritical CO2 fractionation systems for pharmaceutical and nutraceutical applications. Renewable diesel refiners evaluate coconut oil against tallow and used cooking oil on carbon intensity scoring.
North America and Europe Coconut Derivatives Market Competitive Landscape
On the supply side, the industry is consolidating around integrated processors with captive Southeast Asian sourcing networks and dedicated regulatory compliance infrastructure. The vendor base separates into three archetypes: multinational agribusiness conglomerates with backward integration into tropical crushing facilities, mid-cap specialty oil processors with fractionation capabilities, and direct-to-consumer wellness brands controlling premium retail channels. Dominant competitive moves include strategic partnerships for EUDR-compliant documentation and capacity expansion in hybrid extraction systems serving contract manufacturing demand.
Among the named participants, Cargill exemplifies the agribusiness archetype through upstream control over sourcing networks. Barry Callebaut Group occupies a position representing specialized lipid fractionation capabilities for confectionery applications. Vita Coco anchors the direct-to-consumer vector with channel control sustaining premium retail positioning in North American markets.
| Leading Market Players |
|---|
| Danone S.A. |
| Celebes Coconut Corporation |
| Vita Coco |
| Barry Callebaut Group |
| Cargill |
| McCormick & Company |
| Axelum Resources |
| Fresh |
| Hain Celestial |
| Others |
Value Network & Pricing Analysis
Undercapacity in Philippine and Indonesian copra crushing facilities during monsoon-disrupted harvest cycles amplifies spot-price volatility for European refiners, compressing their ability to negotiate quarterly contract terms while forcing US food manufacturers toward longer offtake commitments with integrated processors.
Pricing Analysis
Certification level creates the primary spread between commodity and premium tiers, with REACH-registered cosmetic-grade MCT oils commanding substantial premiums over food-grade refined oils. Three-tier pricing structure across pharmaceutical, food-grade, and industrial feedstock levels stratifies the market, though cost compression in mid-tier coconut milk concentrates is intensifying because oat milk alternatives are displacing volume in price-sensitive barista applications. Industrial food manufacturers exhibit highest price sensitivity, while French and German dermocosmetic houses prioritize certificate-of-analysis reliability over unit cost.
Supply Chain Analysis
Freight rate volatility between Southeast Asian crushing facilities and Rotterdam port congestion dominates operational risk planning for European processors. Raw material supply concentrates in the Philippines, Indonesia, and Sri Lanka, with copra meal and crude coconut oil drawing from tropical plantation networks. Single-source vulnerability intensifies as EUDR documentation requirements force smaller traders to exit, consolidating procurement leverage among integrated processors. Distribution runs through Rotterdam and Hamburg entry points for European refining, with US Midwest manufacturers receiving containerized shipments through Long Beach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label procurement mandates from German retailers and US foodservice distributors are fragmenting supplier qualification pools, creating specialized niches for processors with dedicated regulatory affairs infrastructure and traceable tropical sourcing networks.
For Market Incumbents: Entrench competitive position through backward integration into captive Southeast Asian crushing capacity and accelerated EUDR compliance documentation investment. Oat milk substitution in mid-tier dairy alternatives threatens volume-based margin pools, requiring incumbents to deepen certification premiums in pharmaceutical-grade MCT oils and barista-format coconut milk specifications where brand loyalty persists. For New Entrants and Emerging Players: Establish a beachhead in Eastern European markets including Poland and Romania where clean-label adoption remains nascent and first-mover shelf presence is achievable. Solid lipid nanoparticle formulations in French skincare manufacturing represent the most penetrable technical specification gap, with contract manufacturing partnerships offering the lowest capital-intensity entry path. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid extraction systems serving pharmaceutical and nutraceutical contract manufacturing demand. Long-term viability over the coming decade rests on acquiring processors with demonstrated ECHA registration capabilities and geolocation-verified supply bases. The signal to monitor is EU deforestation-free regulation enforcement intensity at Rotterdam customs checkpoints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tropical Sourcing | Cargill's captive Philippine and Indonesian networks insulate margin predictability from copra price volatility. |
| Hybrid Extraction System Deployment | German and Dutch processors leverage cold-pressed and supercritical CO2 convergence to serve contract manufacturing demand. |
| EUDR Compliance Documentation Investment | Geolocation data maintenance and supplier risk assessment capabilities consolidate procurement leverage among established operators. |
| Direct-to-Consumer Channel Control | Vita Coco's retail positioning sustains premium pricing power in North American virgin coconut oil segments. |
| Fractionation Capability Expansion | Barry Callebaut's specialized lipid fractionation serves confectionery applications with customized triglyceride profiles. |
Research Methodology
Desk research of trade flow databases, ECHA registration filings, and FDA GRAS determination records preceded structured interviews with specialty oil processors, cosmetic house procurement directors, and foodservice distribution category managers. Primary fieldwork with coconut crushing facility operators in Southeast Asia and European refinery technical directors was cross-validated against customs data and industry association publications. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Assumptions regarding REACH enforcement intensity, EUDR phased implementation timelines, and specialty coffee chain expansion trajectories were held fixed across scenarios while copra yield volatility and freight rate fluctuations were stress-tested. Segmentation dimensions included product type, application vertical, end-user procurement sophistication, and distribution channel format. CAGRs were derived from trend extrapolation validated against historical volume elasticities, with ketogenic nutrition positioning and barista-format beverage adoption serving as key demand-side forecast inputs.
Stress conditions across Philippine weather pattern severity, Rotterdam port congestion frequency, and oat milk substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions, with regulatory enforcement intensity and alternative protein technology cost curves representing primary revision risks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Marine Peptides Market
Ingredients
European Brewing Enzymes Market
Ingredients
Cosmetic Bioactive Ingredients Market
Ingredients
Tapioca Pearls Market
Ingredients
Global Dietary Fibers Market
Ingredients
Prenatal Vitamin Ingredients Market
Ingredients
Immunity Support Ingredients Market
Ingredients
Baobab Ingredient Market
Ingredients
Marine Protein Market
Ingredients
Cocoa Butter Market
Ingredients
Hops Market
Ingredients
Vegetable Glycerin Market
Ingredients
Pet Food Ingredients Market
Ingredients
Jojoba Oil Market
Ingredients
South America Protein Market
Ingredients
Glucomannan Market