
 Resistant Starch Market | 2026-2036
Resistant Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Resistant Starch Market Analysis
North American ingredient processors is pivoting toward high-amylose corn and potato-derived resistant starch capacity to serve reformulation demand from major food brands. Ingredion Incorporated leverages its vertically integrated corn wet milling network to secure consistent raw material flows for resistant starch output. Cargill sustains broad geographic coverage through its global grain origination platform, which anchors supply security across multiple continents. Tate & Lyle differentiates via specialty carbohydrate expertise, particularly in heat-stable variants for industrial baking conditions.
Resistant starch comprises starch fractions that resist enzymatic digestion in the small intestine, functioning as fermentable dietary fiber with measurable impacts on glycemic response and gut microbiota composition; commercial grades typically deliver 40-60% total dietary fiber on a dry basis, with amylose content and crystalline structure determining resistance to alpha-amylase hydrolysis. Modified starch variants command premium positioning due to tailored functionality in extruded snacks and retort applications, while native starch segments compete on cost in simpler bakery systems. The dairy application channel is gaining traction as yogurt and beverage manufacturers seek fiber fortification without viscosity disruption.
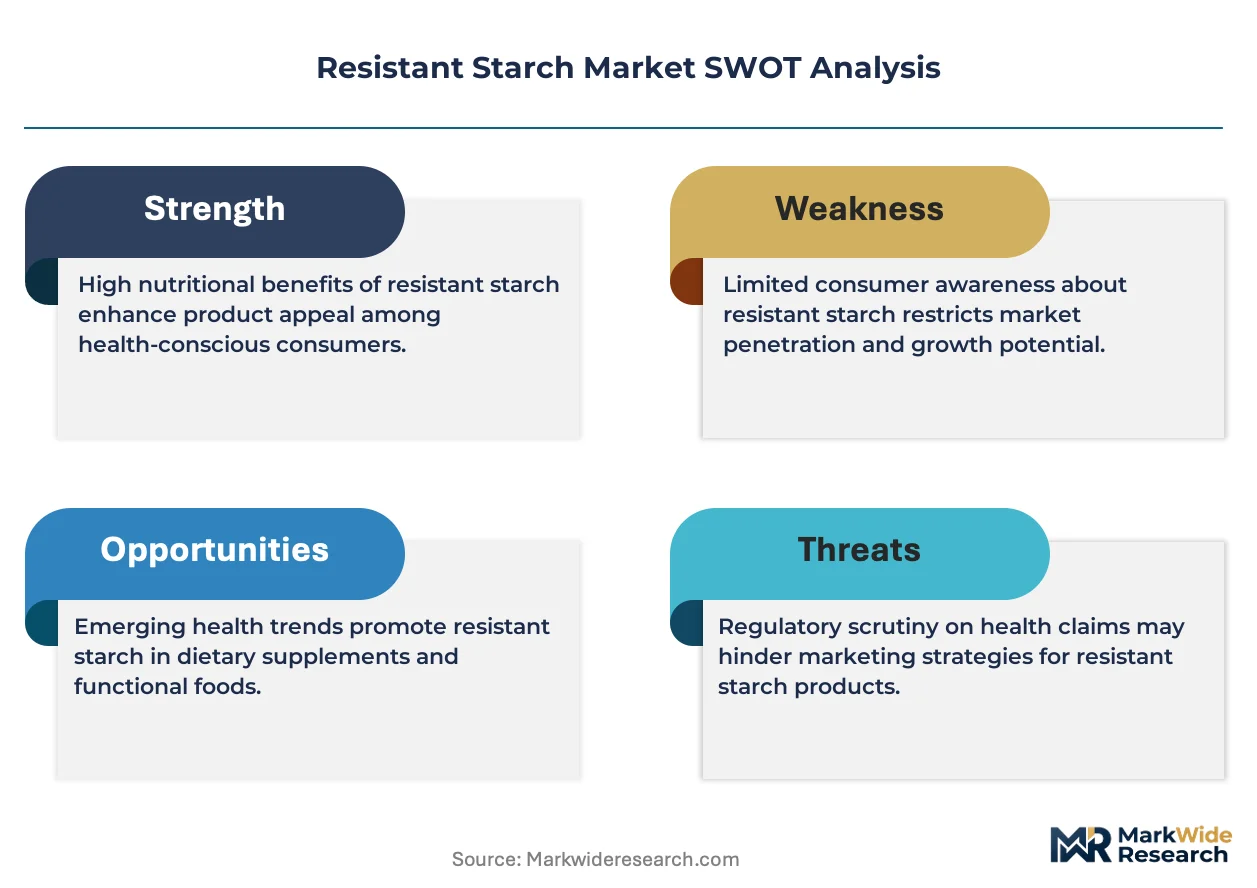
The FDA's dietary fiber definition under Nutrition Facts labeling rules shapes product positioning and health claim substantiation requirements for resistant starch suppliers targeting the US market. EFSA evaluates resistant starch health claims in Europe under strict scientific substantiation protocols, while FSSAI in India governs food additive permissions and labeling standards for imported specialty ingredients. Stakeholders must monitor evolving fiber definition harmonization between Codex Alimentarius frameworks and national regulators to anticipate reformulation timelines and claim permissibility shifts.
Market Dynamics
Clean-label reformulation mandates from major food brands are restructuring procurement patterns for resistant starch, forcing ingredient suppliers to validate fiber content through multiple regulatory pathways simultaneously.
Growth Catalysts
- FDA Dietary Fiber Definition:The FDA's updated Nutrition Facts labeling rules clarified resistant starch's status as a fermentable fiber, enabling brands to substantiate digestive health claims without reformulation.
- Heat-Stable Amylose Variants:Industrial bakers now specify high-amylose corn derivatives that withstand retort and extrusion temperatures above 120°C without fiber degradation.
- United States:American yogurt and beverage manufacturers are pulling resistant starch into fiber fortification protocols that avoid viscosity spikes in liquid matrices.
Market Restraints
- High-Amylose Corn Supply Concentration:North American wet milling capacity for specialized corn hybrids remains limited to a handful of processing corridors, creating input bottlenecks during harvest volatility.
- EFSA Substantiation Protocols:European health claim approvals require extensive human intervention studies, extending time-to-market for resistant starch suppliers targeting EU member states.
- Native Starch Cost Floor:Unmodified potato and tapioca starches compete on price in simple bakery applications where thermal stability is not required, compressing margins for functional grades.
Strategic Opportunities
- India:FSSAI's evolving food additive permissions for imported specialty ingredients create first-mover positioning for suppliers establishing local labeling compliance ahead of market maturation.
- Precision Fermentation Convergence:Microbial starch modification techniques are opening pathways to custom resistant starch structures without agricultural feedstock dependence.
- Dairy Beverage Channel:Drinkable yogurt and plant-based milk alternatives represent underexploited application space where low-viscosity fiber fortification commands formulation premiums.
Industry Challenges
- Analytical Methodology Standardization:Inconsistent alpha-amylase protocols across laboratories generate variable fiber content measurements, complicating supplier-customer specifications.
- Retrogradation Control Expertise:Food manufacturers lack in-house starch crystallization knowledge to optimize resistant starch functionality across diverse moisture and pH conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resistant Starch Market |
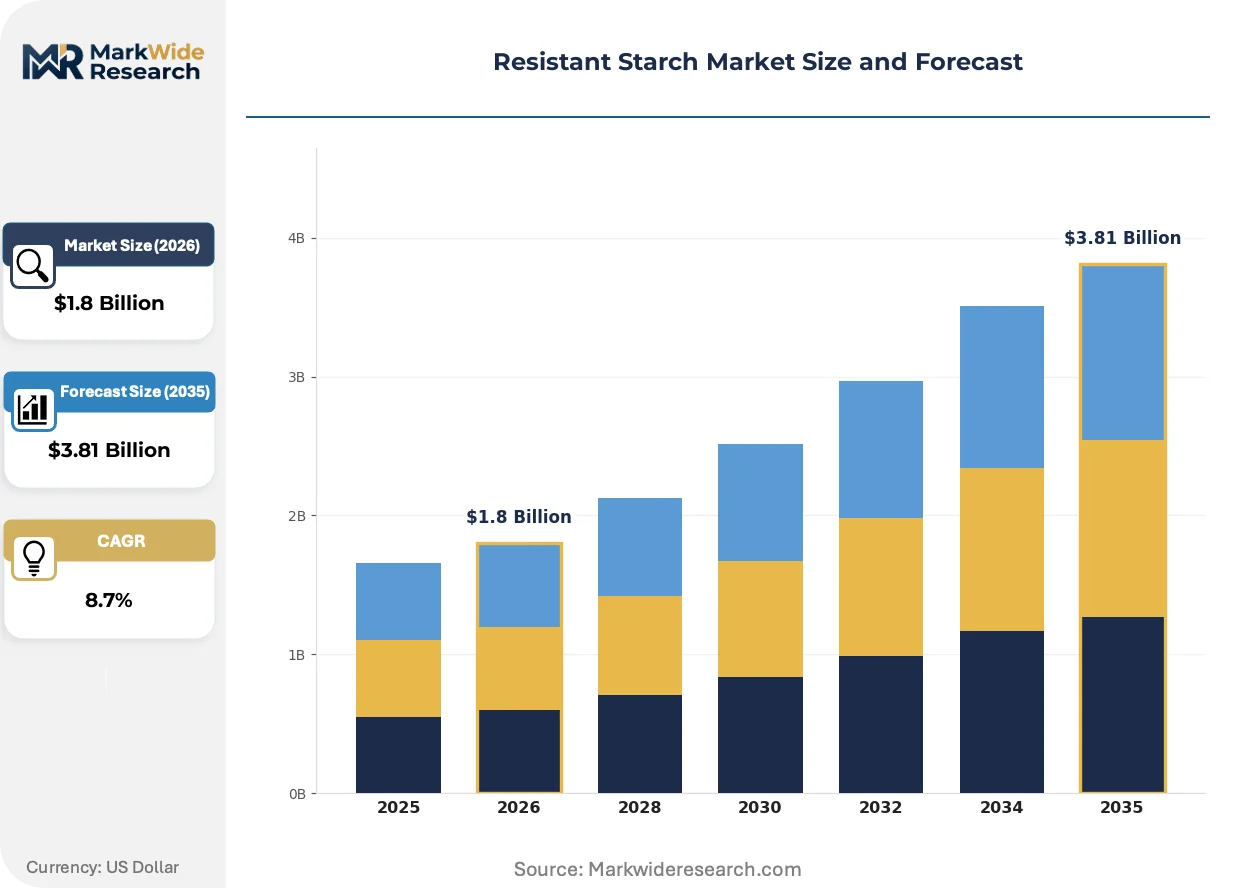
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Starch, Modified Starch, Hi-maize, Potato Starch Application: Baked Goods, Dairy Products, Snacks, Confectionery End User: Food & Beverage, Pharmaceuticals, Animal Feed, Nutraceuticals Form: Powder, Granules, Tablets, Capsules |
| Companies Covered | Ingredion Incorporated, Cargill, Tate & Lyle, ADM, Roquette Frères, MGP Ingredients, Emsland Group, SunOpta, Arcadia Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resistant Starch Market Emerging Trajectories
Novel enzymatic modification techniques are expanding the functional range of resistant starch beyond traditional thermal processing limits, enabling deployment in cold-fill beverages and fresh dairy.
Enzymatic debranching technology is decentralizing resistant starch production away from centralized wet milling complexes. Mid-scale ingredient processors in the United States and Germany are installing membrane bioreactors that convert standard starch into resistant fractions on-site. This distributed manufacturing model is compressing freight costs and enabling just-in-time fiber fortification for regional bakery cooperatives.
EFSA's tightened health claim substantiation requirements under the EU Nutrition and Health Claims Regulation are reshaping clinical trial investment patterns. Resistant starch suppliers now commission multi-center gut microbiome studies to satisfy the 2012 guidance on fiber-related claims. The dairy and bakery segments in France and Germany are most affected, with brands delaying launch timelines until EFSA positive opinions issue.
Direct procurement from ingredient technology platforms is displacing traditional distributor relationships among North American contract manufacturers. Large food brands now specify resistant starch grades through digital sourcing portals that validate certificate of analysis data against FDA fiber definitions. This channel shift is most visible in the United States, where CPG procurement teams have consolidated supplier onboarding through cloud-based quality management systems.
Resistant Starch Market Segmentation
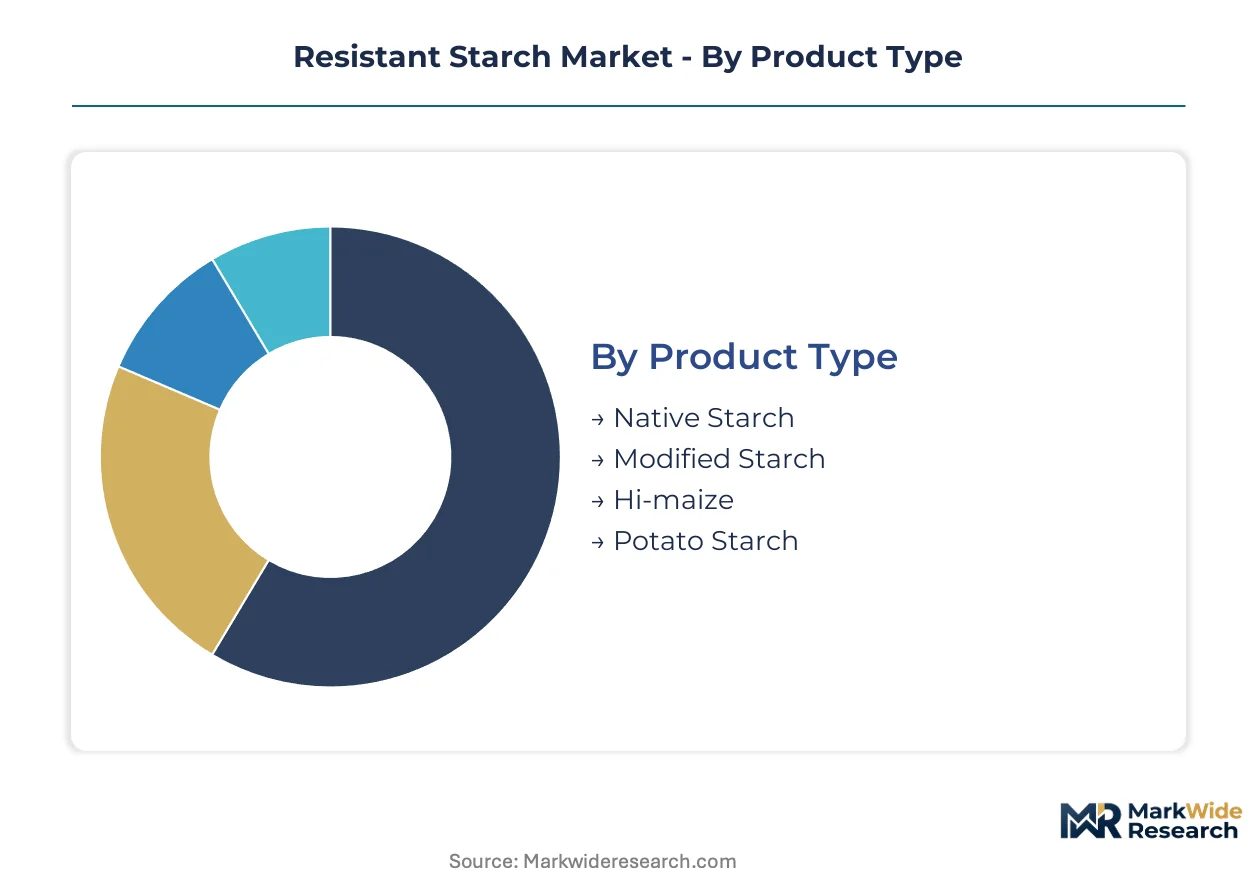
Resistant starch procurement patterns shift dramatically across product grades and application channels. Manufacturers must match thermal stability requirements to processing conditions while navigating divergent regulatory pathways for fiber content claims.
Product Type:
Upgrade cycles in resistant starch purchasing track reformulation mandates from major food brands seeking cleaner label credentials.
- Native Starch:Unmodified potato and tapioca starches deliver baseline fiber fortification at lower cost points. Bakery manufacturers in the United States specify these grades for cookies and crackers where extrusion temperatures remain below 100°C and thermal degradation risks are minimal.
- Modified Starch:Chemical or physical modification creates crystalline structures resistant to alpha-amylase hydrolysis even under severe processing. Retort pouch manufacturers and extruded snack producers pay premiums for these grades to maintain fiber content claims through high-temperature sterilization cycles.
- Hi-maize:High-amylose corn hybrids bred for elevated resistant starch content. Ingredion Incorporated controls much of the proprietary germplasm for this category.
- Potato Starch:European processors favor this source for neutral flavor profiles in dairy applications.
Volume placements concentrate in Modified Starch; the faster expansion belongs to Hi-maize.
Application:
Cost tier differentiation separates commodity fiber fortification from premium functional positioning.
- Baked Goods:Industrial bread and pastry operations specify resistant starch for dual functionality—fiber content elevation and moisture management in extended shelf-life products. The FDA's clarified dietary fiber definition enabled mainstream brands to add digestive health callouts without reformulating base recipes.
- Dairy Products:Drinkable yogurt and plant-based milk alternatives demand low-viscosity fiber solutions that suspend without gelation. Heat-stable amylose variants from high-amylose corn withstand UHT processing without precipitating or altering mouthfeel.
- Snacks:Extruded puffs and chips utilize resistant starch for texture modification and reduced glycemic index positioning.
- Confectionery:Chocolate and candy applications remain limited due to fat interference with starch hydration.
Volume placements concentrate in Baked Goods; the steepest expansion trajectory appears in Dairy Products.
End User:
Customer type determines specification stringency and certificate of analysis requirements.
- Food & Beverage:Dominant demand channel spanning CPG manufacturers, contract bakeries, and dairy processors. Procurement teams specify resistant starch grades through digital sourcing portals that validate fiber content against FDA definitions.
- Pharmaceuticals:Tablet excipient applications require pharmaceutical-grade starches with validated microbial specifications and batch documentation.
- Animal Feed:Pet food manufacturers incorporate resistant starch for digestive health claims in premium positioning.
- Nutraceuticals:Prebiotic supplement formulations represent emerging demand for clinically substantiated resistant starch structures.
Volume placements concentrate in Food & Beverage; Nutraceuticals are climbing the fastest.
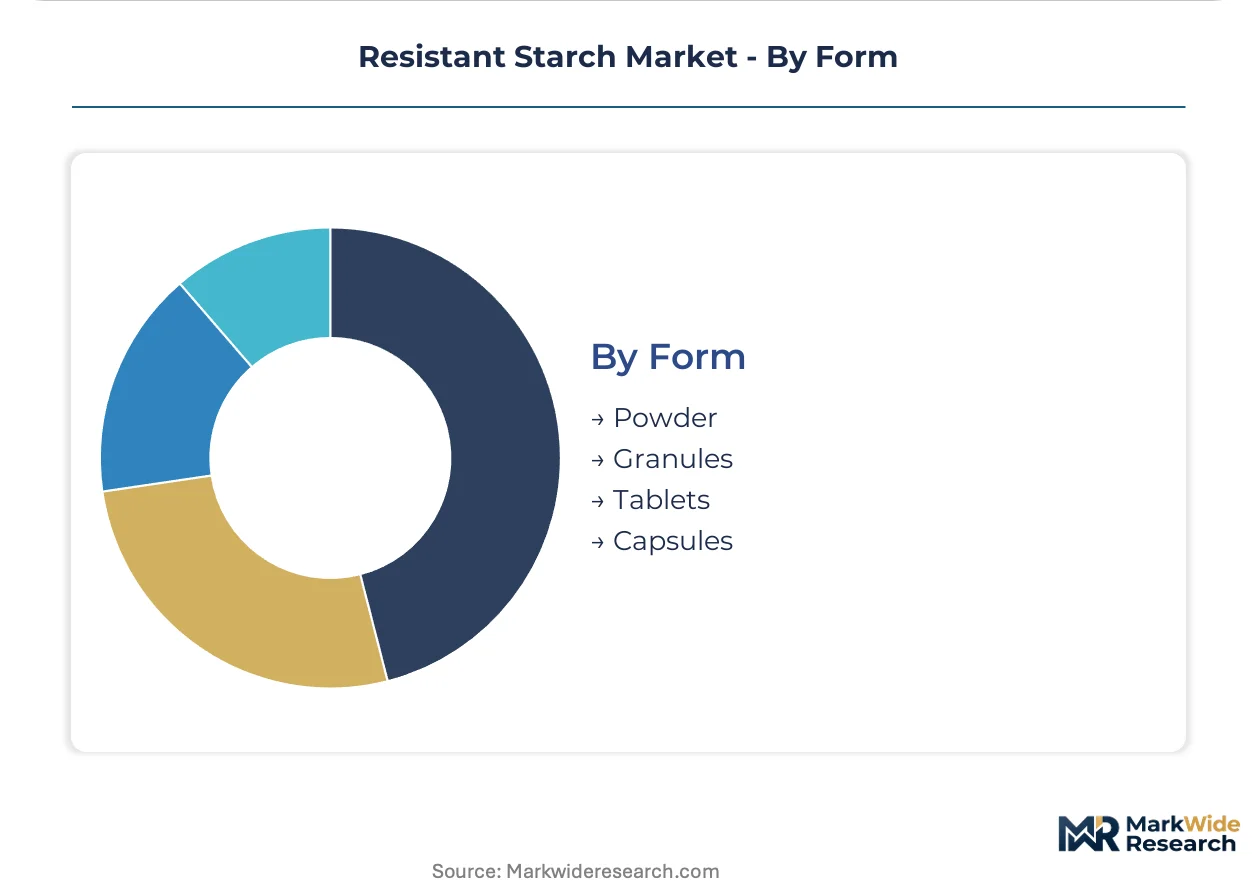
Form:
Supply concentration in powder processing creates margin pressure for alternative physical formats.
- Powder:Standard physical state for bulk ingredient handling and dry blending operations. Spray-dried and agglomerated variants optimize dispersibility in liquid systems without lump formation.
- Granules:Free-flowing forms preferred for direct compression tableting and reduced dusting during manufacturing.
- Tablets:Pre-formulated dosage units for nutraceutical and pharmaceutical channels requiring convenience positioning.
- Capsules:Encapsulated resistant starch for targeted delivery applications and consumer supplement formats.
Volume placements concentrate in Powder; the faster expansion belongs to Granules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-amylose corn hybrids from the US Midwest and specialized potato cultivars from the Netherlands and Germany anchor resistant starch feedstock flows. Processing corridors cluster near these agricultural inputs, with finished ingredient distribution extending to food manufacturing hubs.
United States
Industrial bakers and yogurt manufacturers in the Midwest and Northeast drive procurement volumes for fiber fortification. FDA's clarified dietary fiber definition under Nutrition Facts labeling enables digestive health claims without reformulation. Wet milling complexes in Iowa and Illinois concentrate high-amylose corn processing capacity for resistant starch output.
Germany
Dairy processors in Bavaria and Baden-Württemberg specify low-viscosity resistant starch grades for drinkable yogurt applications. EFSA's strict health claim substantiation protocols under EU Nutrition and Health Claims Regulation extend product launch timelines. Ingredient technology clusters around Cologne and Hamburg support enzymatic modification capabilities for regional bakery cooperatives.
India
Bakery and beverage manufacturers in Maharashtra and Gujarat explore fiber fortification as FSSAI evolves food additive permissions for imported specialty ingredients. Central government PLI scheme incentives for food processing infrastructure accelerate cold-chain investments. Mumbai-Pune industrial corridor attracts first-mover resistant starch suppliers establishing local labeling compliance.
China
Snack manufacturers in Shandong and Guangdong provinces trial resistant starch for texture modification in extruded products. SAMR's national food safety standards govern dietary fiber labeling and additive permissions. Yangtze River Delta food technology parks incubate domestic enzymatic modification capabilities to reduce import dependence.
Brazil
Pet food manufacturers in São Paulo incorporate resistant starch for premium digestive health positioning. ANVISA's food additive regulations govern import permissions for specialty carbohydrate ingredients. Campinas research clusters support cassava-derived resistant starch development leveraging local starch processing expertise.
Resistant Starch Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue precision fermentation and enzymatic modification pathways. The vendor base stratifies across three tiers: global grain processors with captive corn wet milling networks, regional specialty starch houses with tailored bakery and dairy expertise, and biotechnology ventures developing microbial modification techniques. Competitive positioning hinges on backward integration into high-amylose germplasm, regulatory navigation capabilities across FDA and EFSA frameworks, and formulation support services for industrial customers. Capacity expansion and strategic partnerships represent the dominant competitive moves, with processors securing long-term supply agreements with major food brands.
Within the global grain processor archetype, Ingredion Incorporated and Cargill exemplify scale-driven positioning through upstream control over corn origination and wet milling infrastructure. Tate & Lyle occupies a specialty carbohydrate tier, representing heat-stable variant expertise for industrial baking applications. These three entities anchor the competitive structure, with their geographic footprints and regulatory engagement patterns shaping procurement options available to food manufacturers across North America and Europe.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Cargill |
| Tate & Lyle |
| ADM |
| Roquette Frères |
| MGP Ingredients |
| Emsland Group |
| SunOpta |
| Arcadia Biosciences |
| Others |
Supply Flow & Price Mechanics
Enzymatic modification specialists in Germany and the United States command wage premiums that widen spreads between distributed bioreactor-produced resistant starch and commodity-grade native starches. Labor-cost differentials between these technical hubs and centralized wet milling corridors in Iowa and Illinois translate directly into three-tier pricing separation across premium modified grades, standard heat-stable variants, and economy native starches.
Pricing Analysis
Technical support and formulation consulting are bundled into premium modified starch contracts while native grades ship unassisted. Three-tier pricing structure across premium, standard, and economy levels reflects amylose content, thermal stability certification, and FDA fiber definition compliance tier. Pricing pressure stems from native potato and tapioca starches undercutting functional grades in simple bakery applications where extrusion temperatures stay below degradation thresholds. Contract manufacturers and regional bakery cooperatives exhibit highest price sensitivity; retort pouch manufacturers and extruded snack producers show lowest sensitivity due to fiber claim substantiation requirements.
Supply Chain Analysis
Regional distribution centers in Chicago, Rotterdam, and Singapore anchor hub-and-spoke patterns for resistant starch finished goods. Supply concentrates in the United States, the Netherlands, and Germany, drawing from high-amylose corn hybrids in the US Midwest and specialized potato cultivars from Dutch and German processors. Raw material dependencies center on proprietary germplasm for amylose content, enzymatic modification reagents, and membrane bioreactor equipment. Single-source vulnerability for high-amylose corn germplasm controlled by limited proprietary breeders creates structural risk. Distribution runs through food ingredient distributors and direct digital sourcing portals serving CPG procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing backward integration into high-amylose corn germplasm to secure input cost control and fiber content consistency.
For Market Incumbents: Hedge against precision fermentation entrants by locking long-term supply agreements with major food brands before microbial modification techniques achieve scale. Secure captive wet milling capacity in Iowa and Illinois corridors to defend against enzymatic debranching decentralization. Invest in EFSA-compliant clinical trial infrastructure to maintain European market access against tightening health claim substantiation protocols. For New Entrants and Emerging Players: Capture white-space in India's Maharashtra and Gujarat bakery and beverage sectors ahead of FSSAI food additive permission maturation. Target drinkable yogurt and plant-based milk alternatives in the United States where low-viscosity fiber fortification commands formulation premiums. Pursue go-to-market partnerships with regional bakery cooperatives seeking just-in-time fiber fortification through distributed bioreactor installations. For Investors and Strategic Acquirers: Re-rating potential sits with enzymatic modification technology platforms given precision fermentation convergence and microbial starch modification pathway maturation. Long-term viability favors suppliers with regulatory navigation capabilities across FDA and EFSA frameworks plus formulation support services for industrial customers. Watch for EFSA positive opinions on gut microbiome claims as inflection indicator for European dairy and bakery segment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Germplasm | Ingredion Incorporated's proprietary high-amylose corn control secures raw material cost predictability. |
| Enzymatic Modification Scale-Up | Membrane bioreactor installations in Germany and the United States compress freight costs for regional bakery cooperatives. |
| EFSA Clinical Trial Investment | Multi-center gut microbiome studies satisfy EU Nutrition and Health Claims Regulation fiber-related claim requirements. |
| Digital Sourcing Portal Deployment | Cloud-based quality management systems validate certificate of analysis data against FDA fiber definitions for CPG procurement teams. |
| India First-Mover Compliance | FSSAI labeling compliance establishment in Mumbai-Pune corridor captures market share ahead of additive permission maturation. |
Methodological Framework
Document review covered FDA dietary fiber guidance documents, EFSA health claim opinions, FSSAI food additive notifications, and trade flow databases, complemented by interviews with ingredient procurement managers at CPG manufacturers, regulatory affairs directors at starch processors, dairy formulation scientists, bakery operations managers, and enzymatic modification technology specialists. Secondary validation drew from SEC 10-K filings of major grain processors, customs and trade data for starch imports, and food ingredient industry association reports. Bottom-up demand modeling across application channels triangulated against top-down supply capacity assessments.
Segment-level value and volume trajectories across the projection horizon reflect product type, application channel, end-user category, and physical form dimensions. CAGRs were derived from regression analysis of historical procurement patterns and forward pipeline tracking of reformulation mandates from major food brands. Industry-specific forecast inputs included FDA fiber definition compliance timelines, EFSA opinion issuance patterns, and enzymatic debranching technology adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory harmonization between Codex Alimentarius frameworks and national fiber definitions, precision fermentation technology cost curves, and high-amylose corn harvest volatility. Outputs reflect documented assumptions on brand reformulation timelines and claim substantiation investment levels. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Vegetable Extract Market
Ingredients
Tryptose Market
Ingredients
Chickpea Fiber Market
Ingredients
Bertholletia Excelsa Seed Oil Market
Ingredients
Casein Hydrolysate Market
Ingredients
Barley Malt Extract Market
Ingredients
South America Fats and Oil Market
Ingredients
India Bakery Ingredients Market
Ingredients
Cocoa Liquor Market
Ingredients
Plant Based Premix Market
Ingredients
US Ingredients Market
Ingredients
Jojoba Oil Market
Ingredients
Flaxseed Derivatives Market
Ingredients
Vegetable Fats Market
Ingredients
European Brewing Enzymes Market
Ingredients
Agave Inulin Market