
 Global Compound Chocolate Market | 2026-2036
Global Compound Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Compound Chocolate Market Analysis
The ice cream sector is recalibrating its coating and inclusion sourcing toward compound chocolate as dairy butterfat volatility persists. Barry Callebaut leverages its global couverture infrastructure to supply industrial-scale compound solutions across multiple continents. Cargill sustains a dominant position in North American food manufacturing through backward integration into tropical oil supply chains. Puratos Group anchors European bakery demand with technical service teams embedded in industrial customer plants.
Compound chocolate replaces cocoa butter with vegetable fats such as palm kernel or coconut oil, yielding a melt profile engineered for ambient stability in warm-climate distribution. Its primary commercial purpose centers on cost-controlled enrobing, molding, and inclusion applications where precise snap and gloss are secondary to price predictability. Milk compound occupies the largest volume share as confectionery multinationals standardize formulations across branded product lines. Dark compound generates premium positioning among clean-label snack producers seeking reduced-sugar claims without cocoa butter cost exposure. Ruby compound, though nascent, captures margin pools in novelty confectionery targeting younger demographics through color differentiation.
FDA standards of identity for chocolate products in the United States restrict compound chocolate labeling, shaping how suppliers position alternatives in retail versus foodservice channels. EU REACH and EFSA vegetable fat regulations govern palm oil sustainability declarations, while India's FSSAI import protocols affect tropical fat raw material flows into subcontinental manufacturing. BIS certification requirements for chocolate products in India further segment market access between domestic compounders and importers. Stakeholders must monitor evolving vegetable oil sustainability frameworks and regional labeling enforcement to anticipate supply chain qualification costs.
Market Dynamics
Vegetable fat substitution economics are compressing cocoa butter dependency across warm-climate confectionery corridors. Southeast Asian bakery chains now specify compound coatings for ambient-stable distribution without cold-chain infrastructure.
Growth Catalysts
- EU REACH palm oil sustainability mandates:Compound formulations bypass cocoa butter's volatile price swings while satisfying ECHA vegetable fat traceability requirements for European retail access.
- Indonesia's industrial baking corridor:Domestic procurement volumes concentrate in Surabaya-Jakarta manufacturing clusters where ambient-temperature logistics dominate distribution economics.
- Enrobing process standardization:Milk compound coatings enable confectionery multinationals to replicate snap and gloss specifications across tropical and temperate production lines without reformulation.
Market Restraints
- Coconut oil supply concentration:Philippine and Indonesian copra processing bottlenecks create input cost volatility for premium compound formulations targeting clean-label positioning.
- FDA standards of identity restrictions:US retail labeling limitations force suppliers to position compound chocolate exclusively through foodservice and industrial channels, compressing margin capture.
- Cocoa butter price arbitrage:Persistent dairy butterfat volatility in ice cream coatings sustains hybrid demand rather than full compound substitution.
Strategic Opportunities
- India FSSAI import protocol evolution:Streamlined tropical fat raw material flows into subcontinental manufacturing would unlock compound chocolate penetration in domestic biscuit and confectionery segments.
- Ruby compound color differentiation:Novelty confectionery targeting younger demographics through visual distinctiveness commands premium positioning without cocoa butter cost exposure.
- Clean-label dark compound expansion:Reduced-sugar snack producers leverage vegetable fat formulations to achieve premium claims while maintaining price predictability against cocoa butter futures.
Industry Challenges
- EFSA vegetable fat certification timelines:European suppliers face extended qualification periods for palm oil sustainability declarations, delaying customer onboarding.
- Legacy enrobing equipment compatibility:Industrial bakeries retrofitting lines for compound viscosity profiles encounter integration friction with existing tempering infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Compound Chocolate Market |
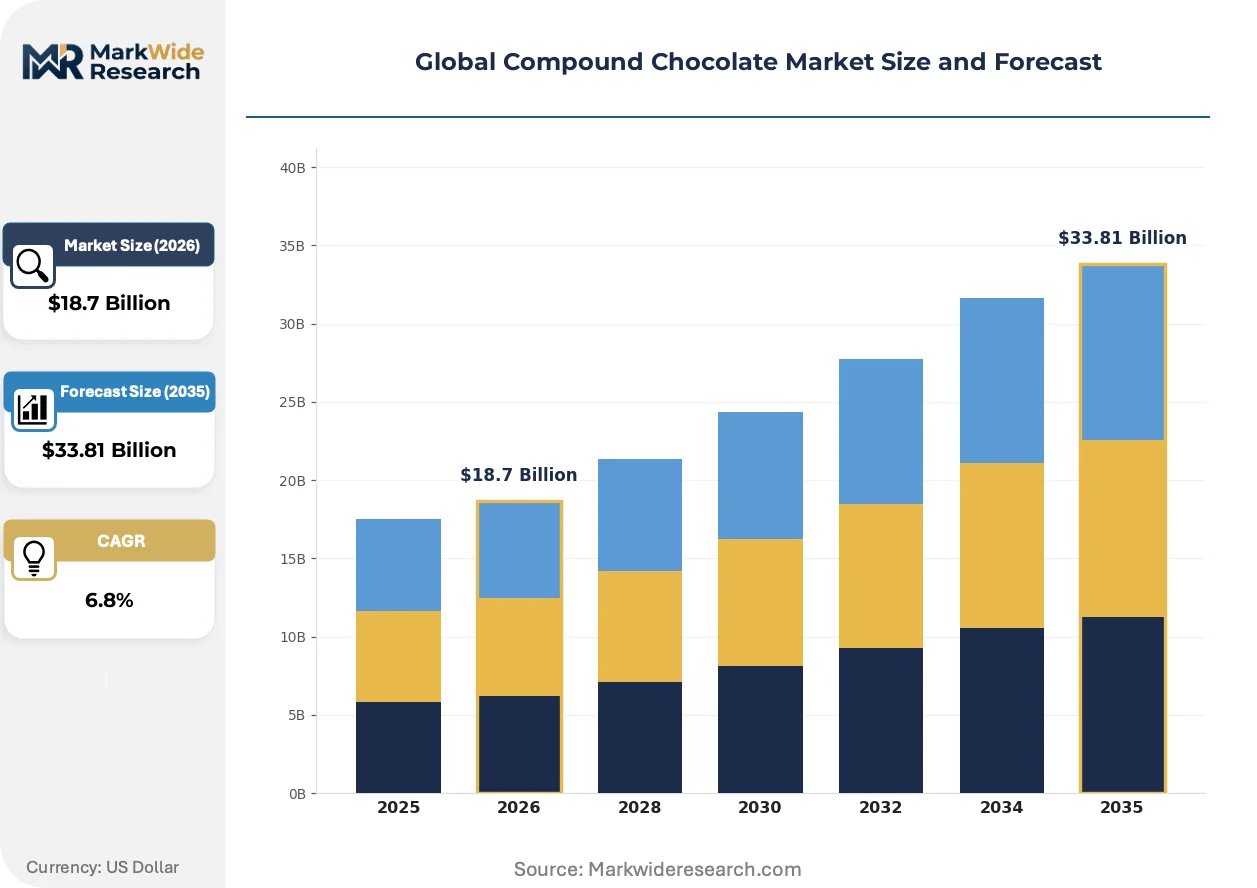
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Compound, Milk Compound, White Compound, Ruby Compound End User: Bakery, Confectionery, Ice Cream, Snacks Distribution Channel: Online, Supermarkets, Specialty Stores, Convenience Stores Packaging Type: Buckets, Bags, Bars, Pouches |
| Companies Covered | Puratos Group, Clasen Quality Chocolate, Barry Callebaut, Blommer Chocolate Company, AAK, Cargill, Cemoi Group, Nestlé Professional, Fuji Oil Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Compound Chocolate Market Emerging Trajectories
Formulation science and regulatory compliance are converging to reshape compound chocolate's functional positioning. Suppliers now engineer melt profiles for specific climate zones rather than generic ambient stability.
Fractionated palm kernel oil with tailored melting point curves is overtaking traditional hydrogenated vegetable fat bases in Southeast Asian coating applications. Industrial bakeries in Indonesia and Thailand adopt these precision fats for enrobing operations where 30-degree Celsius distribution corridors demand engineered snap recovery. The technology is overtaking commodity compound grades by enabling regional formulation standardization without cold-chain dependency.
EU REACH Annex XIV substance authorization requirements are tightening vegetable fat supplier qualification protocols for European compound chocolate manufacturers. ECHA documentation burdens now extend to tropical oil processors in Malaysia and Indonesia seeking EU market access. Dark compound segments face the steepest compliance cost escalation as clean-label positioning intensifies traceability scrutiny.
Bakery chain procurement departments are consolidating supplier relationships around technical service integration rather than spot purchasing. Industrial customers in Indonesia's manufacturing corridor now embed compound chocolate suppliers' formulation teams within plant operations. This operational intimacy concentrates volume among vertically integrated compounders capable of rapid recipe adjustment for humidity-variable production environments.
Global Compound Chocolate Market Segmentation
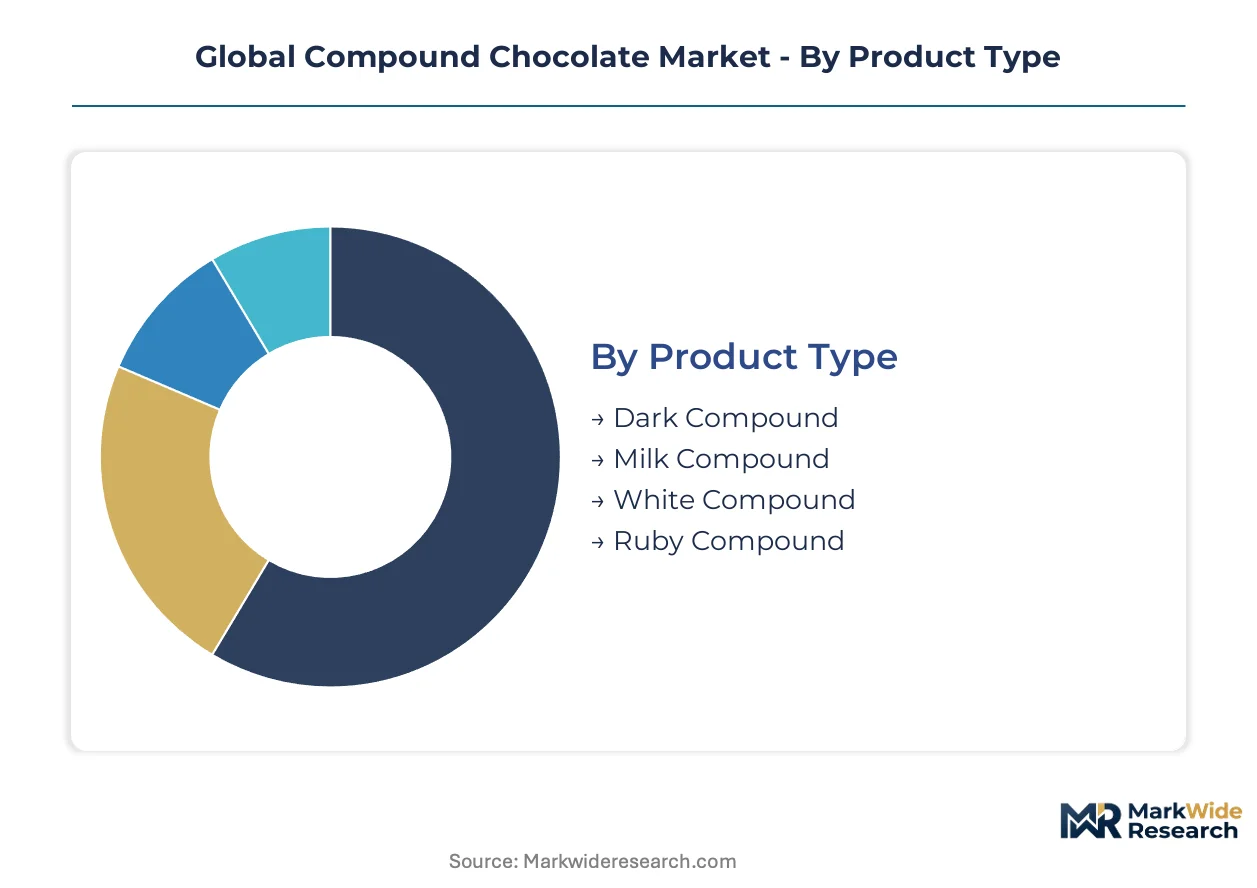
Compound chocolate segments diverge sharply between standalone retail formats and industrial embedded applications. Product type determines vegetable fat selection and melt profile engineering. End-use concentration in warm-climate manufacturing corridors reshapes packaging and channel priorities.
Product Type:
Standalone coating products command premium formulation investment versus inclusion-grade compounds embedded within finished goods.
- Milk Compound:Dominant volume segment formulated with milk solids and hydrogenated or fractionated vegetable fats for standardized snap and gloss. Confectionery multinationals in Indonesia's Surabaya-Jakarta corridor specify milk compound for ambient-stable enrobing without cold-chain dependency.
- Dark Compound:Cocoa powder-based formulations with elevated cocoa solids content enable reduced-sugar positioning. Clean-label snack producers in European markets leverage dark compound to bypass cocoa butter cost exposure while satisfying EFSA vegetable fat traceability requirements.
- White Compound:Cocoa butter-free formulations relying on sugar, milk solids, and deodorized vegetable fats for neutral color bases. Bakery chains deploy white compound as canvas for custom color matching in seasonal confectionery.
- Ruby Compound:Emerging category utilizing color-active compounds derived from specific cocoa bean treatments without artificial dyes. Novelty confectionery targeting younger demographics through visual differentiation commands margin premiums in Asian retail channels.
Milk compound leads volumes today; ruby compound is gaining share fastest.
End User:
Cost tier segmentation separates commodity-scale industrial procurement from premium ingredient specification.
- Bakery:Industrial-scale coating applications dominate, with Southeast Asian chains standardizing compound chocolate for ambient distribution economics. Surabaya manufacturing clusters specify fractionated palm kernel oil formulations for 30-degree Celsius logistics corridors.
- Confectionery:Molded bar and enrobed product lines drive formulation precision requirements. Multinationals replicate snap specifications across tropical and temperate production lines through milk compound standardization.
- Ice Cream:Coating and inclusion sourcing recalibrates toward compound solutions as dairy butterfat volatility persists. Barry Callebaut supplies industrial-scale compound across multiple continents for this segment.
- Snacks:Inclusion-grade compounds for granola bars and trail mixes prioritize cost stability over gloss performance. Clean-label positioning in this segment favors dark compound with reduced-sugar claims.
Bakery leads volumes today; ice cream is climbing the fastest as dairy butterfat arbitrage sustains hybrid demand.
Distribution Channel:
Volume concentration favors direct industrial supply relationships over retail intermediation.
- Supermarkets:Retail-facing compound chocolate faces FDA standards of identity restrictions in US markets, compressing shelf placement options. European supermarkets emphasize palm oil sustainability declarations under REACH mandates.
- Online:B2B procurement platforms serve small-scale bakeries and confectionery startups with formulation customization. Technical service integration lags behind direct supplier relationships.
- Specialty Stores:Premium positioning for artisan chocolatiers seeking small-batch compound with specific melt profiles. Ruby compound novelty distribution concentrates here.
- Convenience Stores:Impulse confectionery containing compound coatings drives volume in Southeast Asian urban corridors. Ambient stability requirements match this channel's infrastructure constraints.
Supermarkets lead volumes today; online is expanding most quickly among small-scale processors.
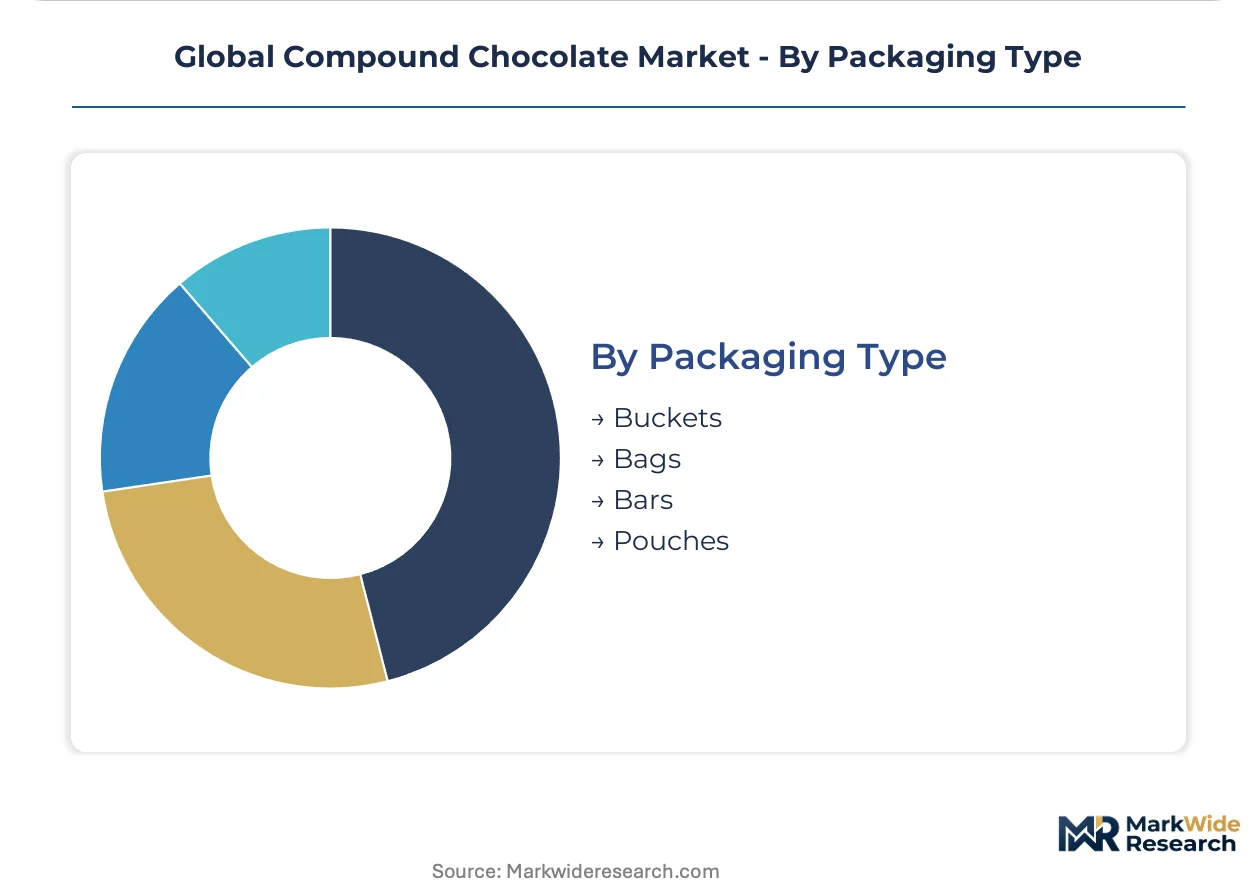
Packaging Type:
Supply concentration in tropical oil processing shapes packaging format selection for industrial versus artisanal end uses.
- Buckets:Industrial-scale liquid compound delivery for high-volume enrobing operations. Indonesian manufacturing corridors specify bucket formats for embedded supplier technical teams.
- Bags:Powdered and chip formats for dry inclusion applications in snack manufacturing. Philippine copra processing bottlenecks create input cost volatility for bagged premium formulations.
- Bars:Solid format for artisanal melting and tempering operations. Specialty store channel concentration favors bar packaging for precise portion control.
- Pouches:Flexible packaging for single-serve and small-batch applications. Convenience store distribution prioritizes pouches for shelf-life optimization in warm climates.
Buckets lead volumes today; pouches are gaining share fastest in convenience-oriented channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's Surabaya-Jakarta manufacturing corridor commands the dominant share of compound chocolate procurement volumes, with bakery chains specifying fractionated palm kernel oil formulations for ambient-stable distribution across tropical logistics networks.
Indonesia
Industrial baking clusters in Surabaya and Jakarta drive concentrated demand for milk compound coatings. FSSAI-aligned import protocols for tropical fat raw materials shape supplier qualification requirements for subcontinental market access. Domestic procurement volumes concentrate in manufacturing corridors where 30-degree Celsius distribution economics eliminate cold-chain dependency.
United States
Ice cream manufacturers recalibrate coating sourcing toward compound solutions as dairy butterfat volatility persists. FDA standards of identity restrict compound chocolate labeling in retail channels, compressing margin capture through foodservice and industrial pathways. Midwest food manufacturing hubs specify Cargill-supplied compound through backward-integrated tropical oil supply chains.
Germany
EFSA vegetable fat traceability requirements govern palm oil sustainability declarations in clean-label dark compound segments. REACH Annex XIV substance authorization timelines extend supplier qualification periods, delaying customer onboarding. Puratos Group anchors European bakery demand through technical service teams embedded in industrial customer plants.
India
BIS certification requirements segment market access between domestic compounders and importers of finished chocolate products. FSSAI import protocols affect tropical fat raw material flows into subcontinental biscuit and confectionery manufacturing. Maharashtra and Gujarat industrial corridors concentrate domestic compound chocolate production for regional bakery chains.
Malaysia
ECHA documentation burdens extend to tropical oil processors seeking EU market access for palm kernel oil derivatives. Fractionated fat technology adoption overtakes commodity compound grades in Southeast Asian coating applications. Penang and Selangor processing hubs supply precision-engineered melt profiles to Indonesian manufacturing corridors.
Global Compound Chocolate Market Vendor Landscape
Capacity expansion dominates the current landscape as suppliers retrofit lines for compound viscosity profiles and humidity-variable production environments. The vendor base stratifies between vertically integrated tropical oil processors, regional formulation specialists, and multinational confectionery ingredient platforms. Three archetypes occupy distinct positions: palm oil backward-integrated giants, European technical-service-embedded compounders, and Asian fractionated fat specialists. M&A activity and geographic expansion constitute the two dominant competitive moves as players secure tropical oil supply chain control and embed formulation teams in customer plants.
Within the vertically integrated tier, Cargill and Barry Callebaut exemplify scale-driven positioning through captive supply of tropical oil inputs and multi-continental industrial supply infrastructure. Puratos Group occupies a distinct European archetype anchored by technical service integration with bakery customers. Fuji Oil Holdings represents the Asian specialist model concentrated on fractionated palm kernel oil processing for regional manufacturing corridors.
| Leading Market Players |
|---|
| Puratos Group |
| Clasen Quality Chocolate |
| Barry Callebaut |
| Blommer Chocolate Company |
| AAK |
| Cargill |
| Cemoi Group |
| Nestlé Professional |
| Fuji Oil Holdings |
| Others |
Supply Flow & Price Mechanics
Fractionated palm kernel oil processing has displaced traditional hydrogenated vegetable fat bases across Southeast Asian coating applications, compressing input cost variability while concentrating formulation expertise among Malaysian and Indonesian processors with captive fractionation infrastructure. This technological transition simultaneously lowers per-unit production costs for ambient-stable compounds and locks pricing power within vertically integrated tropical oil processors capable of precision melt-profile engineering.
Pricing Analysis
Input-cost pass-through from coconut oil and palm kernel oil volatility shapes contract structures across the compound chocolate value chain. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified sustainable formulations from commodity grades and clean-label dark compounds. Price differentiation rests on certification grade and volume scale, with industrial bakery chains commanding lowest unit costs through embedded technical service relationships. Pricing pressure stems from Philippine copra processing bottlenecks that elevate premium formulation costs. Small-scale confectionery startups exhibit highest price sensitivity; multinational food manufacturers with backward-integrated suppliers demonstrate lowest.
Supply Chain Analysis
Direct-to-industrial channels handle hyperscale bakery and confectionery procurement across Indonesia's Surabaya-Jakarta manufacturing corridor. Geographic supply concentrates in Malaysia, Indonesia, and the Philippines, where tropical oil fractionation infrastructure feeds regional compound production. Raw material dependencies center on palm kernel oil, coconut oil, and cocoa powder. Single-source vulnerability runs through Philippine copra processors supplying premium clean-label formulations. Distribution runs through embedded supplier technical teams co-located in customer plants rather than spot-market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
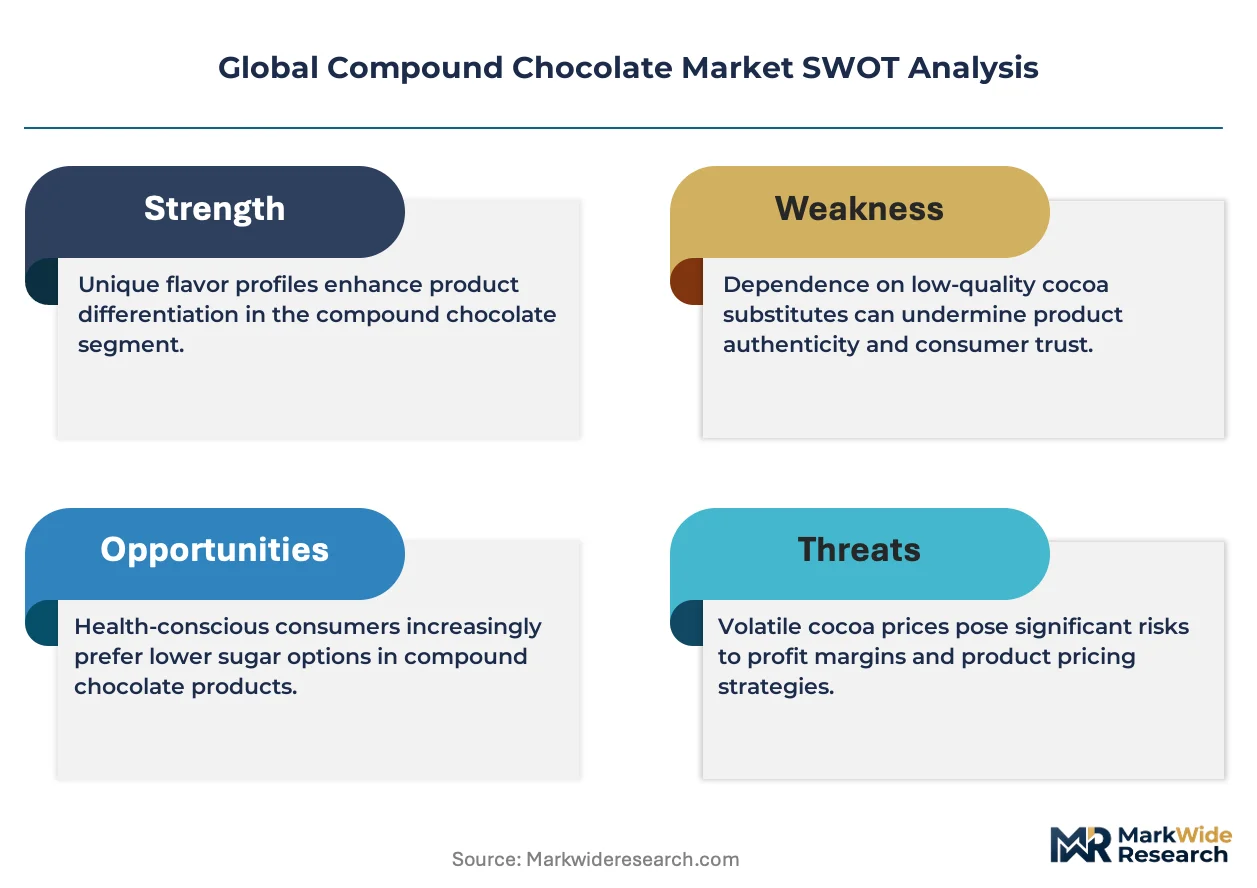
Margin expansion opportunities concentrate in dark compound and ruby compound tiers as clean-label positioning commands premium pricing without cocoa butter cost exposure, while fractionation technology adoption compresses production economics for standard-grade milk compounds.
For Market Incumbents: Acquire fractionation technology assets and captive palm kernel oil processing capacity to defend against Asian specialist encroachment. Secure EFSA REACH certification ahead of Annex XIV substance authorization timelines to delay competitor onboarding. Embed formulation teams within Indonesian manufacturing corridors to lock in volume concentration among bakery chains. For New Entrants and Emerging Players: Novelty confectionery color differentiation through ruby compound formulations offers the most penetrable white-space target for technology-first market entry. Target Indian domestic biscuit manufacturers facing BIS certification barriers to imported finished chocolate. Lead with B2B platform customization for small-scale bakery startups underserved by technical service integration. For Investors and Strategic Acquirers: Roll-up economics work for regional compounders with embedded customer relationships because bakery procurement consolidation favors suppliers with plant-level formulation support. Five-to-ten year viability hinges on sustainability certification infrastructure. Target Asian fractionated fat specialists with EU market access pipelines. Watch ECHA documentation burden escalation as inflection indicator for qualification cost barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tropical Oil Supply | Cargill and Barry Callebaut anchor North American supply security through captive palm kernel sourcing. |
| EFSA REACH Certification Investment | European compounders delay customer onboarding timelines while locking in clean-label dark compound premiums. |
| Embedded Technical Service Deployment | Puratos Group concentrates European bakery volume through plant-level formulation teams. |
| Fractionated Fat Technology Adoption | Fuji Oil Holdings supplies precision melt profiles to Indonesian manufacturing corridors. |
| Ruby Compound Product Line Extension | Novelty confectionery targeting younger demographics commands margin premiums in Asian retail channels. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary data collection engaged compound chocolate procurement managers at Southeast Asian bakery chains, technical R&D directors at European confectionery multinationals, tropical oil processing executives in Malaysia and Indonesia, and regulatory affairs leads navigating EFSA REACH compliance. Secondary validation drew from customs trade data, ECHA substance authorization databases, FSSAI import protocol filings, and SEC 10-K disclosures from listed ingredient suppliers. Bottom-up volume triangulation across product type, end-use, and regional manufacturing clusters converged with top-down market sizing from tropical oil processing capacity analysis.
Segment-weighting approaches distributed value and volume across milk compound, dark compound, white compound, and ruby compound product types, with further disaggregation by bakery, confectionery, ice cream, and snack end-uses. Distribution channel modeling separated direct industrial supply, supermarket retail, online B2B platforms, specialty stores, and convenience stores. CAGRs were derived from regression analysis of historical procurement volumes against tropical oil price indices and regulatory compliance cost trajectories. Forecast inputs incorporated EFSA vegetable fat traceability timeline assumptions and FSSAI protocol evolution scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU REACH Annex XIV authorization delays, Philippine copra supply disruptions, and Indian BIS certification requirement changes. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Low-Fat Candy Market
Confectionery
Licorice Candy Market
Confectionery
Organic Chocolate Confectionery Market
Confectionery
Brain Mint Market
Confectionery
Low Calorie Keto Desserts Market
Confectionery
North America Sugar-Free Chewing Gum Market
Confectionery
Middle East and Africa Confectionery Market
Confectionery
Caramel Market
Confectionery
Mints Market
Confectionery
North America Chocolate Market
Confectionery
Bangladesh Candy Market
Confectionery
United States Caramel Chocolate Market
Confectionery
Ruby Chocolate Market
Confectionery
Europe Compound Chocolate Market
Confectionery
Functional Confectionery Market
Confectionery
South America Confectionery Market