
 Asia-Pacific Food Coating Ingredients Market | 2026-2036
Asia-Pacific Food Coating Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Food Coating Ingredients Market Outlook
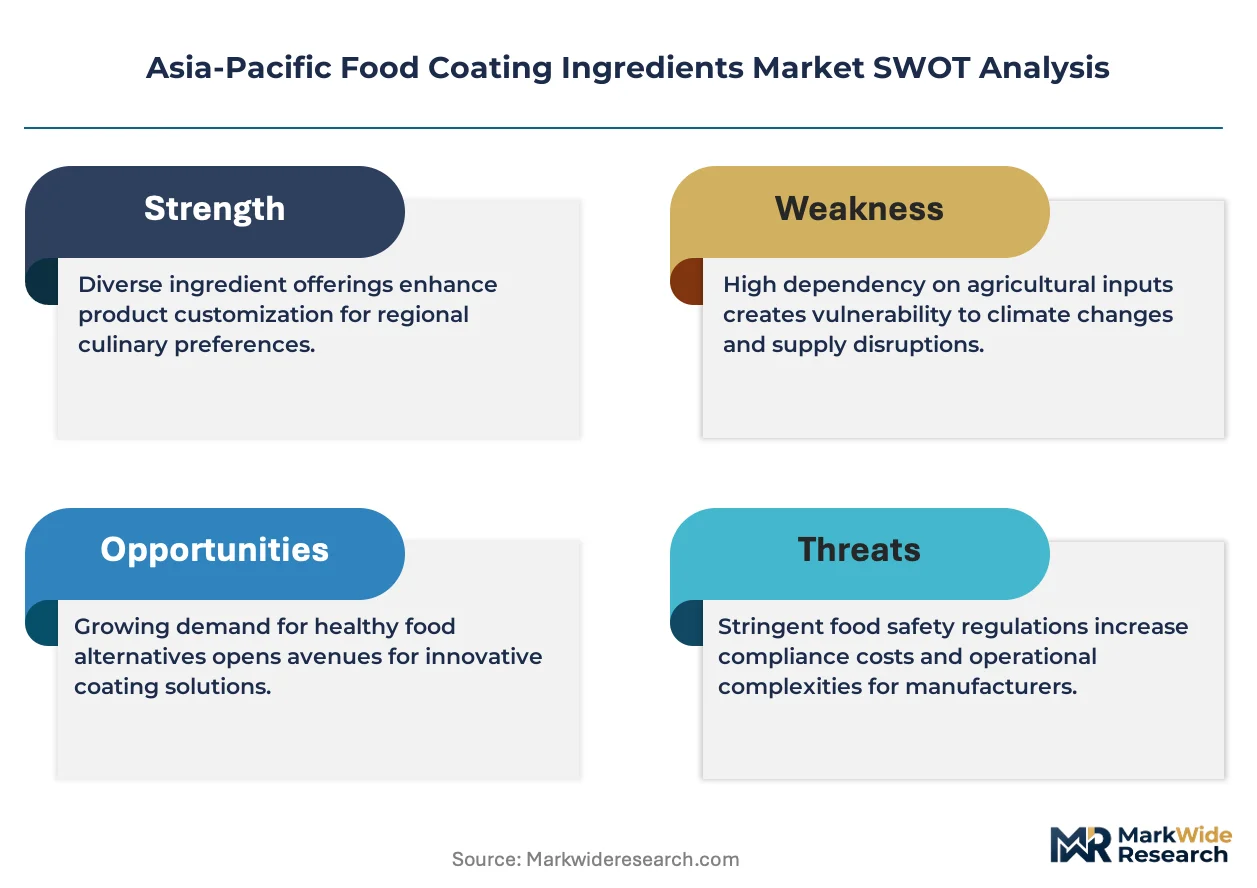
China's Shandong and Jiangsu provinces is fragmenting as regional mills expand modified starch and batter premix capacity to serve export-oriented seafood processors. Kerry Group leverages its regional application centers in Shanghai and Sydney to sustain technical service density for battered protein lines. Cargill Incorporated anchors procurement relationships with Southeast Asian palm oil refiners to secure emulsifier feedstocks for liquid coating systems. Ingredion Incorporated competes through specialty tapioca and waxy maize derivatives tailored to high-humidity frying environments.
Food coating ingredients encompass batters, breadcrumbs, tempura blends, and cornmeal-based systems formulated with specific viscosity profiles, adhesion coefficients, and thermal stability parameters to create protective, textural, or visual layers on processed foods. These compositions typically incorporate modified starches, hydrocolloids, leavening agents, and seasoning carriers to achieve controlled browning, oil uptake reduction, and shelf-life extension in commercial frying or baking operations. Batter and tempura formulations command premium positioning due to their technical complexity and dependence on cold-chain integrity in foodservice distribution. Powder and liquid forms dominate manufacturing-scale procurement, while ready-to-use blends capture margin pools in mid-tier restaurant chains lacking in-house formulation capability.
Japan's Ministry of Health, Labour and Welfare enforces stringent food additive positive lists that constrain hydrocolloid and emulsifier selections for coating systems distributed domestically. China's SAMR and National Health Commission administer GB standards for food contact materials and additive usage limits that directly shape import eligibility and local reformulation requirements. India's FSSAI progressively aligns with Codex Alimentarius frameworks while maintaining distinct labeling and shelf-life declaration rules that complicate pan-Asian product standardization. Stakeholders must monitor divergence between national positive lists and evolving sustainability mandates around palm oil sourcing and clean-label starch modifications.
Market Dynamics
Japan's FSSAI-aligned additive positive lists and China's GB standards for food contact materials are forcing coating system suppliers to maintain parallel formulation inventories, fragmenting R&D budgets and complicating pan-Asian product architecture.
Growth Catalysts
- Quick-service restaurant expansion:Western QSR chains scaling frozen protein processing across India's Maharashtra and Gujarat states are driving bulk procurement of tempura and breadcrumb solutions with specified adhesion coefficients.
- Export-oriented seafood processing:Modified starch and batter premix capacity in Shandong and Jiangsu provinces is expanding to serve cold-chain-dependent export volumes to North American and European buyers.
- Clean-label starch modification:Enzymatic and physical modification processes replacing chemical cross-linking are opening reformulation pathways for brands targeting retail channels with simplified ingredient declarations.
Market Restraints
- Palm oil price volatility:Emulsifier feedstock costs fluctuate with Malaysian and Indonesian crude palm oil futures, compressing margins on liquid coating systems during El Niño-driven supply contractions.
- Regional mill fragmentation:Southeast Asia's modified starch supply concentrates among small-scale processors with inconsistent viscosity specifications, forcing downstream batter blenders to maintain multiple supplier qualifications.
- Positive list divergence:Japan's Ministry of Health, Labour and Welfare maintains hydrocolloid approvals that exceed Codex Alimentarius scope, requiring dedicated domestic SKUs that cannot leverage regional scale.
Strategic Opportunities
- Vietnam's emerging processing corridor:Foreign direct investment in Ho Chi Minh City and Da Nang seafood export zones is creating first-mover advantages for coating ingredient suppliers establishing technical service presence.
- High-humidity frying environments:Specialty tapioca and waxy maize derivatives with enhanced thermal stability parameters address unmet performance requirements in tropical foodservice operations across Thailand and the Philippines.
- Dual carbon alignment:China's national carbon intensity targets are accelerating demand for enzymatically modified starches with lower processing energy footprints versus conventional chemical modification routes.
Industry Challenges
- Reformulation timeline compression:FSSAI's progressive alignment with Codex frameworks requires simultaneous compliance with evolving Indian shelf-life declaration rules and legacy state-level enforcement variations.
- Application technical service density:Batter and tempura formulation complexity demands field-based rheology support that regional ingredient suppliers struggle to staff across dispersed Southeast Asian foodservice clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Food Coating Ingredients Market |
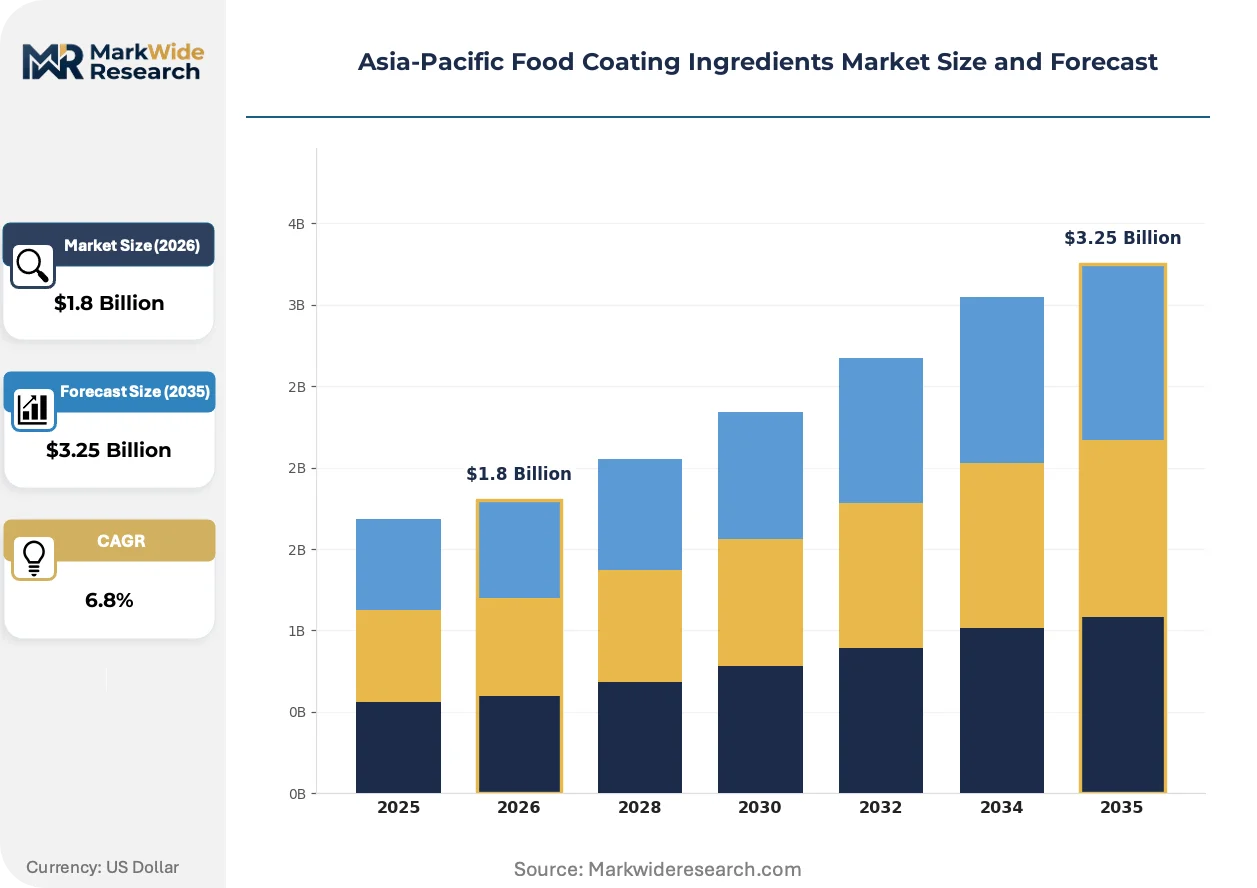
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breadcrumbs, Batter, Tempura, Cornmeal Application: Meat, Bakery, Snacks, Seafood Form: Powder, Liquid, Ready-to-Use, Granules End User: Food Processing, Restaurants, Retail, Catering |
| Companies Covered | Kerry Group, Associated British Foods PLC, Cargill Incorporated, Agrana Beteiligungs-AG, Pioneer Foods, Archer Daniels Midland Company, Ingredion Incorporated, Newly Weds Foods, Tate & Lyle PLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Food Coating Ingredients Market Strategic Shifts
Coating ingredient architecture is pivoting from commodity starch blends toward engineered systems with specified functional parameters, driven by downstream processor demands for fryer throughput optimization and finished product consistency.
Modified starch and hydrocolloid systems is hybridizing to create viscosity-stable batter matrices that maintain adhesion through extended cold-chain distribution. Frozen seafood processors in Thailand and Vietnam are adopting these hybrid systems at accelerating rates to reduce oil uptake and extend fryer oil life. The technology is compressing demand for single-ingredient modified starches while expanding technical service requirements around formulation integration.
China's SAMR and National Health Commission are tightening GB standard enforcement for food contact materials and additive usage limits, directly shaping import eligibility for coating systems containing specific emulsifier classes. Industrial consequence includes mandatory local reformulation for previously approved import SKUs and accelerated domestic certification timelines for multinational suppliers. Batter and breadcrumb categories distributed through cross-border e-commerce channels face the most immediate compliance pressure, with several platforms already requiring pre-listing GB test reports.
Mid-tier restaurant chains across India's western states are consolidating procurement through distributor-managed ready-to-use blend programs, displacing in-house formulation capability that previously sourced component starches and seasoners separately. This channel consolidation concentrates buyer power with regional foodservice distributors who now specify performance parameters and demand volume-tiered pricing structures. The shift is most visible in Maharashtra's quick-service fried chicken and frozen snack segments, where national chain expansion is standardizing coating specifications across franchise networks.
Asia-Pacific Food Coating Ingredients Market Segmentation
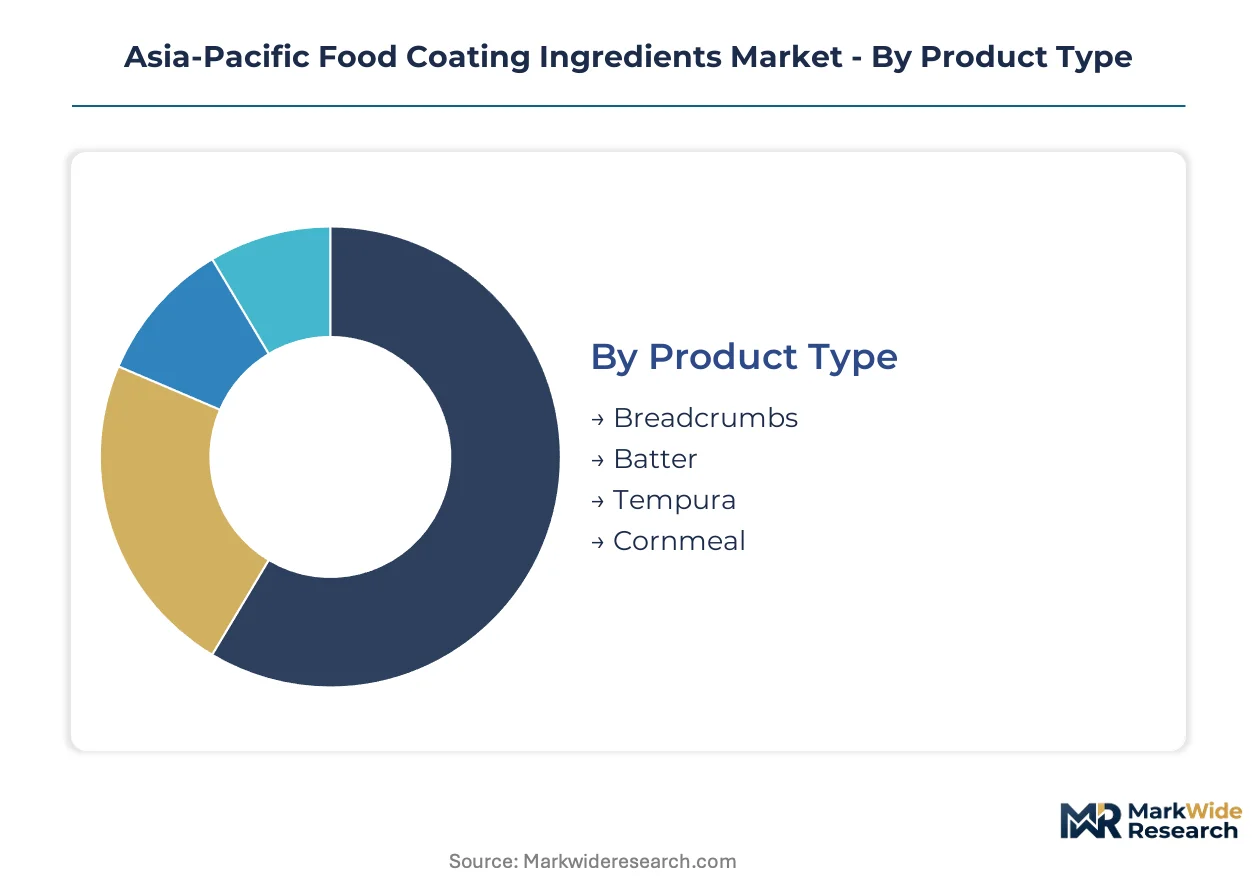
Coating ingredient procurement patterns diverge sharply across product architectures and downstream channels. Each segmentation dimension reveals distinct technical requirements, pricing sensitivities, and service intensity thresholds that shape supplier positioning.
Product Type:
Mature breadcrumb and batter systems anchor volume procurement, while engineered tempura blends command technical premium positioning.
- Batter:Viscosity-engineered wheat and modified starch matrices with specified shear-thinning profiles for automated application lines. Quick-service restaurant chains across Maharashtra and Gujarat specify adhesion coefficients for frozen protein processing at scale.
- Tempura:Leavening-activated systems combining low-protein wheat flour with specialized starch blends for cold-chain-dependent distribution. Seafood processors in Thailand and Vietnam adopt hybrid hydrocolloid matrices to reduce oil uptake and extend fryer life.
- Breadcrumbs:Japanese panko and European-style variants with defined particle size distributions for color development control.
- Cornmeal:Grit-specific formulations for regional snack applications with heritage texture profiles.
Batter handles the majority of throughput; tempura is the fastest mover on share.
Application:
Cost tier stratification separates commodity protein coating from premium bakery finishing systems.
- Seafood:Export-oriented processors in Shandong and Jiangsu provinces drive modified starch and batter premix demand with cold-chain integrity specifications for North American and European buyers.
- Snacks:Southeast Asian manufacturers scale breadcrumb and seasoning carrier procurement for fried and baked extruded products.
- Meat:Frozen poultry and red protein processing specifications standardized across franchise networks.
- Bakery:Specialized finishing systems for visual and textural enhancement in artisan and industrial production.
Seafood commands the highest technical service intensity; snacks deliver the steepest expansion trajectory.
Form:
Customer capability gaps determine powder versus liquid versus ready-to-use procurement splits.
- Powder:Bulk manufacturing-scale procurement of component starches and seasoners requiring in-house formulation infrastructure.
- Ready-to-Use:Pre-blended systems capturing margin pools in mid-tier restaurant chains lacking technical staff across India's western states.
- Liquid:Emulsifier-stabilized coating systems dependent on palm oil derivative feedstocks.
- Granules:Controlled dissolution formats for specific reconstitution requirements.
Powder dominates manufacturing throughput; ready-to-use blends are expanding most quickly.
End User:
Supply concentration varies dramatically between consolidated food processing and fragmented foodservice channels.
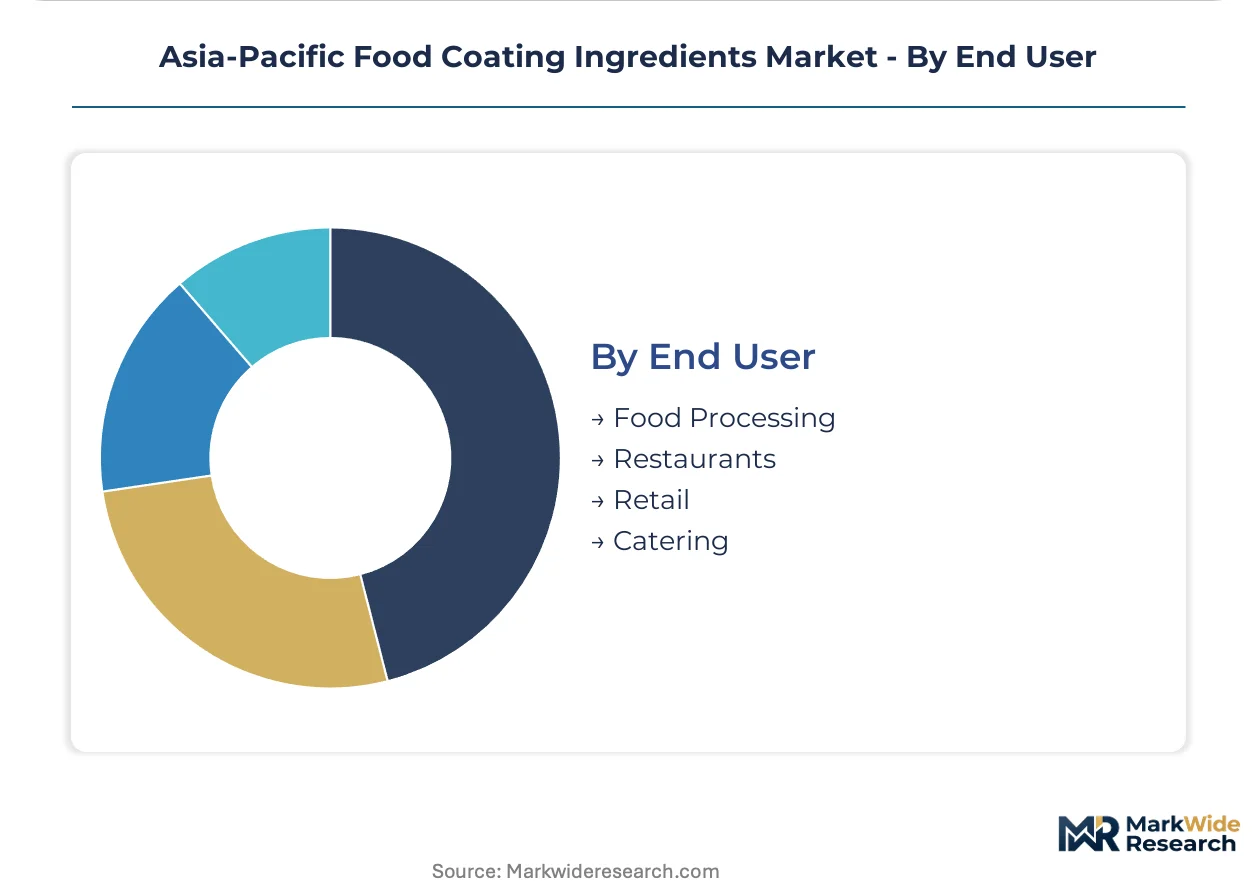
- Food Processing:Large-scale frozen protein and seafood manufacturers with specified performance parameters and volume-tiered pricing leverage.
- Restaurants:Quick-service and casual dining chains standardizing coating specifications across franchise networks in Maharashtra and Gujarat.
- Retail:Packaged food brands demanding clean-label starch modifications for simplified ingredient declarations.
- Catering:Institutional volume procurement with cost-optimized performance thresholds.
Food processing channels concentrate buyer power; restaurant segment procurement is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR anchors the regulatory framework that shapes coating ingredient compliance across the region. India's FSSAI progressively tightens additive standards while Japan's Ministry of Health, Labour and Welfare maintains distinct hydrocolloid positive lists. Southeast Asian markets fragment across national food contact material regulations.
China
Export-oriented seafood processors in Shandong and Jiangsu provinces drive modified starch and batter premix demand with cold-chain specifications for North American buyers. SAMR and the National Health Commission enforce GB standards for food contact materials that mandate local reformulation for previously approved import SKUs. Regional mills in these coastal provinces expand capacity to serve domestic and export markets simultaneously.
India
Quick-service restaurant chains scaling frozen protein processing across Maharashtra and Gujarat states generate bulk procurement of tempura and breadcrumb solutions with specified adhesion coefficients. FSSAI alignment with Codex Alimentarius frameworks proceeds alongside distinct labeling and shelf-life declaration rules that complicate product standardization. Mumbai and Ahmedabad clusters concentrate foodservice distributor consolidation for ready-to-use blend programs.
Japan
Domestic coating system distribution faces stringent food additive positive lists enforced by the Ministry of Health, Labour and Welfare that constrain hydrocolloid and emulsifier selections. These approvals exceed Codex Alimentarius scope, requiring dedicated domestic SKUs that cannot leverage regional manufacturing scale. Tokyo-Osaka industrial corridors host technical service centers supporting battered protein line optimization.
Vietnam
Foreign direct investment in Ho Chi Minh City and Da Nang seafood export zones creates first-mover advantages for coating ingredient suppliers establishing technical service presence. The country's national food safety authority adminulates evolving standards for imported additive systems that shape procurement qualification timelines. Mekong Delta aquaculture processing clusters adopt hybrid hydrocolloid matrices to reduce oil uptake in tropical frying environments.
Thailand
Frozen seafood processors in Bangkok-centered industrial zones accelerate adoption of viscosity-stable batter matrices for extended cold-chain distribution to European markets. The Thai FDA maintains additive approval lists that generally align with Codex while requiring specific documentation for enzymatically modified starch imports. Eastern seaboard seafood processing estates concentrate demand for specialty tapioca derivatives with enhanced thermal stability parameters.
Asia-Pacific Food Coating Ingredients Market Competitive Environment
Capability concentration sits with multinational ingredient specialists; scale advantage sits with regional mill networks. The market structures around three tiers: global suppliers with technical service infrastructure, mid-scale regional blenders, and commodity starch processors. Strategic archetypes include formulation-integrated specialists, palm oil-anchored emulsifier suppliers, and clean-label modification technology providers. Competitive moves center on application center expansion and enzymatic process licensing rather than capacity-led consolidation.
Within the global specialist tier, Kerry Group and Cargill Incorporated exemplify contrasting geographic anchoring strategies. Kerry leverages regional application centers in Shanghai and Sydney to sustain technical service density for battered protein lines. Cargill anchors procurement relationships with Southeast Asian palm oil refiners to secure emulsifier feedstocks. Ingredion Incorporated occupies a position among modification technology specialists, competing through specialty tapioca and waxy maize derivatives tailored to high-humidity frying environments.
| Leading Market Players |
|---|
| Kerry Group |
| Associated British Foods PLC |
| Cargill Incorporated |
| Agrana Beteiligungs-AG |
| Pioneer Foods |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Newly Weds Foods |
| Tate & Lyle PLC |
| Others |
Value Chain & Pricing Dynamics
Shandong and Jiangsu provinces anchor regional modified starch capacity expansion, concentrating supply-side leverage among coastal mills serving export-oriented seafood processors. This geographic clustering enables volume-tiered pricing power for batter premix suppliers while fragmenting procurement options for downstream blenders seeking consistent viscosity specifications.
Pricing Analysis
Malaysian and Indonesian crude palm oil futures generate a 15-20% price spread between liquid emulsifier-stabilized coating systems and powder-based alternatives across Southeast Asian distribution channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under China's GB standards and volume scale commitments from frozen protein processors. Cost compression in standard-tier tempura blends is intensifying because regional mill fragmentation forces multiple supplier qualifications. Quick-service restaurant chains in Maharashtra and Gujarat exhibit highest price sensitivity due to standardized franchise specifications, while export seafood processors in Thailand absorb premium positioning for cold-chain integrity.
Supply Chain Analysis
China's SAMR enforcement of GB standards for food contact materials restricts emulsifier class flows previously approved for import, mandating local reformulation timelines. Supply concentrates in China, Thailand, and Vietnam for modified starch and hydrocolloid matrices, with Indonesia and Malaysia anchoring palm oil derivative feedstocks. Raw material dependencies include tapioca roots, waxy maize, and crude palm oil fractions. Single-source vulnerability pervades Southeast Asia's small-scale processor network where inconsistent viscosity specifications disrupt batter blend consistency. Distribution runs through regional foodservice distributors consolidating procurement for mid-tier restaurant chains across India's western states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: Japan's Ministry of Health, Labour and Welfare maintains hydrocolloid positive lists exceeding Codex scope, creating dedicated domestic SKU requirements that lock in technical service relationships and fragment competitor scale advantages.
For Market Incumbents: Entrench position by deepening application center presence in Ho Chi Minh City and Da Nang to capture Vietnam's emerging seafood processing corridor foreign direct investment. Expand enzymatic modification licensing partnerships to address China's dual carbon alignment pressure on chemical cross-linking routes. Kerry Group's Shanghai-Sydney technical service density model offers template replication for tropical high-humidity frying environment support. For New Entrants and Emerging Players: Mid-tier restaurant chains in Maharashtra and Gujarat lacking in-house formulation capability represent the most penetrable entry point, displacing distributor-managed ready-to-use blend programs with direct technical service relationships. Specialty tapioca derivatives for tropical foodservice operations across Thailand and the Philippines offer white-space positioning against Ingredion's waxy maize focus. Lead with clean-label starch modification credentials targeting retail channel brands demanding simplified ingredient declarations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enzymatic modification specialists with lower processing energy footprints versus conventional chemical routes, aligning with China's national carbon intensity targets. Acquisition target archetype: regional mill networks in Shandong and Jiangsu with export certification infrastructure and coastal logistics access. Monitor divergence between FSSAI's Codex alignment trajectory and India's distinct shelf-life declaration rules as inflection indicator for reformulation service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Application Center Expansion | Shanghai and Sydney technical hubs sustain battered protein line optimization density for Kerry Group's regional positioning. |
| Enzymatic Process Licensing | Lower energy footprint modifications align with China's dual carbon goals and open retail clean-label channels. |
| Palm Oil Refiner Partnerships | Cargill's Southeast Asian feedstock anchoring secures emulsifier supply stability against El Niño-driven price volatility. |
| Hybrid Hydrocolloid Development | Thailand and Vietnam seafood processors adopt viscosity-stable matrices to reduce oil uptake and extend fryer life. |
| GB Standard Compliance Infrastructure | SAMR-mandated local reformulation accelerates domestic certification timelines for multinational coating system suppliers. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FSSAI additive approval databases, SAMR GB standard filings, and ASEAN food contact material harmonization protocols. Primary interviews engaged coating formulation chemists at multinational ingredient suppliers, procurement directors at frozen seafood processors in Shandong and Jiangsu, technical service managers at regional application centers, and foodservice distributors consolidating ready-to-use blend programs across Maharashtra and Gujarat. Secondary validation drew from customs trade data on modified starch flows, SEC 10-K disclosures from listed ingredient specialists, and Codex Alimentarius framework documentation. Bottom-up demand modeling triangulates against top-down capacity assessments from regional mill networks.
Forecast inputs span product type segmentation across batter, tempura, breadcrumb, and cornmeal architectures; application dimensions including seafood, snacks, meat, and bakery; form factors of powder, liquid, ready-to-use, and granules; and end-user channels separating food processing, restaurants, retail, and catering procurement patterns. CAGRs derive from elasticity-adjusted volume projections and value-chain margin compression modeling. Industry-specific inputs include cold-chain distribution integrity specifications for North American and European export markets and tropical frying environment thermal stability parameters.
Practitioners should monitor regulatory divergence between Japan's hydrocolloid positive lists and Codex Alimentarius frameworks, FSSAI shelf-life declaration rule evolution, and Malaysian crude palm oil futures volatility for early signals requiring forecast reassessment. Material shifts in SAMR enforcement intensity for food contact materials or China's dual carbon target acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe Dairy Protein Market
Ingredients
Medium-Chain Triglyceride (MCT) Fat Market
Ingredients
L-Arabinose Market
Ingredients
Jojoba Oil Market
Ingredients
South America Vegetable Oil Market
Ingredients
Fig Ingredient Market
Ingredients
Instant Starches Market
Ingredients
Fish Gelatin Market
Ingredients
Soybean Meal Market
Ingredients
Trait Enhanced Oils Market
Ingredients
Halal Ingredients Market
Ingredients
Sprouted Brown Rice Protein Market
Ingredients
US Ingredients Market
Ingredients
Europe Malt Extract Market
Ingredients
Meat Tenderizer Powder Market
Ingredients
Global Inactive Dried Yeast Market