
 Europe Frozen Pizza Market | 2026-2036
Europe Frozen Pizza Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Frozen Pizza Market Intelligence
Cauliflower and chickpea flour is expanding its footprint across European frozen pizza bases as brands respond to low-carb and allergen-free consumer preferences. Dr. Oetker GmbH leverages its centralized European manufacturing network to maintain cost discipline across thin-crust and gluten-free lines. Nestlé S.A. anchors its portfolio through sustained investment in wood-fired and premium-positioned offerings. Freiberger Lebensmittel GmbH specializes in private-label production, controlling supply relationships with major supermarket chains across Germany and Austria.
Europe frozen pizza comprises pre-baked or unbaked dough topped with sauce, cheese, and ingredients, then flash-frozen at minus 18 degrees Celsius or below for retail distribution and home preparation. The product category serves time-constrained households seeking restaurant-style meals without preparation complexity. Thin crust and gluten-free product types command margin premiums due to ingredient specialization and health-positioned pricing. Family-size packaging dominates volume throughput in supermarket channels, while single-serve formats capture impulse purchases in convenience retail.
EFSA governs additive and preservative approvals for frozen pizza formulations sold across EU member states, while the EU Green Deal mandates progressive reduction of single-use plastic in food packaging. REACH compliance requirements influence sourcing decisions for imported cheese powders and processed tomato concentrates. The EU F-Gas Regulation shapes cold-chain infrastructure investments that affect frozen product distribution economics. Stakeholders must monitor evolving ECHA substance restrictions and national transpositions of packaging waste directives to anticipate reformulation and material-switching costs.
Market Dynamics
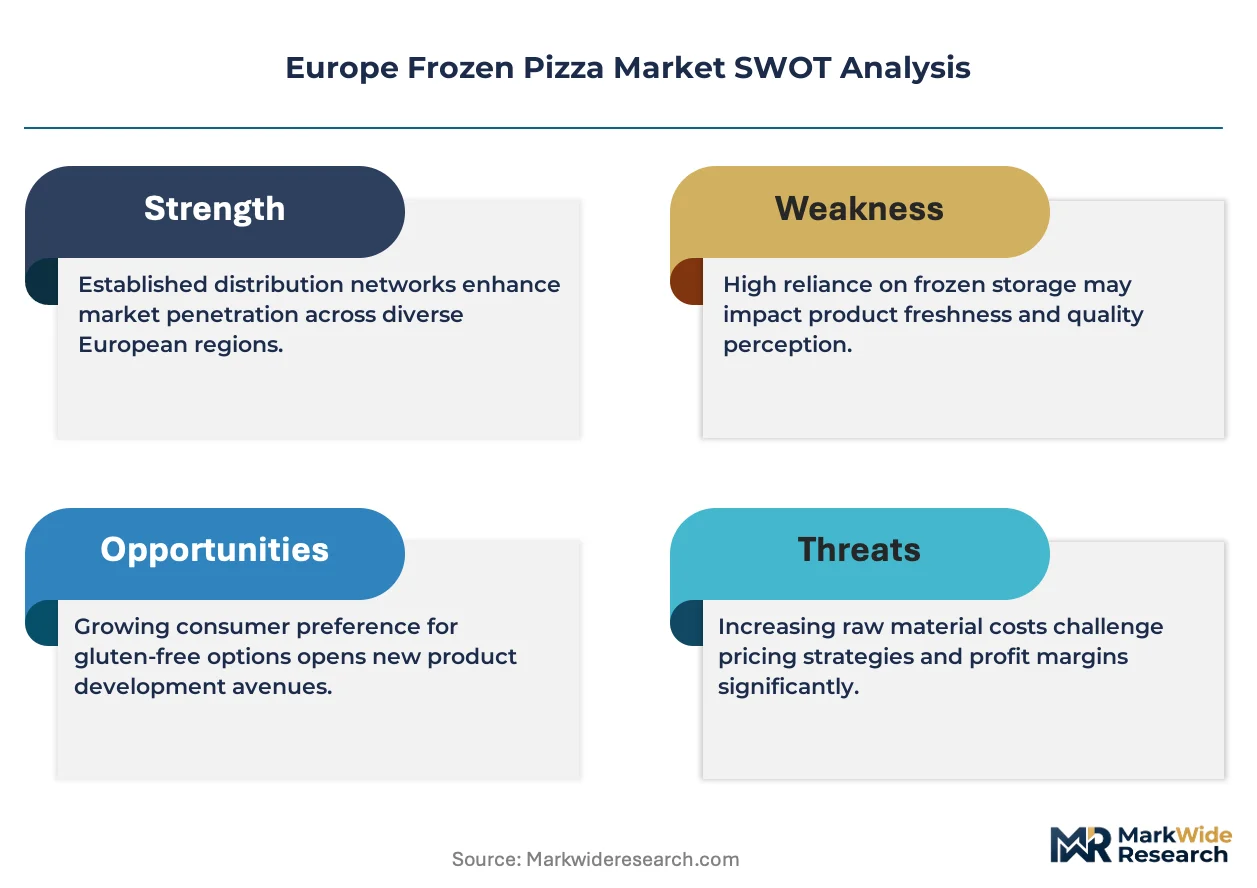
EFSA clean-label mandates and EU Green Deal packaging rules are forcing simultaneous reformulation of preservatives and materials across European frozen pizza supply chains, compressing margins while opening premium positioning windows.
Growth Catalysts
- EU Green Deal packaging mandates:Recyclable material requirements accelerate R&D investment in fiber-based trays and mono-material films, creating first-mover advantages for compliant manufacturers.
- Wood-fired production technology:Authentic flame-cooking methods command price premiums in Italy's premium segment and are expanding into French and German urban markets.
- Young urban professionals:Time-constrained households in Berlin, Paris, and Milan drive online channel penetration for premium single-serve and thin-crust formats.
Market Restraints
- Durum wheat and mozzarella input volatility:Climate-driven supply fluctuations from Italian and Polish agricultural regions create margin pressure on standard and economy product tiers.
- Cold-chain infrastructure concentration:Third-party logistics providers in Germany and the Netherlands control frozen distribution capacity, limiting new entrant market access.
- Fresh pizza delivery substitution:Quick-commerce platforms and ghost kitchens in London, Madrid, and Amsterdam capture impulse meal occasions previously served by frozen retail.
Strategic Opportunities
- Eastern European underpenetration:Poland, Romania, and Czech Republic display frozen pizza consumption rates below Western European averages, offering volume expansion potential for value-positioned family formats.
- Cauliflower and chickpea flour convergence:Low-carb and allergen-free base technologies unlock health-positioned pricing in UK and Scandinavian markets.
- Convenience retail channel innovation:Automated frozen vending and click-and-collect lockers in French and Belgian train stations capture commuter impulse purchases outside traditional grocery.
Industry Challenges
- REACH compliance timeline compression:ECHA substance restriction updates require rapid reformulation of imported cheese powders and tomato concentrates, straining procurement and QA functions.
- Legacy cold-chain asset reconfiguration:EU F-Gas Regulation phase-downs force capital-intensive refrigeration retrofits across distribution networks serving Spain, Portugal, and Greece.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Frozen Pizza Market |
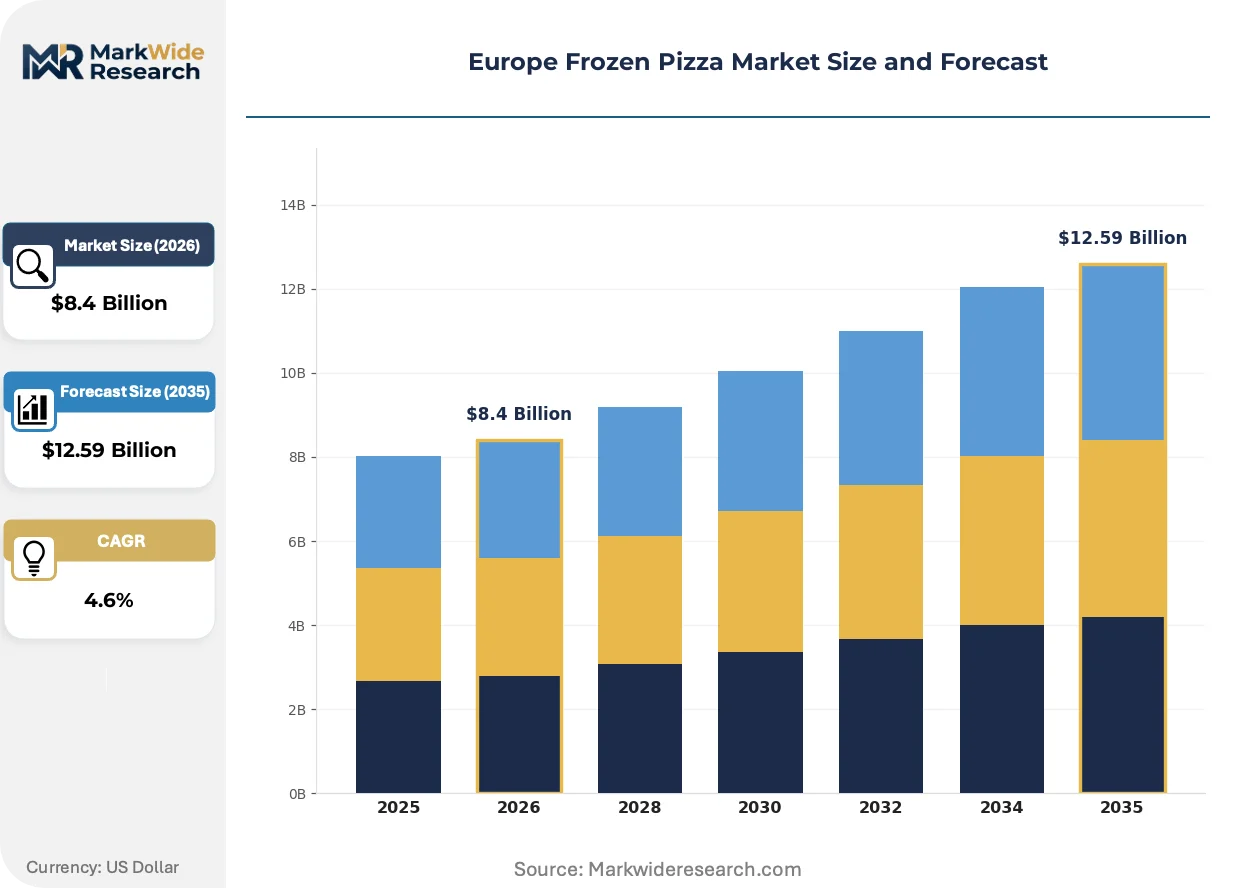
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin Crust, Deep Dish, Gluten-Free, Wood-Fired Topping Variety: Pepperoni, Vegetarian, Seafood, BBQ Chicken Packaging Type: Single Serve, Multi-Pack, Family Size, Retail Display Sales Channel: Supermarkets, Online Retailers, Convenience Stores, Food Service |
| Companies Covered | Conagra Brands Inc., Palermo Villa Inc., Nestlé S.A., Daiya Foods Inc., Schwan's Consumer Brands Inc., Dr. Oetker GmbH, Freiberger Lebensmittel GmbH, Amy's Kitchen Inc., General Mills Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Frozen Pizza Market Strategic Shifts & Innovations
European frozen pizza manufacturing is absorbing simultaneous pressures from ingredient transparency demands, packaging material transitions, and channel fragmentation, reshaping how products are formulated, positioned, and delivered to households.
High-pressure processing and natural fermentation cultures are replacing chemical preservatives in sauce and cheese applications. Italian and Spanish manufacturers lead adoption, responding to EFSA additive scrutiny. This shift is absorbing shelf-life risk while enabling clean-label claims that support premium pricing in supermarket channels.
REACH and the EU F-Gas Regulation now govern material sourcing and refrigeration chemistry across member states. Manufacturers must document substance safety for imported concentrates and retrofit cold-chain assets to lower-GWP refrigerants. Small and mid-sized producers in Portugal and Greece face disproportionate compliance burdens relative to integrated competitors with centralized QA functions.
Young urban households now assemble weekly meal plans through rapid grocery delivery apps rather than planned supermarket trips. This pattern fragments volume across channels, with UK and German consumers splitting purchases between premium direct-to-door subscriptions and discount bulk buys. Convenience retail captures impulse occasions previously concentrated in hypermarket frozen aisles.
Europe Frozen Pizza Market Segmentation
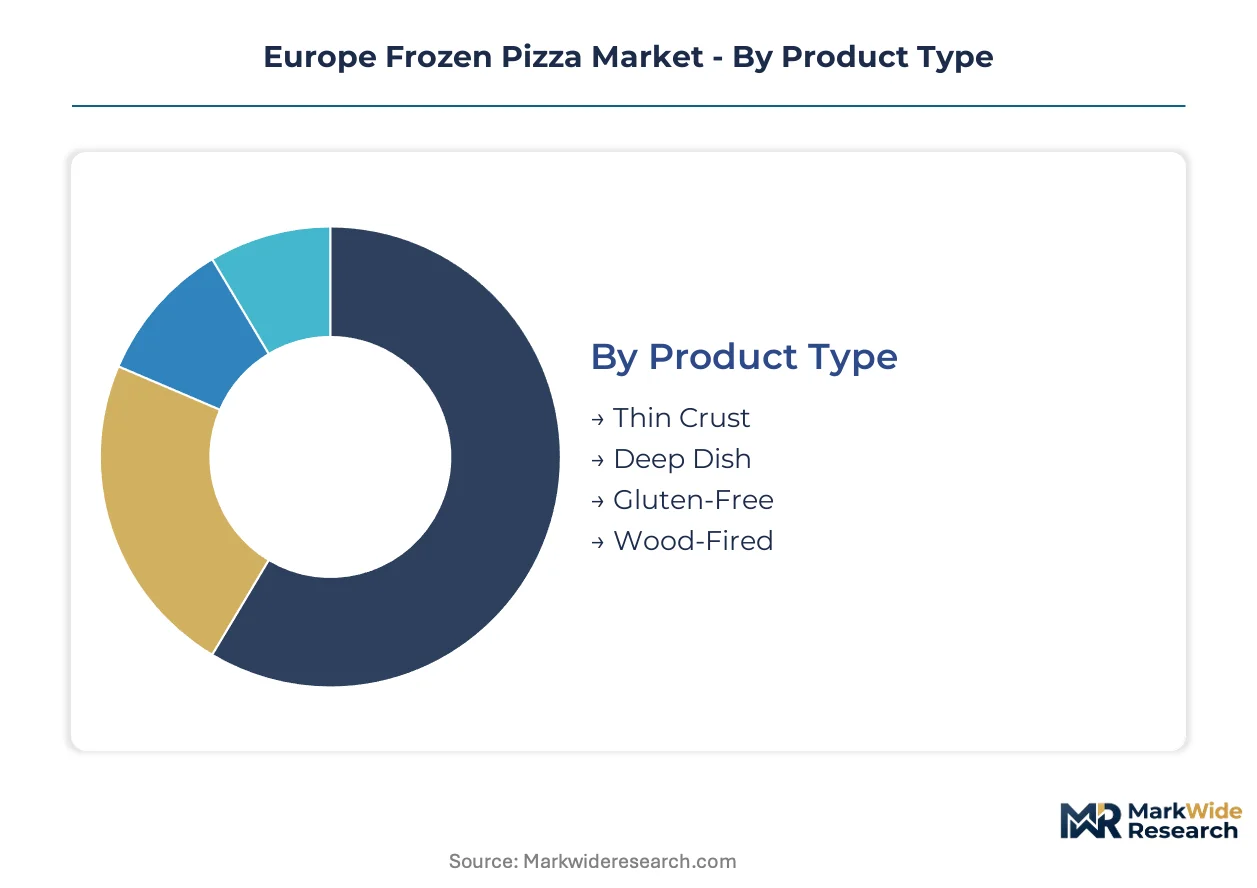
European frozen pizza purchasing patterns diverge sharply across preparation formats, dietary positioning, and retail occasions. Manufacturers must align production capacity with distinct margin profiles and channel requirements rather than treating the category as homogeneous.
Product Type:
Price sensitivity and preparation convenience drive consumer selection across crust formats, with health-positioned variants commanding meaningful premiums.
- Thin Crust:Par-baked dough sheets with reduced moisture content enable faster home oven cooking. Urban households in France and Germany favor this format for weeknight convenience, absorbing higher per-gram pricing in exchange for speed.
- Wood-Fired:Flame-cooked bases with charred blistering replicate restaurant authenticity. Italian manufacturers dominate this segment, exporting premium-positioned SKUs to Benelux and Scandinavian markets where experience-seeking buyers tolerate elevated price points.
- Deep Dish:High-edge dough profiles with extended bake times. Chicago-style variants find niche demand in UK and Irish markets through specialty retail.
- Gluten-Free:Rice flour and tapioca starch formulations certified under EFSA allergen thresholds. Cauliflower and chickpea flour bases are expanding fastest in UK and Netherlands as low-carb positioning converges with celiac compliance.
Volume sits with Thin Crust; growth tilts toward Wood-Fired.
Topping Variety:
Protein sourcing and regional taste preferences shape formulation decisions, with plant-based alternatives forcing ingredient list transparency.
- Pepperoni:Cured pork and beef slices with paprika-based coloring. German and Polish consumers drive volume through discount retail, though EFSA nitrate scrutiny is accelerating clean-label reformulation costs.
- Vegetarian:Grilled vegetables, plant-based cheese analogs, and herb-infused oils. UK supermarkets are expanding facings for this segment as flexitarian diets penetrate family purchasing decisions.
- Seafood:Shrimp, anchovy, and tuna preparations with Mediterranean herb profiles. Spanish and Portuguese coastal markets sustain regional demand despite cold-chain complexity.
- BBQ Chicken:Smoked poultry with molasses-based sauce coatings. Limited traction outside UK and Irish markets where American flavor profiles retain cultural resonance.
Standard meat toppings dominate shelf space; plant-forward varieties are climbing fastest.
Packaging Type:
Household composition and storage constraints determine format selection, with EU Green Deal mandates forcing material transitions across all configurations.
- Family Size:Multi-sleeve cartons with 400-600 gram net weights. Supermarket chains in Germany and Austria negotiate aggressive terms for this high-velocity format, compressing margins despite volume concentration.
- Single Serve:Individual portions in fiber-based trays. French convenience retail and Belgian train station vending are absorbing production shifts as commuter occasion fragmentation accelerates.
- Multi-Pack:Two-to-three unit bundles targeting small households. UK discount channels favor this format for promotional depth.
- Retail Display:Open-front cartons designed for freezer aisle visibility. Italian premium brands invest disproportionately here to signal artisan positioning.
Family Size commands throughput; Single Serve formats are gaining share fastest.
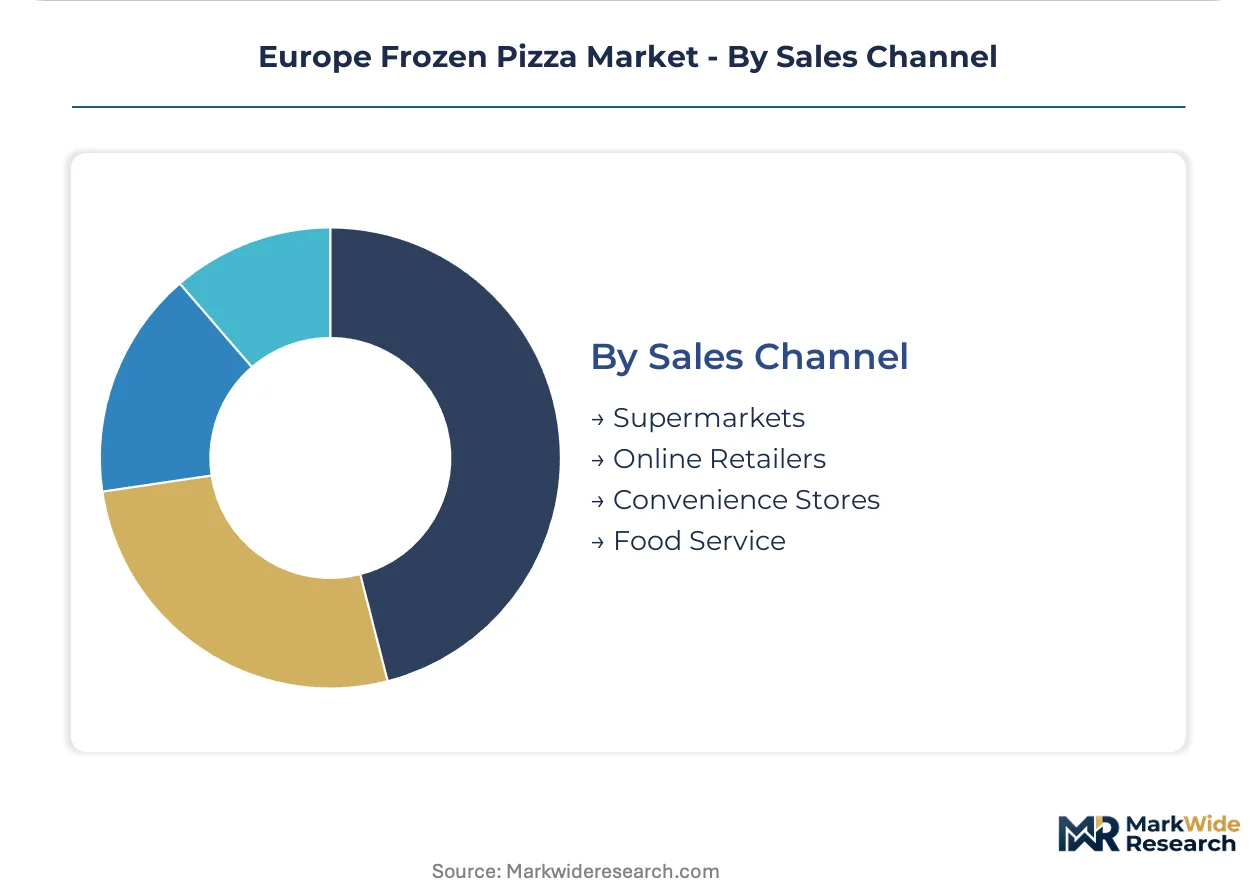
Sales Channel:
Route-to-market economics vary dramatically, with cold-chain requirements and promotional intensity creating distinct competitive barriers.
- Supermarkets:Full-range frozen aisles with promotional calendar dependency. German and Dutch retail consolidation gives chains outsized negotiation leverage on listing fees and trade spend.
- Online Retailers:Direct-to-door delivery with insulated packaging. Berlin, Paris, and Milan urban professionals are shifting planned purchases here, fragmenting volume from traditional grocery.
- Convenience Stores:Limited assortment with impulse-driven placement. French and Belgian automated frozen lockers are capturing commuter occasions outside conventional retail hours.
- Food Service:Bulk formats for hospitality and institutional catering. Italian pizzeria chains source partially-baked bases for finishing in wood-fired ovens.
Supermarkets anchor volume; Online Retailers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban professional households in Germany and France generate the strongest per-capita demand for premium frozen pizza formats, while Italy's artisan heritage anchors the wood-fired segment and the United Kingdom drives volume through value-oriented family purchasing.
Germany
Berlin and Munich professionals favor thin-crust and single-serve formats through rapid grocery delivery apps. EFSA clean-label standards compel reformulation of imported cheese powders and tomato concentrates. Freiberger Lebensmittel GmbH leverages centralized manufacturing in Lower Saxony to supply private-label volumes across Aldi, Lidl, and Rewe networks.
France
Parisian commuter corridors absorb automated frozen vending and click-and-collect locker placements for impulse single-serve purchases. EU Green Deal packaging mandates accelerate fiber-based tray adoption by major retail chains. Dr. Oetker GmbH maintains distribution dominance through its French subsidiary network serving Carrefour and Intermarché.
Italy
Milan and Rome households pay premiums for wood-fired authenticity and certified regional toppings. REACH compliance timelines strain procurement of imported durum wheat and specialty mozzarella from Puglia and Campania. Nestlé S.A. anchors premium positioning through sustained investment in flame-cooking technology licensed to Italian production facilities.
United Kingdom
London and Manchester families concentrate purchases in 400-600 gram family formats through Tesco, Sainsbury's, and Asda promotional calendars. ECHA substance restrictions force rapid QA adjustments on tomato concentrate imports. Cauliflower and chickpea flour bases from Amy's Kitchen Inc. and Daiya Foods Inc. capture fastest growth in gluten-free and low-carb segments.
Poland
Warsaw and Krakow consumption rates trail Western European averages, creating expansion windows for value-positioned family formats. EU F-Gas Regulation phase-downs require cold-chain refrigeration retrofits across distribution networks serving Poznań and Wrocław. Schwan's Consumer Brands Inc. evaluates market entry through partnership structures with Polish retail consolidators.
Europe Frozen Pizza Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated multinationals controlling premium wood-fired and thin-crust lines while private-label fabricators dominate supermarket value tiers. The vendor base organizes around three strategic archetypes: heritage European food conglomerates with centralized manufacturing networks, North American health-positioned entrants leveraging allergen-free credentials, and specialized contract producers serving retail-owned brands. Competitive intensity manifests through M&A activity targeting regional sauce and cheese suppliers, and capacity expansion into Eastern European production zones.
Among heritage European specialists, Dr. Oetker GmbH and Freiberger Lebensmittel GmbH exemplify divergent strategic positions—one anchoring branded premium distribution, the other controlling private-label supply relationships. Nestlé S.A. occupies a position as the scale-driven multinational with sustained wood-fired technology investment. These three represent the competitive spectrum from specialized contract manufacturing to integrated global portfolio management.
| Leading Market Players |
|---|
| Conagra Brands Inc. |
| Palermo Villa Inc. |
| Nestlé S.A. |
| Daiya Foods Inc. |
| Schwan's Consumer Brands Inc. |
| Dr. Oetker GmbH |
| Freiberger Lebensmittel GmbH |
| Amy's Kitchen Inc. |
| General Mills Inc. |
| Others |
Cost & Logistics Intelligence
Durum wheat futures from the Bologna commodity exchange cascade through Italian mill networks into frozen pizza base costs, compressing margins on standard-tier products while wood-fired and gluten-free variants absorb ingredient premiums through health-positioned pricing. This input-cost transmission splits the market between volume-driven family formats negotiating thin supermarket margins and specialty lines commanding price insulation through EFSA clean-label certification.
Pricing Analysis
Volume throughput concentrates in family-size formats through German and Austrian discount retail, where Aldi and Lidl procurement leverage squeezes per-unit margins below premium tiers. Three-tier pricing structure across premium, standard, and economy levels separates wood-fired artisan positioning from private-label value plays, with certification grade and geographic delivery cost as primary differentiation drivers. Cost compression in economy tiers is intensifying because Polish and Romanian retail consolidation demands promotional depth. Quick-commerce platforms in Berlin and Paris show least price sensitivity for single-serve impulse purchases.
Supply Chain Analysis
Cold-chain logistics costs from Lower Saxony distribution hubs to Benelux retail networks absorb margin through specialized refrigerated transport contracting. Ingredient sourcing concentrates in Italy for durum wheat and specialty mozzarella, Germany for centralized manufacturing infrastructure, and the Netherlands for third-party frozen distribution capacity. Production rests on imported tomato concentrates from Spain, cheese powders from Poland, and cauliflower flour from UK specialty mills. Single-source vulnerability sits with concentrated third-party logistics providers controlling frozen distribution capacity. Distribution runs through supermarket chains with promotional calendar dependency, though online retail fragments volume through direct-to-door insulated packaging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European frozen pizza manufacturing is transitioning from chemical preservation to high-pressure processing and natural fermentation cultures, with EFSA additive scrutiny accelerating technology replacement timelines across sauce and cheese applications.
For Market Incumbents: Acquire regional sauce and cheese supplier capabilities to secure clean-label ingredient streams against REACH compliance timeline compression. Nestlé S.A. and Dr. Oetker GmbH should expand centralized QA functions into Portugal and Greece to offset disproportionate compliance burdens on smaller competitors. Capacity addition in Poland and Romania captures underpenetrated Eastern European demand for value-positioned family formats. For New Entrants and Emerging Players: Rapid grocery delivery apps in Berlin, Paris, and Milan offer the lowest barrier entry for premium single-serve and thin-crust formats targeting time-constrained urban professionals. White-space targets include Romanian and Czech Republic frozen pizza consumption gaps below Western European averages, and UK gluten-free segments where cauliflower and chickpea flour convergence unlocks health-positioned pricing. Direct-to-door subscription models bypass supermarket listing fee negotiations. For Investors and Strategic Acquirers: Distressed-cycle entries favor private-label contract manufacturers in Germany and Austria facing margin pressure from retail consolidation, particularly those with existing Aldi and Lidl supply relationships. Long-term viability over a multi-year horizon rests on cold-chain infrastructure ownership and EFSA-compliant clean-label certification capabilities. Watch for EU F-Gas Regulation phase-downs forcing asset sales from undercapitalized distributors in Southern Europe as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | High-pressure processing adoption satisfies EFSA additive scrutiny while enabling premium supermarket positioning. |
| Fiber-Based Packaging Transition | EU Green Deal compliance creates first-mover advantage in French and Belgian automated vending channels. |
| Eastern European Capacity Expansion | Polish and Romanian production zones capture volume growth in underpenetrated value-tier markets. |
| Cold-Chain Infrastructure Acquisition | Ownership of refrigerated distribution networks in Germany and Netherlands defends against logistics provider concentration. |
| Wood-Fired Technology Licensing | Flame-cooking authenticity commands price premiums in Italian export markets and French urban corridors. |
Research Approach
Document review covered customs and trade data for durum wheat and mozzarella imports, EU regulatory filings on EFSA additive standards and EU Green Deal packaging mandates, and Nielsen retail audit data for frozen pizza category performance, complemented by interviews with category buyers at German and French supermarket chains, supply planners at centralized manufacturing facilities, and regulatory affairs leads navigating REACH compliance. Bottom-up volume modeling from production facility disclosures triangulated against top-down expenditure estimates from household consumption surveys.
Historical shipment data cross-referenced against panel input from plant managers and channel sales heads anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include crust format, topping variety, packaging configuration, and sales channel, with regional regulatory cluster as an industry-specific overlay. CAGRs were derived through trend extrapolation validated against stakeholder capacity expansion announcements, incorporating wood-fired technology adoption curves and cauliflower flour ingredient substitution rates as forecast inputs.
Inputs from supermarket procurement databases and cold-chain logistics operators were available through the study window; gaps in real-time commodity price volatility for durum wheat and mozzarella introduce uncertainty bands around margin projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Bangladesh Frozen Food Market
Processed and Frozen Foods
US Frozen Dessert Market
Processed and Frozen Foods
Freeze-Dried Food Market
Processed and Frozen Foods
Frozen Smoked Salmon Market
Processed and Frozen Foods
Asia-Pacific Frozen Food Market
Processed and Frozen Foods
Frozen Desserts Market
Processed and Frozen Foods
Chocolate Ice Cream Market
Processed and Frozen Foods
Middle East and Africa Frozen Bread Market
Processed and Frozen Foods
Germany Frozen Snack Market
Processed and Frozen Foods
Frozen Basil Leaves Market
Processed and Frozen Foods
Deli Meat Market
Processed and Frozen Foods
Freeze Dried Tropical Fruits Market
Processed and Frozen Foods
Global Frozen Breakfast Entrees/Sandwiches Market
Processed and Frozen Foods
Commercial Walk in Freezer Market
Processed and Frozen Foods
Frozen Meat Market
Processed and Frozen Foods
Chilled Meal Kits Market