
 Europe Plant Protein Ingredients Market | 2026-2036
Europe Plant Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Plant Protein Ingredients Market Foresight
Modular ingredient bundling—pre-blended protein-fat-flavor systems sold as turnkey bases—is hardening as the default procurement format for mid-sized European food manufacturers. Roquette Frères leverages its decades of extrusion expertise to dominate textured protein supply for meat alternative brands. Cargill Incorporated anchors its position through backward integration into European pea and soy origination networks. Kerry Group PLC differentiates via flavor-protein co-development services that reduce customer formulation cycles.
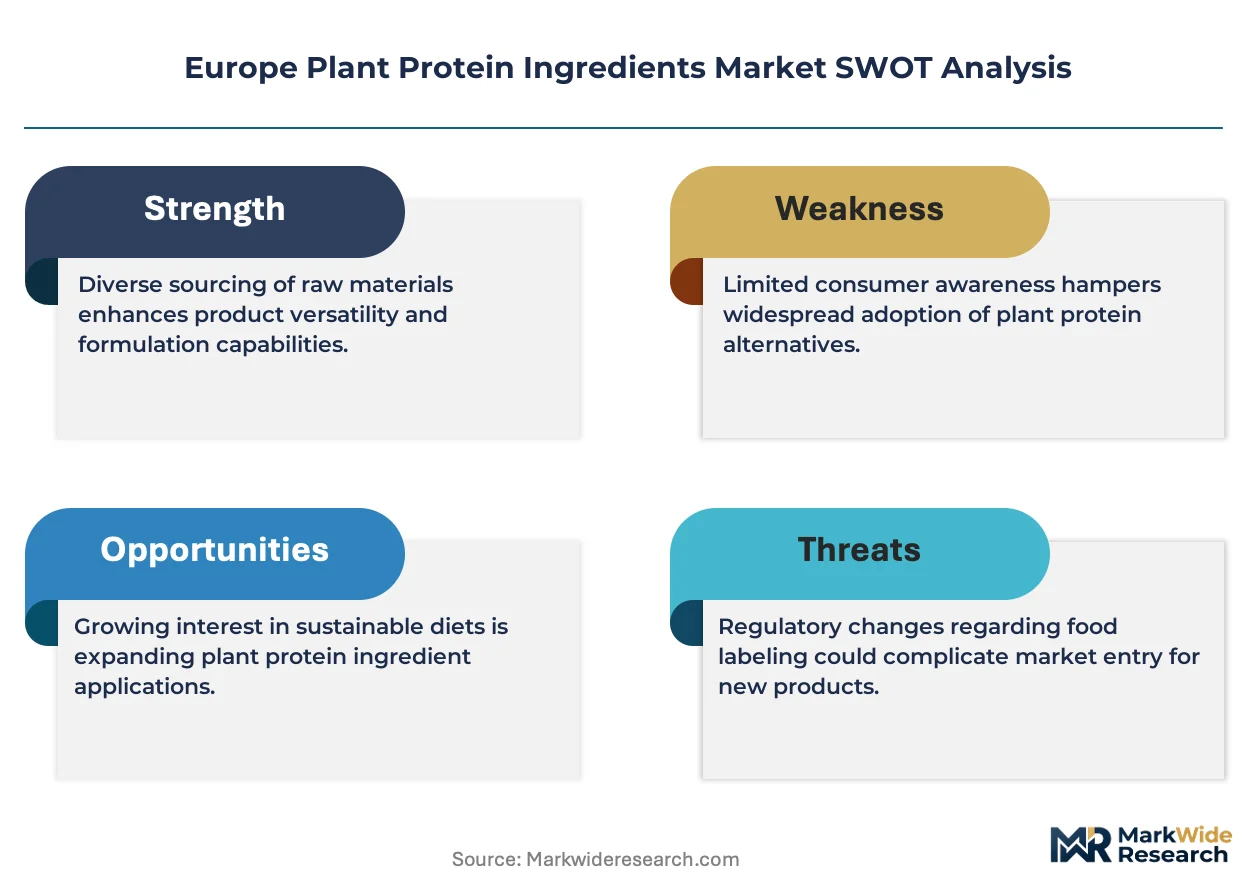
Europe plant protein ingredients comprise fractionated, concentrated, or isolated protein extracts derived from legumes, cereals, and oilseeds, typically achieving protein contents ranging from 50% to 90% on a dry-weight basis, and function primarily as functional replacers for animal proteins in formulated foods. Isolates command the deepest margin pools due to their superior emulsification and gelation performance in dairy alternatives. Pea protein sustains the steepest volume trajectory as allergen labeling rules and GMO avoidance preferences displace soy in multiple applications. Textured protein occupies a mature but stable position in meat analogues where European extrusion capacity remains concentrated among a handful of specialized processors.
The European Food Safety Authority (EFSA) evaluates novel protein safety claims under the EU Novel Food Regulation, while REACH governs processing aid chemicals and extraction solvents used in protein fractionation. EFSA's evolving guidance on protein quality scoring and the EU Green Deal's farm-to-fork emissions targets are jointly reshaping supplier certification requirements and customer procurement criteria. Stakeholders must monitor how the EU AI Act and forthcoming digital product passport mandates will alter traceability obligations across multi-tier ingredient supply chains.
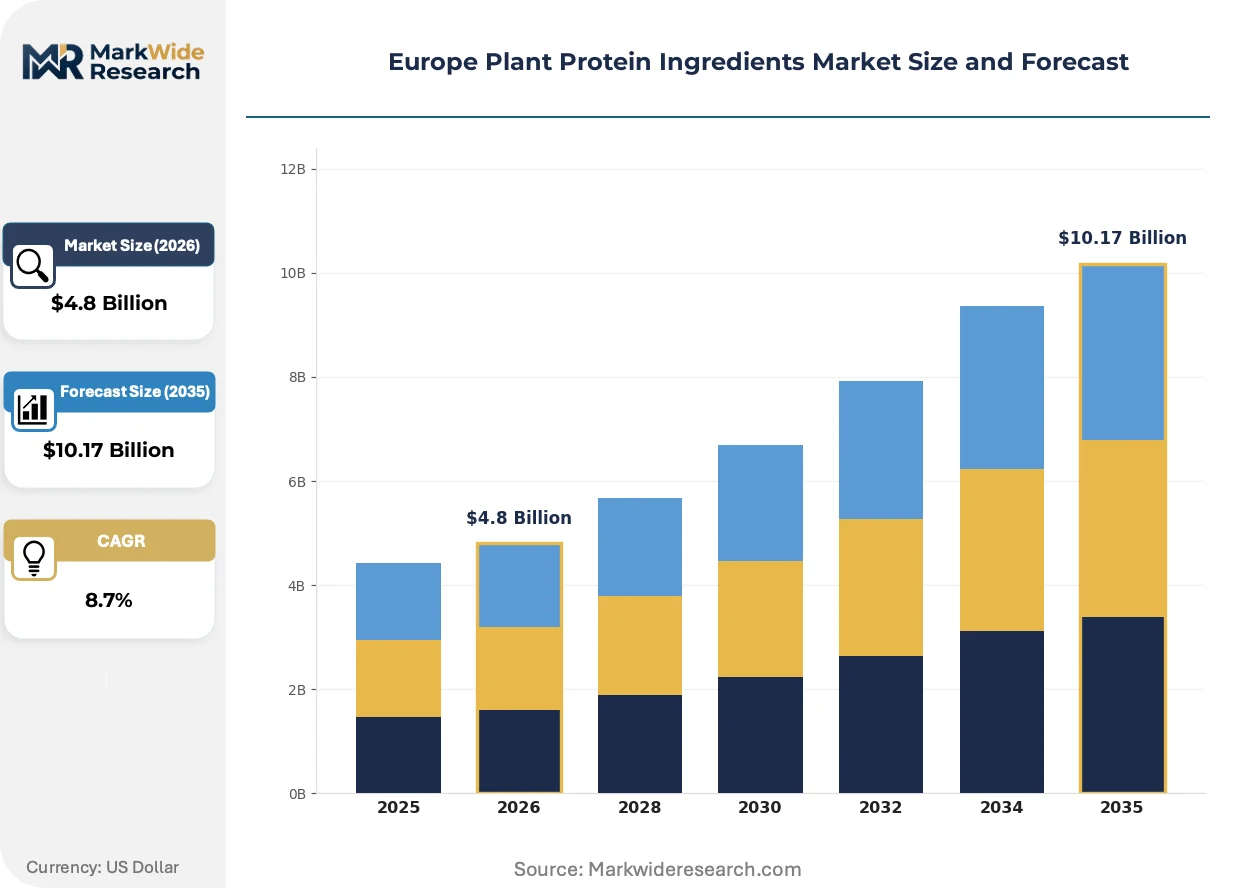
Market Dynamics
Modular ingredient bundling is hardening procurement patterns across mid-sized European food manufacturers, compressing supplier lists and rewarding processors capable of delivering turnkey protein-fat-flavor systems rather than commodity isolates.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Binding emissions reduction mandates force reformulation toward lower-carbon protein inputs, accelerating pea and fava bean isolate adoption in dairy alternatives.
- EFSA novel protein safety pathways:Streamlined evaluation frameworks for fermented and precision-fermented proteins reduce time-to-market for next-generation ingredients.
- Germany's processing cluster density:Concentrated extrusion and fractionation infrastructure in Lower Saxony and Bavaria shortens logistics loops for Benelux and Scandinavian buyers.
Market Restraints
- Pea protein input cost volatility:Yellow pea futures fluctuate with Black Sea origination disruptions and Canadian prairie weather patterns, compressing processor margins.
- EFSA protein quality scoring uncertainty:Pending digestibility-corrected amino acid score (DIAAS) implementation creates formulation risk for nutrition-positioned products.
- European extrusion capacity concentration:Textured protein supply depends on a handful of specialized processors in France and the Netherlands, creating single-source vulnerability.
Strategic Opportunities
- Poland and Romania food manufacturing expansion:Greenfield plant protein processing investments serve Central European meat alternative production growth with lower energy costs than Western Europe.
- EU digital product passport mandates:Upcoming traceability requirements favor suppliers with blockchain-enabled origination tracking, creating certification-based differentiation.
- Precision fermentation-alternative protein convergence:Microbial biomass proteins integrated with conventional extrusion expand texture and functionality beyond plant-only systems.
Industry Challenges
- REACH compliance for extraction solvents:Registration and authorization timelines for novel fractionation chemicals delay process innovation deployment by 18-36 months.
- Protein technologist talent scarcity:European universities produce insufficient graduates with combined food science and extrusion engineering expertise to staff expanding R&D facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Plant Protein Ingredients Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolates, Concentrates, Textured Protein, Hydrolysates Source: Pea, Soy, Wheat, Rice End User: Food & Beverage, Nutritional Supplements, Animal Feed, Bakery Products Application: Meat Alternatives, Dairy Alternatives, Protein Enrichment, Bakery Applications |
| Companies Covered | Archer Daniels Midland Company, Ingredion Incorporated, Roquette Frères, Cargill Incorporated, Kerry Group PLC, Südzucker AG, Emsland Group, International Flavors & Fragrances Inc, Lantmännen, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Plant Protein Ingredients Market Shifts & Advancements
Technology convergence, regulatory digitization, and procurement centralization are simultaneously reshaping how European food manufacturers source, formulate, and certify plant protein ingredients.
Fermentation-derived functional proteins are converging with conventional extrusion infrastructure to enable hybrid meat analogues with improved fibrous texture and reduced off-flavor burden. Mid-sized European brands in Germany and the Netherlands are piloting these systems at commercial scale. The structural consequence is compression in standalone isolate demand as buyers prefer pre-optimized protein systems.
REACH authorization requirements for processing aid chemicals are tightening solvent recovery and waste handling standards across protein fractionation facilities. Industrial consequence includes capital redirection toward closed-loop extraction systems and aqueous fractionation methods. Italian and Spanish olive and sunflower protein processors are most affected, accelerating partnerships with engineering firms specializing in membrane filtration retrofits.
Consolidated procurement desks at pan-European food manufacturers are unbundling historical supplier relationships in favor of multi-year framework agreements with traceability guarantees. Direct sourcing from origination cooperatives is replacing layered distributor networks for high-volume pea and fava bean contracts. This pattern is most visible in France, where retail private-label meat alternative programs demand single-point accountability from field to finished ingredient.
Europe Plant Protein Ingredients Market Segmentation
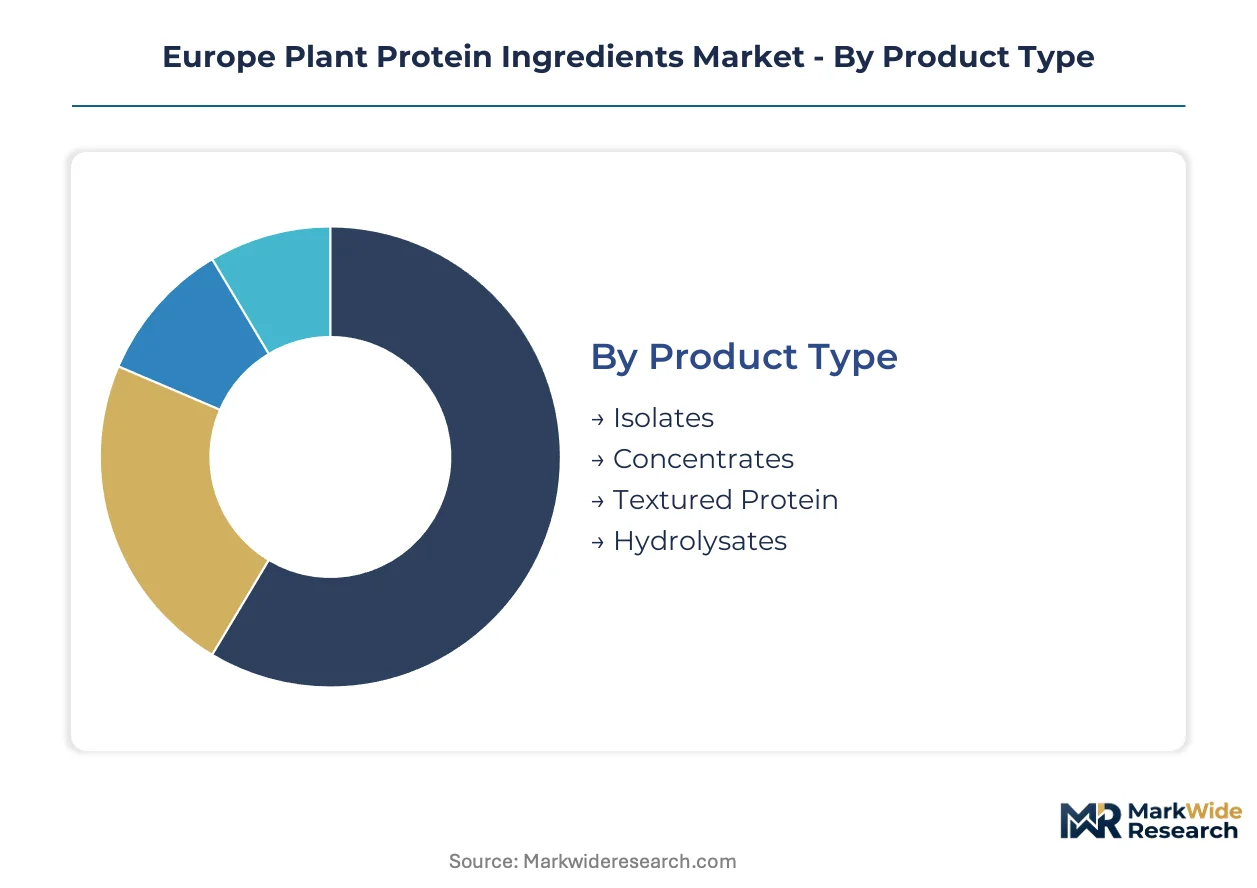
Plant protein ingredient purchasing in Europe stratifies sharply by technical performance requirements and regulatory exposure. Buyers select protein formats based on formulation complexity, end-product positioning, and sustainability certification needs rather than commodity pricing alone.
Product Type:
Margin capture and functional versatility separate procurement decisions across protein formats.
- Isolates:Protein contents exceeding 85% enable superior emulsification and gelation in dairy alternatives. German and Dutch dairy alternative manufacturers drive demand for pea and soy isolates with EU Green Deal-aligned carbon accounting.
- Textured Protein:Extruded fibrous structures replicate meat mouthfeel through controlled denaturation and alignment. French and Dutch extrusion specialists supply meat analogue producers with turnkey textured systems that shorten customer formulation cycles.
- Concentrates:Intermediate protein levels suit cost-sensitive bakery and snack applications where full isolate performance is unnecessary.
- Hydrolysates:Pre-digested peptides serve specialized nutritional supplements and clinical nutrition with rapid amino acid absorption profiles.
Volume sits with concentrates; growth tilts toward isolates.
Source:
Allergen labeling and GMO avoidance reshape origination preferences faster than agronomic yields.
- Pea:Non-allergenic status and European cultivation suitability displace soy in clean-label formulations. French and Baltic pea processors expand fractionation capacity to serve German meat alternative brands.
- Soy:Established supply chains and cost advantages retain volume in conventional applications despite GMO disclosure requirements. Spanish and Italian processors dominate European soy isolate production.
- Wheat:Gluten-containing proteins serve bakery applications where viscoelastic functionality is essential rather than meat or dairy alternatives.
- Rice:Hypoallergenic properties command premium positioning in infant nutrition and sensitive dietary products with limited volume scale.
Procurement weight rests with soy; expansion concentrates in pea.
End User:
Formulation sophistication and regulatory scrutiny intensity diverge across customer categories.
- Food & Beverage:Meat and dairy alternative manufacturers represent the dominant demand pool with complex multi-protein formulations and EFSA novel food compliance requirements. German, Dutch, and British brands lead reformulation investment.
- Nutritional Supplements:Sports nutrition and senior nutrition products demand higher protein purity with DIAAS scoring visibility pending EFSA implementation.
- Animal Feed:Pet food manufacturers adopt plant proteins for premium positioning with lower regulatory barriers than human food applications.
- Bakery Products:Partial egg and gluten replacement drives volume in industrial bread and pastry production with cost-driven procurement.
Revenue concentrates in Food & Beverage; Nutritional Supplements climb fastest.
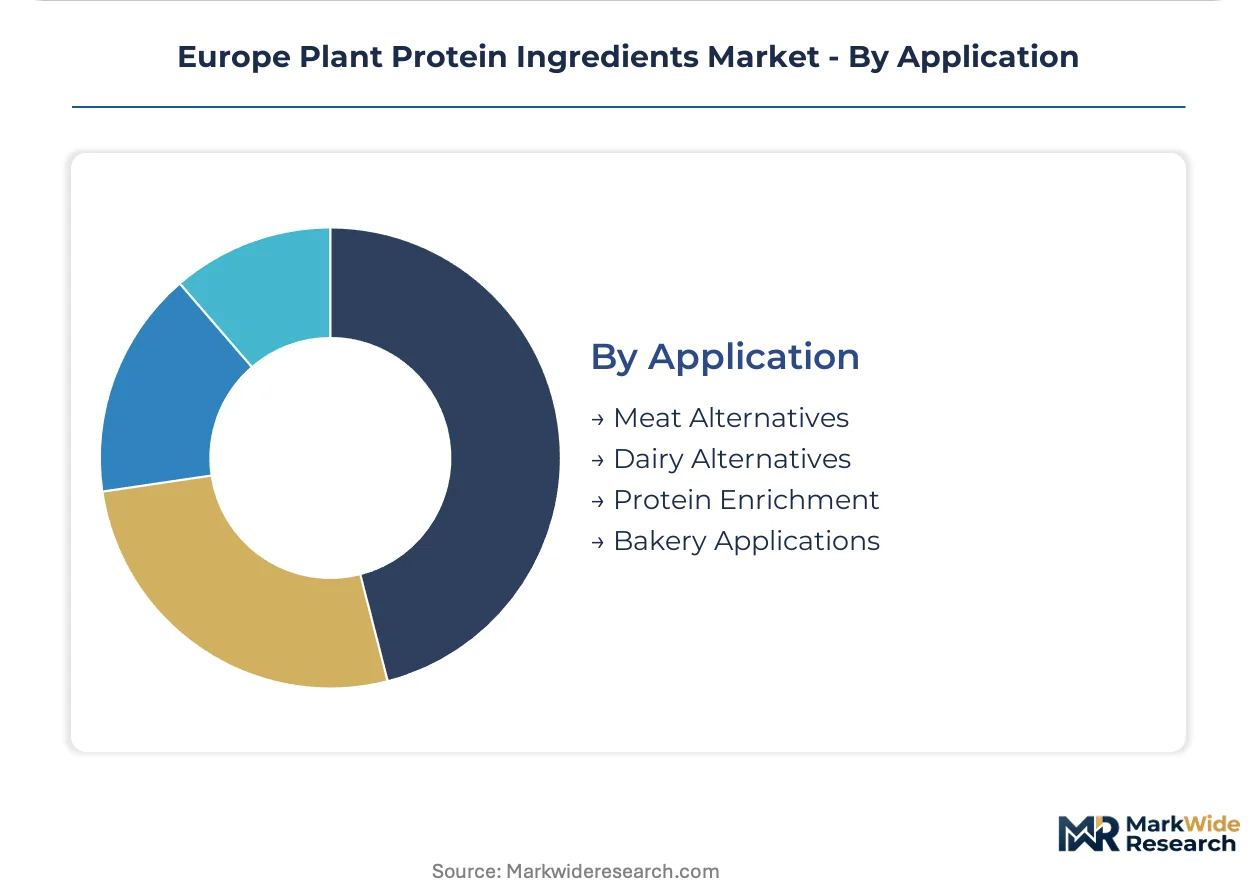
Application:
Texture replication difficulty and consumer sensory expectations determine protein format selection.
- Meat Alternatives:Fibrous texture requirements demand textured protein and isolate combinations with fermentation-derived flavor masking. Dutch and German brands pilot hybrid systems at commercial scale.
- Dairy Alternatives:Emulsion stability and mouthfat simulation drive isolate preference in oat and almond milk protein fortification.
- Protein Enrichment:Neutral-flavor concentrates serve snack and beverage fortification with minimal sensory modification.
- Bakery Applications:Dough conditioning and egg replacement utilize wheat and pea concentrates with established functionality profiles.
Investment flows toward meat alternatives; dairy alternatives hold installed volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Lower Saxony and Bavaria concentrate European plant protein processing capacity, with tax incentives for clean-tech manufacturing accelerating facility siting decisions. Benelux logistics hubs and Scandinavian demand centers orbit these German processing clusters.
Germany
Meat alternative brands in Berlin and Hamburg drive isolate demand for reformulated burger and sausage applications. The EU Green Deal farm-to-fork emissions targets force dairy alternative manufacturers toward pea protein sourcing with carbon accounting documentation. Lower Saxony hosts Roquette Frères' extrusion facilities supplying textured protein to pan-European customers.
Netherlands
Dutch food manufacturers pioneer hybrid fermentation-extrusion systems for next-generation meat analogues. REACH authorization timelines for novel extraction solvents delay aqueous fractionation adoption at Emsland Group processing sites. Wageningen anchors Europe's densest food science R&D corridor with university-industry protein functionality partnerships.
France
French retail private-label meat alternative programs demand single-point traceability from field to finished ingredient. EFSA novel food evaluation pathways for fermented proteins accelerate time-to-market for Paris-based ingredient startups. Roquette Frères dominates textured protein supply from its Lestrem processing complex in Hauts-de-France.
United Kingdom
British sports nutrition brands drive hydrolysate demand for rapid amino acid absorption products. Divergence from EU REACH frameworks creates parallel chemical registration requirements for protein fractionation solvents. Greater Manchester hosts Kerry Group PLC flavor-protein co-development services reducing customer formulation cycles.
Poland
Central European meat alternative production growth attracts greenfield plant protein processing investments with lower energy costs than Western Europe. EU digital product passport mandates favor Polish suppliers building blockchain-enabled origination tracking from Baltic Sea port logistics. Warsaw-based distributors serve expanding Romanian and Hungarian food manufacturing demand.
Europe Plant Protein Ingredients Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across ingredient supply tiers, creating a bifurcated market structure where scale-driven processors and technical specialists occupy distinct competitive positions. Tier-one suppliers command multi-year framework agreements with pan-European food manufacturers through traceability guarantees and turnkey protein-fat-flavor systems. Strategic archetypes include backward-integrated agricultural processors, extrusion technology specialists, and flavor-protein co-development service providers. Dominant competitive moves center on capacity expansion in Central European low-cost energy zones and strategic partnerships bridging fermentation-derived and conventional plant protein technologies.
Among France-based processors, Roquette Frères exemplifies the extrusion technology specialist archetype through decades of textured protein supply relationships. Cargill Incorporated occupies a position representing backward-integrated agricultural conglomerates with origination network control. Kerry Group PLC anchors the flavor-protein co-development service tier, reducing customer formulation complexity through integrated technical support.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Roquette Frères |
| Cargill Incorporated |
| Kerry Group PLC |
| Südzucker AG |
| Emsland Group |
| International Flavors & Fragrances Inc |
| Lantmännen |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap processors in France and the Netherlands anchor European textured protein supply, translating generational extrusion expertise into pricing discipline that resists commodity volatility. Their captive relationships with origination cooperatives in the Baltics and Black Sea basin insulate margin structures from spot-market pea price swings.
Pricing Analysis
Cost-down pressure on isolate tiers accelerates because German dairy alternative manufacturers negotiate multi-year framework agreements with carbon-accounting documentation requirements. Contract-based long-term offtake dominates procurement, with price differentiation hinging on EU Green Deal-aligned certification grade and volume scale. Pea protein faces acute buyer price sensitivity among mid-sized meat alternative brands in Poland and Romania, while premium-positioned Dutch hybrid fermentation-extrusion systems command lowest price elasticity.
Supply Chain Analysis
Workforce availability constraints in Lower Saxony and Bavaria extrusion corridors tighten operational flexibility at Roquette Frères and Emsland Group facilities. Supply concentrates in France, the Netherlands, and Germany, with raw material dependencies on Baltic yellow peas, Canadian prairie soy, and Black Sea fava beans. Single-source vulnerability pervades European extrusion capacity. Distribution runs through Benelux logistics hubs serving Scandinavian and British demand centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH authorization timelines for novel extraction solvents erect 18-36 month barriers that favor incumbent processors with established chemical registrations.
For Market Incumbents: Acquire aqueous fractionation engineering capabilities to preempt REACH-driven solvent restrictions. Secure backward integration into Baltic and Romanian pea origination networks before Central European processing capacity saturates. DIAAS scoring uncertainty from EFSA creates formulation risk that favors suppliers with in-house protein quality testing infrastructure. For New Entrants and Emerging Players: Enter via precision fermentation-extrusion hybrid technology partnerships with Wageningen corridor startups. Target Polish meat alternative manufacturers with lower energy-cost processing solutions. White-space concentrates in blockchain-enabled origination tracking for EU digital product passport compliance. For Investors and Strategic Acquirers: Distressed-cycle entries favor extrusion technology specialists with stranded capacity in French Hauts-de-France region. Long-term viability hinges on 5-10 year convergence between microbial biomass and conventional plant protein systems. Monitor EFSA novel protein safety pathway streamlining as inflection signal for fermentation-derived ingredient valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Origination Networks | Cargill's European pea and soy origination control secures supply priority during Black Sea disruptions. |
| Hybrid Fermentation-Extrusion Partnership | Dutch brands pilot microbial biomass integration with conventional extrusion at commercial scale. |
| Blockchain-Enabled Traceability Buildout | Polish suppliers leverage Baltic Sea port logistics for EU digital product passport compliance. |
| Aqueous Fractionation Capacity Retrofit | Italian and Spanish processors partner with membrane filtration engineering firms for REACH compliance. |
| Flavor-Protein Co-Development Service Expansion | Kerry Group's Greater Manchester facility reduces customer formulation cycles for British sports nutrition brands. |
Research Methodology
EFSA novel food safety filings, REACH chemical registration databases, and EU customs trade data formed the secondary backbone for this analysis. Primary interviews with protein fractionation plant managers, procurement leads at German meat alternative manufacturers, extrusion engineering specialists, and regulatory affairs directors at French ingredient processors combined with secondary validation. Bottom-up and top-down triangulation anchored volume estimates.
Bottom-up modeling traced isolate, concentrate, and textured protein demand through end-use applications and source crop origination patterns. Top-down cross-checks validated totals against EU Green Deal farm-to-fork emissions targets and EFSA protein quality scoring evolution. Segmentation dimensions included product format, legume source, end-user category, and application across the projection horizon. CAGRs derived from installed capacity expansion announcements and reformulation pipeline visibility at pan-European food manufacturers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Black Sea origination disruption scenarios and EFSA DIAAS implementation delays. Material deviation in REACH authorization timelines or EU AI Act traceability mandates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Potato Protein Market
Ingredients
India Olive Oil Market
Ingredients
Middle East & Africa Prebiotic Ingredients Market
Ingredients
France Soy Protein Market
Ingredients
Eucalyptus Oil Market
Ingredients
Stock Cubes Market
Ingredients
Global Organic Personal Care Ingredients Market
Ingredients
Pork Skin Gelatin Market
Ingredients
Soy Flour Market
Ingredients
Cocoa Fiber Market
Ingredients
Bread Flour Market
Ingredients
Middle East and Africa Lipids Market
Ingredients
Rennet Market
Ingredients
Halal and Kosher Empty Capsules Market
Ingredients
Roasted Grain Ingredients Market
Ingredients
South America Lipid Market