
 Tryptose Market | 2026-2036
Tryptose Market Size, Share, and Industry Trends Forecast 2026-2036
Tryptose Market Analytics
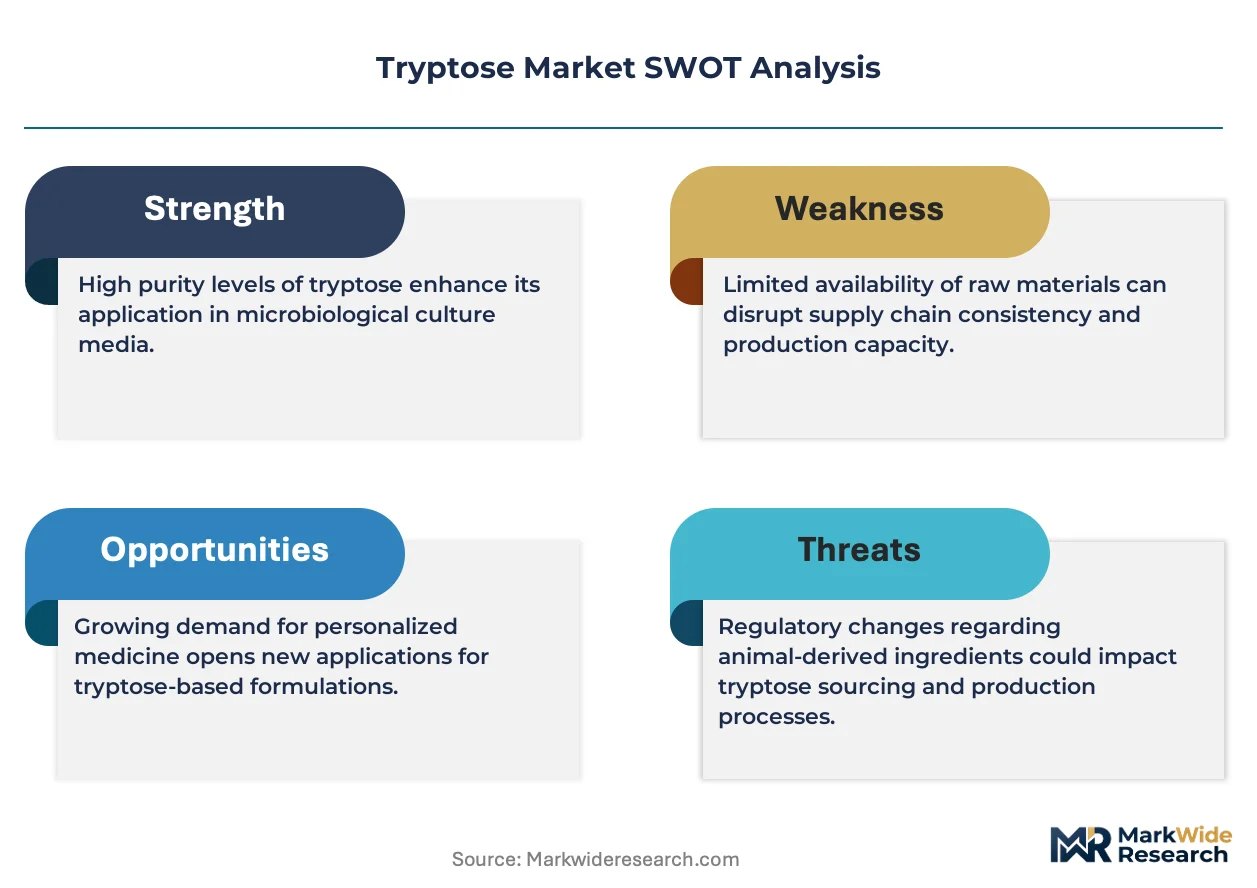
REACH compliance is rebalancing the cost-of-entry calculus for European tryptose suppliers, forcing reformulation investments and raw material traceability upgrades. Thermo Fisher Scientific leverages its captive supply chain to maintain cost discipline across pharmaceutical-grade batches. Sigma-Aldrich sustains pricing power through ISO-certified manufacturing protocols that exceed baseline regulatory floors. Merck Millipore anchors its position via deep backward integration into peptone sourcing, insulating margin structures from animal-derived raw material volatility.
Tryptose is a pancreatic digest of casein yielding a complex mixture of peptides and amino acids, typically standardized to support robust microbial propagation across pH ranges of 7.2 to 7.4. The material serves as a nitrogen-rich foundation in microbiological culture media, diagnostic reagent formulations, and industrial fermentation seed trains. Tryptose powder dominates current procurement volumes due to extended shelf stability and flexible reconstitution protocols, though liquid formats are gaining traction in high-throughput automated laboratories. Biochemical reactions represent the fastest-expanding application segment as enzyme manufacturers adopt tryptose-enriched buffers for recombinant protein expression workflows.
EMA guidelines on culture media quality for cell-based therapies, FDA oversight of diagnostic substrate consistency, and ISO 11133 standards for food microbiology testing collectively elevate product qualification burdens. These frameworks compel manufacturers to maintain batch-to-batch homogeneity records and endotoxin documentation that many legacy suppliers cannot readily produce. Stakeholders must evaluate whether their current quality infrastructure can absorb pending revisions to pharmacopeial monographs before committing to capacity expansion.
Market Dynamics
ISO 17025 accreditation requirements are compressing supplier margins while elevating barriers to entry for culture media manufacturers serving pharmaceutical and diagnostic end-uses.
Growth Catalysts
- EMA cell therapy guidelines:European pharmaceutical manufacturers are expanding tryptose procurement to meet endotoxin documentation requirements for cell-based therapy workflows.
- Enzyme manufacturing expansion:Recombinant protein expression protocols are incorporating tryptose-enriched buffers to improve yield consistency in biochemical reactions.
- German biotechnology clusters:Specialized life science hubs in Munich and Heidelberg are driving premium-grade tryptose consumption for vaccine production seed trains.
Market Restraints
- Animal-derived raw material volatility:Casein supply fluctuations from dairy markets create unpredictable input cost swings for pancreatic digest manufacturers.
- REACH compliance burden:European suppliers face reformulation investments and raw material traceability upgrades that extend qualification timelines.
- Soy peptone substitution:Plant-derived nitrogen sources are gaining traction in industrial fermentation applications with less stringent performance requirements.
Strategic Opportunities
- India CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Bengaluru are building new capacity requiring qualified culture media supply partnerships.
- Liquid format automation:High-throughput clinical laboratories are converting from powder reconstitution to ready-to-use liquid tryptose for robotic liquid handling systems.
- ISO 11133 harmonization:Food microbiology testing standardization across EU member states is creating demand for certified reference media with documented batch homogeneity.
Industry Challenges
- Endotoxin testing capacity:Manufacturers struggle to secure sufficient LAL reagent supply and trained analytical chemists for compendial testing protocols.
- Legacy batch record systems:Paper-based documentation infrastructure cannot readily generate the electronic audit trails required for pharmacopeial monograph revisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tryptose Market |
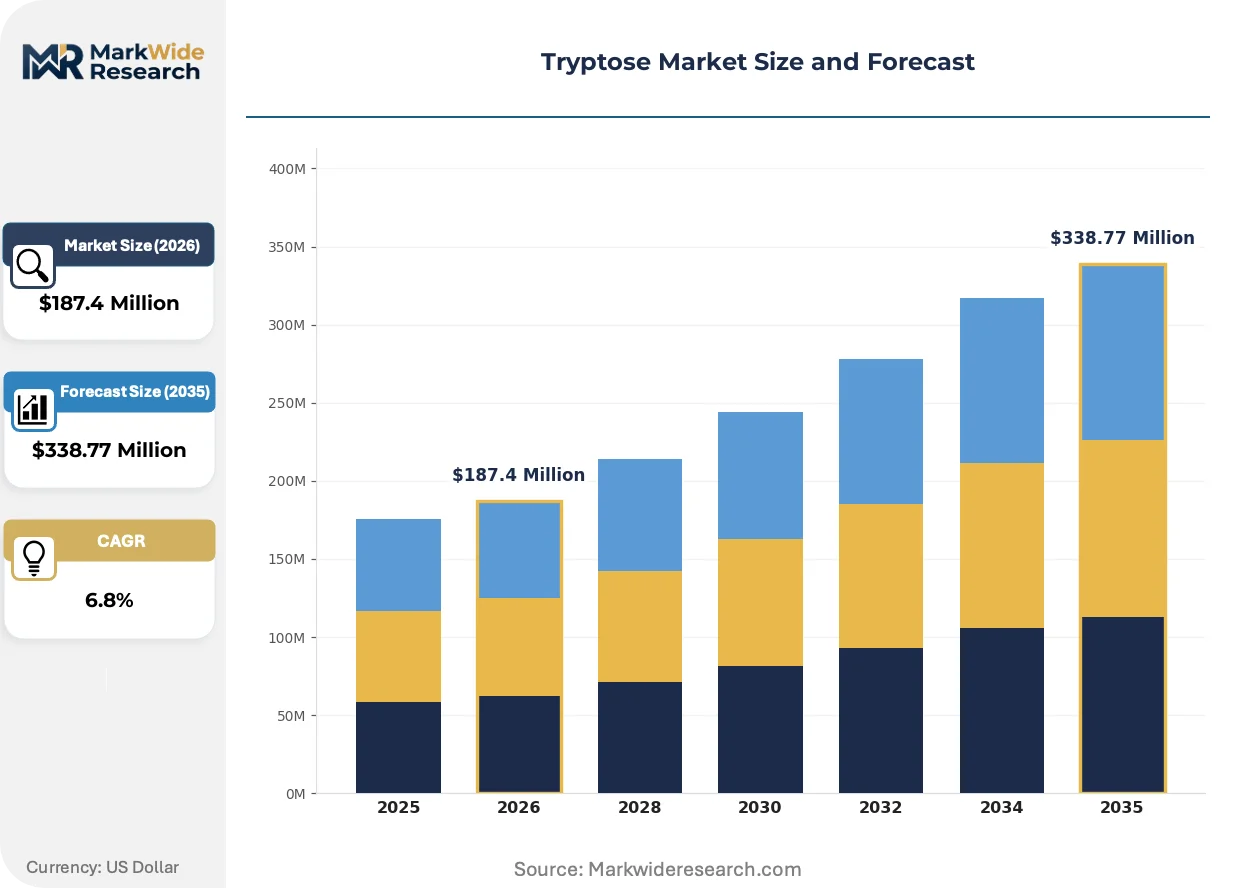
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tryptose Powder, Tryptose Liquid, Tryptose Tablets, Tryptose Capsules Application: Microbiological Culture, Cell Growth, Biochemical Reactions, Fermentation Processes End User: Pharmaceutical Companies, Research Institutions, Biotechnology Firms, Hospitals Distribution Channel: Online Sales, Direct Sales, Medical Supply Distributors, Wholesale Suppliers |
| Companies Covered | Thermo Fisher Scientific, Sigma-Aldrich, Becton Dickinson, Merck Millipore, Promega Corporation, Agilent Technologies, Sartorius AG, Novozymes, BIOZYM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tryptose Market Evolving Landscape
Synthetic biology workflows and automated manufacturing systems are redefining how nitrogen-rich culture media are formulated, qualified, and delivered to end-users.
Spray-dried tryptose microgranules are integrating into single-use bioreactor workflows to eliminate powder handling contamination risks. Vaccine manufacturers in Belgium and the Netherlands are adopting these formats for closed-system cell culture. This integration is compressing the traditional powder-to-liquid supply chain into integrated media delivery systems.
REACH substance registration deadlines are forcing European suppliers to disclose full supply chain compositions for animal-derived peptones. Culture media manufacturers must now document bovine spongiform encephalopathy compliance back to slaughterhouse origins. Diagnostic substrate producers in Germany and France are responding by qualifying secondary suppliers with pre-validated traceability systems.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships for mid-sized pharmaceutical firms. Hospital networks and research consortia in the United Kingdom are centralizing culture media buying through specialized life science distributors. This concentration is most visible in National Health Service pathology laboratories converting to sole-source agreements with ISO-certified suppliers.
Tryptose Market Segmentation
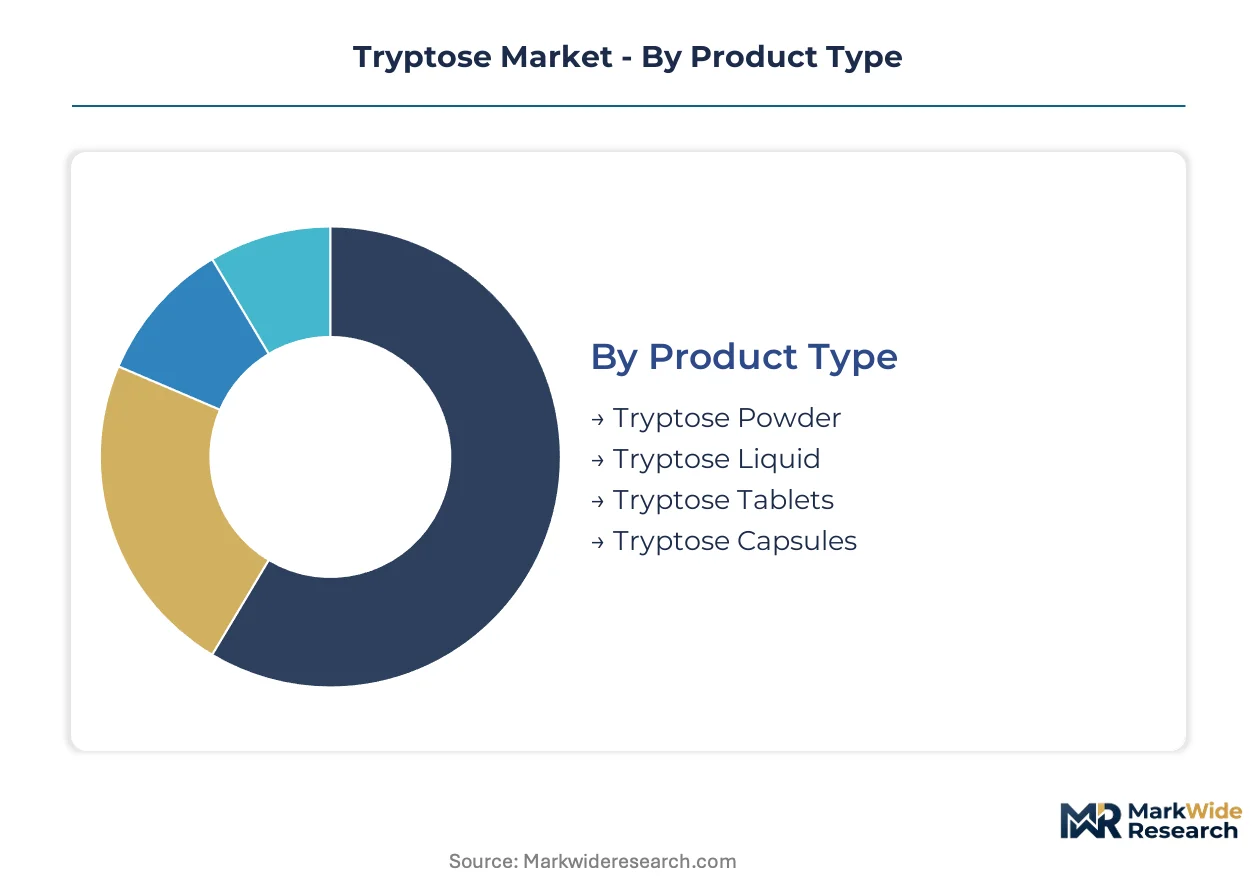
Tryptose procurement patterns diverge sharply across product formats and end-use workflows. Pharmaceutical manufacturers prioritize powder stability for long-horizon vaccine campaigns, while automated laboratories drive liquid format conversions. Understanding these segment boundaries clarifies where qualification investments yield competitive positioning.
Product Type:
Upgrade cycles favor formats that reduce contamination exposure and handling labor in high-throughput environments.
- Tryptose Powder:Spray-dried microgranules deliver extended shelf stability and flexible reconstitution protocols. Vaccine seed train operations in Belgium and the Netherlands favor this format for closed-system bioreactor integration.
- Tryptose Liquid:Ready-to-use solutions eliminate powder handling contamination risks in robotic liquid handling systems. High-throughput clinical laboratories in Germany are converting from powder reconstitution to liquid formats for automated workflows.
- Tryptose Tablets:Pre-measured solid dosage forms suit field microbiology testing with limited analytical infrastructure. Environmental monitoring teams in remote manufacturing sites utilize tablet formats for simplified preparation.
- Tryptose Capsules:Encapsulated variants target specialized fermentation applications requiring controlled nitrogen release. Niche enzyme manufacturers in Switzerland deploy capsule formats for extended culture runs.
Volume placements concentrate in Tryptose Powder; the faster expansion belongs to Tryptose Liquid.
Application:
Cost tier differentiation separates premium-qualified applications from commodity industrial uses with relaxed documentation requirements.
- Microbiological Culture:Standardized nitrogen-rich foundations support bacterial propagation across diagnostic and research protocols. ISO 11133 harmonization across EU member states is creating demand for certified reference media with documented batch homogeneity.
- Cell Growth:EMA guidelines on culture media quality for cell-based therapies impose endotoxin documentation burdens. European pharmaceutical manufacturers are expanding procurement to meet these qualification thresholds.
- Biochemical Reactions:Recombinant protein expression protocols incorporate tryptose-enriched buffers to improve yield consistency. Enzyme manufacturers are adopting these formulations for industrial-scale production.
- Fermentation Processes:Industrial seed trains utilize tryptose for microbial biomass amplification with less stringent performance requirements. Soy peptone substitution is gaining traction in this cost-sensitive segment.
Revenue concentration sits with Microbiological Culture; steepest expansion trajectory appears in Biochemical Reactions.
End User:
Customer type determines whether procurement flows through consolidated purchasing organizations or direct manufacturer relationships.
- Pharmaceutical Companies:Vaccine manufacturers require pharmacopeial-grade tryptose with full batch traceability and endotoxin documentation. REACH compliance is forcing these buyers to qualify secondary suppliers with pre-validated traceability systems.
- Research Institutions:Academic laboratories prioritize cost efficiency over exhaustive qualification for non-clinical applications. Group purchasing organizations are displacing direct manufacturer relationships for mid-sized research consortia.
- Biotechnology Firms:Cell therapy developers demand ISO-certified manufacturing protocols that exceed baseline regulatory floors. Specialized clusters in Munich and Heidelberg drive premium-grade consumption.
- Hospitals:Pathology laboratories convert to sole-source agreements with ISO-certified suppliers for diagnostic substrate consistency. National Health Service networks in the United Kingdom are centralizing buying through specialized life science distributors.
Procurement volume aggregates in Pharmaceutical Companies; Biotechnology Firms are climbing the fastest.
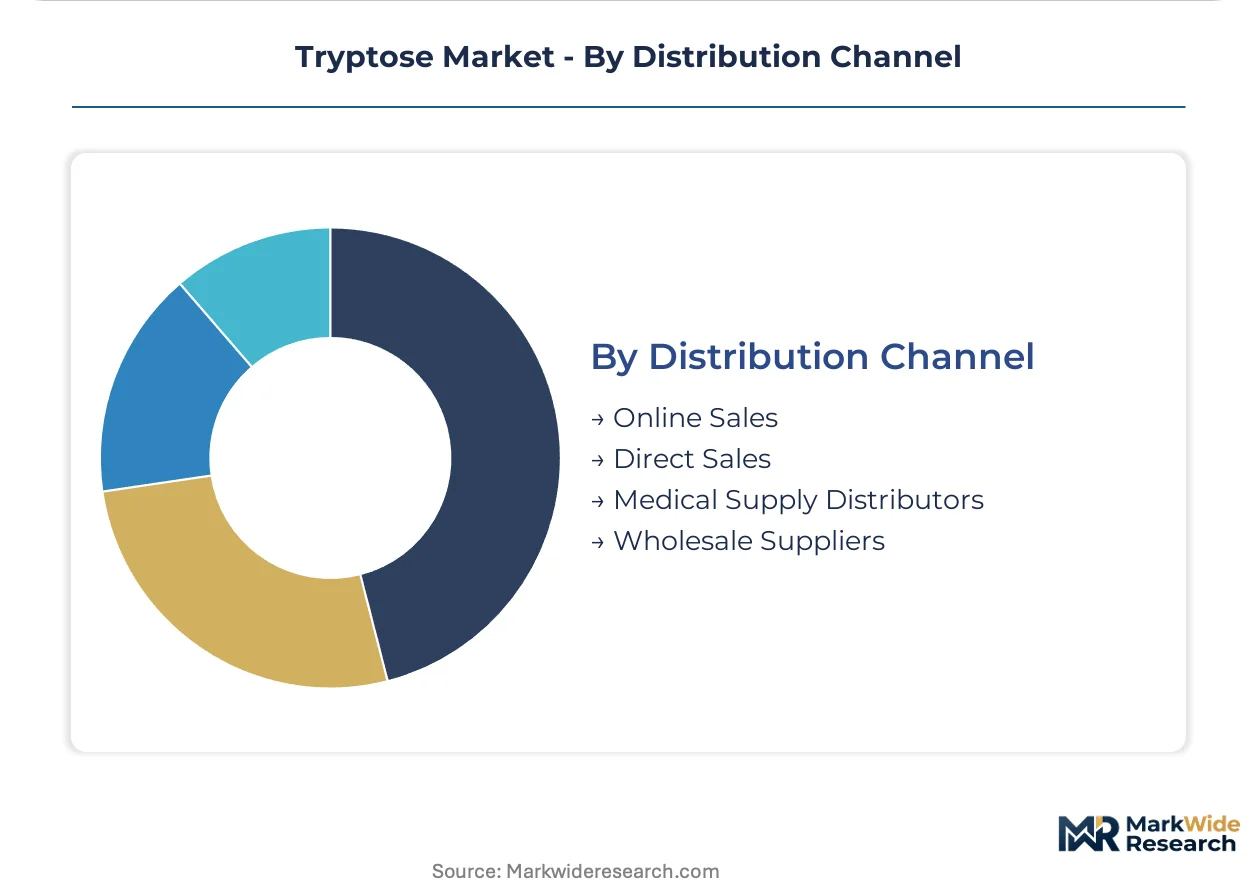
Distribution Channel:
Supply concentration shapes how qualification burdens and margin structures flow through intermediary layers.
- Online Sales:E-commerce platforms serve small-volume research customers with standard-grade products and limited technical support. Digital procurement is gaining share in academic and startup segments.
- Direct Sales:Manufacturer relationships persist for large pharmaceutical accounts requiring customized formulations and dedicated technical service. Thermo Fisher Scientific leverages captive supply chains to maintain cost discipline across direct channels.
- Medical Supply Distributors:Specialized life science distributors consolidate procurement for hospital networks and mid-sized pharmaceutical firms. These intermediaries absorb ISO 17025 accreditation compliance burdens on behalf of smaller buyers.
- Wholesale Suppliers:Bulk commodity channels serve industrial fermentation applications with standardized specifications and minimal documentation. Margin compression is most severe in this tier.
Transaction volume flows through Medical Supply Distributors; Direct Sales channels are gaining share fastest among qualified buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German biotechnology clusters anchor European tryptose procurement through specialized tax incentives for life science manufacturing zones. Munich and Heidelberg drive premium-grade consumption for vaccine production workflows. India CDMO expansion in Hyderabad and Bengaluru is reshaping supply chain geography.
United States
FDA oversight of diagnostic substrate consistency elevates documentation burdens for culture media suppliers. The National Institutes of Health procurement frameworks prioritize ISO-certified manufacturers with validated batch homogeneity records. Boston-Cambridge biotech corridor demands pharmacopeial-grade tryptose for cell therapy development pipelines.
Germany
EMA guidelines on culture media quality for cell-based therapies compel endotoxin documentation upgrades across pharmaceutical manufacturers. REACH substance registration deadlines force disclosure of full supply chain compositions for animal-derived peptones. Munich and Heidelberg clusters consume premium-grade tryptose for vaccine seed train operations.
Belgium
Vaccine manufacturers adopt spray-dried tryptose microgranules for closed-system bioreactor workflows. EMA cell therapy guidelines drive qualification investments in batch-to-batch homogeneity infrastructure. Antwerp-Ghent pharmaceutical corridor integrates single-use media delivery systems into automated manufacturing lines.
India
Contract development and manufacturing organizations in Hyderabad and Bengaluru build capacity requiring qualified culture media supply partnerships. CDSCO quality benchmarks for biologics manufacturing tighten raw material traceability requirements. Karnataka and Telangana life science parks attract multinational fermentation equipment installations.
United Kingdom
National Health Service pathology laboratories convert to sole-source agreements with ISO-certified suppliers for diagnostic substrate consistency. MHRA guidance on culture media for in-vitro diagnostics elevates qualification thresholds. Oxford-Cambridge biotech cluster drives demand for automated liquid handling-compatible tryptose formats.
Tryptose Market Competitive Landscape
German producers anchor one tier; US specialists hold differentiated positions through captive supply chain architectures. The supplier base concentrates around ISO 17025-accredited manufacturers with validated traceability systems. Three archetypes dominate: vertically integrated chemical conglomerates, specialized culture media pure-plays, and diversified life science distributors. Capacity expansion and strategic partnerships represent the dominant competitive vectors as qualification timelines extend.
Among diversified laboratory supply conglomerates, Thermo Fisher Scientific and Merck Millipore exemplify scale-driven positions with backward integration into peptone sourcing. Sigma-Aldrich occupies a specialist tier through ISO-certified manufacturing protocols. These three entities represent how quality infrastructure investments separate premium-tier suppliers from commodity competitors in pharmaceutical-grade segments.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Sigma-Aldrich |
| Becton Dickinson |
| Merck Millipore |
| Promega Corporation |
| Agilent Technologies |
| Sartorius AG |
| Novozymes |
| BIOZYM |
| Others |
Value Network & Pricing Analysis
Casein input costs cascade through pancreatic digest manufacturing into three distinct pricing tiers that separate pharmacopeial-grade batches from commodity industrial fermentation supplies. Dairy market volatility in Europe and North America transmits directly to tryptose procurement contracts, with REACH compliance investments adding fixed-cost layers that compress margins at the standard-grade tier.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as vaccine manufacturers in Belgium and the Netherlands pay significant markups for qualified inventory on 30-day delivery windows. Three-tier pricing structure across premium, standard, and economy levels separates ISO-certified pharmaceutical batches from research-grade powder and bulk fermentation inputs. Price differentiation hinges on endotoxin documentation depth and ISO 17025 accreditation status. Cost compression in the economy tier is intensifying because soy peptone substitutes erode volume commitments. Industrial fermentation buyers exhibit highest price sensitivity; cell therapy developers show least.
Supply Chain Analysis
Trained analytical chemist availability constrains manufacturing scale-up in Germany, Belgium, and the Netherlands where EMA-qualification requirements exceed regional labor pool depth. Supply concentrates in Germany and Belgium for premium-grade production; India and China anchor economy-tier fermentation media. Raw material dependencies center on dairy-derived casein, porcine pancreatic enzymes, and spray-drying energy inputs. Single-source vulnerability runs through bovine spongiform encephalopathy-compliant slaughterhouse traceability systems. Distribution runs through specialized life science distributors consolidating hospital network procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 17025 accreditation timelines are compressing weaker suppliers out of pharmaceutical-grade segments, creating acquisition opportunities for quality-infrastructure leaders. Consolidation pressure intensifies as batch homogeneity documentation requirements exceed legacy system capabilities.
For Market Incumbents: Acquire distressed ISO 17025-accredited manufacturing facilities in Germany and Belgium to absorb qualification capacity. Deepen backward integration into BSE-compliant casein sourcing to insulate margin structures from dairy volatility. Expand spray-dried microgranule production lines for single-use bioreactor integration demand. For New Entrants and Emerging Players: CDSCO quality benchmarks in India open a window for qualified culture media partnerships with Hyderabad and Bengaluru CDMOs. Target automated liquid handling format conversions in high-throughput German clinical laboratories. Penetrate through technical service bundling with robotic workflow integration support. For Investors and Strategic Acquirers: Distressed-cycle entries favor ISO-certified pure-play culture media specialists in German biotechnology clusters with validated endotoxin testing infrastructure. Long-term viability centers on regulatory moat sustainability through pharmacopeial monograph alignment. Watch for LAL reagent supply constraints as inflection signal for testing capacity scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Peptone Sourcing | Merck Millipore's captive supply chain insulates margins from animal-derived raw material volatility. |
| ISO 17025 Accreditation Investment | Sigma-Aldrich exceeds baseline regulatory floors through certified manufacturing protocols. |
| Liquid Format Automation Partnership | Thermo Fisher Scientific serves robotic liquid handling demand in German high-throughput laboratories. |
| India CDMO Supply Agreement | Hyderabad and Bengaluru capacity builds require qualified culture media partnerships with traceability documentation. |
| Spray-Dried Microgranule Capacity Expansion | Belgian and Dutch vaccine manufacturers adopt closed-system bioreactor integration formats. |
Research Methodology
Multi-period observation of EMA guideline implementation timelines, REACH registration deadlines, and ISO 11133 harmonization progress anchored the trend analysis, supplemented by interviews with culture media manufacturing executives, pharmaceutical procurement directors, diagnostic laboratory managers, and fermentation process engineers. Secondary validation drew from FDA warning letter databases, EMA inspection outcome reports, CDSCO biologics guidance documents, and customs trade flows for pancreatic digest classifications. Bottom-up volume estimates from end-use application segments triangulated against top-down manufacturer capacity assessments.
Segment-weighting across product format, application workflow, end-user archetype, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from modeled adoption curves for liquid format conversion and biochemical reaction applications. Forecast inputs incorporated CDMO capacity buildout schedules in India, spray-dried microgranule integration rates in Belgian vaccine facilities, and soy peptone substitution elasticities in industrial fermentation.
The model assumes a particular technology adoption path for automated liquid handling systems; alternative pathways for powder reconstitution robotics would alter the outlook. Forecasts reflect assumptions about REACH substance registration compliance timelines and LAL reagent supply stability. Material deviation in EMA pharmacopeial monograph revision schedules or bovine spongiform encephalopathy regulatory triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cheese Ingredients Market
Ingredients
Europe Fruit and Vegetable Ingredients Market
Ingredients
Rose Hips Extract Market
Ingredients
South America Fruit and Vegetable Ingredients Market
Ingredients
Chickpea Protein Ingredients Market
Ingredients
North America Sodium Reduction Ingredients Market
Ingredients
Global Protein Hydrolysate Ingredients Market
Ingredients
United States Corn Glucose Market
Ingredients
Coconut Cream Powder Market
Ingredients
RTD/High Strength Premixes Market
Ingredients
Chickpea Protein Market
Ingredients
Omega-3 Encapsulation Market
Ingredients
Anhydrous Caffeine Market
Ingredients
North America Plant Protein Ingredients Market
Ingredients
Encapsulated Ingredients Market
Ingredients
Glucuronolactone Market