
 Sugar Free Cookies Market | 2026-2036
Sugar Free Cookies Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Free Cookies Market Analysis
Aftermarket recipe licensing revenue is fragmenting as branded manufacturers build in-house zero-sugar capabilities. Burton's Biscuit Company anchors British retail shelf presence through direct store delivery networks. Galletas Gullon leverages Mediterranean ingredient sourcing to compete on clean-label positioning. Fat Snax specializes in direct-to-consumer channels that bypass traditional wholesale markups.
Sugar free cookies are baked goods formulated without sucrose, typically employing bulking agents like erythritol or stevia glycosides to achieve comparable texture and browning reactions in dough matrices. Commercial production requires modified thermal profiles to compensate for altered moisture retention and Maillard reaction kinetics. Chocolate chip and peanut butter variants occupy the core volume tier, while coconut macaroon formats command premium positioning through almond flour ingredient costs. Erythritol-based formulations lead ingredient-type momentum due to cooling-effect masking improvements and digestive tolerance profiles.
The FDA governs sugar-free labeling claims and sweetener GRAS determinations in the United States, while EFSA establishes acceptable daily intake thresholds for polyols across European formulations. India's FSSAI and CDSCO scrutinize novel sweetener imports, creating compliance barriers for multinational cookie brands entering that market. Stakeholders must monitor evolving WHO sugar reduction guidelines and patchwork national sweetener approvals that determine which ingredient portfolios travel across borders.
Market Dynamics
The sugar free cookies market pivots on FDA and EFSA sweetener approval cycles, which determine which polyol formulations manufacturers can deploy across Atlantic supply chains without triggering relabeling costs or import holds.
Growth Catalysts
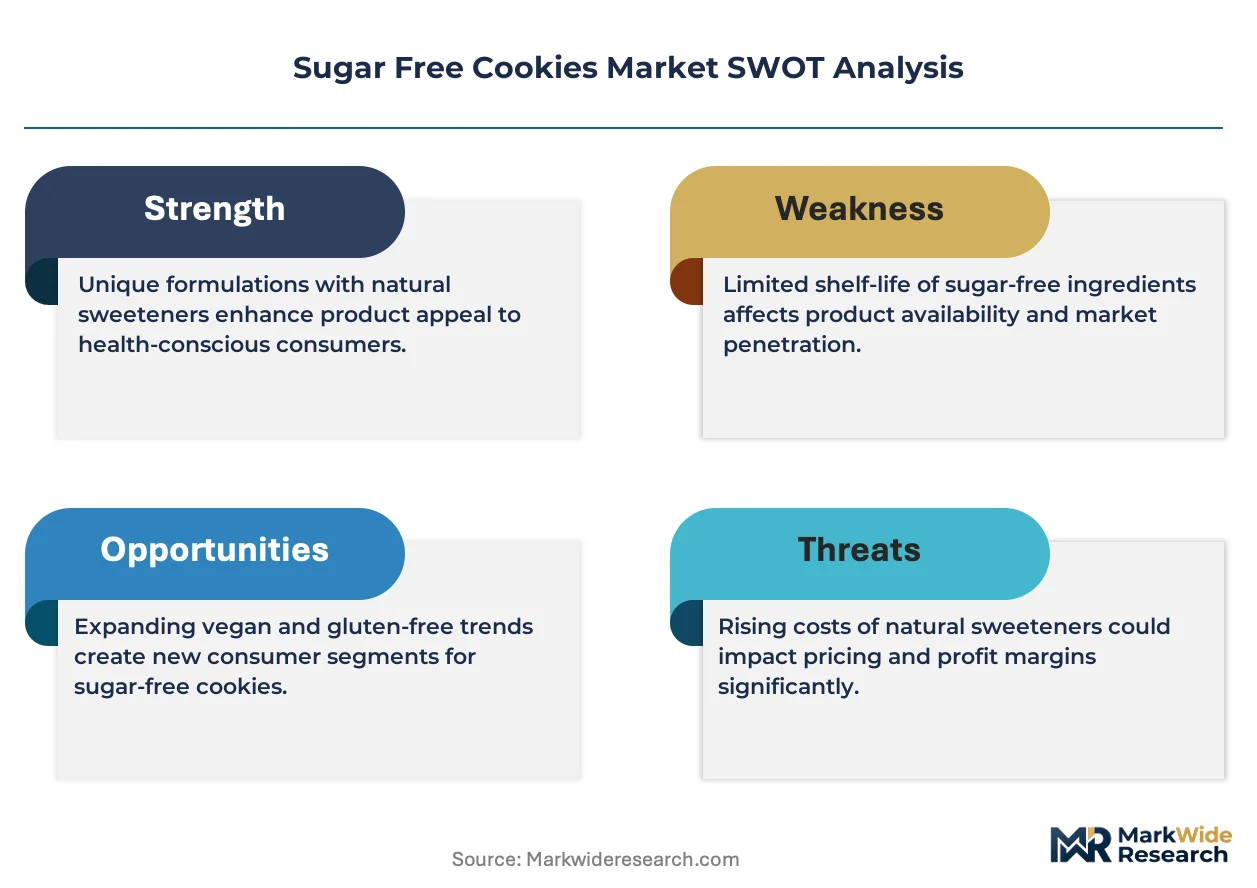
- Erythritol GRAS expansion:FDA rulings on high-purity erythritol variants unlock cleaner-label positioning for US bakery brands seeking to displace maltitol in chocolate chip formats.
- Almond flour cost curves:California and Spanish orchard expansions compress nut flour input prices, enabling premium macaroon SKUs to migrate from specialty to mass retail.
- German reformulation mandates:The country's federal nutrition strategy pressures conventional cookie producers to develop zero-sugar alternatives for school and hospital procurement channels.
Market Restraints
- Stevia supply concentration:Chinese stevia leaf processing controls 70% of global Reb-A supply, exposing formulators to tariff volatility and currency swings.
- Polyol digestive labeling:EFSA mandatory laxative warnings on maltitol and sorbitol packages deter impulse purchases in European convenience retail.
- Thermal profile retrofit costs:Existing tunnel ovens require humidity control upgrades to handle erythritol's faster moisture release without cracking dough matrices.
Strategic Opportunities
- Indian FSSAI pathway navigation:First-movers establishing novel sweetener dossiers with CDSCO can preempt multinational competitors in a 1.4 billion consumer market.
- Direct-to-consumer subscription:Monthly cookie box models bypass slotting fee barriers that freeze out emerging brands from Kroger and Tesco shelf resets.
- Clean-label convergence:Pairing monk fruit with prebiotic fibers addresses both sugar reduction and gut health positioning in US natural channel expansion.
Industry Challenges
- Maillard reaction engineering:Food science talent capable of calibrating browning kinetics without sucrose remains scarce relative to conventional bakery R&D pools.
- Cross-contamination protocols:Shared production lines require validated cleaning procedures to satisfy FDA gluten-free and sugar-free dual certification audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Free Cookies Market |
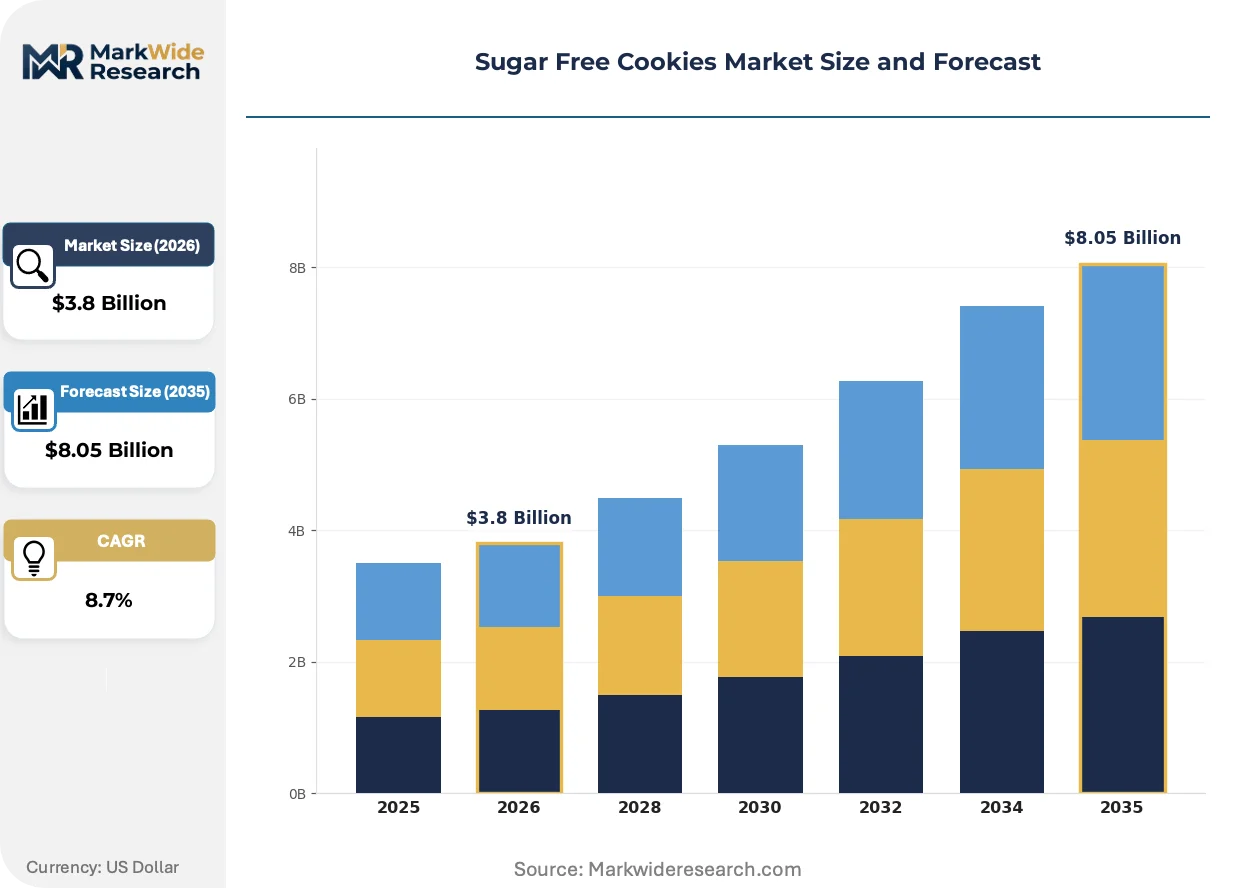
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate Chip, Oatmeal Raisin, Peanut Butter, Coconut Macaroon Ingredient Type: Almond Flour, Coconut Sugar, Stevia, Erythritol Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops Customer Type: Health-conscious Consumers, Diabetics, Fitness Enthusiasts, Families |
| Companies Covered | Burton's Biscuit Company, Fat Snax, Aunt Gussie's Cookies & Crackers, Diabliss Consumer Products Pvt. Ltd., Good Dees, Baker Street, Galletas Gullon, Voortman Bakery, Bisk Farm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Free Cookies Market Emerging Trajectories
Formulation science and channel architecture are rewriting competitive rules in sugar free cookies, with thermal engineering advances and regulatory arbitrage creating distinct winners across geographies.
Enzymatic browning accelerants are collapsing the sensory gap between erythritol-sweetened and sucrose-based cookies. Premium US brands are adopting these enzyme systems to achieve comparable crust color without caramelization byproducts. The technology is collapsing the premium pricing umbrella that almond-flour macaroons previously commanded on visual appeal alone.
EFSA's 2023 revised acceptable daily intake framework for polyols is forcing reformulation timelines across European manufacturing. The regulation compresses allowable sorbitol percentages in single-serve packages, pushing manufacturers toward erythritol-allulose blends. German and Dutch producers are accelerating pilot trials to maintain shelf presence ahead of 2025 enforcement windows.
Hospital and corporate cafeteria procurement is consolidating around certified low-glycemic index specifications. Foodservice distributors are replacing open-stock cookie offerings with contracted single-source supply agreements. This pattern is most visible in US healthcare systems where CMS reimbursement metrics now incorporate patient glycemic management outcomes.
Sugar Free Cookies Market Segmentation
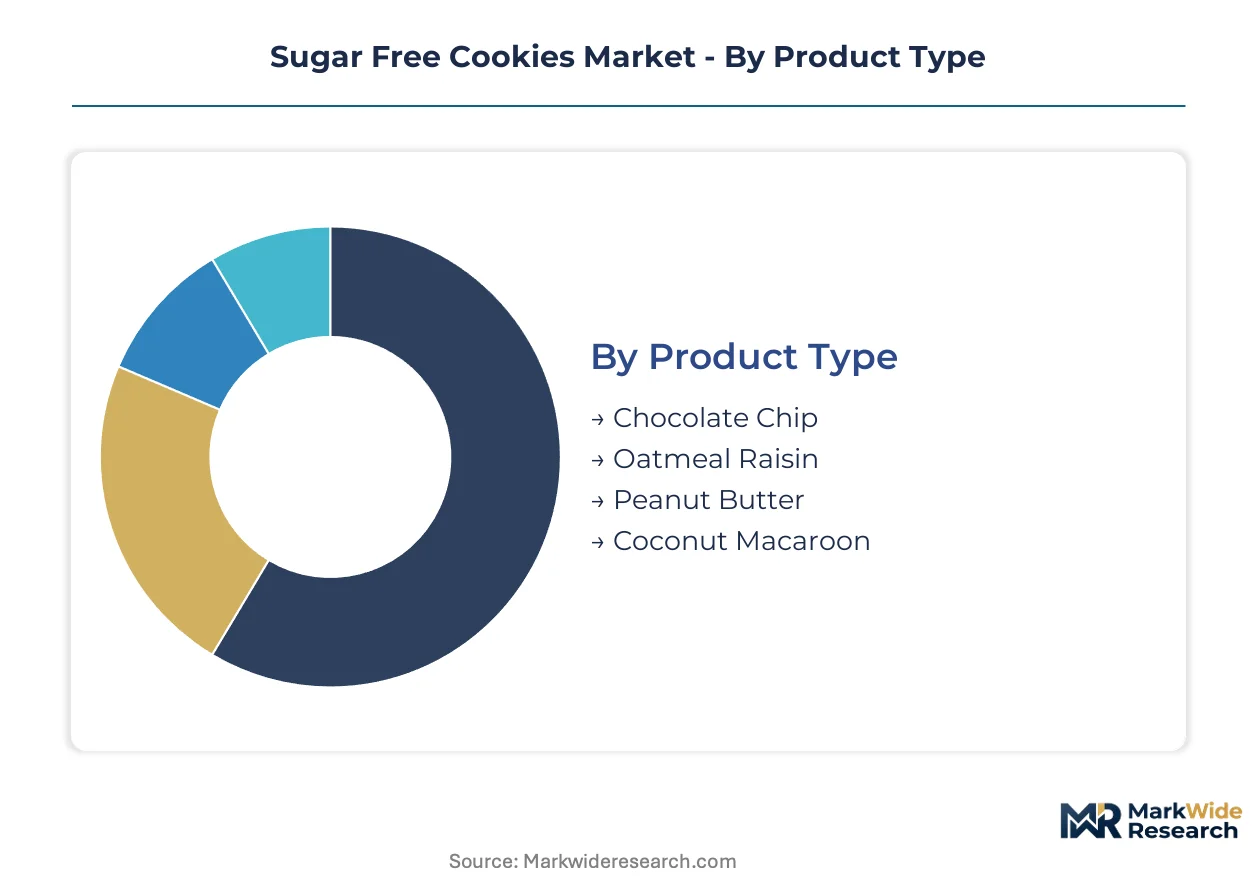
Sugar free cookie manufacturers engineer distinct product architectures around thermal processing constraints and glycemic positioning. Each segment category demands specialized formulation expertise, from Maillard reaction calibration to sweetener GRAS compliance across FDA and EFSA jurisdictions.
Product Type:
After-sales formulation support varies sharply by product complexity, with macaroon variants requiring ongoing technical assistance for moisture control troubleshooting.
- Chocolate Chip:Erythritol-sweetened dough matrices with modified thermal profiles compensate for absent sucrose caramelization. Demand clusters in US mass retail channels where Burton's Biscuit Company and Fat Snax compete on clean-label positioning.
- Peanut Butter:High-fat formulations mask cooling effects from polyol sweeteners while delivering dense texture profiles. German and Dutch manufacturers are accelerating production trials ahead of EFSA's revised polyol intake frameworks.
- Oatmeal Raisin:Fiber-forward positioning targets prebiotic health claims in natural channel expansion.
- Coconut Macaroon:Almond flour cost curves determine premium tier accessibility.
By volume, Chocolate Chip leads. By growth pace, Coconut Macaroon is ahead.
Ingredient Type:
Cost tier stratification separates commodity polyols from premium nut flour inputs, with California and Spanish orchard economics reshaping competitive access.
- Erythritol:High-purity variants achieve FDA GRAS status for cleaner-label positioning, displacing maltitol in chocolate chip formats. US bakery brands prioritize this polyol for digestive tolerance profiles and cooling-effect masking improvements.
- Almond Flour:Nut flour premiums compress as orchard expansions in California and Spain enable mass retail migration from specialty positioning. Mediterranean sourcing clusters give Galletas Gullon cost advantages in European clean-label competition.
- Stevia:Chinese leaf processing concentration exposes formulators to tariff volatility.
- Coconut Sugar:Lower glycemic indexing supports natural channel placement.
By volume, Erythritol leads. By margin expansion, Almond Flour is climbing fastest.
Distribution Channel:
Customer acquisition economics diverge between slotting-fee barriers in conventional retail and subscription lifetime value in direct channels.
- Online Retail:Monthly cookie box models bypass Kroger and Tesco slotting fees that freeze emerging brands from shelf resets. Fat Snax specializes in this channel architecture, capturing recurring revenue through DTC subscription mechanics.
- Supermarkets:Direct store delivery networks anchor British retail presence for established manufacturers like Burton's Biscuit Company, with hospital and corporate cafeteria procurement consolidating around certified low-glycemic specifications.
- Health Food Stores:Natural channel placement rewards monk fruit and prebiotic fiber convergence.
- Specialty Shops:Premium macaroon SKUs command almond flour ingredient cost premiums.
By volume, Supermarkets lead. By customer lifetime value, Online Retail is expanding most quickly.
Customer Type:
Application-specific glycemic requirements separate medical-nutrition procurement from discretionary wellness purchasing.
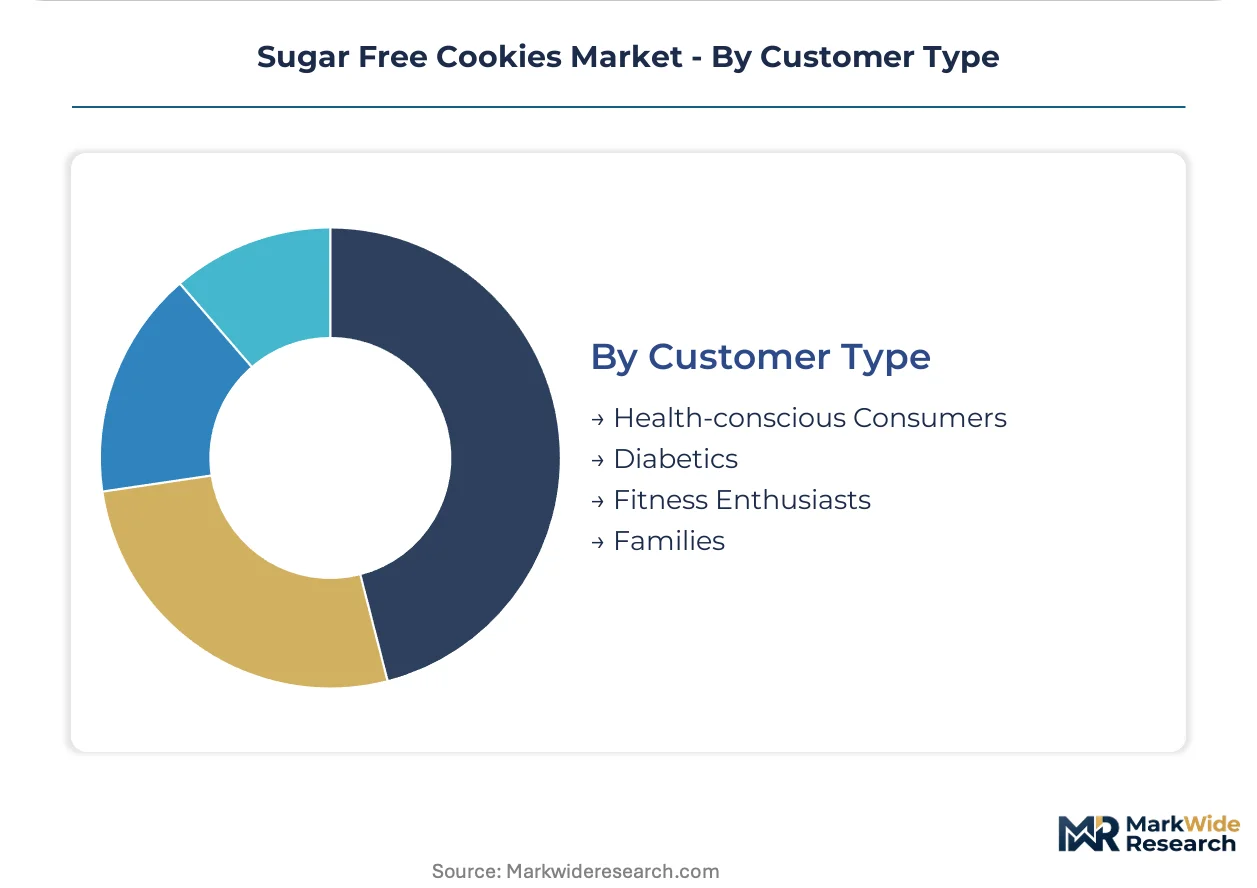
- Diabetics:CMS reimbursement metrics in US healthcare systems now incorporate patient glycemic management outcomes, driving foodservice distributor consolidation around contracted single-source supply agreements for certified low-GI cookies.
- Health-conscious Consumers:Clean-label convergence targets simultaneous sugar reduction and gut health positioning through erythritol-allulose blends and prebiotic fiber fortification in German and US natural channels.
- Fitness Enthusiasts:Macro-tracking precision demands transparent polyol net carb labeling.
- Families:School procurement channels in Germany face federal nutrition strategy pressure for zero-sugar alternatives.
By volume, Health-conscious Consumers lead. By contract value concentration, Diabetics is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Almond flour milling capacity clusters in California's Central Valley and Spain's Levante region, with erythritol fermentation capacity expanding in Chinese biotech corridors. FDA and EFSA regulatory divergence is fragmenting formulation standards across Atlantic supply chains.
United States
FDA GRAS rulings on high-purity erythritol variants unlock cleaner-label positioning for bakery brands seeking maltitol displacement in chocolate chip formats. CMS reimbursement metrics now incorporate patient glycemic management outcomes, driving foodservice distributor consolidation around certified low-GI supply agreements. California's almond orchard expansions compress nut flour input prices, enabling premium macaroon SKUs to migrate from specialty to mass retail channels.
Germany
Federal nutrition strategy mandates pressure conventional cookie producers to develop zero-sugar alternatives for school and hospital procurement channels. EFSA's revised acceptable daily intake framework for polyols compresses allowable sorbitol percentages in single-serve packages, forcing reformulation toward erythritol-allulose blends. North Rhine-Westphalia's industrial bakery clusters accelerate pilot trials to maintain shelf presence ahead of 2025 enforcement windows.
United Kingdom
Direct store delivery networks anchor British retail shelf presence for established manufacturers competing on clean-label positioning. NHS procurement guidelines increasingly specify low-glycemic index certifications for patient and staff catering contracts. Burton's Biscuit Company leverages Midlands-based production infrastructure to serve both supermarket multiples and foodservice distributors.
India
FSSAI and CDSCO scrutiny of novel sweetener imports creates compliance barriers for multinational brands entering the 1.4 billion consumer market. First-movers establishing sweetener dossiers with central drug regulators can preempt competitors in institutional procurement channels. Maharashtra's packaged food manufacturing corridors see rising domestic production of erythritol-based formulations for diabetic and health-conscious urban consumers.
Spain
Mediterranean almond sourcing clusters give domestic producers cost advantages in European clean-label competition. EFSA mandatory laxative warnings on maltitol packages deter impulse purchases, accelerating consumer migration toward erythritol-sweetened alternatives. Valencia's ingredient processing hubs expand capacity to serve reformulation demand from German and Dutch bakery manufacturers.
Sugar Free Cookies Market Vendor Landscape
Direct-to-consumer specialists and conventional bakery conglomerates split the market along channel architecture lines, with subscription mechanics challenging slotting-fee barriers in traditional retail. The vendor base separates into three strategic archetypes: DTC-native brands bypassing wholesale markups, established manufacturers with direct store delivery networks, and Mediterranean-sourced clean-label positioning specialists. Competitive moves concentrate on geographic licensing partnerships and in-house zero-sugar capability building that fragments aftermarket recipe revenue streams.
Among DTC-channel specialists, Fat Snax exemplifies subscription-based customer acquisition mechanics that capture recurring revenue outside conventional supermarket resets. Burton's Biscuit Company and Galletas Gullon occupy positions within the established manufacturer tier, with the former representing British direct store delivery infrastructure and the latter anchoring Mediterranean ingredient sourcing advantages in European clean-label competition.
| Leading Market Players |
|---|
| Burton's Biscuit Company |
| Fat Snax |
| Aunt Gussie's Cookies & Crackers |
| Diabliss Consumer Products Pvt. Ltd. |
| Good Dees |
| Baker Street |
| Galletas Gullon |
| Voortman Bakery |
| Bisk Farm |
| Others |
Supply Flow & Price Mechanics
Chinese stevia leaf processing concentration controls seventy percent of global Reb-A supply, anchoring margin pools in erythritol-allulose blend formulations that US and European manufacturers are accelerating toward. FDA GRAS rulings on high-purity erythritol variants compress pricing premiums for cleaner-label positioning, while almond flour cost curves from California and Spanish orchards reshape premium tier accessibility.
Pricing Analysis
EFSA mandatory laxative warnings on maltitol and sorbitol packages dictate the pricing tier structure across European retail channels, forcing reformulation investment that stratifies erythritol-sweetened products at premium positioning against legacy polyol formats. Certification grade for low-glycemic index specifications separates hospital procurement contracts from mass retail SKUs, with German school and hospital channels commanding price premiums for documented glycemic outcomes. Cost compression in standard-tier chocolate chip formats is intensifying because California almond orchard expansions compress nut flour input prices, enabling premium macaroon SKUs to migrate downward. Health-conscious consumers in natural channels show least price sensitivity for monk fruit-prebiotic fiber convergence, while families in conventional supermarket channels exhibit highest elasticity.
Supply Chain Analysis
US export-control scrutiny of Chinese biotech corridors limits erythritol fermentation technology flows, constraining capacity expansion timelines for manufacturers seeking to displace maltitol-dependent formulations. Supply concentrates in Chinese stevia processing, Spanish and California almond milling, and German industrial bakery clusters. Raw material dependencies span Reb-A glycosides, high-purity erythritol crystals, and almond flour from Mediterranean and Central Valley sourcing. Single-source vulnerability in Chinese stevia leaf concentration exposes formulators to tariff volatility and currency swings. Distribution runs through direct store delivery networks anchoring British retail presence, monthly subscription models bypassing slotting fees, and foodservice distributor consolidation around certified low-GI supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against emerging allulose-stevia hybrid formulations that threaten erythritol's cleaner-label positioning, requiring rapid capability building to maintain formulation leadership.
For Market Incumbents: Harden thermal profile engineering capabilities to capture Maillard reaction calibration talent scarce relative to conventional bakery R&D pools. Deepen backward integration into almond flour milling through California orchard equity stakes or long-term offtake contracts with Spanish Levante processors. The allulose-stevia hybrid threat demands preemptive formulation pipelines, while EFSA's revised polyol intake frameworks compress reformulation windows to maintain European shelf presence. For New Entrants and Emerging Players: Maharashtra's packaged food manufacturing corridors offer underpenetrated institutional procurement channels where first-movers establishing FSSAI sweetener dossiers can preempt multinational competitors. Target diabetic and health-conscious urban consumers through direct-to-consumer subscription mechanics that bypass Kroger and Tesco slotting fee barriers freezing emerging brands from conventional resets. The most penetrable segment combines certified low-GI specifications with hospital and corporate cafeteria procurement consolidating around single-source supply agreements. For Investors and Strategic Acquirers: Capital is best deployed toward DTC-native brands with validated subscription unit economics and proprietary thermal processing IP, rather than conventional manufacturers burdened by tunnel oven retrofit costs for erythritol moisture release profiles. Long-term viability hinges on regulatory arbitrage capabilities across FDA, EFSA, and FSSAI jurisdictions, with five-to-ten year windows favoring formulators with multi-continent GRAS dossier expertise. The signal to watch is CDSCO approval velocity for novel sweetener imports, which would unlock institutional procurement scale in the 1.4 billion consumer market.| Strategic Initiative | Industry Significance |
|---|---|
| Erythritol GRAS Dossier Expansion | Unlocks cleaner-label positioning in FDA jurisdictions against maltitol-dependent competitors. |
| Almond Orchard Backward Integration | Captures cost compression from California and Spanish Levante nut flour expansions. |
| Direct-to-Consumer Subscription Launch | Bypasses Kroger and Tesco slotting fees that freeze emerging brands from shelf resets. |
| Hospital Procurement Certification | Secures CMS reimbursement-aligned supply agreements in US healthcare systems. |
| EFSA Reformulation Pipeline Acceleration | Maintains European shelf presence ahead of revised polyol intake framework enforcement. |
Methodological Framework
A spread of perspectives from bakery R&D directors, retail category buyers, foodservice procurement managers, and regulatory affairs specialists converged on the working assumptions driving this analysis. Primary interviews with thermal processing engineers and sweetener formulators combined with secondary validation from FDA GRAS notices, EFSA scientific opinions, FSSAI import guidelines, and customs trade data on almond flour and erythritol flows. Bottom-up SKU-level volume builds triangulated against top-down category spend estimates from Nielsen retail audit data and hospital procurement database analysis.
Demand-supply balance modeling across the projection horizon anchored volume forecasts to almond orchard yield projections, erythritol fermentation capacity expansion timelines, and reformulation cycle speeds driven by regulatory enforcement windows. Segmentation dimensions spanned product type, ingredient composition, distribution channel architecture, and customer glycemic requirement intensity. CAGRs derived from fitted growth curves calibrated to historical adoption patterns for prior sweetener substitution cycles, with explicit modeling of EFSA polyol threshold impacts and CMS reimbursement metric integration in US healthcare foodservice.
Macroeconomic conditions sit as an overlay; deviation in almond commodity pricing, Chinese currency volatility affecting stevia leaf processing economics, or biotech corridor trade policy would shift the trajectory. Forecasts reflect assumptions about regulatory approval velocity, thermal processing retrofit adoption rates, and subscription customer acquisition cost stability. Material shifts in FDA allulose GRAS determinations or CDSCO novel sweetener import pathways would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Asia-Pacific Ready-To-Eat Food Market
Packaged Foods
US Canned Foods Market
Packaged Foods
Organic Energy Bar Market
Packaged Foods
Packaged Zhug Market
Packaged Foods
South America Breakfast Cereals Market
Packaged Foods
Global Fruit Spreads Market
Packaged Foods
High-End Instant Noodles Market
Packaged Foods
Cocoa Fillings Market
Packaged Foods
South America Canned Fruits Market
Packaged Foods
North America Pasta and Noodles Market
Packaged Foods
Eco Bowls Market
Packaged Foods
North America Ready Meals Market
Packaged Foods
On-The-Go Breakfast Cereals Market
Packaged Foods
North America Pasta Market
Packaged Foods
Asia-Pacific Breakfast Cereals Market
Packaged Foods
Global Breakfast Cereals Market