
 PHO Oils Market | 2026-2036
PHO Oils Market Size, Share, and Industry Trends Forecast 2026-2036
PHO Oils Market Intelligence
Buyer concentration among food manufacturers is shifting as large-scale processors consolidate procurement volumes while regional bakeries fragment demand across specialty blends. Wilmar International leverages its integrated palm oil supply chain to sustain cost advantages in solid fat production. Cargill competes through its global oilseed processing network, while AAK AB specializes in tailored lipid solutions for industrial baking customers.
Partially hydrogenated oils are vegetable oils treated with hydrogen to raise melting points and improve oxidative stability, typically achieving iodine values below 100 and trans fat content historically exceeding 20 percent. These functional properties made PHOs indispensable for shortening, margarine, and deep-frying applications requiring extended shelf life and specific crystallization behavior. Liquid oils within the product type category now lead volume as formulators seek pourable alternatives with modified functionality. The sauces application segment shows accelerated reformulation activity as emulsion stability requirements drive interest in structured lipid systems. Margarine remains the most mature product type, facing sustained displacement from non-hydrogenated spreads in retail channels.
The FDA's 2015 GRAS revocation and subsequent compliance deadlines fundamentally reshaped domestic PHO demand, with EPA and USDA biofuel mandates indirectly redirecting oilseed flows toward energy rather than food hydrogenation. EFSA's ongoing trans fat limit evaluations in Europe and Health Canada's similar prohibition create parallel compliance pressures across multiple jurisdictions. Stakeholders must monitor emerging enzyme interesterification technologies and tropical oil supply sustainability certifications to secure formulation flexibility.
Market Dynamics
Enzymatic interesterification is compressing demand for partial hydrogenation as food manufacturers race to eliminate trans fats from legacy formulations. This catalytic process enables precise control over triglyceride structure without generating trans isomers, redirecting capital toward lipid modification infrastructure.
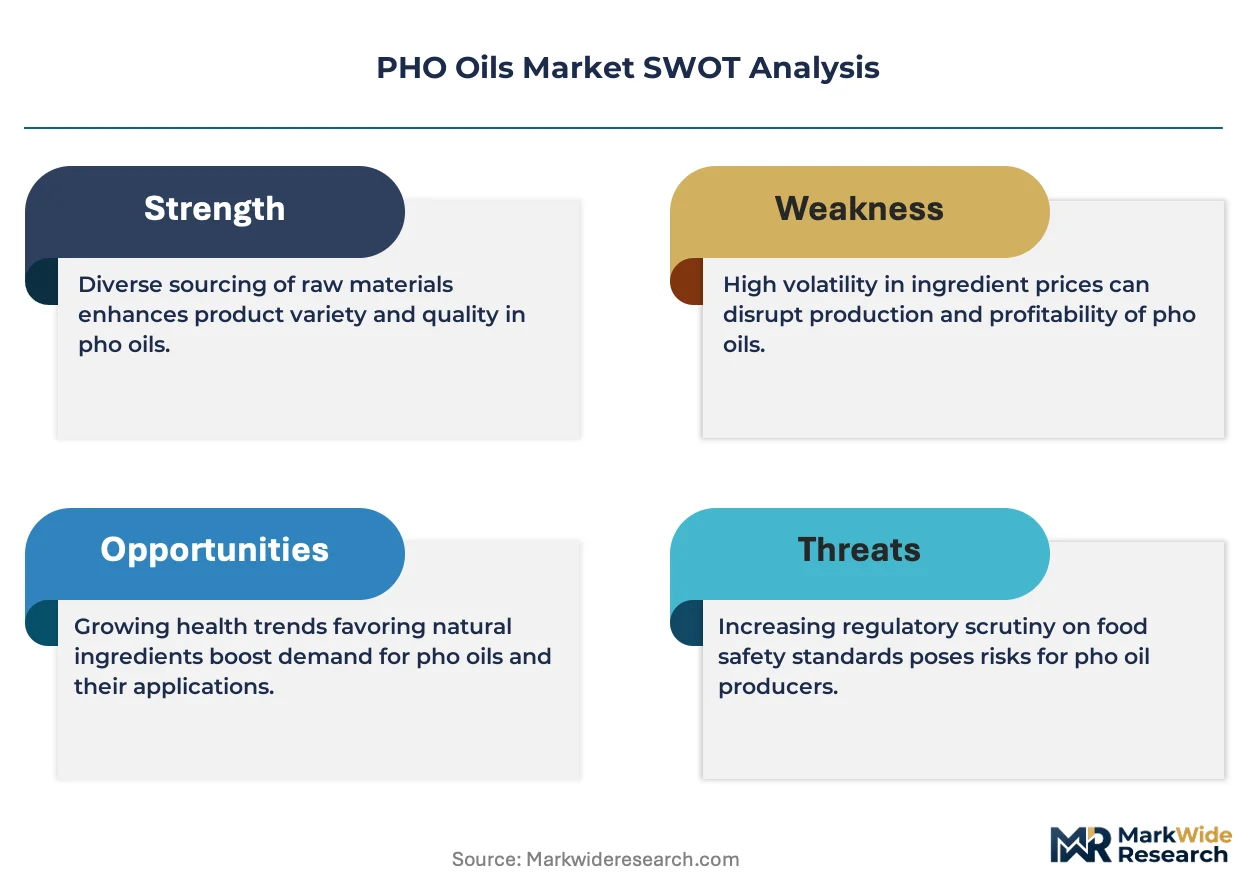
Growth Catalysts
- US FDA GRAS Revocation:The 2015 determination that PHOs are no longer generally recognized as safe continues to force reformulation across processed baked goods, shortening, and margarine categories.
- Enzymatic Interesterification:Lipase-catalyzed restructuring of triglycerides enables precise solid fat functionality without trans fat generation, attracting investment from industrial baking customers.
- Palm Oil Supply Concentration:Malaysian and Indonesian plantation expansion provides cost-competitive feedstock for palm-based alternatives displacing hydrogenated soybean and cottonseed oils.
Market Restraints
- Feedstock Price Volatility:Crude palm oil futures fluctuate with El Niño weather patterns and Indonesian export policy shifts, compressing margins for structured fat producers.
- Technical Crystallization Limits:Palm oil fractions exhibit inconsistent polymorphic stability compared to fully hydrogenated basestocks, requiring complex blending protocols for shortening applications.
- Substitution by Non-Hydrogenated Spreads:Retail margarine channels face sustained displacement from plant-based and butter-blend alternatives with cleaner label positioning.
Strategic Opportunities
- Underpenetrated Industrial Sauces:Mayonnaise and salad dressing emulsions present reformulation white space where structured lipids can stabilize oil-in-water systems without hydrogenation.
- EU Green Deal Bioeconomy Incentives:Circular economy funding streams support enzymatic processing facilities that reduce chemical catalyst waste and energy intensity.
- Direct-to-Bakery Distribution:Regional craft bakeries fragmenting from consolidated procurement create channel openings for tailored lipid solution providers with technical service capabilities.
Industry Challenges
- Reformulation Timeline Compression:Tight FDA compliance deadlines strain R&D capacity as multiple product lines require simultaneous lipid system redesign.
- Supply Chain Reconfiguration Friction:Shifting from domestic oilseed crushing to tropical oil import dependence introduces port logistics and sustainability certification complexity.
- Specialized Lipid Chemistry Talent Scarcity:Formulation expertise spanning crystallography, emulsion science, and enzyme kinetics concentrates among aging technical specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PHO Oils Market |
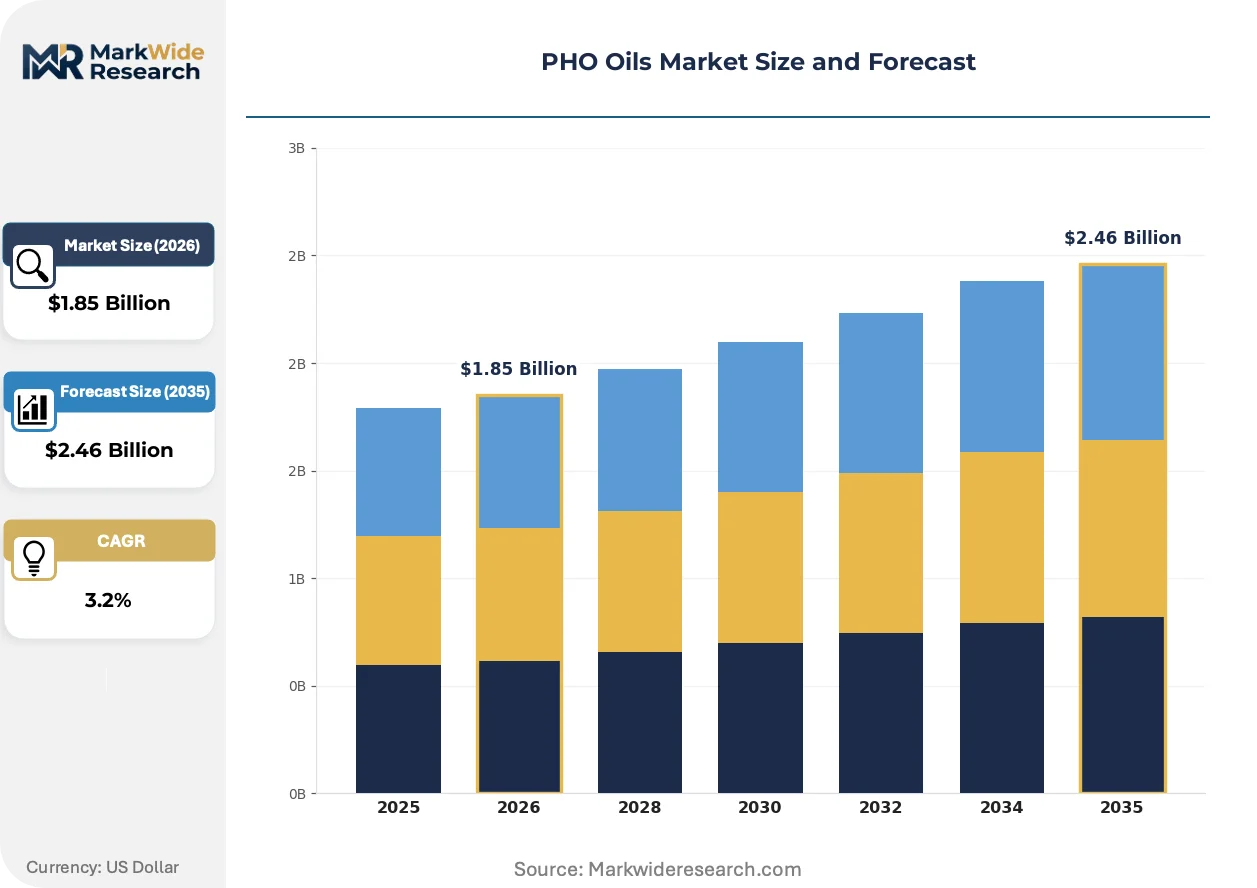
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.46 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Oils, Solid Fats, Blends, Margarine Application: Baking, Frying, Sauces, Spreads End User: Food Manufacturers, Restaurants, Bakeries, Catering Services Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Wilmar International, IOI Group, Cargill, Ingredion Incorporated, Golden Agri-Resources, Archer Daniels Midland, AAK AB, DuPont Nutrition & Biosciences, Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PHO Oils Market Strategic Shifts & Innovations
Process intensification and clean-label imperatives are restructuring how solid fats achieve functional performance. The transition from chemical to biological modification routes dominates capital allocation decisions.
Enzymatic interesterification is converging with membrane filtration fractionation to produce structured lipids with tailored melting profiles. Industrial baking customers in the United States and Western Europe are adopting these systems at pilot scale before full-line conversion. This technological pairing is converging with supply chain digitization to enable real-time quality control and batch traceability.
EFSA's ongoing trans fat limit evaluations are tightening the regulatory envelope across European Union member states. The proposed 2% trans fat cap in total fat content forces accelerated reformulation timelines for margarine and shortening manufacturers. Central and Eastern European markets with higher legacy PHO dependency face steeper compliance costs and technical adaptation requirements.
Buyer concentration among multinational food processors is fragmenting procurement volumes across specialty lipid suppliers. Regional bakery cooperatives and mid-scale snack manufacturers are consolidating purchasing power through group procurement platforms. This behavioral shift is most visible in Germany and France, where industrial baking associations negotiate collective supply agreements for interesterified fat blends.
PHO Oils Market Segmentation
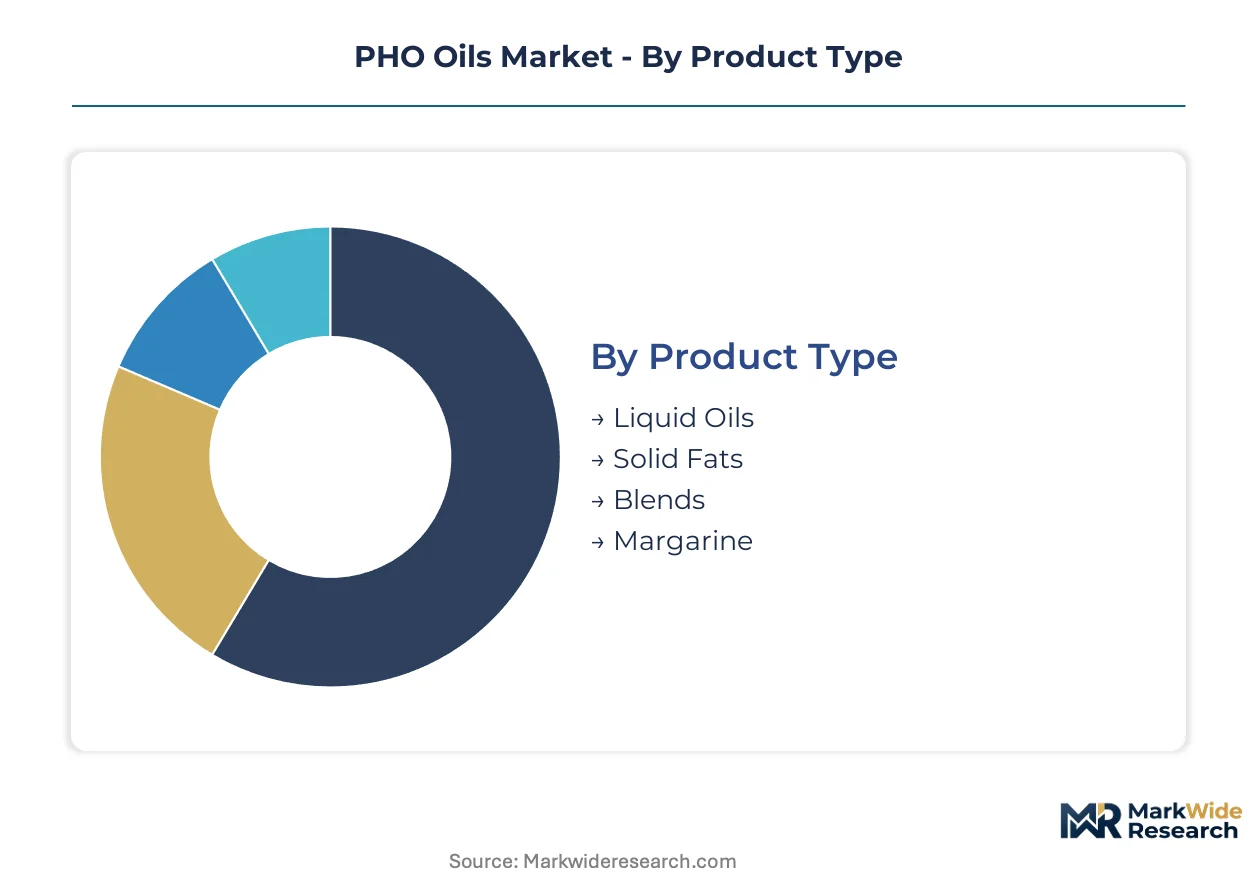
Segmentation in the PHO Oils Market reveals how reformulation pressures and distribution economics concentrate value across distinct product configurations and customer channels. Understanding these divisions exposes where procurement power aggregates and where technical service investments yield formulation lock-in.
Product Type:
Supply concentration in palm oil fractionation infrastructure has restructured competitive dynamics across physical form categories, with Malaysian and Indonesian processing clusters dominating cost positions in solid fat outputs.
- Liquid Oils:Pourable PHO variants achieve modified functionality through partial hydrogenation to iodine values between 100-130, preserving fluidity while enhancing oxidative stability. Demand concentrates in industrial frying operations across the United States, where extended fry life requirements and existing equipment compatibility sustain procurement volumes despite regulatory headwinds.
- Solid Fats:Fully hydrogenated basestocks with iodine values below 10 provide crystalline structure for shortening and margarine applications, though trans fat content historically exceeded 20 percent. Food manufacturers in legacy baked goods categories maintain procurement for reformulation bridging, particularly where palm-based alternatives exhibit polymorphic instability in high-ratio cake systems.
- Blends:Structured fat systems combine hydrogenated and non-hydrogenated components to achieve target solid fat indices across temperature ranges.
- Margarine:Spreadable emulsion products face sustained displacement from non-hydrogenated alternatives in retail channels.
Liquid oils absorb the bulk of installed capacity; solid fats are expanding most quickly as enzymatic interesterification infrastructure scales.
Application:
Cost tier differentiation across application segments reflects varying technical barriers to reformulation and penalty costs of functional failure.
- Baking:Shortening-dependent applications including cookies, crackers, and laminated pastries require precise plasticity ranges and creaming performance that PHOs historically delivered through controlled crystallization. Regional bakeries in the United States fragment procurement across specialty blend suppliers as reformulation timelines compress, creating channel openings for technical service-intensive vendors.
- Frying:Deep-fat frying applications prioritize oxidative stability and extended fry life over crystallization behavior, with industrial potato and snack processing operations representing concentrated demand nodes.
- Sauces:Mayonnaise and salad dressing emulsions present reformulation white space where structured lipids stabilize oil-in-water systems.
- Spreads:Retail and foodservice margarine channels face displacement from butter-blend and plant-based alternatives.
Baking commands the deepest technical relationships with suppliers; sauces is climbing the fastest as emulsion stability requirements drive structured lipid adoption.
End User:
Customer type segmentation exposes divergent procurement sophistication, with consolidated food manufacturers leveraging volume concentration against fragmented regional operators.
- Food Manufacturers:Large-scale processors consolidate procurement volumes for reformulation at enterprise scale, negotiating technical service agreements and supply security commitments from lipid solution providers. These buyers concentrate in the United States and Western Europe, where FDA and EFSA compliance deadlines force simultaneous multi-product line redesign.
- Restaurants:Foodservice frying operations prioritize cost stability and fry life performance over label positioning.
- Bakeries:Regional craft bakeries fragment from consolidated procurement, creating demand for tailored lipid solutions with direct technical support.
- Catering Services:Institutional feeding operations balance cost constraints with nutritional specification compliance.
Food manufacturers absorb the bulk of supplier attention; bakeries are gaining share fastest as cooperative procurement platforms aggregate fragmented purchasing power.
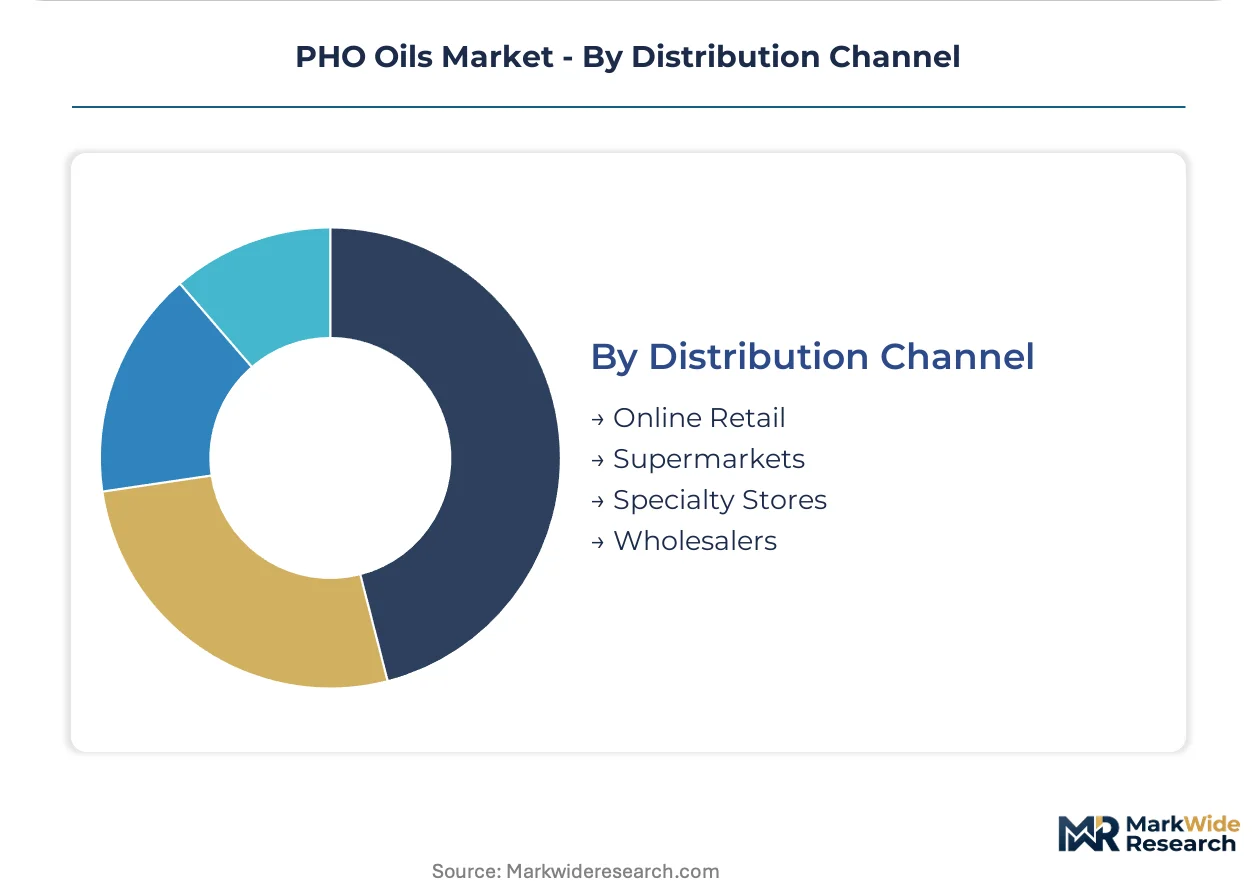
Distribution Channel:
Volume concentration in wholesale channels reflects the industrial character of PHO demand, though digital procurement platforms are restructuring access economics for smaller operators.
- Wholesalers:Bulk lipid distributors dominate throughput, consolidating shipments from palm oil refiners and interesterification facilities to industrial baking and frying customers. These channels concentrate in port-proximate distribution centers handling tropical oil imports, with sustainability certification documentation adding administrative burden.
- Supermarkets:Retail margarine and consumer shortening sales persist in conventional grocery.
- Specialty Stores:Professional bakery supply outlets serve artisanal producers requiring technical consultation.
- Online Retail:Digital procurement platforms aggregate fragmented regional bakery demand.
Wholesalers control the bulk of physical volume; online retail is expanding most quickly as group procurement platforms digitize cooperative buying.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States food manufacturers concentrate the most acute PHO reformulation demand as FDA compliance deadlines compress procurement timelines. Legacy baked goods processors across the Midwest and Southeast simultaneously redesign multiple product lines. Regional bakery cooperatives in these areas fragment purchasing power through emerging group procurement platforms.
United States
Industrial baking operations in Illinois and Ohio drive concentrated demand for interesterified fat alternatives as shortening reformulation accelerates. The FDA's 2015 GRAS revocation and subsequent compliance mandates force simultaneous multi-product line redesign across legacy processors. Chicago and Cincinnati processing clusters anchor technical service relationships with lipid solution providers.
Germany
EFSA's proposed trans fat limit evaluations tighten formulation requirements for margarine and industrial baking customers. The EU Green Deal bioeconomy incentives redirect capital toward enzymatic processing facilities with reduced chemical catalyst waste. North Rhine-Westphalia's food processing corridor concentrates reformulation activity among mid-scale bakery manufacturers.
Indonesia
Plantation expansion in Sumatra and Kalimantan sustains cost-competitive palm oil feedstock flows for structured fat production. Indonesian export policy shifts and El Niño weather patterns introduce crude palm oil price volatility affecting downstream margin structures. Surabaya and Medan refining clusters dominate fractionation infrastructure for solid fat outputs.
Malaysia
Integrated palm oil supply chains in Peninsular Malaysia sustain cost advantages for solid fat production displacing hydrogenated alternatives. Sustainability certification requirements from RSPO and ISPO add administrative burden to port-proximate distribution logistics. Port Klang and Pasir Gudang processing hubs handle bulk tropical oil shipments to industrial baking customers.
Canada
Health Canada's PHO prohibition creates parallel compliance pressures to FDA mandates for cross-border food manufacturers. Prairie oilseed crushing operations face redirected flows as biofuel mandates from EPA and USDA compete for soybean and canola supplies. Toronto and Montreal food processing clusters concentrate margarine reformulation demand.
PHO Oils Market Key Industry Players
Southeast Asian plantation-integrated producers anchor one tier; European and North American lipid modification specialists hold formulation service advantages closer to end-use customers. The vendor base concentrates around palm oil supply chain control and enzymatic processing capabilities. Three archetypes dominate: integrated plantation-to-refinery operators, global oilseed processors with fractionation assets, and tailored lipid solution providers with technical service intensity. Competitive moves center on backward integration into plantation assets and enzymatic interesterification capacity expansion.
Within the integrated plantation tier, Wilmar International and Golden Agri-Resources represent upstream supply control archetypes. Among global oilseed processors, Cargill and Bunge Limited exemplify scale-driven positions with fractionation infrastructure. AAK AB occupies a specialist position in tailored lipid solutions for industrial baking customers requiring direct technical support.
| Leading Market Players |
|---|
| Wilmar International |
| IOI Group |
| Cargill |
| Ingredion Incorporated |
| Golden Agri-Resources |
| Archer Daniels Midland |
| AAK AB |
| DuPont Nutrition & Biosciences |
| Bunge Limited |
| Others |
Cost & Logistics Intelligence
Family-owned plantation conglomerates in Malaysia and Indonesia anchor upstream supply control, translating crude palm oil cost advantages into disciplined pricing power over downstream structured fat producers. Their captive refining assets compress margin capture for independent processors while sustaining premium-mid-economy pricing differentiation across enzymatic interesterification tiers.
Pricing Analysis
Volume concentration in industrial baking contracts absorbs procurement scale discounts, while margin capture concentrates in enzymatic processing tiers serving reformulation-sensitive food manufacturers. Three-tier pricing structure across premium, standard, and economy levels stratifies by RSPO certification grade and technical service intensity. Cost compression in standard palm fractions is intensifying because El Niño-driven feedstock volatility strains blending margin structures. Regional bakery cooperatives exhibit acute price sensitivity; multinational food manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Indonesian domestic-content mandates for plantation licensing reshape sourcing patterns, redirecting capital toward in-country fractionation infrastructure. Geographic supply concentration centers on Indonesia, Malaysia, and the Philippines, with Surabaya and Port Klang refining clusters dominating solid fat outputs. Raw material flows draw from crude palm oil, palm kernel oil, and imported soybean oil for enzymatic restructuring. Single-source vulnerability concentrates in Malaysian port logistics handling RSPO-certified shipments. Distribution runs through bulk wholesalers consolidating tropical oil imports for industrial baking and frying customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic interesterification capacity scarcity props pricing discipline as food manufacturers compete for reformulation-ready lipid supply. This supply-constrained structure favors incumbents with backward integration into plantation assets.
For Market Incumbents: Acquire palm oil fractionation facilities in Peninsular Malaysia to secure feedstock cost advantages against emerging enzymatic specialists. Expand technical service teams in Midwest industrial baking corridors to lock in reformulation partnerships. Certification investment in RSPO and ISPO credentials defends position against sustainability-focused procurement mandates from multinational food processors. For New Entrants and Emerging Players: Begin with direct-to-bakery distribution models targeting fragmented regional cooperatives in Ohio and Illinois. White-space opportunity concentrates in underpenetrated industrial sauces requiring emulsion stability without hydrogenation. Group procurement platform partnerships offer the most penetrable channel for aggregating fragmented purchasing power. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale enzymatic processors with stranded capacity in Western Europe facing EFSA compliance cost pressures. Long-term viability hinges on five-to-ten-year structural demand for trans-fat-free alternatives as global regulatory envelopes tighten. Watch Indonesian export policy shifts as the inflection signal for feedstock cost trajectory reversals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Captures crude palm oil margin compression and secures RSPO certification traceability for European buyers. |
| Enzymatic Processing Capacity Expansion | Positions suppliers for FDA-compliant reformulation demand from Midwest baked goods processors. |
| Technical Service Partnership Programs | Locks in regional bakery cooperatives through direct crystallography and emulsion science support. |
| Sustainability Certification Investment | Enables premium tier access as EFSA and Health Canada procurement specifications tighten. |
| Direct-to-Bakery Distribution Buildout | Captures fragmented demand from craft bakeries consolidating through Ohio and Illinois cooperatives. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with lipid solution technical directors, bakery procurement managers, and palm oil refinery operations heads combined with FDA GRAS docket submissions, EFSA scientific opinions, and Malaysian Palm Oil Board production statistics. Bottom-up volume modeling and top-down value triangulation cross-validated segment-level outputs.
Granularity-level framing applied product type, application, and end-user dimensions at country-level resolution across the projection horizon. Physical form categories modeled liquid oils, solid fats, blends, and margarine separately. CAGRs derived from trend extrapolation of enzymatic capacity buildout and regulatory compliance deadline clustering. Forecast inputs incorporated palm oil futures curve behavior and industrial baking production indices.
Underlying measurement precision varies by segment; enzymatic interesterification volumes carry tighter precision than legacy PHO displacement estimates. Forecasts reflect assumptions about EFSA trans fat limit adoption timing and Indonesian export policy stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Soybean Meal Market
Ingredients
North America Protein Ingredients Market
Ingredients
Coconut Oil Based Products Market
Ingredients
Fiber Rich Flours Market
Ingredients
Pumpkin Seed Protein Market
Ingredients
South America Feed Yeast Market
Ingredients
Specialty Feed Additives Market
Ingredients
Hydrolysed Vegetable Protein (HVP) Market
Ingredients
Wheat Protein Concentrates Market
Ingredients
Interesterified CBE Market
Ingredients
Middle East and Africa Fruit and Vegetable Ingredients Market
Ingredients
Collagen Casings Market
Ingredients
Anti-Aging Ingredients Market
Ingredients
Corn Starch Market
Ingredients
Meat Starter Culture Market
Ingredients
Plant Based Thickener Market