
 Corn Steep Liquor Market | 2026-2036
Corn Steep Liquor Market Size, Share, and Industry Trends Forecast 2026-2036
Corn Steep Liquor Market Intelligence
Aftermarket service revenue for corn steep liquor processing equipment is fragmenting across regional service networks and original equipment channels. Cargill leverages its captive wet-milling infrastructure to control downstream liquor quality and logistics costs. Archer Daniels Midland anchors North American supply through integrated corn-processing complexes in the Midwest. Roquette Frères competes in European pharmaceutical-grade segments with specialized extraction protocols.
Corn steep liquor is the concentrated liquid extract remaining after steeping corn in warm water during wet-milling, containing soluble proteins, amino acids, lactic acid, and minerals at specific gravity ranges suitable for industrial fermentation. Feed Grade material dominates volume as the default specification for animal nutrition rations, while Pharmaceutical Grade commands premium positioning in precision fermentation and vaccine substrate applications. Liquid Form sustains the largest share of bulk shipments to integrated livestock operations, though Spray-Dried Form is gaining traction among aquaculture feed compounders seeking extended shelf stability and reduced freight costs.
USDA and FDA jointly oversee feed-ingredient safety classifications for corn steep liquor entering animal nutrition channels, while EPA permitting governs effluent discharge from wet-milling facilities producing the material. In Europe, EFSA evaluates novel food and feed applications under evolving sustainability criteria, and REACH registration requirements constrain import pathways for non-EU suppliers. Buyers and processors must monitor regulatory divergence between jurisdictions to avoid supply chain disqualification as purity standards tighten.
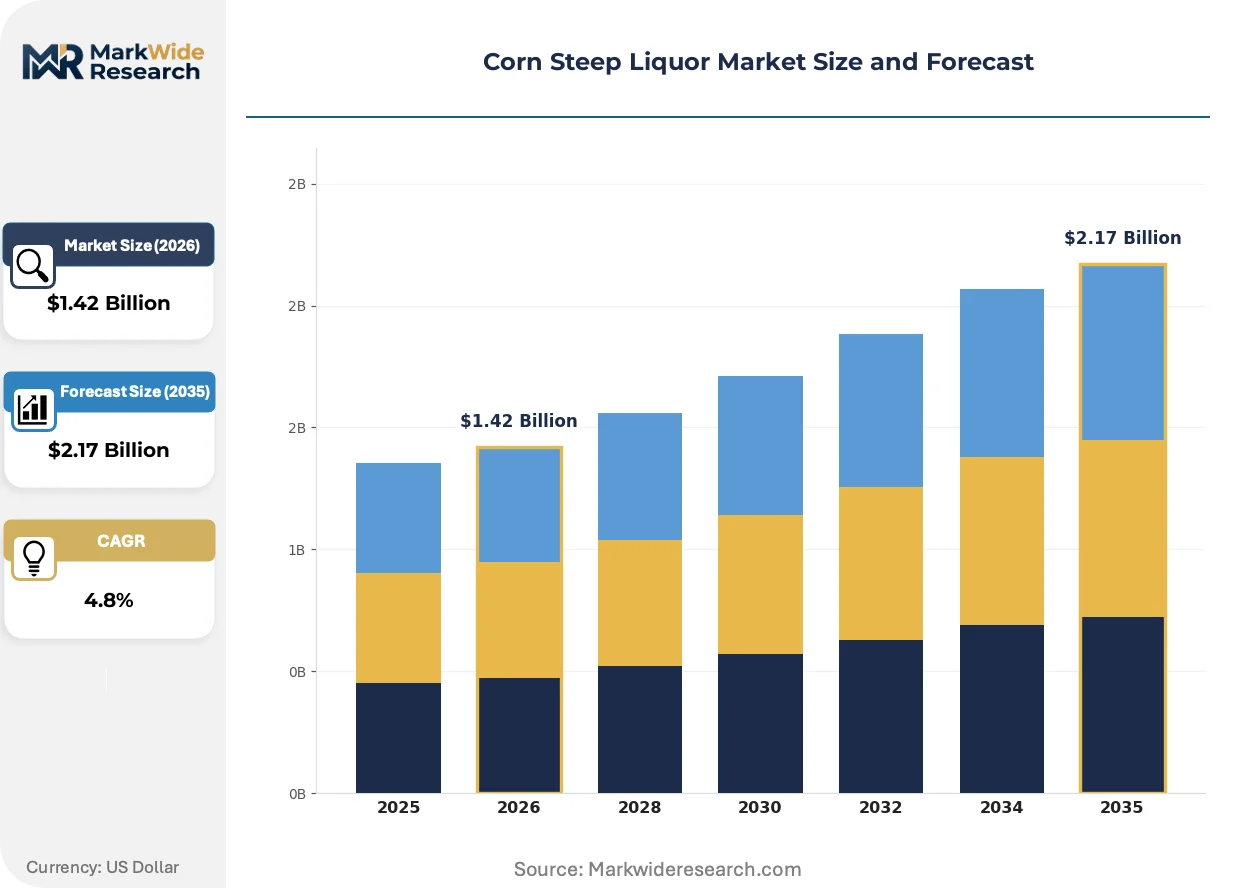
Market Dynamics
Wet-milling capacity consolidation around the US Corn Belt is tightening supply availability for independent buyers, while pharmaceutical-grade purity requirements from EMA and FDA are forcing processors to requalify extraction protocols.
Growth Catalysts
- Poultry feed ration reformulation:US livestock integrators are substituting corn steep liquor for soybean meal to reduce feed costs amid volatile oilseed markets. Broiler operations in Georgia and Arkansas are driving volume uptake.
- REACH registration pathways:European chemical compliance frameworks are creating preferential access for EU-based wet-millers with pre-registered dossiers, disadvantaging spot-market importers from non-EU origins.
- Precision fermentation scale-up:Contract manufacturers producing enzyme and probiotic cultures are standardizing on food-grade corn steep liquor as a nitrogen source, displacing synthetic yeast extracts in bioreactor media formulations.
Market Restraints
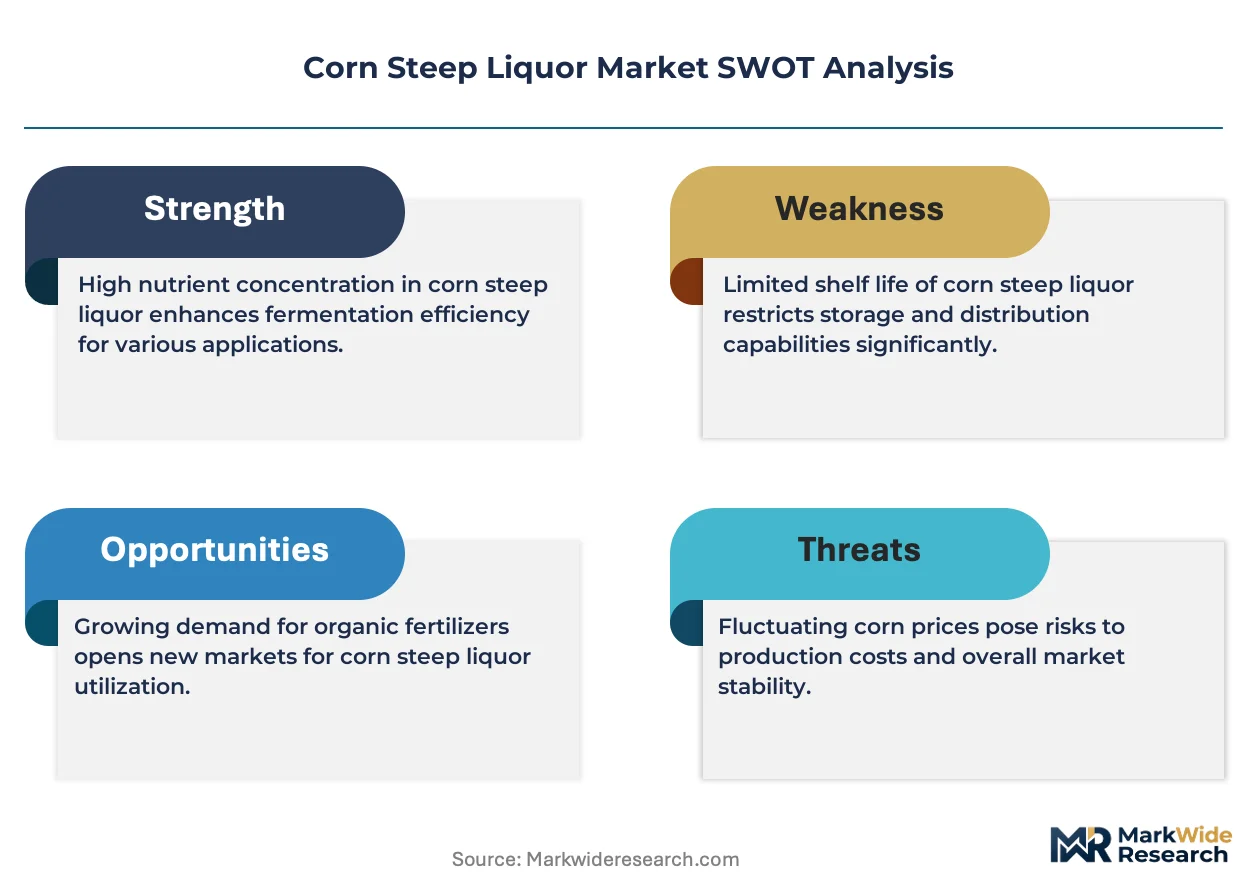
- Corn price volatility:Input cost swings tied to US Department of Agriculture crop forecasts and ethanol mandate adjustments compress wet-miller margins and destabilize long-term supply contracts.
- Supply concentration in Midwest wet-milling:Cargill, ADM, and Tate & Lyle control over seventy percent of North American steep liquor output, creating single-source risk for compound feed mills without alternative procurement channels.
- Substitution by distillers dried grains:Ethanol plant co-products with comparable protein profiles are capturing share in ruminant feed applications where amino acid precision matters less.
Strategic Opportunities
- Brazilian aquaculture expansion:Shrimp and tilapia producers in São Paulo and Santa Catarina states are importing spray-dried corn steep liquor for pelleted feed formulations, opening a new demand corridor outside traditional livestock channels.
- EU Green Deal bioeconomy incentives:Circular economy funding streams for valorizing agricultural waste streams are subsidizing wet-milling retrofits that upgrade steep liquor to pharmaceutical-grade specifications.
- Blockchain-enabled provenance tracking:Integration of distributed ledger systems with batch-level quality documentation is allowing premium-priced pharmaceutical-grade material to command traceability premiums from vaccine substrate buyers.
Industry Challenges
- Pharmaceutical-grade certification timelines:Achieving EMA-compliant GMP certification for corn steep liquor extraction requires eighteen-to-twenty-four month validation cycles that delay market entry for new processors.
- Specialized fermentation technologist scarcity:Wet-milling facilities lack personnel trained in pharmaceutical substrate contamination control, forcing reliance on external consultants for FDA pre-approval inspections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn Steep Liquor Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feed Grade, Food Grade, Pharmaceutical Grade, Industrial Grade Application: Animal Nutrition, Food Additives, Fermentation Industry, Biochemical Production End Use: Poultry Industry, Swine Industry, Aquaculture, Plant Growth Form: Liquid Form, Powder Form, Concentrated Form, Spray-Dried Form |
| Companies Covered | Ingredion, Tate & Lyle, Cargill, Juci Corn Biotechnology, Gulshan Polyols, Archer Daniels Midland, Roquette Frères, Global Bio-chem Technology Group, Tereos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn Steep Liquor Market Strategic Shifts & Innovations
Extraction technology convergence with membrane filtration and chromatographic purification is redefining grade boundaries, while regulatory divergence between FDA and EMA pathways is fragmenting supplier qualification requirements.
Membrane filtration systems incorporating ceramic microfiltration followed by nanofiltration concentration are hybridizing traditional evaporation-based steep liquor processing with precision separation techniques borrowed from biopharmaceutical downstream operations. Pharmaceutical substrate manufacturers in Germany and Switzerland are adopting these hybrid trains to meet residual protein specifications below five hundred parts per million. The technology is hybridizing cost structures, compressing energy consumption per liter by forty percent while doubling capital intensity for equipment installation.
REACH Article 33 disclosure obligations and evolving SCIP database requirements for articles containing substances of very high concern are tightening documentary burdens on corn steep liquor importers into the European Economic Area. Wet-millers must now submit full supply chain substance declarations to ECHA for downstream users in pharmaceutical applications. German and French fermentation houses are responding by demanding batch-level analytical certificates from US and Brazilian suppliers, effectively screening out traders without laboratory infrastructure.
Compound feed mills are consolidating procurement through integrated supply agreements that bundle corn steep liquor with amino acid premixes and vitamin packages under single-source contracts. This disintermediation is displacing independent distributors who historically managed spot purchases and logistics coordination. The shift is most visible in US broiler operations across the Southeast, where Tyson Foods and Pilgrim's Pride are internalizing ingredient sourcing to secure cost visibility and volume guarantees through multi-year offtake structures.
Corn Steep Liquor Market Segmentation
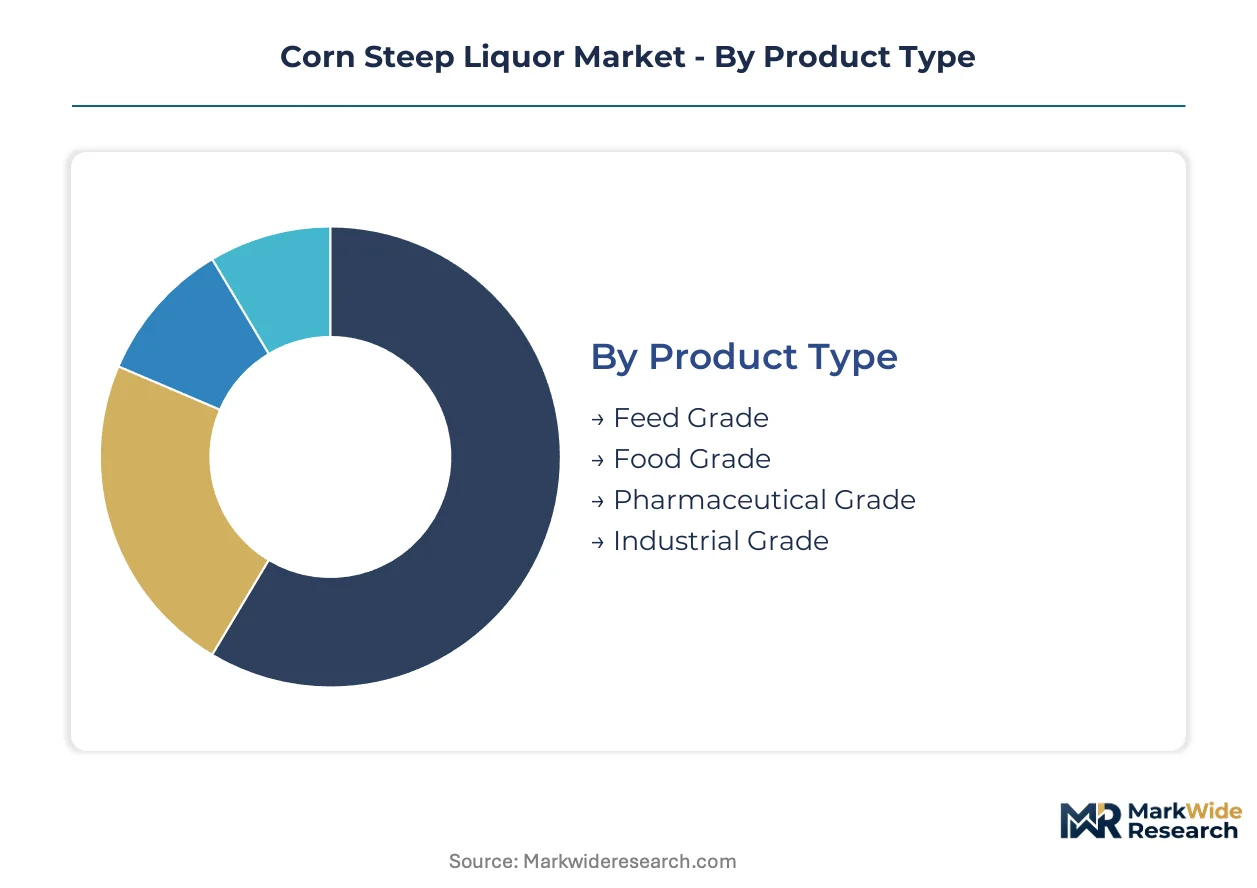
Corn steep liquor segmentation reflects divergent purity thresholds and logistics requirements across end-use channels. Grade specifications, application intensity, and physical form each create distinct procurement patterns and margin structures for wet-millers and compounders.
Product Type:
Mature specifications dominate volume flows while emerging grades capture premium positioning in precision applications.
- Feed Grade:Standard protein and amino acid concentrations suitable for bulk livestock rations without pharmaceutical purity requirements. Poultry integrators in Georgia and Arkansas absorb the largest volumes as soybean meal substitution accelerates amid volatile oilseed markets.
- Pharmaceutical Grade:Residual protein specifications below five hundred parts per million achieved through membrane filtration and chromatographic purification. German and Swiss fermentation houses demand batch-level analytical certificates under REACH Article 33 disclosure obligations, screening out traders lacking laboratory infrastructure.
- Food Grade:Intermediate purity tier serving enzyme and probiotic culture manufacturers with nitrogen source requirements stricter than feed applications but below pharmaceutical thresholds.
- Industrial Grade:Lowest specification tier for biochemical production where amino acid precision matters less than cost per unit nitrogen.
Feed Grade handles the majority of throughput; Pharmaceutical Grade is the fastest mover on share.
Application:
Cost tier stratification separates commodity volume plays from precision fermentation opportunities.
- Animal Nutrition:Bulk protein supplementation for livestock operations prioritizing cost per unit metabolizable energy over amino acid profile precision. US broiler and swine operations drive procurement concentration through integrated supply agreements bundling steep liquor with premixes.
- Fermentation Industry:Nitrogen source standardization for contract manufacturers producing enzyme and probiotic cultures displacing synthetic yeast extracts in bioreactor media. China, India, and Brazil concentrate procurement around food-grade and pharmaceutical-grade specifications.
- Food Additives:Flavor enhancement and nutritional fortification applications requiring intermediate purity certification.
- Biochemical Production:Organic acid and solvent fermentation feedstock where impurity tolerance permits industrial-grade sourcing.
Animal Nutrition commands the largest revenue base; Fermentation Industry is expanding most quickly as precision biomanufacturing scales.
End Use:
Customer type fragmentation separates integrated livestock operations from specialized aquaculture and agricultural channels.
- Poultry Industry:Broiler operations reformulating rations to substitute corn steep liquor for soybean meal, with Tyson Foods and Pilgrim's Pride internalizing ingredient sourcing through multi-year offtake structures.
- Aquaculture:Shrimp and tilapia producers in São Paulo and Santa Catarina states importing spray-dried material for pelleted feed formulations, opening demand outside traditional livestock channels.
- Swine Industry:Finishing ration applications where lysine and methionine supplementation economics favor steep liquor inclusion rates.
- Plant Growth:Foliar fertilizer and soil amendment applications leveraging lactic acid and mineral content for horticultural operations.
Poultry Industry maintains the deepest volume penetration; Aquaculture is climbing the fastest as Brazilian import corridors mature.
Form:
Supply concentration around liquid bulk contrasts with emerging dried formats for extended distribution reach.
- Liquid Form:Bulk shipments to integrated livestock operations within economical trucking radius of Midwest wet-milling complexes. Cargill and ADM control downstream logistics through captive infrastructure.
- Spray-Dried Form:Shelf-stable powder gaining traction among aquaculture feed compounders seeking reduced freight costs and extended storage stability for international shipment.
- Powder Form:Intermediate dehydration tier for regional distribution networks without spray-drying capital investment.
- Concentrated Form:Reduced moisture content for customers with on-site dilution capabilities and storage constraints.
Liquid Form dominates shipment volumes; Spray-Dried Form is gaining share fastest as aquaculture procurement globalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: livestock feed dominates procurement in the Americas, while pharmaceutical-grade extraction drives European purchasing, and fermentation feedstock absorbs volume in Asian biomanufacturing hubs.
United States
Poultry integrators in Georgia and Arkansas are absorbing record volumes of feed-grade material as soybean meal substitution accelerates. FDA feed-ingredient guidelines and USDA safety classifications govern import and processing standards for animal nutrition channels. Wet-milling complexes across Iowa, Illinois, and Indiana concentrate over seventy percent of domestic steep liquor output under integrated processor control.
Brazil
Shrimp and tilapia producers in São Paulo and Santa Catarina states are importing spray-dried formulations for pelleted aquafeed, opening a demand corridor outside traditional livestock channels. ANVISA regulates feed additive safety classifications while the Ministry of Agriculture oversees import licensing for agricultural inputs. The São Paulo state cluster anchors South American distribution logistics for dried product formats.
Germany
Precision fermentation houses in Bavaria and Baden-Württemberg are standardizing on pharmaceutical-grade nitrogen sources for enzyme and probiotic culture production. REACH Article 33 disclosure obligations and ECHA registration requirements constrain import pathways and favor EU-based wet-millers with pre-registered dossiers. The Rhine-Ruhr industrial corridor hosts downstream bioprocessing facilities demanding batch-level analytical certification.
China
Contract manufacturers in Jiangsu and Shandong provinces are scaling food-grade procurement for bioreactor media formulations displacing synthetic yeast extracts. NMPA and SAMR jointly oversee pharmaceutical substrate safety standards while GB standards govern feed-grade material specifications. The Yangtze River Delta biotech cluster concentrates demand from precision fermentation scale-up operations.
India
Compound feed mills in Gujarat and Maharashtra are integrating corn steep liquor into poultry and swine rations as cost-effective protein alternatives to oilseed meals. FSSAI and BIS regulate feed ingredient safety classifications while state agricultural departments monitor wet-milling effluent discharge. The Ahmedabad-Vadodara industrial corridor hosts emerging processing capacity serving domestic livestock operations.
Corn Steep Liquor Market Key Industry Players
Capability concentration sits with wet-millers commanding captive corn supply and extraction infrastructure; scale advantage sits with diversified agribusiness conglomerates operating integrated processing complexes. The market structure tiers into three archetypes: integrated grain processors with downstream liquor control, specialized bioproduct extractors serving pharmaceutical purity tiers, and regional compounders bundling steep liquor with premix offerings. Dominant competitive moves include backward integration into corn sourcing and multi-year offtake contracting with livestock integrators.
Within the integrated processor tier, Cargill and Archer Daniels Midland exemplify scale-driven positioning through Midwest wet-milling infrastructure. Roquette Frères occupies a specialized position in European pharmaceutical-grade segments. Among Asia-Pacific players, Juci Corn Biotechnology represents regional fermentation feedstock supply capability.
| Leading Market Players |
|---|
| Ingredion |
| Tate & Lyle |
| Cargill |
| Juci Corn Biotechnology |
| Gulshan Polyols |
| Archer Daniels Midland |
| Roquette Frères |
| Global Bio-chem Technology Group |
| Tereos |
| Others |
Cost & Logistics Intelligence
Midwest rail corridors connecting Iowa wet-milling complexes to Georgia poultry operations concentrate freight economics, amplifying Cargill and ADM's pricing power while forcing independent buyers to absorb basis risk or pay premiums for alternative sourcing.
Pricing Analysis
Long-term offtake contracts dominate procurement between integrated processors and livestock integrators, compressing spot-market liquidity and widening bid-ask spreads for independent compound feed mills. Price differentiation hinges on pharmaceutical-grade certification status and volume scale, with EMA-compliant batches commanding substantial premiums over feed-grade material. Pricing pressure intensifies as distillers dried grains from ethanol plants undercut steep liquor in ruminant applications. Poultry integrators exhibit the highest price sensitivity due to thin operating margins, while vaccine substrate manufacturers prioritize purity consistency over unit cost.
Supply Chain Analysis
Tariff exposure between Brazil and European pharmaceutical buyers constrains import pathway economics for non-EU wet-millers lacking REACH pre-registration. Supply concentrates in the United States, Brazil, and China, with Midwest corn belt infrastructure anchoring North American output. Raw material dependencies center on yellow corn supply, natural gas for evaporation energy, and membrane filtration consumables. Single-source vulnerability pervades the pharmaceutical-grade tier where EMA validation cycles create eighteen-month supplier lock-in. Distribution runs through captive logistics networks for liquid bulk and specialized cold-chain forwarding for spray-dried exports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern corn steep liquor value capture as blockchain-enabled batch documentation creates interoperability between wet-miller quality systems and pharmaceutical buyer ERP platforms, shifting competitive advantage toward data-integrated suppliers.
For Market Incumbents: Harden defensive positioning by deepening backward integration into corn origination in Brazil's Mato Grosso expansion zones and accelerating pharmaceutical-grade certification investments to preempt EMA regulatory tightening. Substitute threat from precision-fermentation synthetic nitrogen sources demands faster GMP validation cycles to maintain substrate market share.
For New Entrants and Emerging Players: Brazilian aquaculture feed compounders in Santa Catarina represent the most penetrable entry point, combining import-dependent demand with lower regulatory barriers than pharmaceutical channels. Spray-dried production capacity with ANVISA-aligned documentation offers a viable go-to-market angle against established liquid-bulk incumbents.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agribusiness conglomerates with underutilized wet-milling assets lacking pharmaceutical-grade extraction infrastructure. Long-term viability rests on fermentation industry demand scaling, with precision biomanufacturing capacity build-out in China's Yangtze River Delta serving as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Certification Investment | EMA-compliant GMP validation unlocks vaccine substrate contracts from German fermentation houses. |
| Spray-Dried Capacity Expansion | Extended shelf stability captures Brazilian aquaculture demand outside Midwest liquid-bulk radius. |
| Blockchain Provenance Integration | Distributed ledger documentation commands traceability premiums from Swiss pharmaceutical buyers. |
| Backward Integration into Corn Origination | Captive supply from Mato Grosso expansion zones insulates against USDA crop forecast volatility. |
| Long-Term Offtake Contracting | Multi-year structures with Tyson Foods and Pilgrim's Pride secure volume visibility and logistics optimization. |
Research Approach
Cross-validation between wet-miller procurement directors and pharmaceutical fermentation technologists anchors the qualitative findings, with secondary triangulation against ECHA registration databases and FDA feed-ingredient guidance archives. Primary interviews engaged plant managers at Midwest processing complexes, procurement leads at Southeast poultry integrators, regulatory affairs specialists at European fermentation houses, and distribution channel partners in São Paulo. Secondary sources encompassed customs trade data, SEC filings from diversified agribusiness conglomerates, REACH Article 33 disclosure records, and ANVISA feed additive safety classifications. Bottom-up volume modeling from individual facility throughput reconciled against top-down industry association estimates.
Calibration against historical grade-tier price spreads and freight rate indices informed the projection framework across the analysis window. Segmentation dimensions modeled included grade specification, application intensity, physical form, and regional regulatory cluster. CAGRs derived from weighted average of capacity expansion announcements, import licensing trajectories, and substitution elasticity estimates for soybean meal and distillers dried grains. Forecast inputs incorporated wet-milling energy cost structures and pharmaceutical substrate contamination control investment cycles.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, corn futures volatility, or EMA inspection backlogs would shift the trajectory. Forecasts reflect documented assumptions about regulatory convergence timelines and fermentation industry scale-up cadence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Boysenberry Extract Market
Ingredients
Chickpea Protein Market
Ingredients
Lupine Peptides Market
Ingredients
India Starch and Starch Derivative Market
Ingredients
Asia-Pacific Plant Protein Ingredients Market
Ingredients
Wheat Germ Oil Market
Ingredients
Collagen Casings Market
Ingredients
Pea Protein Ingredients Industry Status and Prospects Professional Market
Ingredients
Wheat Protein Concentrates Market
Ingredients
Dried Beet Pulp Market
Ingredients
Soybean Meal Market
Ingredients
Halal and Kosher Empty Capsules Market
Ingredients
Food Grade Hydrolyzed Casein Market
Ingredients
Whey Permeate Market
Ingredients
United States Avocado Oil Market
Ingredients
Pea Fiber Market