
 Refined Coconut Oil Market | 2026-2036
Refined Coconut Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Refined Coconut Oil Market Analytics
Market Context
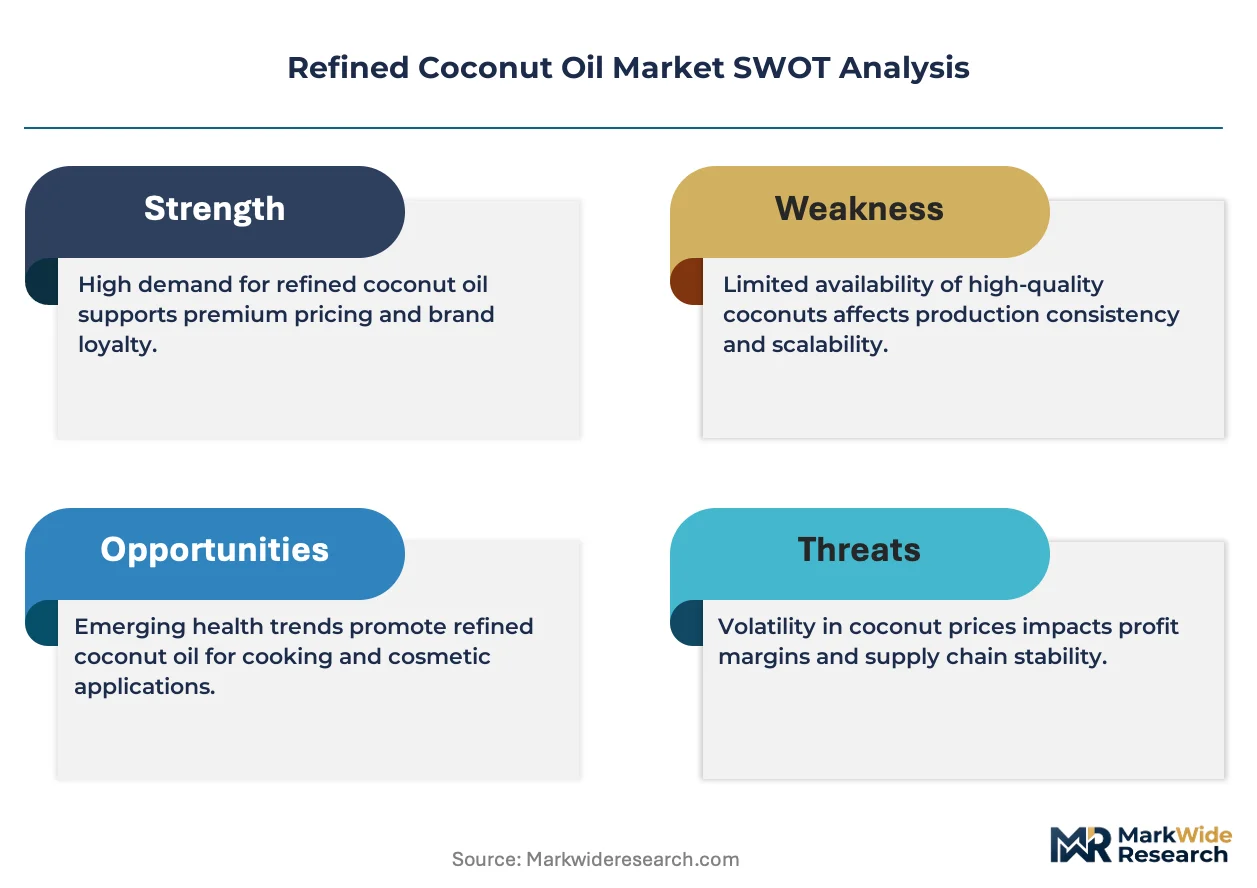
REACH compliance is expanding the cost-of-entry calculus for refined coconut oil exporters targeting European cosmetic and food manufacturers. Cargill Incorporated leverages its integrated supply chain from Southeast Asian copra sources to European refineries, sustaining volume commitments to industrial buyers. Greenville Agro Corporation anchors its position through specialized cosmetic-grade production, while Tantuco Enterprises competes on geographic proximity to Philippine coconut plantations.
Technical Definition and Segment Structure
Refined coconut oil is a deodorized, bleached lipid extracted from dried coconut kernel (copra) with a free fatty acid content typically below 0.1 percent and a melting point near 24 degrees Celsius, serving as a stable frying medium, cosmetic emollient, and oleochemical feedstock. Food Grade product dominates volume throughput due to institutional catering and snack food manufacturing, though Cosmetic Grade commands superior margin pools from premium skincare formulators in France and South Korea. Application concentration in cooking reflects emerging-market dietary transitions, while medicinal use remains nascent but structurally supported by healthcare provider trials in India and Germany.
Regulatory Frame and Outlook
EMA cosmetic ingredient guidelines, FDA food contact substance notifications, and BIS refining purity standards collectively shape product specifications and cross-border market access for refined coconut oil suppliers. These frameworks elevate testing costs for smaller Philippine and Indonesian refiners while advantaging integrated multinationals with captive laboratory capacity. Stakeholders must monitor evolving EU deforestation-free supply chain due diligence rules, which will soon require geolocation traceability for every copra batch entering European cosmetic and food channels.
Market Dynamics
REACH compliance and EU deforestation-free supply chain due diligence rules are compressing margins for Philippine and Indonesian refiners while advantaging integrated multinationals with captive laboratory and traceability infrastructure.
Growth Catalysts
- Clean-label food processing:Southeast Asian snack manufacturers are reformulating with refined coconut oil to eliminate trans fats, pulling volume through Indonesia's oleochemical corridor.
- EMA cosmetic ingredient guidelines:Premium skincare formulators in France and South Korea are specifying cosmetic-grade refined coconut oil with sub-0.1% free fatty acid content, tightening supplier qualification.
- Philippine Bureau of Product Standards mandates:Stricter free fatty acid thresholds are filtering out low-grade exporters and consolidating procurement among compliant integrated refiners.
Market Restraints
- Copra supply concentration:Philippine and Indonesian smallholder cooperatives dominate raw material sourcing, exposing processors to weather-driven yield volatility and quality inconsistency.
- REACH registration costs:European chemical safety documentation requirements impose six-figure euro expenditures per substance, excluding mid-scale Southeast Asian refiners from cosmetic-grade export channels.
- Palm olein substitution:Industrial frying and oleochemical feedstock buyers in India and Malaysia are switching to lower-cost palm-derived alternatives where label claims permit.
Strategic Opportunities
- Medicinal application trials:Healthcare provider studies in India and Germany are evaluating refined coconut oil for pharmaceutical excipient and nutraceutical delivery systems, opening regulated channel access.
- EU deforestation-free geolocation traceability:Early compliance with incoming supply chain due diligence rules positions integrated operators for preferential procurement contracts with European cosmetic houses.
- Cold-pressed hybrid processing:Conventional deodorization with enzymatic degumming is electrifying premium cosmetic-grade production, commanding 40-60% price premiums over standard refined grades.
Industry Challenges
- Analytical chemistry capacity gaps:Philippine and Indonesian mid-scale refiners lack in-house mass spectrometry and contaminant testing, creating bottlenecks in REACH and FDA food contact substance notification timelines.
- Legacy refinery reconfiguration:Converting solvent-extraction plants to physical refining for cosmetic-grade output requires stainless steel column replacement and vacuum system upgrades, stretching capital deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refined Coconut Oil Market |
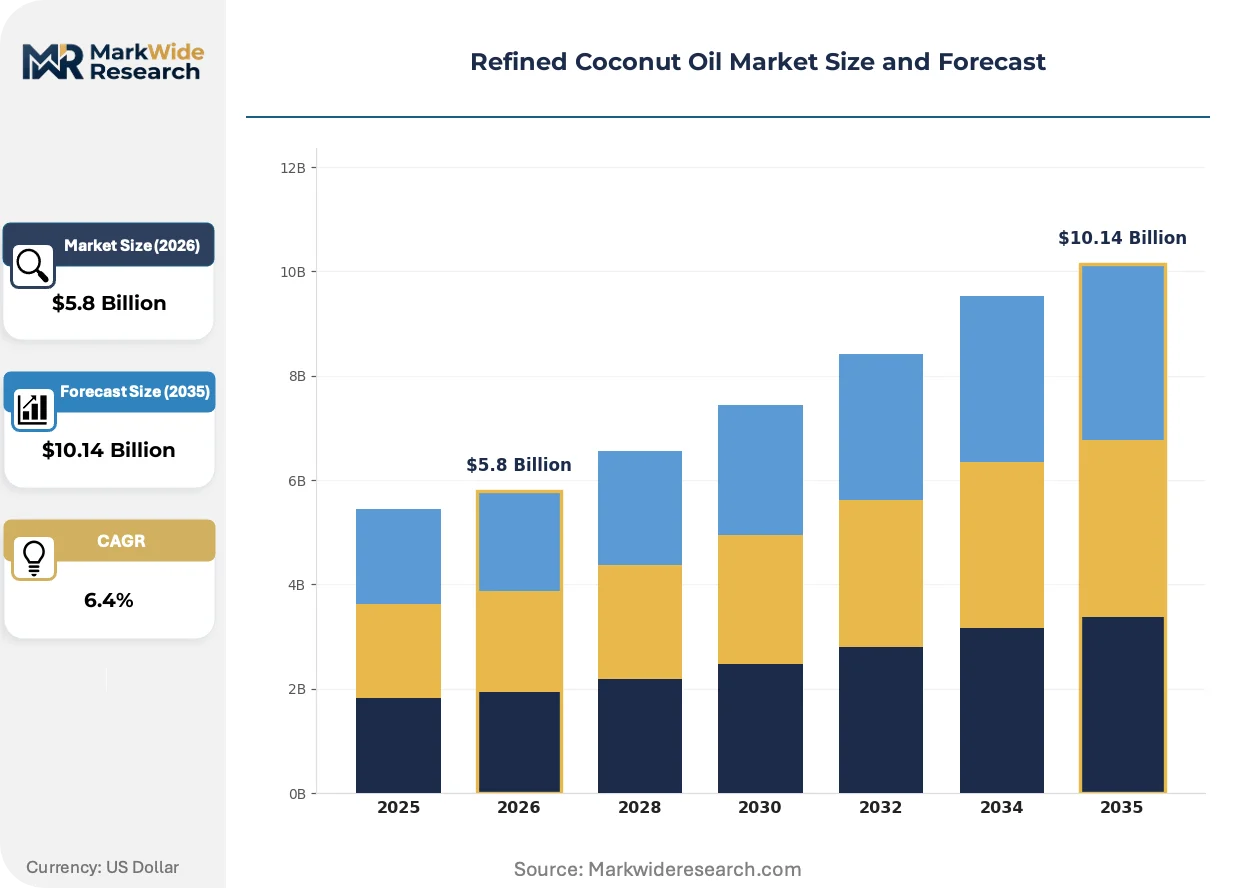
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Cosmetic Grade, Industrial Grade, Pharmaceutical Grade Application: Cooking, Skincare, Haircare, Medicinal Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales End User: Household, Food Processing, Cosmetic Manufacturers, Healthcare Providers |
| Companies Covered | Cargill Incorporated, Greenville Agro Corporation, Tantuco Enterprises, Roycefood Corporation, Celebes Coconut Corporation, Archer Daniels Midland Company, Bunge Limited, SC Coco Products, AarhusKarlshamn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refined Coconut Oil Market Evolving Landscape
Processing technology convergence with traceability infrastructure is redefining competitive advantage in refined coconut oil, separating integrated operators from commodity traders.
Enzymatic interesterification combined with membrane filtration is electrifying cosmetic-grade production by enabling sub-0.05% free fatty acid content without thermal degradation of tocopherols. Premium skincare formulators in South Korea and France are qualifying these grades for anti-aging serums and clean-label emollients. The technology is compressing traditional caustic refining margins and forcing asset write-downs among solvent-extraction dependent operators.
EU deforestation-free supply chain due diligence rules will mandate geolocation traceability for every copra batch entering European cosmetic and food channels by late 2025. Philippine Bureau of Product Standards and Indonesian National Standard certification bodies are scrambling to align batch-level documentation with satellite verification systems. Cosmetic-grade exporters with early compliance infrastructure are securing multi-year volume commitments from French and German formulators.
Clean-label procurement is consolidating buyer power among Southeast Asian institutional catering chains and European private-label snack manufacturers. Direct contracting with integrated Philippine and Indonesian refiners is displacing spot-market purchasing through Singapore trading houses. This pattern is most visible in Indonesia's oleochemical corridor, where food brands now specify refinery-of-origin documentation for frying oil supply agreements.
Refined Coconut Oil Market Segmentation
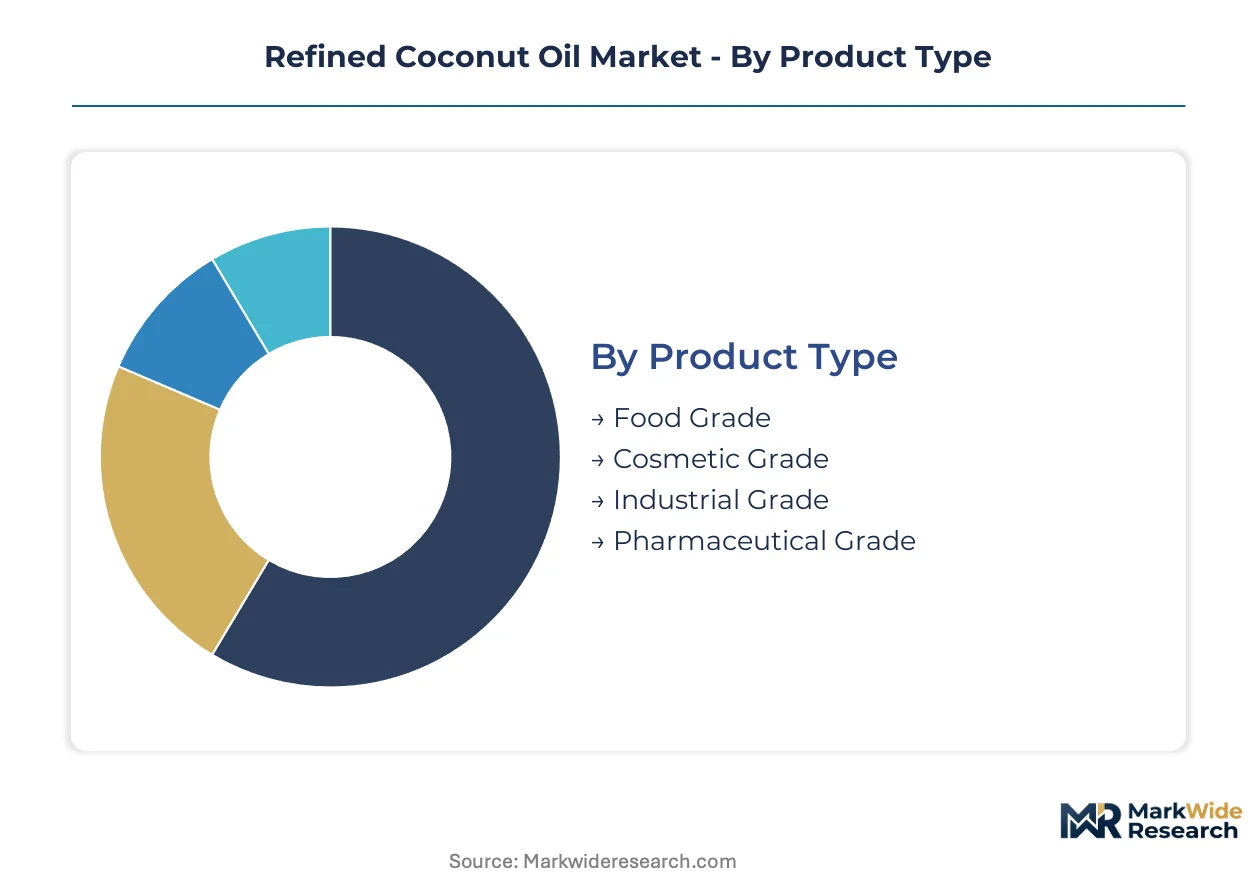
Segmentation in refined coconut oil reveals how quality thresholds and regulatory compliance reshape procurement patterns across food, cosmetic, and industrial channels. Distinct specifications for free fatty acid content, deodorization intensity, and traceability documentation create tiered market access that rewards integrated refiners over commodity traders.
Product Type:
Upgrade cycles in refining infrastructure are segmenting the market as processors replace solvent-extraction systems with physical refining columns to meet cosmetic-grade and pharmaceutical-grade thresholds.
- Food Grade:Deodorized and bleached to below 0.1% free fatty acid content with neutral flavor profile. Institutional catering chains in Indonesia and snack manufacturers across Southeast Asia specify refinery-of-origin documentation for frying oil supply agreements. Philippine Bureau of Product Standards mandates are filtering out non-compliant exporters and consolidating procurement among integrated operators with stainless steel column infrastructure.
- Cosmetic Grade:Sub-0.05% free fatty acid content achieved through enzymatic degumming and membrane filtration without thermal tocopherol degradation. Premium skincare formulators in France and South Korea qualify these grades for anti-aging serums and clean-label emollients. REACH registration costs and EMA cosmetic ingredient guidelines exclude mid-scale Southeast Asian refiners from this channel.
- Industrial Grade:Standardized feedstock for oleochemical derivatives and surfactant manufacturing with moderate purity tolerances.
- Pharmaceutical Grade:Ultra-purified batches meeting excipient standards for nutraceutical delivery systems and clinical trials in India and Germany.
Volume placements concentrate in Food Grade; the faster expansion belongs to Cosmetic Grade.
Application:
Cost tier differentiation separates commodity frying applications from premium personal care formulations requiring batch-level geolocation traceability.
- Cooking:Dominant throughput channel serving institutional catering, snack food manufacturing, and household frying across emerging-market dietary transitions. Indonesian oleochemical corridor refiners supply both domestic food brands and export markets with stable high-heat performance specifications.
- Skincare:Premium emollient applications demanding sub-0.1% free fatty acid content and preserved antioxidant profiles. French and German cosmetic houses specify compliant grades for clean-label positioning.
- Haircare:Conditioner and treatment oil formulations leveraging coconut oil's lipid penetration characteristics.
- Medicinal:Nascent but structurally supported by healthcare provider trials evaluating pharmaceutical excipient and nutraceutical delivery applications.
Household and institutional cooking absorb the largest volume; skincare applications command the steepest expansion trajectory.
Distribution Channel:
Customer type fragmentation is restructuring channel economics as direct contracting displaces spot-market purchasing through Singapore trading houses.
- Direct Sales:Integrated refiners in Indonesia's oleochemical corridor and Philippine plantation-proximate processors contract directly with food brands and European cosmetic manufacturers. EU deforestation-free supply chain due diligence rules favor operators with captive geolocation traceability infrastructure.
- Supermarkets:Mass-market bottled oil retail through Southeast Asian and European grocery chains with private-label specifications.
- Specialty Stores:Premium cosmetic-grade and cold-pressed hybrid products targeting organic and clean-label consumers.
- Online Retail:Direct-to-consumer channels for artisanal and certified grades with batch documentation.
Procurement gravity centers on Direct Sales; Online Retail is gaining share fastest among premium cosmetic grades.
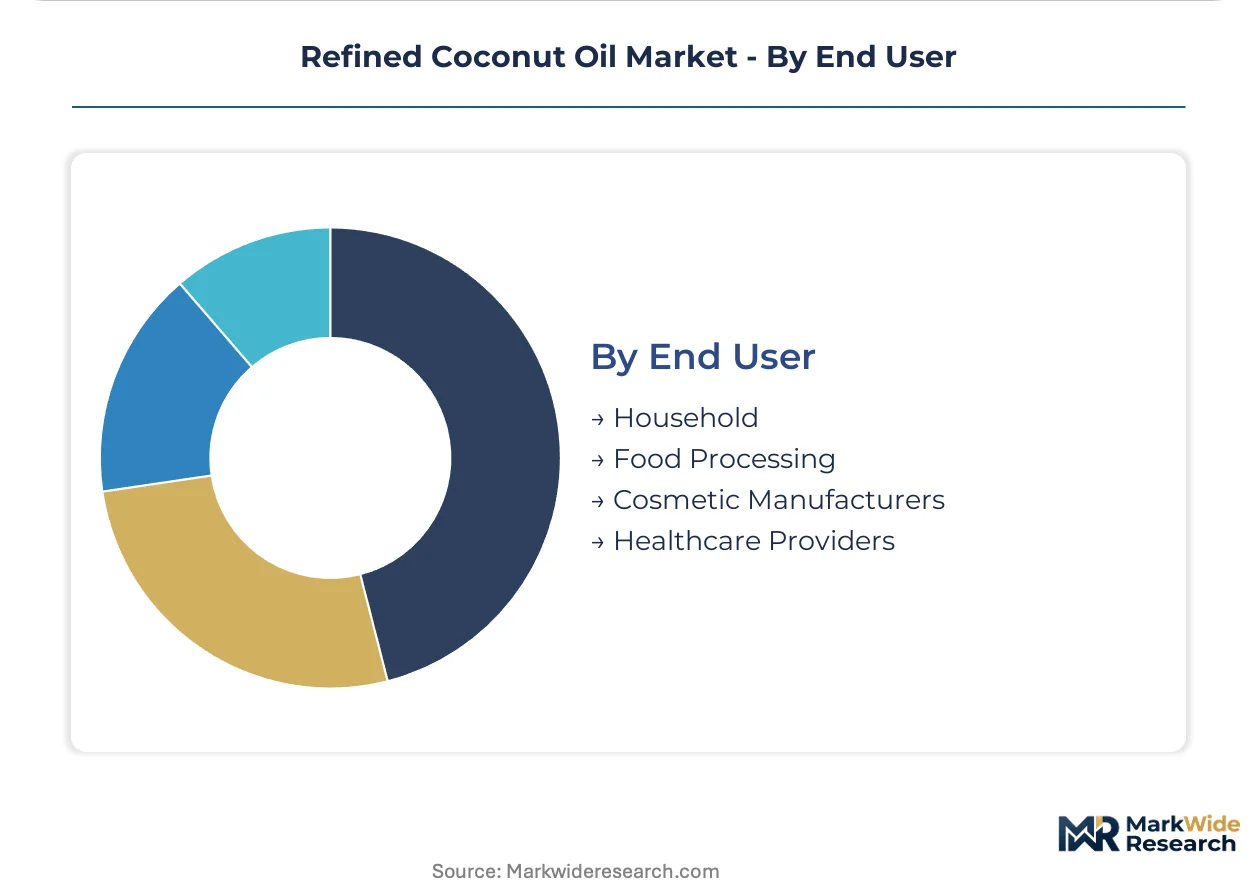
End User:
Supply concentration among integrated refiners is reshaping how volume flows to food processing manufacturers versus cosmetic formulators with divergent compliance burdens.
- Food Processing:Southeast Asian snack manufacturers reformulating to eliminate trans fats pull volume through Indonesia's oleochemical corridor. Clean-label procurement is consolidating buyer power and mandating refinery-of-origin documentation.
- Cosmetic Manufacturers:Premium skincare formulators in France and South Korea specify cosmetic-grade refined coconut oil with sub-0.1% free fatty acid content and REACH-compliant documentation.
- Household:Retail consumers purchasing through supermarkets and online channels for cooking and personal care applications.
- Healthcare Providers:Clinical trial sponsors in India and Germany evaluating pharmaceutical excipient and nutraceutical delivery system applications.
Food Processing anchors current volume; Healthcare Providers represent the most rapid climb in regulated channel access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's oleochemical corridor operates as a tax-incentive zone concentrating integrated refining capacity, while Philippine special economic zones cluster plantation-proximate processors serving export channels.
Indonesia
Snack manufacturers eliminating trans fats pull refined coconut oil volume through Surabaya and Jakarta's integrated refineries. BIS-aligned National Standard certification bodies align batch documentation with satellite verification systems. The oleochemical corridor supplies both domestic food brands and European cosmetic houses with stable high-heat performance specifications.
Philippines
Smallholder cooperatives in Quezon and Davao regions anchor raw material sourcing for deodorized and bleached output. The Bureau of Product Standards mandates stricter free fatty acid thresholds, filtering out low-grade exporters. Davao City processors with stainless steel column infrastructure consolidate procurement among compliant integrated operators.
France
Premium skincare formulators in Paris and Lyon specify cosmetic-grade refined coconut oil with sub-0.1% free fatty acid content for clean-label emollient applications. EMA cosmetic ingredient guidelines and REACH compliance elevate testing costs for Southeast Asian exporters. Cosmetic houses in the Île-de-France cluster secure multi-year volume commitments from early-compliant integrated operators.
South Korea
Seoul-based anti-aging serum manufacturers qualify enzymatic degumming grades with sub-0.05% free fatty acid content. MFDS cosmetic safety documentation requirements parallel EMA standards for preservative-free positioning. The Seoul Capital Area concentration drives specification tightening for tocopherol-preserving membrane filtration outputs.
Germany
Healthcare provider trials in Munich and Berlin evaluate pharmaceutical excipient applications for nutraceutical delivery systems. REACH registration costs impose six-figure euro expenditures per substance, excluding mid-scale Southeast Asian refiners. The Bavaria cluster anchors regulated channel access for ultra-purified batches meeting clinical trial standards.
Refined Coconut Oil Market Competitive Landscape
Philippine producers anchor one tier; Indonesian specialists hold geographic proximity advantages to plantation sources. The vendor base fragments across solvent-extraction dependent operators and physical refining upgraders, with consolidation pressure mounting from compliance cost burdens. Three archetypes dominate: integrated plantation-to-refinery operators, standalone cosmetic-grade specialists, and diversified agribusiness conglomerates with captive laboratory capacity. Capacity expansion and strategic partnerships represent the dominant competitive moves, as asset reconfiguration cycles stretch capital deployment timelines.
Among diversified agribusiness conglomerates, Cargill Incorporated and Archer Daniels Midland Company exemplify integrated supply chain operators with Southeast Asian copra sourcing infrastructure. Greenville Agro Corporation occupies a position within the cosmetic-grade specialist tier, while Tantuco Enterprises sits within the plantation-proximate processor archetype competing on raw material access. These three company profiles represent the structural segmentation between scale-driven diversification, premium-grade specialization, and geographic anchoring strategies.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Greenville Agro Corporation |
| Tantuco Enterprises |
| Roycefood Corporation |
| Celebes Coconut Corporation |
| Archer Daniels Midland Company |
| Bunge Limited |
| SC Coco Products |
| AarhusKarlshamn |
| Others |
Value Network & Pricing Analysis
Skilled refinery technicians in Surabaya and Davao City concentrate enzymatic degumming expertise, compressing labor-cost spreads between cosmetic-grade premiums and standard food-grade benchmarks. Philippine Bureau of Product Standards compliance investments widen tier differentials as non-compliant operators exit contract channels.
Pricing Analysis
Expedited lead-time premiums reward integrated Indonesian refiners with stainless steel column infrastructure serving European cosmetic houses, while spot-market copra purchases from Philippine smallholder cooperatives trade at volume discounts. Three-tier pricing structure across cosmetic-grade, food-grade, and industrial-grade levels reflects free fatty acid thresholds and REACH documentation burdens. Cost compression in standard food-grade runs through palm olein substitution in Indian frying applications. Industrial oleochemical buyers exhibit highest price sensitivity; French skincare formulators absorb premiums for sub-0.05% free fatty acid content with preserved tocopherol profiles.
Supply Chain Analysis
Copra supply rests on Philippine Quezon and Davao smallholder cooperatives alongside Indonesian Sulawesi and Sumatra plantation networks, with weather-driven yield volatility exposing processors to quality inconsistency. Solvent-extraction equipment, stainless steel refining columns, and membrane filtration systems constitute critical capital dependencies. Single-source vulnerability concentrates in Philippine smallholder channels lacking satellite-verified geolocation traceability. Distribution runs through direct contracting between integrated refiners and European cosmetic manufacturers, displacing Singapore trading house intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refined coconut oil supply is tightening around REACH-compliant laboratory capacity, with Philippine and Indonesian mid-scale refiners lacking mass spectrometry infrastructure excluded from premium cosmetic channels.
For Market Incumbents: Extend analytical chemistry capabilities through captive laboratory investment or third-party certification partnerships to defend cosmetic-grade margins against enzymatic degumming specialists. Consolidate procurement relationships with European cosmetic houses by pre-positioning EU deforestation-free geolocation traceability infrastructure ahead of regulatory deadlines. For New Entrants and Emerging Players: Cold-pressed hybrid processing with enzymatic degumming offers a technology-first wedge into South Korean anti-aging serum and French clean-label emollient segments underserved by solvent-extraction incumbents. Target pharmaceutical-grade production for Indian and German healthcare provider trials, leveraging regulatory greenfield status before incumbent laboratory capacity expands. For Investors and Strategic Acquirers: Re-rating potential sits with integrated plantation-to-refinery operators possessing captive geolocation traceability given EU deforestation-free due diligence rule enforcement. Five-to-ten year viability favors Philippine and Indonesian processors with backward integration into smallholder cooperative networks. Watch for REACH registration completion timelines as inflection signals for cosmetic-grade channel access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Smallholder Cooperatives | Captive copra supply secures volume commitments from European cosmetic houses requiring batch-level traceability. |
| Enzymatic Degumming Technology Deployment | Sub-0.05% free fatty acid achievement commands premium positioning in South Korean anti-aging formulations. |
| EU Deforestation-Free Compliance Infrastructure | Satellite verification systems unlock multi-year contracts with French and German skincare manufacturers. |
| Pharmaceutical-Grade Capacity Addition | Ultra-purified output accesses regulated channels for Indian and German clinical trial applications. |
| Analytical Chemistry Laboratory Investment | In-house mass spectrometry accelerates REACH and FDA food contact substance notification timelines. |
Research Methodology
Document review covered customs and trade flow databases, Philippine Bureau of Product Standards filings, and EMA cosmetic ingredient guidelines, complemented by interviews with refinery operations managers, procurement leads at European cosmetic manufacturers, Indonesian oleochemical corridor technical directors, and Singapore trading house commodity specialists. Secondary validation drew from FDA food contact substance notifications, REACH registration databases, and BIS refining purity standards. Bottom-up volume estimates triangulated against top-down demand projections from food processing and cosmetic formulation end-uses.
Segmented outputs across product grade tiers, application channels, and geographic production clusters informed value projections over the analysis window. Modeled dimensions spanned food-grade versus cosmetic-grade specifications, direct sales versus trading house distribution, and Indonesian versus Philippine supply origin. CAGRs derived from historical volume trajectories adjusted for regulatory compliance cost inflections and substitution elasticity with palm olein alternatives. Forecast inputs incorporated Philippine smallholder yield volatility patterns and European cosmetic house procurement consolidation trends.
Several conditions sit outside the modeled scope, including sudden Philippine weather shocks disrupting copra supply, accelerated palm olein substitution in Indian industrial frying, and unilateral REACH registration fee adjustments. Forecasts reflect documented assumptions regarding regulatory timeline adherence and smallholder cooperative documentation system readiness. A small set of named triggers warrants ongoing watch: EU deforestation-free enforcement rigor, Philippine Bureau of Product Standards threshold revisions, and South Korean MFDS cosmetic safety documentation alignment with EMA standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Autolyzed Yeast Extract Market
Ingredients
Dry Malt Products Market
Ingredients
Cocoa Market
Ingredients
Yeast Autolysates Market
Ingredients
India Protein Market
Ingredients
Valerian Root Oil Market
Ingredients
Global Yeast Market
Ingredients
Carob Protein Market
Ingredients
South America Protein Market
Ingredients
Wheat Protein Concentrates Market
Ingredients
Global Amaranth Oil Market
Ingredients
Low-Odor Fish Protein Hydrolysates from Med Species Market
Ingredients
Alginate Market
Ingredients
Fucoidan Extract Market
Ingredients
Middle East and Africa Fermented Ingredients Market
Ingredients
North America Alcohol Ingredients Market