
 Fried Potato Chips Market | 2026-2036
Fried Potato Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Fried Potato Chips Market Analysis
Subscription-based snack replenishment services is repositioning how fried potato chips reach repeat buyers. PepsiCo, Inc. leverages its direct-to-consumer infrastructure to capture recurring revenue streams. Calbee, Inc. anchors its growth on Japanese convenience store exclusivity and flavor localization. The Kellogg Company competes through controlled retail shelf placement and promotional bundling with cereal portfolios.
Fried potato chips are thin-sliced potatoes deep-fried in vegetable oils at temperatures between 350°F and 375°F, then seasoned and packaged for shelf-stable consumption; the process yields a moisture content below 2% that ensures crispness and extended storage. Their primary commercial purpose is to serve as impulse-purchase snack items across retail and foodservice channels. Classic flavor profiles still dominate volume sales, though barbecue variants are capturing faster growth in North American convenience stores. Pouch packaging is displacing rigid formats in online retail channels due to lower shipping weights and reduced breakage rates.
The FDA governs nutritional labeling and trans fat disclosures for fried potato chips sold in the United States, while the EFSA and EU Green Deal frameworks are pressuring European manufacturers toward lower-emission frying processes and sustainable packaging materials. India's FSSAI enforces additive limits and hygiene standards that determine which imported brands gain market access. Stakeholders must monitor how oil innovation timelines intersect with tightening regulatory thresholds for acrylamide and saturated fat content.
Market Dynamics
The FDA's updated trans fat labeling requirements are forcing wholesale reformulation of frying oil compositions across the entire fried potato chips value chain, compressing margins for manufacturers dependent on legacy hydrogenated oil supply contracts.
Growth Catalysts
- Quick-service restaurant expansion:Southeast Asian QSR chains are aggressively adding chip-based side menus to capture snack-adjacent revenue streams, pulling volume from traditional retail channels.
- EU Green Deal compliance:European manufacturers investing in lower-emission frying processes gain preferential shelf placement from sustainability-focused retail buyers.
- Flavor localization:Regional taste adaptation in Japanese convenience stores is unlocking repeat purchase frequency previously unattainable with standardized global portfolios.
Market Restraints
- Input cost volatility:Sunflower and palm oil prices fluctuate with commodity futures, squeezing gross margins for mid-tier producers without long-term agricultural contracts.
- Supply concentration risk:Specialty fryer equipment manufacturing concentrates in German and Japanese industrial clusters, creating procurement bottlenecks during capacity constraints.
- Acrylamide regulatory thresholds:EFSA guidelines on process contaminant limits require capital-intensive production line modifications that smaller operators cannot finance.
Strategic Opportunities
- Subscription channel penetration:Direct-to-consumer replenishment services bypass retail slotting fees and capture lifetime value through automated reorder algorithms.
- India's urban snack corridors:Dense metropolitan consumption clusters in Mumbai, Delhi, and Bangalore offer concentrated distribution economics for premium-positioned entrants.
- Pouch packaging innovation:Flexible film formats reduce shipping weights by 40% versus rigid containers, enabling profitable e-commerce fulfillment previously uneconomical for fragile products.
Industry Challenges
- Process engineering talent scarcity:Deep-fat frying optimization requires specialized food science expertise that vocational programs in emerging production regions fail to produce.
- Oil innovation timeline compression:R&D cycles for next-generation low-saturated-fat formulations must accelerate to meet overlapping FDA, EFSA, and FSSAI disclosure deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fried Potato Chips Market |
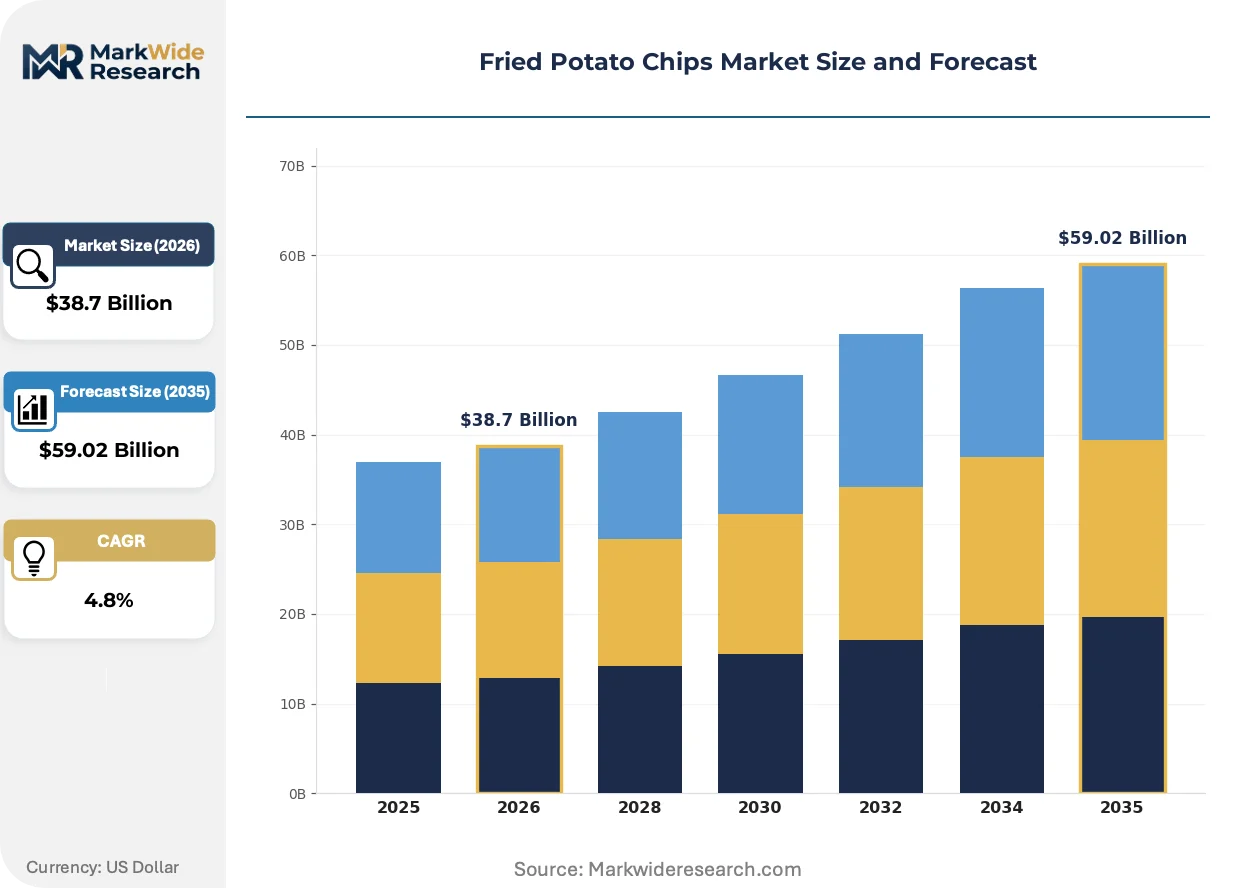
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic, Barbecue, Sour Cream & Onion, Cheddar Cheese Packaging Type: Bags, Cups, Boxes, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Wholesalers Customer Type: Households, Restaurants, Food Trucks, Snack Bars |
| Companies Covered | Calbee, Inc., Mondelez International, Inc., PepsiCo, Inc., The Kellogg Company, Herr Foods Inc., Kellanov, Utz Brands, Inc., Tayto Group Limited, Intersnack Group GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fried Potato Chips Market Emerging Trajectories
Three intersecting forces are restructuring how fried potato chips are formulated, regulated, and delivered to end consumers, with implications rippling from agricultural inputs through final-mile logistics.
Vacuum frying technology is integrating into premium product lines as a lower-temperature alternative to conventional atmospheric frying, preserving native potato flavor compounds while reducing oil uptake. Japanese and South Korean snack manufacturers are adopting these systems fastest, driven by consumer willingness to pay for cleaner-label positioning. The structural consequence is a bifurcation in equipment supplier relationships, with traditional fryer OEMs losing share to specialized vacuum system vendors.
EFSA's evolving stance on acrylamide mitigation is compelling European manufacturers to implement real-time process control systems that monitor Maillard reaction endpoints. Industrial consequence includes mandatory HACCP protocol revisions and third-party verification audits for export eligibility. German and Dutch production facilities face the steepest compliance curves due to their concentration of private-label manufacturing for pan-European retail chains.
Urban Indian consumers are consolidating snack purchases around bundled delivery apps that aggregate kirana stores, supermarkets, and direct brand inventory into single-basket fulfillment. Quick-commerce platforms are displacing traditional distributor networks in Mumbai and Bangalore, compressing delivery windows to under ten minutes. This pattern is most visible in premium flavor variants where impulse substitution risk is lowest and basket-building economics favor higher-margin SKUs.
Fried Potato Chips Market Segmentation
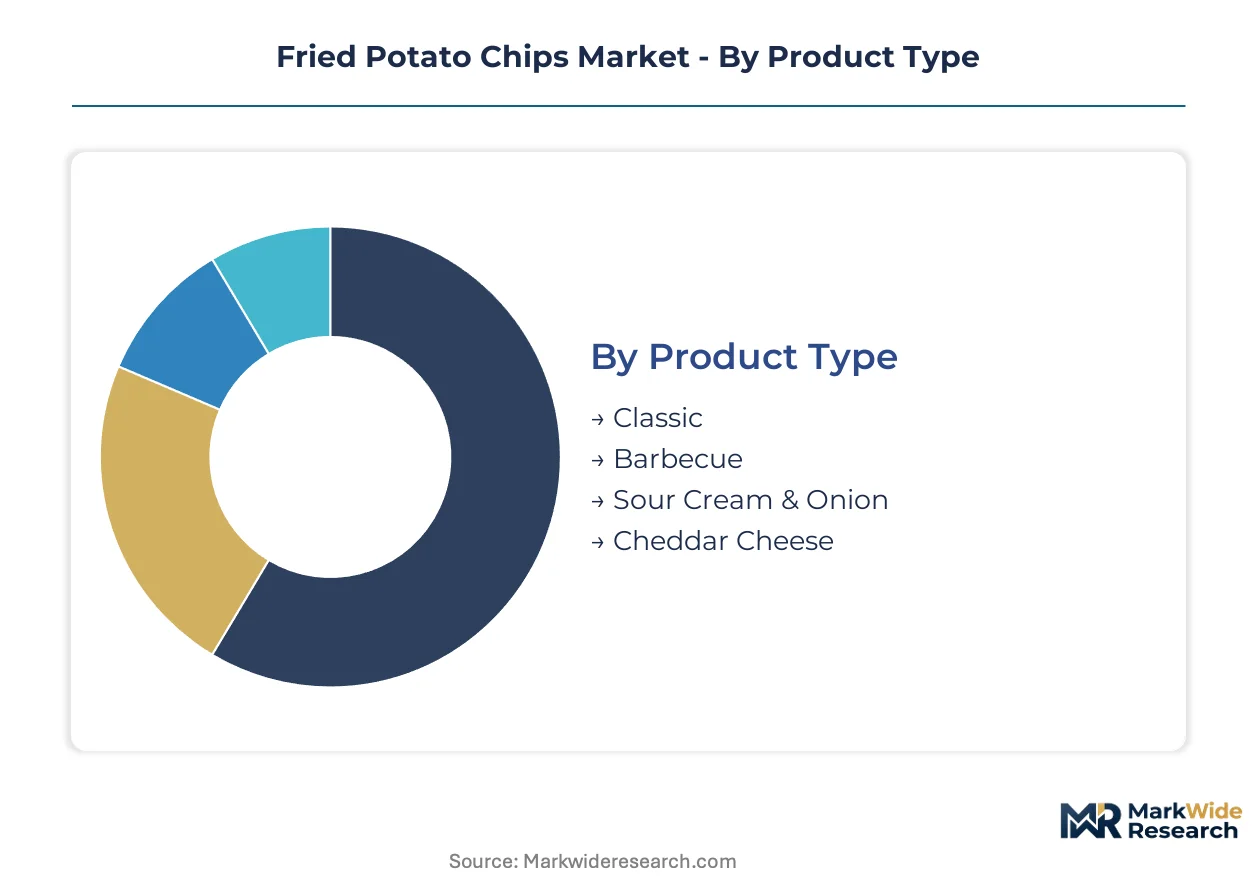
Segmentation in fried potato chips reveals how formulation, format, and channel choices cascade through margin structures. Manufacturers align R&D spend and packaging investments against distinct buyer willingness-to-pay thresholds across consumption occasions.
Product Type:
Flavor preference separates impulse buyers from planned purchasers, with taste loyalty driving repeat purchase rates and premium pricing tolerance.
- Classic:Unseasoned or lightly salted formulations dominate volume shipments across all retail tiers. Demand concentrates in Indian urban snack corridors and Southeast Asian QSR side-menu programs where neutral flavor profiles accommodate diverse regional palates alongside local condiments.
- Barbecue:Tomato-based, smoke-flavored coatings capture faster velocity in North American convenience stores. Growth tilts toward this segment as limited-time regional barbecue variants—Carolina vinegar, Texas mesquite—extend purchase frequency through novelty cycling.
- Sour Cream & Onion:Dairy-forward seasoning systems require modified atmosphere packaging to preserve volatile flavor compounds. European retail buyers favor this profile for promotional bundling with dip and beverage categories.
- Cheddar Cheese:Cheese powder adhesion demands specialized oil formulations to prevent clumping during high-temperature frying. This segment commands shelf placement in US club store formats where multi-pack configurations justify warehouse-scale packaging.
Volume sits with Classic; growth tilts toward Barbecue.
Packaging Type:
Format selection determines distribution economics, with shipping density and breakage rates dictating channel viability.
- Bags:Flexible film laminates with nitrogen flush systems remain the default for retail shelf placement. Demand concentrates in supermarkets and wholesale clubs where vertical bag displays maximize linear footage efficiency and visual blocking at point-of-purchase.
- Pouches:Stand-up flexible formats with resealable closures reduce shipping weights by 40% versus rigid alternatives. Growth is accelerating fastest in online retail channels where dimensional weight pricing and last-mile handling costs favor collapsible structures.
- Cups:Rigid single-serve containers target immediate consumption occasions in transit hubs and vending networks. Japanese convenience store operators specify cup formats for grab-and-go placement adjacent to beverage coolers.
- Boxes:Corrugated or paperboard enclosures serve institutional foodservice and promotional gift configurations. Indian kirana aggregators utilize box formats for quick-commerce bundling where multi-SKU consolidation reduces per-delivery cost.
Volume sits with Bags; growth tilts toward Pouches.
Distribution Channel:
Channel selection determines margin capture, with slotting fees and delivery windows compressing profitability at different rates.
- Supermarkets:Full-format grocery operators demand promotional calendar compliance and category management support. PepsiCo and Kellogg deploy dedicated shelf-reset teams to defend linear footage against private-label encroachment in this channel.
- Convenience Stores:Small-format retailers with limited backroom storage require frequent direct-store-delivery cycles. Calbee anchors Japanese growth through exclusive flavor distribution agreements with Lawson and 7-Eleven Japan.
- Online Retailers:E-commerce fulfillment centers prioritize crush-resistant packaging and extended shelf-life specifications. Pouch packaging innovation enables profitable shipping of fragile products previously uneconomical for direct-to-consumer channels.
- Wholesalers:Broadline distributors serve institutional accounts and independent retail operators with pallet-scale purchasing. This channel concentrates in India's urban snack corridors where distributor networks aggregate fragmented kirana demand.
Volume sits with Supermarkets; growth tilts toward Online Retailers.
Customer Type:
End-use application dictates product specification, with food safety requirements and portion control needs diverging sharply.
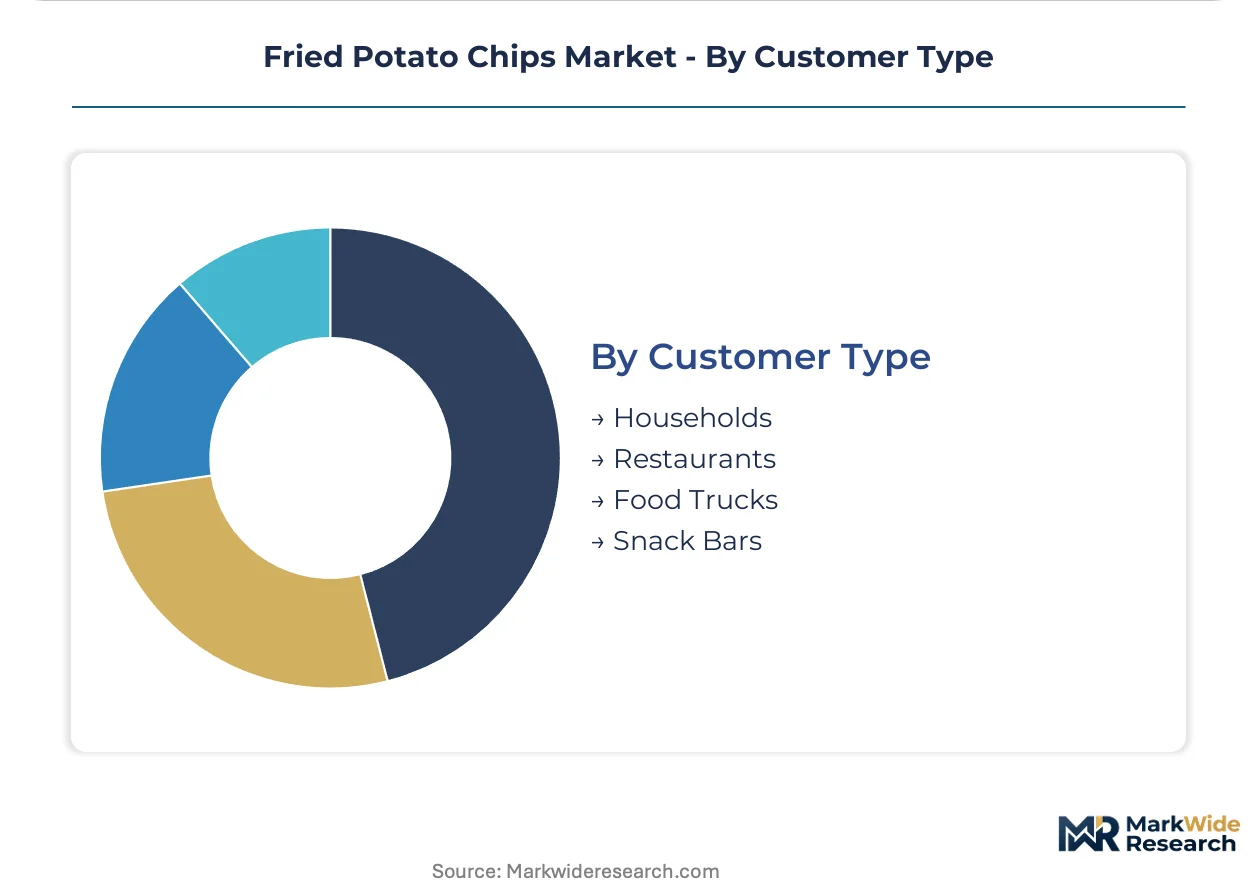
- Households:Individual consumers purchasing for at-home consumption drive flavor variety and package size proliferation. Subscription-based replenishment services target this segment with automated reorder algorithms that bypass retail slotting fees.
- Restaurants:Quick-service and casual dining operators specify bulk formats with holding-time stability for batch frying operations. Southeast Asian QSR chains are expanding chip-based side menus, pulling volume from traditional retail channels into foodservice procurement.
- Food Trucks:Mobile foodservice operators require shelf-stable, ambient-temperature storage without refrigeration infrastructure. Pre-portioned bag formats minimize serving labor and inventory tracking complexity for rotating menu boards.
- Snack Bars:Dedicated snack retail concepts and cinema concessions demand proprietary flavor exclusives and co-branded packaging. Japanese convenience store exclusivity models demonstrate how snack bar partnerships build defensible regional positions.
Volume sits with Households; growth tilts toward Restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in North American and European processing hubs, while consumption growth accelerates across Asian urban corridors. This geographic split shapes capital deployment patterns and regulatory compliance investments across the value chain.
United States
Impulse-purchase velocity in convenience stores and quick-service restaurant side-menu adoption drive volume demand. FDA trans fat labeling requirements are forcing wholesale oil reformulation across legacy hydrogenated supply contracts. Processing clusters in the Midwest and Southeast maintain proximity to potato agriculture and distribution infrastructure.
India
Urban snack corridors in Mumbai, Delhi, and Bangalore concentrate premium consumption through quick-commerce aggregator platforms. FSSAI additive limits and hygiene standards determine import eligibility for international brands. Kirana store digitization is displacing traditional distributor networks in metropolitan clusters.
Germany
Private-label manufacturing for pan-European retail chains dominates production volume. EU Green Deal frameworks are pressuring lower-emission frying processes and sustainable packaging material transitions. Industrial equipment manufacturing concentrates in Baden-Württemberg and North Rhine-Westphalia, creating procurement dependencies for fryer system upgrades.
Japan
Convenience store exclusivity agreements and flavor localization unlock repeat purchase frequency unavailable to standardized global portfolios. METI industrial standards shape equipment specification requirements for domestic production facilities. Vacuum frying technology adoption concentrates in Kansai and Chubu regional manufacturing bases.
United Kingdom
Promotional bundling with beverage and dip categories sustains retail shelf placement economics. EFSA acrylamide mitigation guidelines require real-time process control system implementation across production lines. Snack bar and cinema concession partnerships in London and Southeast England build defensible regional positions through proprietary flavor exclusives.
Fried Potato Chips Market Vendor Landscape
Top-tier vendors anchor scale-driven portfolio diversification, while mid-tier specialists compete through regional flavor localization and channel exclusivity. The vendor base stratifies across three archetypes: multinational conglomerates with direct-to-consumer infrastructure, regional convenience store partners with exclusive distribution agreements, and private-label manufacturers serving retail chain consolidation. Dominant competitive moves include M&A activity targeting flavor technology capabilities and strategic partnerships with quick-commerce platforms.
Within the multinational tier, PepsiCo, Inc. and The Kellogg Company occupy positions exemplifying scale-driven retail shelf defense and promotional bundling integration. Calbee, Inc. represents the regional specialist archetype, anchoring growth through Japanese convenience store exclusivity. These three entities collectively illustrate how competitive positioning diverges between global portfolio breadth and localized channel penetration.
| Leading Market Players |
|---|
| Calbee, Inc. |
| Mondelez International, Inc. |
| PepsiCo, Inc. |
| The Kellogg Company |
| Herr Foods Inc. |
| Kellanov |
| Utz Brands, Inc. |
| Tayto Group Limited |
| Intersnack Group GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
Process engineering talent scarcity in Baden-Württemberg and North Rhine-Westphalia compresses R&D labor cost differentials, widening spreads between premium vacuum-fried lines and economy atmospheric-fried tiers across European and Asian production bases.
Pricing Analysis
Margin tightening in mid-tier SKUs traces to sunflower and palm oil futures volatility that squeezes producers lacking long-term agricultural contracts. Three-tier pricing structure across premium, standard, and economy levels separates vacuum-fried positioning from conventional lines from QSR bulk formats. Cost-down pressure on standard-tier products accelerates because EFSA acrylamide compliance investments concentrate capital among scale players. Quick-service restaurant procurement teams show highest price sensitivity; subscription-channel households demonstrate lowest.
Supply Chain Analysis
Freight cost inflation on flexible film laminates from German and Japanese industrial clusters compresses margin capture for pouch-format innovators. Potato sourcing concentrates in the United States, Germany, and India; specialty fryer equipment manufacturing anchors in Baden-Württemberg and Chubu. Palm oil and nitrogen flush packaging films constitute critical input dependencies. Single-source vulnerability in vacuum fryer OEM relationships creates procurement chokepoints. Distribution runs through wholesaler networks in Indian urban corridors and direct-store-delivery systems in Japanese convenience store channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EFSA acrylamide mitigation guidelines erect barrier-to-entry moats favoring capital-rich incumbents with real-time process control capabilities.
For Market Incumbents: Hedge margin exposure through backward integration into specialty oil formulation R&D and captive supply of vacuum frying equipment. Acquire flavor technology capabilities before FDA disclosure deadlines compress acquisition premiums. Defend shelf position by locking exclusive quick-commerce partnerships in Mumbai and Bangalore corridors against emerging regional specialists. For New Entrants and Emerging Players: Subscription-based replenishment services offer the lowest-friction entry vector, bypassing slotting fees that consume 12-18 points of gross margin in traditional retail. Target India's urban snack corridors where kirana digitization displaces legacy distributor relationships. Lead with pouch-format premium positioning to exploit 40% shipping weight advantages against rigid-container incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with private-label manufacturers serving pan-European retail chains given EU Green Deal compliance investments that smaller operators cannot finance. Long-term viability favors scale players with cross-regulatory certification spanning FDA, EFSA, and FSSAI frameworks. Watch for vacuum fryer equipment vendor consolidation as the inflection signal for premium-tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Oil Formulation R&D Investment | Low-saturated-fat formulations meeting overlapping FDA and EFSA thresholds capture premium shelf placement. |
| Vacuum Frying Technology Adoption | Japanese and South Korean manufacturers leverage lower-temperature processing for cleaner-label positioning. |
| Quick-Commerce Platform Partnership | Ten-minute delivery aggregators in Mumbai and Bangalore displace traditional kirana distributor networks. |
| Flexible Pouch Packaging Transition | 40% shipping weight reduction enables profitable e-commerce fulfillment for fragile products. |
| Flavor Localization Programs | Japanese convenience store exclusivity agreements build defensible repeat purchase frequency. |
Methodological Framework
Multi-period observation of frying oil futures, equipment procurement lead times, and regulatory disclosure timelines anchored the trend analysis, supplemented by interviews with plant engineers at German and Japanese manufacturing facilities, category buyers at Southeast Asian QSR chains, flavor technology R&D directors, and quick-commerce platform supply chain managers. Secondary validation drew from FDA guidance documents, EFSA scientific opinions on process contaminants, FSSAI additive notifications, customs trade data on potato and oil imports, and SEC filings of publicly traded snack manufacturers. Bottom-up production capacity modeling and top-down consumption clustering across urban Indian corridors were triangulated.
Input-output matrices mapped potato supply, oil formulation, frying technology, and packaging format against distribution channel economics across the projection horizon. Segmentation dimensions modeled included flavor profile, packaging type, distribution channel, and customer type. CAGRs were derived from regression analysis of historical volume trajectories and elasticity-adjusted price assumptions. Industry-specific forecast inputs incorporated EFSA acrylamide threshold implementation schedules and METI equipment specification revisions.
The model holds under stable regulatory disclosure timelines and contained commodity volatility; deviation in palm oil price spikes or accelerated FSSAI hygiene enforcement would shift volume projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
South America Frozen Snacks Market
Snacks
Corn Chips Market
Snacks
Low Fat Crackers Market
Snacks
Global Snack Food Market
Snacks
South Korea Snack Bar Market
Snacks
Extruded Snacks Market
Snacks
Low Fat Granola Market
Snacks
Italy Energy Bar Market
Snacks
Europe Frozen Snacks Market
Snacks
Spicy Sticks (Chinese Snack) Market
Snacks
United Kingdom Snack Bar Market
Snacks
Low Sodium Snacks Market
Snacks
Austria Snack Bar Market
Snacks
Veggie Chips Market
Snacks
Saudi Arabia French Fries Market
Snacks
Flexible Plastic Snack Food Packaging Market