
 Icing Shortening Market | 2026-2036
Icing Shortening Market Size, Share, and Industry Trends Forecast 2026-2036
Icing Shortening Market Foresight
North American production capacity is reshaping competitive dynamics in icing shortening. Cargill Incorporated leverages its integrated oilseed processing network to secure supply chain advantages across the continent. Bunge Limited anchors its position through extensive crushing and refining infrastructure in the United States and Canada. AAK AB differentiates via specialty fat technologies tailored to confectionery applications.
Icing shortening comprises refined vegetable or animal fats formulated with emulsifiers to achieve specific plasticity, melting profiles, and aeration stability for decorative cake coatings and fillings. Manufacturers hydrogenate or interesterify oils to control solid fat content across temperature ranges, ensuring consistent texture during whipping and piping operations. Vegetable shortening dominates volume due to cost efficiency and cleaner flavor neutrality in frosting applications. Solid and semi-solid forms command premium positioning among artisanal bakeries requiring precise workability, while liquid formats gain traction in industrial automated depositing systems.
FDA nutrition labeling mandates and PHO restrictions continue driving reformulation toward fully hydrogenated and non-hydrogenated alternatives in the United States. BIS quality standards and FSSAI food safety codes govern product specifications and import requirements in India. Stakeholders must monitor evolving regulatory thresholds for saturated fat claims and emerging sustainability certification demands from palm oil sourcing regions.
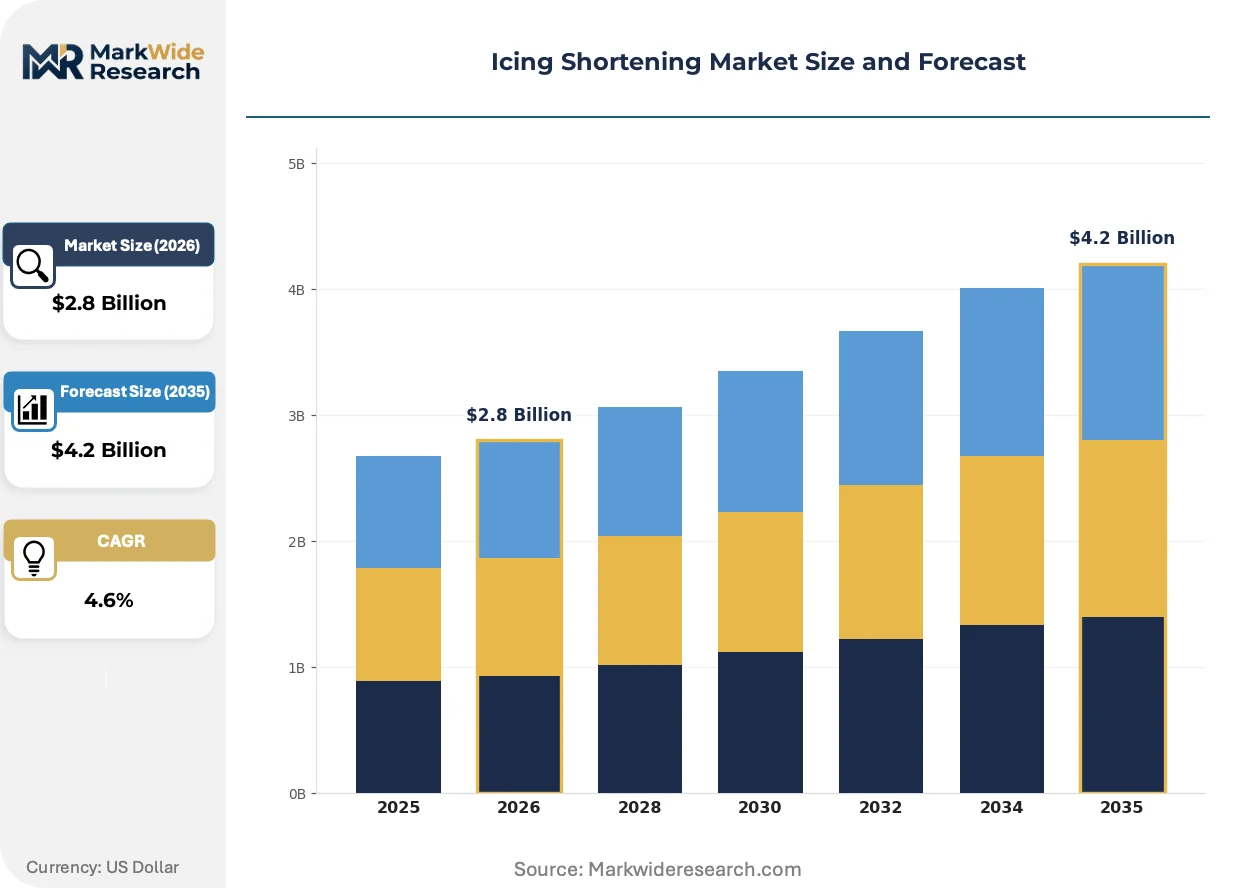
Market Dynamics
Trans fat elimination mandates across North American and European jurisdictions are forcing complete reformulation of hydrogenated fat portfolios, redirecting capital toward enzymatic interesterification and fractionation infrastructure.
Growth Catalysts
- Clean-label procurement mandates:Commercial bakeries in the United States and Canada now require non-hydrogenated shortening certificates, pulling volume toward fully hydrogenated and palm-based alternatives.
- EFSA saturated fat thresholds:European confectionery manufacturers are reformulating to meet evolving nutrition claim standards, expanding demand for structured lipids with controlled solid fat content curves.
- Interestification technology maturation:Enzymatic processes now achieve precise triglyceride positioning without trans fat generation, enabling texture parity with legacy PHO formulations.
Market Restraints
- Palm oil price volatility:Indonesian and Malaysian export duty fluctuations create margin compression for refiners dependent on Southeast Asian feedstock supply.
- Technical performance gaps:Non-hydrogenated alternatives in certain high-ratio cake applications fail to match the aeration stability and creaming power of traditional PHO-based shortenings.
- FDA labeling friction:Added sugars disclosure requirements and saturated fat callout rules complicate marketing positioning for premium frosting applications targeting health-conscious consumers.
Strategic Opportunities
- Indian bakery modernization:FSSAI enforcement of standardized shortening specifications creates first-mover advantage for suppliers offering pre-certified, import-ready formulations.
- Shea butter fractionation convergence:Blending shein olein with palm mid-fraction yields novel fat systems with distinct melting profiles for temperate climate distribution.
- E-commerce ingredient channels:Direct-to-bakery digital platforms bypass traditional foodservice distributors, capturing artisanal segment volume with smaller MOQ flexibility.
Industry Challenges
- Reformulation technical talent scarcity:Lipid chemistry expertise capable of balancing cost, functionality, and clean-label positioning commands premium compensation and extended recruitment timelines.
- Legacy equipment incompatibility:Industrial bakeries running automated depositing systems face retrofit requirements when transitioning between solid and liquid shortening formats.
- Multi-jurisdiction certification complexity:Simultaneous compliance with FDA, EFSA, and BIS standards extends product development cycles and testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Icing Shortening Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Shortening, Animal Shortening, Margarine, Blends End Use: Baking, Frosting, Confectionery, Snacks Form: Liquid, Solid, Semi-Solid, Powder Packaging Type: Buckets, Pails, Cartons, Tubs |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Bunge Limited, Barry Callebaut, Wilmar International Limited, AAK AB, Fuji Oil Holdings, Ventura Foods, Manildra Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Icing Shortening Market Shifts & Advancements
Digital formulation tools and accelerated stability testing protocols are compressing product development cycles, while sustainability verification systems reshape procurement qualification criteria across industrial bakery supply chains.
Enzymatic interesterification is virtualizing the traditional hydrogenation infrastructure requirement. Mid-sized North American refiners deploy continuous enzymatic reactors to produce trans-free shortening with precise solid fat content control. This technology is virtualizing the capital barrier that previously concentrated high-performance shortening production among integrated oilseed processors with legacy hydrogenation assets.
REACH authorization requirements for food-contact substances and the EU Green Deal sustainable palm certification mandates are restructuring European supply chains. Refiners must now document mass-balance chain of custody through RSPO-certified channels. German and French confectionery manufacturers face the steepest compliance burden, accelerating backward integration into certified palm fractionation.
Artisanal bakery clusters are consolidating purchasing through cooperative buying platforms that disintermediate traditional broadline distributors. Brooklyn, Melbourne, and London craft bakery networks now aggregate demand for specialty fats with defined plasticity ranges and origin documentation. This channel shift concentrates negotiation leverage among platform operators while fragmenting volume across multiple regional shortening suppliers.
Icing Shortening Market Segmentation
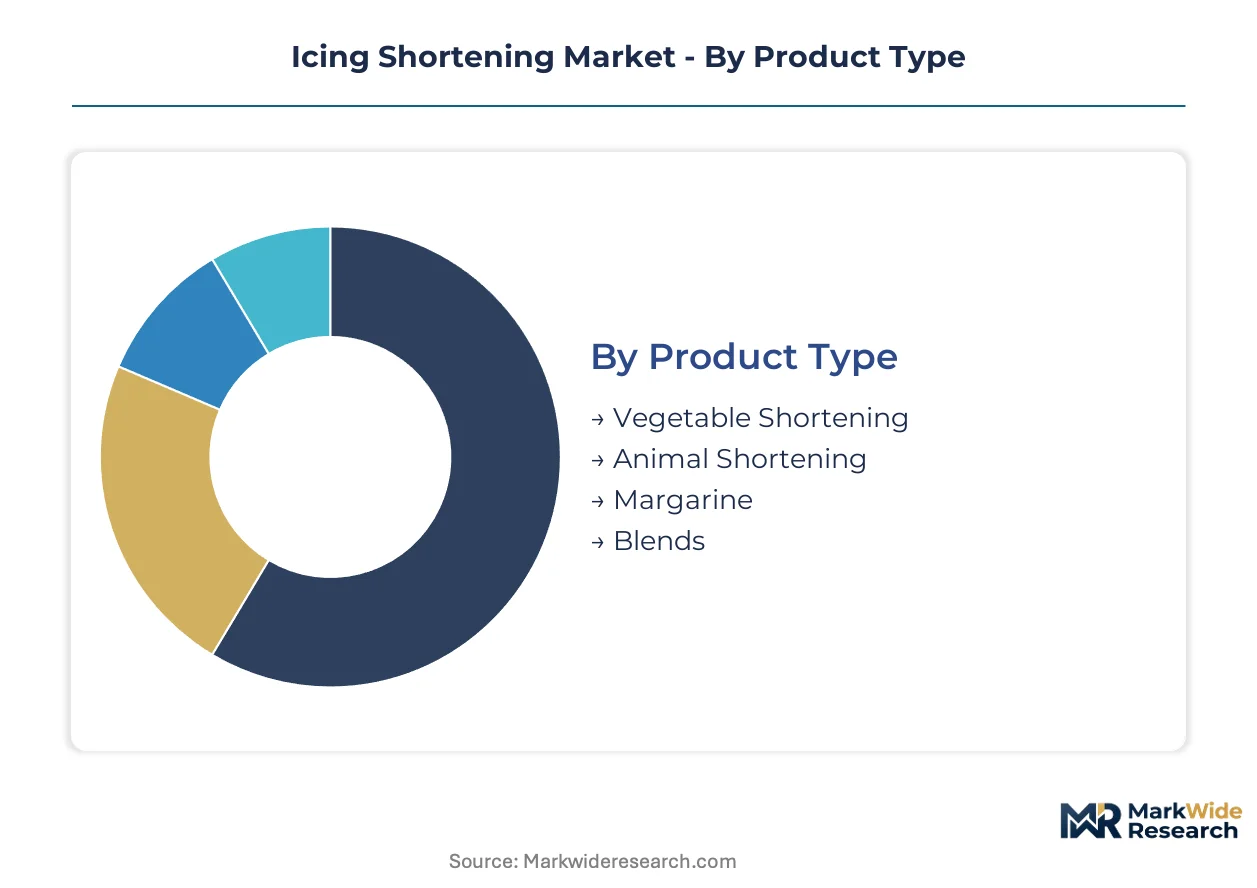
Icing shortening formulation varies dramatically across product architectures, with each segment commanding distinct supply chain configurations and technical specifications. Manufacturers align production assets to specific end-use performance requirements rather than pursuing universal formulations.
Product Type:
Cost tier differentiation separates commodity vegetable bases from premium animal-derived and specialty blend alternatives.
- Vegetable Shortening:Refined palm, soybean, or canola oils undergo full hydrogenation or interesterification to achieve controlled solid fat content curves. Commercial bakeries in the United States and Canada now mandate non-hydrogenated certificates, redirecting procurement toward enzymatically processed palm fractions.
- Animal Shortening:Rendered beef tallow and lard deliver superior creaming power and distinctive flavor profiles for heritage bakery applications. Artisanal producers in Brooklyn and London pay premiums for traceable sourcing despite restricted volume scalability.
- Margarine:Water-in-fat emulsions with lower saturated fat positioning target health-claim labeling requirements.
- Blends:Hybrid formulations balance cost efficiency with targeted melting behavior for climate-specific distribution.
Vegetable shortening commands the established base. The steepest expansion runs through enzymatically processed palm fractions.
End Use:
Application-driven performance specifications determine emulsifier selection and plasticity engineering priorities.
- Baking:Lamination and cake applications demand precise solid fat content across temperature ranges to ensure consistent crumb structure. Industrial facilities in Germany and France require RSPO-certified mass-balance documentation for palm-derived inputs.
- Frosting:Decorative applications prioritize aeration stability and piping definition. Brooklyn and Melbourne craft bakery networks now aggregate demand through cooperative platforms with defined plasticity range specifications.
- Confectionery:Chocolate-compatible fat systems require sharp melting profiles and bloom resistance.
- Snacks:Frying stability and extended shelf life drive interesterified formulations with oxidative resistance.
Baking applications anchor volume concentration. Frosting specialization is climbing the fastest as artisanal segment procurement consolidates.
Form:
Physical state selection reflects automation compatibility and climate-adjusted workability requirements.
- Solid:Block and flake formats deliver maximum shelf stability and precise portion control for small-batch operations. Artisanal bakeries in temperate climates prefer solid forms for manual creaming methods.
- Semi-Solid:Tub-packed shortenings balance scoopability with structure retention. Automated depositing systems in industrial facilities favor pumpable semi-solids with controlled yield stress.
- Liquid:Pourable interesterified oils suit continuous mixing operations and warm-climate distribution.
- Powder:Encapsulated fat systems enable extended shelf life and reduced cold-chain dependency for remote bakery operations.
Solid forms retain the largest installed base. Semi-solids are expanding most quickly through industrial automation retrofit cycles.
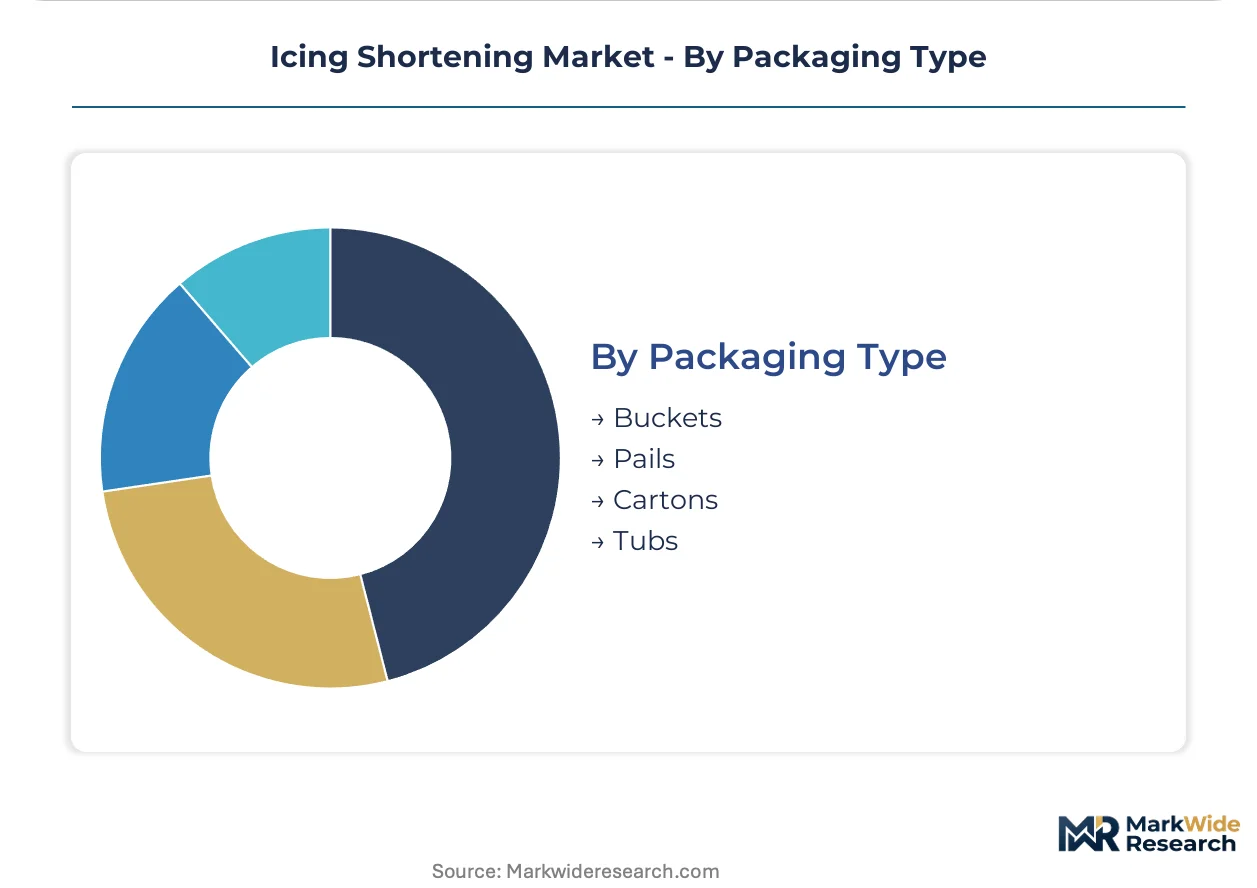
Packaging Type:
Container engineering aligns with volume scale, handling automation, and foodservice versus manufacturing channel requirements.
- Buckets:High-density polyethylene containers with tamper-evident seals serve high-volume commercial bakery operations. E-commerce ingredient platforms now offer smaller MOQ flexibility through resealable bucket formats.
- Pails:Metal and composite pails handle bulk industrial procurement with forklift-compatible stacking geometry.
- Cartons:Rectangular formats optimize pallet utilization and retail shelf presence for grocery channel distribution.
- Tubs:Consumer-scale packaging with snap-lock lids targets small bakery and home-use segments.
Buckets dominate commercial procurement. Tubs are gaining share fastest through direct-to-bakery digital channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated oilseed processors in the United States and Canada hold concentrated refining capacity for high-performance shortening. Southeast Asian palm fractionation clusters in Indonesia and Malaysia feed raw material streams into global supply chains.
United States
Commercial bakeries across the Midwest and Southeast are mandating non-hydrogenated shortening certificates for procurement contracts. FDA trans fat restrictions and updated nutrition labeling rules continue forcing reformulation of legacy fat portfolios. Chicago and Minneapolis-St. Paul industrial corridors host major crushing and refining infrastructure serving North American bakery demand.
Germany
Confectionery manufacturers in the Rhine-Ruhr and Bavaria regions are restructuring supply chains to meet EU Green Deal sustainable palm certification mandates. REACH authorization requirements for food-contact substances add compliance layers to imported fat systems. Cologne and Hamburg refiners are accelerating backward integration into RSPO-certified palm fractionation channels.
Indonesia
Palm oil export duty fluctuations are compressing margins for refiners dependent on Sumatran and Kalimantan feedstock supply. National sustainability certification programs are layering additional documentation requirements onto traditional export channels. Medan and Surabaya processing clusters are consolidating fractionation capacity to serve Asian and European bakery markets.
India
FSSAI enforcement of standardized shortening specifications is creating first-mover advantage for suppliers offering pre-certified formulations. Commercial bakery modernization in Maharashtra and Gujarat is pulling demand toward structured lipids with defined plasticity ranges. Mumbai and Ahmedabad industrial zones are seeing accelerated import qualification timelines for certified shortening products.
United Kingdom
Artisanal bakery networks in London and Greater Manchester are aggregating demand through cooperative buying platforms with defined origin documentation requirements. Post-Brexit border inspection protocols are extending lead times for palm-derived ingredient imports. Birmingham food manufacturing corridors are retrofitting production lines for enzymatically processed fat systems.
Icing Shortening Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fractionation and emulsifier technology. The vendor base separates into three distinct tiers: integrated agribusiness conglomerates with captive oilseed supply, mid-scale regional refiners with flexible batch capabilities, and specialty fat technology houses focused on confectionery applications. Competitive dynamics center on enzymatic interesterification licensing and certified sustainable palm procurement contracts.
Among integrated agribusiness conglomerates, Cargill Incorporated and Bunge Limited exemplify the capital-intensive tier with continent-spanning crushing and refining infrastructure. AAK AB occupies a position within the specialty fat technology segment, differentiating through structured lipid formulations tailored to precise aeration and melting requirements. These three anchors illustrate how scale advantages and technical specialization split competitive positioning across the value chain.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Bunge Limited |
| Barry Callebaut |
| Wilmar International Limited |
| AAK AB |
| Fuji Oil Holdings |
| Ventura Foods |
| Manildra Group |
| Others |
Supply & Pricing Matrix
Medan and Surabaya palm fractionation clusters in Indonesia concentrate feedstock supply, translating export duty volatility into margin compression that refiners pass downstream through contract renegotiation clauses. Chicago and Minneapolis-St. Paul industrial corridors absorb these fluctuations via long-term offtake agreements with built-in price adjustment mechanisms.
Pricing Analysis
FDA trans fat restrictions dictate the pricing tier structure across the United States market. Three-tier pricing structure across premium enzymatically processed, standard fully hydrogenated, and economy commodity vegetable bases separates certified clean-label formulations from legacy portfolios. Price differentiation hinges on RSPO mass-balance certification and volume scale commitments. Cost compression in standard tiers is intensifying because Indonesian export duty fluctuations feed directly into palm mid-fraction input costs. Artisanal bakeries in Brooklyn and London exhibit highest price sensitivity, while industrial confectionery manufacturers in Germany and France absorb premiums for traceable origin documentation.
Supply Chain Analysis
EU Green Deal sustainable palm certification mandates function as de facto export controls limiting uncertified feedstock flows into European channels. Supply concentrates in Indonesia, Malaysia, and Brazil as the dominant palm and soybean oil sourcing geographies. Raw material dependencies rest on palm mid-fraction, shea olein, and fully hydrogenated soybean oil as structural lipid inputs. Single-source vulnerability runs through Sumatran and Kalimantan plantation clusters exposed to climate disruption. Distribution runs through integrated agribusiness conglomerates with captive crushing infrastructure, mid-scale regional refiners with flexible batch enzymatic reactors, and specialty fat technology houses serving confectionery applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label procurement mandates from commercial bakeries signal early-cycle expansion as enzymatic interesterification technology penetrates beyond integrated oilseed processors to mid-scale refiners.
For Market Incumbents: Build regulatory certification moats through RSPO mass-balance backward integration and FSSAI pre-certification for Indian import channels. Cargill Incorporated and Bunge Limited anchor positions via continent-spanning crushing infrastructure that emerging enzymatic reactor specialists threaten to displace. Capacity addition in Medan and Surabaya fractionation clusters secures feedstock cost advantages against Malaysian competitors. For New Entrants and Emerging Players: Pursue artisanal bakery cooperative platforms in London, Melbourne, and Brooklyn as the most penetrable demand aggregation channel. These networks fragment volume across multiple suppliers but concentrate negotiation leverage, creating entry points for specialty fat technology houses with defined plasticity range capabilities. Direct-to-bakery digital platforms bypass traditional foodservice distributors with smaller MOQ flexibility as the primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because enzymatic interesterification technology is virtualizing the capital barrier that previously concentrated production among legacy hydrogenation asset holders. Target acquisition archetype: mid-scale North American refiners with continuous enzymatic reactor deployments and established clean-label certificates. The signal to watch is FSSAI enforcement intensity in Maharashtra and Gujarat, which would accelerate import qualification timelines and premium pricing for pre-certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Interesterification Licensing | Virtualizes capital barriers for mid-scale refiners seeking trans-free production parity. |
| RSPO Mass-Balance Certification | Unlocks EU Green Deal compliance for German and French confectionery manufacturers. |
| Direct-to-Bakery Digital Platform Launch | Captures artisanal segment volume through cooperative buying network aggregation. |
| Shea Butter Fractionation Integration | Blends olein with palm mid-fraction for temperate climate distribution advantages. |
| FSSAI Pre-Certification Investment | Creates first-mover advantage in Maharashtra and Gujarat bakery modernization. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with commercial bakery procurement directors, confectionery manufacturing R&D leads, palm oil refinery plant managers, and specialty fat technology formulators. Secondary validation drew from FDA labeling guidance documents, FSSAI food safety codes, EFSA nutrition claim standards, RSPO supply chain certification databases, and customs trade flow records. Bottom-up volume modeling across product type, end use, form, and packaging segments was triangulated against top-down macroeconomic indicators.
Calibration anchored volume and value outputs across the analysis window through multi-scenario stress testing of regulatory enforcement timelines and feedstock price volatility assumptions. Segmentation dimensions modeled included vegetable versus animal base formulations, baking versus frosting versus confectionery applications, solid versus semi-solid versus liquid physical states, and bucket versus pail versus carton packaging formats. CAGRs were derived from elasticity-adjusted demand projections incorporating enzymatic technology adoption curves and clean-label certificate penetration rates.
Sensitivities concentrate around Indonesian and Malaysian export duty policy shifts, FDA saturated fat disclosure rulemaking, and artisanal platform consolidation velocity. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology cost reduction trajectories. Material shifts in EU Green Deal certification mandates or enzymatic reactor capital cost curves would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Jasmine Extract Market
Ingredients
Custom Dry Ingredients Blends Market
Ingredients
Liquid Egg Market
Ingredients
Asia-Pacific Whey Protein Ingredients Market
Ingredients
Wheat Protein Concentrates Market
Ingredients
South America Vegetable Oil Market
Ingredients
Global Dietary Fibers Market
Ingredients
Low-Odor Fish Protein Hydrolysates from Med Species Market
Ingredients
Energy Ingredients Market
Ingredients
Egg White Powder Market
Ingredients
Truffle Oil Market
Ingredients
Algae Omega-3 Ingredients Market
Ingredients
Cocoa Bean Extract Market
Ingredients
Vitamin C Ingredients Market
Ingredients
Global Distillers Grains Market
Ingredients
Vitex Agnus Castus Extract Market