
 Eco-Friendly Straw Market | 2026-2036
Eco-Friendly Straw Market Size, Share, and Industry Trends Forecast 2026-2036
Eco-Friendly Straw Market Analysis
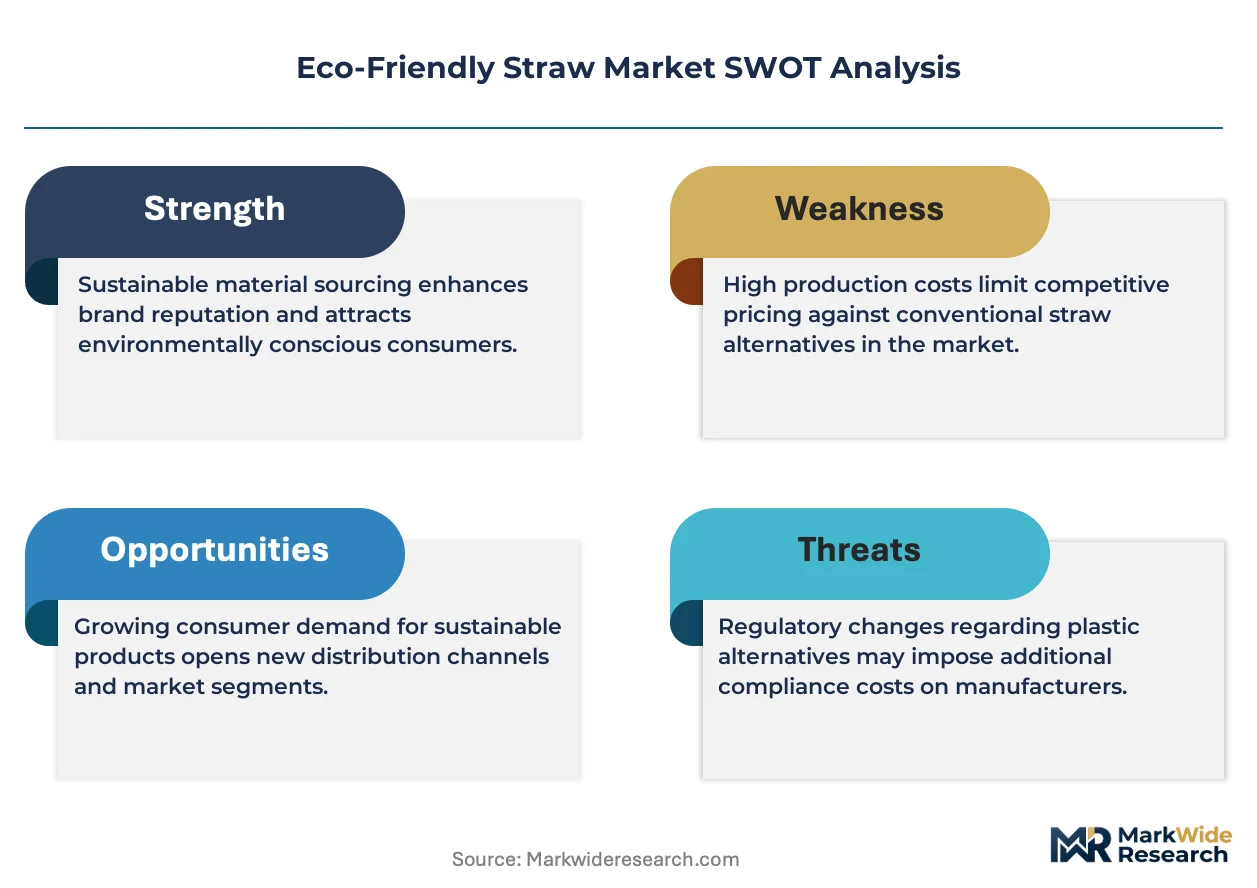
Buyer concentration among quick-service restaurant chains is restructuring procurement volumes across the Eco-Friendly Straw Market. Huhtamaki OYJ Straws leverages its European manufacturing footprint to supply branded foodservice chains with compostable paper straws. Tetra Pak International SA anchors demand through its integrated beverage packaging ecosystem, bundling straw solutions with carton systems. Footprint LLC differentiates via molded fiber technology leadership, targeting hot-beverage applications where structural integrity matters.
Eco-friendly straws are drinking implements manufactured from plant-derived substrates including cellulose fiber, bamboo pulp, wheat stems, or grass stalks, engineered to deliver liquid conveyance for beverages while meeting biodegradability standards under industrial composting conditions. Their primary commercial purpose is enabling foodservice operators to maintain consumer drinking convenience while complying with plastic restriction mandates. Paper straws dominate current procurement volumes among restaurants and cafes due to cost parity and established supply chains, though bamboo and wheat variants are gaining fastest in premium channels where tactile experience commands margin. Compostable product types capture the deepest margin pools as certification requirements create qualification barriers for undifferentiated competitors.
The European Union's Single-Use Plastics Directive and the U.S. FDA's food-contact substance regulations jointly shape material approval pathways and market access conditions for straw manufacturers. California's statewide plastic straw restrictions, alongside municipal ordinances in Seattle and New York City, create layered compliance obligations that favor suppliers with multi-jurisdiction certification capabilities. Stakeholders must monitor evolving compostability standards from BPI and TÜV Austria, as certification fragmentation threatens to segment addressable markets by regional acceptance protocols.
Market Dynamics
Quick-service restaurant chains are consolidating procurement volumes, forcing straw manufacturers to reconfigure production lines for multi-million-unit contracts with standardized specifications and certified compostability.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandated phase-outs across member states are redirecting foodservice procurement toward compostable alternatives, with enforcement timelines creating predictable demand windows.
- Bamboo pulp processing:Advanced fiber refinement techniques are extending straw structural integrity in hot beverages, opening premium café channels previously closed to plant-based substitutes.
- Municipal procurement clusters:California, New York, and Seattle ordinances are generating concentrated volume commitments that justify dedicated manufacturing capacity.
Market Restraints
- Cellulose fiber price volatility:Pulp input costs fluctuate with timber harvest cycles and energy-intensive drying processes, compressing margin stability for paper straw producers.
- Industrial composting infrastructure gaps:Limited certified facility availability in mid-size US metropolitan areas creates geographic pockets where compostable straws lack end-of-life validation.
- Reusable straw substitution:Metal and silicone permanent alternatives are capturing home consumption and dine-in segments, constraining addressable market expansion.
Strategic Opportunities
- India foodservice expansion:Quick-service penetration in tier-2 cities is outpacing plastic straw infrastructure, creating first-mover positioning for certified compostable suppliers.
- Cold-chain beverage bundling:Integration with aseptic carton packaging systems enables straw-in-lid configurations for ambient distribution channels.
- BPI certification leverage:Fragmented regional compostability standards favor suppliers with multi-jurisdiction qualifications, creating qualification moats.
Industry Challenges
- TÜV Austria OK Compost HOME timeline:Home-compostable certification cycles extend 14-18 months, delaying product launches and locking working capital in pre-revenue inventory.
- Hot-beverage structural engineering:Maintaining integrity above 60°C requires proprietary fiber bonding techniques that demand specialized R&D talent scarce in traditional packaging sectors.
- Legacy injection-molding retooling:Converting plastic straw production assets to molded fiber lines requires capital commitments that strain mid-cap manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eco-Friendly Straw Market |
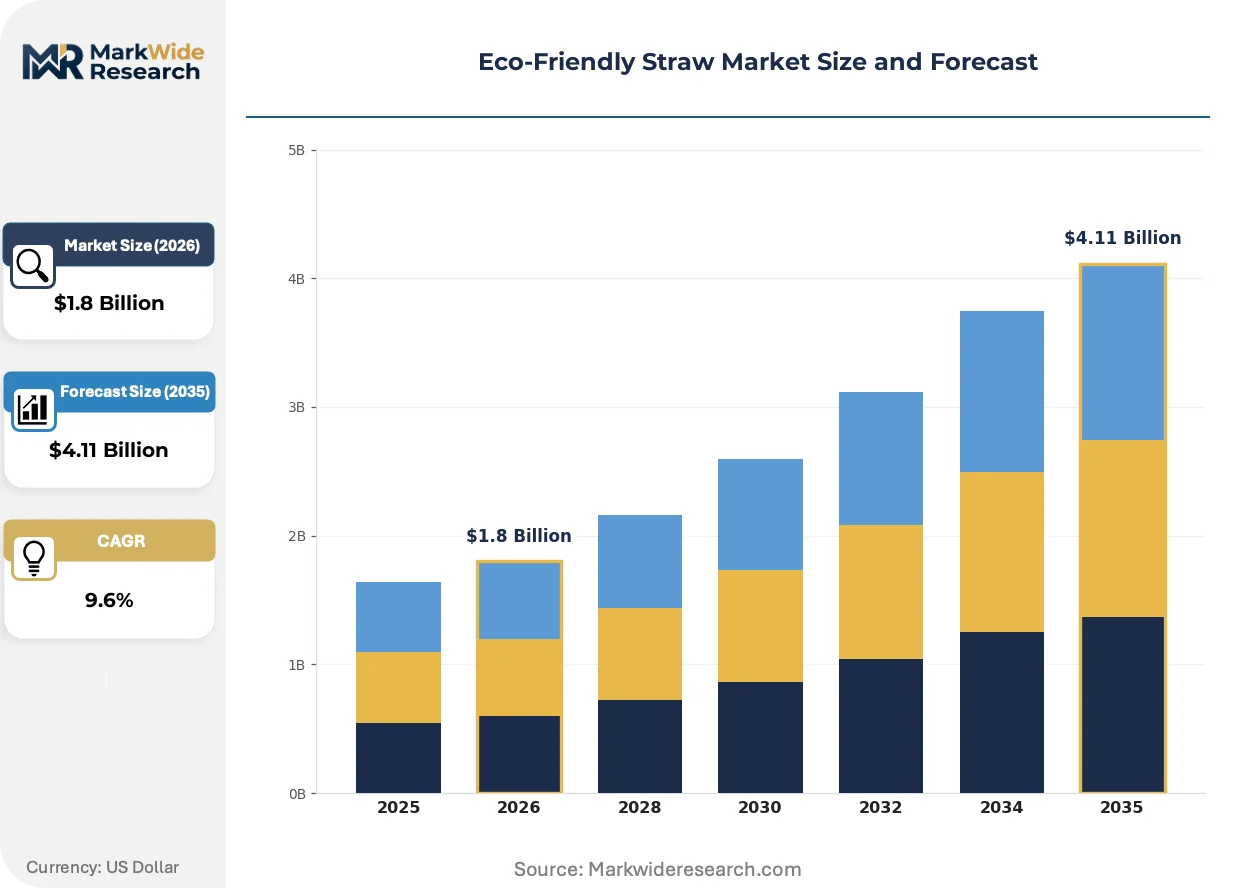
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.11 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Bamboo, Paper, Wheat, Grass Product Type: Reusable, Disposable, Biodegradable, Compostable End User: Restaurants, Cafes, Events, Households Size: Short, Long, Extra Long, Custom Length |
| Companies Covered | BioPak, Vegware, Huhtamaki OYJ Straws, Canada Brown Eco Products, Merrypak, Tetra Pak International SA, Footprint LLC, Biopac UK Ltd, Aardvark Straws, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eco-Friendly Straw Market Emerging Trajectories
Material science advances and regulatory enforcement timelines are compressing product development cycles while fragmenting certification requirements across jurisdictions. Manufacturers must now synchronize innovation pipelines with evolving biodegradability standards.
Automated fiber molding is automating precision compression of agricultural residues into uniform straw geometries with sub-millimeter diameter tolerance. European packaging equipment suppliers are deploying these systems for quick-service chain contracts. The technology is automating labor-intensive forming stages that previously constrained throughput scaling.
REACH chemical registration requirements for novel bio-based coatings are extending material approval timelines for European market entry. Industrial consequence includes delayed launch schedules for moisture-resistant formulations. Hot-beverage applications in Germany and France are most affected, with suppliers prioritizing BPI-certified US launches first.
Chain-level sustainability scorecards are consolidating supplier qualification around third-party certifications rather than material claims alone. Foodservice procurement teams are disintermediating distributors to contract directly with certified manufacturers. This pattern is most visible in US coastal metropolitan markets with active plastic restriction enforcement.
Eco-Friendly Straw Market Segmentation
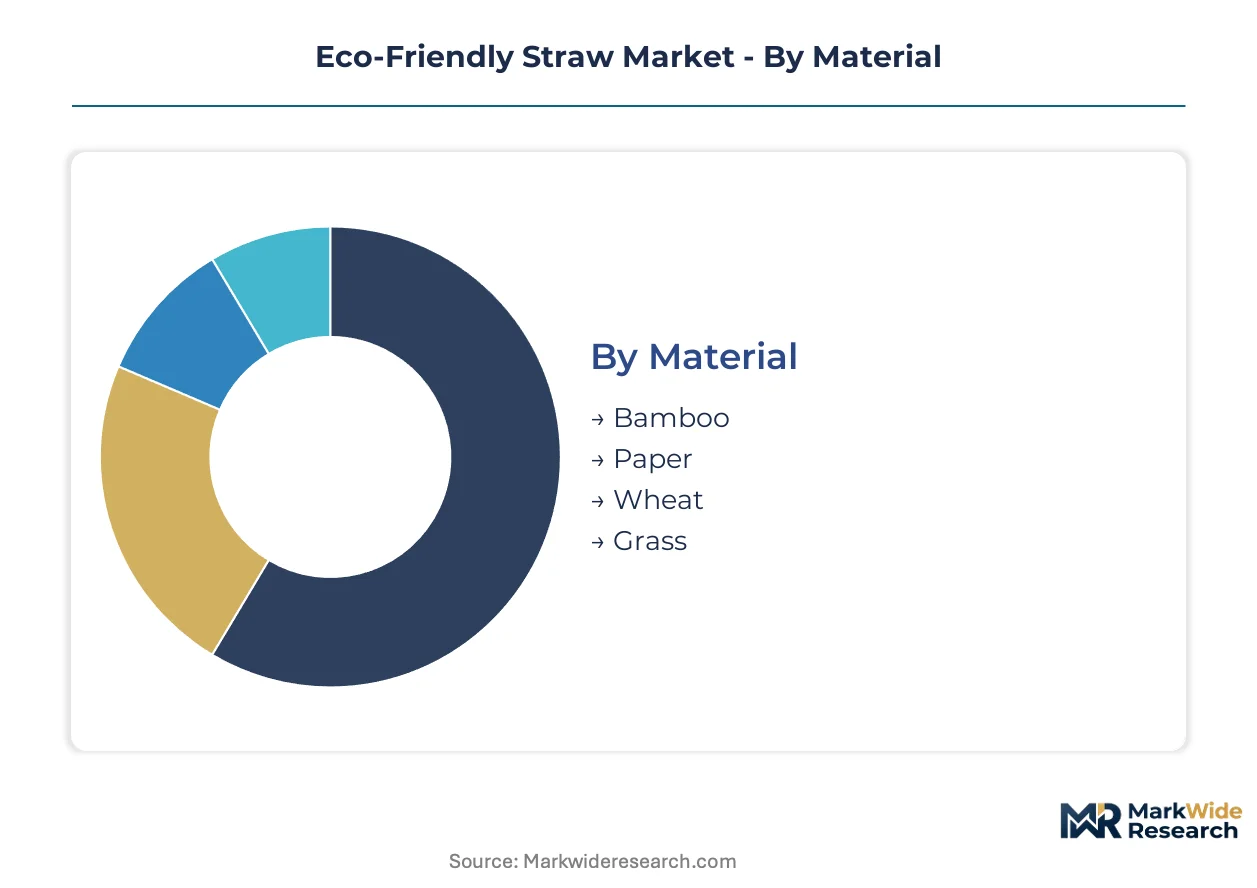
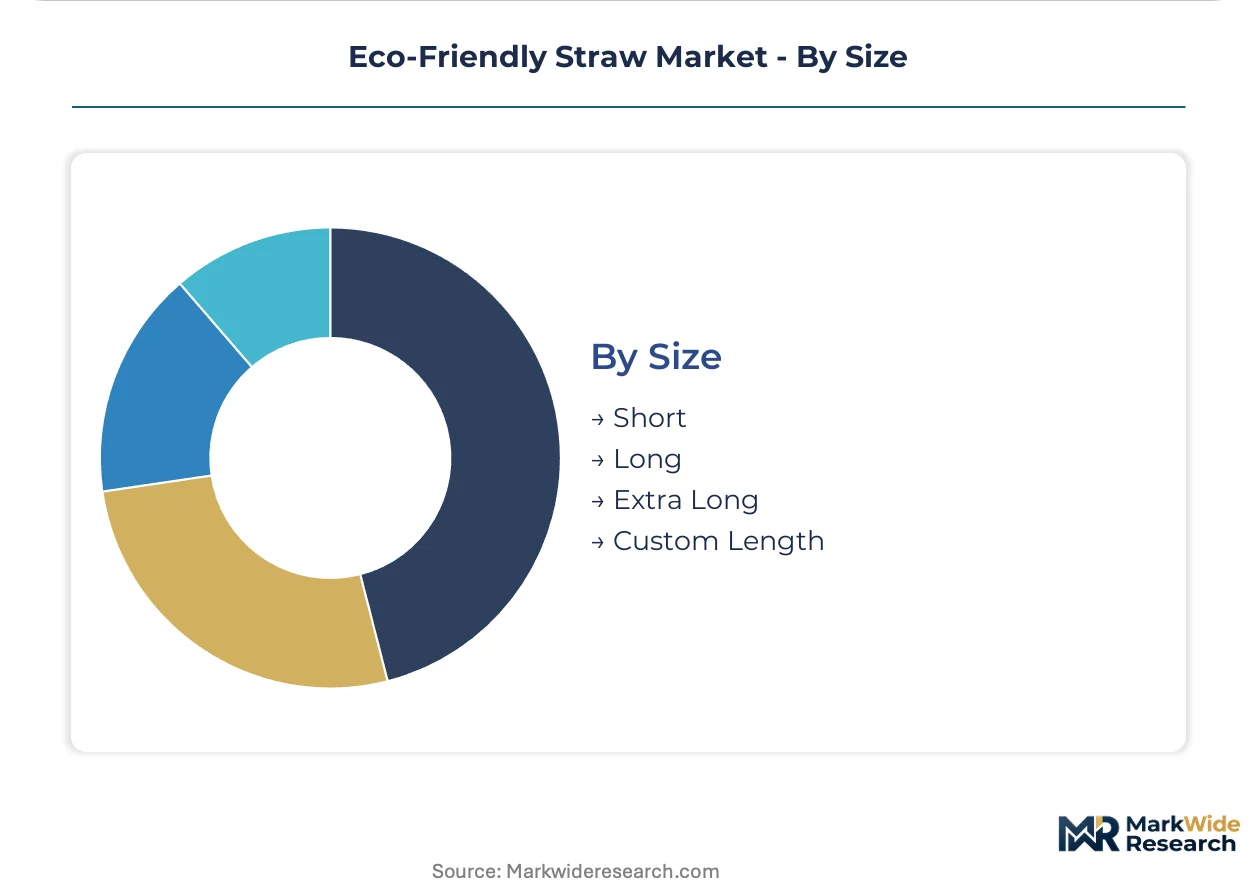
Segmentation in the Eco-Friendly Straw Market determines procurement specifications, certification requirements, and margin capture. Material choice dictates compostability pathways. Product type governs regulatory compliance obligations. End user concentration shapes volume contracts. Size customization drives manufacturing flexibility investments.
Material:
Customization-to-standardization tension runs deepest here — bamboo and grass demand specialized processing, while paper leverages existing pulp infrastructure.
- Paper:Cellulose fiber construction with FDA food-contact coatings dominates quick-service procurement. California, New York, and Seattle municipal bans concentrate demand for BPI-certified paper straws in US coastal foodservice chains.
- Bamboo:Advanced fiber refinement techniques deliver structural integrity above 60°C. Premium café channels in Germany and France prioritize bamboo for tactile differentiation, though REACH chemical registration extends approval timelines.
- Wheat:Agricultural residue utilization appeals to sustainability scorecard requirements. European quick-service chains specify wheat stems for circular economy alignment under EU Green Deal procurement guidelines.
- Grass:Meadow grass pulp processing remains nascent, with limited commercial scale. Nordic packaging specialists pilot grass fiber for moisture-resistant cold-beverage applications.
Leading the category by volume: Paper. Growing fastest: Bamboo.
Product Type:
Margin capture stratifies sharply — compostable certification creates qualification moats, while reusable alternatives bypass industrial infrastructure dependencies.
- Compostable:Industrial composting certification under BPI and TÜV Austria standards commands procurement premiums. Quick-service chains in the United States contract directly with certified manufacturers to meet California and Seattle ordinance requirements.
- Disposable:Single-use paper and plant-fiber variants anchor foodservice volume. Municipal plastic restriction enforcement across US metropolitan areas redirects procurement toward certified disposable alternatives.
- Biodegradable:Unspecified biodegradability claims face regulatory scrutiny. The European Union's Single-Use Plastics Directive mandates specific compostability standards, marginalizing vague biodegradable positioning.
- Reusable:Metal and silicone permanent straws capture home consumption and dine-in segments. This substitution constrains addressable market expansion for single-use manufacturers in household channels.
Highest margin capture: Compostable. Steepest volume trajectory: Disposable.
End User:
Procurement consolidation intensity varies — restaurant chains centralize specifications, while events demand flexible fulfillment.
- Restaurants:Quick-service chains consolidate multi-million-unit contracts with standardized specifications. Huhtamaki OYJ and Tetra Pak International SA leverage direct manufacturer relationships to bypass distributor margins.
- Cafes:Premium hot-beverage applications require proprietary fiber bonding for structural integrity above 60°C. Bamboo pulp variants gain traction in German and French café channels where tactile experience commands pricing power.
- Events:Temporary foodservice operations prioritize cost-efficient paper straws with minimal certification overhead. Procurement clusters around municipal ban jurisdictions in California and New York.
- Households:Reusable metal and silicone alternatives displace single-use demand in home consumption. This segment shows weakest growth for disposable compostable manufacturers.
Contract concentration peaks: Restaurants. Fastest-expanding channel: Cafes.
Size:
Manufacturing complexity escalates with length customization — standardization enables automation, while custom lengths require manual finishing.
- Long:Standard 8-inch specification serves fountain beverages and casual dining. Automated fiber molding systems from European packaging equipment suppliers optimize throughput for this geometry.
- Short:Compact 5-inch format targets espresso and cocktail applications. Italian and Spanish café cultures drive specification demand for short straw variants.
- Extra Long:Extended 10-inch construction accommodates tall tumblers and specialty drinks. Limited production runs require manual quality control, compressing margins.
- Custom Length:Brand-specific dimensional requirements serve chain-level sustainability scorecards. Footprint LLC and molded fiber specialists configure precision compression for sub-millimeter diameter tolerance.
Automation economics favor: Long. Premium positioning concentrates: Custom Length.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quick-service restaurant procurement concentrates most visibly in the United States, where municipal bans in California, New York, and Seattle generate concentrated volume commitments that justify dedicated manufacturing capacity. The European Union's Single-Use Plastics Directive mandates phase-outs of conventional plastic straws, accelerating material transitions across member states. Demand clusters in specific metropolitan areas and national capitals where enforcement timelines create predictable procurement windows.
United States
California's statewide plastic straw restrictions, alongside municipal ordinances in Seattle and New York City, create layered compliance obligations that favor suppliers with multi-jurisdiction certification capabilities. The FDA's food-contact substance regulations shape material approval pathways for straw manufacturers seeking national distribution. Procurement concentrates in coastal metropolitan markets with active plastic restriction enforcement, where foodservice chains contract directly with certified manufacturers.
Germany
Premium café channels in Germany prioritize bamboo pulp variants for tactile differentiation where hot-beverage structural integrity above 60°C commands pricing power. REACH chemical registration requirements extend material approval timelines for European market entry, delaying launch schedules for moisture-resistant formulations. The ECHA registration process affects industrial clusters in Bavaria and North Rhine-Westphalia where packaging specialists pilot advanced fiber bonding techniques.
France
French café culture drives specification demand for short straw variants targeting espresso and cocktail applications. ANSM and EFSA compliance frameworks govern food-contact material approvals for compostable alternatives entering the market. Paris and Lyon metropolitan areas anchor procurement volumes for quick-service chains aligning with EU Green Deal procurement guidelines.
India
Quick-service penetration in tier-2 cities outpaces plastic straw infrastructure, creating first-mover positioning for certified compostable suppliers. FSSAI food safety standards and BIS certification requirements establish regulatory entry barriers for international manufacturers. Procurement clusters in Maharashtra and Karnataka where foodservice expansion generates demand for cost-efficient paper straws with minimal certification overhead.
United Kingdom
London and Southeast England concentrate procurement volumes for branded foodservice chains replacing plastic straws at scale. The UK Environment Agency enforces packaging waste regulations that redirect foodservice procurement toward compostable alternatives. Biopac UK Ltd leverages its domestic manufacturing footprint to supply quick-service chains with certified paper straws meeting municipal ordinance requirements.
Eco-Friendly Straw Market Vendor Landscape
European producers anchor one tier; North American specialists hold differentiated positions in molded fiber and integrated packaging systems. The vendor base fragments across material science competencies, with paper pulp incumbents, bamboo fiber refiners, and agricultural residue processors occupying distinct qualification tiers. Three archetypes dominate: integrated packaging conglomerates with beverage system bundling capabilities, molded fiber technology specialists targeting hot-beverage applications, and regional paper converters serving municipal ban jurisdictions. Competitive moves concentrate on multi-jurisdiction certification acquisition and direct manufacturer relationships with quick-service chains.
Among European-based fabricators, Huhtamaki OYJ Straws and Tetra Pak International SA represent the integrated packaging tier, leveraging direct manufacturer relationships to bypass distributor margins in quick-service procurement. Footprint LLC occupies a position within the molded fiber specialization tier, exemplifying technology leadership in precision compression applications. These three companies anchor the competitive structure through distinct geographic and technological positioning strategies.
| Leading Market Players |
|---|
| BioPak |
| Vegware |
| Huhtamaki OYJ Straws |
| Canada Brown Eco Products |
| Merrypak |
| Tetra Pak International SA |
| Footprint LLC |
| Biopac UK Ltd |
| Aardvark Straws |
| Others |
Supply Flow & Price Mechanics
EU Single-Use Plastics Directive enforcement timelines gate qualified supply access and premium-tier pricing power, restricting multi-million-unit quick-service contracts to manufacturers holding BPI or TÜV Austria certifications while compressing margins for uncertified paper converters.
Pricing Analysis
Volume-mass contracts for disposable paper straws operate on thin margins, while certified compostable variants capture pricing premiums through qualification moats. Three-tier pricing structure across premium, standard, and economy levels separates BPI-certified industrial compostables from municipal-ban-compliant disposables and uncertified imports. Cost compression in standard-grade paper straws is intensifying because pulp input volatility and energy-intensive drying processes squeeze converter margins. Quick-service restaurant chains exhibit highest price sensitivity due to procurement consolidation, while premium German and French cafés prioritize tactile differentiation over unit cost.
Supply Chain Analysis
Cellulose fiber supply rests on Scandinavian and Brazilian pulp producers, with bamboo pulp sourcing anchored in Chinese and Southeast Asian fiber refinement facilities. Raw material dependencies span timber harvest cycles, agricultural residue collection networks, and specialty bio-based coating chemicals. Single-source vulnerability concentrates in European packaging equipment suppliers controlling automated fiber molding systems. Distribution runs through direct manufacturer relationships that bypass distributor margins for certified suppliers serving California, New York, and Seattle municipal ban jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where upstream control over pulp supply and downstream direct contracting with quick-service chains determines margin capture and contract security.
For Market Incumbents: Deploy multi-jurisdiction certification acquisition to defend contract positions against emerging molded fiber specialists. Secure captive supply of bamboo pulp through backward integration into Southeast Asian fiber refinement facilities. Anchor manufacturing capacity in US coastal metropolitan markets with active plastic restriction enforcement to minimize logistics exposure. For New Entrants and Emerging Players: Capture tier-2 Indian city quick-service penetration before plastic straw infrastructure solidifies. Target Maharashtra and Karnataka procurement clusters with cost-efficient paper straws carrying minimal FSSAI certification overhead. Pursue white-label manufacturing partnerships with European distributors seeking BPI-qualified supply alternatives. For Investors and Strategic Acquirers: REACH chemical registration completion timelines for moisture-resistant coatings is the leading indicator that European market entry barriers are falling for molded fiber specialists. Position acquisition targets around mid-cap manufacturers with proven hot-beverage structural engineering above 60°C and established quick-service chain relationships. Monitor TÜV Austria OK Compost HOME certification cycles as signals of working capital efficiency and product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Acquisition | BPI and TÜV Austria qualifications unlock California and EU quick-service procurement windows. |
| Backward Integration into Pulp Supply | Captive bamboo fiber refinement secures margin stability against timber harvest volatility. |
| Automated Fiber Molding Deployment | European equipment supplier partnerships enable sub-millimeter tolerance for chain-level contracts. |
| Direct Manufacturer Relationship Building | Bypassing distributor margins captures procurement consolidation value in coastal US markets. |
| Hot-Beverage Structural Engineering Investment | Proprietary fiber bonding above 60°C opens German and French premium café channels. |
Methodological Framework
Trade association filings, customs and import-export records, and regulatory submission databases formed the secondary backbone, cross-referenced with primary interviews involving foodservice procurement directors, pulp supply managers, packaging equipment specialists, and sustainability compliance officers. Bottom-up volume triangulation across material-grade segments reconciled with top-down market sizing derived from quick-service chain disclosed procurement volumes and municipal ban enforcement timelines.
Historical trendline analysis of paper straw adoption curves in California, New York, and Seattle preceded forward projection across the analysis window. Segmentation modeling incorporated material substrate, compostability certification tier, end-user channel concentration, and regional regulatory enforcement intensity. CAGR derivation weighted enforcement timeline certainty, pulp cost trajectory assumptions, and substitution elasticity from reusable metal and silicone alternatives.
The model holds under continued municipal and national plastic restriction expansion; deviation in industrial composting infrastructure buildout rates or cellulose fiber supply disruption would shift volume and value trajectories. Forecasts reflect documented assumptions regarding certification adoption curves and quick-service chain consolidation patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
Wheat Straw Cutlery Market
Sustainable Packaging
Europe Sustainable Packaging Market
Sustainable Packaging
Asia-Pacific Eco-Friendly Packaging Market
Sustainable Packaging
Compostable Tableware Market
Sustainable Packaging
Compostable Food Trays Market
Sustainable Packaging
Green Packaging Market
Sustainable Packaging
Global Disappearing Packaging Market
Sustainable Packaging
Japan Green Packaging Market
Sustainable Packaging
North America Eco-Friendly Packaging Market
Sustainable Packaging
PVC-Free Packaging Market
Sustainable Packaging
Eco Friendly Bottles Market
Sustainable Packaging
Sustainable Packaging Market
Sustainable Packaging
Europe Eco-Friendly Packaging Market
Sustainable Packaging
United States Green Packaging Market
Sustainable Packaging
Sustainable Plastic Packaging Market
Sustainable Packaging
Asia-Pacific Sustainable Packaging Market