
 Europe Eco-Friendly Packaging Market | 2026-2036
Europe Eco-Friendly Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Eco-Friendly Packaging Market Foresight
The EU Packaging and Packaging Waste Regulation is hardening material recovery targets and extended producer responsibility thresholds across member states. Amcor leverages its integrated fiber and polymer platform to supply certified recyclable formats to major European grocery retailers. Smurfit Westrock anchors corrugated recycling infrastructure across the Benelux and Iberian markets. Mondi competes through kraft paper innovation tailored to fresh-protein supply chains.
Eco-friendly packaging encompasses materials and structures engineered for reduced environmental persistence, including biodegradable polymers with ASTM D6400 compostability certification, molded fiber with minimum 80% recycled content, and mono-material films designed for mechanical recycling streams. Paper and biodegradable plastics lead material adoption due to established industrial composting infrastructure and brand-level carbon reduction pledges. Bags and containers capture dominant volume within product formats, while wraps represent the fastest-expanding category driven by e-commerce fulfillment demand for lightweight protective layers.
EMA, ECHA, and the EU Green Deal framework collectively shape material approval pathways, chemical safety thresholds, and circular economy mandates that determine market access across the continent. REACH compliance and F-Gas Regulation restrictions on fluorinated barrier coatings are redirecting R&D investment toward bio-based moisture barriers. Stakeholders must monitor delegated acts under the revised Packaging Directive that will define recyclability performance grades and modulated fee structures for EPR schemes.
Market Dynamics
The EU Packaging and Packaging Waste Regulation's hardening compliance timelines are compressing conversion cycles for food and beverage manufacturers across Germany, France, and Italy. This regulatory pressure is forcing rapid capital redeployment toward certified biodegradable alternatives before enforcement deadlines crystallize.
Growth Catalysts
- EPR Scheme Expansion:Extended producer responsibility thresholds under the revised EU Packaging Directive are compelling brand owners to internalize end-of-life costs. This redirects procurement budgets toward mono-material formats that qualify for modulated fee reductions.
- Industrial Composting Infrastructure:Germany's anaerobic digestion network now processes ASTM D6400-certified bioplastics at scale. Food service operators in Hamburg and Munich leverage this capacity to eliminate landfill diversion costs for organic waste streams.
- Kraft Paper Innovation:Fresh-protein supply chains are adopting high-barrier kraft solutions that replace multi-layer plastic laminates. Mondi's integrated pulp-to-paper operations supply these formats with verified carbon footprint reductions.
Market Restraints
- Barrier Coating Input Costs:REACH-compliant bio-based moisture barriers require specialty cellulose derivatives whose prices fluctuate with Nordic pulp harvest cycles. This volatility compresses margins for converters serving price-sensitive retail private labels.
- Fluorinated Chemistry Phase-Out:The F-Gas Regulation's restrictions on perfluorinated barrier coatings eliminate proven grease-resistant solutions. Bakery and fast-food packaging segments face performance gaps while bio-alternatives mature.
- Mechanical Recycling Contamination:Biodegradable plastics entering conventional PET streams degrade regranulate quality. Sorting infrastructure in Southern Europe lacks near-infrared detection systems to separate these resin categories.
Strategic Opportunities
- E-Commerce Protective Wraps:Lightweight molded fiber cushions are displacing polyethylene air pillows in Benelux fulfillment centers. Amazon's European operations pilot fiber-based alternatives for fragile goods shipping.
- CSRD-Driven Disclosure:The Corporate Sustainability Reporting Directive mandates Scope 3 packaging emissions disclosure. This creates procurement preference for suppliers offering product-level lifecycle data verified to ISO 14040 standards.
- Iberian Corrugated Recovery:Spain and Portugal maintain lower recycled fiber collection rates than Northern Europe. Smurfit Westrock's integrated mill network can capture margin expansion by closing this collection gap.
Industry Challenges
- Compostability Certification Backlogs:ASTM D6400 and EN 13432 testing queues at European laboratories now exceed eight months. Product launches stall while brands await documentation for regulatory submissions.
- Legacy Heat-Sealing Equipment Retrofit:Bioplastic films require modified temperature profiles that strain existing form-fill-seal lines. Converters face downtime costs and technician retraining investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Eco-Friendly Packaging Market |
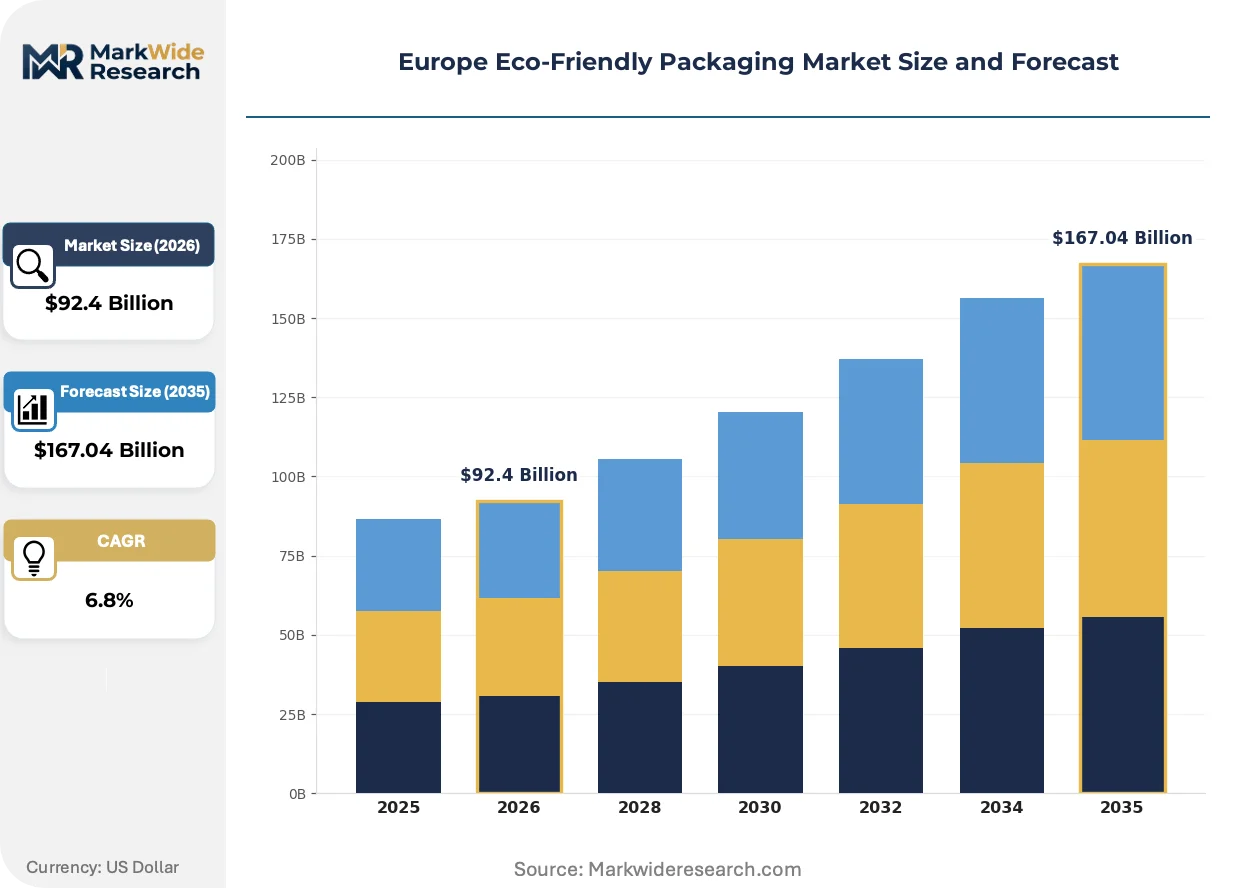
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $167.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Biodegradable Plastics, Paper, Glass, Metal Product Type: Bags, Containers, Boxes, Wraps End Use: Food & Beverage, Personal Care, Consumer Electronics, Healthcare Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Amcor, Notpla, Smurfit Westrock, Hipli, Elopak, Stora Enso, Mondi, Bloom Biorenewables, Tetra Pak, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Eco-Friendly Packaging Market Shifts & Advancements
Material science breakthroughs and regulatory disclosure mandates are converging to redefine performance specifications across European packaging procurement. The competitive frontier now centers on verifiable circularity credentials rather than incremental weight reduction.
Molded fiber technology is expanding into temperature-sensitive applications previously dominated by expanded polystyrene. Cold-chain pharmaceutical distributors in the Netherlands and Belgium now specify fiber-based insulated shippers for last-mile vaccine delivery. This displacement of petroleum-derived thermal protection is compressing demand for EPS molding capacity while stimulating investment in fiber drying and pressing equipment.
The EU Green Deal's circular economy action plan is accelerating harmonized recyclability performance grades across member states. Delegated acts under the Packaging Directive will define modulated EPR fee structures based on design-for-recycling scores. German grocery retailers are pre-emptively reformulating private-label packaging to secure top-tier classifications before fee differentials activate.
Fresh-protein processors are consolidating supplier relationships around integrated fiber and film platforms that simplify Scope 3 emissions accounting. This concentration of procurement volume favors converters with in-house pulp operations and certified polymer compounding capabilities. The shift is most visible in France's poultry and seafood processing corridors, where sustainability-linked supply agreements now span five-year terms with penalty clauses for non-compliance.
Europe Eco-Friendly Packaging Market Segmentation
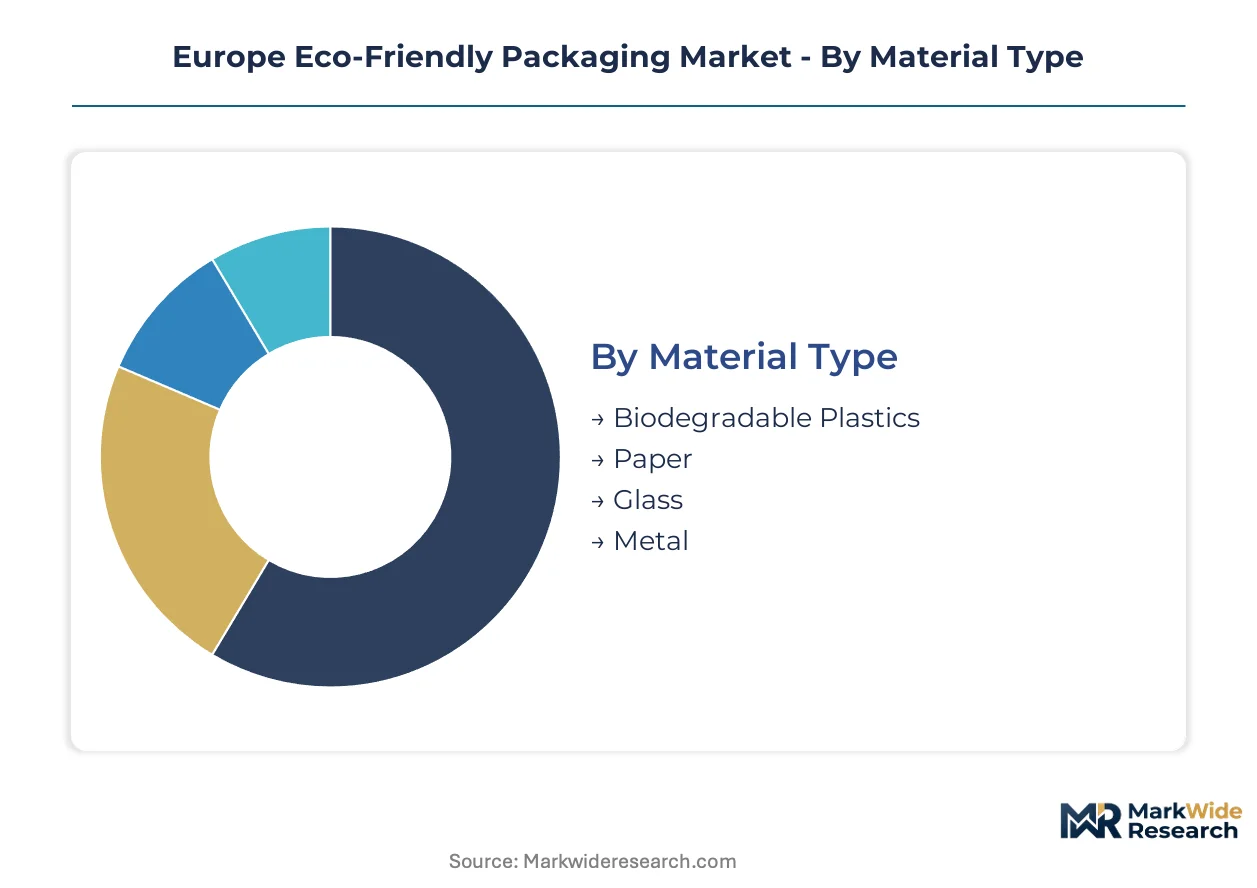
Segmentation in European eco-friendly packaging reveals how regulatory pressure and supply chain capabilities fragment procurement decisions across material grades, product formats, and compliance thresholds. Understanding these divisions exposes where capital concentrates and where conversion costs create competitive moats.
Material Type:
Technical specifications determine recyclability certification pathways and EPR fee modulation under EU Packaging Directive delegated acts.
- Biodegradable Plastics:ASTM D6400-certified polymers including PLA, PHA, and starch blends decompose in industrial composting facilities. German food service operators in Hamburg and Munich leverage anaerobic digestion infrastructure to eliminate landfill diversion costs for organic waste streams.
- Paper:Kraft paper with minimum 80% recycled content and molded fiber formats dominate fresh-protein supply chains. Mondi's integrated pulp-to-paper operations supply high-barrier solutions that replace multi-layer plastic laminates in France's poultry processing corridors.
- Glass:Returnable bottle systems persist in premium beverage segments across Germany and Italy, though weight penalties limit e-commerce applicability.
- Metal:Aluminum and steel cans with recycled content verification serve aerosol and concentrated product categories where barrier performance is non-negotiable.
Paper leads on scale; biodegradable plastics lead on momentum.
Product Type:
Format selection tracks fulfillment channel requirements and mechanical recycling compatibility constraints.
- Bags:Mono-material PE and paper formats qualify for modulated EPR fee reductions. German grocery retailers pre-emptively reformulate private-label packaging to secure top-tier recyclability classifications before fee differentials activate.
- Containers:Rigid molded fiber and bioplastic tubs serve ready-meal and dairy segments. REACH-compliant bio-based moisture barriers face price volatility tied to Nordic pulp harvest cycles.
- Boxes:Corrugated recovery rates in Spain and Portugal lag Northern Europe, creating margin expansion opportunities for integrated mill networks.
- Wraps:Lightweight protective layers expand most quickly as Amazon's European operations pilot fiber-based alternatives for fragile goods shipping in Benelux fulfillment centers.
Bags lead on scale; wraps gain share fastest.
End Use:
Customer procurement authority and Scope 3 disclosure mandates determine specification stringency.
- Food & Beverage:The EU Packaging and Packaging Waste Regulation's hardening compliance timelines compress conversion cycles for manufacturers across Germany, France, and Italy. CSRD-driven disclosure mandates create preference for suppliers offering ISO 14040-verified lifecycle data.
- Personal Care:Premium positioning supports glass and aluminum formats despite higher unit costs.
- Consumer Electronics:E-commerce fulfillment demand drives molded fiber cushion adoption over polyethylene air pillows.
- Healthcare:Cold-chain pharmaceutical distributors in the Netherlands and Belgium specify fiber-based insulated shippers for last-mile vaccine delivery.
Food & Beverage leads on scale; Healthcare shows steepest expansion trajectory.
Distribution Channel:
Channel control over packaging specification varies with private-label penetration and fulfillment infrastructure ownership.
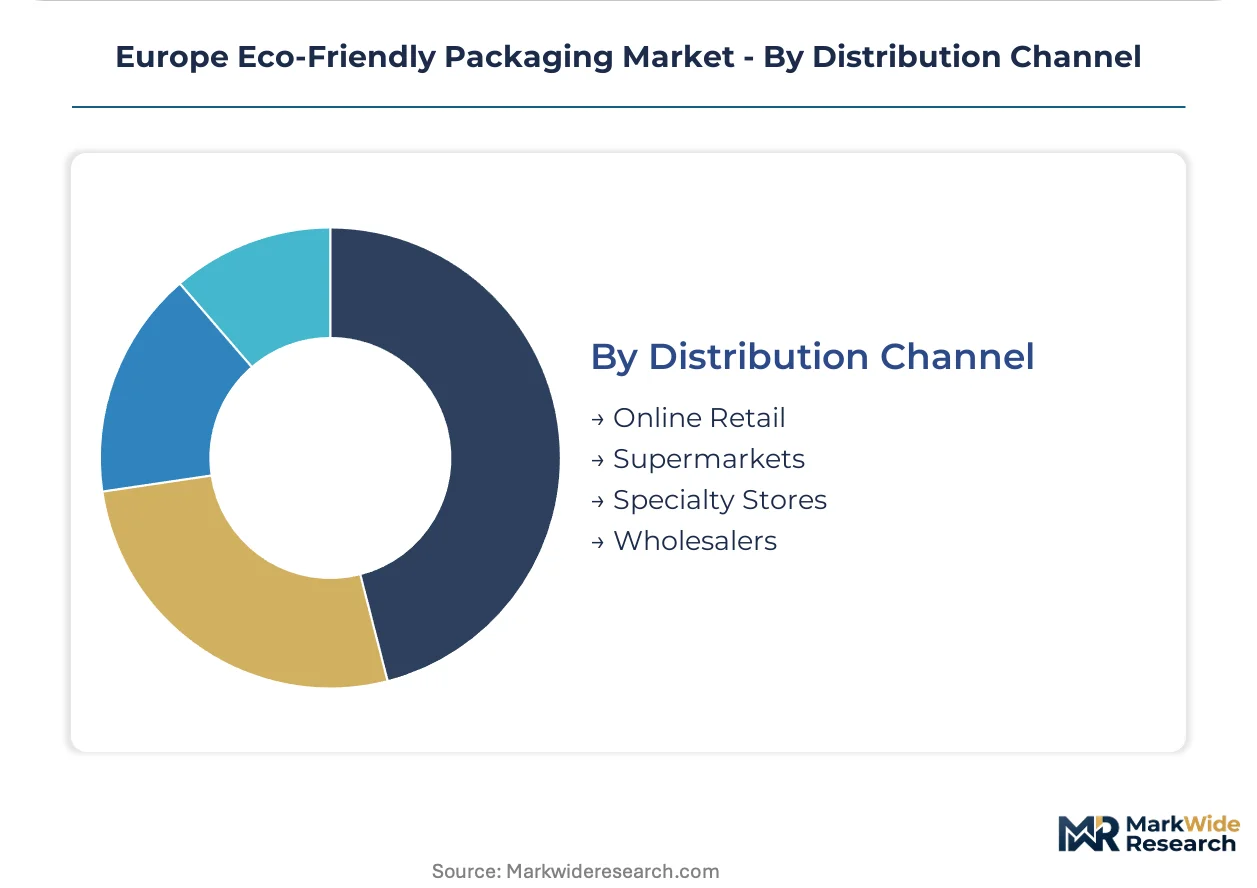
- Online Retail:Platform operators dictate protective wrap specifications to optimize dimensional weight pricing. Amazon's European logistics network drives standardization toward fiber-based alternatives.
- Supermarkets:German grocery retailers anchor demand for certified recyclable formats through sustainability-linked supply agreements spanning five-year terms with penalty clauses.
- Specialty Stores:Curated assortments support premium material grades with verified carbon footprint reductions.
- Wholesalers:Price-sensitive volume procurement favors standard corrugated and plastic formats with established collection infrastructure.
Supermarkets lead on scale; Online Retail climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer chemists and pulp engineers cluster along the Rhine corridor and Nordic timber belt, anchoring Europe's conversion capacity for certified biodegradable formats.
Germany
Food manufacturers along the Hamburg-Munich industrial corridor accelerate procurement of ASTM D6400-certified bioplastics to meet EU Packaging and Packaging Waste Regulation deadlines. The country's anaerobic digestion network processes certified materials at scale, eliminating landfill diversion costs for organic waste streams. Bavaria's automotive suppliers pilot molded fiber protective packaging for precision component shipments.
France
Poultry and seafood processors in Brittany and Pays de la Loire consolidate supplier relationships around integrated fiber platforms that simplify Scope 3 emissions accounting. CSRD disclosure mandates create procurement preference for ISO 14040-verified lifecycle data. The Île-de-France region hosts sustainability-linked supply agreements spanning five-year terms with penalty clauses for non-compliance.
Italy
Ready-meal manufacturers in Emilia-Romagna and Lombardy face compressed conversion cycles as EPR fee modulation approaches. The F-Gas Regulation's fluorinated chemistry restrictions redirect R&D investment toward bio-based moisture barriers for bakery applications. Milan's design houses influence premium packaging aesthetics across Mediterranean export markets.
Netherlands
Cold-chain pharmaceutical distributors in Rotterdam and Utrecht specify fiber-based insulated shippers for last-mile vaccine delivery. REACH compliance requirements shape material approval pathways for barrier coatings entering fresh-protein supply chains. The country's mechanical recycling infrastructure leads near-infrared detection deployment to separate biodegradable plastics from conventional PET streams.
Spain
Corrugated recovery rates in Catalonia and Madrid lag Northern European benchmarks, creating margin expansion opportunities for integrated mill networks. E-commerce fulfillment centers in Barcelona pilot lightweight molded fiber cushions displacing polyethylene air pillows. The Iberian peninsula's lower collection rates attract capital deployment toward closed-loop fiber systems.
Europe Eco-Friendly Packaging Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Europe's eco-friendly packaging sector. Integrated pulp-to-paper operators control raw material flows while specialty converters focus on certification and customization. Three archetypes dominate: multinational material platforms with captive fiber supply, regional converters with compostability expertise, and technology licensors with barrier coating patents. Competitive moves concentrate on backward integration into Nordic pulp assets and strategic partnerships with anaerobic digestion operators.
Among integrated material platforms, Amcor and Mondi exemplify the capital-intensive archetype with in-house polymer compounding and pulp operations. Smurfit Westrock anchors corrugated recycling infrastructure across multiple European markets. Within the specialty tier, Notpla and Hipli occupy positions tied to novel material formats and e-commerce fulfillment innovation respectively. Stora Enso represents Nordic fiber dominance with controlled timber supply chains.
| Leading Market Players |
|---|
| Amcor |
| Notpla |
| Smurfit Westrock |
| Hipli |
| Elopak |
| Stora Enso |
| Mondi |
| Bloom Biorenewables |
| Tetra Pak |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between ASTM D6400-compliant bioplastics and uncertified alternatives splits procurement budgets and reshapes supplier hierarchies across the continent. German food service operators pay premiums for documented compostability that unlocks anaerobic digestion cost savings, while Spanish converters absorb margin compression from REACH-compliant barrier coating volatility.
Pricing Analysis
Bundled certification-and-logistics packages command premiums over unbundled material-only supply in the European market. Three-tier pricing structure across premium certified, standard recyclable, and economy conventional formats reflects EPR fee modulation differentials under EU Packaging Directive delegated acts. Pricing pressure stems from Nordic pulp harvest cycle volatility affecting bio-based moisture barrier input costs. Private-label retail buyers exhibit highest price sensitivity, while cold-chain pharmaceutical distributors prioritize performance over unit economics.
Supply Chain Analysis
Reverse-logistics flows for corrugated recovery and industrial composting returns anchor supply chain design across Northern Europe. Raw material concentration centers on Finland, Sweden, and Germany for kraft pulp and polymer compounding capacity. The network draws from Nordic timber belts for fiber supply and Rhine corridor chemical clusters for biodegradable polymer production. Single-source vulnerability exists in specialty cellulose derivatives for barrier coatings. Distribution runs through integrated mill networks and regional converter hubs serving grocery retail and food service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between Germany's premium-certified procurement and Spain's lagging recovery infrastructure creates margin capture opportunities for integrated operators. EPR fee modulation timelines compress faster in Northern Europe than Iberia, rewarding early certification investment.
For Market Incumbents: Acquire anaerobic digestion partnerships and Nordic pulp assets to lock in backward integration before REACH-compliant barrier coating costs spike. Defend position by accelerating ASTM D6400 certification backlogs that stall competitor product launches. Capacity addition in Finland and Sweden secures fiber supply against harvest cycle volatility.
For New Entrants and Emerging Players: CSRD-driven disclosure mandates in France and Germany open a window for ISO 14040-verified lifecycle data services. Target Spain and Portugal's underdeveloped corrugated recovery infrastructure with closed-loop fiber collection systems. White-space exists in molded fiber temperature-sensitive applications for pharmaceutical cold-chain logistics.
For Investors and Strategic Acquirers: Consolidation pressure builds where compostability certification expertise concentrates in regional laboratory networks and specialty converter tiers. Long-term viability favors integrated pulp-to-paper platforms with captive timber supply and in-house polymer compounding. Watch for F-Gas Regulation enforcement deadlines as inflection indicators for bio-based barrier coating adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Pulp Assets | Captive fiber supply insulates margin from harvest cycle volatility affecting kraft paper pricing. |
| ASTM D6400 Certification Fast-Track Program | Accelerated laboratory partnerships compress eight-month testing queues that stall competitor launches. |
| Anaerobic Digestion Operator Partnership | Integrated waste processing access eliminates landfill diversion costs for German food service clients. |
| ISO 14040 Lifecycle Data Platform | Verified Scope 3 emissions documentation satisfies CSRD disclosure mandates for French poultry processors. |
| Iberian Corrugated Recovery Network Buildout | Closed-loop collection infrastructure captures margin expansion in Spain and Portugal's lagging markets. |
Research Methodology
Direct dialogue with sustainability officers at major grocery retailers, procurement leads at food and beverage manufacturers, technical directors at corrugated converters, and regulatory affairs specialists at packaging material suppliers grounded qualitative findings. Secondary validation drew from ECHA substance registrations, EU Packaging Directive delegated acts, customs trade data for pulp and polymer flows, and SEC filings of listed packaging companies. Bottom-up volume modeling and top-down macroeconomic triangulation cross-checked segment-level outputs.
Bottom-up demand modeling tracked material type, product format, end-use industry, and country-level regulatory cluster across the analysis window. CAGRs were derived from segment-level volume trajectories and value-per-unit assumptions tied to certification premiums. Forecast inputs included EPR fee modulation schedules, industrial composting capacity buildout timelines, and REACH compliance cost curves for barrier coating transitions.
Revisions become necessary when EU Packaging Directive enforcement timelines accelerate, Nordic pulp harvest disruptions exceed historical variance bands, or bio-based moisture barrier technical performance gaps persist beyond projected maturation curves. Periodic stress-testing of base assumptions against delegated act publication schedules and laboratory certification throughput is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
Bagasse Bowls Market
Sustainable Packaging
Asia-Pacific Sustainable Packaging Market
Sustainable Packaging
Zero Waste Packaging Market
Sustainable Packaging
Sustainable Packaging Market
Sustainable Packaging
North America Eco-Friendly Packaging Market
Sustainable Packaging
Sustainable Foodservice Packaging Market
Sustainable Packaging
Bio-Based Cutlery Market
Sustainable Packaging
Asia-Pacific Eco-Friendly Packaging Market
Sustainable Packaging
PVC-Free Packaging Market
Sustainable Packaging
Sustainable Plastic Packaging Market
Sustainable Packaging
Green Packaging Market
Sustainable Packaging
Japan Green Packaging Market
Sustainable Packaging
United States Green Packaging Market
Sustainable Packaging
Bagasse Tableware Products Market
Sustainable Packaging
Global Paper Straw Market
Sustainable Packaging
Wheat Straw Cutlery Market