
 Fluted Carton Trays Market | 2026-2036
Fluted Carton Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Fluted Carton Trays Market Foresight
EU Packaging and Packaging Waste Regulation is decoupling virgin fiber access from historical cost baselines, forcing converters to recalibrate raw material procurement. DS Smith leverages integrated paper mill networks across Northern Europe to sustain margin stability under escalating compliance costs. Smurfit Kappa anchors its competitive stance through closed-loop fiber collection systems that reduce external pulp dependency. Mondi specializes in lightweight flute engineering that navigates the tension between gram-weight reduction and stacking strength requirements.
Fluted carton trays are corrugated paperboard structures formed with arched flutes sandwiched between linerboards, typically manufactured through single-facer corrugation and rotary die-cutting processes to achieve precise dimensional tolerances for automated packing lines. Their primary purpose centers on unitizing perishable goods and consumer products for shelf-ready presentation while absorbing distribution stresses. Kraft paper material dominates volume production due to its tear resistance and natural moisture management, though recycled fiberboard represents the fastest-expanding category as brand owners impose post-consumer content minimums. Protective packaging applications lead absolute demand across electronics components and pharmaceutical products, while retail display configurations command premium positioning in personal care and food service channels where visual merchandising directly influences purchase conversion.
REACH compliance through ECHA governs chemical treatments in coating layers, while FSC chain-of-custody certification shapes supplier qualification protocols for multinational food and beverage brands. CE marking under the EU Green Deal framework is accelerating substitution of plastic thermoformed trays in prepared food segments. Stakeholders must monitor how forthcoming EU Deforestation Regulation due diligence obligations recalibrate virgin fiber sourcing from Nordic and Baltic pulp suppliers.
Market Dynamics
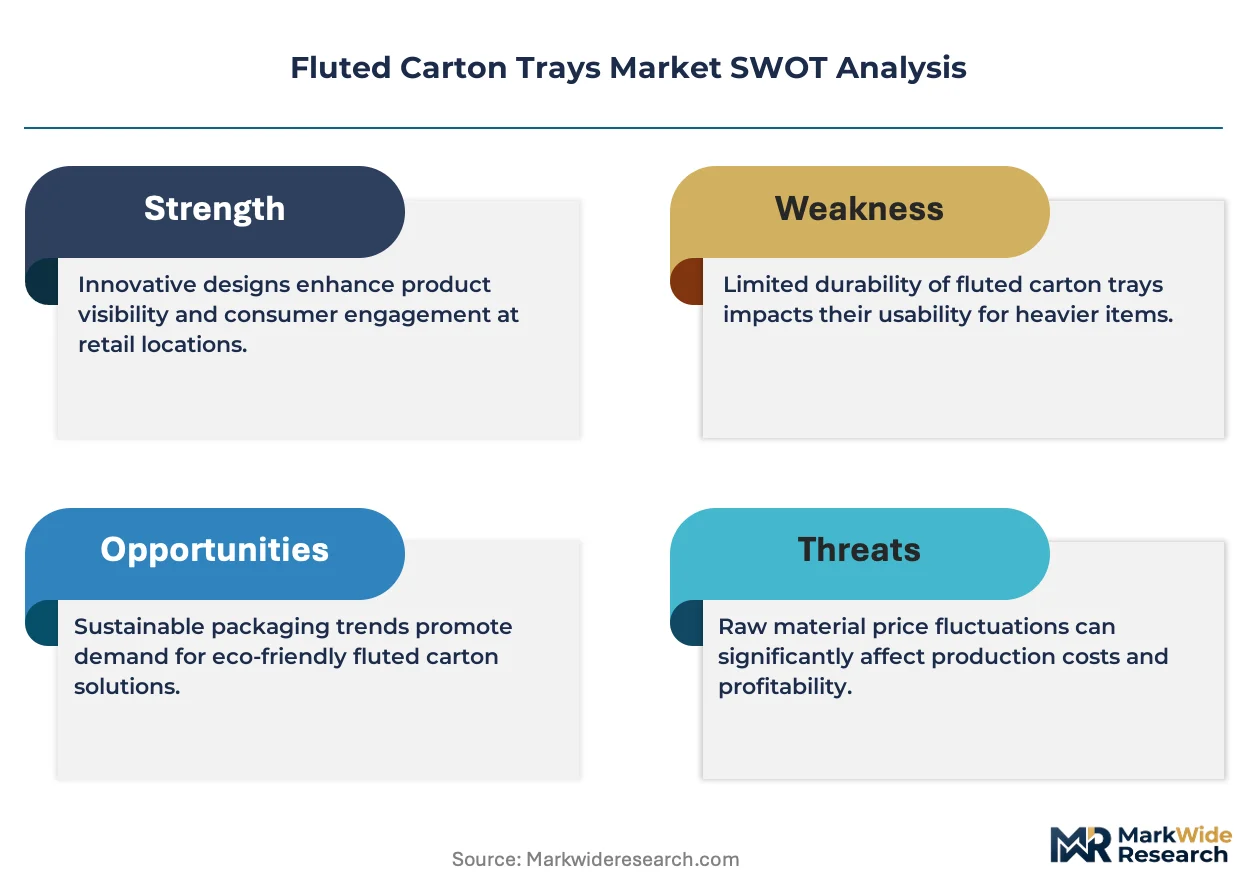
The EU Packaging and Packaging Waste Regulation is forcing converters to rebuild raw material procurement around recycled fiber minimums, compressing virgin kraft paper demand curves while elevating closed-loop collection infrastructure to strategic priority status.
Growth Catalysts
- CE marking acceleration:Prepared food processors across Germany and France are abandoning plastic thermoformed trays ahead of EU Green Deal enforcement deadlines, redirecting capex toward fluted carton tray conversion lines.
- Retail-ready packaging standardization:Benelux supermarket chains are mandating shelf-ready tray formats that eliminate secondary handling, pulling corrugated display configurations into produce and dairy supply contracts.
- Lightweight flute engineering:Advances in E-flute and F-flute micro-corrugation are expanding tray applicability into pharmaceutical blister packs and electronics component shipping without sacrificing stacking strength thresholds.
Market Restraints
- Recycled fiber cost volatility:Post-consumer pulp prices fluctuate with municipal collection program funding cycles, exposing converters to margin compression when OCC (old corrugated containers) supply tightens during packaging demand surges.
- Nordic pulp supplier concentration:Virgin kraft linerboard production clusters in Swedish and Finnish mill networks, creating geographic single-point-of-failure risk for FSC-certified virgin fiber dependent on Baltic Sea logistics corridors.
- Plastic tray residual cost advantage:Thermoformed PET and PP retain lower unit economics at high volumes above 500,000 units, blocking fluted carton penetration in mass-market beverage multipacks and frozen food segments.
Strategic Opportunities
- Poland and Czech Republic retail expansion:Discounter format growth in Central European markets is importing Western European retail-ready packaging standards, creating first-mover advantage for tray converters establishing regional production.
- Pharmaceutical cold-chain compliance:Temperature-stable flute structures with integrated insulating liners are capturing share from expanded polystyrene shippers in vaccine distribution networks governed by EMA Good Distribution Practice guidelines.
- E-commerce produce subscription channels:Direct-to-home fresh produce delivery services in urban France and Germany are specifying custom tray dimensions for automated fulfillment lines, bypassing traditional retail distribution entirely.
Industry Challenges
- Rotary die-cutting precision engineering:Automated packing lines at dairy processors demand dimensional tolerances below 0.5mm, requiring capital-intensive tooling upgrades that strain mid-cap converter balance sheets.
- FSC chain-of-custody audit complexity:Multinational food brands are extending certification requirements to tier-three suppliers, forcing smaller converters to absorb third-party verification costs or exit qualified vendor lists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluted Carton Trays Market |
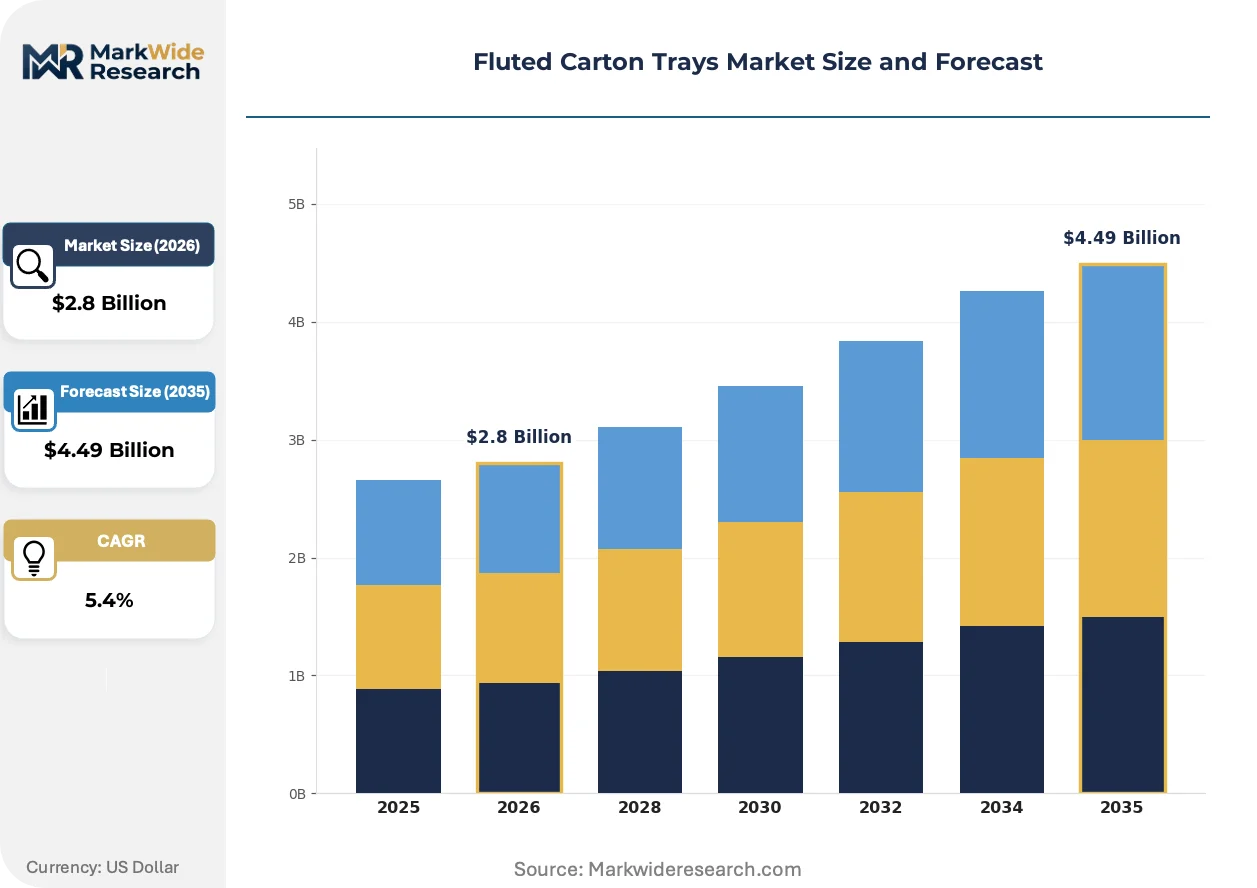
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Kraft Paper, Bleached Paperboard, Recycled Fiberboard, Coated Paper, Virgin Fiberboard End Use Industry: Food & Beverage, Personal Care, Household Products, Electronics Components, Pharmaceutical Products Application: Protective Packaging, Retail Display, Storage Solutions, Transportation Packaging, Promotional Packaging Packaging Style: Folding Trays, Die-Cut Trays, Set-Up Trays, Sleeve Trays, Windowed Trays |
| Companies Covered | DS Smith, Smurfit Kappa, International Paper, WestRock Company, Mondi, Georgia-Pacific, Packaging Corporation of America, Stora Enso, Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluted Carton Trays Market Shifts & Advancements
Active substitution of plastic thermoformed packaging is compressing development cycles for fiber-based alternatives, while regulatory compliance tooling and lightweight engineering are converging to redefine performance benchmarks across perishable goods distribution.
Micro-flute corrugation technology is absorbing structural loads previously assigned to heavier B-flute and C-flute configurations, enabling gram-weight reductions of 15-20% without compromising compression strength. Pharmaceutical logistics providers in the Netherlands are adopting these formats for temperature-sensitive shipments. The technology is absorbing market share from molded fiber and expanded polystyrene in premium cold-chain applications where dimensional stability determines insurance liability.
REACH compliance through ECHA is mandating chemical disclosure across coating layers used for moisture resistance and grease barriers, compelling converters to reformulate wax and polyethylene treatments. The regulation is extending qualification timelines for new tray specifications by 8-12 months in food-contact applications. Prepared meal manufacturers in France are responding by consolidating supplier bases around established REACH-compliant coating portfolios.
Buyer concentration among pan-European retail alliances is compressing contract renewal cycles from three-year frameworks to annual tenders with performance scorecards. Produce distributors in Germany are consolidating purchasing through centralized procurement cooperatives that standardize tray specifications across regional subsidiaries. This concentration is most visible in the Rhein-Ruhr and Hamburg logistics corridors where three retail groups control 60% of fluted carton tray volume.
Fluted Carton Trays Market Segmentation
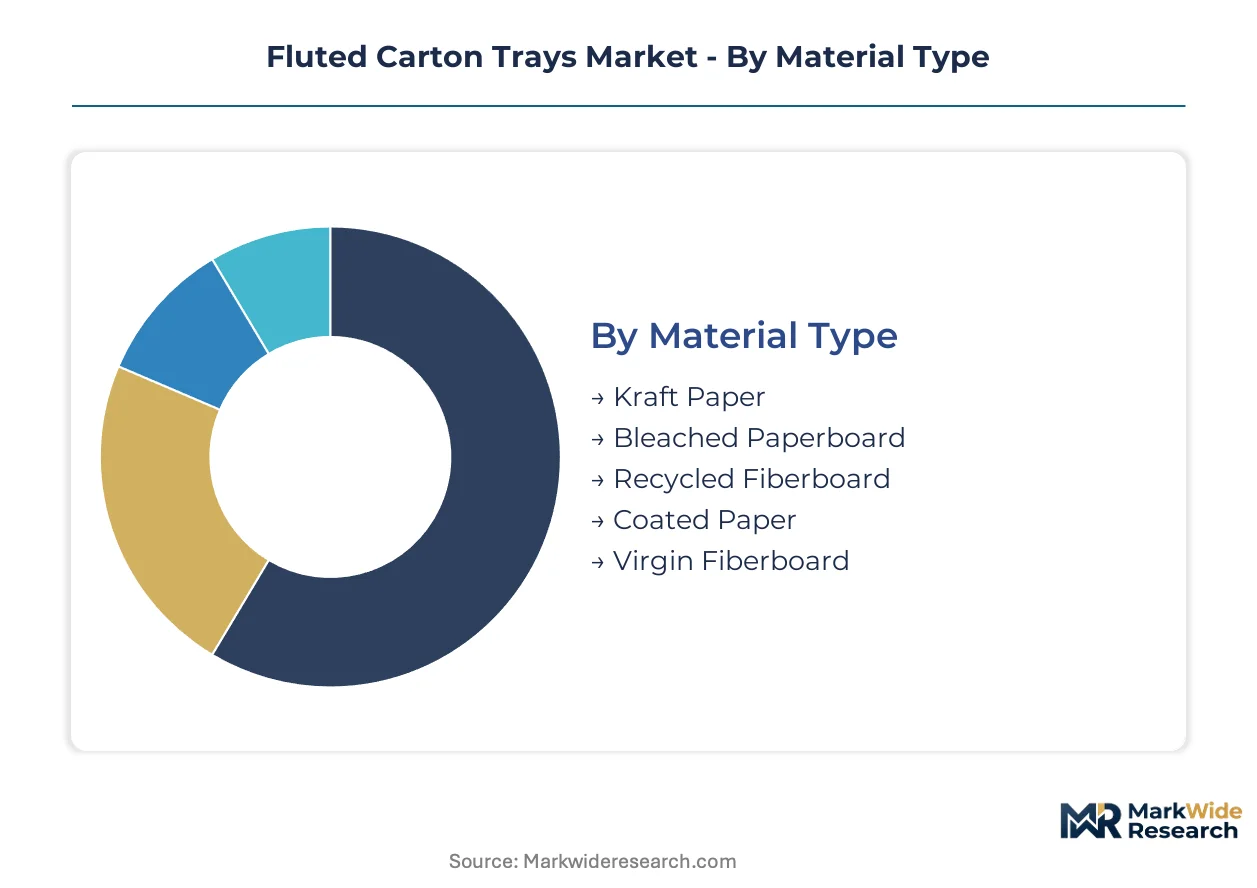
Material selection dictates cost structure and regulatory compliance pathways for tray converters navigating EU Packaging and Packaging Waste Regulation mandates. End-use concentration in perishables and pharmaceuticals shapes performance specifications across flute engineering and coating chemistry investments.
Material Type:
Buyers prioritize tear resistance and moisture management characteristics when specifying linerboard grades for automated packing lines.
- Kraft Paper:Unbleached sulfate pulp delivers superior tear strength and natural moisture absorption for fresh produce distribution. German fruit exporters specify this grade for Rhein-Ruhr logistics corridors where humidity fluctuation stresses tray integrity.
- Recycled Fiberboard:Post-consumer OCC content satisfies brand-owner minimums under tightening circular economy targets. French prepared meal manufacturers are consolidating procurement around REACH-compliant recycled fiber suppliers to preempt ECHA disclosure audits.
- Bleached Paperboard:Bright white surfaces support high-graphics retail display applications in personal care channels.
- Coated Paper:Polyethylene and wax barrier treatments extend shelf life for moist food contact.
- Virgin Fiberboard:FSC-certified Nordic pulp retains preference for pharmaceutical cold-chain where dimensional stability governs insurance liability.
Kraft paper leads on scale; recycled fiberboard leads on momentum.
End Use Industry:
Regulatory pressure on single-use plastics is redirecting capital allocation toward fiber-based alternatives in prepared food and healthcare segments.
- Food & Beverage:Prepared meal processors across Benelux supermarket chains are abandoning thermoformed PET ahead of EU Green Deal enforcement deadlines. CE marking acceleration is pulling corrugated display configurations into dairy and produce supply contracts.
- Pharmaceutical Products:Temperature-stable flute structures with integrated insulating liners are capturing share from expanded polystyrene in vaccine distribution networks governed by EMA Good Distribution Practice guidelines. Dutch logistics providers specify micro-flute engineering for dimensional stability.
- Personal Care:Visual merchandising requirements drive premium tray specifications for shelf-ready presentation.
- Electronics Components:E-flute and F-flute micro-corrugation expands applicability into static-sensitive shipping without sacrificing stacking strength.
- Household Products:Standard C-flute configurations dominate non-perishable distribution economics.
Food and beverage leads on scale; pharmaceutical products lead on momentum.
Application:
Automation readiness and handling efficiency determine tray format selection across distribution network configurations.
- Protective Packaging:Compression strength engineering absorbs distribution stresses for electronics and pharmaceutical components. EMA guidelines on temperature excursion liability are elevating structural specification priority in cold-chain networks.
- Retail Display:Shelf-ready formats eliminate secondary handling for Benelux supermarket chains. German discounters are mandating standardized dimensions for automated replenishment systems.
- Transportation Packaging:B-flute and C-flute configurations optimize pallet cube utilization for bulk produce movements.
- Storage Solutions:Stackable tray designs support warehouse density targets in urban fulfillment centers.
- Promotional Packaging:Limited-run graphics capabilities serve seasonal campaign cycles.
Protective packaging leads on scale; retail display leads on momentum.
Packaging Style:
Tooling investment and changeover flexibility shape converter capacity allocation across order volume profiles.
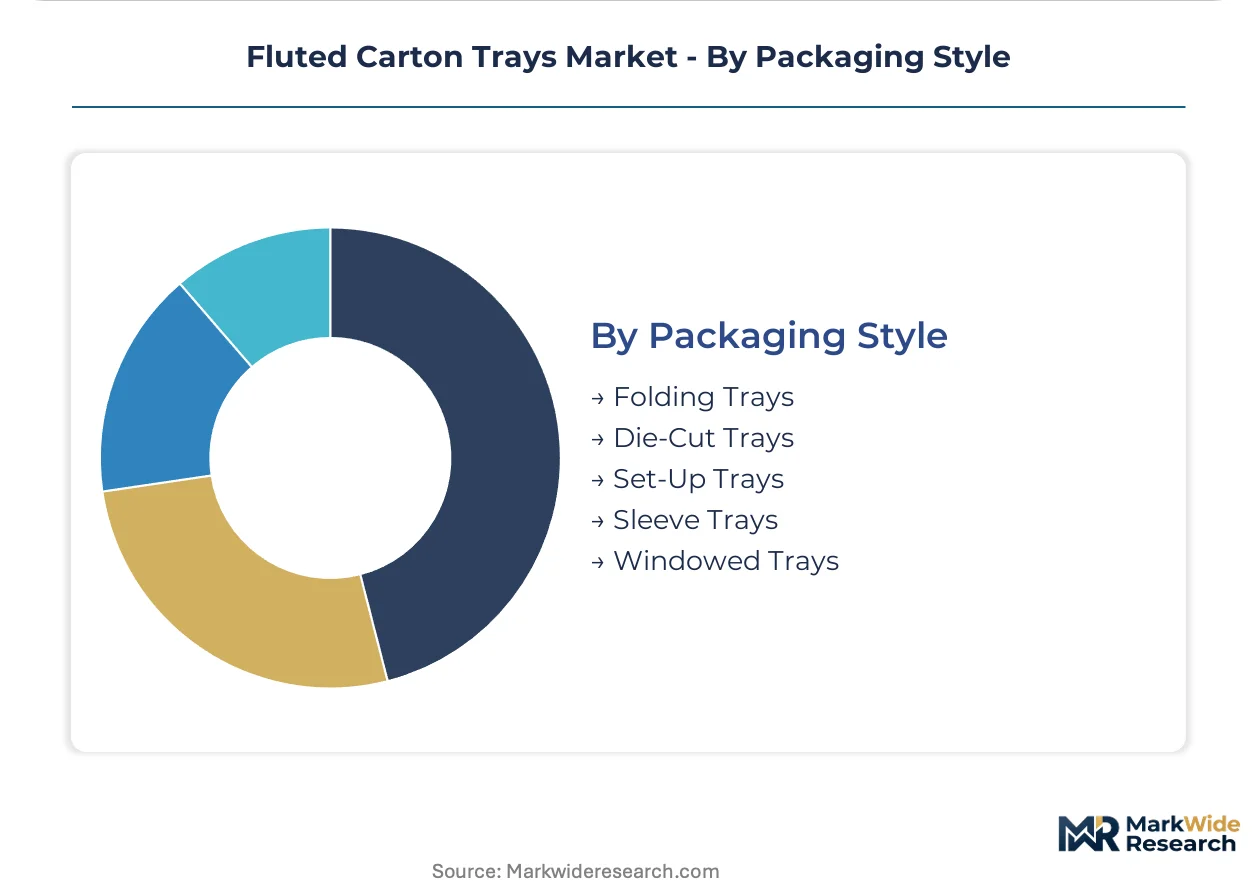
- Die-Cut Trays:Rotary die-cutting achieves dimensional tolerances below 0.5mm for automated dairy packing lines. Precision engineering demands capital-intensive tooling upgrades that strain mid-cap converter balance sheets.
- Folding Trays:Flat-blank shipping minimizes logistics cost for e-commerce produce subscription channels in urban France and Germany. Custom dimensions bypass traditional retail distribution entirely.
- Set-Up Trays:Rigid sidewall construction supports premium product presentation in personal care.
- Sleeve Trays:Combination formats reduce material weight for beverage multipacks.
- Windowed Trays:Film integration requirements complicate recycling stream compliance under EU Packaging and Packaging Waste Regulation.
Die-cut trays lead on scale; folding trays lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentrated packaging engineering talent in the Benelux corridor and Northern Germany anchors European fluted carton tray innovation, with converter networks clustering around major pulp terminals and automated dairy processing hubs.
Germany
Rhein-Ruhr logistics corridors and Hamburg port infrastructure drive demand for retail-ready tray formats among fresh produce distributors. CE marking under the EU Green Deal accelerates substitution of plastic thermoformed trays in prepared food segments. Bavarian dairy processors specify die-cut trays with dimensional tolerances below 0.5mm for automated packing lines.
France
Prepared meal manufacturers in the Île-de-France region consolidate procurement around REACH-compliant recycled fiber suppliers. ECHA disclosure mandates extend qualification timelines for new tray specifications by 8-12 months. Auvergne-Rhône-Alpes logistics providers adopt micro-flute engineering for pharmaceutical cold-chain distribution.
Netherlands
Dutch supermarket chains mandate shelf-ready tray formats that eliminate secondary handling across produce and dairy supply contracts. EMA Good Distribution Practice guidelines elevate structural specification priority for vaccine distribution networks. Rotterdam port clustering supports integrated paper mill networks serving converter demand.
Belgium
Benelux retail alliances compress contract renewal cycles from three-year frameworks to annual tenders with performance scorecards. EU Packaging and Packaging Waste Regulation tightens material recovery targets for corrugated display configurations. Antwerp-Brussels logistics corridors concentrate 60% of regional fluted carton tray volume through three retail procurement cooperatives.
Poland
Discounter format growth in Central European markets imports Western European retail-ready packaging standards. FSC chain-of-custody certification shapes supplier qualification protocols for multinational food brands establishing regional production. Warsaw-Łódź industrial zones attract first-mover tray converters seeking proximity to expanding retail distribution networks.
Fluted Carton Trays Market Competitive Landscape
The competitive structure tilts toward integrated paper producers with captive pulp supply and closed-loop fiber collection capabilities. Tier-one players leverage mill network density across Northern Europe to sustain margin stability under escalating compliance costs. Mid-cap specialists concentrate on precision die-cutting engineering for automated dairy and pharmaceutical lines. Dominant competitive moves include backward integration into recycled fiber collection infrastructure and geographic expansion into Central European retail growth corridors.
Within the integrated producer tier, DS Smith and Smurfit Kappa occupy positions defined by captive paper mill networks and closed-loop fiber systems. Mondi exemplifies the lightweight engineering specialist archetype, anchoring competitive stance through micro-flute technology development. These three companies represent distinct strategic vectors: integrated supply security, circular infrastructure control, and performance-driven material science.
| Leading Market Players |
|---|
| DS Smith |
| Smurfit Kappa |
| International Paper |
| WestRock Company |
| Mondi |
| Georgia-Pacific |
| Packaging Corporation of America |
| Stora Enso |
| Berry Global |
| Others |
Supply & Pricing Matrix
Centralized procurement cooperatives in the Rhein-Ruhr and Hamburg corridors are mandating standardized tray specifications with REACH-compliant coatings, forcing converters to absorb third-party verification costs or exit qualified vendor lists. This buyer consolidation compresses margin buffers across mid-cap specialists while rewarding integrated producers with captive FSC-certified fiber supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates die-cut precision trays for automated dairy lines from folding formats for e-commerce subscription channels. Price differentiation rests on FSC chain-of-custody certification grade and volume scale commitments, with annual tender frameworks replacing three-year contracts. Cost compression in the standard tier is intensifying because recycled fiberboard demand surges outpace municipal OCC collection capacity. Mass-market beverage multipacks exhibit highest price sensitivity due to residual plastic tray cost advantages above 500,000 units.
Supply Chain Analysis
Dual-sourcing requirements from pan-European retail alliances mandate multi-supplier qualification for FSC-certified virgin fiber, with production clustering in Sweden, Finland, and Germany. Raw material dependencies center on Nordic kraft linerboard, post-consumer OCC pulp, and REACH-compliant barrier coatings. Single-source vulnerability concentrates around Baltic Sea logistics corridors for virgin fiber delivery. Distribution runs through Rotterdam and Hamburg port terminals serving converter networks across the Benelux and Northern Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Prepared meal manufacturers across Germany and France are consolidating procurement around REACH-compliant recycled fiber suppliers, elevating certification-grade tray specifications above commodity alternatives.
For Market Incumbents: To counter margin compression from centralized retail procurement, DS Smith and Smurfit Kappa should deepen backward integration into closed-loop fiber collection infrastructure across Northern Europe. Captive pulp supply anchors pricing power under escalating EU Packaging and Packaging Waste Regulation compliance costs. For New Entrants and Emerging Players: Pharmaceutical cold-chain logistics providers in the Netherlands represent an underserved buyer archetype seeking temperature-stable micro-flute engineering for vaccine distribution. First-mover positioning in Poland and Czech Republic discounter format expansion offers white-space access before Western retail-ready standards fully penetrate. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap die-cutting specialists possessing precision engineering capabilities below 0.5mm tolerance thresholds. Long-term viability over the next decade hinges on rotary tooling upgrade cycles and EMA Good Distribution Practice qualification timelines. Watch for EU Deforestation Regulation due diligence obligations recalibrating Nordic virgin fiber sourcing as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Collection | Closed-loop infrastructure reduces external pulp dependency under tightening circular economy targets. |
| Micro-Flute Engineering R&D Investment | E-flute and F-flute advances capture pharmaceutical cold-chain share from expanded polystyrene shippers. |
| Central European Production Footprint Expansion | Polish and Czech facilities serve discounter format growth importing Western retail-ready standards. |
| REACH-Compliant Coating Portfolio Consolidation | Prequalified barrier treatments accelerate qualification timelines for French prepared meal manufacturers. |
| FSC Chain-of-Custody Certification Investment | Tier-three supplier compliance preserves multinational food brand vendor list eligibility. |
Research Methodology
Direct dialogue with corrugated converter plant managers, procurement leads at Benelux supermarket chains, dairy processor packaging engineers, and ECHA regulatory affairs specialists grounded qualitative findings. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, FSC chain-of-custody audit databases, EMA Good Distribution Practice guidelines, and customs trade data for kraft linerboard imports. Bottom-up tray volume estimates triangulated against top-down pulp consumption forecasts across the analysis window.
Top-down macroeconomic drivers and bottom-up segment-level demand curves converged in the analytical framework. Segmentation dimensions modeled include material type, end-use industry, application format, and packaging style across the projection horizon. CAGR derivation incorporated pharmaceutical cold-chain adoption rates, retail-ready packaging standardization timelines, and lightweight flute engineering penetration curves.
Underlying measurement precision varies by segment; pharmaceutical and food-contact applications carry tighter precision than household products due to regulatory disclosure requirements. Forecasts reflect assumptions around EU Deforestation Regulation implementation scope and recycled fiber collection program funding cycles. Deviation in Baltic Sea logistics corridor reliability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Thailand Folding Cartons and Corrugated Packaging Market
Cartons
Pick and Place Carton Packers Market
Cartons
Asia Pacific Folding Carton Market
Cartons
Folding Carton in Healthcare Market
Cartons
Carton Display Market
Cartons
Global Printed Cartons Market
Cartons
Africa Folding Carton Market
Cartons
Microwaveable Carton Market
Cartons
GCC Corrugated Box Packaging Market
Cartons
Folding Cartons Market
Cartons
GCC Folding Carton Market
Cartons
Fully Enclosed Cartons Market
Cartons
Litho Laminated Cartons Market
Cartons
Tuck Top Box Market
Cartons
Metallized PET Cartons Market
Cartons
XXL Packaging Market