
 Sustainable Plastic Packaging Market | 2026-2036
Sustainable Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainable Plastic Packaging Market Outlook
Buyer concentration in European grocery retail is decoupling from traditional petrochemical supply chains as supermarket chains consolidate purchasing power. Amcor leverages its global manufacturing footprint to serve these consolidated buyers with certified recyclable formats. Huhtamaki Group anchors its position through specialized fiber-based and molded pulp solutions for food service clients. Mondi competes by controlling paper and recycled plastic feedstocks across Central European production hubs.
Sustainable plastic packaging encompasses materials engineered to reduce environmental persistence through biodegradation, recyclability, or renewable feedstock origins, typically meeting compostability standards such as EN 13432 or ASTM D6400 for industrial decomposition within 180 days. These materials serve primarily to contain, protect, and preserve consumer goods while minimizing fossil resource extraction and post-consumer waste accumulation. Recycled content formats, particularly RPET, dominate volume flows as established collection infrastructure and regulatory mandates expand supply. Plant-based alternatives, led by PLA and starch-based compounds, represent the fastest-expanding material class as brand owners seek to differentiate beyond conventional recycling narratives. Biodegradable segments remain niche with concentrated margin pools in premium food service and agricultural film applications where composting infrastructure exists.
The EU Green Deal and F-Gas Regulation shape European demand by banning specific single-use plastic items and mandating minimum recycled content thresholds. The FDA and EPA influence United States market access through food contact safety approvals and emerging extended producer responsibility frameworks at state levels. BIS and CDSCO in India are developing bio-plastic standards for pharmaceutical and food contact applications that will determine import eligibility. Stakeholders must monitor how fragmented national implementations of these frameworks create compliance complexity that favors suppliers with multi-certification capabilities.
Market Dynamics
Retailer sustainability scorecards are consolidating procurement power across European and North American grocery chains, forcing material substitutions faster than production capacity can adapt. This demand compression is restructuring supplier relationships around certified recyclable and compostable formats.
Growth Catalysts
- EU Green Deal mandates:Minimum recycled content thresholds and single-use plastic bans are creating guaranteed offtake for certified materials across food and beverage packaging applications.
- Plant-based film innovation:PLA and starch-based compounds are capturing premium positioning as brand owners seek differentiation beyond conventional recycling narratives.
- German retail consolidation:Discounters and supermarket chains are pooling purchasing power to impose uniform sustainability standards on their supplier bases.
Market Restraints
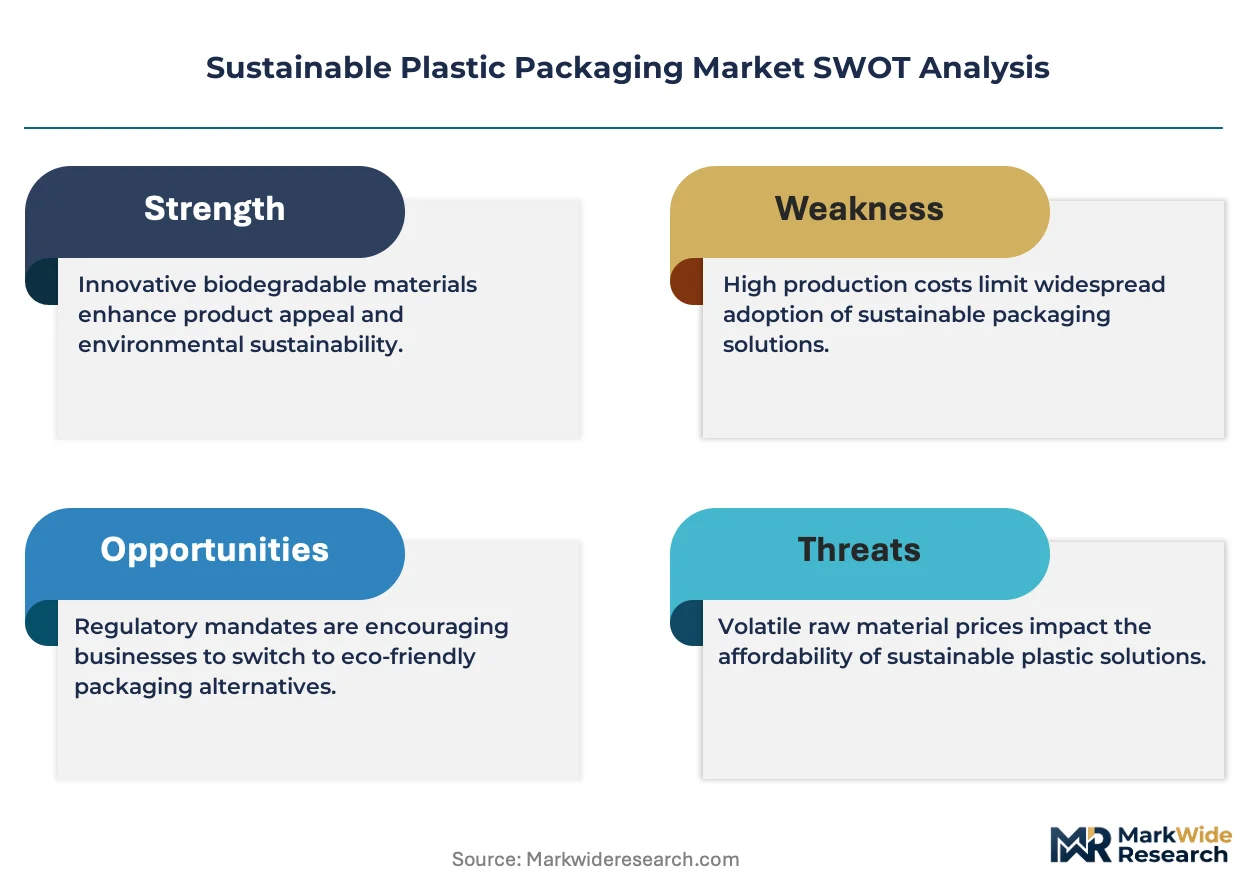
- Feedstock cost volatility:Agricultural commodity prices for corn and sugarcane directly impact PLA production economics, squeezing margins during harvest disruptions.
- Composting infrastructure gaps:Industrial decomposition facilities meeting EN 13432 standards remain concentrated in France, Germany, and the Netherlands, limiting addressable market for biodegradable formats.
- Recycled resin supply concentration:RPET collection and reprocessing capacity clusters in Germany and Italy, creating bottleneck risk for converters elsewhere.
Strategic Opportunities
- Indian regulatory development:BIS and CDSCO bio-plastic standards for pharmaceutical and food contact applications will determine import eligibility and first-mover advantage for certified suppliers.
- Agricultural film applications:Biodegradable mulch and greenhouse films represent concentrated margin pools where composting infrastructure already exists at farm level.
- Digital product passport integration:EU CSRD alignment is unifying traceability requirements with packaging certification, creating bundled service opportunities.
Industry Challenges
- Multi-certification complexity:Fragmented national implementations of compostability standards force suppliers to maintain parallel EN 13432, ASTM D6400, and emerging BIS compliance pathways simultaneously.
- Collection infrastructure capex:Scaling post-consumer RPET supply requires sorting facility investments that municipal budgets struggle to fund without extended producer responsibility frameworks.
- Food contact safety timelines:FDA and EFSA novel material approvals stretch 18-36 months, delaying commercialization of next-generation barrier coatings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustainable Plastic Packaging Market |
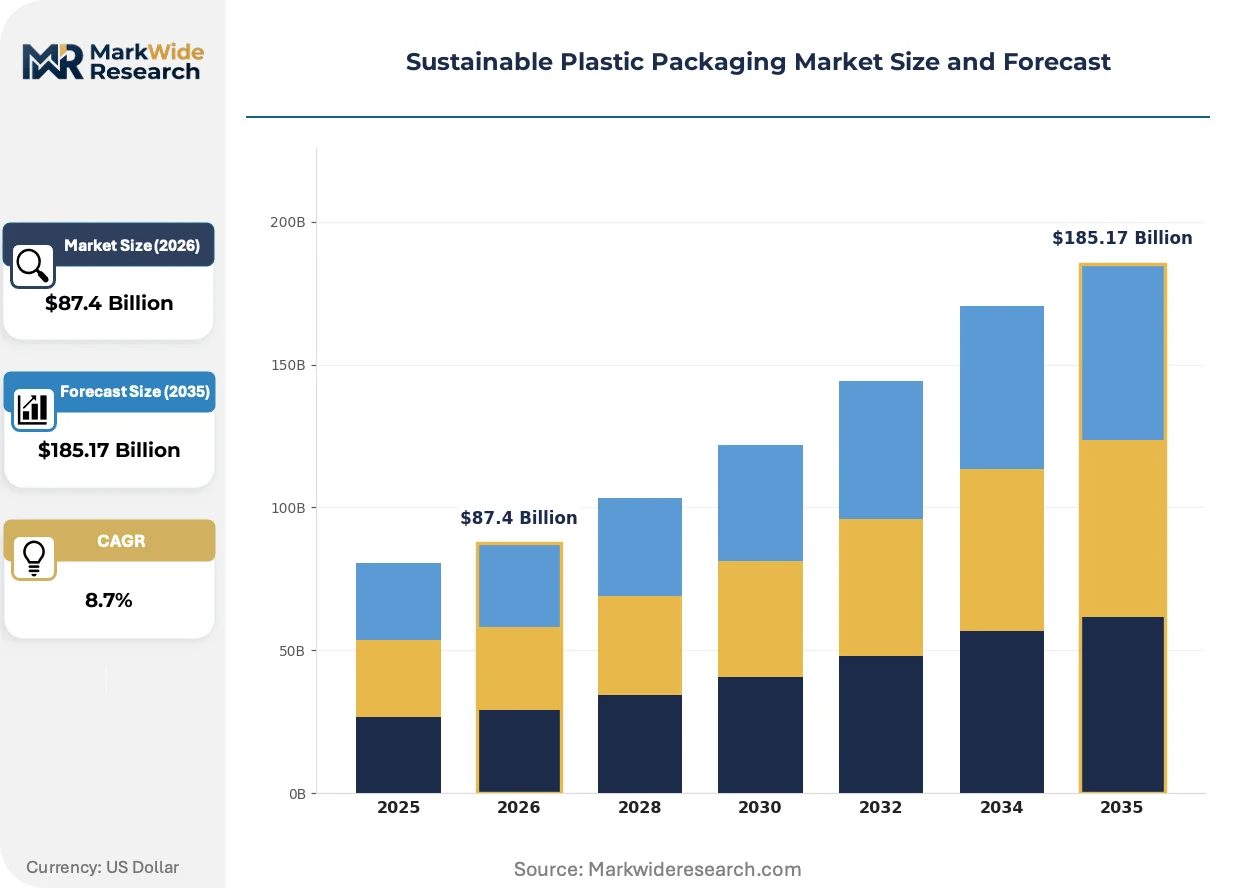
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $185.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable, Recycled, Plant-Based, Compostable Application: Food Packaging, Consumer Goods, Pharmaceuticals, Personal Care Material: PLA, PHA, RPET, Starch-Based Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Crown Holdings, Huhtamaki Group, Amcor, Ball Corporation, Tetra Pak, WestRock, Mondi, AptarGroup, Smurfit Kappa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainable Plastic Packaging Market Strategic Shifts
Active packaging formats are converging with sustainability mandates, creating hybrid solutions that extend shelf life while meeting compostability criteria. Material science breakthroughs are compressing the performance gap between renewable and fossil-based barriers.
Mono-material barrier films are unifying oxygen and moisture protection within single-polymer structures that simplify recycling streams. Food processors in Germany and France are adopting these formats ahead of 2025 regulatory deadlines. This unification is compressing demand for multi-layer laminates that previously dominated premium snack and fresh produce segments.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating conventional grease-resistant coatings from paper-based food service items. Manufacturers are pivoting to bio-based barrier alternatives for fast-food packaging and bakery applications. Central European converters are most exposed given their concentration of quick-service restaurant supply contracts.
Retailers are embedding sustainability metrics into supplier scorecards that determine shelf access and promotional placement. Grocery chains in the United States are displacing conventional procurement committees with cross-functional teams combining sustainability, quality, and cost criteria. California and New York state-level extended producer responsibility laws are accelerating this behavioral shift among national brand owners.
Sustainable Plastic Packaging Market Segmentation
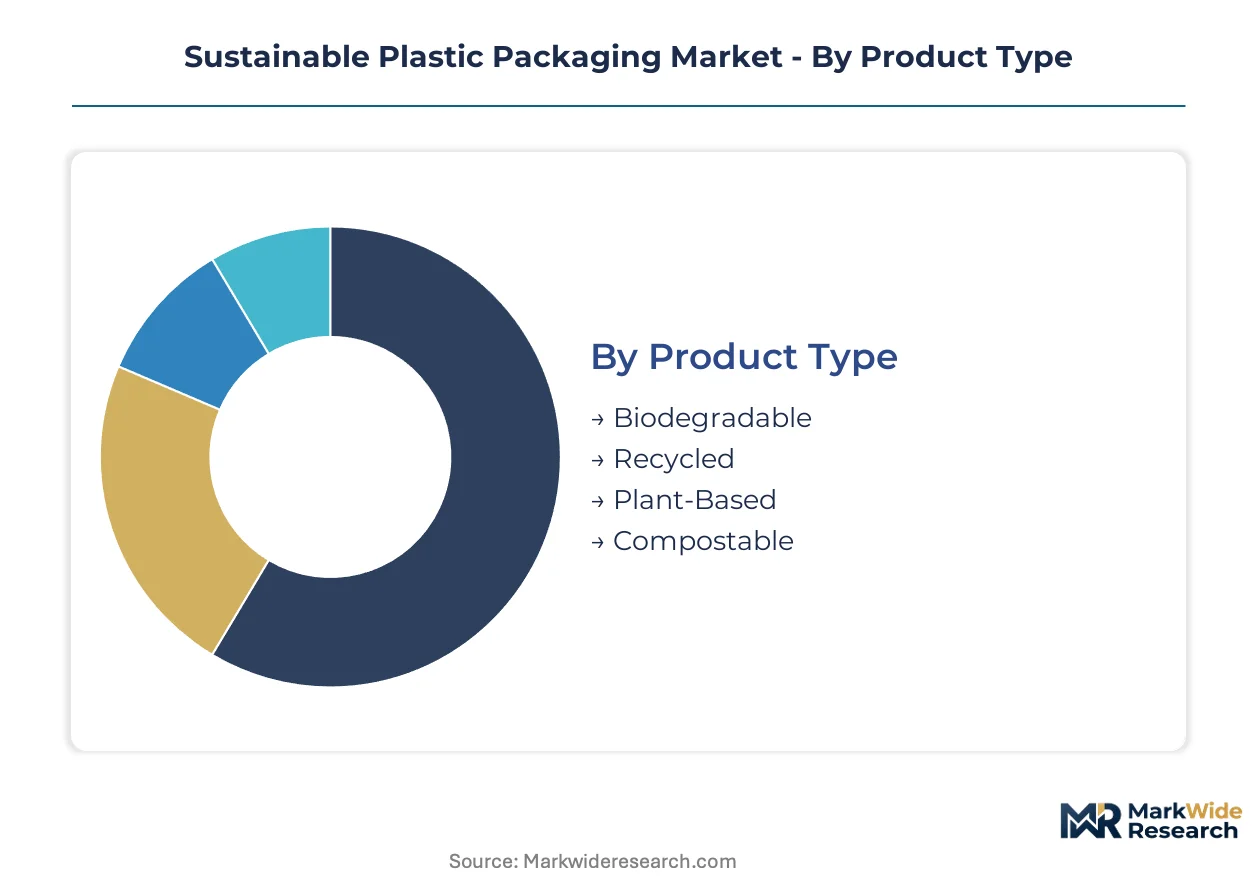
Segmentation in sustainable plastic packaging reveals how buyer procurement criteria diverge across regulatory environments and end-use requirements. Material certification standards and composting infrastructure availability create distinct addressable markets that reshape competitive positioning.
Product Type:
Procurement teams weight total cost of ownership against regulatory compliance timelines when selecting sustainable formats.
- Biodegradable:Formulations engineered for microbial decomposition under industrial composting conditions per EN 13432 or ASTM D6400 standards. Agricultural film buyers in France and the Netherlands prioritize these formats where on-farm composting infrastructure eliminates collection costs.
- Recycled:Post-consumer resin streams, predominantly RPET, that leverage established collection infrastructure and meet EU Green Deal minimum content mandates. German beverage brands are consolidating procurement around certified recycled content to satisfy retailer sustainability scorecards.
- Plant-Based:Derived from annually renewable feedstocks including corn starch and sugarcane bagasse.
- Compostable:Certified for both industrial and home decomposition pathways where infrastructure permits.
Recycled formats lead on scale; plant-based alternatives lead on momentum.
Application:
End-use specifications determine barrier performance requirements and food contact safety approval pathways.
- Food Packaging:Dominates volume flows across fresh produce, dairy, and prepared meal segments where oxygen and moisture barriers are non-negotiable. European grocery retailers are imposing uniform sustainability standards that favor mono-material recyclable formats over multi-layer laminates.
- Consumer Goods:Electronics and household product segments prioritize durability and aesthetic finish over biodegradability.
- Pharmaceuticals:Child-resistant and tamper-evident features combine with US FDA and EU EMA compliance requirements.
- Personal Care:Premium cosmetic brands differentiate through bio-based content claims and refillable format compatibility.
Food packaging commands the largest procurement volumes; pharmaceuticals impose the steepest certification barriers.
Material:
Feedstock availability and polymer processing economics determine regional manufacturing footprints.
- PLA:Polylactic acid derived from corn or sugarcane fermentation offers clarity and processability comparable to conventional plastics. Thai and Brazilian converters benefit from proximate sugarcane supply chains that compress raw material logistics costs.
- PHA:Polyhydroxyalkanoates produced through bacterial fermentation enable marine biodegradation pathways that PLA cannot match.
- RPET:Recycled polyethylene terephthalate from post-consumer bottle streams.
- Starch-Based:Blends incorporating native or modified starches for cost-sensitive disposable applications.
RPET dominates current production volumes; PHA exhibits the steepest expansion trajectory among emerging alternatives.
Distribution Channel:
Channel selection reflects order scale, certification documentation requirements, and technical service intensity.
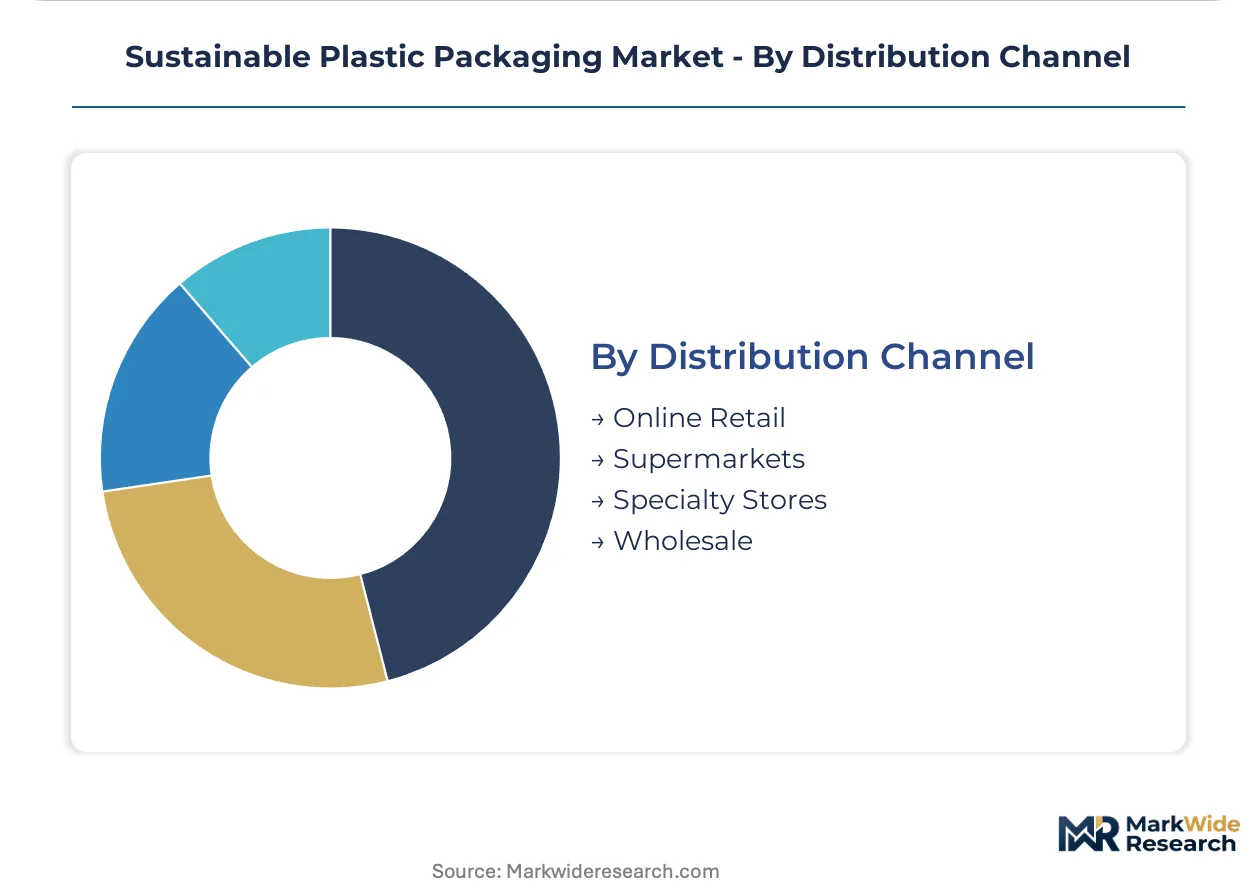
- Online Retail:Direct-to-brand platforms serving mid-size food processors and specialty cosmetic manufacturers. These channels aggregate demand from buyers lacking procurement scale to engage converters directly.
- Supermarkets:Private-label packaging procurement concentrated among European discounters pooling specifications across national markets.
- Specialty Stores:Catering to artisan food producers and premium personal care brands requiring low minimum order quantities.
- Wholesale:Volume aggregation for standardized formats serving quick-service restaurant chains and institutional food service.
Supermarket consolidation is displacing wholesale intermediaries; online retail is gaining share fastest among emerging brand owners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's retail consolidation outpaces United States regulatory fragmentation in driving material substitutions, while France and the Netherlands build composting infrastructure that Belgium and Italy lack.
Germany
Aldi and Lidl pool procurement specifications across discounter networks, compressing supplier margins around certified recyclable formats. The EU Green Deal mandates minimum recycled content thresholds for beverage packaging from 2025. The Düsseldorf-Cologne corridor hosts converter clusters serving private-label food brands with mono-material barrier films.
France
Carrefour and Intermarché impose sustainability scorecards determining shelf access for packaged food suppliers. The national anti-waste law for a circular economy (AGEC) mandates phased elimination of single-use plastics. Industrial composting facilities in the Île-de-France and Rhône-Alpes regions process biodegradable agricultural films at farm level.
United States
Walmart and Kroger displace conventional procurement committees with cross-functional sustainability teams. California and New York state-level extended producer responsibility laws accelerate behavioral shifts among national brand owners. The Chicago-Milwaukee corridor concentrates RPET reprocessing capacity serving Great Lakes beverage bottlers.
India
ITC and Dabur expand bio-plastic procurement for food and personal care applications ahead of import standard finalization. BIS and CDSCO develop pharmaceutical and food contact standards that will determine supplier eligibility. The Mumbai-Pune and Ahmedabad-Surat corridors attract converters positioning for first-mover certification advantage.
Netherlands
Ahold Delhaize consolidates North Sea purchasing power across Albert Heijn and Delhaize banners. National organic waste regulations mandate separate collection streams compatible with compostable packaging formats. The Rotterdam-Antwerp port cluster handles biopolymer feedstock imports for Central European converters.
Sustainable Plastic Packaging Market Competitive Environment
European producers anchor the integrated tier; North American specialists hold positions in metal and fiber-based formats. The supplier base organizes around three archetypes: diversified materials conglomerates with global manufacturing footprints, fiber and molded pulp specialists serving food service, and rigid packaging fabricators with beverage industry relationships. Consolidation proceeds through acquisition of regional converters with certification capabilities, while capacity expansion targets Central European hubs proximate to German retail demand.
Among diversified packaging conglomerates, Amcor and Mondi occupy positions spanning recyclable films and paper-based solutions. Huhtamaki Group exemplifies the fiber-based specialist archetype with concentrated food service exposure. These three entities represent contrasting strategic postures: global scale with multi-material portfolios, regional feedstock control, and dedicated format specialization.
| Leading Market Players |
|---|
| Crown Holdings |
| Huhtamaki Group |
| Amcor |
| Ball Corporation |
| Tetra Pak |
| WestRock |
| Mondi |
| AptarGroup |
| Smurfit Kappa |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between industrial compostable and conventional recyclable formats manifests in parallel pricing premiums and feedstock sourcing strategies across converter networks. Buyers in Germany and France absorb EN 13432-certified premiums while supply chains reorganize around proximate agricultural resin production.
Pricing Analysis
Capacity additions in Thailand and Brazil are reshaping price floors for PLA grades as sugarcane-proximate producers compress logistics differentials against corn-based North American supply. Three-tier pricing structure across premium certified compostable, standard recycled content, and economy virgin-equivalent levels segments buyer budgets by sustainability scorecard stringency. Pricing pressure stems from agricultural commodity volatility in corn and sugarcane feedstocks that converters struggle to pass through under fixed retail procurement contracts. Quick-service restaurant chains exhibit highest price sensitivity due to volume scale and thin operating margins, while premium cosmetic brands absorb premiums for bio-based content claims.
Supply Chain Analysis
Freight cost differentials between biopolymer feedstock origins and Central European conversion hubs are restructuring supplier geographic priorities. Manufacturing concentrates in Germany, Italy, and the Netherlands where beverage bottlers and food processors cluster around established RPET reprocessing infrastructure. Raw material dependencies center on post-consumer PET collection streams, corn and sugarcane fermentation feedstocks, and specialty barrier coating chemistries. Single-source vulnerability runs through German RPET reprocessing capacity that serves cross-border demand from France and Benelux markets. Distribution runs through supermarket private-label procurement committees that pool specifications across national banners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sustainable plastic packaging market functions as a stable compounder where regulatory mandate ratchets guarantee offtake expansion regardless of macroeconomic cyclicality. EU Green Deal threshold escalations and state-level extended producer responsibility laws in the United States embed demand visibility across the projection horizon.
For Market Incumbents: Deploy multi-certification capability as the primary defensive lever against margin compression from emerging Asian converters. Anchor position through backward integration into post-consumer collection infrastructure in Germany and Italy, eliminating third-party RPET supply bottlenecks. Defend against specialty fiber-based entrants by accelerating mono-material barrier film R&D to match Huhtamaki's food service penetration.
For New Entrants and Emerging Players: Direct-to-brand digital platforms serving mid-size European food processors represent the most penetrable white-space corridor bypassing incumbent converter relationships. Target Indian pharmaceutical and food contact applications ahead of BIS and CDSCO standard finalization to secure first-mover certification advantage. Agricultural film segments in France and the Netherlands offer concentrated margin pools where on-farm composting infrastructure eliminates collection cost competition.
For Investors and Strategic Acquirers: Consolidation pressure builds where regional converters hold EN 13432 or ASTM D6400 certifications that multi-national buyers require for procurement compliance. The market supports long-term viability framing around compound annual demand expansion driven by regulatory mandate rather than discretionary brand preference. Acquisition targets should exhibit certification depth across multiple geographies plus proximate relationships with Ahold Delhaize or Aldi procurement networks. Monitor EU Green Deal threshold escalation announcements as the signal indicating accelerated capacity investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Infrastructure | Captive RPET supply secures volume commitments from German beverage bottlers facing EU Green Deal mandates. |
| Multi-Certification Investment | Parallel EN 13432, ASTM D6400, and emerging BIS pathways unlock procurement access across fragmented regulatory regimes. |
| Mono-Material Barrier Film Development | Single-polymer structures simplify recycling streams and satisfy Carrefour sustainability scorecard requirements ahead of competitors. |
| Agricultural Film Specialization | Farm-level composting infrastructure in France and Netherlands enables premium pricing without municipal collection dependency. |
| Digital Product Passport Integration | EU CSRD alignment bundles traceability with packaging certification, creating service revenue beyond commodity conversion margins. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to triangulate demand signals across the sustainable packaging value chain. Primary fieldwork engaged sustainability procurement directors at European grocery retailers, technical R&D leads at biopolymer converters, regulatory affairs managers navigating multi-jurisdiction certification, and category buyers at quick-service restaurant chains. Secondary validation drew from EU Green Deal implementation documents, FDA food contact safety filings, BIS draft standard consultations, and customs trade data tracking biopolymer feedstock flows. Bottom-up capacity assessments at converter facilities were reconciled against top-down demand projections from retail procurement scorecard analysis.
Segment-weighted modeling distributed volume and value across material type, application end-use, and geographic regulatory cluster dimensions throughout the forecast period. CAGRs were derived from regression analysis against EU Green Deal threshold implementation schedules and state-level extended producer responsibility adoption curves. Industry-specific inputs included PLA production capacity expansion timelines from Thai and Brazilian fermentation facilities, RPET collection infrastructure investment pipelines in Germany and Italy, and composting facility commissioning rates across France and the Netherlands.
The model assumes a particular technology adoption path; alternative pathways for PHA marine biodegradation or advanced chemical recycling would alter the outlook if cost curves compress faster than projected. Forecasts reflect documented assumptions around regulatory enforcement consistency and retailer sustainability scorecard penetration rates. A model refresh is warranted upon material change in EU Green Deal threshold acceleration or FDA novel material approval timeline shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
Global Disappearing Packaging Market
Sustainable Packaging
Asia-Pacific Eco-Friendly Packaging Market
Sustainable Packaging
Zero Waste Packaging Market
Sustainable Packaging
GCC Green Packaging Market
Sustainable Packaging
Japan Green Packaging Market
Sustainable Packaging
Sustainable Foodservice Packaging Market
Sustainable Packaging
Bagasse Tableware Products Market
Sustainable Packaging
Plant Based Packaging Market
Sustainable Packaging
Europe Eco-Friendly Packaging Market
Sustainable Packaging
Compostable Tableware Market
Sustainable Packaging
Areca Plates Market
Sustainable Packaging
Middle East and Africa Eco-Friendly Packaging Market
Sustainable Packaging
Europe Green Packaging Market
Sustainable Packaging
North America Eco-Friendly Packaging Market
Sustainable Packaging
Eco-Friendly Straw Market
Sustainable Packaging
Bagasse Bowls Market