
 Green Packaging Market | 2026-2036
Green Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Green Packaging Market Analysis
The EU Green Deal is restructuring procurement priorities across European consumer goods supply chains. Amcor plc leverages its integrated fiber and film platform to capture volume in recyclable flexible formats. Mondi Group anchors its position through kraft-paper innovation for e-commerce void-fill applications. DS Smith competes via closed-loop carton recycling partnerships with major grocery retailers.
Green packaging encompasses containers, wraps, and protective structures engineered from renewable, recyclable, or biodegradable substrates with certified end-of-life pathways, typically incorporating minimum post-consumer recycled thresholds or bio-based content above 30% by mass, serving to reduce environmental burden while maintaining product integrity through distribution. Recyclable paper formats currently dominate volume flows, though compostable plant-based plastics represent the fastest-expanding material category as industrial composting infrastructure scales. Food and beverage applications command the largest share of demand, while personal care brands are shifting toward glass and metal refill systems to differentiate on circularity credentials.
EMA guidelines on pharmaceutical packaging sustainability, REACH restrictions on persistent chemicals in food-contact materials, and the EU F-Gas Regulation on blowing agents for foam protective packaging collectively tighten compliance thresholds and redirect R&D spending toward verified low-impact alternatives. Stakeholders must monitor evolving Extended Producer Responsibility fee structures and bio-based certification schemes to anticipate margin compression and access advantages.
Market Dynamics
Industrial composting infrastructure expansion across Northern Europe is compressing the cost premium between conventional plastics and certified compostable alternatives, forcing converters to retool extrusion lines ahead of anticipated EPR fee escalations.
Growth Catalysts
- EU Green Deal packaging compliance thresholds:Germany's retail chains now mandate minimum recycled content in private-label packaging, pulling film converters toward certified post-consumer feedstock.
- Foodservice brands:Quick-service restaurant chains across France and Italy are replacing polypropylene cutlery with PLA and bagasse alternatives to preempt single-use plastic bans.
- Cellulose fiber molding:Wet-lignin processes are scaling for protective packaging applications, displacing expanded polystyrene in consumer electronics shipments.
Market Restraints
- Recycled PET flake supply concentration:Collection infrastructure bottlenecks in Southern Europe limit feedstock availability for bottle-to-bottle applications.
- Industrial composting facility gaps:Only 42% of European municipalities operate aerobic digestion capacity compatible with EN 13432-certified materials.
- REACH authorization delays:Persistent chemical restrictions on food-contact additives are extending reformulation timelines by 18-24 months.
Strategic Opportunities
- Poland and Czech Republic manufacturing:Central European converters can capture overflow demand as Western European capacity saturates.
- Reusable packaging-as-a-service:Pooling systems for B2B logistics are emerging in the Benelux corridor, enabled by RFID track-and-trace infrastructure.
- CSRD disclosure mandates:Scope 3 emissions reporting requirements are pushing FMCG brands toward verified low-carbon packaging certificates.
Industry Challenges
- Compostability certification backlogs:TÜV Austria and DIN CERTCO testing queues now exceed eight months, delaying product launches.
- Legacy heat-sealing equipment incompatibility:Bio-based films require modified jaw temperatures and dwell times, necessitating line reconfiguration investments.
- Cross-contamination in municipal sorting:Biodegradable plastics entering conventional PET streams degrade recycling yields, triggering quality penalties from offtakers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Packaging Market |
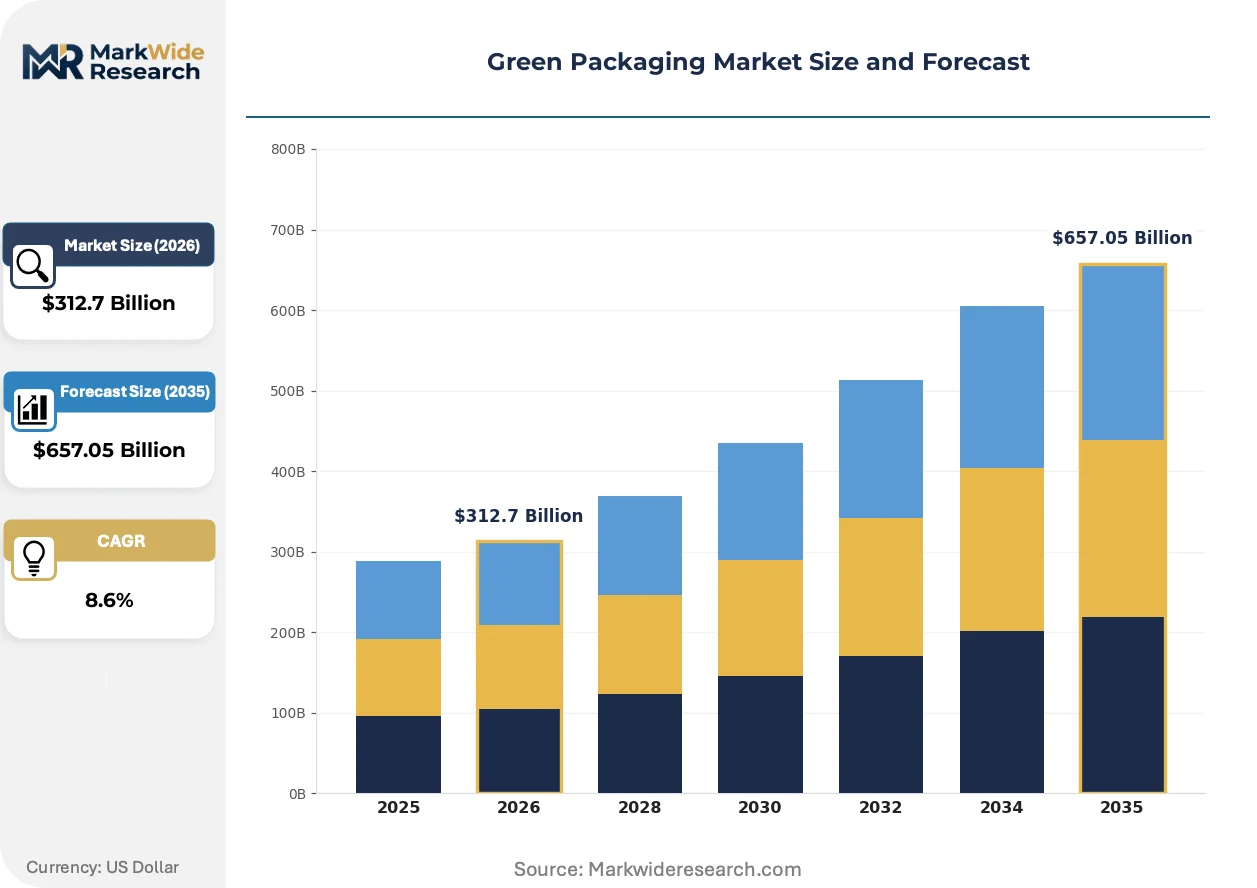
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $657.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable, Biodegradable, Compostable, Recyclable Material: Paper, Plant-based Plastics, Glass, Metal Application: Food & Beverage, Personal Care, Electronics, Pharmaceuticals End User: Retailers, Manufacturers, Wholesalers, Distributors |
| Companies Covered | Amcor plc, Mondi Group, DS Smith, Sealed Air Corporation, Ball Corporation, DuPont, Evergreen Packaging, Tetra Pak International S.A., Ardagh Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Packaging Market Emerging Trajectories
Material science breakthroughs in barrier coatings and fiber engineering are collapsing the performance gap between sustainable formats and incumbent plastics, enabling substitution in oxygen-sensitive applications previously reserved for multilayer films.
Mono-material polyethylene structures with plasma-deposited silicon oxide barrier layers are absorbing volume from aluminum-laminated flexible pouches in snack and coffee packaging. Nestlé and Unilever procurement teams in Switzerland and the Netherlands have accelerated qualification timelines for these formats from 24 months to 14 months. The technology is absorbing margin pressure from EPR fee differentials that now penalize non-recyclable multilayer constructions.
REACH restrictions on per- and polyfluoroalkyl substances in food-contact materials are eliminating grease-resistant fluorochemical coatings from paperboard applications. Danish and Swedish dairy brands are piloting polysaccharide-based oil barriers in butter wrap and ice cream carton applications. The regulation is compressing the addressable market for conventional barrier chemistries while expanding certified compostable alternatives in chilled dairy.
Retailers in Germany and France are consolidating private-label packaging specifications around three standardized format families to simplify reverse logistics and bale sorting. Aldi Nord and Carrefour have eliminated 40% of their historical SKU count in dry grocery flexible packaging since 2023. This concentration is forcing mid-tier converters to absorb tooling costs for format standardization or exit the supplier roster entirely.
Green Packaging Market Segmentation
Segmentation in green packaging reveals how procurement priorities diverge across material certifications, application requirements, and supply chain positions. Understanding these divides exposes where margin compression concentrates and where technical differentiation commands pricing power.
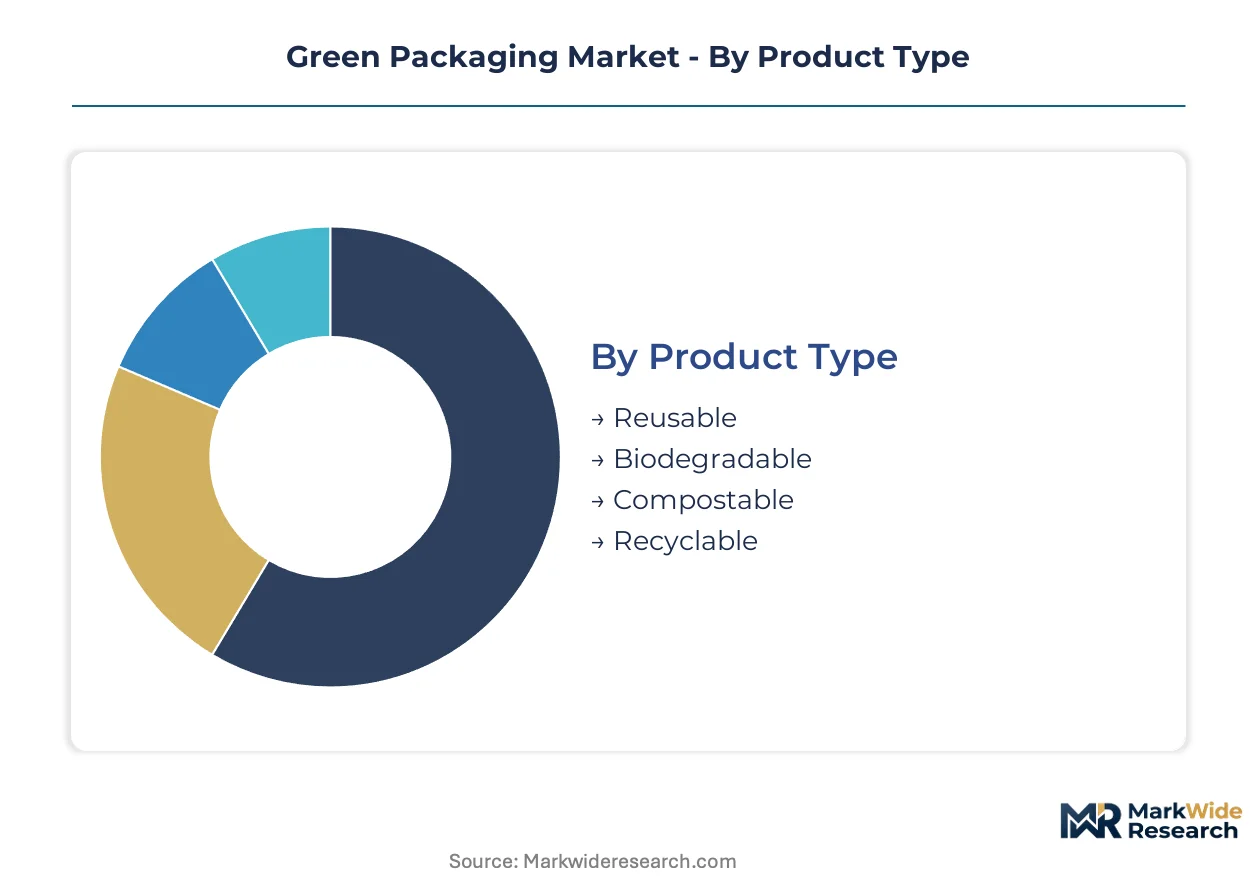
Product Type:
Standardization dominates reusable and recyclable formats with established certification schemes, while biodegradable and compostable variants demand customized testing protocols and regional infrastructure alignment.
- Reusable:Pooling systems and returnable transport items engineered for 50+ use cycles. German beverage retailers and Dutch e-commerce platforms anchor procurement volume, driven by EPR fee avoidance and CSRD Scope 3 reporting requirements.
- Biodegradable:Materials meeting EN 13432 or ASTM D6400 degradation thresholds in industrial or home composting conditions. French quick-service restaurant chains and Italian grocery retailers absorb capacity as single-use plastic bans tighten compliance windows.
- Compostable:Certified materials requiring industrial aerobic digestion infrastructure with defined disintegration timelines.
- Recyclable:Mono-material or easily separable constructions compatible with existing municipal sorting streams.
Leading the category by volume: Recyclable. Growing fastest: Compostable.
Material:
Cost tiers separate fiber-based substrates with mature recycling infrastructure from emerging plant-based polymers carrying feedstock and processing premiums.
- Paper:Kraft, molded fiber, and corrugated formats with post-consumer recycled content thresholds. German retail chains and Swedish e-commerce platforms mandate minimum recycled percentages in private-label specifications.
- Plant-based Plastics:PLA, PHA, and starch-blend polymers derived from corn, sugarcane, or agricultural residues. Danish dairy brands and Dutch foodservice distributors pilot these in chilled applications where barrier performance gaps are narrowing.
- Glass:Infinite-loop recyclable containers with refill system integration in personal care and premium beverage segments.
- Metal:Aluminum and steel formats with established scrap recovery economics in aerosol and rigid container applications.
Paper commands the largest installed capacity. Plant-based plastics scale most aggressively where composting infrastructure expands.
Application:
Application maturity varies sharply: food and beverage carries decades of regulatory precedent, while pharmaceutical sustainability specifications remain under EMA guideline development.
- Food & Beverage:Oxygen-sensitive and moisture-barrier requirements in fresh, chilled, and ambient shelf-stable categories. REACH restrictions on fluorochemical barriers and EU Green Deal recycled content mandates reshape material selection across German, French, and Italian supply chains.
- Personal Care:Refill systems and concentrated formats reducing primary packaging mass. Swiss and Dutch brands lead qualification of glass and aluminum reuse platforms for premium positioning.
- Electronics:Protective structures displacing expanded polystyrene in device shipments.
- Pharmaceuticals:Blister packs, vials, and secondary packaging navigating EMA sustainability guidance while maintaining child-resistance and barrier integrity.
Food and beverage generates the highest absolute demand. Personal care exhibits the steepest shift toward circular service models.
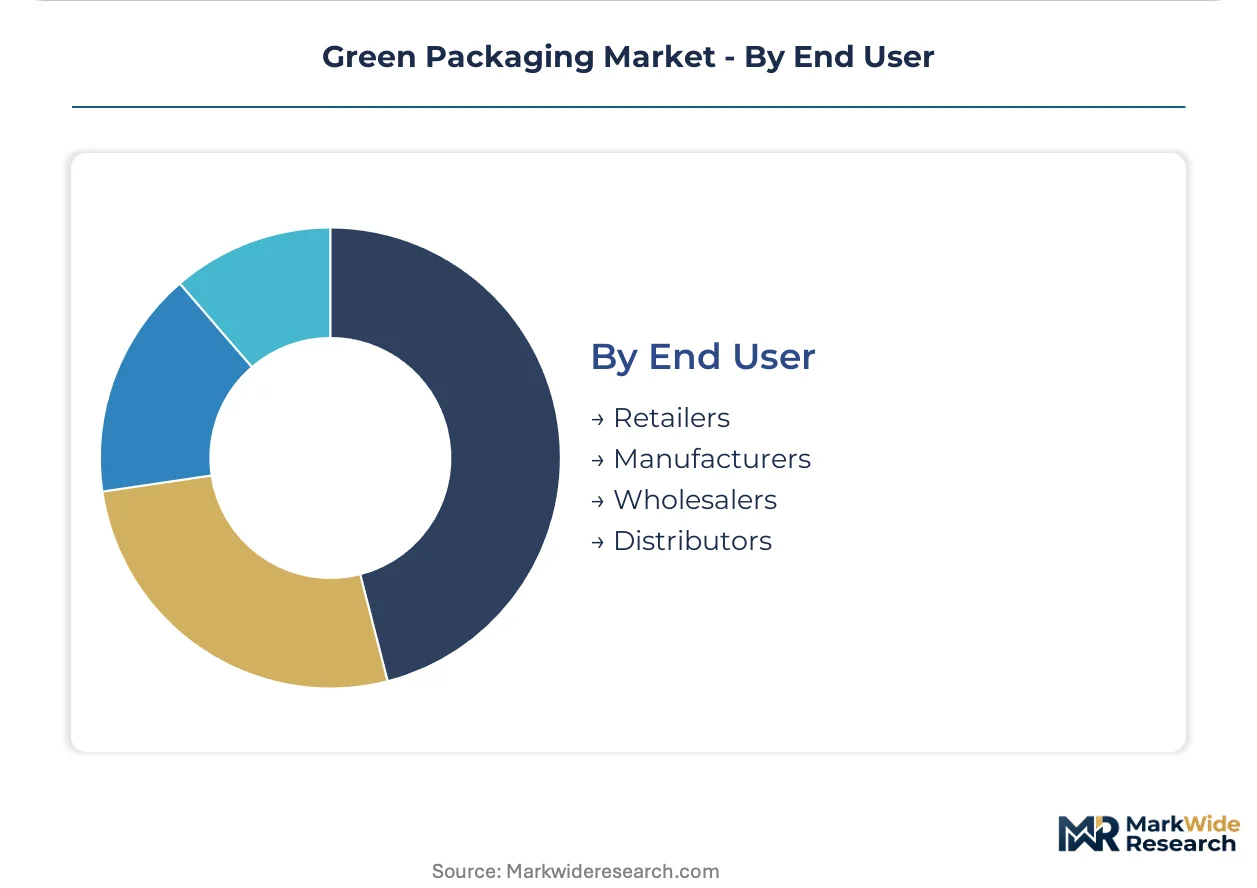
End User:
Customer type determines specification authority: retailers dictate format standards, while manufacturers balance compliance cost against brand differentiation.
- Retailers:Supermarket chains and e-commerce platforms with private-label packaging mandates and reverse logistics control. Aldi Nord and Carrefour consolidation of format families forces converter tooling investments or supplier exit.
- Manufacturers:Consumer goods brands with direct procurement of primary and secondary packaging. Nestlé and Unilever accelerated qualification timelines for mono-material flexible formats from 24 months to 14 months.
- Wholesalers:Intermediate distributors with limited specification influence but volume aggregation power in fragmented markets.
- Distributors:Logistics service providers specifying transport packaging and void-fill for B2B shipment protection.
Retailers exercise the tightest specification control. Manufacturers represent the fastest-growing procurement autonomy as brands internalize circularity targets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European green packaging capacity, with converter clusters in Düsseldorf and Cologne supplying certified mono-material films to German retail chains under EU Green Deal mandates.
Germany
Aldi Nord and Carrefour procurement teams mandate minimum recycled content thresholds in private-label flexible packaging. REACH restrictions on fluorochemical barriers in food-contact materials accelerate reformulation toward polysaccharide-based oil barriers. The Baden-Württemberg converter belt around Stuttgart retools extrusion lines for bio-based films compatible with industrial composting infrastructure.
France
Quick-service restaurant chains across Paris and Lyon replace polypropylene cutlery with PLA and bagasse alternatives ahead of single-use plastic bans. The EU Green Deal packaging compliance thresholds pull film converters toward certified post-consumer feedstock. The Grand Est region hosts expanding industrial composting facilities serving cross-border demand from Benelux markets.
Italy
Grocery retailers in Milan and Rome absorb compostable packaging capacity as municipal sorting infrastructure upgrades. EMA guidelines on pharmaceutical packaging sustainability redirect R&D spending toward verified low-impact alternatives for blister packs. The Emilia-Romagna packaging district scales cellulose fiber molding for protective applications displacing expanded polystyrene.
Netherlands
Dutch e-commerce platforms and foodservice distributors pilot reusable packaging-as-a-service pooling systems enabled by RFID track-and-trace infrastructure. CSRD disclosure mandates push FMCG brands toward verified low-carbon packaging certificates. The Rotterdam port cluster handles growing volumes of bio-based polymer feedstocks from South American sugarcane sources.
Poland
Central European converters capture overflow demand as Western European capacity saturates, with Warsaw and Łódź emerging as cost-competitive extrusion hubs. Extended Producer Responsibility fee structures in neighboring markets create margin advantages for Polish-based suppliers. The Silesian industrial zone attracts tooling investments from mid-tier converters facing format standardization pressures.
Green Packaging Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification complexity and barrier performance tiers. The vendor base organizes around integrated fiber-film platforms, kraft-paper specialists, and closed-loop carton recyclers. Three archetypes dominate: multinational converters with vertical control over raw material sourcing, regional specialists in certified compostable formats, and circular-economy platform operators managing reverse logistics. Competitive moves concentrate on M&A for bio-based polymer capacity and strategic partnerships with industrial composting operators.
Among integrated packaging conglomerates, Amcor plc and Mondi Group exemplify scale-driven archetypes with multi-material platform coverage. DS Smith occupies a position within the circular-economy specialist tier, anchoring closed-loop recycling partnerships with major grocery retailers. Sealed Air Corporation represents the protective packaging vector, while Ball Corporation sits within the metal container circularity segment. Tetra Pak International S.A. exemplifies the aseptic carton system archetype with established fiber-based barrier expertise.
| Leading Market Players |
|---|
| Amcor plc |
| Mondi Group |
| DS Smith |
| Sealed Air Corporation |
| Ball Corporation |
| DuPont |
| Evergreen Packaging |
| Tetra Pak International S.A. |
| Ardagh Group |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between EN 13432 compostable formats and conventional recyclable substrates drives divergent margin structures across European converter tiers, with premium-certificate holders capturing pricing power in Germany and France while commodity-grade suppliers absorb EPR fee compression in Poland and Czech Republic.
Pricing Analysis
Value-based pricing anchored to end-of-life certification throughput dominates the European green packaging market. Three-tier pricing structure across premium compostable, standard recyclable, and economy conventional levels separates certified bio-based films from post-consumer recycled content and virgin alternatives. Pricing pressure stems from Extended Producer Responsibility fee escalations in Germany and France that penalize non-recyclable multilayer constructions. Quick-service restaurant chains and private-label retail buyers exhibit highest price sensitivity, while pharmaceutical and premium personal care brands demonstrate lowest sensitivity due to CSRD disclosure requirements.
Supply Chain Analysis
Regional distribution centers in Düsseldorf, Rotterdam, and Warsaw anchor hub-and-spoke patterns for bio-based polymer feedstocks and finished packaging formats. Geographic supply concentrates in Germany, Poland, and the Netherlands, with raw material dependencies on South American sugarcane-derived PLA, Nordic kraft pulp, and post-consumer PET flake from Western European collection infrastructure. Single-source vulnerability in industrial composting facility access creates supply chain risk for certified compostable formats. Distribution runs through converter-direct relationships with major retail chains and pooled logistics platforms for reusable packaging-as-a-service models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The green packaging market sits in a material-transition phase where mono-material polyethylene structures with plasma-deposited silicon oxide barriers displace aluminum-laminated flexible pouches in oxygen-sensitive applications.
For Market Incumbents: Anchor market position through backward integration into bio-based polymer feedstocks and captive certification testing capacity. Invest in closed-loop carton recycling partnerships with Aldi Nord and Carrefour to defend against format standardization pressures. Prioritize retooling extrusion lines for industrial composting-compatible films ahead of anticipated EPR fee escalations in France and Italy. For New Entrants and Emerging Players: Launch via reusable packaging-as-a-service pooling systems enabled by RFID track-and-trace infrastructure in the Benelux corridor. Target pharmaceutical blister pack applications navigating EMA sustainability guidance as the most penetrable segment. Pursue white-label manufacturing partnerships with Central European converters facing capacity overflow from Western European saturation. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated fiber-film conglomerates seeking bio-based polymer capacity. Long-term viability favors certified compostable specialists with established TÜV Austria or DIN CERTCO credentials and industrial composting operator partnerships. Watch compostability certification queue lengths as the signal to watch for margin compression inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | Captive PLA and PHA supply from South American sugarcane secures margin control against commodity resin volatility. |
| Industrial Composting Infrastructure Partnership | Strategic alliances with Grand Est and Northern European digestion facilities lock in end-of-life pathway certification. |
| Mono-material Flexible Format Qualification | Accelerated 14-month approval timelines with Nestlé and Unilever procurement teams displace multilayer incumbent suppliers. |
| Reusable Packaging-as-a-Service Launch | RFID-enabled pooling systems for Dutch e-commerce platforms capture CSRD-driven Scope 3 reporting demand. |
| Format Standardization Compliance Investment | Tooling alignment with Aldi Nord and Carrefour consolidated SKU families prevents supplier roster exit. |
Methodological Framework
Independent corroboration across converter plant managers, retail category buyers, regulatory affairs leads at certification bodies, and industrial composting facility operators underwrites the qualitative findings in this study. Primary interviews with procurement teams at German and French retail chains combined with secondary validation from EU Green Deal implementation reports, ECHA REACH restriction updates, and customs trade data for bio-based polymer imports. Bottom-up capacity assessments at Düsseldorf and Warsaw extrusion hubs triangulate against top-down demand modeling from CSRD disclosure mandates and EPR fee structure announcements.
Rate-of-change decomposition across material substitution trajectories, certification adoption curves, and infrastructure buildout timelines structures the analytical framework over the projection horizon. Segmentation dimensions modeled include product certification tier, substrate material family, application barrier requirements, end-user specification authority, and regional regulatory cluster. CAGRs derive from installed capacity expansion announcements, pilot program scaling timelines, and policy implementation schedules. Industry-specific forecast inputs incorporate industrial composting facility commissioning rates and REACH authorization delay backlogs for food-contact additive reformulations.
Policy implementation delays, certification testing queue extensions, and feedstock supply disruptions from agricultural commodity volatility are the dominant revision risks to the forecast outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
United States Green Packaging Market
Sustainable Packaging
Europe Green Packaging Market
Sustainable Packaging
PVC-Free Packaging Market
Sustainable Packaging
Areca Plates Market
Sustainable Packaging
Plant Based Packaging Market
Sustainable Packaging
Bagasse Bowls Market
Sustainable Packaging
Sustainable Packaging Market
Sustainable Packaging
Global Paper Straw Market
Sustainable Packaging
Global Disappearing Packaging Market
Sustainable Packaging
Wheat Straw Cutlery Market
Sustainable Packaging
Eco-Friendly Straw Market
Sustainable Packaging
Sustainable Plastic Packaging Market
Sustainable Packaging
Middle East and Africa Eco-Friendly Packaging Market
Sustainable Packaging
Europe Sustainable Packaging Market
Sustainable Packaging
Sustainable Foodservice Packaging Market
Sustainable Packaging
Eco Friendly Bottles Market