
 Eco-Friendly Paper Plates Market | 2026-2036
Eco-Friendly Paper Plates Market Size, Share, and Industry Trends Forecast 2026-2036
Eco-Friendly Paper Plates Market Foresight
Modular bundling of plates with cutlery and napkins into single-SKU event packs is rebalancing buyer choice toward convenience-oriented SKUs. Huhtamaki leverages its molded fiber manufacturing scale to dominate foodservice contract channels. Pactiv sustains backward integration into recycled pulp sourcing, insulating margin pressure from fiber cost swings. Novolex Holdings competes through geographic density, operating distribution centers within two-day reach of most US metropolitan caterers.
Eco-friendly paper plates are single-use foodservice items manufactured from unbleached or chlorine-free pulp, plant-based coatings, or post-consumer recycled fiber, engineered to withstand hot and cold food contact without synthetic plastic liners. The category serves commercial foodservice, institutional catering, and household consumption where disposal infrastructure supports composting or landfill biodegradation. Sugarcane bagasse configurations lead volume due to structural rigidity and microwave tolerance, while bamboo variants occupy premium positioning through faster renewability credentials. Compostable SKUs certified to ASTM D6400 or EN 13432 standards command higher unit margins but face constrained supply from limited industrial composting facility access. Online retail channels for household and small-event buyers are expanding fastest, though wholesale direct sales to national restaurant chains still capture the largest revenue pool.
US EPA landfill diversion targets and state-level single-use plastic restrictions in California, New York, and Washington are reshaping product specifications toward certified compostable substrates. The EU Packaging and Packaging Waste Regulation alongside France's AGEC anti-waste law mandates recyclability or compostability labeling, forcing importers to reformulate coatings and verify fiber provenance. China's GB standards for food contact paper and its dual carbon goals are pressuring domestic mills to shift bleaching chemistry and energy sourcing. Stakeholders must monitor composting infrastructure buildout rates against certification requirement timelines, as geographic mismatches between product claims and actual decomposition pathways create regulatory exposure and consumer litigation risk.
Market Dynamics
Municipal organic waste bans across California, New York, and Washington are forcing quick-service restaurants to replace polyethylene-lined disposables with certified compostable alternatives, compressing specification timelines and rewiring procurement criteria toward ASTM D6400 and EN 13432 certification.
Growth Catalysts
- Extended Producer Responsibility Laws:France's AGEC anti-waste law and California's SB 54 impose fees on conventional plastic disposables, redirecting foodservice procurement toward bagasse and bamboo fiber substrates.
- Industrial Composting Buildout:Germany and the Netherlands are expanding anaerobic digestion capacity, creating viable end-of-life pathways for certified compostable SKUs that were previously landfilled.
- Quick-Service Restaurant Chains:North American fast-casual operators are mandating compostable tableware across franchise networks, aggregating demand sufficient to justify dedicated molded fiber production lines.
Market Restraints
- Pulp Cost Volatility:Recycled fiber and bagasse prices fluctuate with agricultural yields and packaging demand cycles, compressing margins for non-integrated converters.
- Coating Supply Concentration:PLA and PBS barrier coatings rely on a limited base of fermentation-derived resin suppliers concentrated in Thailand and Nebraska.
- Composting Infrastructure Mismatch:Industrial composting facilities accessible to foodservice operators remain sparse in Texas, Florida, and most of the US Southeast, invalidating product claims in those markets.
Strategic Opportunities
- Household Online Retail:E-commerce channels for small-event and household buyers remain underdeveloped relative to foodservice, offering margin expansion through direct-to-consumer bundling.
- Microwave-Tolerant Bamboo Variants:Premium positioning of rapidly renewable bamboo fiber is converging with consumer willingness to pay for performance parity with plastic foam.
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability labeling creates first-mover advantage for importers with pre-verified fiber provenance and coating formulations.
Industry Challenges
- Certification Timeline Compression:ASTM D6400 and EN 13432 testing cycles lag product development schedules, delaying market entry for reformulated coatings.
- Coating Equipment Retooling:Shifting from polyethylene extrusion to aqueous barrier application requires capital investment in drying and curing infrastructure that many mid-scale converters lack.
- Composting Standard Fragmentation:Divergent state-level definitions of "compostable" create compliance complexity for national distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eco-Friendly Paper Plates Market |
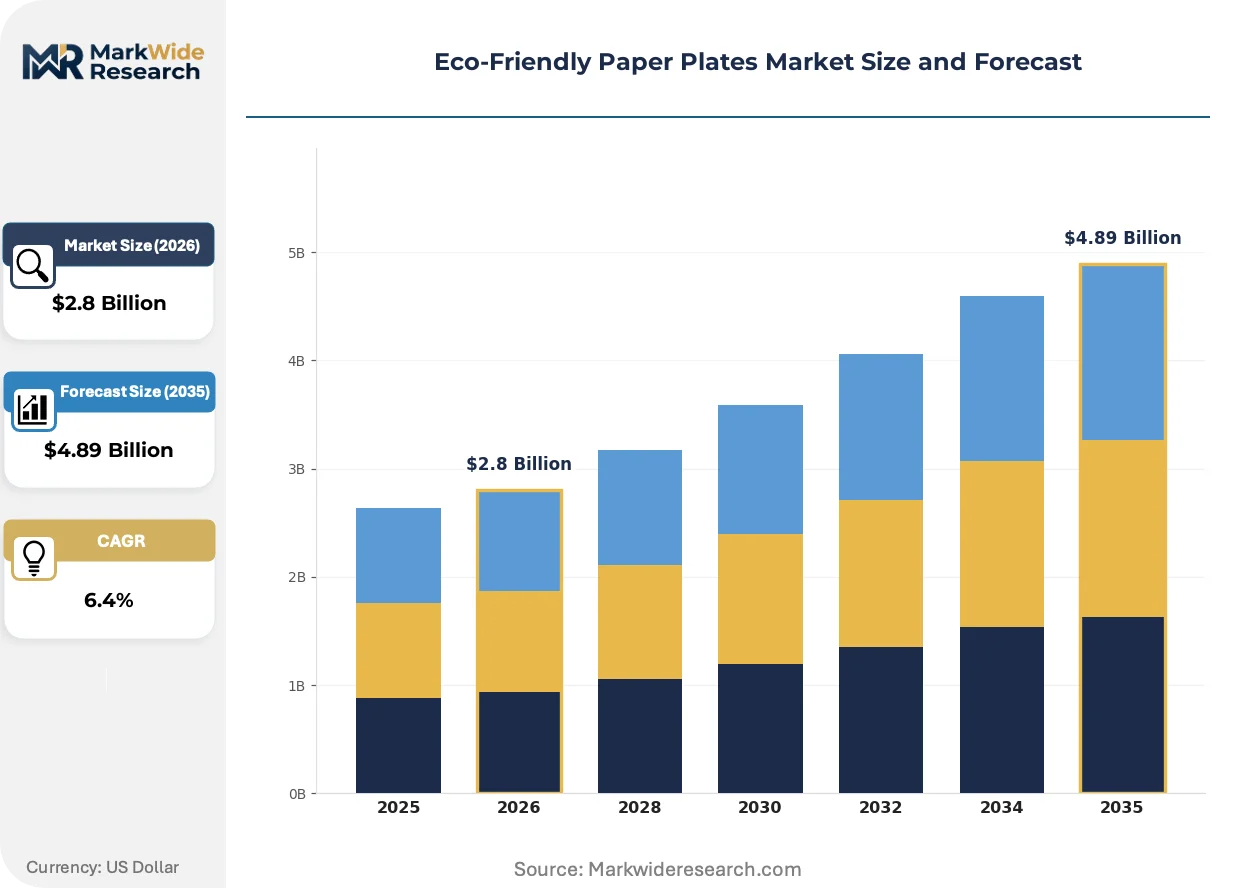
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compostable, Biodegradable, Sugarcane, Bamboo End User: Restaurants, Caterers, Households, Events Distribution Channel: Online Retail, Supermarkets, Wholesale, Direct Sales Material: Pulp, Paperboard, Plant-Based Coatings, Recycled Fiber |
| Companies Covered | Pactiv, Novolex Holdings, Huhtamaki, Genpak, Clearwater Paper Corporation, Graphic Packaging, Duni, You Cheng, Dart Container, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eco-Friendly Paper Plates Market Shifts & Advancements
Barrier coating chemistry and fiber sourcing protocols are undergoing simultaneous transformation as buyers demand performance parity with plastic while regulators close disposal loopholes. These shifts are compressing product development cycles and redrawing supplier qualifications.
Aqueous plant-based barrier coatings derived from alginate and chitosan are converging with traditional molded fiber forming to eliminate synthetic liners while maintaining grease resistance. Quick-service chains in California and Washington are piloting these formulations at scale. The technology is converging with existing production infrastructure to reduce capital barriers for mid-tier converters.
The EU Packaging and Packaging Waste Regulation mandates recyclability or compostability labeling by 2030, forcing Asian exporters to reformulate coatings and document fiber provenance. Importers face testing costs and timeline risks. Foodservice contract channels are most affected, with buyers now requiring pre-submitted certification packets before vendor qualification.
Event-pack bundling of plates with cutlery and napkins into single-SKU offerings is displacing à-la-carte purchasing for household and small-catering buyers. Amazon and specialty e-commerce platforms are capturing this shift. The pattern is most visible in California and Germany, where convenience-oriented buyers prioritize simplified disposal over unit cost optimization.
Eco-Friendly Paper Plates Market Segmentation
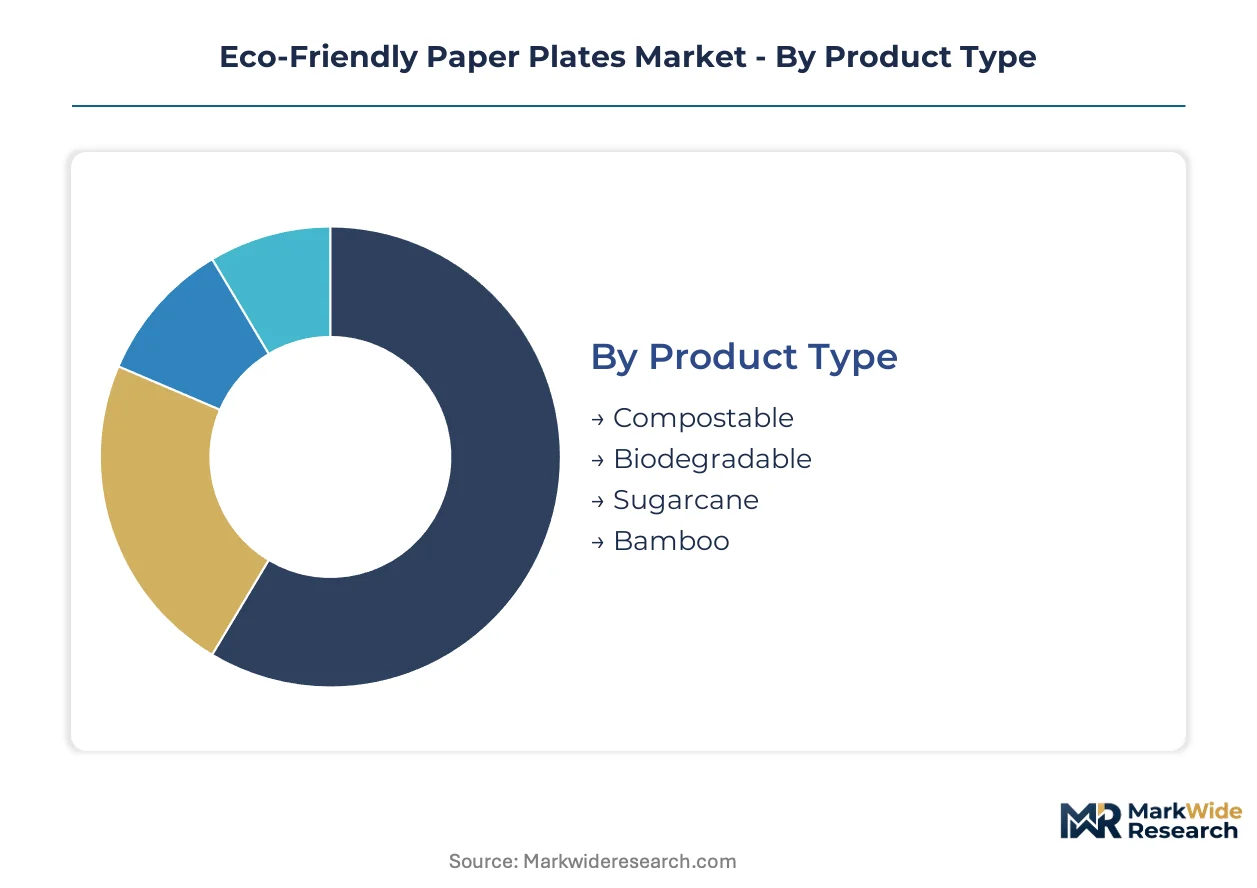
Segmentation in eco-friendly paper plates reveals divergent performance requirements across foodservice and household channels. Material composition and certification status determine pricing power and regulatory compliance, while distribution economics reshape competitive access.
Product Type:
Integration depth varies sharply: compostable SKUs function as standalone certified products for regulated foodservice channels, while biodegradable variants embed in less stringent disposal environments.
- Compostable:ASTM D6400 and EN 13432 certified configurations command premium positioning through verified industrial composting pathways. Quick-service restaurant chains in California and Washington mandate these specifications for franchise compliance.
- Sugarcane:Bagasse-derived plates deliver structural rigidity and microwave tolerance through high-pressure molded fiber forming. North American fast-casual operators aggregate procurement volumes sufficient to justify dedicated production lines.
- Biodegradable:Uncertified variants rely on landfill biodegradation claims without standardized testing protocols.
- Bamboo:Rapidly renewable fiber sources support premium household positioning through faster harvest cycles.
Volume placements concentrate in sugarcane; the faster expansion belongs to compostable.
End User:
Cost tier stratification separates contract-scale foodservice procurement from fragmented household purchasing.
- Restaurants:National quick-service chains leverage centralized procurement to extract volume pricing on certified compostable SKUs. Municipal organic waste bans in California, New York, and Washington compress specification timelines toward ASTM D6400 compliance.
- Caterers:Event-service operators demand performance parity with plastic foam under thermal stress. Geographic density of industrial composting facilities determines product claim validity in Texas and Florida markets.
- Households:Small-quantity buyers prioritize convenience-oriented event packs over unit cost optimization.
- Events:Single-use volume spikes concentrate in seasonal and institutional procurement cycles.
Revenue gravity centers on restaurants; households are climbing the fastest.
Distribution Channel:
Application context dictates channel selection: foodservice contracts flow through direct sales, while household replenishment shifts online.
- Wholesale:National restaurant chains capture largest revenue pool through direct manufacturer relationships. Two-day distribution center proximity determines contract win rates.
- Direct Sales:Molded fiber manufacturers qualify vendors through pre-submitted certification packets before contract negotiation.
- Online Retail:Amazon and specialty platforms expand fastest for small-event and household buyers through modular bundling strategies.
- Supermarkets:Mass retail placement supports brand awareness but carries higher slotting cost burdens.
Wholesale direct sales anchor volume; online retail gains share fastest.
Material:
Supply concentration in coating chemistry and fiber sourcing determines margin stability across converter tiers.
- Pulp:Unbleached and chlorine-free virgin fiber provides baseline grease resistance for cold food applications. Finland and China suppliers dominate plant-based coating technology development.
- Plant-Based Coatings:Alginate and chitosan aqueous barriers eliminate synthetic liners while maintaining performance parity. California quick-service chains pilot these formulations at production scale.
- Paperboard:Structural substrates support rigidity requirements for heavy food loads.
- Recycled Fiber:Post-consumer content satisfies extended producer responsibility mandates in France and Germany.
Pulp maintains volume dominance; plant-based coatings show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finland and China dominate plant-based coating technology development, while consumption concentrates in jurisdictions with stringent organic waste regulations. The production-consumption divide forces importers to navigate divergent certification timelines across major markets.
United States
California, New York, and Washington drive procurement shifts through municipal organic waste bans and SB 54 extended producer responsibility fees. EPA landfill diversion targets compress specification timelines toward ASTM D6400 certification. Quick-service restaurant chains in Los Angeles and Seattle metro areas now mandate compostable tableware across franchise networks.
Germany
Industrial composting buildout in Bavaria and North Rhine-Westphalia creates viable end-of-life pathways for certified SKUs. The EU Packaging and Packaging Waste Regulation mandates recyclability labeling by 2030, forcing coating reformulation. Berlin-based caterers aggregate demand sufficient to justify dedicated molded fiber production lines.
China
GB standards for food contact paper and dual carbon goals pressure domestic mills to shift bleaching chemistry. Zhejiang and Guangdong provinces concentrate aqueous barrier coating pilot programs. Shanghai quick-service operators test alginate-derived formulations at production scale.
France
The AGEC anti-waste law imposes fees on conventional plastic disposables, redirecting foodservice procurement toward bagasse substrates. Île-de-France caterers demand pre-submitted certification packets before vendor qualification. Lyon and Marseille event-service operators prioritize convenience-oriented modular bundling.
Japan
METI guidelines on sustainable packaging accelerate industrial composting facility investment around Tokyo and Osaka. Extended producer responsibility frameworks penalize conventional plastic disposables in Kanto and Kansai regions. Convenience store chains pilot microwave-tolerant bamboo variants for premium household positioning.
Eco-Friendly Paper Plates Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across contract foodservice and household retail channels. The vendor base organizes around manufacturing scale, geographic density, and backward integration into fiber sourcing. Three archetypes dominate: molded fiber specialists with captive pulp supply, distribution-heavy converters optimizing two-day metropolitan reach, and coating technology licensors. Capacity expansion and certification pre-qualification constitute the primary competitive moves.
Among scale-driven molded fiber manufacturers, Huhtamaki anchors the foodservice contract channel through manufacturing breadth. Pactiv exemplifies backward integration strategy, controlling recycled pulp sourcing to insulate margin pressure. Novolex Holdings occupies the geographic density archetype, positioning distribution infrastructure within rapid reach of major metropolitan caterers. These three represent divergent responses to fiber cost volatility and coating supply concentration.
| Leading Market Players |
|---|
| Pactiv |
| Novolex Holdings |
| Huhtamaki |
| Genpak |
| Clearwater Paper Corporation |
| Graphic Packaging |
| Duni |
| You Cheng |
| Dart Container |
| Others |
Supply & Pricing Matrix
Backward integration into recycled pulp sourcing anchors both supply security and margin stability for converters facing agricultural fiber price swings. Pactiv's captive supply of post-consumer fiber insulates production costs from bagasse yield volatility, while non-integrated competitors absorb margin compression through spot market exposure.
Pricing Analysis
Cost-down pressure on standard-grade SKUs accelerates because municipal organic waste bans are compressing specification timelines toward ASTM D6400 certification. Three-tier pricing structure across certified compostable, microwave-tolerant sugarcane, and uncertified biodegradable levels separates foodservice contract buyers from household convenience seekers. Price differentiation rests on certification grade and volume scale, with national quick-service chains extracting double-digit discounts through centralized procurement. Household buyers show lowest price sensitivity, prioritizing event-pack convenience over unit economics.
Supply Chain Analysis
Barrier coating chemistry rests on fermentation-derived resin suppliers concentrated in Thailand and Nebraska. Raw material flows draw from bagasse processors in India and China, recycled pulp mills in the US Southeast, and bamboo fiber cultivators in Vietnam. Single-source vulnerability in PLA and PBS coating supply creates procurement risk for mid-scale converters lacking long-term offtake agreements. Distribution runs through wholesale direct sales to national restaurant chains, with two-day metropolitan reach determining contract win rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial composting facility buildout lags certification mandates, creating a capacity bottleneck that props pricing for verified SKUs in compliant jurisdictions.
For Market Incumbents: Lock in coating supply through long-term resin offtake agreements with Thai and Nebraska fermentation producers before capacity constraints tighten. Expand molded fiber production lines in California and Washington to capture quick-service contract volume as SB 54 fees redirect procurement toward certified substrates. Defend margin position by accelerating aqueous barrier pilot programs ahead of mid-tier converter retooling cycles. For New Entrants and Emerging Players: Capture household online retail white space through modular event-pack bundling strategies on Amazon and specialty platforms. Target Texas and Florida caterers facing composting infrastructure mismatch, offering biodegradable variants with landfill biodegradation claims where industrial facilities remain sparse. Penetrate through direct-to-consumer subscription models for seasonal event buyers prioritizing convenience over certification. For Investors and Strategic Acquirers: Exit pathways concentrate in coating technology licensors with aqueous barrier patents and pre-qualified fiber provenance documentation. Long-term viability favors converters with backward integration into pulp sourcing and geographic density within two-day reach of major metropolitan foodservice clusters. Watch industrial composting facility permitting velocity in Texas and Florida as the inflection signal for product claim validity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Pulp | Pactiv's captive fiber supply insulates margins from agricultural yield volatility. |
| Aqueous Barrier Coating Scale-Up | Alginate-derived formulations eliminate synthetic liners for California quick-service pilots. |
| Geographic Distribution Density | Novolex positions centers within two-day reach of US metropolitan caterers. |
| Certification Pre-Qualification | ASTM D6400 packets accelerate vendor approval for national restaurant chains. |
| Modular Event-Pack Bundling | Amazon channels capture household buyers prioritizing convenience over unit cost. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with foodservice procurement directors, molded fiber plant managers, coating technology R&D leads, and municipal waste compliance officers combined with secondary validation from EPA diversion reports, FDA food contact submissions, and EU Packaging and Packaging Waste Regulation draft texts. Bottom-up volume modeling and top-down value reconciliation triangulated market sizing across the analysis window.
Data-stream reconciliation integrated shipment volumes from pulp suppliers, certification database tracking from BPI and TÜV, and foodservice contract award announcements. Segmentation dimensions modeled include material composition, end-user channel, distribution pathway, and geographic regulatory cluster. CAGRs derived from trend extrapolation of historical volume patterns adjusted for policy implementation timelines, with coating technology adoption curves and composting facility buildout rates as industry-specific forecast inputs.
The model holds under steady regulatory enforcement timelines; deviation in industrial composting permitting velocity or resin supply disruption would shift volume trajectories. Forecasts reflect documented assumptions on certification compliance rates and fiber cost normalization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Corrugated Boxes Market
Paper & Paperboard Packaging
Corrugated Shippers Market
Paper & Paperboard Packaging
Latin America Paper Packaging Market
Paper & Paperboard Packaging
Envelope Market
Paper & Paperboard Packaging
Machine Glazed Paper Market
Paper & Paperboard Packaging
Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Asia-Pacific Paper Bags Market
Paper & Paperboard Packaging
GCC Paper Cup Market
Paper & Paperboard Packaging
Pre-Impregnated Paper Market
Paper & Paperboard Packaging
Testliner Market
Paper & Paperboard Packaging
Foam Cups Market
Paper & Paperboard Packaging
Push-Pull Slip Sheets Market
Paper & Paperboard Packaging
Tea Filter Paper Market
Paper & Paperboard Packaging
GCC Paper Packaging Market
Paper & Paperboard Packaging
Morocco Corrugated Board Market
Paper & Paperboard Packaging
North America Paper Cups Market