
 Asia-Pacific Eco-Friendly Packaging Market | 2026-2036
Asia-Pacific Eco-Friendly Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Eco-Friendly Packaging Market Outlook
Bioplastics production capacity across Thailand and Malaysia is expanding as fermentation-based PLA resin output scales to serve regional converters. Amcor plc leverages its integrated film and fiber network to supply multinational food brands with recyclable flexible packaging formats. Huhtamaki Group anchors molded fiber cup and plate manufacturing through facilities in China and India, sustaining regional quick-service restaurant contracts. Mondi plc competes in kraft paper and containerboard segments with operations spanning South Africa into Asia-Pacific markets.
Eco-friendly packaging encompasses materials and designs engineered to minimize environmental impact through biodegradation, recyclability, or renewable sourcing, typically incorporating fiber-based substrates with specified gram weights, barrier coatings derived from plant waxes, and adhesives meeting compostability standards per ASTM D6400 or EN 13432. The primary commercial purpose centers on containing, protecting, and presenting goods while enabling end-of-life recovery through existing recycling streams or industrial composting infrastructure. Recyclable cardboard and paper materials dominate volume flows due to established municipal collection systems and repulp economics, while bioplastics represent the fastest-expanding material category as polylactic acid and polyhydroxyalkanoate production costs decline relative to petroleum-derived alternatives. Food & Beverage end users command the largest share of specification activity, driven by fresh produce exporters and ready-meal processors seeking shelf-life extension without multilayer plastic constructions.
China's SAMR enforces GB standards limiting excessive packaging for cosmetics and food products, while India's BIS certification mandates recyclability labeling under Plastic Waste Management Rules. Japan's METI promotes biomass-based material targets through its Green Growth Strategy, shaping procurement criteria for consumer electronics exporters. Australia's TGA imposes pharmaceutical packaging traceability requirements that favor serialized paperboard over blister formats. Stakeholders must monitor evolving extended producer responsibility fee structures and biomaterial feedstock competition from food security priorities when committing to capacity investments.
Market Dynamics
India's BIS recyclability labeling mandates and China's GB standards on excessive packaging are forcing rapid format redesign across the Asia-Pacific region, compressing development cycles for converters serving multinational food and electronics brands.
Growth Catalysts
- Extended Producer Responsibility frameworks:India's Plastic Waste Management Rules impose fee structures that reward mono-material designs, pushing converters toward fiber-based alternatives with established repulp pathways.
- E-commerce fulfillment specifications:Coastal Chinese provinces including Guangdong and Zhejiang now mandate corrugated substitutes for poly mailers in last-mile logistics, creating guaranteed offtake for containerboard producers.
- Bagasse container adoption:Southeast Asian quick-service restaurant chains specify molded fiber trays and sugarcane-based clamshells for dine-in and takeaway, displacing conventional PS foam across Thailand and Vietnam.
Market Restraints
- PLA resin cost volatility:Fermentation-based polylactic acid production depends on corn starch feedstock prices, which fluctuate with agricultural commodity markets and food security priorities in Thailand and Malaysia.
- Barrier coating performance gaps:Plant wax and alginate-based moisture barriers on molded fiber cups fail to match the shelf-life extension of polyethylene-lined alternatives, limiting penetration in ready-meal exports.
- Industrial composting infrastructure concentration:Certified composting facilities accepting ASTM D6400 materials cluster in Japan and South Korea, leaving much of Southeast Asia without viable end-of-life recovery for bioplastic packaging.
Strategic Opportunities
- Philippines regulatory white space:The absence of federal EPR legislation creates first-mover advantage for converters establishing collection and recycling partnerships before anticipated 2026-2027 policy implementation.
- Pharmaceutical serialization migration:Australia's TGA traceability requirements favor serialized paperboard cartons over blister packs, opening specification opportunities for track-and-trace-enabled fiber packaging in regional pharma exports.
- Marine-degradable film development:Polyhydroxyalkanoate and seaweed-based flexible packaging for fresh seafood exports addresses Japan's METI biomass targets while serving Indonesian and Vietnamese fishing industry logistics.
Industry Challenges
- Compostability certification timeline compression:EN 13432 and ASTM D6400 testing protocols require 180-day industrial composting validation, delaying product launches for converters racing to meet seasonal procurement windows.
- Molded fiber tooling capex intensity:Precision thermoforming dies for complex tray geometries demand seven-figure capital commitments, favoring established players over mid-scale entrants in India's fragmented converter base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Eco-Friendly Packaging Market |
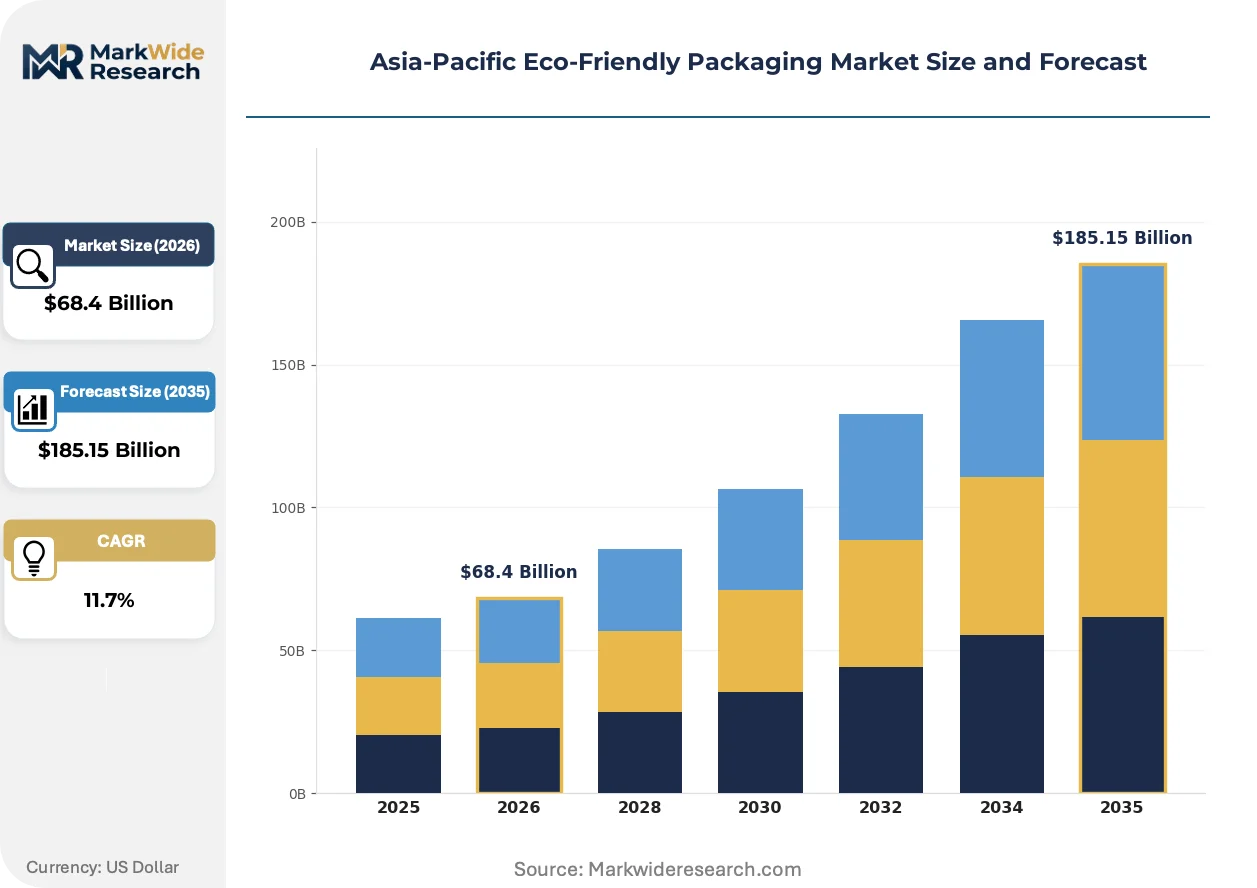
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $185.15 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Biodegradable, Recyclable, Compostable, Plant-Based Material: Cardboard, Paper, Glass, Bioplastics End User: Food & Beverage, Personal Care, Healthcare, Electronics Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | International Paper Company, Huhtamaki Group, Amcor plc, Constantia Flexibles, Sonoco Products Company, Sealed Air Corporation, DS Smith PLC, Graphic Packaging Holding Company, Mondi plc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Eco-Friendly Packaging Market Strategic Shifts
Barrier technology convergence and digital printing integration are compressing the traditional trade-off between shelf-life performance and end-of-life recoverability, enabling specification upgrades in previously plastic-locked applications.
Active and intelligent packaging incorporating oxygen scavengers and freshness indicators is modularizing across premium fresh produce exports from Australia and New Zealand. Japanese supermarket chains now specify time-temperature indicators printed directly on corrugated cases for seafood and dairy logistics. This integration is modularizing quality assurance into the packaging substrate itself, reducing the need for separate monitoring hardware and collapsing supplier tiers in cold chain documentation.
Japan's METI Green Growth Strategy biomass utilization targets are redirecting procurement criteria for consumer electronics exporters toward certified paperboard with minimum renewable content thresholds. South Korean appliance manufacturers now face mandatory disclosure of packaging recyclability rates under amended resource circulation legislation. Electronics OEMs serving these markets are responding by specifying molded pulp cushions and kraft paper wraps in place of expanded polystyrene, with design verification required prior to product registration.
Centralized purchasing by ASEAN quick-service restaurant franchisors is consolidating supplier relationships around converters with multi-country certification coverage. Regional procurement teams now mandate unified packaging specifications across Indonesia, Malaysia, and Thailand outlets, displacing country-specific sourcing arrangements. This concentration is most visible in beverage cup and food container categories, where single-source contracts cover thousands of franchise locations with standardized molded fiber formats and centralized quality auditing.
Asia-Pacific Eco-Friendly Packaging Market Segmentation
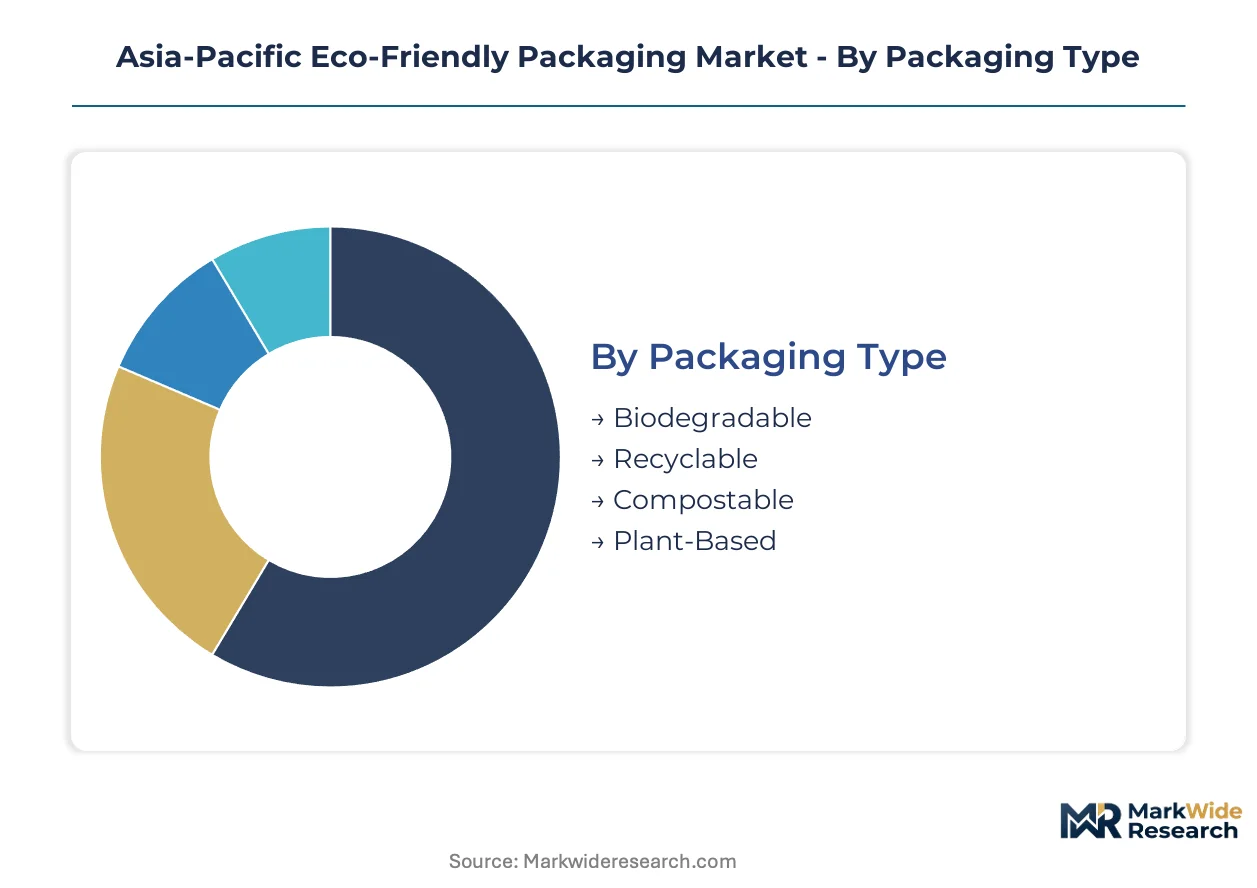
Converters across the Asia-Pacific region must navigate divergent regulatory timelines and end-user specifications. Segmentation reveals where standardization yields scale economies versus where customization commands premium positioning.
Packaging Type:
Standardization dominates biodegradable and recyclable formats where certification harmonization reduces compliance costs, while compostable and plant-based variants require bespoke formulations for specific end-of-life pathways.
- Biodegradable:Materials engineered for microbial decomposition under anaerobic or aerobic conditions, typically starch blends or oxo-degradable additives. Demand concentrates in India's agricultural export sector where BIS labeling mandates accelerate format shifts away from conventional plastics.
- Recyclable:Mono-material constructions compatible with established municipal paper and plastic collection streams, including corrugated cases and PET bottles. China's coastal e-commerce hubs in Guangdong and Zhejiang now specify these formats for last-mile fulfillment, displacing poly mailers through SAMR-guided procurement rules.
- Compostable:ASTM D6400 or EN 13432 certified materials requiring industrial composting infrastructure.
- Plant-Based:Feedstock-derived alternatives including bagasse, bamboo fiber, and agricultural residues.
Most installed capacity flows through Recyclable formats. Expansion is steepest in Compostable as industrial composting infrastructure spreads beyond Japan and South Korea.
Material:
Cost tiers separate commodity fiber from specialty substrates, with bioplastics occupying a volatile middle ground between petroleum price linkage and agricultural feedstock exposure.
- Cardboard:Containerboard and corrugated medium for protective shipping applications. Thailand's quick-service restaurant chains specify molded fiber trays for dine-in service, displacing PS foam through centralized ASEAN procurement.
- Paper:Kraft wraps, flexible pouches, and labels with barrier coatings. Australia's TGA pharmaceutical serialization requirements favor paperboard cartons over blister packs for regional drug exports.
- Glass:Returnable and single-use bottles for beverage and personal care.
- Bioplastics:PLA, PHA, and starch-based resins from Thailand and Malaysian fermentation capacity.
Cardboard commands the largest volume share. Bioplastics are climbing the fastest as polylactic acid production costs decline relative to conventional polymers.
End User:
Application requirements dictate performance specifications, with food safety and shelf-life extension driving the most stringent barrier demands.
- Food & Beverage:Fresh produce exporters and ready-meal processors dominate specification activity. Japanese supermarket chains mandate time-temperature indicators on corrugated cases for seafood logistics, integrating quality assurance directly into packaging substrates.
- Personal Care:China's SAMR GB standards on excessive packaging hit cosmetics brands hardest, forcing format reduction and material substitution.
- Healthcare:Australia's TGA traceability rules and India's CDSCO serialization requirements favor fiber-based formats.
- Electronics:Japan's METI biomass targets and South Korean resource circulation legislation mandate molded pulp cushions replacing expanded polystyrene.
Food & Beverage absorbs the majority of regional capacity. Electronics represents the fastest-growing trajectory as OEMs redesign for circular economy compliance.
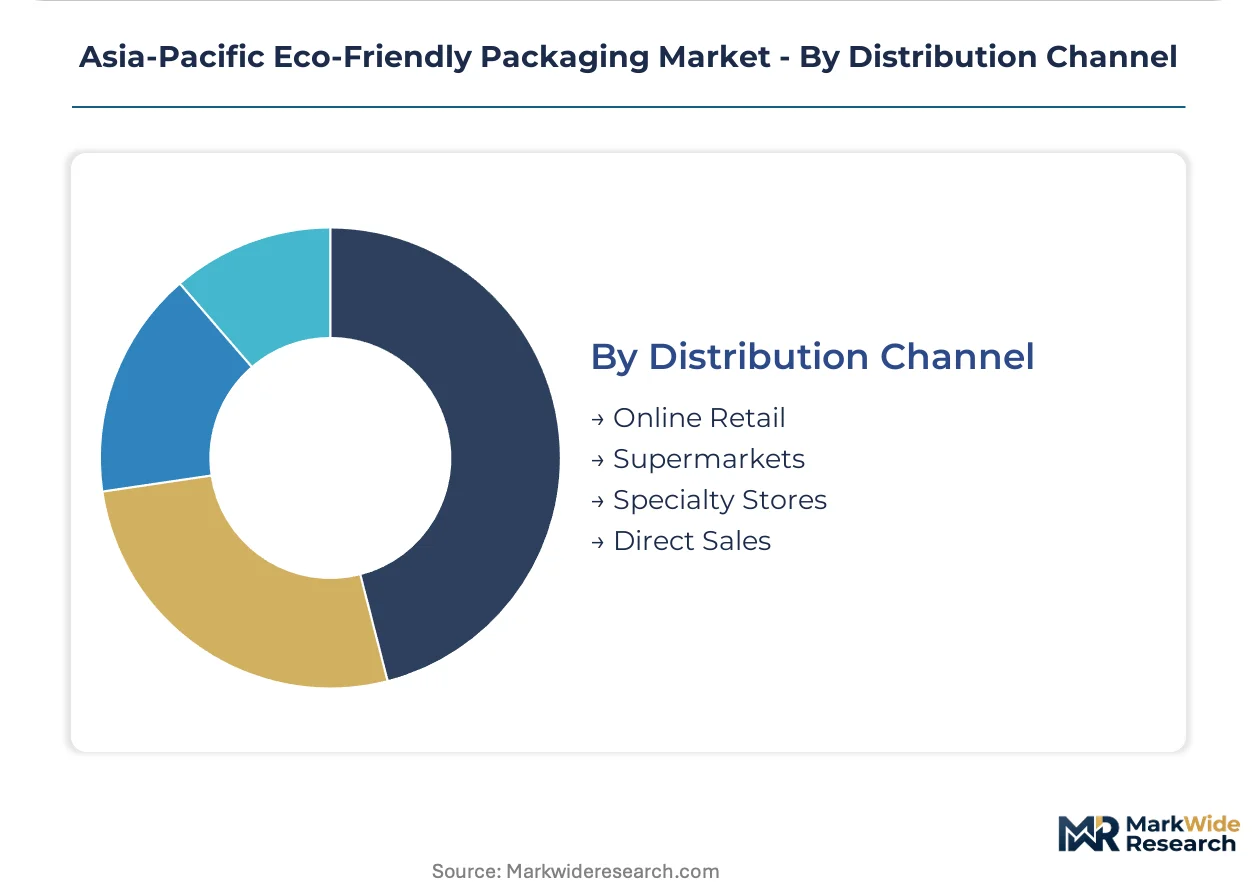
Distribution Channel:
Channel concentration shapes order patterns, with direct sales enabling customization while retail intermediaries demand scale and consistency.
- Online Retail:E-commerce fulfillment drives corrugated demand across China's manufacturing provinces. Alibaba and JD.com logistics specifications now exclude non-recyclable poly mailers for cross-border shipments.
- Supermarkets:Centralized produce and private-label procurement in Japan and Australia favors standardized formats with certified sustainability credentials.
- Specialty Stores:Premium positioning allows higher material costs for distinctive tactile and visual properties.
- Direct Sales:B2B contracts with multinational food and electronics brands enable co-development of proprietary formats.
Supermarkets move the highest volumes. Online Retail is gaining share fastest as e-commerce penetration deepens across Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters are relocating capacity across Asia-Pacific to exploit gaps in extended producer responsibility enforcement, with China's coastal provinces absorbing investment from manufacturers fleeing India's tightening BIS certification timelines.
China
E-commerce fulfillment centers in Guangdong and Zhejiang now mandate corrugated substitutes for poly mailers, displacing plastic-intensive logistics formats. SAMR enforces GB standards limiting excessive packaging for cosmetics and food products, compressing design cycles for multinational brands. The Yangtze River Delta hosts the densest concentration of molded fiber tooling operations serving quick-service restaurant chains.
India
Fresh produce exporters and ready-meal processors dominate specification activity for shelf-life extension without multilayer plastics. BIS recyclability labeling mandates under Plastic Waste Management Rules force rapid format redesign across the converter base. Maharashtra and Gujarat host the primary clusters of bagasse container manufacturing serving domestic quick-service restaurant contracts.
Japan
Supermarket chains specify time-temperature indicators printed directly on corrugated cases for seafood and dairy logistics. METI promotes biomass-based material targets through its Green Growth Strategy, redirecting procurement for consumer electronics exporters. The Kanto region anchors industrial composting infrastructure accepting ASTM D6400 certified materials.
South Korea
Appliance manufacturers face mandatory disclosure of packaging recyclability rates under amended resource circulation legislation. Electronics OEMs specify molded pulp cushions replacing expanded polystyrene prior to product registration. The Seoul Capital Area concentrates demand from chaebol-affiliated electronics brands with centralized sustainability procurement.
Thailand
Quick-service restaurant chains specify molded fiber trays and sugarcane-based clamshells for dine-in and takeaway service. Fermentation-based PLA resin output scales to serve regional converters, though feedstock prices fluctuate with agricultural commodity markets. Bangkok anchors centralized ASEAN procurement teams mandating unified specifications across Indonesia, Malaysia, and Thailand outlets.
Asia-Pacific Eco-Friendly Packaging Market Competitive Environment
Chinese producers anchor the volume tier serving e-commerce logistics specifications; European and Australian specialists hold premium positions in certified compostable formats and pharmaceutical serialization. The vendor base stratifies across three tiers: integrated multinational converters with multi-country certification coverage, regional molded fiber specialists with captive agricultural residue supply, and emerging bioplastic compounders dependent on Thai and Malaysian fermentation capacity. M&A activity concentrates on acquiring industrial composting certification assets, while capacity expansion targets bagasse pulping operations in Vietnam and Indonesia.
Among integrated multinational converters, Amcor plc and Huhtamaki Group occupy positions exemplifying the certification-coverage archetype, with facility networks spanning China and India to sustain regional quick-service restaurant and food brand contracts. Mondi plc represents the fiber-to-packaging integration model, with operations extending from South African pulp sources into Asia-Pacific containerboard markets. These three entities anchor the competitive structure through their ability to offer unified specifications across fragmented national regulatory environments.
| Leading Market Players |
|---|
| International Paper Company |
| Huhtamaki Group |
| Amcor plc |
| Constantia Flexibles |
| Sonoco Products Company |
| Sealed Air Corporation |
| DS Smith PLC |
| Graphic Packaging Holding Company |
| Mondi plc |
| Others |
Value Chain & Pricing Dynamics
China's SAMR GB standards on excessive packaging and India's BIS recyclability mandates gate qualified supply to converters with certified fiber sourcing and barrier-coating capabilities, compressing margins for uncertified competitors while enabling premium-tier pricing for holders of ASTM D6400 and EN 13432 validation.
Pricing Analysis
Retailer markup layers in Japanese and Australian supermarket channels absorb 15-25% of converter pricing, while direct-to-OEM contracts with ASEAN quick-service restaurant franchisors trade volume discounts for multi-country specification lock-in. Three-tier pricing structure across premium certified compostable, standard recyclable fiber, and economy biodegradable tiers tracks certification grade and barrier performance. Cost compression in standard recyclable grades is intensifying because Chinese e-commerce fulfillment specifications favor corrugated over poly mailers. Small-scale Indian converters serving domestic fresh produce exporters exhibit the highest price sensitivity, while multinational food brands with EPR compliance deadlines show inelastic demand for certified formats.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Chinese e-commerce fulfillment centers and ASEAN quick-service restaurant chains, while distributor-mediated flows serve fragmented Indian and Indonesian converter bases. Raw material supply concentrates in China for containerboard pulp, Thailand and Malaysia for PLA resin fermentation feedstock, and India for bagasse agricultural residue. Barrier coating chemistries draw from South Korean and Japanese specialty chemical producers, creating import dependency for moisture-resistant molded fiber formats. Single-source vulnerability runs through Thai corn starch supply for PLA production, which fluctuates with agricultural commodity markets and food security priorities. Distribution runs through regional logistics hubs in Guangdong, Maharashtra, and Bangkok with last-mile consolidation into e-commerce fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: converters relocating capacity from India's tightening BIS certification timelines to China's coastal manufacturing provinces capture qualified supply premiums while avoiding compliance cost compression.
For Market Incumbents: Deploy certification coverage expansion as the primary defensive lever. Amcor plc and Huhtamaki Group should extend ASTM D6400 validation to Vietnamese and Indonesian facilities before anticipated EPR implementation, insulating against emerging bioplastic compounders with Thai fermentation partnerships. Backward integration into bagasse pulping operations in Vietnam and Indonesia secures captive agricultural residue supply against feedstock competition from food security priorities. For New Entrants and Emerging Players: The 40-60% price-point gap between premium certified compostable and economy biodegradable tiers in India's fragmented converter base offers white-space entry. Target Maharashtra and Gujarat bagasse container manufacturing clusters with BIS pre-certification partnerships, positioning for domestic quick-service restaurant contract consolidation. Philippines regulatory white space before 2026-2027 federal EPR legislation enables first-mover collection and recycling infrastructure partnerships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Indian converters with BIS certification gaps but established fresh produce exporter relationships. Long-term viability over the projection horizon hinges on industrial composting infrastructure spread beyond Japan and South Korea. Acquisition targets should demonstrate multi-country certification coverage or captive agricultural residue supply. The signal to watch is PLA resin cost convergence with petroleum-derived alternatives as Thai and Malaysian fermentation capacity scales.| Strategic Initiative | Industry Significance |
|---|---|
| Industrial Composting Certification Acquisition | ASTM D6400 and EN 13432 validation unlocks premium-tier pricing in Japanese and South Korean markets. |
| Bagasse Pulping Capacity Expansion | Vietnamese and Indonesian agricultural residue processing secures feedstock against Thai corn starch volatility. |
| Barrier Coating R&D Partnership | Japanese and South Korean specialty chemical collaboration closes shelf-life performance gaps versus polyethylene-lined alternatives. |
| Multi-Country Specification Lock-In | Centralized ASEAN procurement teams mandate unified formats across Indonesia, Malaysia, and Thailand outlets. |
| E-Commerce Fulfillment Integration | Alibaba and JD.com logistics specifications now exclude non-recyclable poly mailers for cross-border shipments. |
Study Parameters
Multiple input streams — converter production data, regulatory filing analysis, and end-user procurement specifications — were reconciled through bottom-up and top-down triangulation. Primary interviews with sustainability procurement leads at multinational food brands, technical directors at molded fiber tooling operations, regulatory affairs specialists navigating BIS and SAMR compliance, and category buyers at ASEAN quick-service restaurant franchisors informed demand-side validation. Secondary sources included GB standards documentation, Plastic Waste Management Rules filings, METI Green Growth Strategy biomass targets, customs records for containerboard and PLA resin trade flows, and SEC disclosures from packaging converters with Asia-Pacific facility networks.
Historical volume trajectories were cross-referenced against panel input from industry participants to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated packaging type, material grade tier, end-use industry application, distribution channel concentration, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion announcements. Forecast inputs included e-commerce penetration rates in Southeast Asia, industrial composting facility buildout timelines, and PLA resin production cost curves from Thai and Malaysian fermentation capacity.
Caveats apply where PLA feedstock price volatility, barrier coating performance failures, or accelerated EPR implementation in Philippines and Indonesia could materially shift the outlook. Forecasts reflect assumptions about certification timeline compression and biomaterial feedstock competition from food security priorities. Periodic stress-testing of base assumptions is recommended against actual BIS enforcement intensity and SAMR excessive packaging penalty structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
Sustainable Plastic Packaging Market
Sustainable Packaging
Japan Green Packaging Market
Sustainable Packaging
Zero Waste Packaging Market
Sustainable Packaging
Global Paper Straw Market
Sustainable Packaging
Middle East and Africa Eco-Friendly Packaging Market
Sustainable Packaging
Global Disappearing Packaging Market
Sustainable Packaging
Compostable Food Trays Market
Sustainable Packaging
Green Packaging Market
Sustainable Packaging
Bagasse Bowls Market
Sustainable Packaging
Bio-Based Cutlery Market
Sustainable Packaging
Areca Plates Market
Sustainable Packaging
Eco-Friendly Straw Market
Sustainable Packaging
Europe Eco-Friendly Packaging Market
Sustainable Packaging
GCC Green Packaging Market
Sustainable Packaging
Sustainable Packaging Market
Sustainable Packaging
Compostable Tableware Market