
 Compostable Tableware Market | 2026-2036
Compostable Tableware Market Size, Share, and Industry Trends Forecast 2026-2036
Compostable Tableware Market Analysis
Catering services is expanding as a share of compostable tableware offtake, driven by corporate sustainability procurement rules and zero-waste event mandates. Huhtamaki leverages its European manufacturing footprint to supply certified compostable cups and plates under EFSA-reviewed formulations. BioPak sustains market presence through integrated composting partnerships that close the loop from tableware use to organic waste processing. Vegware differentiates via fiber-based product lines that target hot-food applications where PLA performance limits apply.
Compostable tableware comprises single-use serving items engineered from biogenic polymers or plant fibers to decompose within industrial or home composting environments within defined timeframes, typically meeting ASTM D6400 or EN 13432 certification thresholds for disintegration and ecotoxicity. These products serve the foodservice industry's need to eliminate persistent plastic waste while maintaining functional performance for hot, cold, and liquid contents. Bagasse and bamboo materials occupy the fastest-expanding material tier, as fiber-based options bypass PLA's temperature limitations and fossil feedstock dependencies. Plates and bowls lead product type volume, while cups command margin concentration due to barrier coating complexity and certification stringency. The events end-user segment shows structural growth acceleration as festival organizers and sports venues adopt mandatory compostable serving protocols.
The EU F-Gas Regulation and REACH frameworks indirectly shape compostable tableware markets by restricting fluorinated barrier coatings, pushing manufacturers toward PFAS-free alternatives. ASTM D6400 in the United States and EN 13432 in Europe set the dominant certification thresholds that determine product labeling legitimacy and municipal procurement eligibility. BIS compostability standards in India and China's GB/T standards for biodegradable plastics add compliance layers for suppliers targeting Asia-Pacific expansion. Stakeholders must monitor regulatory divergence between industrial and home composting certification pathways, as this split determines addressable market scope and capital allocation for manufacturing and labeling investments.
Market Dynamics
Industrial composting infrastructure expansion is reshaping demand geography for certified compostable tableware, pulling manufacturing investment toward regions with operational anaerobic digestion and composting facilities.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory phase-out of petroleum-based disposables across member states creates procurement pull-through for EN 13432-certified alternatives in foodservice and hospitality sectors.
- Bamboo fiber engineering:Advanced fiber-molding processes now deliver heat resistance above 100°C, unlocking hot-food applications previously restricted to conventional plastics.
- Germany:Packaging ordinances combined with municipal organic waste mandates establish the most mature demand cluster for bagasse and molded fiber tableware in Europe.
Market Restraints
- PLA resin supply concentration:Lactic acid fermentation capacity clusters in Thailand and the United States, exposing converters to feedstock cost volatility and currency risk.
- Temperature performance ceiling:Polylactic acid formulations soften above 55°C, excluding the material from soup, hot beverage, and microwave applications without barrier coatings.
- Composting facility access gaps:Industrial composting infrastructure remains concentrated in Northern Europe and coastal United States, leaving interior markets without end-of-life pathways for certified products.
Strategic Opportunities
- India:BIS compostability standards implementation and urban municipal solid waste rules create first-mover advantage for suppliers establishing local manufacturing and certification pathways.
- Home composting certification divergence:Separate labeling regimes for industrial versus home composting open premium positioning for products meeting stricter domestic decomposition timelines.
- Events and sports venues:Zero-waste mandates at music festivals and stadium concessions drive bulk procurement of fiber-based serving items with embedded traceability.
Industry Challenges
- PFAS-free barrier development:ECHA restrictions on fluorinated coatings force reformulation of grease-resistant molded fiber, extending R&D timelines and certification costs.
- Multi-standard compliance complexity:ASTM D6400, EN 13432, and emerging Asia-Pacific standards require parallel testing protocols, fragmenting quality assurance resources.
- Composting contamination rates:Consumer confusion between biodegradable, compostable, and recyclable labeling reduces facility acceptance rates and increases sorting costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compostable Tableware Market |
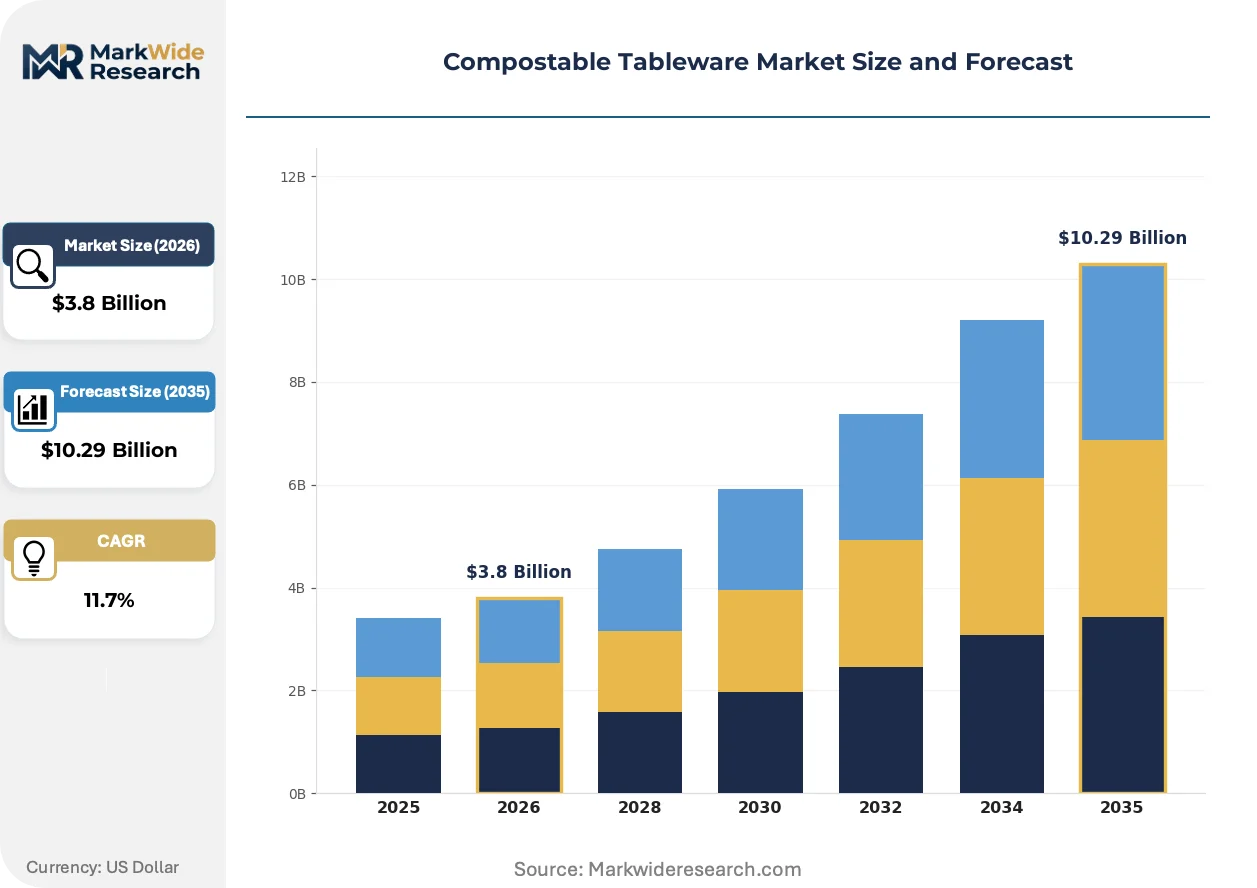
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Bowls, Cutlery, Cups Material: PLA, Bagasse, Bamboo, Palm Leaf End User: Restaurants, Catering Services, Retail, Events Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Vegware, Ecoware, BioPak, MVI ECOPACK, Biotrem, Bioleader, PacknWood, Xiamen Environmental Protection Technology, Huhtamaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compostable Tableware Market Emerging Trajectories
Material science convergence with waste infrastructure policy is compressing product development cycles and recalibrating competitive advantage toward certification breadth rather than unit economics alone.
Molded fiber technology is consolidating competitive positioning in hot-food applications where PLA thermal limitations persist. Stadium concessions and corporate catering operations are adopting bagasse and bamboo plates at accelerating rates. This material shift is consolidating supplier margins around fiber-sourcing relationships and coating formulation IP rather than resin commodity trading.
REACH frameworks and the EU F-Gas Regulation are restricting fluorinated barrier coatings across food-contact materials. Manufacturers are pivoting toward mineral and plant-based grease barriers that satisfy EFSA migration limits. Hot-food container segments face the steepest compliance cost escalation as legacy PFAS formulations lose regulatory legitimacy.
Corporate sustainability procurement rules now mandate compostable serving protocols for external events and employee dining. Facility management contracts are unbundling disposable sourcing from broader catering agreements, creating direct purchasing relationships between tableware suppliers and enterprise sustainability officers. This pattern concentrates in Germany and California where scope-three emissions reporting obligations apply to supply chain partners.
Compostable Tableware Market Segmentation
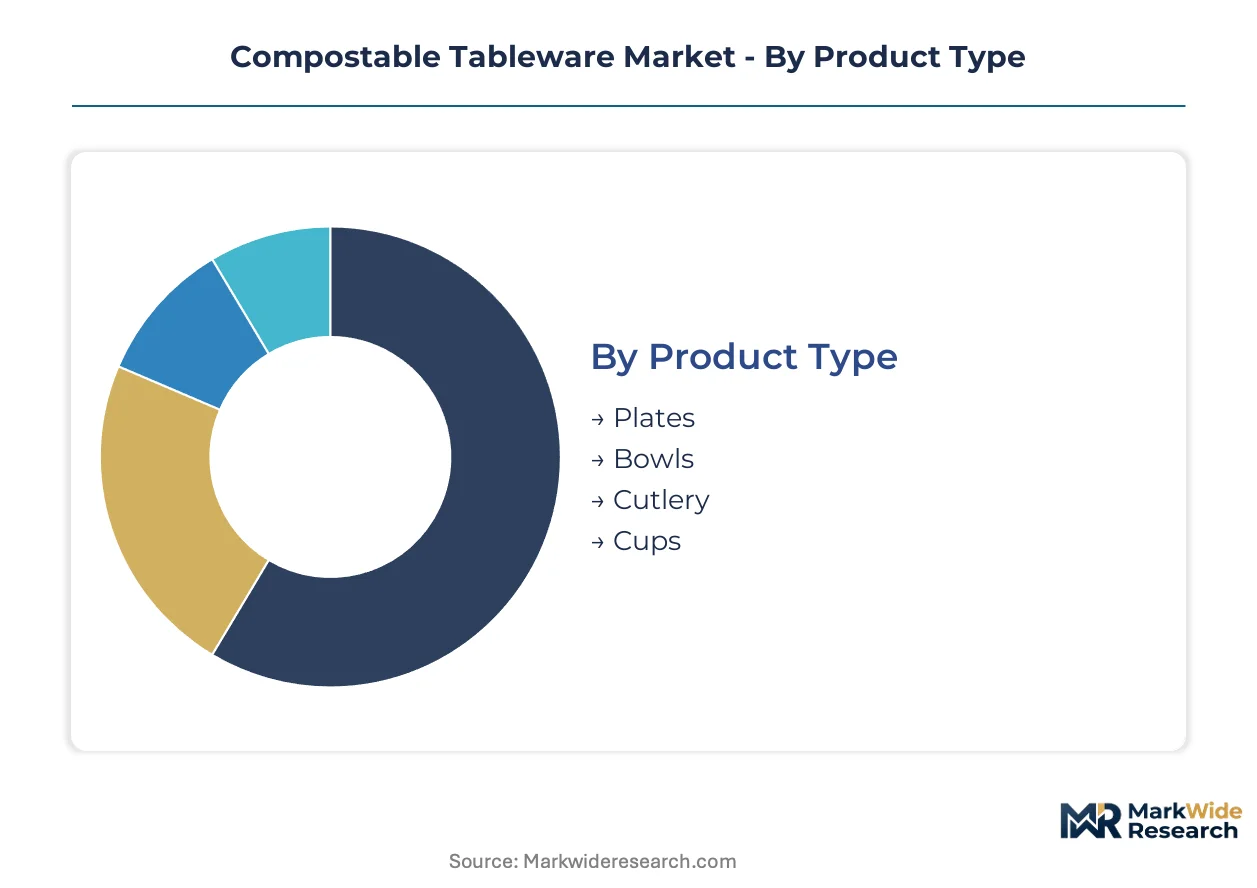
Compostable tableware segmentation reflects divergent performance requirements across temperature exposure, decomposition pathways, and procurement scale. Material selection and end-use application together determine certification complexity and margin structure for suppliers navigating multi-standard compliance.
Product Type:
Standardization dominates commodity serving items while customization concentrates in barrier-coated formats requiring formulation IP.
- Plates:Molded fiber and bagasse substrates form the structural backbone of casual dining replacement programs. Demand clusters in Germany and California where municipal organic waste mandates create procurement pull-through for EN 13432 and ASTM D6400-certified formats.
- Cups:Multi-layer construction with PLA linings or bio-based barrier coatings addresses liquid containment and heat resistance simultaneously. Stadium concessions and corporate campuses in coastal US markets drive volume where industrial composting infrastructure supports end-of-life processing.
- Bowls:Deeper draw molding processes for soup and grain applications.
- Cutlery:Reinforced PLA or CPLA formulations for rigidity under load.
Leading the category by volume: Plates. Growing fastest: Cups.
Material:
Cost tiers separate fossil-derived biopolymers from agricultural fiber alternatives with divergent feedstock exposure.
- Bagasse:Sugarcane fiber residue processed through high-pressure molding delivers heat resistance above 100°C without petroleum inputs. European quick-service chains and Indian institutional catering are expanding procurement as REACH restrictions on fluorinated coatings accelerate PFAS-free migration.
- Bamboo:Rapid-renewable grass fibers engineered through advanced pulp processing achieve dimensional stability for hot-food contact. Japanese and South Korean foodservice operators are driving specification tightening around EFSA migration limits.
- PLA:Corn and sugarcane-derived polylactic acid with temperature ceiling constraints.
- Palm Leaf:Areca nut sheath pressing for premium aesthetic positioning.
Volume leadership sits with bagasse. Steepest expansion trajectory belongs to bamboo as thermal performance engineering matures.
End User:
Customer type determines batch size, certification stringency, and direct versus distributor purchasing relationships.
- Restaurants:Chain operators with scope-three emissions reporting obligations are unbundling disposable sourcing from broadline distribution. California and New York municipal mandates are forcing system-wide transitions ahead of federal standardization.
- Events:Zero-waste protocols at music festivals and sports venues mandate certified compostable serving items with embedded batch traceability. European summer festival circuits and North American stadium concessions are consolidating supplier relationships around single-source accountability.
- Catering Services:Corporate sustainability procurement rules for external meetings and employee dining.
- Retail:Consumer packaged formats for home entertaining and outdoor recreation.
Restaurants dominate current procurement volume. Events are climbing the fastest as mandatory composting protocols proliferate.
Distribution Channel:
Supply concentration versus fragmentation shapes pricing transparency and technical specification support availability.
- Wholesale:Broadline foodservice distributors bundle compostable tableware with janitorial and food ingredients, capturing institutional scale through contract consolidation. National accounts in the United States and Germany leverage volume commitments for price stability.
- Online:Direct-to-operator platforms bypass distributor markups for small-batch specialty formats. Urban independent restaurants and event planners in fragmented municipal markets utilize digital procurement for rapid specification switching.
- Supermarkets:Retail shelf placement for consumer event preparation and household stock-up.
- Specialty Stores:Curated selection for premium eco-conscious positioning.
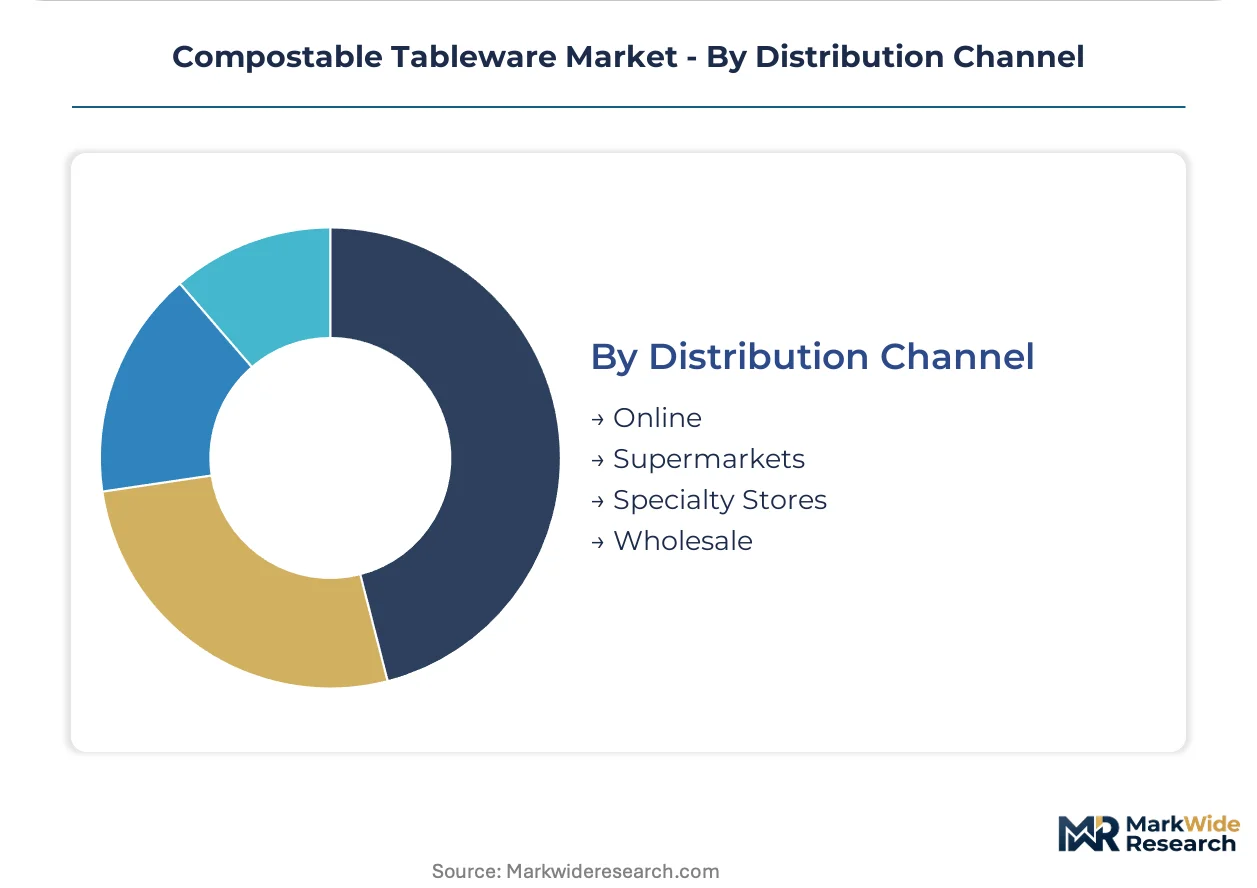
Wholesale channels capture the largest share. Online distribution is expanding most quickly as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Thailand and the United States around PLA resin fermentation, while consumption concentrates in Germany and coastal North American cities with industrial composting infrastructure. This geographic mismatch creates freight cost premiums and currency exposure for converters serving European and Asian foodservice markets.
United States
California and New York municipal organic waste mandates are forcing chain restaurant transitions ahead of federal standardization. EPA enforcement of food waste diversion targets is accelerating procurement of ASTM D6400-certified formats. Stadium concessions in Los Angeles and Seattle are consolidating supplier relationships around single-source accountability for zero-waste protocols.
Germany
Packaging ordinances combined with municipal organic waste mandates establish Europe's most mature demand cluster for bagasse and molded fiber tableware. ECHA restrictions on fluorinated coatings under REACH frameworks are pushing manufacturers toward PFAS-free barrier alternatives. Berlin and Hamburg foodservice operators are driving specification tightening around EFSA migration limits for hot-food contact materials.
India
BIS compostability standards implementation and urban municipal solid waste rules are creating first-mover advantage for suppliers establishing local manufacturing. FSSAI food-contact material regulations are tightening compliance requirements for imported biopolymers. Maharashtra and Karnataka institutional catering operations are expanding procurement of bagasse-based serving items as REACH-aligned restrictions accelerate.
China
GB/T standards for biodegradable plastics are adding compliance layers for suppliers targeting domestic foodservice markets. MEE enforcement of plastic restriction policies is pulling manufacturing investment toward certified compostable alternatives. Yangtze River Delta converters are scaling fiber-molding capacity to serve export demand from European quick-service chains.
Japan
METI carbon neutrality roadmaps are embedding compostable serving protocols in corporate sustainability procurement rules. JIS standards for biodegradable plastics are determining product labeling legitimacy for food-contact applications. Tokyo and Osaka foodservice operators are driving specification adoption around EFSA-aligned migration limits for hot-food containers.
Compostable Tableware Market Vendor Landscape
Top-tier vendors anchor European and North American certification leadership, while Asian specialists concentrate on fiber-molding scale and cost positioning. Mid-tier converters occupy regional niches around municipal procurement eligibility and distributor relationships. Three archetypes dominate: integrated composting partners, fiber-sourcing specialists, and resin-technology licensors. Capacity expansion and strategic partnerships are the dominant competitive moves, with players securing anaerobic digestion tie-ins and PFAS-free coating IP.
Within the integrated solutions tier, Vegware and BioPak exemplify archetypes that close the loop from tableware use to organic waste processing. Huhtamaki anchors the multinational manufacturing vector with European production footprints serving EFSA-reviewed formulations. Chinese specialists including Xiamen Environmental Protection Technology occupy positions in fiber-molding scale for export markets.
| Leading Market Players |
|---|
| Vegware |
| Ecoware |
| BioPak |
| MVI ECOPACK |
| Biotrem |
| Bioleader |
| PacknWood |
| Xiamen Environmental Protection Technology |
| Huhtamaki |
| Others |
Supply Flow & Price Mechanics
Bagasse fiber costs originating in Thai and Indian sugarcane processing mills cascade through three pricing tiers before reaching European foodservice operators, with EN 13432 certification premiums separating industrial-grade from home-compostable tableware at each conversion stage.
Pricing Analysis
Margin tightening in fiber-molded plates reflects PLA resin price volatility and REACH-driven PFAS-free coating reformulation costs. Three-tier pricing structure across premium, standard, and economy levels segments by certification stringency and thermal performance grade. Chain restaurants with scope-three reporting obligations show lowest price sensitivity, while independent event planners in fragmented municipal markets drive hardest bargain.
Supply Chain Analysis
ASTM D6400 and EN 13432 certification gating concentrates converter relationships around accredited testing laboratories in Germany and the United States. Bagasse supply draws from Thai and Indian sugarcane mills, while PLA fermentation capacity clusters in Thailand and the United States. Single-source vulnerability in lactic acid feedstock exposes converters to currency risk. Distribution runs through broadline foodservice distributors with national account pricing power.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compostable tableware markets consolidate around certification breadth and composting infrastructure partnerships, with ECHA PFAS restrictions and multi-standard compliance complexity forcing sub-scale converters toward exit.
For Market Incumbents: Anchor market position through captive supply of bagasse fiber from Thai mill partnerships and backward integration into PFAS-free barrier coating IP. Defend against emerging Chinese fiber-molders by securing anaerobic digestion tie-ins that close the loop for corporate sustainability procurement. Certification investment in parallel ASTM D6400 and EN 13432 pathways preserves access to California and Germany municipal mandates. For New Entrants and Emerging Players: Urban independent restaurants in interior U.S. markets without industrial composting access represent the most penetrable buyer archetype. Home composting certification divergence creates premium positioning for products meeting stricter domestic decomposition timelines. Digital procurement platforms enable rapid specification switching without broadline distributor relationships. For Investors and Strategic Acquirers: BIS compostability standards implementation in India is the leading indicator that first-mover manufacturing advantage will accrue to early certifiers. Five-to-ten year viability hinges on PFAS-free coating formulation ownership and fiber-sourcing relationships rather than resin commodity trading. Watch for Maharashtra and Karnataka institutional catering procurement shifts as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Coating Development | ECHA REACH restrictions eliminate legacy fluorinated barriers, forcing reformulation investment. |
| Industrial Composting Partnership | Anaerobic digestion tie-ins close the loop for corporate sustainability procurement mandates. |
| Multi-Standard Certification Investment | Parallel ASTM D6400 and EN 13432 testing preserves access to California and Germany markets. |
| Bagasse Fiber Supply Integration | Captive sourcing from Thai and Indian sugarcane mills insulates against feedstock volatility. |
| Home Composting Certification Pathway | Premium positioning opens in fragmented municipal markets lacking industrial composting infrastructure. |
Methodological Framework
Multi-period observation of municipal organic waste mandate adoption, composting facility buildout rates, and EN 13432 certification volumes anchored the trend analysis, supplemented by interviews with foodservice procurement directors, sustainability officers at chain restaurant groups, fiber-molding plant managers, and EFSA regulatory affairs specialists. Secondary validation drew from EPA food waste diversion reports, ECHA REACH restriction updates, BIS standard notifications, and customs trade data for bagasse and PLA resin flows. Bottom-up segment sizing triangulated against top-down market aggregation.
Input-output matrix modeling connected feedstock capacity in Thailand and the United States to converter output across product types, materials, and end-user segments over the projection horizon. Segmentation dimensions included temperature exposure requirements, decomposition pathway certification, and procurement scale. CAGRs derived from regression against historical mandate adoption curves and infrastructure investment pipelines, with PLA resin price indices and industrial composting facility counts as key forecast inputs.
Revisions become necessary when ECHA expands PFAS restrictions beyond food-contact materials, when BIS or GB/T standards diverge from ASTM/EN frameworks, or when major municipalities reverse organic waste mandates. A model refresh is warranted upon material change in industrial composting infrastructure buildout rates across target geographies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
Asia-Pacific Sustainable Packaging Market
Sustainable Packaging
Green Packaging Market
Sustainable Packaging
United States Green Packaging Market
Sustainable Packaging
Europe Sustainable Packaging Market
Sustainable Packaging
Wheat Straw Cutlery Market
Sustainable Packaging
Global Disappearing Packaging Market
Sustainable Packaging
PVC-Free Packaging Market
Sustainable Packaging
Sustainable Foodservice Packaging Market
Sustainable Packaging
Areca Plates Market
Sustainable Packaging
Japan Green Packaging Market
Sustainable Packaging
GCC Green Packaging Market
Sustainable Packaging
Global Paper Straw Market
Sustainable Packaging
Asia-Pacific Eco-Friendly Packaging Market
Sustainable Packaging
Europe Eco-Friendly Packaging Market
Sustainable Packaging
Bio-Based Cutlery Market
Sustainable Packaging
Eco Friendly Bottles Market