
 United States Green Packaging Market | 2026-2036
United States Green Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United States Green Packaging Market Intelligence
Biodegradable polymer formulation is narrowing the performance gap between conventional plastics and plant-derived alternatives in moisture barrier applications. Amcor plc leverages its integrated film manufacturing network to supply compostable laminates at scale. DS Smith plc anchors its position through recycled paperboard specialization across e-commerce and food service channels. Mondi plc competes with kraft paper-based flexible packaging systems designed for existing recycling streams.
Green packaging comprises containers, wraps, and protective structures engineered from renewable, recyclable, or biodegradable feedstocks with specified end-of-life pathways such as industrial composting or closed-loop recycling. These materials must meet ASTM D6400 or D6868 biodegradation standards and maintain functional barrier properties against oxygen and moisture across distribution cycles. Recycled paper occupies the largest volume share due to mature collection infrastructure and FDA compliance for food contact surfaces. Biodegradable plastics represent the fastest-expanding material category as resin costs decline and retail brands mandate petroleum-free portfolios. Active packaging technology commands premium positioning through oxygen-scavenging and humidity-control functions that extend shelf life without synthetic preservatives.
The EPA prioritizes sustainable materials management through waste reduction hierarchies that elevate reusable and recyclable packaging designs. State regulators in California, New York, and Washington enforce extended producer responsibility statutes that assign end-of-life collection costs to brand owners. FDA food contact notification requirements govern migration limits for recycled and bio-based materials entering food packaging applications. Stakeholders must monitor evolving compostability certification standards and state-by-state policy fragmentation that complicates national packaging strategies.
Market Dynamics
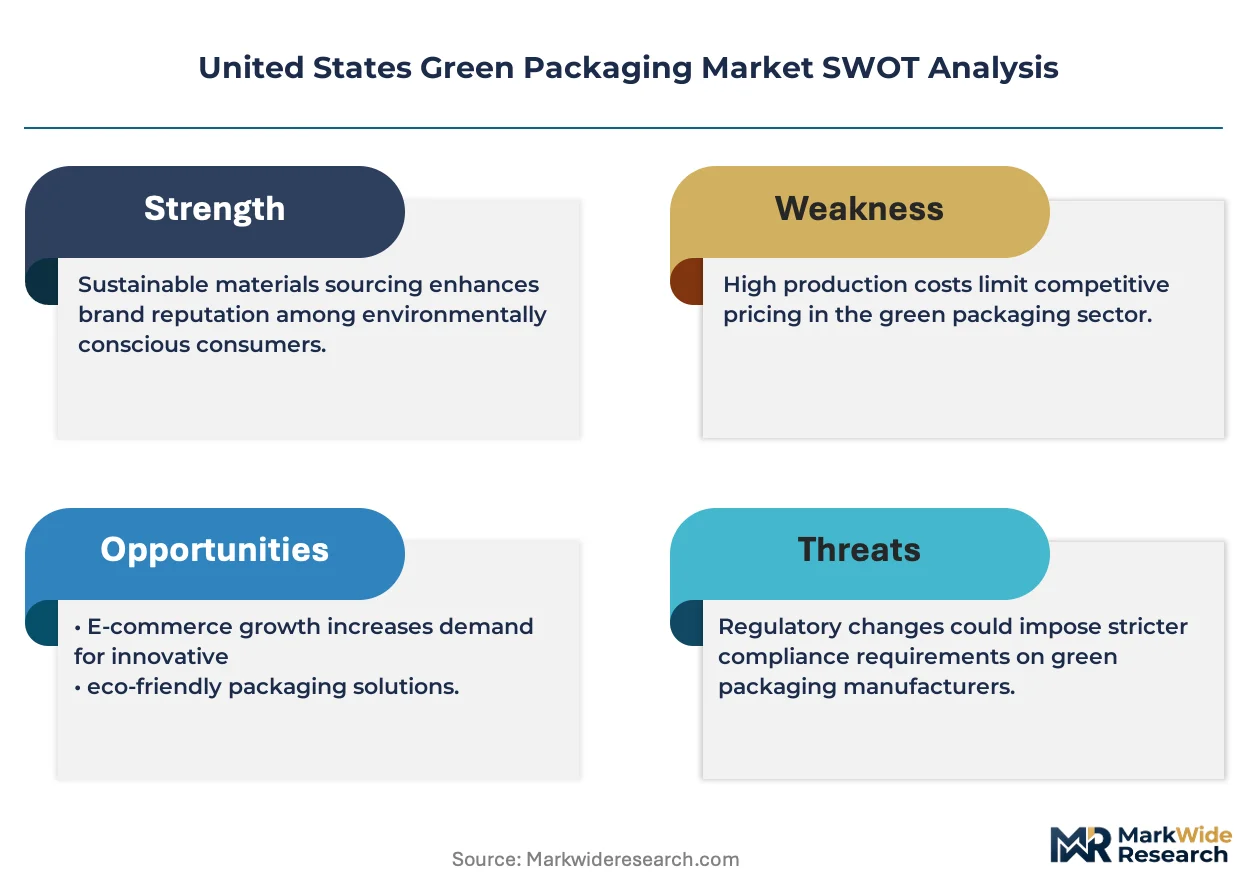
State-level extended producer responsibility statutes are reassigning end-of-life collection costs from municipalities to brand owners, forcing packaging redesigns and material substitutions across food, beverage, and e-commerce supply chains.
Growth Catalysts
- California SB 54 mandates:The state's plastic pollution producer responsibility act requires 30% post-consumer recycled content by 2028, compelling CPG brands to accelerate sourcing of compliant substrates.
- Industrial composting infrastructure:Municipal facilities in the Northeast corridor now accept ASTM D6400-certified packaging, unlocking biodegradable polymer demand from food service operators.
- Moisture barrier breakthroughs:Bio-based coating technologies have achieved oxygen transmission rates competitive with conventional multilayer films, satisfying shelf-life requirements for snack and fresh produce applications.
Market Restraints
- Resin cost volatility:PLA and PHA feedstock prices track corn and sugarcane commodity swings, compressing margins for converters serving price-sensitive food retail channels.
- Collection infrastructure gaps:Curbside composting reaches fewer than 200 US counties, limiting addressable market for certified biodegradable formats outside coastal metropolitan zones.
- Performance trade-offs:Kraft paper barriers exhibit moisture sensitivity in frozen supply chains, restricting substitution potential for ice cream and prepared meal segments.
Strategic Opportunities
- Texas and Florida expansion:These underpenetrated Sun Belt states lack EPR frameworks but show rising corporate sustainability commitments from headquarters-relocated CPG firms.
- Reusable packaging systems:Loop-style refill platforms are gaining traction in personal care and household cleaning, creating service revenue streams beyond single-unit sales.
- USDA BioPreferred procurement:Federal purchasing preferences for biobased products open institutional food service channels requiring ASTM-compliant disposable serviceware.
Industry Challenges
- Composting certification timelines:BPI and TUV Austria validation processes extend 12-18 months, delaying product launches and freezing R&D budgets during regulatory uncertainty.
- Legacy equipment retrofitting:Converting extrusion lines from petroleum-based to bio-based resins requires capital outlays and specialized technician training that mid-tier converters struggle to finance.
- Migration testing complexity:FDA food contact notification requirements for recycled and novel bio-based materials demand extensive extraction studies, lengthening compliance pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Green Packaging Market |
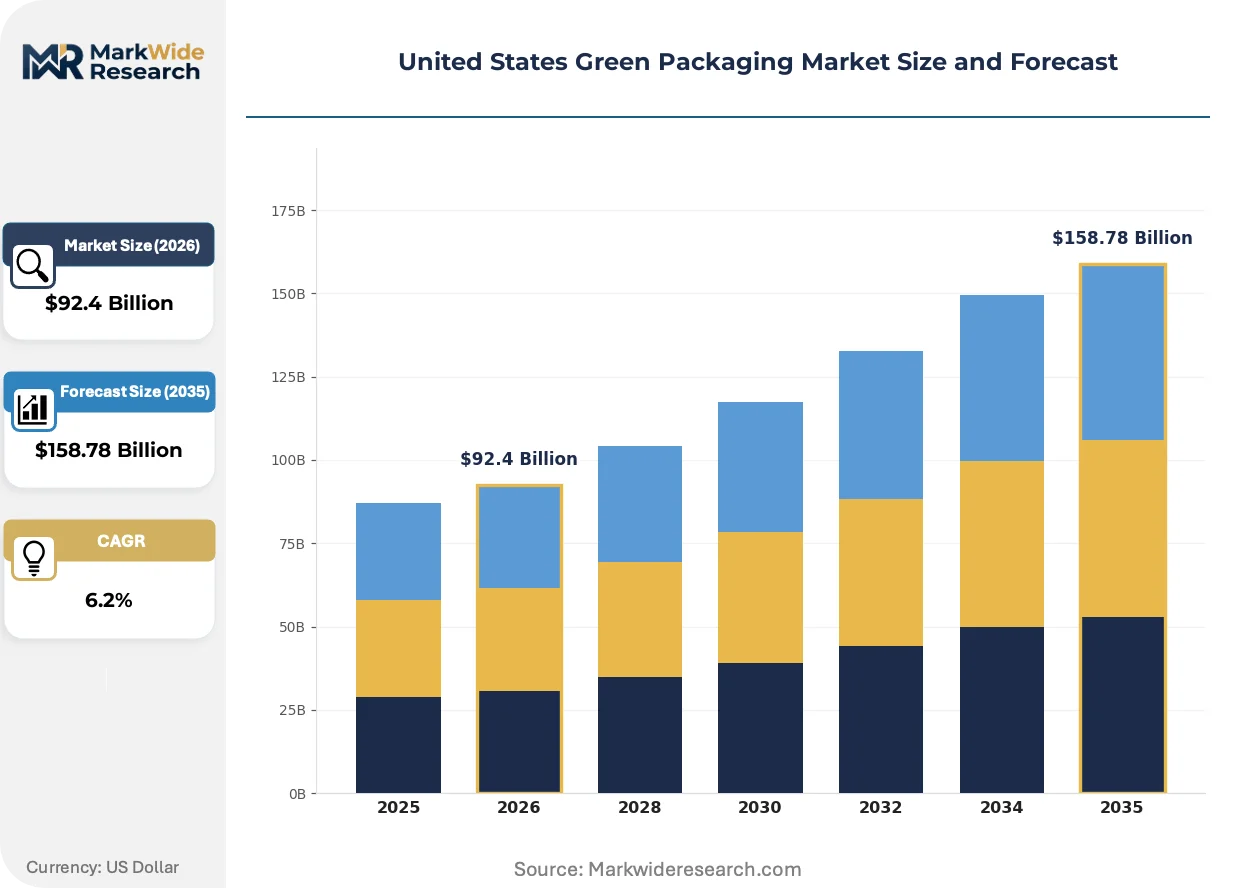
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $158.78 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Biodegradable Plastics, Recycled Paper, Plant-based Materials, Glass Application: Food Packaging, Healthcare Packaging, Personal Care, Electronics Packaging End User: Retail, Food and Beverage, Pharmaceuticals, Electronics Technology: Active Packaging, Intelligent Packaging, Vacuum Packaging, Modified Atmosphere Packaging |
| Companies Covered | Amcor plc, DS Smith plc, Mondi plc, Sealed Air Corporation, Ball Corporation, Pactiv Evergreen Inc, Sonoco Products Company, Evergreen Packaging LLC, Smurfit Kappa Group plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Green Packaging Market Strategic Shifts & Innovations
Material science advances and regulatory pressure are converging to collapse the performance gap between conventional plastics and plant-derived alternatives, while procurement patterns shift toward specification-driven supplier consolidation.
Barrier coating technology is migrating from petroleum-derived ethylene vinyl alcohol to alginate and chitosan bio-polymers that achieve comparable oxygen scavenging. Frozen food processors in the Upper Midwest are piloting these substrates for vegetable and seafood applications. The transition is compressing reliance on multilayer structures that complicate mechanical recycling streams.
EPA sustainable materials management priorities now explicitly elevate reusable and recyclable designs within federal procurement guidelines. This hierarchy shift redirects R&D investment away from compostable-only formats toward mechanically recyclable mono-materials. Brand owners with national distribution footprints are responding by simplifying laminate constructions to meet Association of Plastic Recyclers design standards.
Retail buyer consolidation is concentrating specification authority among Walmart, Target, and Kroger sustainability procurement teams. These centralized functions are displacing fragmented category-manager decision-making with standardized scorecards penalizing non-recyclable formats. The pattern is most visible in private-label food and household product lines where packaging redesign cycles have compressed from 36 to 18 months.
United States Green Packaging Market Segmentation
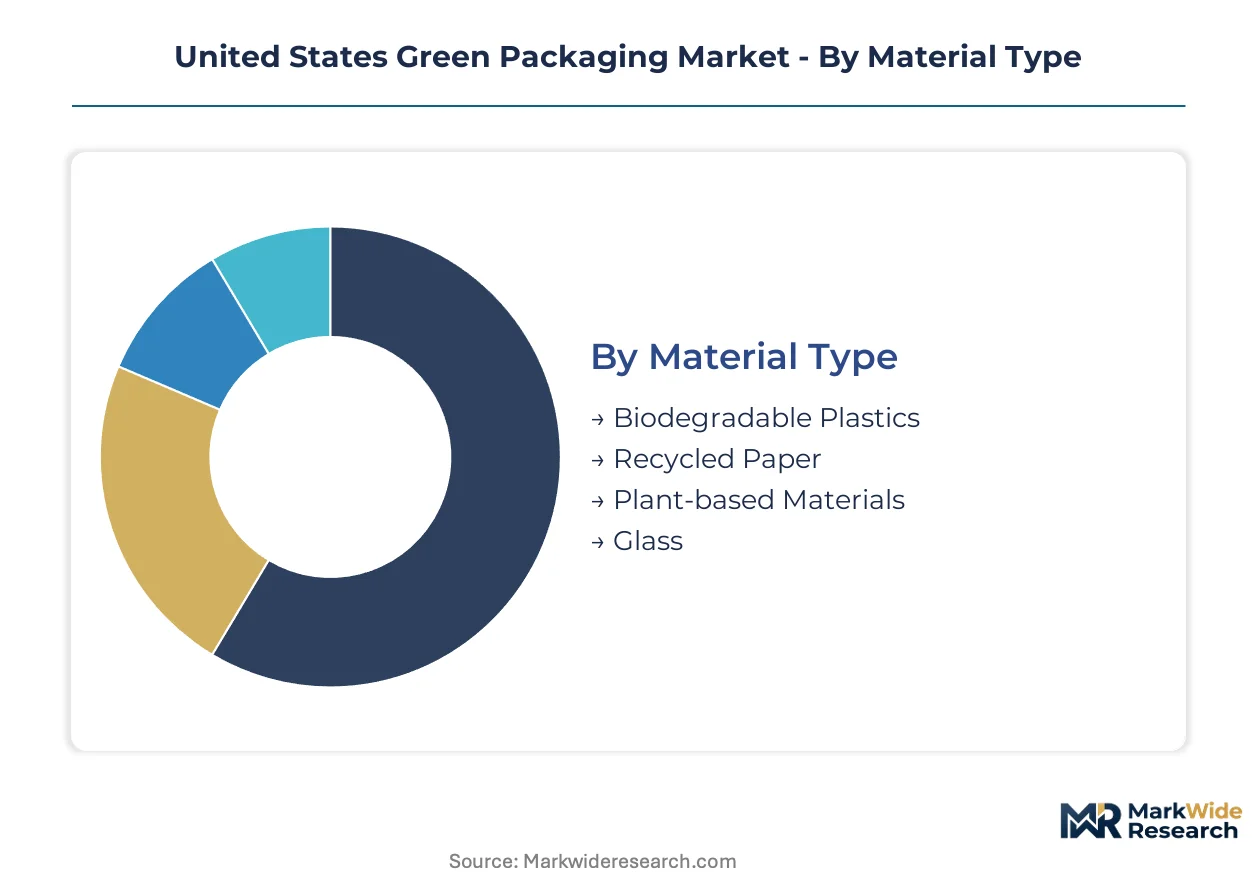
Material specifications, application requirements, and end-user procurement cycles create distinct velocity profiles across the United States green packaging landscape. Understanding these turnover rhythms enables suppliers to align inventory and R&D investments with segment-specific demand pulses.
Material Type:
Recycled paper turns inventory fastest due to mature collection infrastructure and FDA food contact compliance, while glass cycles slowest owing to weight logistics and regional manufacturing concentration.
- Biodegradable Plastics:PLA and PHA resins formulated to ASTM D6400 standards achieve oxygen barriers competitive with conventional multilayer films. Food service operators in California and the Northeast corridor are expanding procurement as municipal composting capacity scales.
- Recycled Paper:Post-consumer fiber processed to FDA migration limits dominates e-commerce void fill and food service clamshells. Mature de-inking infrastructure and established baling networks keep unit costs stable across volatile resin markets.
- Plant-based Materials:Molded fiber and agricultural residue composites serve prepared meal trays and produce containers.
- Glass:Recycled cullet content satisfies premium beverage and pharmaceutical stability requirements.
Recycled paper anchors the volume base while biodegradable plastics gain share at the steepest rate.
Application:
Food packaging commands the deepest specification layers owing to FDA notification requirements, while electronics packaging operates on extended validation cycles driven by electrostatic discharge protocols.
- Food Packaging:Moisture-barrier bio-laminates and oxygen-scavenging active layers extend shelf life for fresh produce and snack applications. Retail buyers at Walmart and Kroger are consolidating procurement around mechanically recyclable mono-material designs.
- Healthcare Packaging:Sterile barrier systems combining bio-based films with ethylene oxide compatibility satisfy FDA device regulations. Hospital procurement committees are mandating mercury-free sterilization indicators.
- Personal Care:Refillable pump systems and aluminum-free deodorant sticks drive format innovation.
- Electronics Packaging:Anti-static molded pulp and corrugated cushions protect semiconductor shipments.
Food packaging generates the highest absolute demand while healthcare packaging commands the steepest premium expansion.
End User:
Food and beverage procurement cycles compress to 18 months as private-label redesign accelerates, while pharmaceutical qualification timelines extend to 36 months due to stability testing requirements.
- Food and Beverage:CPG brands are redesigning portfolios to meet California SB 54 post-consumer recycled content mandates. Plant-based containers for ready-to-drink beverages and prepared meals are displacing conventional PET at the fastest clip.
- Retail:Private-label sustainability scorecards at Target and Kroger are standardizing packaging specifications across household and personal care categories.
- Pharmaceuticals:Blister packs and vial containment systems face USP migration testing for novel bio-based materials.
- Electronics:Original equipment manufacturers are specifying recycled-content corrugated for finished goods distribution.
Food and beverage anchors the volume base while retail channels gain specification authority at the steepest rate.
Technology:
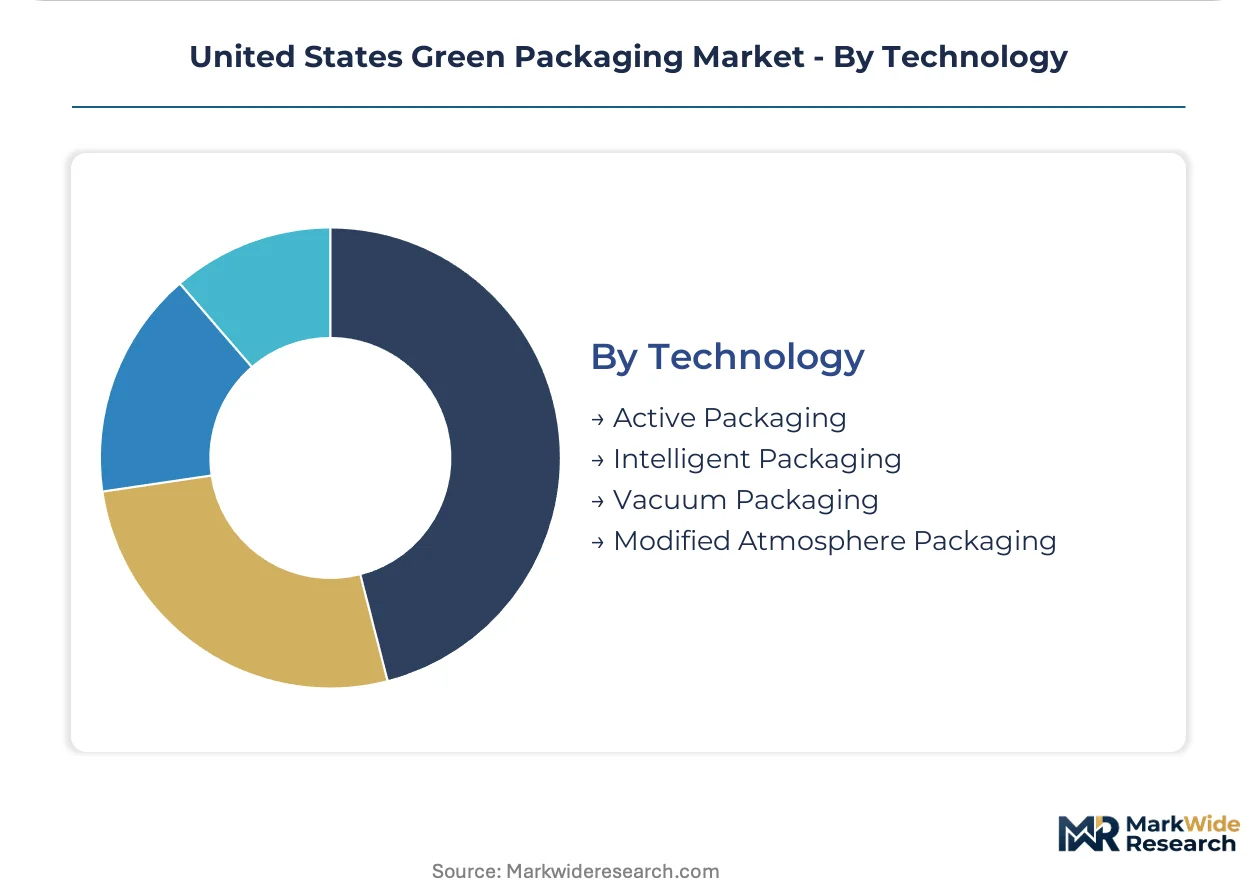
Active packaging commands the longest development cycles due to extraction study requirements, while vacuum packaging leverages existing thermoforming infrastructure for rapid deployment.
- Active Packaging:Oxygen-scavenging sachets and humidity-control inserts extend shelf life without synthetic preservatives. FDA food contact notification for bio-based scavenger formulations requires 12-18 month validation timelines.
- Intelligent Packaging:Time-temperature indicators and RFID-enabled traceability layers support cold chain verification for seafood and vaccine distribution.
- Vacuum Packaging:Thermoformed PET and PLA trays with barrier skins serve processed meat and cheese applications.
- Modified Atmosphere Packaging:Gas-flush systems with compostable lidding films preserve fresh produce respiration rates.
Vacuum packaging anchors the installed equipment base while active packaging climbs the fastest on premium shelf-life extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Green packaging demand concentrates in coastal metropolitan zones where municipal composting infrastructure and extended producer responsibility statutes create procurement pull. Import volumes of bio-based resins track California and Northeast corridor consumption patterns, while domestic recycled paperboard production serves interior distribution networks.
California
Food service operators and CPG brands drive procurement of ASTM D6400-certified containers under SB 54 mandates. The state's plastic pollution producer responsibility act requires escalating post-consumer recycled content thresholds through 2032. Los Angeles and San Francisco anchor conversion capacity for compostable laminates serving ready-to-drink beverage portfolios.
Northeast Corridor
Municipal composting facilities in New York, Massachusetts, and Vermont accept certified biodegradable packaging, unlocking demand from institutional food service. State-level extended producer responsibility statutes assign end-of-life collection costs to brand owners. Boston and New York City concentrate pilot programs for reusable packaging systems in personal care and household cleaning channels.
Pacific Northwest
Corporate sustainability commitments from technology and retail headquarters relocate procurement specifications toward petroleum-free portfolios. Oregon and Washington enforce packaging reduction targets through state environmental agencies. Seattle anchors regional distribution for molded fiber meal trays and produce containers serving natural grocery chains.
Texas
Sun Belt expansion opportunities emerge as CPG firms relocate headquarters without facing state-level EPR frameworks. Houston and Dallas-Fort Worth concentrate e-commerce fulfillment centers specifying recycled-content corrugated for void fill applications. Corporate procurement teams are mandating sustainability scorecards independent of regulatory pressure.
Midwest
Frozen food processors in Illinois and Ohio pilot bio-based barrier coatings for vegetable and seafood applications. The region's mechanical recycling infrastructure supports mono-material packaging designs favored by Association of Plastic Recyclers standards. Chicago anchors distribution networks for recycled paperboard serving private-label retail consolidation.
United States Green Packaging Market Key Industry Players
On the supply side, the industry is consolidating around integrated film manufacturers and recycled paperboard specialists with national distribution footprints. Tiered competitive positioning separates scale-driven multinationals from regional converters serving localized composting infrastructure. Three archetypes dominate: integrated resin-to-film manufacturers, recycled fiber specialists, and bio-based coating innovators. Capacity expansion and strategic partnerships represent the dominant competitive moves as converters retrofit legacy equipment for bio-based resin processing.
Within the integrated packaging tier, Amcor plc, DS Smith plc, and Mondi plc exemplify divergent strategic positioning. Amcor plc leverages global film manufacturing networks to supply compostable laminates at scale. DS Smith plc anchors its competitive position through recycled paperboard specialization across e-commerce and food service channels. Mondi plc occupies a position competing with kraft paper-based flexible packaging systems designed for existing recycling streams. These three entities represent the spectrum from petroleum-free portfolio mandates to mechanically recyclable mono-material designs.
| Leading Market Players |
|---|
| Amcor plc |
| DS Smith plc |
| Mondi plc |
| Sealed Air Corporation |
| Ball Corporation |
| Pactiv Evergreen Inc |
| Sonoco Products Company |
| Evergreen Packaging LLC |
| Smurfit Kappa Group plc |
| Others |
Cost & Logistics Intelligence
Chicago's recycled paperboard manufacturing cluster anchors North American supply capacity, and its proximity to Midwest agricultural feedstock sources shapes converter pricing power across biodegradable resin markets. Cost compression in PLA and PHA grades intensifies when corn and sugarcane commodity swings transmit through biopolymer supply contracts, squeezing margins for converters serving price-sensitive food retail channels.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stabilize volume commitments against resin volatility. Price differentiation rests on certification grade—ASTM D6400 compliance commands premium positioning over non-certified alternatives—and volume scale, with national CPG brands extracting favorable terms through consolidated procurement. Pricing pressure stems from state EPR statutes forcing material substitutions ahead of cost-parity timelines. Small regional converters exhibit highest price sensitivity due to limited balance sheet capacity for inventory hedging, while integrated multinationals with captive resin supply demonstrate lowest sensitivity.
Supply Chain Analysis
Corn and sugarcane agricultural feedstocks from the US Midwest and Brazil supply PLA and PHA resin production, with fossil-derived barrier coatings and specialty additives completing formulation requirements. Geographic supply concentration centers on Nebraska and Iowa for domestic corn starch, while Brazilian sugarcane ethanol feeds international biopolymer capacity. Single-source vulnerability runs through limited ASTM-certified compostable laminate converters serving California and Northeast corridor demand. Distribution runs through national CPG brand direct procurement networks and regional food service distributor channels, with e-commerce fulfillment centers specifying recycled-content corrugated for void fill applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against conventional petroleum-based packaging incumbents whose scale advantages and established recycling infrastructure threaten bio-based alternative penetration. The defensive imperative intensifies as mechanical recycling improvements narrow the end-of-life advantage that compostable formats currently claim.
For Market Incumbents: Insulate market position through backward integration into agricultural feedstock supply and dedicated compostable laminate capacity additions in California. FDA food contact notification timelines for novel bio-based materials represent a regulatory moat that early certification investments can deepen. Channel control through exclusive supply agreements with Walmart and Kroger sustainability procurement teams limits entrant access to specification authority. For New Entrants and Emerging Players: Establish a beachhead in Texas and Florida Sun Belt markets where corporate sustainability commitments from relocated CPG headquarters create demand without state EPR compliance costs. USDA BioPreferred federal procurement channels offer specification-driven entry into institutional food service with shorter validation cycles than retail private-label qualification. A co-development partnership approach with mid-tier converters lacking R&D capacity accelerates market access without capital-intensive equipment retrofitting. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory arbitrage play because state-level EPR expansion will mechanically expand addressable market for compliant formats regardless of underlying consumer preference shifts. Acquisition targets should emphasize converters with validated ASTM certification pipelines and established relationships with municipal composting facility operators. The signal to watch is BPI and TUV Austria certification backlog duration—compression indicates supply constraint and pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive corn and sugarcane sourcing insulates PLA/PHA converters from commodity volatility compressing margins. |
| ASTM Certification Pipeline Investment | BPI and TUV Austria validation capacity accelerates product launches ahead of California SB 54 compliance deadlines. |
| Reusable Packaging System Development | Loop-style refill platforms in personal care create service revenue streams beyond single-unit sales cycles. |
| Mono-Material Simplification R&D | Mechanically recyclable designs satisfy Association of Plastic Recyclers standards preferred by national retail buyers. |
| Municipal Composting Facility Partnerships | Direct relationships with Northeast corridor operators secure offtake capacity for certified biodegradable formats. |
Research Approach
A spread of perspectives from packaging procurement managers at national retailers, sustainability officers at CPG brands, composting facility operators, and resin converter technical directors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through EPA sustainable materials management documentation, FDA food contact notification databases, and state-level EPR statute analysis. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across material type, application, and end-user dimensions.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation by material specification, application requirements, technology type, and regional regulatory cluster. CAGRs derived from historical substitution elasticities between conventional and bio-based formats, adjusted for policy mandate implementation timelines. Industry-specific forecast inputs included municipal composting capacity buildout schedules and post-consumer recycled content compliance thresholds.
Stress conditions across resin cost volatility, certification timeline delays, and EPR policy adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding infrastructure buildout and brand owner compliance behavior. Material shifts in federal procurement preference strength or mechanical recycling technology breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
PVC-Free Packaging Market
Sustainable Packaging
Asia-Pacific Eco-Friendly Packaging Market
Sustainable Packaging
Compostable Food Trays Market
Sustainable Packaging
Asia-Pacific Sustainable Packaging Market
Sustainable Packaging
Bio-Based Cutlery Market
Sustainable Packaging
Wheat Straw Cutlery Market
Sustainable Packaging
GCC Green Packaging Market
Sustainable Packaging
Eco-Friendly Straw Market
Sustainable Packaging
Sustainable Foodservice Packaging Market
Sustainable Packaging
North America Eco-Friendly Packaging Market
Sustainable Packaging
Plant Based Packaging Market
Sustainable Packaging
Eco Friendly Bottles Market
Sustainable Packaging
Sustainable Plastic Packaging Market
Sustainable Packaging
Bagasse Bowls Market
Sustainable Packaging
Middle East and Africa Eco-Friendly Packaging Market
Sustainable Packaging
Green Packaging Market