
 Bamboo Plate Market | 2026-2036
Bamboo Plate Market Size, Share, and Industry Trends Forecast 2026-2036
Bamboo Plate Market Analysis
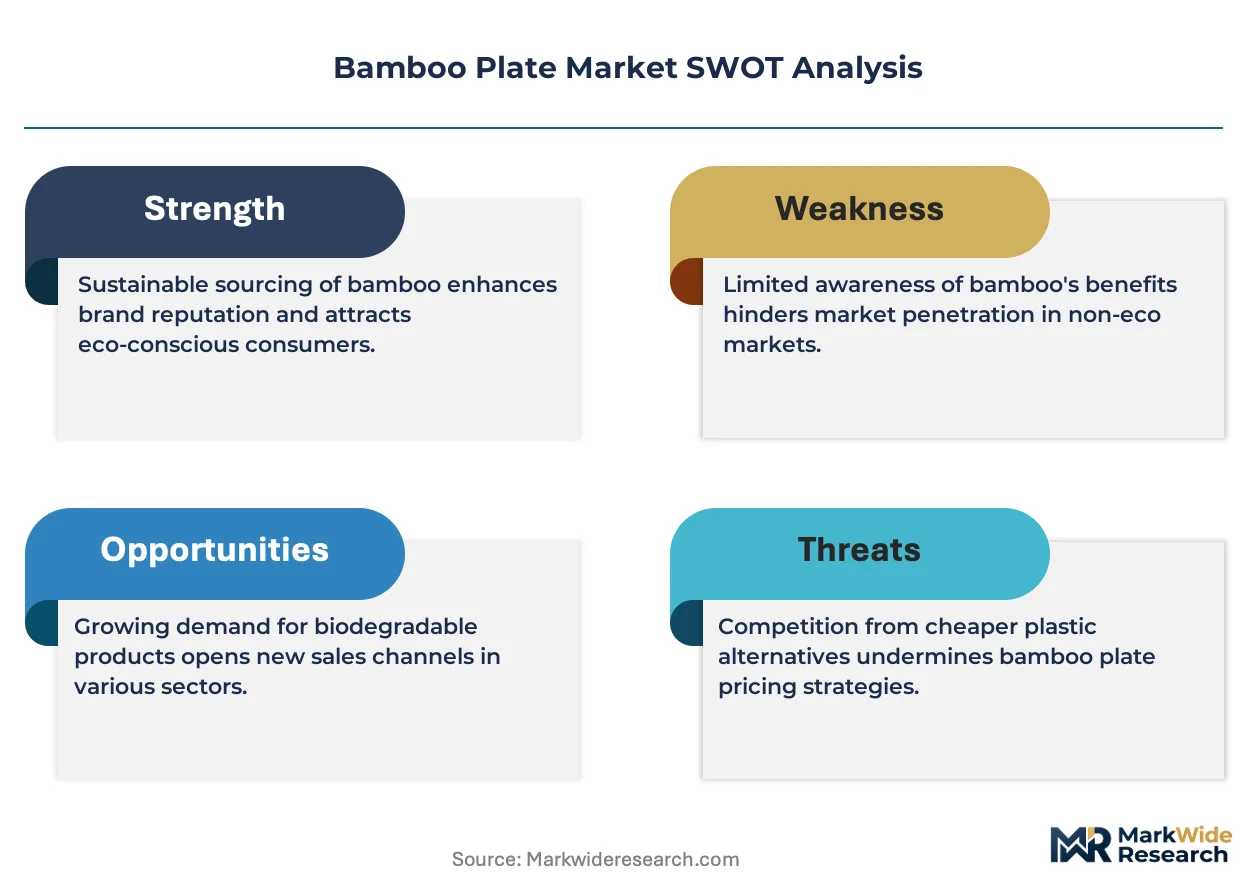
The bamboo plate category is rebalancing between premium artisan-positioned offerings and mass-market commodity disposables. Panabam leverages its European retail footprint to command shelf space in specialty kitchenware channels. Yi Bamboo anchors its position through direct control of Anji County raw material sourcing in Zhejiang Province. PacknWood differentiates by supplying branded bamboo dinnerware to Michelin-starred restaurants across Paris and London.
Bamboo plates are rigid serving vessels manufactured from laminated or heat-pressed moso bamboo fibers, typically finished with food-grade plant-based binders and certified compostable under EN 13432 standards. Their primary commercial purpose is to replace petroleum-based disposables in foodservice operations subject to plastic restriction mandates. The reusable segment leads margin capture due to higher unit economics and repeat purchase cycles, while the biodegradable category grows fastest as institutional buyers face compliance deadlines under extended producer responsibility frameworks. Online sales channels are expanding most rapidly among direct-to-consumer specialists, though wholesale still controls volume flows to restaurant groups and event management companies.
The EU Green Deal and F-Gas Regulation indirectly shape bamboo plate demand by accelerating plastic phase-out timelines across member states, while FDA food contact substance notifications govern US import clearance for bamboo-composite serviceware. BIS certification requirements in India and GB standards in China create divergent compliance pathways that fragment supplier qualification protocols. Stakeholders must monitor how national implementation of the EU Packaging and Packaging Waste Regulation recalibrates compostability testing thresholds and whether these standards propagate into bilateral trade agreements with Asian manufacturing hubs.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing plastic phase-out timelines across foodservice channels, forcing procurement officers to source compostable alternatives ahead of compliance deadlines.
Growth Catalysts
- EU Green Deal mandates:National packaging laws in Germany, France, and the Netherlands now require compostable serviceware in institutional catering contracts.
- Extended producer responsibility frameworks:Restaurant groups face financial penalties for non-compliant disposable inventories, accelerating substitution toward bamboo fiber alternatives.
- Anji County raw material concentration:Zhejiang Province's integrated bamboo processing clusters enable cost-competitive laminated fiber production at scale.
Market Restraints
- Moso bamboo input volatility:Weather-driven harvest fluctuations in subtropical growing zones create raw material price instability for laminated fiber processors.
- Single-source geography risk:Heat-press manufacturing capacity concentrates in eastern Chinese provinces, exposing buyers to logistics disruption and tariff exposure.
- EN 13432 certification friction:Compostability testing timelines and documentation requirements delay product qualification for EU foodservice distributors.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden, Denmark, and Finland maintain lower bamboo plate penetration despite stringent national plastic restrictions, creating first-mover whitespace.
- Event management channel innovation:Direct-to-venue rental models for reusable bamboo dinnerware bypass wholesale markups and capture recurring revenue streams.
- Technology convergence:Laser-etching personalization combined with plant-based antimicrobial coatings enables premium positioning in wedding and corporate gifting segments.
Industry Challenges
- Food-contact substance compliance talent gap:Few technical specialists understand both FDA notification pathways and EU food contact material regulations simultaneously.
- Heat-press equipment capex intensity:Industrial-scale lamination machinery requires substantial capital outlay, constraining mid-tier manufacturer expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bamboo Plate Market |
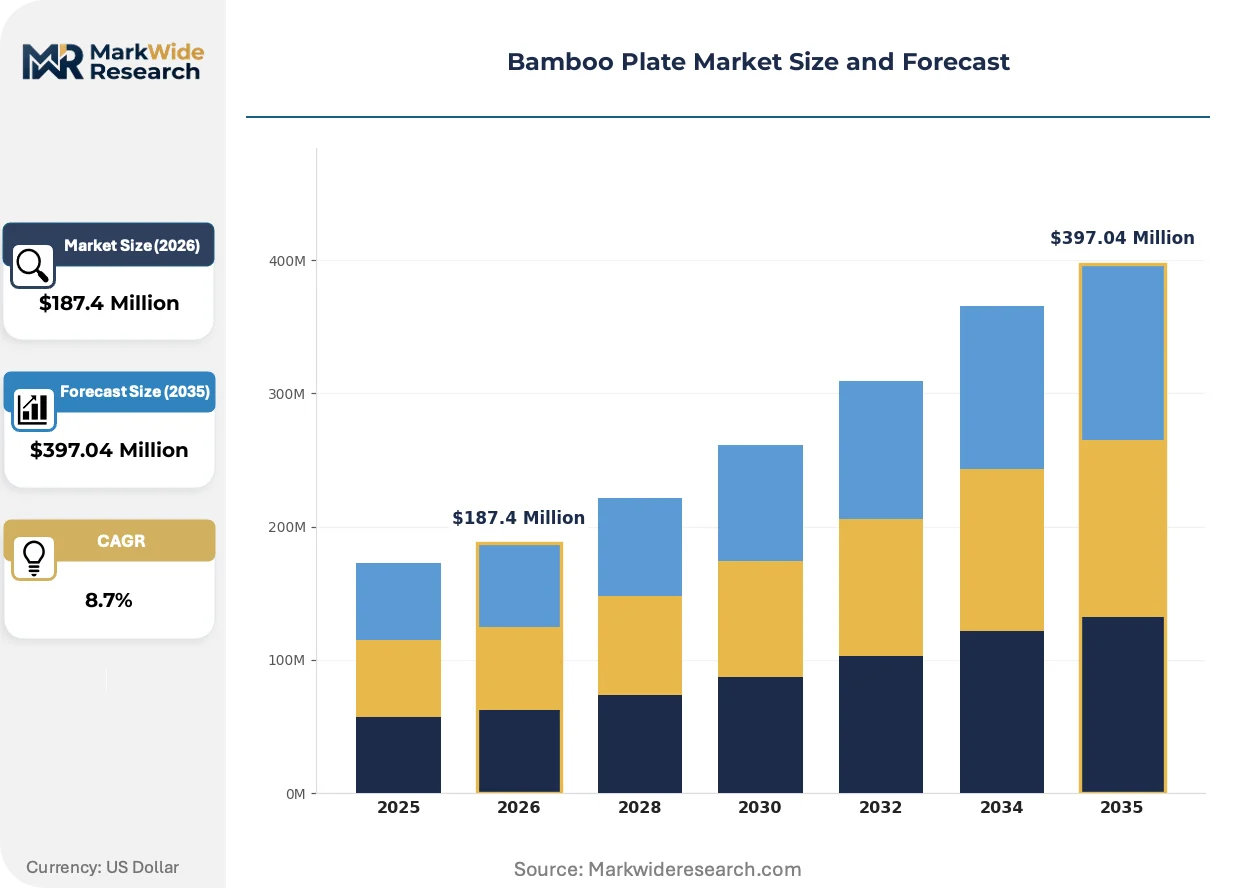
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Biodegradable, Eco-Friendly Distribution Channel: Retail Stores, Online Sales, Wholesale, Direct Sales End User: Households, Restaurants, Caterers, Events Size: Small, Medium, Large, Custom |
| Companies Covered | Panabam, Yi Bamboo, PacknWood, Xiamen Ebei Import and Export Co. Ltd, BambooVision, bambu LLC, You Cheng, Pefso Co. Ltd, Mann Bamboo Fiber Ware Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bamboo Plate Market Emerging Trajectories
Product differentiation is migrating from basic compostability claims toward functional performance attributes and aesthetic customization capabilities.
Plant-based antimicrobial coatings derived from chitosan and tea polyphenols are overtaking conventional food-grade lacquers in premium bamboo plate specifications. Michelin-starred kitchens in Paris and London specify these finishes for extended service durability. The shift is compressing margins for untreated commodity plates while enabling three-tier pricing stratification.
REACH restrictions on formaldehyde-releasing binders are forcing laminated bamboo processors to reformulate adhesive systems. Industrial laboratories in Zhejiang Province now validate soy-protein and lignin-based alternatives for structural integrity. Small-batch artisan producers in Portugal and Spain are capturing specialty retail shelf space with certified zero-formaldehyde offerings.
Certification-driven preference shifts are fragmenting procurement authority within restaurant groups. Sustainability officers now override purchasing managers on serviceware selection, prioritizing BPI or TÜV Austria OK Compost HOME labels over unit cost metrics. This behavioral change is most visible in German and Dutch corporate catering contracts, where compliance documentation requirements have doubled vendor qualification timelines.
Bamboo Plate Market Segmentation
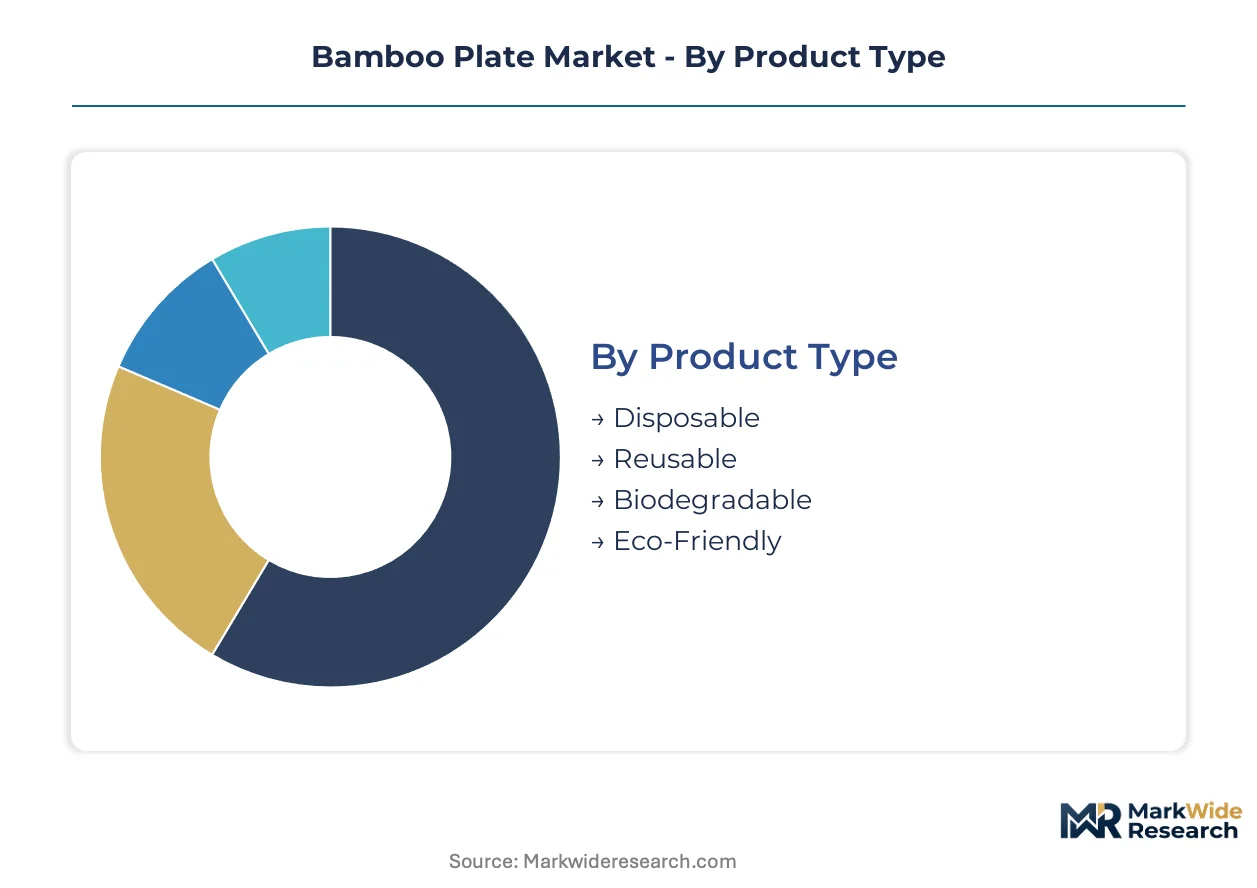
Bamboo plate procurement splits sharply between high-frequency disposable contracts and premium reusable programs. Understanding where volume concentrates versus where margins thicken enables suppliers to calibrate manufacturing investments and certification spending.
Product Type:
Volume flows overwhelmingly through single-use channels, while premium capture concentrates in durable tableware with extended replacement cycles.
- Disposable:Heat-pressed moso bamboo fiber plates with food-grade binders serve institutional catering and quick-service contracts. Procurement officers in German and Dutch restaurant groups source these under EU Green Deal compliance mandates, accepting higher unit costs than petroleum-based alternatives to avoid extended producer responsibility penalties.
- Reusable:Laminated bamboo dinnerware with reinforced edges withstands commercial dishwasher cycles. Michelin-starred kitchens in Paris and London specify these for front-of-house service, driving three-tier pricing stratification based on finish quality and antimicrobial coating specifications.
- Biodegradable:EN 13432-certified plates engineered for industrial composting facilities.
- Eco-Friendly:Uncertified but marketed as sustainable alternatives with minimal processing.
Mature deployment sits with Reusable. Newer deployment is concentrated in Biodegradable.
Distribution Channel:
Channel selection determines margin retention and customer relationship depth, with wholesale controlling institutional volume while direct models capture recurring revenue.
- Retail Stores:Specialty kitchenware chains and eco-lifestyle boutiques stock premium bamboo plate sets. Panabam leverages its European retail footprint to secure endcap placement in German and French urban centers where sustainability-marked products command shelf space.
- Online Sales:Direct-to-consumer specialists bypass wholesale markups through subscription and bulk-purchase models. The channel is expanding most quickly among wedding and corporate gifting segments where laser-etching personalization drives premium positioning.
- Wholesale:Volume flows to restaurant groups and event management companies through distributor networks.
- Direct Sales:Manufacturer-to-venue rental models for reusable dinnerware capture recurring revenue streams.
Established procurement patterns sit with Wholesale. Channel innovation is concentrated in Direct Sales.
End User:
User segmentation reveals divergent performance requirements between household occasional use and commercial high-cycle environments.
- Restaurants:Front-of-house and back-of-house operations demand distinct specifications—fine dining requires polished finishes and antimicrobial coatings, while casual concepts prioritize cost-efficient disposables. Sustainability officers in German corporate catering contracts now override purchasing managers, prioritizing BPI or TÜV Austria OK Compost HOME labels.
- Caterers:Mobile foodservice operations require lightweight, stackable inventory with rapid turnover. Swedish, Danish, and Finnish markets present underpenetrated whitespace despite stringent national plastic restrictions.
- Households:Occasional-use consumers purchasing through retail and online channels.
- Events:Single-occasion bulk procurement for weddings, festivals, and corporate functions.
Institutional procurement maturity sits with Restaurants. Volume expansion is concentrated in Caterers.
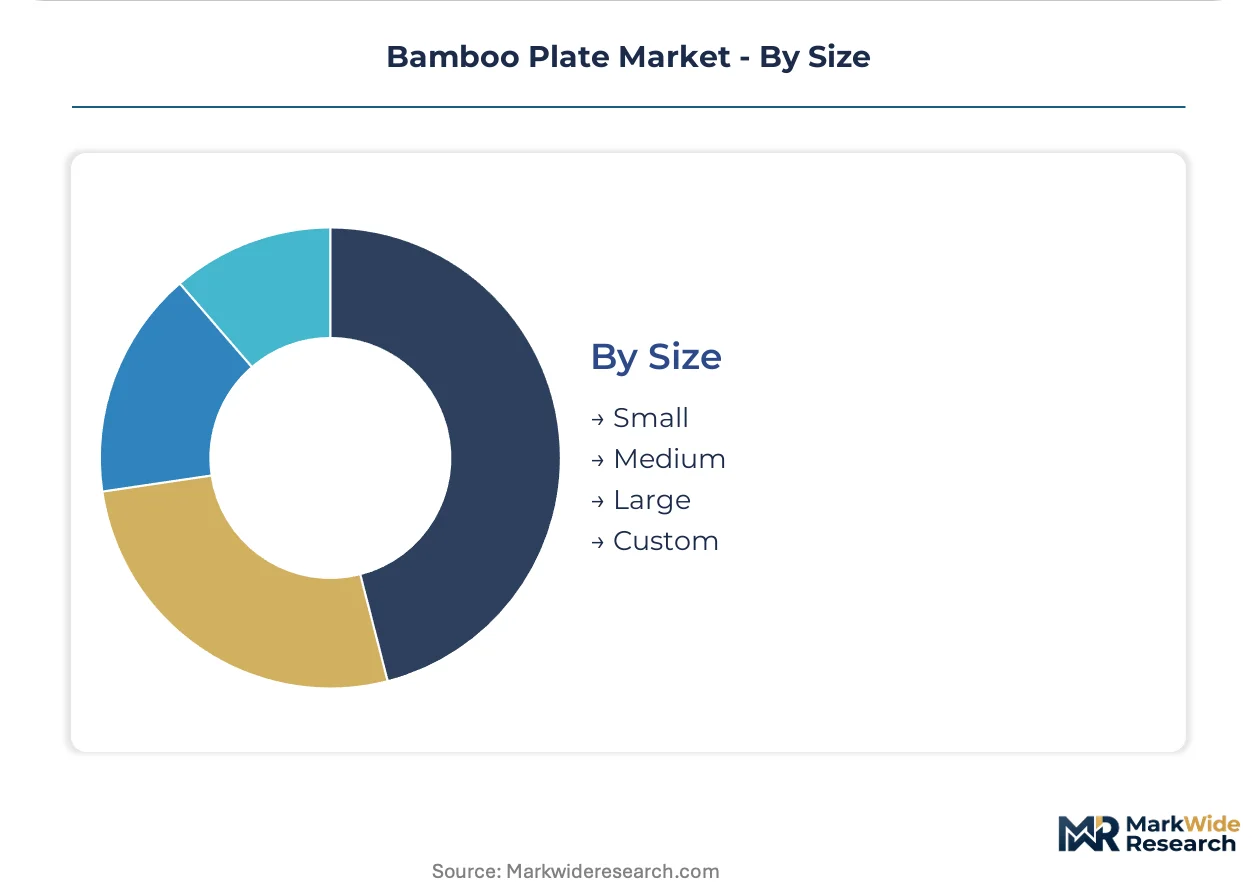
Size:
Size specification correlates with end-use formality and portion requirements, driving differentiated manufacturing setups.
- Large:Dinner plates and serving platters for full-course presentation. Heat-press equipment capex intensity constrains mid-tier manufacturer expansion in this format, concentrating supply among Zhejiang Province integrated processors with captive lamination capacity.
- Custom:Dimensional and shape specifications for branded hospitality programs. REACH restrictions on formaldehyde-releasing binders force reformulation of adhesive systems for structural integrity validation.
- Small:Appetizer and dessert plates for tasting menus and catering.
- Medium:Standard lunch and casual dining formats.
Standardized production sits with Medium. Specification complexity is concentrated in Custom.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Anji County in Zhejiang Province anchors global bamboo plate manufacturing through integrated fiber processing clusters that supply laminated raw materials to converters worldwide. Restaurant procurement patterns diverge sharply across regulatory environments, with EU Green Deal compliance deadlines compressing substitution timelines in Western European foodservice channels.
Germany
Corporate catering contracts in Berlin and Munich now mandate compostable serviceware under national packaging law implementations. Extended producer responsibility frameworks impose financial penalties on restaurant groups maintaining non-compliant disposable inventories. Sustainability officers in Frankfurt-based hospitality conglomerates override traditional purchasing managers, prioritizing TÜV Austria OK Compost HOME certification over unit cost metrics.
France
Michelin-starred kitchens in Paris specify antimicrobial-coated bamboo dinnerware for front-of-house presentation, driving premium-tier procurement. REACH restrictions on formaldehyde-releasing binders force laminated processors to reformulate adhesive systems for structural integrity. Small-batch artisan producers in Provence capture specialty retail shelf space with certified zero-formaldehyde offerings.
Netherlands
Institutional foodservice operators in Amsterdam and Rotterdam face accelerated plastic phase-out timelines under EU Packaging and Packaging Waste Regulation transposition. Wholesale distributor networks concentrate in Randstad logistics corridors, channeling volume to restaurant groups and event management companies. EN 13432 certification documentation requirements have doubled vendor qualification timelines for procurement officers.
China
Heat-press manufacturing capacity concentrates in eastern provinces, with Zhejiang's integrated bamboo processing clusters enabling cost-competitive laminated fiber production. GB standards govern domestic food contact material compliance, creating divergent qualification pathways from EU and US regulatory frameworks. Weather-driven harvest fluctuations in subtropical growing zones generate raw material price instability for fiber processors.
United States
FDA food contact substance notifications govern import clearance for bamboo-composite serviceware entering through West Coast ports. Direct-to-consumer specialists in California bypass wholesale markups through subscription and bulk-purchase models. Wedding and corporate gifting segments in New York and Los Angeles drive laser-etching personalization demand for premium positioning.
Bamboo Plate Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification and finish quality tiers, with three-tier pricing stratification separating antimicrobial-coated specifications from untreated commodity plates. The vendor base organizes around raw material control, retail footprint scale, and foodservice channel specialization. Three archetypes dominate: Zhejiang-based integrated processors with captive lamination capacity, European distributors commanding specialty kitchenware shelf space, and direct-to-consumer specialists capturing recurring revenue through personalization services. Capacity expansion and certification portfolio diversification represent the dominant competitive moves as compliance deadlines compress procurement windows.
Within the integrated processor tier, Yi Bamboo exemplifies raw material control through direct sourcing from Anji County, while Xiamen Ebei Import and Export Co. Ltd occupies a position among Fujian-based fabricators with export-oriented production scale. PacknWood represents the foodservice specialization archetype, anchoring premium positioning through supply relationships with Michelin-starred establishments in Paris and London.
| Leading Market Players |
|---|
| Panabam |
| Yi Bamboo |
| PacknWood |
| Xiamen Ebei Import and Export Co. Ltd |
| BambooVision |
| bambu LLC |
| You Cheng |
| Pefso Co. Ltd |
| Mann Bamboo Fiber Ware Co. Ltd |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap processors in Zhejiang Province anchor supply discipline through captive lamination capacity, translating raw material control into pricing power over commodity converters lacking backward integration into Anji County fiber sourcing. This ownership pattern compresses margins for wholesale distributors while enabling three-tier pricing stratification across certification tiers.
Pricing Analysis
Value-based pricing anchored to EN 13432 certification outcomes dominates procurement contracts, with TÜV Austria OK Compost HOME labels commanding premium placement over uncertified alternatives. Price differentiation rests on antimicrobial coating specifications and formaldehyde-free adhesive validation, with German sustainability officers least sensitive to unit cost and Dutch institutional caterers most responsive to per-plate economics. Cost compression in untreated commodity tiers is intensifying because REACH-mandated binder reformulation is raising processor compliance overhead.
Supply Chain Analysis
Single-source vulnerability sits with heat-press manufacturing capacity concentrated in Zhejiang, Fujian, and Jiangsu provinces, where weather-driven moso bamboo harvest fluctuations generate raw material price instability. Laminated fiber production draws from subtropical growing zones, food-grade plant-based binders, and industrial composting certification services, with tariff exposure on EU-bound shipments representing the dominant structural risk. Distribution runs through Randstad logistics corridors and German wholesale networks to restaurant groups and event management companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where EN 13432 certification friction and heat-press equipment capex intensity force smaller converters into distressed sales or contract manufacturing relationships.
For Market Incumbents: Deepen upstream control over Anji County fiber processing clusters to defend margin position against Zhejiang-based integrated competitors expanding into European direct sales. Prioritize TÜV Austria certification portfolio diversification ahead of EU Packaging and Packaging Waste Regulation implementation deadlines compressing vendor qualification windows. For New Entrants and Emerging Players: Enter via underpenetrated Nordic markets where Swedish, Danish, and Finnish institutional caterers face plastic restriction mandates without established bamboo plate supply relationships. Target direct-to-venue rental models for reusable dinnerware, bypassing wholesale markups through recurring revenue structures in wedding and corporate gifting segments. For Investors and Strategic Acquirers: Distressed-cycle entries favor Zhejiang-based processors with captive lamination capacity but weak EU distribution relationships, particularly those facing working capital constraints from extended compostability testing timelines. Watch for inflection signals in German corporate catering contract RFP volumes as extended producer responsibility penalty enforcement tightens.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Processing | Anji County captive sourcing insulates margin from weather-driven raw material volatility. |
| Certification Portfolio Diversification | TÜV Austria OK Compost HOME labeling unlocks German institutional procurement channels. |
| Direct-to-Venue Rental Model Launch | Recurring revenue structures bypass wholesale markups in event management channels. |
| Antimicrobial Coating R&D Investment | Chitosan and tea polyphenol finishes command Michelin-starred kitchen specifications. |
| Nordic Market Distribution Partnership | First-mover positioning in Sweden, Denmark, and Finland captures whitespace ahead of compliance deadlines. |
Methodological Framework
Trade customs data, EU regulatory filings, and foodservice procurement databases formed the secondary backbone, cross-referenced with primary interviews involving sustainability officers at German restaurant groups, procurement managers at Dutch catering operators, Zhejiang-based fiber processors, and EN 13432 certification laboratory directors. Bottom-up volume estimates from laminated fiber production capacities were triangulated against top-down substitution rates for petroleum-based disposables under EU Green Deal mandates.
Historical trendline analysis of compostable serviceware adoption patterns informed the projection framework across product type, distribution channel, end user, and size segmentation dimensions. CAGRs were derived from elasticity modeling of regulatory compliance deadlines against price differentials with plastic alternatives, incorporating heat-press equipment deployment cycles and certification timeline lags as industry-specific forecast inputs throughout the modeling period.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged EN 13432 documentation delays or acute moso bamboo harvest disruptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Europe Canned Food Packaging Market
Food Packaging
Meat, Poultry, and Seafood Packaging Market
Food Packaging
Latin America Canned Food Packaging Market
Food Packaging
Cereal Packaging Market
Food Packaging
Processed Meat Packaging Market
Food Packaging
Chilled Food Packaging Market
Food Packaging
North America Food Packaging Market
Food Packaging
Asia-Pacific Skin Packaging for Fresh Meat Market
Food Packaging
Egg Cartons Market
Food Packaging
Spreads and Toppings Packaging Market
Food Packaging
Nordic Beverage Packaging Market
Food Packaging
Global Disposable Plates Market
Food Packaging
Frozen Food Packaging Market
Food Packaging
Disposable Hot Cups & Lids Market
Food Packaging
Food Can Market
Food Packaging
Europe Food Packaging Market