
 Global Paper Straw Market | 2026-2036
Global Paper Straw Market Size, Share, and Industry Trends Forecast 2026-2036
Global Paper Straw Market Outlook
Asian kraft paper producers is broadening output of food-grade pulp substrates to serve converting lines in Europe and North America. Huhtamaki Oyj leverages integrated converting assets across multiple continents to secure food-service contracts. Hoffmaster Group, Inc. anchors North American supply through specialized disposable-tableware distribution. Transcend Packaging Ltd. dominates United Kingdom quick-service accounts with certified compostable specifications.
Paper straws are cylindrical beverage-conveyance devices fabricated from bonded kraft paper layers with water-resistant adhesive systems, typically rated for 30-60 minute liquid immersion without structural failure. Their primary commercial purpose is to replace petroleum-based plastic straws in regulated food-service environments. Wrapped product configurations command premium placement in full-service hospitality settings where hygiene presentation drives procurement. Food service end users represent the dominant volume pool as quick-service chains execute plastic-phaseout commitments. Compostable-grade materials capture margin concentration where municipal organics-collection infrastructure exists.
The European Union's Single-Use Plastics Directive and the United States FDA food-contact regulations jointly determine material-safety thresholds and market-access conditions for cross-border suppliers. China's GB standards for paper products and Japan's JIS food-hygiene specifications add compliance layers for Asia-Pacific sourcing channels. Stakeholders must monitor evolving compostability-certification requirements across municipal waste systems before committing capital to regional capacity expansion.
Market Dynamics
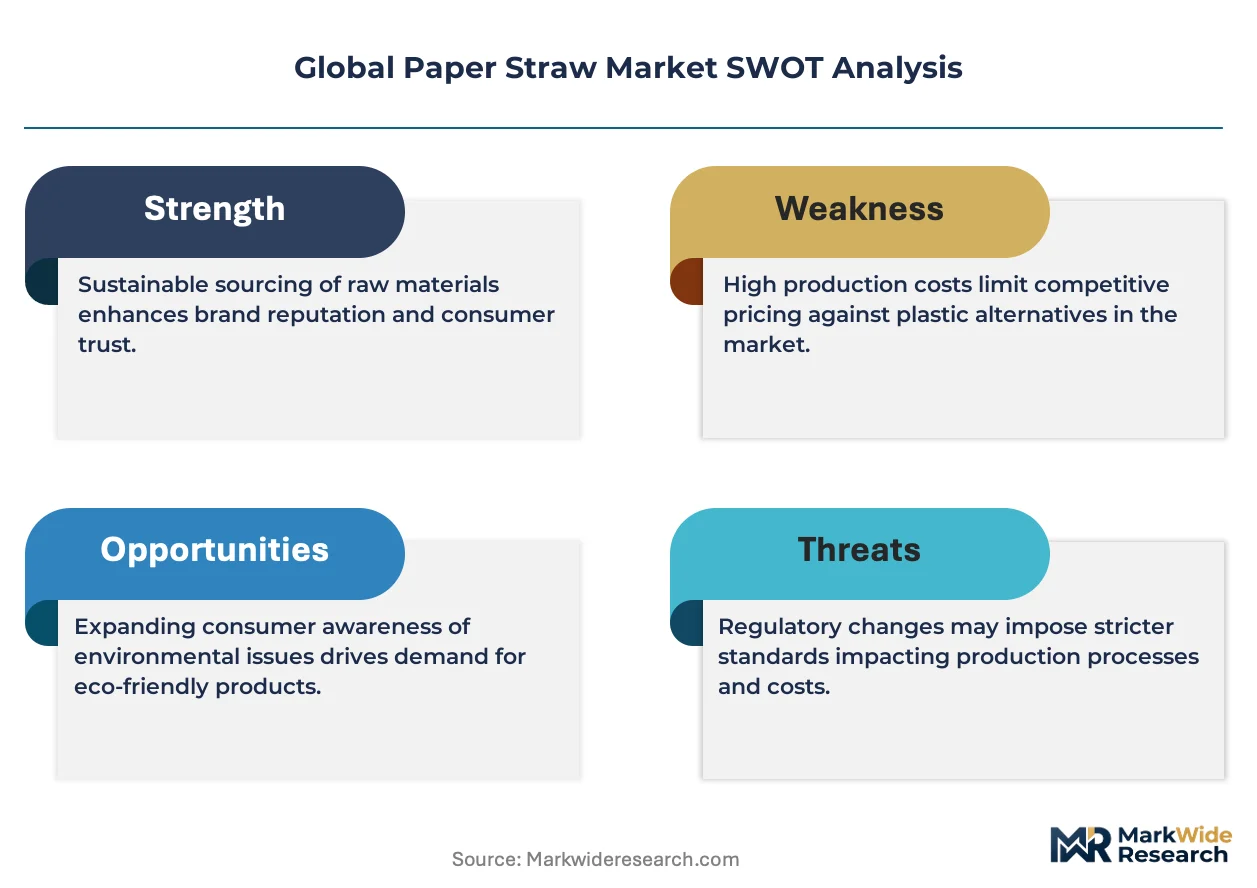
The EU Single-Use Plastics Directive and parallel FDA food-contact compliance requirements are forcing converters to requalify adhesive chemistries and substrate grades, compressing formulation flexibility while opening certified-supplier premiums.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandated phase-outs of conventional plastic straws across member states are pulling forward replacement demand from quick-service chains and institutional food service.
- Kraft paper substrate innovation:Food-grade pulp treatments with enhanced wet-strength bonding are extending functional immersion windows, satisfying full-service hospitality specifications.
- United States:Major beverage brands have committed to sustainable packaging roadmaps, locking in multi-year supply agreements with certified converters.
Market Restraints
- Pulp input volatility:Bleached kraft pulp prices fluctuate with Nordic and Canadian softwood harvest cycles, squeezing converter margins during supply tightness.
- Composting infrastructure gaps:Municipal organics-collection systems remain underdeveloped across most US metropolitan areas, limiting premium-grade material uptake.
- Polypropylene straw substitution:Reusable and durable plastic alternatives retain cost advantages in unregulated food-service segments.
Strategic Opportunities
- India:Quick-service restaurant expansion and FSSAI packaging safety mandates are creating first-mover advantages for certified importers.
- Pharmaceutical liquid dosing:Sterile, single-use paper straws for pediatric and geriatric formulations represent an emerging high-margin application.
- Extended Producer Responsibility frameworks:EU and UK packaging-waste regulations are shifting cost accountability upstream, favoring vertically integrated substrate-to-converter operations.
Industry Challenges
- Adhesive chemist talent scarcity:Food-safe, water-resistant bonding expertise sits concentrated with legacy packaging specialists, constraining new-entrant R&D velocity.
- Compostability-certification timelines:Multi-jurisdictional testing for TÜV OK compost HOME and INDUSTRIAL marks delays product launches by 12-18 months.
- Legacy equipment retrofit costs:Converting lines engineered for plastic extrusion require capital-intensive reconfiguration to handle paper web tension and adhesive curing profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Paper Straw Market |
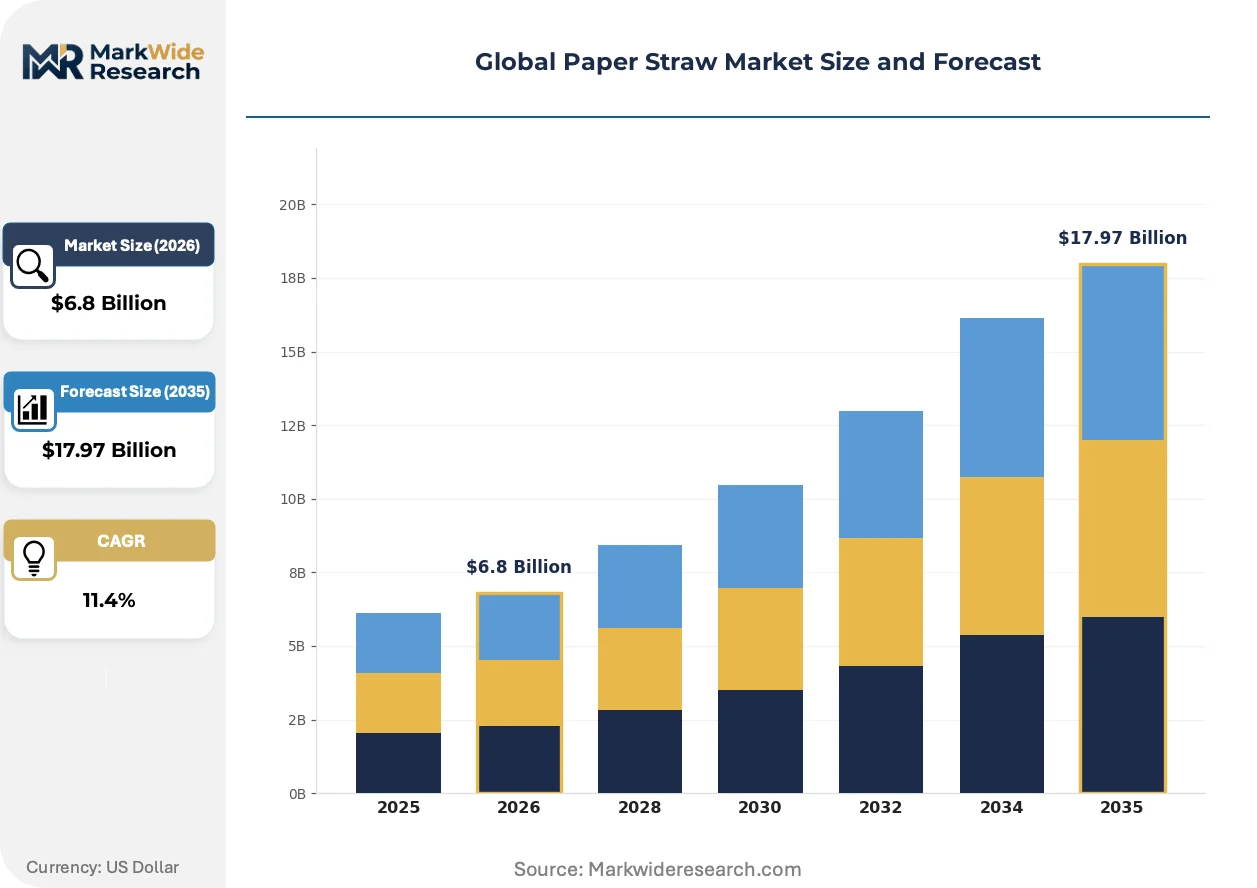
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unwrapped, Wrapped, Biodegradable, Compostable End User: Food Service, Retail, Hospitality, Events Diameter: Standard, Large, Extra Large, Mini Distribution Channel: Online, Retail Stores, Wholesale, Direct Sales |
| Companies Covered | Hoffmaster Group, Inc., Huhtamaki Oyj, Transcend Packaging Ltd., Footprint, BioPak, Novolex, Aardvark Straws LLC, Nippon Paper Industries Co. Ltd., Tetra Laval Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Paper Straw Market Strategic Shifts
Adhesive chemistry evolution and regulatory certification layering are compressing product development cycles while fragmenting competitive advantage around technical compliance rather than scale alone.
Multi-layer kraft paper laminates with bio-based water-resistant adhesives are absorbing structural stress from extended liquid immersion. Quick-service chains in Germany and France are adopting these specifications for cold-beverage applications. The technology is absorbing margin pressure from shorter usage windows, enabling converters to defend premium positioning against conventional plastic alternatives.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant chemistries from food-contact applications. European converters must reformulate barrier coatings or forfeit market access. Full-service hospitality chains in Italy and Spain are accelerating supplier audits to preempt compliance failures.
Direct procurement relationships between quick-service chains and substrate mills are disintermediating traditional distribution tiers. Large beverage brands now specify pulp grades and adhesive systems rather than accepting converter recommendations. This pattern concentrates most visibly in the United States, where centralized sustainability offices negotiate master supply agreements spanning thousands of franchise locations.
Global Paper Straw Market Segmentation
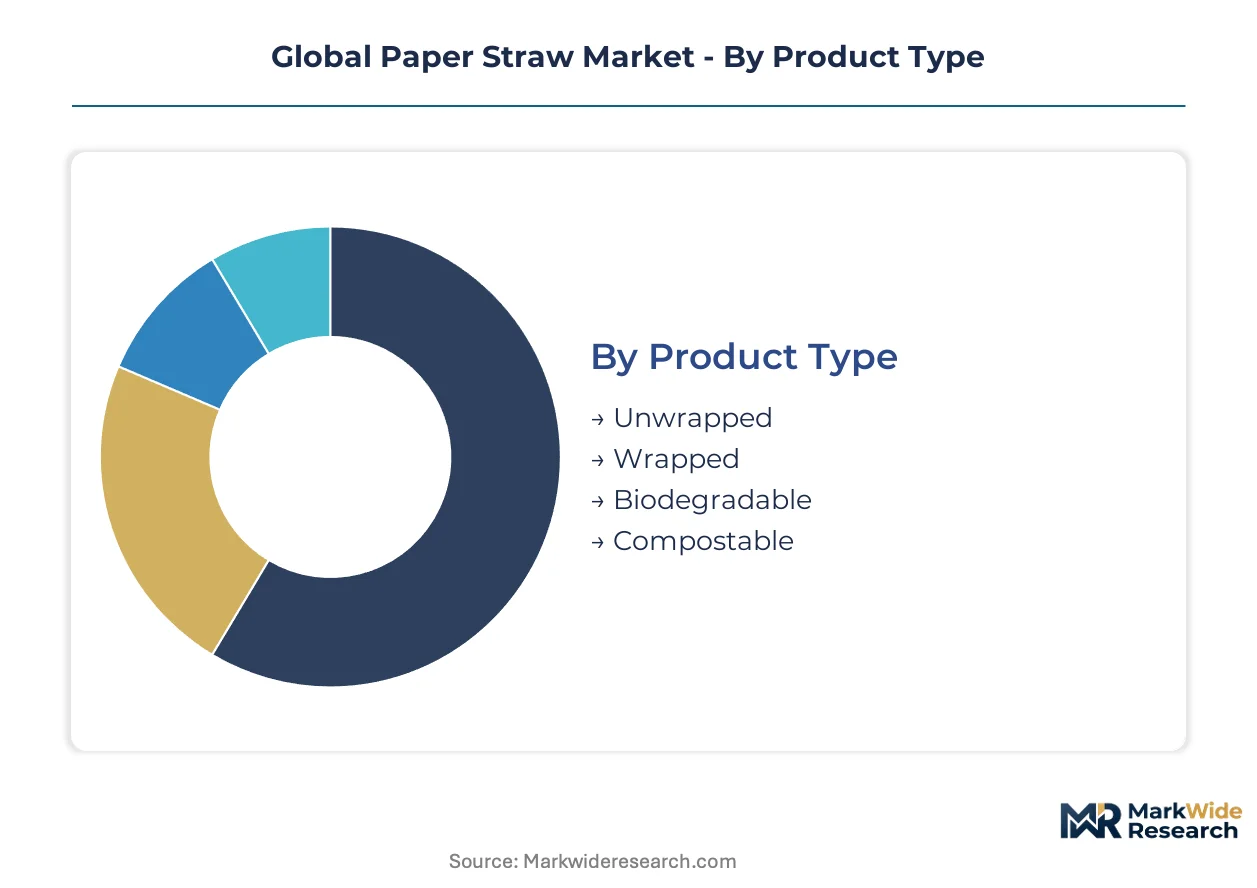
Paper straw procurement patterns diverge sharply between embedded food-service supply chains and standalone retail purchases. Converters must configure production lines differently for each integration depth, as wrapped specifications for hospitality carry hygiene-certification requirements absent from unwrapped bulk food-service contracts.
Product Type:
Integration depth separates segments that ship as standalone consumer units versus those embedded in institutional procurement systems.
- Wrapped:Individual paper or film sleeves enclose each straw, satisfying full-service hospitality hygiene protocols. Demand clusters in United States and United Kingdom hotel chains where front-of-house presentation drives specification. FDA and EU food-contact compliance requirements elevate certified-supplier premiums above unwrapped alternatives.
- Compostable:TÜV OK compost HOME and INDUSTRIAL certification enables disposal through municipal organics streams. Germany and France quick-service chains specify these grades where collection infrastructure exists. Certification timelines of 12-18 months constrain supply elasticity.
- Unwrapped:Bulk configurations serve high-volume food-service accounts with back-of-house dispensing systems.
- Biodegradable:Broader decomposition claims without specific composting-standard verification appeal to price-sensitive retail channels.
Volume placements concentrate in Unwrapped; the faster expansion belongs to Compostable.
End User:
Customer procurement sophistication determines margin capture, with centralized sustainability offices commanding specification authority over fragmented operators.
- Food Service:Quick-service restaurant chains execute plastic-phaseout commitments through multi-year master supply agreements. United States beverage brands centralize procurement across thousands of franchise locations, specifying pulp grades and adhesive systems directly. This segment absorbs the majority of converter capacity.
- Hospitality:Full-service hotels and restaurants prioritize wrapped configurations with premium presentation characteristics. Italy and Spain chains accelerate supplier audits to preempt REACH compliance failures on barrier coatings.
- Retail:Consumer-packaged formats through grocery and convenience channels.
- Events:Temporary large-scale consumption occasions with variable quality tolerance.
Procurement centralization favors Food Service for volume; Hospitality delivers superior per-unit margins.
Diameter:
Functional performance requirements scale with beverage viscosity and consumption duration.
- Standard:6-8mm internal diameter serves carbonated soft drinks and chilled water across quick-service applications. United States chains specify these for fountain beverage programs. Wet-strength bonding must sustain 30-60 minute immersion without structural failure.
- Large:10-12mm diameter accommodates smoothies and milkshakes with higher particulate content. Demand concentrates in European coffeehouse chains expanding cold-beverage menus.
- Extra Large:Specialized configurations for thick formulations and bubble-tea applications.
- Mini:Reduced-diameter specifications for cocktail and sample-size portions.
Standard diameter commands absolute unit volume; Large specifications are climbing the fastest.
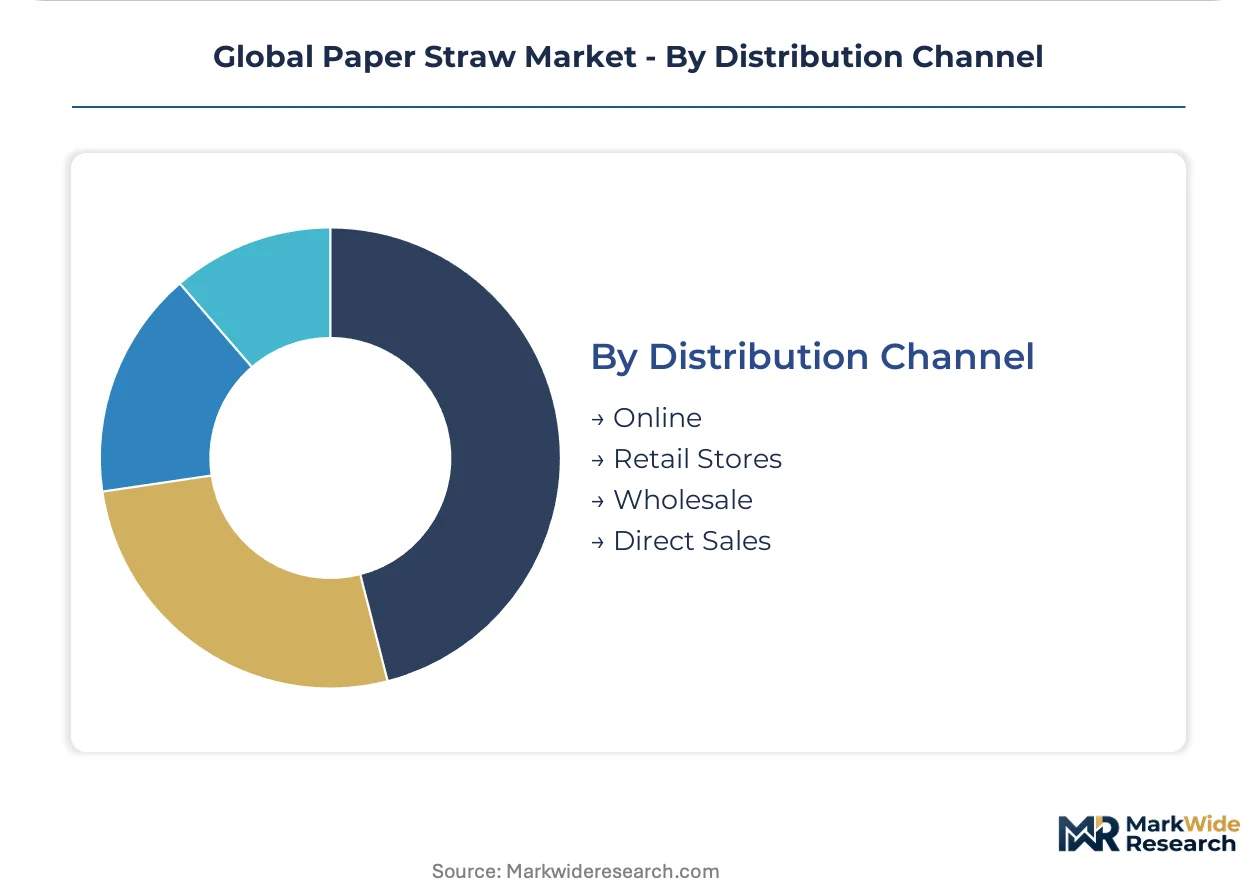
Distribution Channel:
Channel selection reflects buyer scale and technical specification complexity.
- Direct Sales:Large beverage brands and quick-service chains negotiate directly with substrate mills and converters, disintermediating traditional distribution. United States sustainability offices specify adhesive chemistries and pulp grades across continental networks.
- Wholesale:Specialized disposable-tableware distributors aggregate fragmented food-service demand. Hoffmaster Group anchors North American supply through this channel.
- Online:E-commerce platforms serve small-format retail and event procurement with limited technical requirements.
- Retail Stores:Brick-and-mortar consumer packaged goods placement.
Wholesale retains volume dominance among mid-tier operators; Direct Sales is gaining share fastest as procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nordic softwood pulp from Swedish and Finnish mills anchors substrate supply for European and North American converting lines. Asian kraft paper producers in China and Indonesia are expanding food-grade capacity to serve export demand. Regulatory phase-outs of plastic straws across multiple jurisdictions are redrawing procurement geography.
United States
Major beverage brands and quick-service chains execute centralized plastic-phaseout commitments through multi-year supply agreements. FDA food-contact regulations govern adhesive chemistry and substrate safety thresholds for cross-border suppliers. Converting capacity concentrates in the Midwest and Southeast, where specialized disposable-tableware distributors anchor supply networks for franchise operators.
Germany
Quick-service chains specify compostable-grade straws where municipal organics-collection infrastructure supports disposal. REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy barrier coatings from food-contact applications. Industrial clusters in Bavaria and North Rhine-Westphalia host converters reformulating adhesive systems to maintain market access.
China
GB standards for paper products add compliance layers for domestic producers targeting export channels. Kraft paper mills in Shandong and Guangdong provinces are broadening food-grade pulp substrate output. Converting lines in the Yangtze River Delta serve European and North American quick-service accounts with certified specifications.
United Kingdom
Extended Producer Responsibility frameworks are shifting cost accountability upstream to substrate-to-converter operations. Quick-service accounts specify certified compostable grades where collection infrastructure exists. Converting capacity in England dominates quick-service supply, with suppliers securing multi-year contracts against plastic-phaseout deadlines.
India
Quick-service restaurant expansion and FSSAI packaging safety mandates are creating procurement windows for certified importers. Food-grade substrate imports from Southeast Asian mills serve converting lines near Mumbai and Delhi. Domestic pulp treatment capabilities remain limited, constraining local supply elasticity against demand acceleration.
Global Paper Straw Market Competitive Environment
Global majors compete with regional champions across certification depth and substrate integration. The vendor base stratifies around three archetypes: integrated packaging conglomerates with captive pulp supply, specialized disposable-tableware converters with distribution scale, and substrate-focused mills backward integrating into finished goods. Consolidation pressure concentrates among mid-tier operators lacking certified adhesive expertise or compostability credentials. Dominant competitive moves include direct procurement relationships disintermediating distribution tiers and geographic expansion through regulatory-first market entry.
Among integrated packaging specialists, Huhtamaki Oyj exemplifies the multinational archetype with converting assets spanning multiple continents. Hoffmaster Group, Inc. occupies a position within North American distribution-centric supply, while Transcend Packaging Ltd. represents the regional champion model with concentrated quick-service penetration in the United Kingdom. These three anchors illustrate divergent scale-versus-specialization trade-offs shaping competitive positioning.
| Leading Market Players |
|---|
| Hoffmaster Group, Inc. |
| Huhtamaki Oyj |
| Transcend Packaging Ltd. |
| Footprint |
| BioPak |
| Novolex |
| Aardvark Straws LLC |
| Nippon Paper Industries Co. Ltd. |
| Tetra Laval Group |
| Others |
Value Chain & Pricing Dynamics
Captive substrate-to-converter integration anchors pricing power for certified suppliers serving quick-service chains with multi-year master agreements. Nordic pulp mills and integrated packaging conglomerates leverage backward control over food-grade kraft supply to defend margin positions against spot-market converters. This structural concentration amplifies premium capture where FDA and EU food-contact compliance creates non-substitutable supplier relationships.
Pricing Analysis
Certification-bundling separates quoted prices: TÜV OK compost HOME and INDUSTRIAL marks carry 12-18 month validation timelines embedded in contract terms. Three-tier pricing structure across compostable-certified, wrapped-hospitality, and unwrapped food-service levels tracks adhesive chemistry complexity and pulp grade specification. Cost compression in standard unwrapped tiers is intensifying because Asian kraft mills are expanding food-grade capacity for export. Quick-service chains with centralized procurement offices exhibit lowest price sensitivity; fragmented event and retail channels absorb greatest margin pressure.
Supply Chain Analysis
Ocean freight differentials between Nordic softwood pulp origins and Southeast Asian converting hubs feed into landed cost structures for cross-border suppliers. Raw material sourcing draws from Swedish and Finnish bleached kraft pulp mills, Indonesian and Chinese food-grade paper producers, and specialized bio-based adhesive formulators in Germany and the United States. Single-source vulnerability concentrates in certified adhesive chemistry expertise held by legacy packaging specialists. Distribution runs through specialized disposable-tableware wholesalers anchoring North American mid-tier food-service supply, with direct mill relationships displacing traditional tiers among large beverage brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Single-Use Plastics Directive and REACH per- and polyfluoroalkyl substance restrictions have erected a cost-of-compliance moat that filters out uncertified competitors and consolidates margin capture among validated suppliers.
For Market Incumbents: Hedge against polypropylene reusable straw substitution in unregulated segments by deepening captive pulp supply arrangements with Nordic mills. Prioritize TÜV OK compost INDUSTRIAL certification investment to lock out mid-tier converters lacking 12-18 month validation timelines. Channel control through direct procurement relationships with quick-service sustainability offices reinforces pricing power against wholesale-distributor erosion.
For New Entrants and Emerging Players: Begin with India quick-service restaurant expansion corridors where FSSAI packaging safety mandates are creating first-mover windows for certified importers. Target pharmaceutical liquid dosing applications for pediatric and geriatric formulations as a high-margin white space with limited incumbent specialization. A regulatory-first market entry strategy—securing compostability credentials before capacity buildout—secures shelf space in German and French municipal organics-collection zones.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated packaging conglomerates seeking substrate-to-converter vertical control. Long-term viability hinges on 5-10 year regulatory durability of single-use plastic phase-outs across multiple jurisdictions. The signal to watch is REACH barrier-coating reformulation compliance failures among European converters, which will trigger distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Compostability Certification Investment | TÜV OK compost HOME and INDUSTRIAL marks unlock German and French quick-service supply contracts. |
| Backward Integration into Kraft Pulp Supply | Nordic softwood pulp captive arrangements defend margins against Asian export price volatility. |
| Direct Procurement Relationship Development | United States beverage brand sustainability offices specify adhesive chemistries across continental networks. |
| Pharmaceutical Application Diversification | Sterile single-use paper straws for pediatric dosing command premium positioning in healthcare channels. |
| Regulatory-First Geographic Expansion | India FSSAI compliance anchoring creates defensible positioning against later entrant price competition. |
Study Parameters
Multi-period observation of pulp price indices, certification timeline distributions, and quick-service plastic-phaseout commitments anchored the trend analysis, supplemented by interviews with food-grade adhesive R&D directors, quick-service procurement executives, disposable-tableware distribution channel managers, and municipal waste-system policy officers. Secondary validation drew from EU Single-Use Plastics Directive implementation tracking, FDA food-contact guidance updates, TÜV certification registry data, and Nordic pulp mill production disclosures. Bottom-up converter capacity modeling and top-down quick-service demand aggregation were triangulated against trade flow data.
Input-output matrices mapped kraft pulp substrate supply through adhesive formulation, converting line configuration, and distribution channel segmentation across the analysis window. Modeled dimensions included product type integration depth, end-user procurement centralization, diameter functional requirements, and regional regulatory framework clusters. CAGRs were derived from elasticity-adjusted demand curves incorporating quick-service commitment timelines and municipal organics-collection infrastructure rollouts. Forecast inputs included REACH chemical restriction evolution and FDA adhesive chemistry requalification patterns.
Underlying measurement precision varies by segment; compostable-certified and wrapped-hospitality categories carry tighter precision than unwrapped bulk food-service tiers due to certification registry granularity. Forecasts reflect documented assumptions on regulatory phase-out adherence and pulp harvest cycle normalization. Pulp input volatility, composting infrastructure deployment delays, and polypropylene substitution elasticity in unregulated channels represent revision risks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
Zero Waste Packaging Market
Sustainable Packaging
Europe Sustainable Packaging Market
Sustainable Packaging
PVC-Free Packaging Market
Sustainable Packaging
Europe Green Packaging Market
Sustainable Packaging
Japan Green Packaging Market
Sustainable Packaging
GCC Green Packaging Market
Sustainable Packaging
Eco Friendly Bottles Market
Sustainable Packaging
Sustainable Foodservice Packaging Market
Sustainable Packaging
Sustainable Plastic Packaging Market
Sustainable Packaging
Asia-Pacific Eco-Friendly Packaging Market
Sustainable Packaging
Eco-Friendly Straw Market
Sustainable Packaging
Asia-Pacific Sustainable Packaging Market
Sustainable Packaging
North America Eco-Friendly Packaging Market
Sustainable Packaging
Areca Plates Market
Sustainable Packaging
Wheat Straw Cutlery Market
Sustainable Packaging
Bagasse Tableware Products Market