
 Sustainable Packaging Market | 2026-2036
Sustainable Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainable Packaging Market Analysis
Multi-source procurement for biopolymer feedstocks is shifting toward vertically integrated resin production among top converters. Amcor plc anchors global flexible film capacity through captive bioplastic sourcing partnerships. Mondi plc competes with integrated kraft paper and pulp operations across European forestry networks. Huhtamaki Oyj specializes in molded fiber tooling for foodservice applications, leveraging regional manufacturing scale.
Sustainable packaging comprises materials and designs engineered to minimize environmental burden across extraction, use, and end-of-life phases, typically incorporating recycled content percentages above 30% or biodegradability certifications under ASTM D6400 or EN 13432 standards. Its primary purpose centers on containing, protecting, and presenting goods while reducing carbon intensity and circularity losses. Flexible packaging leads material efficiency metrics due to source reduction, though rigid containers capture premium pricing in personal care where dispensing precision matters. Recycled paper occupies mature volume positions in corrugated boxes, while bioplastics represent the fastest-expanding margin pool as polymerization costs decline.
The EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds, while the FDA governs food-contact notifications for post-consumer recycled substrates in the United States. ECHA's REACH restrictions on per- and polyfluoroalkyl substances further redirect coating chemistries toward silicone and clay barriers. Stakeholders must monitor evolving extended producer responsibility fee structures and certification harmonization between composting and mechanical recycling streams to align capital deployment with policy trajectories.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing immediate capital reallocation across converter networks, as mechanical recycling targets and extended producer responsibility fees reshape unit economics for flexible film and rigid container formats alike.
Growth Catalysts
- Extended Producer Responsibility Mandates:Germany's Verpackungsgesetz imposes strict recycling quotas on brand owners, accelerating demand for mono-material designs that simplify sortation at municipal facilities.
- Foodservice Biopolymer Adoption:Quick-service chains in France and Italy are replacing PS foam with PLA-lined molded fiber for hot-fill applications, creating pull-through for compostable certification pipelines.
- Pulp Integration Economics:Nordic forestry networks are capturing margin from kraft paper barrier coatings, as integrated pulp-to-package operations undercut merchant market resin costs.
Market Restraints
- Biopolymer Feedstock Volatility:Corn and sugarcane price swings directly compress PLA and PHA converter margins, with no viable hedge instruments trading at scale.
- Asian Base Chemical Concentration:PTA and MEG supply clusters in China create single-source vulnerability for European rPET flake producers seeking bottle-grade resin.
- PFAS Substitution Deadlock:ECHA's REACH restrictions on fluorinated barriers have outpaced viable silicone and clay coating scale-up, leaving grease-resistant food packaging without certified alternatives.
Strategic Opportunities
- Reusable Packaging Infrastructure:France's AGEC law mandates reuse targets for e-commerce by 2025, opening logistics networks for pooled crate and tote systems.
- Digital Watermark Sortation:HolyGrail 2.0 tracer technology convergence with near-infrared detection is enabling flexible film circularity where mechanical recycling previously failed.
- Pharmaceutical Compliance Services:US FDA food-contact notification bottlenecks for post-consumer recycled content create advisory revenue pools for testing laboratories certifying substrate purity.
Industry Challenges
- Composting Infrastructure Misalignment:ASTM D6400 and EN 13432 certification timelines exceed actual industrial composting facility availability in most German municipalities.
- Molded Fiber Tooling Lead Times:Foodservice converters face 18-month waits for thermoformed fiber tooling from specialized equipment builders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustainable Packaging Market |
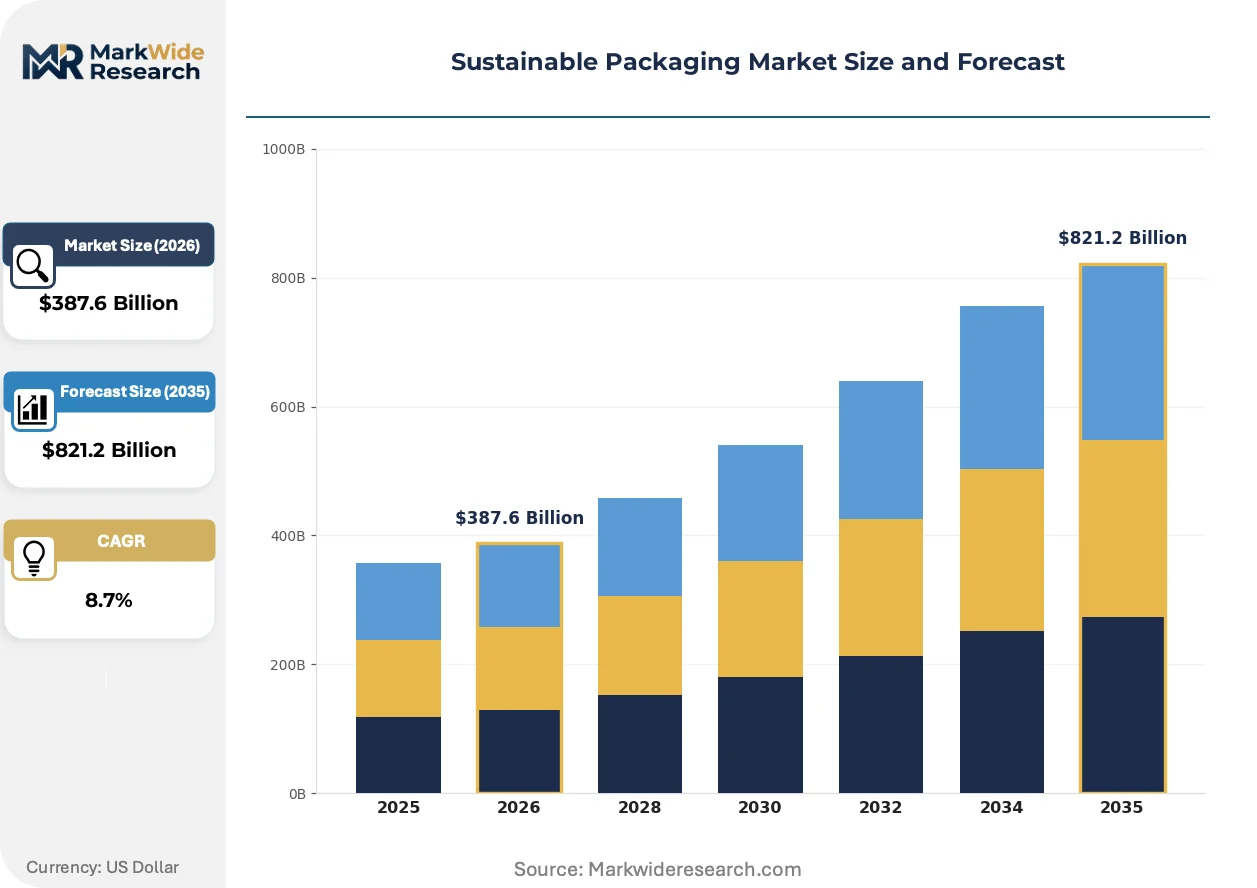
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Bioplastics, Recycled Paper, Plant-Based Materials, Glass Product Type: Flexible Packaging, Rigid Containers, Paperboards, Corrugated Boxes End User: Food & Beverage, Personal Care, Electronics, Healthcare Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Amcor plc, Tetra Pak International SA, Smurfit WestRock Company, Sonoco Products Company, Sealed Air Corporation, Berry Global Inc., Mondi plc, DS Smith, Huhtamaki Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainable Packaging Market Emerging Trajectories
Barrier coating chemistry is undergoing forced migration away from fossil-derived polymers, with mineral and bio-based alternatives capturing development budgets previously allocated to conventional multilayer films.
Silicone oxide vapor deposition is absorbing capital from metallized PET operations as snack brands seek transparent high-barrier films compatible with existing flexible packaging lines. European converters are retrofitting metallizers with SiOx chambers at pace. The technology is absorbing market share in savory applications where oxygen transmission rates below 0.5 cc/m²/day are mandatory.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant fluorinated coatings from food-contact applications by 2025. Paperboard converters are trialing clay-latex composites and plasma-enhanced chemical vapor deposition as replacements. Bakery and fast-food packaging in Germany and the Netherlands faces immediate reformulation pressure.
Brand-owner consolidation in personal care is compressing supplier rosters and unbundling sustainability certification from commodity procurement. Unilever and L'Oréal are centralizing packaging specification authority at headquarters level, demanding ISO 14001 chain-of-custody documentation from tier-two converters. This pattern concentrates most visibly in the UK and French beauty markets.
Sustainable Packaging Market Segmentation
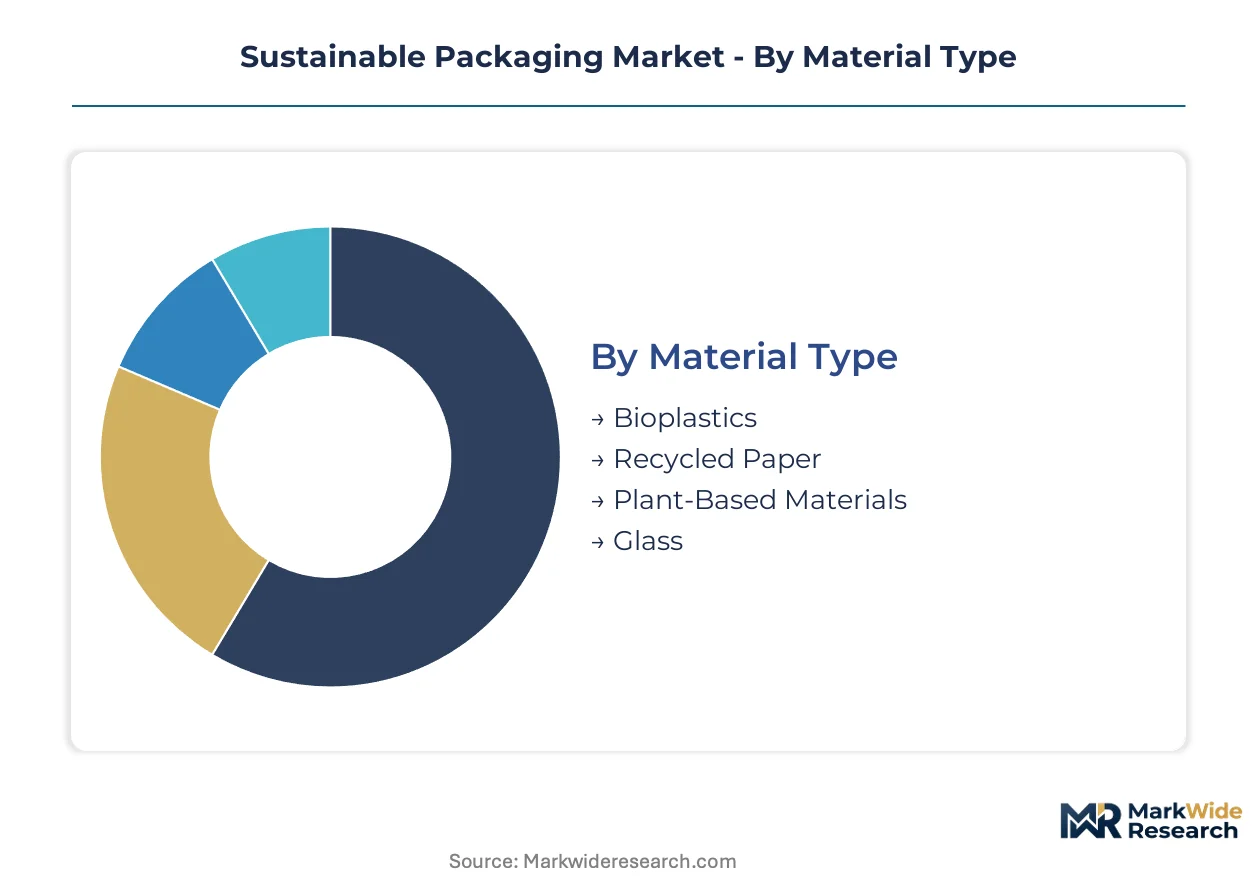
Sustainable packaging segmentation reveals divergent capital requirements and margin profiles across material technologies. Converters allocate CAPEX toward segments offering regulatory compliance certainty or feedstock security advantages.
Material Type:
Bioplastics demand the heaviest upfront investment in polymerization infrastructure and fermentation capacity, while recycled paper benefits from depreciated pulping assets.
- Bioplastics:Polylactic acid and polyhydroxyalkanoates require dedicated fermentation and purification trains. Demand concentrates in German foodservice applications where EN 13432 compostability certification satisfies Verpackungsgesetz mandates. Capital intensity limits new entrants despite premium pricing.
- Recycled Paper:Post-consumer fiber processing integrates into existing kraft mill infrastructure with lower incremental CAPEX. French and Italian corrugated converters dominate volume through established collection partnerships with municipal waste operators.
- Plant-Based Materials:Agricultural residue pulping and mycelium composites attract venture funding for pilot-scale demonstration.
- Glass:Container reuse systems in Nordic markets leverage established deposit-return infrastructure with minimal new furnace investment.
Most installed capacity flows through Recycled Paper. Expansion is steepest in Bioplastics.
Product Type:
Volume distribution skews toward formats compatible with existing filling and logistics infrastructure, while premium positioning favors rigid solutions in regulated end-uses.
- Flexible Packaging:Mono-material films and barrier-coated substrates minimize material weight per unit. German snack brands are retrofitting metallizers with silicon oxide deposition chambers to meet ECHA REACH fluorinated barrier restrictions. Line speed compatibility preserves converter switching economics.
- Corrugated Boxes:Double-wall and triple-wall constructions dominate e-commerce fulfillment through established flute standards. French AGEC law reuse targets are redirecting some demand toward pooled plastic totes, pressuring virgin linerboard growth.
- Rigid Containers:Injection-molded biopolymer jars and bottles capture personal care applications requiring dispensing precision.
- Paperboards:Folding cartons with clay-latex barrier coatings are displacing polyethylene extrusion in bakery packaging.
Corrugated Boxes carry the highest throughput tonnage. Flexible Packaging is gaining share fastest in food-contact conversions.
End User:
Regulatory exposure and shelf-life requirements create divergent specification intensity across customer verticals.
- Food & Beverage:Oxygen and moisture barrier demands dominate material selection, with hot-fill and retort applications requiring specialized heat-resistant biopolymers. Italian pasta brands and French dairy processors are specifying PLA-lined molded fiber for ready-meal trays.
- Personal Care:Dispensing precision and aesthetic finish sustain rigid container preference. UK and French beauty markets are centralizing procurement authority at headquarters level, demanding ISO 14001 chain-of-custody documentation.
- Healthcare:Sterility assurance and child-resistance compliance limit material substitution flexibility.
- Electronics:Static-dissipative molded fiber is displacing expanded polystyrene in German consumer electronics fulfillment.
Food & Beverage commands the largest volume commitment. Personal Care is expanding most quickly on premium positioning.
Distribution Channel:
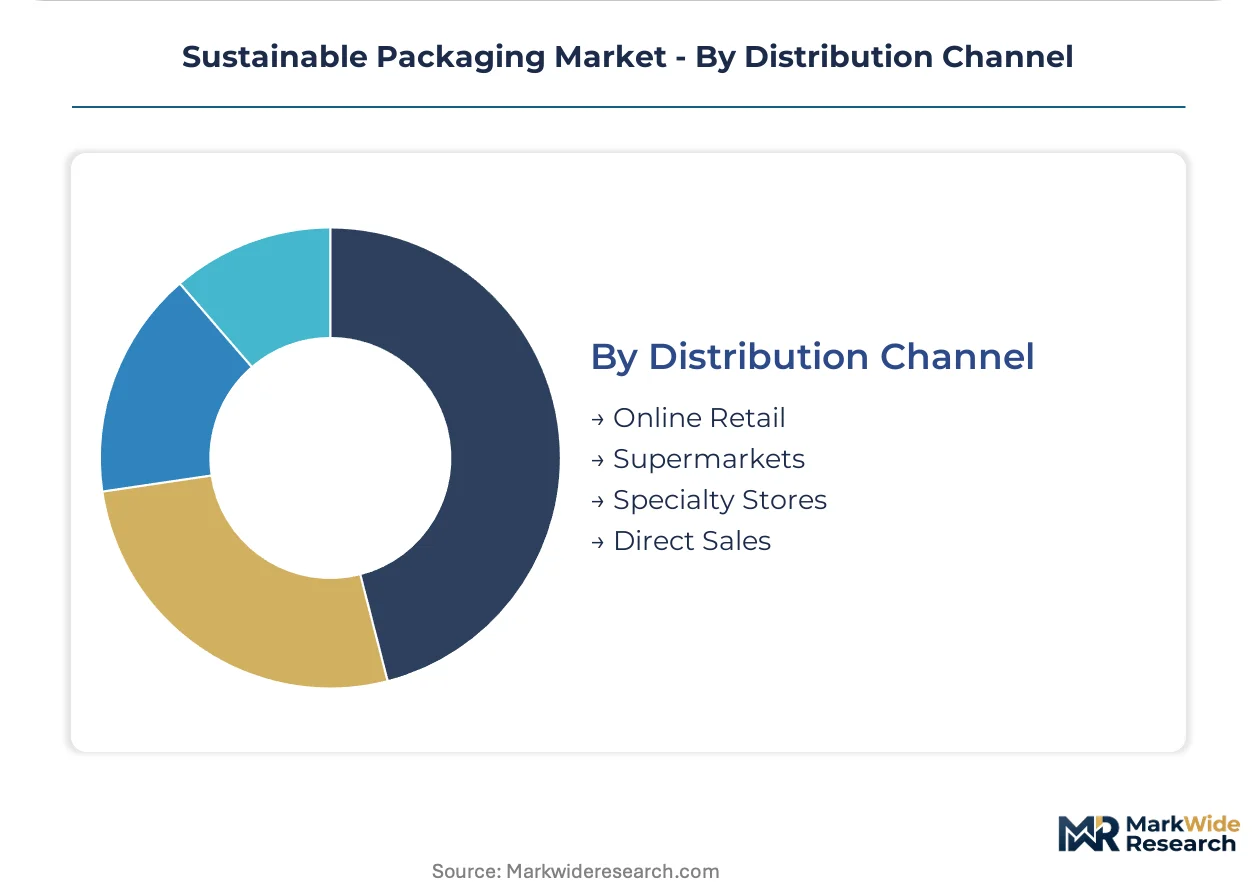
Channel selection influences pack size, graphic requirements, and reverse logistics feasibility for reuse systems.
- Supermarkets:Shelf-ready packaging and secondary display requirements drive corrugated and paperboard specification. German retailers are imposing extended producer responsibility fee transparency on suppliers.
- Online Retail:Dimensional weight optimization and damage resistance prioritize light-weighting and protective efficiency. French AGEC mandates are accelerating reusable crate pilot programs for last-mile delivery.
- Direct Sales:Subscription fulfillment enables standardized returnable packaging loops with customer registration.
- Specialty Stores:Premium unboxing experiences sustain higher material cost tolerance for rigid formats.
Supermarkets process the highest case volume. Online Retail shows the steepest trajectory shift on reuse mandate compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr corridor concentrates converter capacity serving pan-European brand owners. Extended producer responsibility mandates across multiple jurisdictions are redirecting investment toward circular infrastructure and mono-material processing lines.
Germany
Foodservice biopolymer procurement and rigid container demand from personal care brands dominate converter order books. The Verpackungsgesetz imposes strict recycling quotas and modulated EPR fees based on design recyclability. The Hamburg-Bremen port cluster anchors import logistics for rPET flake and bioplastic resin feedstocks.
France
AGEC law reuse targets for e-commerce and quick-service packaging specifications drive specification intensity. The national anti-waste statute mandates plastic reduction trajectories and standardizes labeling for sorting instructions. The Lyon-Saint-Étienne manufacturing belt hosts molded fiber tooling specialists serving pan-European foodservice chains.
United States
FDA food-contact notification requirements for post-consumer recycled content create compliance service demand and substrate purity testing revenue pools. State-level extended producer responsibility legislation in California and Oregon precedes federal harmonization efforts. The Chicago-Milwaukee corridor concentrates flexible film metallization and barrier coating capacity for snack brands.
Italy
Pasta and ready-meal processors specify PLA-lined molded fiber trays for retail distribution. National packaging consortium obligations enforce recycling contribution schemes and design-for-recycling standards. The Emilia-Romagna packaging machinery district supplies thermoforming and filling equipment to bioplastic converters across Southern Europe.
China
Domestic demand for e-commerce corrugated and export-oriented molded fiber electronics packaging sustains capacity expansion. The national dual carbon policy framework imposes energy intensity benchmarks on paperboard and glass manufacturing. The Yangtze River Delta hosts integrated pulp-to-package operations supplying barrier-coated kraft paper to Japanese and South Korean brand owners.
Sustainable Packaging Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue compostable certification pipelines and reusable logistics systems. The market structure reflects moderate consolidation among integrated paper and film converters, with specialist molded fiber and biopolymer players occupying fragmented niches. Three archetypes dominate: integrated forestry-to-package operators, captive bioplastic resin producers, and foodservice application specialists. Capacity expansion and strategic partnerships for feedstock security represent the dominant competitive vectors.
Among integrated paper-based operators, Mondi plc and Smurfit WestRock Company exemplify scale-driven positions anchored in European forestry networks and corrugated infrastructure. Amcor plc occupies a distinct archetype as a flexible film specialist with backward integration into bioplastic sourcing partnerships. These three entities represent divergent strategic postures: fiber integration, resin supply control, and barrier technology specialization.
| Leading Market Players |
|---|
| Amcor plc |
| Tetra Pak International SA |
| Smurfit WestRock Company |
| Sonoco Products Company |
| Sealed Air Corporation |
| Berry Global Inc. |
| Mondi plc |
| DS Smith |
| Huhtamaki Oyj |
| Others |
Supply Flow & Price Mechanics
Molded fiber tooling engineers in the Lyon-Saint-Étienne manufacturing belt command wage premiums that compress converter margins, widening spreads between artisanal small-batch packaging and mass-market commodity formats across European procurement tiers.
Pricing Analysis
Input-cost pass-through from corn and sugarcane feedstock volatility directly squeezes PLA and PHA converter margins, with no exchange-traded hedge instruments available at scale. Three-tier pricing structure across premium, standard, and economy levels separates EN 13432-certified compostable grades from uncertified bioplastics and virgin fossil-based alternatives. Pricing pressure stems from Asian PTA and MEG concentration creating single-source vulnerability for European rPET flake producers. Foodservice chains exhibit highest price sensitivity due to thin operating margins, while personal care brands tolerate premium positioning for ISO 14001-documented chain-of-custody substrates.
Supply Chain Analysis
Direct-to-brand-owner channels handle hyperscale demand from Unilever and L'Oréal headquarters-level procurement centralization, bypassing traditional distributor networks. Geographic supply concentrates in Germany, France, and Italy for molded fiber tooling and barrier-coated kraft paper, with China anchoring base chemical clusters for rPET resin feedstocks. Raw material dependencies rest on Nordic forestry networks for pulp integration, Yangtze River Delta for PTA/MEG intermediates, and Hamburg-Bremen port logistics for bioplastic resin imports. Single-source vulnerability in Chinese base chemical concentration presents structural supply chain risk. Distribution runs through integrated converter-direct relationships for tier-one brand owners, with merchant markets serving regional foodservice chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Germany's strict Verpackungsgesetz compliance costs and France's AGEC law reuse infrastructure subsidies, rewarding converters with cross-border operational flexibility.
For Market Incumbents: Deepen captive bioplastic resin partnerships to offset feedstock volatility exposure from corn and sugarcane price swings. Secure molded fiber tooling capacity through exclusive equipment builder relationships, addressing 18-month lead time bottlenecks that threaten order book fulfillment. Prioritize mono-material film retrofit investments to capture modulated EPR fee advantages under German recycling quota enforcement.
For New Entrants and Emerging Players: Foodservice distributors represent the most accessible channel partner type for compostable certification pipeline entry, leveraging existing quick-service chain relationships in France and Italy. Target pharmaceutical compliance advisory services as the most penetrable white-space segment, where FDA food-contact notification bottlenecks create testing laboratory revenue pools. Pursue digital watermark sortation technology licensing as the primary go-to-market angle for flexible film circularity solutions.
For Investors and Strategic Acquirers: Integrated forestry-to-package operators are the most active acquirer in this space, consolidating corrugated capacity across European kraft mill networks. The five-to-ten-year viability window favors targets with backward integration into pulp supply and established EN 13432 certification pipelines. Watch for HolyGrail 2.0 tracer technology convergence with near-infrared detection as the critical inflection signal for flexible film mechanical recycling economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bioplastic Resin | Amcor plc's captive sourcing partnerships insulate converter margins from agricultural feedstock volatility. |
| Mono-Material Film Retrofit Investment | German snack brands retrofit metallizers with SiOx chambers to satisfy ECHA REACH fluorinated barrier restrictions. |
| Reusable Packaging Infrastructure Deployment | France's AGEC law mandates reuse targets, opening logistics networks for pooled crate and tote systems. |
| Digital Watermark Sortation Adoption | HolyGrail 2.0 tracer technology enables flexible film circularity where mechanical recycling previously failed. |
| Pharmaceutical Compliance Service Expansion | FDA food-contact notification bottlenecks create advisory revenue pools for substrate purity testing laboratories. |
Methodological Framework
Coverage spans Germany, France, Italy, the United States, and China, with primary inputs from each regional cluster combining interviews with converter operations directors, brand-owner sustainability procurement leads, molded fiber tooling equipment builders, and EPR scheme administrators. Secondary validation draws from EU Packaging and Packaging Waste Regulation filings, FDA food-contact notification databases, ECHA REACH restriction updates, and national packaging consortium contribution records. Bottom-up capacity assessments triangulate against top-down demand modeling from end-use sector consumption patterns.
Granularity-level modeling operates at material type, product format, end-use vertical, and distribution channel dimensions, with additional disaggregation by compostability certification status and extended producer responsibility fee tier. CAGRs derive from segment-level volume trajectories cross-referenced against policy mandate timelines and feedstock cost curve projections. Industry-specific forecast inputs include biopolymer fermentation capacity buildout schedules and industrial composting facility availability by municipality.
Revisions become necessary when ECHA REACH restriction timelines accelerate, biopolymer feedstock price volatility exceeds historical bands, or major brand owners consolidate procurement authority beyond current headquarters-level centralization patterns. Forecasts reflect documented assumptions regarding regulatory harmonization between mechanical recycling and composting certification streams. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
Areca Plates Market
Sustainable Packaging
Plant Based Packaging Market
Sustainable Packaging
Asia-Pacific Eco-Friendly Packaging Market
Sustainable Packaging
Europe Eco-Friendly Packaging Market
Sustainable Packaging
Europe Green Packaging Market
Sustainable Packaging
Compostable Food Trays Market
Sustainable Packaging
Europe Sustainable Packaging Market
Sustainable Packaging
Sustainable Plastic Packaging Market
Sustainable Packaging
Zero Waste Packaging Market
Sustainable Packaging
Asia-Pacific Sustainable Packaging Market
Sustainable Packaging
PVC-Free Packaging Market
Sustainable Packaging
Eco-Friendly Straw Market
Sustainable Packaging
Sustainable Foodservice Packaging Market
Sustainable Packaging
North America Eco-Friendly Packaging Market
Sustainable Packaging
Compostable Tableware Market
Sustainable Packaging
Bagasse Bowls Market