
 Japan Green Packaging Market | 2026-2036
Japan Green Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Green Packaging Market Intelligence
Multi-source procurement of bio-based resins is restructuring supply relationships across Japan's packaging value chain. Asahi Kasei Corporation leverages its cellulose nanofiber pilot lines to anchor domestic sourcing of high-strength barrier films. Rengo Co., Ltd. competes through integrated pulp-to-box operations across its Kyushu and Kanto mill networks. Dai Nippon Printing Co., Ltd. differentiates via gravure-printed compostable wrappers for premium confectionery clients.
Japan green packaging encompasses materials and containers engineered to minimize environmental burden through biodegradability, recyclability, or renewable feedstock content, typically meeting JIS standards for compostability or recycled paperboard stiffness thresholds above 200 kPa. Its primary purpose spans protective containment of perishables and consumer goods while satisfying corporate sustainability commitments and retailer compliance mandates. Recycled paper and plant-based materials command the deepest margin pools due to established collection infrastructure and consumer familiarity, whereas compostable films represent the fastest-expanding material class as film converters retrofit blown-film extrusion lines. E-commerce and retail packaging applications absorb the majority of volume growth as Japanese logistics platforms adopt right-sized corrugated alternatives to reduce void fill.
METI's Plastic Resource Circulation Strategy, JIS compostability certifications, and the Act on Promotion of Resource Circulation for Plastics collectively shape product specifications and market access thresholds for domestic and imported packaging. Compliance with these frameworks now determines eligibility for government procurement contracts and major retailer shelf placement. Stakeholders must monitor revision timelines for recycled content mandates and prepare qualification pathways for next-generation barrier technologies.
Market Dynamics
METI's recycled content mandates are compressing design cycles for consumer-facing containers while cellulose nanofiber pilot investments restructure raw material sourcing relationships across the archipelago.
Growth Catalysts
- Act on Promotion of Resource Circulation for Plastics:This framework mandates phased recycled content thresholds for household containers, forcing brand owners to qualify domestic suppliers ahead of enforcement deadlines.
- Cellulose nanofiber film extrusion:Pilot-scale production lines in Ibaraki and Shizuoka prefectures are validating barrier performance for moisture-sensitive confectionery applications at commercial throughputs.
- Kanto logistics corridor:E-commerce fulfillment centers in Tokyo and Kanagawa are adopting right-sized corrugated formats to eliminate void fill and reduce dimensional weight charges.
Market Restraints
- Imported bio-resin price volatility:Polylactic acid and starch-based feedstock pricing tracks agricultural commodity indices, compressing converter margins when yen weakness coincides with harvest shortfalls.
- Single-region pulp concentration:Kyushu island hosts over half of Japan's bleached kraft pulp capacity, exposing paperboard supply chains to typhoon disruption and shipping bottlenecks through Kanmon Strait.
- Oxygen barrier limitations:Current plant-based films fail to match metallized PET performance for shelf-stable retort applications, restricting adoption in ambient meal kits.
Strategic Opportunities
- Chubu pharmaceutical corridor:Shizuoka and Aichi prefectures host dense clusters of OTC and prescription drug manufacturers seeking child-resistant yet compostable blister alternatives.
- JIS compostability certification acceleration:Streamlined testing protocols for home-compostable films reduce qualification timelines from 18 to 8 months, enabling faster product launches.
- Convenience store reverse logistics:Seven-Eleven and Lawson pilot programs collect used bento trays for closed-loop recycling, creating captive feedstock pools for participating converters.
Industry Challenges
- Barrier chemist talent scarcity:Formulation expertise for bio-based oxygen scavengers concentrates among retiring specialists at legacy synthetic resin houses, constraining R&D velocity.
- Blown-film line retrofit capex:Converting fossil-based extrusion equipment for thermoplastic starch processing requires screw and die replacements exceeding 200 million yen per line.
- JIS testing backlog:Certified laboratory capacity for disintegration and ecotoxicity validation runs 6-9 months, delaying product launches ahead of retailer compliance deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Green Packaging Market |
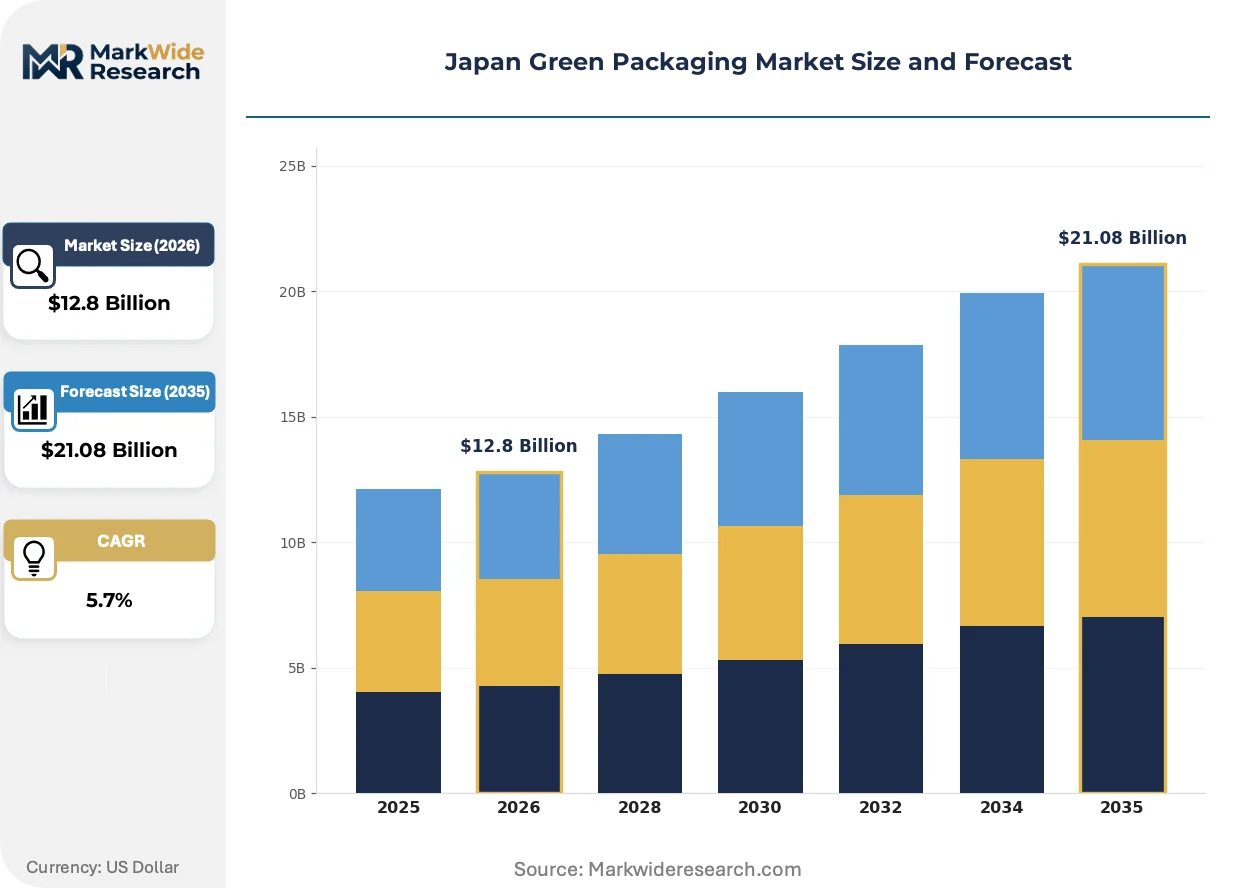
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bags, Containers, Wraps Material: Biodegradable Plastic, Recycled Paper, Compostable Films, Plant-based Materials End User: Food & Beverages, Personal Care, Electronics, Consumer Goods Application: Retail Packaging, Industrial Packaging, E-commerce, Shipping Packaging |
| Companies Covered | Asahi Kasei Corporation, Dai Nippon Printing Co., Ltd., Nippon Paper Industries Co., Ltd., Sumitomo Chemical Co., Ltd., Mitsubishi Chemical Corporation, Rengo Co., Ltd., Toyobo Co., Ltd., Tetra Pak Japan Ltd., Futamura Chemical Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Green Packaging Market Strategic Shifts & Innovations
Distributed manufacturing models and regulatory compression timelines are forcing packaging converters to relocate compounding and forming operations closer to brand owner specifications.
Cellulose nanofiber reinforcement is decentralizing barrier film supply chains by enabling regional pulp mills to integrate downstream into high-performance packaging substrates without polymer resin dependencies. Pharmaceutical and premium food manufacturers in Osaka and Nagoya are qualifying these materials for oxygen-sensitive applications. The technology is decentralizing converter relationships away from petrochemical distributors toward vertically integrated forestry-product suppliers.
METI's Plastic Resource Circulation Strategy enforcement timelines are accelerating qualification pathways for recycled content verification systems. Brand owners must document post-consumer feedstock percentages through mass-balance chain-of-custody protocols. Retail packaging for household chemicals and personal care in the Kanto region faces the most immediate compliance pressure, with Aeon and Ito-Yokado demanding supplier certifications by Q3 2026.
Buyer consolidation among Japanese e-commerce platforms is compressing packaging specification cycles and unbundling design from manufacturing contracts. Rakuten and Amazon Japan now issue dimensional tolerances and material certifications as standalone procurement lots, displacing legacy converter-designer relationships. This pattern concentrates most visibly in Tokyo Bay fulfillment zones where same-day delivery density justifies packaging automation investments.
Japan Green Packaging Market Segmentation
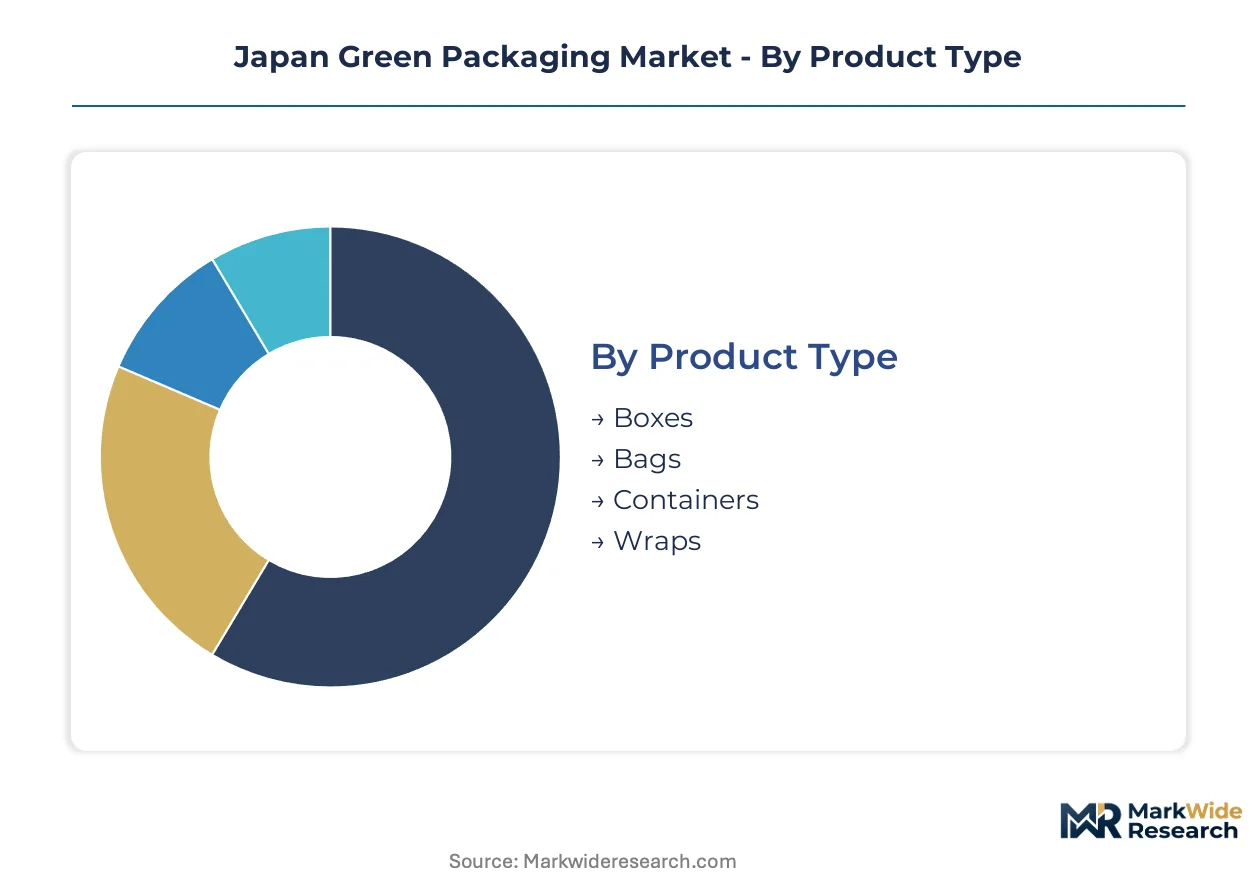
Segmentation in Japan's green packaging market reveals how regulatory pressure and supply chain restructuring reshape procurement patterns across material classes and end-use applications. Each dimension exposes distinct margin structures and qualification barriers that determine competitive positioning.
Product Type:
Converters are upgrading forming equipment to capture recycled content mandates and right-sizing requirements across Japan's logistics corridors.
- Boxes:Corrugated formats with 90%+ recycled paperboard content dominate e-commerce fulfillment in Tokyo and Kanagawa prefectures. Seven-Eleven and Lawson reverse logistics programs generate captive feedstock pools for closed-loop production.
- Bags:Stand-up pouches and gusseted formats incorporate cellulose nanofiber layers for moisture-sensitive confectionery applications. Pilot extrusion lines in Ibaraki validate barrier performance at commercial throughputs.
- Containers:Thermoformed trays for ready meals and bento boxes face METI's phased recycled content thresholds. Domestic polylactic acid compounding capacity constrains supply security for food-contact grades.
- Wraps:Stretch films and cling wraps for fresh produce bundling transition from petroleum-based resins to thermoplastic starch formulations.
Boxes sit at the top of the volume ranking, with Bags climbing the fastest.
Material:
Material selection in Japan tracks JIS certification accessibility and regional pulp mill integration depth rather than raw commodity pricing alone.
- Recycled Paper:Bleached kraft pulp from Kyushu mills feeds integrated boxboard operations across Rengo's mill network. Typhoon exposure through Kanmon Strait creates supply vulnerability during peak shipping seasons.
- Compostable Films:Blown-film extrusion retrofits exceed 200 million yen per line, concentrating investment among converters with pharmaceutical corridor access in Shizuoka and Aichi prefectures.
- Biodegradable Plastic:Polylactic acid pricing tracks agricultural commodity indices and yen exchange rates, compressing margins during harvest shortfalls.
- Plant-based Materials:Bamboo fiber and agricultural residue pulps serve premium cosmetic brands seeking tactile differentiation in Osaka and Nagoya markets.
Recycled Paper commands the highest volume share, while Compostable Films gain share fastest among converters qualifying for Aeon and Ito-Yokado certification deadlines.
End User:
End-user demand concentrates where shelf-stable barrier requirements intersect with retailer compliance mandates and consumer visibility.
- Food & Beverages:Ambient meal kits and retort applications drive oxygen barrier innovation. Current plant-based films fail to match metallized PET performance, restricting adoption in shelf-stable segments.
- Personal Care:Premium cosmetic brands in Osaka demand gravure-printed compostable wrappers with stiffness thresholds above 200 kPa per JIS standards.
- Electronics:Anti-static corrugated and molded pulp formats protect high-value components during Kanto corridor distribution.
- Consumer Goods:Household chemical containers face immediate compliance pressure under METI's Plastic Resource Circulation Strategy enforcement timelines.
Food & Beverages sits at the top of the volume ranking, with Personal Care climbing the fastest.
Application:
Application segmentation reflects automation investment density and dimensional tolerance requirements across Japan's fulfillment infrastructure.
- E-commerce:Rakuten and Amazon Japan unbundle design from manufacturing contracts, issuing material certifications as standalone procurement lots in Tokyo Bay zones.
- Retail Packaging:Point-of-sale displays and primary containers for Aeon and Ito-Yokado require mass-balance chain-of-custody documentation for post-consumer feedstock percentages.
- Shipping Packaging:Right-sized corrugated eliminates void fill and reduces dimensional weight charges across Kanto logistics corridors.
- Industrial Packaging:Bulk containers and dunnage for automotive and electronics manufacturing prioritize structural integrity over compostability.
E-commerce sits at the top of the volume ranking, with Retail Packaging climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kanto industrial corridor anchors Japan's green packaging demand concentration, with Tokyo and Kanagawa prefectures hosting dense clusters of e-commerce fulfillment centers and food processing facilities that drive specifications for recycled-content corrugated and compostable films.
Kanto/Tokyo
Rakuten and Amazon Japan fulfillment centers in Tokyo Bay zones issue standalone material certification procurement lots, compressing specification cycles for right-sized corrugated formats. METI's Plastic Resource Circulation Strategy enforcement timelines create immediate compliance pressure on household chemical containers. Seven-Eleven and Lawson pilot reverse logistics programs in Saitama and Chiba prefectures collect used bento trays for closed-loop recycling.
Kansai/Osaka
Premium cosmetic brands in Osaka demand gravure-printed compostable wrappers with JIS stiffness thresholds above 200 kPa for tactile differentiation. The Act on Promotion of Resource Circulation for Plastics mandates phased recycled content thresholds that force brand owners to qualify domestic suppliers ahead of enforcement deadlines. Pharmaceutical manufacturers in Kyoto and Hyogo prefectures seek child-resistant yet compostable blister alternatives for OTC and prescription drug packaging.
Chubu/Nagoya
Shizuoka and Aichi prefectures host dense clusters of pharmaceutical manufacturers driving demand for oxygen-sensitive barrier applications. Pilot-scale cellulose nanofiber film extrusion lines in Ibaraki and Shizuoka validate moisture barrier performance for confectionery at commercial throughputs. Automotive and electronics manufacturing in Aichi prioritizes anti-static corrugated and molded pulp formats for component protection during distribution.
Kyushu
Bleached kraft pulp capacity concentrates on Kyushu island, feeding integrated boxboard operations across mill networks that supply Kanto and Kansai corridors. Typhoon exposure through Kanmon Strait creates supply vulnerability during peak shipping seasons. Agricultural residue pulps from Fukuoka and Saga prefectures serve premium cosmetic brands seeking sustainable feedstock differentiation.
Hokkaido
Food processing facilities in Sapporo and Hakodate drive demand for plant-based trays and wraps for fresh seafood and dairy distribution. JIS compostability certification acceleration reduces qualification timelines for home-compostable films, enabling faster product launches for regional brands. Limited domestic polylactic acid compounding capacity constrains supply security for food-contact grade containers.
Japan Green Packaging Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue cellulose nanofiber and pharmaceutical-grade barrier specializations. The vendor base stratifies across integrated pulp-to-box operators, film converters with blown-film retrofit capabilities, and gravure printing specialists serving premium confectionery and cosmetic clients. Three archetypes dominate: forestry-integrated paperboard suppliers, chemical conglomerates with bio-resin portfolios, and precision converters focused on JIS-certified compostable films. Competitive moves concentrate on backward integration into pulp supply and technology licensing for barrier chemistries.
Within the integrated paperboard tier, Rengo Co., Ltd. and Nippon Paper Industries Co., Ltd. exemplify operators with captive pulp supply and mill network control. Among chemical conglomerates diversifying into bio-based materials, Asahi Kasei Corporation and Mitsubishi Chemical Corporation occupy positions spanning resin production through film extrusion. Precision converters with JIS certification capabilities include Dai Nippon Printing Co., Ltd., which anchors gravure-printed compostable wrapper supply for premium brand clients.
| Leading Market Players |
|---|
| Asahi Kasei Corporation |
| Dai Nippon Printing Co., Ltd. |
| Nippon Paper Industries Co., Ltd. |
| Sumitomo Chemical Co., Ltd. |
| Mitsubishi Chemical Corporation |
| Rengo Co., Ltd. |
| Toyobo Co., Ltd. |
| Tetra Pak Japan Ltd. |
| Futamura Chemical Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Barrier chemist concentration in Osaka and Nagoya pharmaceutical corridors widens pricing spreads between certified compostable films and standard recycled paperboard tiers, as formulation expertise scarcity forces converters to absorb premium labor costs or pass them downstream to Aeon and Ito-Yokado procurement officers.
Pricing Analysis
Input-cost pass-through from agricultural commodity indices and yen exchange rate volatility governs polylactic acid and starch-based resin pricing, compressing converter margins during harvest shortfalls. Three-tier pricing structure across premium JIS-certified compostable films, standard recycled-content paperboard, and economy-grade conventional plastics tracks certification grade and volume scale. Pricing pressure stems from blown-film line retrofit capex exceeding 200 million yen per installation, forcing smaller converters toward toll manufacturing arrangements. Brand owners in the Kanto logistics corridor exhibit highest price sensitivity for corrugated void-fill elimination, while pharmaceutical manufacturers in Chubu accept premiums for oxygen barrier performance.
Supply Chain Analysis
Single-source vulnerability sits with Kyushu island bleached kraft pulp capacity, which feeds over half of Japan's paperboard substrate demand through typhoon-exposed Kanmon Strait shipping lanes. Raw material dependencies center on imported polylactic acid from Thailand and US agricultural residues, alongside domestic cellulose nanofiber pilot production in Ibaraki and Shizuoka. Supply chain risk concentrates in logistics chokepoint exposure during peak shipping seasons, compounded by JIS testing laboratory backlogs running 6-9 months. Distribution runs through integrated pulp-to-box mill networks for paperboard and chemical conglomerate resin distribution channels for bio-based films.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan green packaging functions as a regulatory compounder where METI's Plastic Resource Circulation Strategy enforcement timelines compress supplier qualification windows and force premature capital deployment ahead of recycled content mandate deadlines.
For Market Incumbents: Lock in captive pulp supply through Kyushu mill network consolidation before typhoon season disrupts Kanmon Strait shipping lanes, and accelerate JIS compostability certification investments to capture Aeon and Ito-Yokado procurement deadlines ahead of smaller converters facing testing laboratory backlogs. For New Entrants and Emerging Players: Capture white-space in child-resistant yet compostable blister packaging for Chubu pharmaceutical manufacturers, and exploit streamlined home-compostable film qualification protocols reducing timelines from 18 to 8 months to outpace legacy gravure printing specialists on product launch velocity. For Investors and Strategic Acquirers: Valuations sit cheapest among blown-film converters with incomplete JIS certification pipelines and stranded fossil-based extrusion assets, where long-term viability over the next decade hinges on successful pharmaceutical corridor qualification and cellulose nanofiber barrier technology licensing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Rengo and Nippon Paper secure captive bleached kraft feedstock against Kyushu typhoon disruption. |
| JIS Certification Acceleration | Dai Nippon Printing exploits streamlined testing protocols to compress compostable wrapper launch timelines. |
| Cellulose Nanofiber Licensing | Asahi Kasei transfers barrier film technology to regional converters seeking pharmaceutical corridor access. |
| Reverse Logistics Partnership | Seven-Eleven and Lawson pilot programs create closed-loop bento tray feedstock pools for participating converters. |
| Blown-Film Line Retrofit | Toyobo and Futamura Chemical deploy thermoplastic starch processing capability ahead of METI enforcement deadlines. |
Research Approach
Bottom-up e-commerce and retail packaging modeling reconciled against top-down pulp mill capacity and bio-resin import tracking forms the analytical core of this study. Primary interviews with corrugated plant managers, pharmaceutical packaging procurement leads, JIS certification laboratory directors, and convenience store reverse logistics coordinators combined with secondary validation from METI policy filings, Japan Paper Association production statistics, customs trade data for polylactic acid imports, and SEC disclosures from chemical conglomerates with packaging divisions. Triangulation across these sources ensures supply-side capacity estimates align with demand-side procurement patterns.
Input-output matrix framing connects cellulose nanofiber pilot line throughput assumptions to confectionery and pharmaceutical barrier film demand, while segmented CAGRs derive from material substitution elasticity models and regulatory compliance cost curves across the analysis window. Segmentation dimensions include product type, material class, end-use industry, and application with regional production cluster overlays. Forecast inputs incorporate JIS certification timeline acceleration, blown-film retrofit investment cycles, and METI enforcement schedule revisions.
Regulatory timeline delays, yen weakness amplifying agricultural commodity import costs, and typhoon frequency disrupting Kyushu pulp shipments are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about substitution rates and capacity ramp schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
Europe Sustainable Packaging Market
Sustainable Packaging
Bagasse Bowls Market
Sustainable Packaging
Wheat Straw Cutlery Market
Sustainable Packaging
Global Paper Straw Market
Sustainable Packaging
Bagasse Tableware Products Market
Sustainable Packaging
Green Packaging Market
Sustainable Packaging
Bio-Based Cutlery Market
Sustainable Packaging
Compostable Tableware Market
Sustainable Packaging
Areca Plates Market
Sustainable Packaging
Zero Waste Packaging Market
Sustainable Packaging
Plant Based Packaging Market
Sustainable Packaging
Sustainable Foodservice Packaging Market
Sustainable Packaging
Asia-Pacific Eco-Friendly Packaging Market
Sustainable Packaging
Eco-Friendly Straw Market
Sustainable Packaging
Compostable Food Trays Market
Sustainable Packaging
Europe Eco-Friendly Packaging Market