
 PVC-Free Packaging Market | 2026-2036
PVC-Free Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
PVC-Free Packaging Market Analytics
Food-grade barrier specifications is collapsing the legacy cost gap between PVC and polyethylene alternatives. Amcor PLC leverages its global film extrusion network to supply multilayer PE solutions for protein packaging. Mondi anchors European demand through integrated kraft paper and barrier coating capacity. Stora Enso specializes in fiber-based rigid formats that replace vinyl blister packs for premium cosmetics.
PVC-free packaging denotes material systems engineered without polyvinyl chloride resin, typically employing polyethylene, polylactic acid, or paper substrates with oxygen and moisture barrier coatings applied through extrusion lamination or vapor deposition processes. These systems serve to contain, protect, and present goods while eliminating chlorine-based polymer hazards from supply chains and waste streams. Flexible packaging leads volume adoption due to its dominance in fresh food and snack wrapping where downgauging and seal integrity requirements are most acute. Rigid packaging occupies the highest margin pool in healthcare and electronics segments where dimensional stability and ESD protection command premium pricing. Bioplastics represent the fastest-expanding material class as PLA and PHA formulations achieve commercial scale in thermoformed trays and molded fiber applications.
The EPA regulates vinyl chloride emissions under the Clean Air Act, while the EU REACH framework restricts chlorinated polymers in articles with prolonged skin contact, and the FDA maintains strict residual vinyl chloride monomer limits for food-contact substances. These overlapping standards compel converters to validate alternative chemistries through migration testing and compositional certifications. Stakeholders must monitor evolving state-level extended producer responsibility laws and bioplastics degradation labeling requirements that will determine which material platforms achieve scalable regulatory clearance.
Market Dynamics
The EU REACH regulation restricting vinyl chloride monomer in consumer-facing materials is forcing converters to revalidate entire material portfolios through migration testing and compositional certifications.
Growth Catalysts
- REACH chemical restrictions:The EU framework bans chlorinated polymers in articles with prolonged skin contact, compelling brands to eliminate PVC from primary packaging. Food and beverage manufacturers face immediate compliance deadlines.
- Barrier coating advances:Vapor deposition and extrusion lamination processes now deliver oxygen and moisture protection comparable to legacy vinyl films. Protein packagers in Germany are switching to multilayer polyethylene solutions.
- Retail chain procurement mandates:German retail chains enforce strict packaging covenants that exclude PVC from supplier specifications. This concentrates demand acceleration in Central European markets.
Market Restraints
- Petrochemical feedstock volatility:Polyethylene resin prices fluctuate with crude oil indices, compressing margins for converters locked into long-term supply contracts with food brands.
- Bioplastic production concentration:PLA and PHA fermentation capacity clusters in Thailand and Nebraska, creating geographic supply risk for European thermoformers.
- Heat-seal temperature limitations:Polylactic acid substrates require narrower processing windows than PVC, slowing line speeds in high-volume snack packaging operations.
Strategic Opportunities
- Healthcare blister pack conversion:Rigid fiber-based formats with barrier coatings can capture premium pricing in pharmaceutical packaging where dimensional stability and child-resistance specifications command value.
- Extended producer responsibility tailwinds:State-level EPR laws in California and Maine impose fees on non-recyclable packaging, creating economic preference for certified compostable alternatives.
- Electronics ESD protection convergence:Molded fiber with vapor-deposited metal layers combines antistatic performance with chlorine-free credentials for semiconductor shipping trays.
Industry Challenges
- Migration testing backlog:FDA residual vinyl chloride monomer limits for food-contact substances require lengthy analytical validation, delaying new product launches by quarters.
- Legacy equipment retrofit costs:Converting blown film lines from PVC to high-density polyethylene demands screw and die modifications that strain mid-cap extruder balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVC-Free Packaging Market |
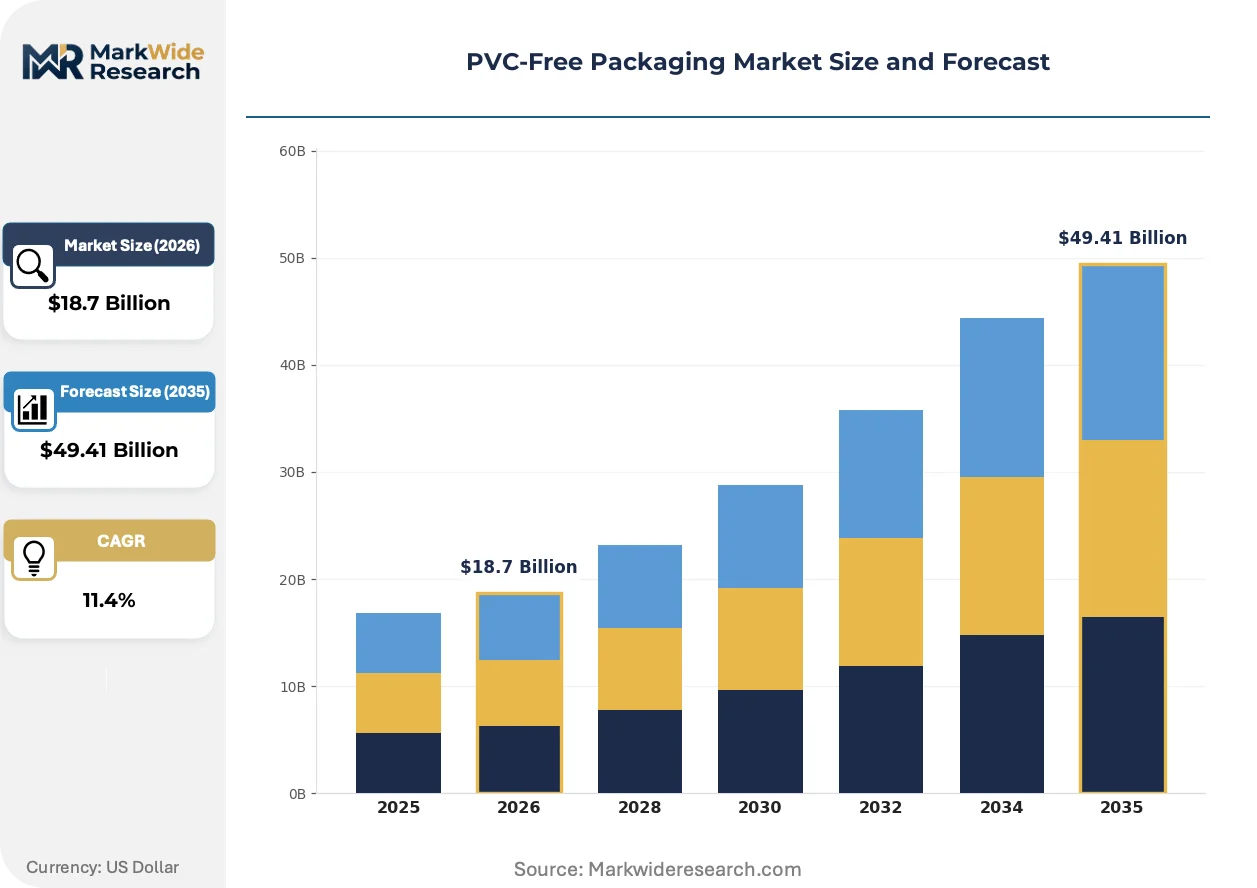
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Rigid Boxes, Pouches Material: PE, PLA, Paper, Bioplastics End User: Food & Beverage, Cosmetics, Electronics, Healthcare Distribution Channel: Online, Retail, Direct Sales, Third-party Distributors |
| Companies Covered | Amcor PLC, Mondi, DS Smith, Smurfit Kappa, WestRock Company, Huhtamaki OYJ, Stora Enso, Sealed Air Corporation, Tetra Pak International S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVC-Free Packaging Market Evolving Landscape
Active barrier technologies and substrate engineering are collapsing the performance gap between chlorine-free materials and legacy vinyl systems across fresh food and healthcare applications.
Water-based barrier coatings with nanoclay dispersions are displacing chlorine-containing films in fresh produce wrapping. German supermarket chains have mandated their adoption for private-label salad bags. The technology is compressing the cost premium against PVC to under fifteen percent at commercial volumes.
The EPA regulates vinyl chloride emissions under the Clean Air Act while tightening residual monomer thresholds for food-contact substances. Converters must install scrubber systems and implement real-time emissions monitoring. Protein packagers in the Midwest are consolidating supplier audits to verify compliance across multiple facilities.
Brand sustainability scorecards now weight packaging chemistry alongside carbon footprint in procurement decisions. Retail buyers in Scandinavia prioritize suppliers with ECHA-registered alternatives. This certification-driven preference shift is fragmenting incumbent converter relationships and opening specification windows for validated substitutes.
PVC-Free Packaging Market Segmentation
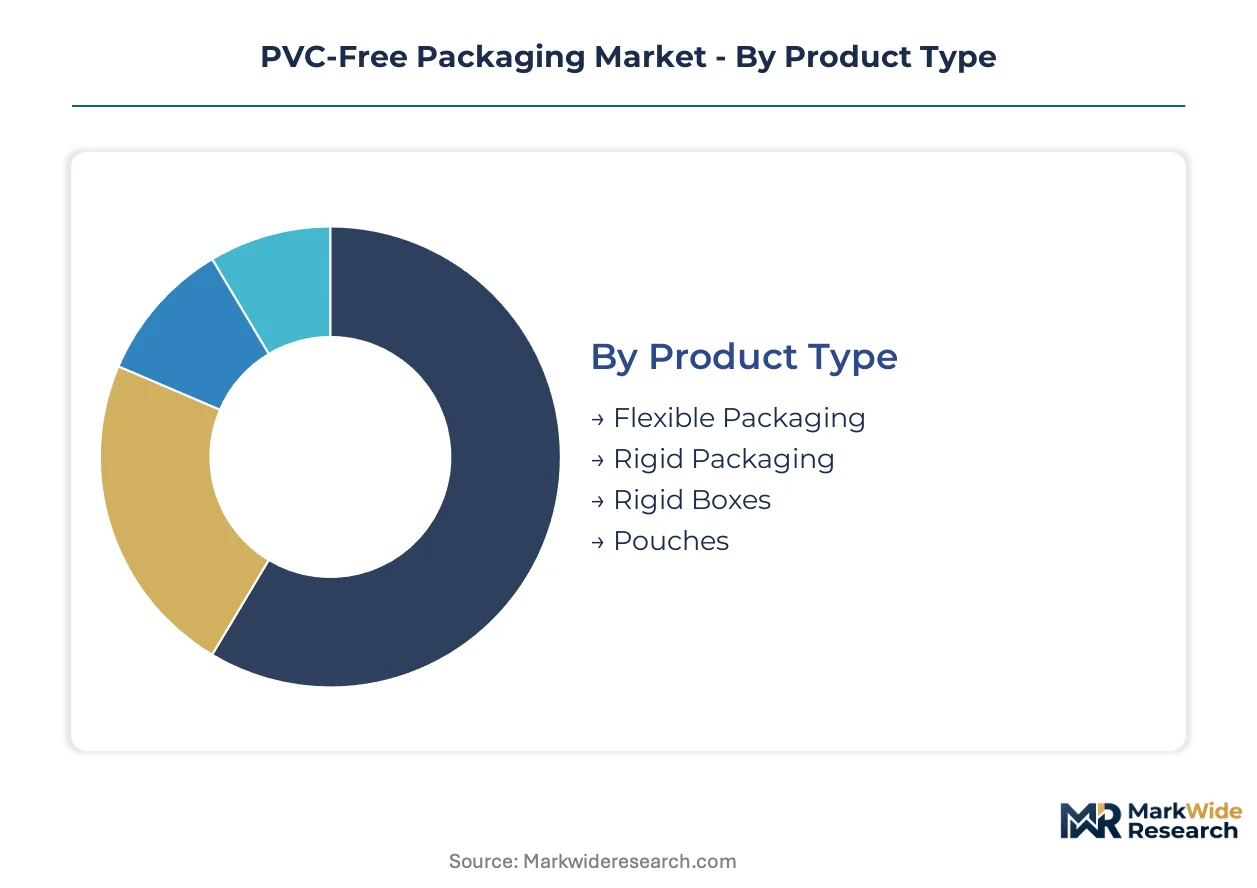
Segmentation in PVC-free packaging reveals how material choices and format specifications cascade through regulatory compliance requirements and retail procurement systems. Each dimension exposes distinct margin structures and conversion technology barriers that determine competitive positioning across converter tiers.
Product Type:
Flexible formats dominate foodservice and retail private-label channels where downgauging and high-speed sealing are critical. Rigid systems flow through healthcare and electronics supply chains demanding dimensional precision and ESD protection.
- Flexible Packaging:Multilayer polyethylene and bio-based films with vapor-deposited barrier layers serve fresh protein and snack applications. German retail chains mandate these formats for private-label salad and deli meat programs under strict packaging covenants.
- Rigid Packaging:Thermoformed PLA trays and molded fiber formats replace vinyl blister packs in pharmaceutical and cosmetic applications. Demand concentrates in Scandinavian markets where ECHA-registered alternatives receive procurement preference in sustainability scorecards.
- Rigid Boxes:Fiber-based formats with aqueous barrier coatings protect premium electronics and luxury cosmetics during distribution.
- Pouches:Stand-up and flat pouch configurations in high-density polyethylene serve dry goods and beverage concentrate segments.
Flexible packaging dominates installed base. Rigid packaging is where expansion concentrates.
Material:
Cost tiers separate petrochemical alternatives from fermentation-derived bioplastics, with paper substrates occupying a mid-tier position dependent on barrier coating sophistication.
- PE:Polyethylene resins—LDPE, HDPE, and metallocene grades—form the backbone of converted film supply. Barrier coating advances now deliver oxygen and moisture protection comparable to legacy vinyl films.
- PLA:Polylactic acid from corn and sugarcane fermentation requires narrower heat-seal windows than conventional polymers. Thai and Nebraska production clusters create geographic supply risk for European thermoformers.
- Paper:Kraft and specialty papers with extrusion-laminated or vapor-deposited barrier layers displace chlorine-containing films in fresh produce wrapping.
- Bioplastics:PHA and starch-based formulations achieve commercial scale in molded fiber and thermoformed tray applications where compostability certification commands premium positioning.
Polyethylene anchors volume production. Bioplastics are climbing the fastest as EPR laws in California and Maine impose fees on non-recyclable alternatives.
End User:
Application requirements dictate barrier specifications and regulatory validation intensity, with food-contact substances facing the most stringent residual monomer testing protocols.
- Food & Beverage:Protein packagers and snack manufacturers drive flexible film demand. FDA residual vinyl chloride monomer limits require lengthy analytical validation that delays new product launches.
- Cosmetics:Premium brands specify fiber-based rigid formats with barrier coatings for primary and secondary packaging. Stora Enso specializes in these applications through integrated kraft paper and coating capacity.
- Electronics:Semiconductor and component manufacturers require ESD protection combined with chlorine-free credentials. Molded fiber with vapor-deposited metal layers serves this specification.
- Healthcare:Pharmaceutical blister packs and medical device trays demand dimensional stability and child-resistance features. This segment occupies the highest margin pool in rigid formats.
Food and beverage commands volume share. Healthcare is where margin expansion concentrates.
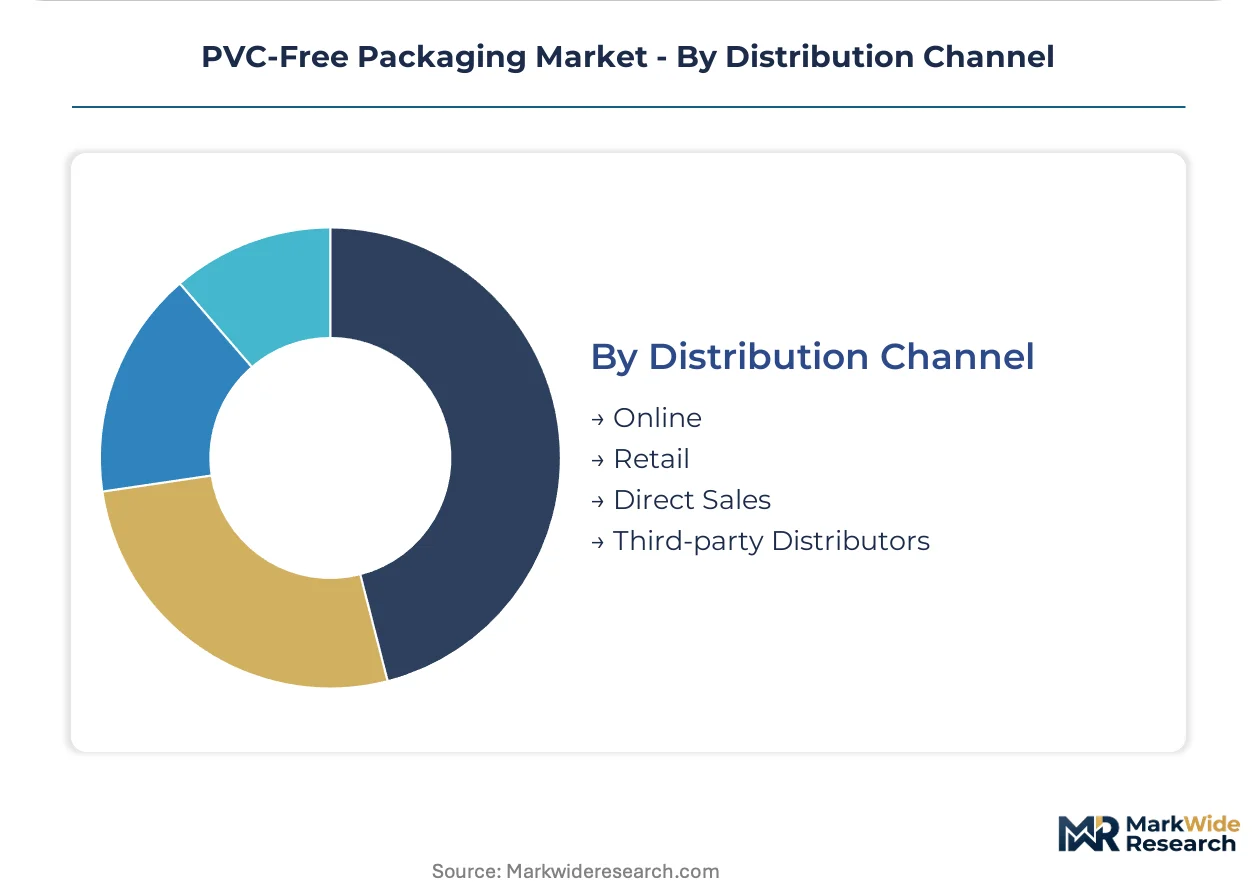
Distribution Channel:
Customer type determines order configuration and technical service intensity, with direct relationships favoring large-format converters and distributor networks serving fragmented regional accounts.
- Online:E-commerce fulfillment demands damage-resistant formats with minimal dimensional variation. Specifications prioritize stackability and print consistency for unboxing experience.
- Retail:Supermarket and big-box procurement teams enforce packaging covenants that exclude PVC from supplier specifications. German chains concentrate demand acceleration through mandatory compliance deadlines.
- Direct Sales:National food brands and healthcare OEMs contract directly with integrated converters for multiyear supply agreements. These relationships lock in volume commitments and joint development programs.
- Third-party Distributors:Regional paper and film merchants stock standard grades for mid-cap converters and local packagers. Inventory risk concentrates with distributors during resin price volatility cycles.
Direct sales relationships dominate strategic accounts. Third-party distributors handle geographic coverage expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in PVC-free packaging materials reveal distinct regional specializations. Germany and the United States function as net technology exporters, while Thailand and China concentrate bioplastic resin production for cross-border supply.
Germany
Retail chain procurement mandates and REACH chemical restrictions drive domestic converter demand. The EU framework bans chlorinated polymers in articles with prolonged skin contact, forcing immediate portfolio revalidation. Industrial concentration clusters around the Rhine-Ruhr corridor where multilayer PE extrusion capacity serves protein packaging for Aldi and Lidl private-label programs.
United States
EPA Clean Air Act enforcement and state-level EPR laws in California and Maine accelerate domestic substitution. FDA residual vinyl chloride monomer limits require lengthy analytical validation for food-contact substances. Midwest protein packagers consolidate supplier audits across Illinois and Wisconsin facilities to verify compliance.
China
Domestic food brands and electronics exporters face downstream pressure from EU and US buyers to eliminate chlorine-based materials. The country's national environmental regulator enforces stricter emissions standards for vinyl chloride production. Yangtze River Delta converters develop vapor-deposited barrier coatings for semiconductor shipping trays.
Thailand
PLA and PHA fermentation capacity clusters serve European thermoformer demand, creating geographic supply risk exposure. The country's board of investment promotes bioplastics through tax incentives and infrastructure support. Eastern Economic Corridor facilities export to German and Scandinavian markets where ECHA-registered alternatives receive procurement preference.
Sweden
Brand sustainability scorecards weight packaging chemistry alongside carbon footprint in Nordic procurement decisions. ECHA-registered alternatives receive explicit preference in retail buyer specifications. Stora Enso's integrated kraft paper and barrier coating capacity in the Stockholm region supplies fiber-based rigid formats for premium cosmetics.
PVC-Free Packaging Market Competitive Landscape
Listed leaders compete with private specialists across integrated film extrusion and fiber-based rigid formats. The market structure consolidates around three tiers: global converters with multiregional extrusion networks, regional paper-based packaging specialists with coating capabilities, and mid-cap bioplastic thermoformers with narrow geographic footprints. Strategic archetypes include barrier technology licensors, retail covenant compliance enablers, and compostable certification aggregators. Dominant competitive moves span M&A for coating technology access and backward integration into resin compounding.
Among integrated paper and fiber specialists, Stora Enso and Mondi occupy positions exemplifying the Nordic-European archetype of kraft-based barrier solutions. Amcor PLC represents the global converter tier with multilayer PE film supply relationships spanning protein packagers and retail private-label programs. These three entities anchor the competitive map across distinct material platforms without overlapping core technology positions.
| Leading Market Players |
|---|
| Amcor PLC |
| Mondi |
| DS Smith |
| Smurfit Kappa |
| WestRock Company |
| Huhtamaki OYJ |
| Stora Enso |
| Sealed Air Corporation |
| Tetra Pak International S.A. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between German retail chains and multilayer PE converters lock in volume commitments while providing price visibility against petrochemical resin volatility. These agreements concentrate procurement power among Aldi and Lidl private-label programs, forcing mid-cap extruders to absorb margin compression during crude oil price spikes.
Pricing Analysis
Industrial OEM buyers anchor contract-based pricing structures across food-contact and healthcare segments. Three-tier pricing structure across premium, standard, and economy levels separates ECHA-registered barrier coatings from commodity polyethylene films and uncoated fiber substrates. Pricing pressure stems from Thai and Nebraska PLA fermentation capacity bottlenecks that inflate bioplastic resin premiums. Snack manufacturers exhibit highest price sensitivity due to thin margins and high volume throughput, while pharmaceutical blister pack converters accept premium positioning for dimensional stability certification.
Supply Chain Analysis
Inventory cycles stretch 8-12 weeks for vapor-deposited barrier coatings sourced from Rhine-Ruhr corridor specialists. Raw material flows draw from Saudi Arabian ethylene crackers, Thai sugarcane fermentation facilities, and Swedish kraft pulp mills. Single-source vulnerability concentrates in PLA resin supply where European thermoformers rely on Eastern Economic Corridor exports. Distribution runs through integrated converter direct sales for national food brands, with regional paper merchants handling fragmented local accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier coating validation services and compositional certification programs are expanding faster than base material supply, creating recurring revenue attach opportunities for technical service providers. Equipment retrofit consulting and migration testing support now command premium positioning alongside physical packaging sales.
For Market Incumbents: Consolidate multilayer extrusion capacity in Germany to capture Aldi and Lidl covenant compliance deadlines before mid-cap competitors complete screw and die modifications. Acquire vapor deposition technology specialists to defend against Asian coating innovators entering European healthcare specifications. Lock in backward integration into metallocene PE compounding to offset petrochemical feedstock volatility threatening converter margins. For New Entrants and Emerging Players: Lead with compostable certification aggregation for California and Maine EPR compliance, targeting mid-size snack brands lacking in-house regulatory affairs capacity. White-space exists in molded fiber ESD protection for semiconductor shipping trays where Yangtze River Delta converters face EU buyer pressure. Go-to-market through equipment retrofit partnerships with Midwest protein packagers consolidating supplier audits. For Investors and Strategic Acquirers: Capital is best deployed toward integrated kraft paper and barrier coating specialists with ECHA-registered alternative portfolios. Long-term viability hinges on regulatory clearance scalability across REACH chemical restrictions and FDA residual monomer limits. Watch for FDA migration testing backlog resolution as inflection signal for new product launch velocity and converter capacity utilization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive metallocene PE supply insulates German converters from crude oil price spikes. |
| Barrier Coating Technology Acquisition | Vapor deposition specialists command premium positioning in pharmaceutical blister specifications. |
| Compostable Certification Program | California EPR compliance creates preference for certified PLA and PHA alternatives. |
| Equipment Retrofit Service Launch | Mid-cap extruders require screw and die modifications to switch from PVC to HDPE. |
| Healthcare Specification Partnership | Dimensional stability validation opens premium margin pools in pharmaceutical packaging. |
Research Methodology
The analysis maps flexible film extrusion, rigid thermoforming, and fiber-based barrier coating sub-sectors, each validated through converter plant managers, retail procurement leads, and regulatory affairs specialists at food brands. Primary interviews with equipment retrofit consultants and migration testing laboratories combined with secondary triangulation against EU REACH enforcement bulletins, FDA food-contact substance filings, and German retail chain packaging covenant disclosures. Bottom-up capacity assessments and top-down demand modeling cross-validated segment outputs.
Consistency checks against customs trade data and SEC filings from listed packaging converters validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product format flexibility, material chemistry tier, end-use regulatory intensity, and geographic compliance cluster. CAGRs derived from elasticity-adjusted demand curves incorporating REACH deadline phasing and EPR law implementation trajectories. Forecast inputs included resin price indices and retail procurement mandate adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity or bioplastic fermentation scale-up would require recalibration. Forecasts reflect documented assumptions about regulatory compliance deadlines and substitution elasticity in protein packaging. Specific risk factors include Thai PLA supply disruption and FDA migration testing backlog extension. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
Green Packaging Market
Sustainable Packaging
Japan Green Packaging Market
Sustainable Packaging
United States Green Packaging Market
Sustainable Packaging
Europe Eco-Friendly Packaging Market
Sustainable Packaging
Areca Plates Market
Sustainable Packaging
Bio-Based Cutlery Market
Sustainable Packaging
Middle East and Africa Eco-Friendly Packaging Market
Sustainable Packaging
Global Disappearing Packaging Market
Sustainable Packaging
Asia-Pacific Sustainable Packaging Market
Sustainable Packaging
Asia-Pacific Eco-Friendly Packaging Market
Sustainable Packaging
Europe Sustainable Packaging Market
Sustainable Packaging
Sustainable Foodservice Packaging Market
Sustainable Packaging
Zero Waste Packaging Market
Sustainable Packaging
Compostable Tableware Market
Sustainable Packaging
Sustainable Plastic Packaging Market
Sustainable Packaging
Europe Green Packaging Market