
 North America Eco-Friendly Packaging Market | 2026-2036
North America Eco-Friendly Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Eco-Friendly Packaging Market Analytics
Food-grade compostable certification is unwinding cost barriers that previously blocked mainstream adoption. Amcor plc leverages its integrated film manufacturing network to secure resin supply for biodegradable applications. WestRock Company anchors North American containerboard recovery through its mill system and retail collection partnerships. Sealed Air differentiates its portfolio with inflatable plant-based cushioning systems that displace petroleum-derived void fill.
North America eco-friendly packaging encompasses materials and containers engineered for reduced environmental persistence, typically incorporating post-consumer recycled fiber content above 35 percent, ASTM D6400 compostable substrates, or bio-based polymers derived from corn starch or sugarcane bagasse, and serves to contain, protect, and present goods while minimizing landfill contribution and fossil resource extraction. Recycled paper dominates volume flows through established municipal recovery infrastructure, yet plant-based plastics capture expanding share as resin costs compress and performance gaps narrow against conventional polyethylene. Food & Beverage end users drive specification intensity, with fresh produce and prepared meal segments demanding moisture-barrier coatings that meet FDA food-contact requirements without perfluorinated compounds.
EPA recycled content guidelines, California SB 54 extended producer responsibility mandates, and FDA food-contact notification requirements collectively reshape material eligibility and compliance costs across the value chain. The Federal Trade Commission's Green Guides enforcement actions are tightening substantiation standards for environmental marketing claims, forcing label revisions and third-party certifications. Stakeholders must monitor emerging state-level packaging EPR legislation in New York and Colorado to anticipate compliance scope expansion and infrastructure investment timing.
Market Dynamics
California SB 54 mandates 30 percent recycled content in plastic packaging by 2028, forcing converters across the Great Lakes corridor to requalify resin streams and retool extrusion lines ahead of enforcement deadlines.
Growth Catalysts
- Extended Producer Responsibility Mandates:California SB 54 assigns end-of-life costs to brand owners, redirecting capital toward domestic recycling infrastructure and certified compostable alternatives.
- Plant-Based Resin Cost Compression:Corn starch and sugarcane bagasse-derived polymers achieve price parity with virgin polyethylene in high-volume food service applications.
- Great Lakes Manufacturing Concentration:Michigan, Ohio, and Ontario host integrated paperboard mills and blow-molding facilities that shorten logistics loops for CPG brands.
Market Restraints
- Post-Consumer Recycled Resin Supply Volatility:Baled PET and HDPE availability fluctuates with municipal collection rates, squeezing converters dependent on FDA food-contact certified flake.
- Composting Infrastructure Gaps:Industrial composting facilities accepting ASTM D6400-certified packaging remain concentrated in the Pacific Northwest and Northeast, leaving central states with landfill diversion bottlenecks.
- Per-Unit Cost Premium:Bio-based flexible films carry 15-40 percent cost premiums versus conventional multilayer structures, limiting penetration in private-label retail.
Strategic Opportunities
- Canadian Prairie Expansion:Alberta and Saskatchewan agricultural processing clusters generate underutilized wheat straw fiber feedstocks for molded pulp packaging serving protein and dairy exporters.
- Pharmaceutical Cold Chain:Cellulose-based insulated shippers with phase-change materials capture share from expanded polystyrene in temperature-sensitive biologics distribution.
- FTC Green Guides Compliance Services:Third-party substantiation of environmental marketing claims creates recurring revenue streams for certification bodies and testing laboratories.
Industry Challenges
- Food-Contact Notification Timelines:FDA clearance for novel bio-based barrier coatings extends 18-24 months, delaying product launches and freezing R&D budgets.
- Legacy Heat-Seal Equipment Retrofit:Converting lines engineered for polyolefin webs require temperature and pressure recalibration to run compostable films without seal integrity failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Eco-Friendly Packaging Market |
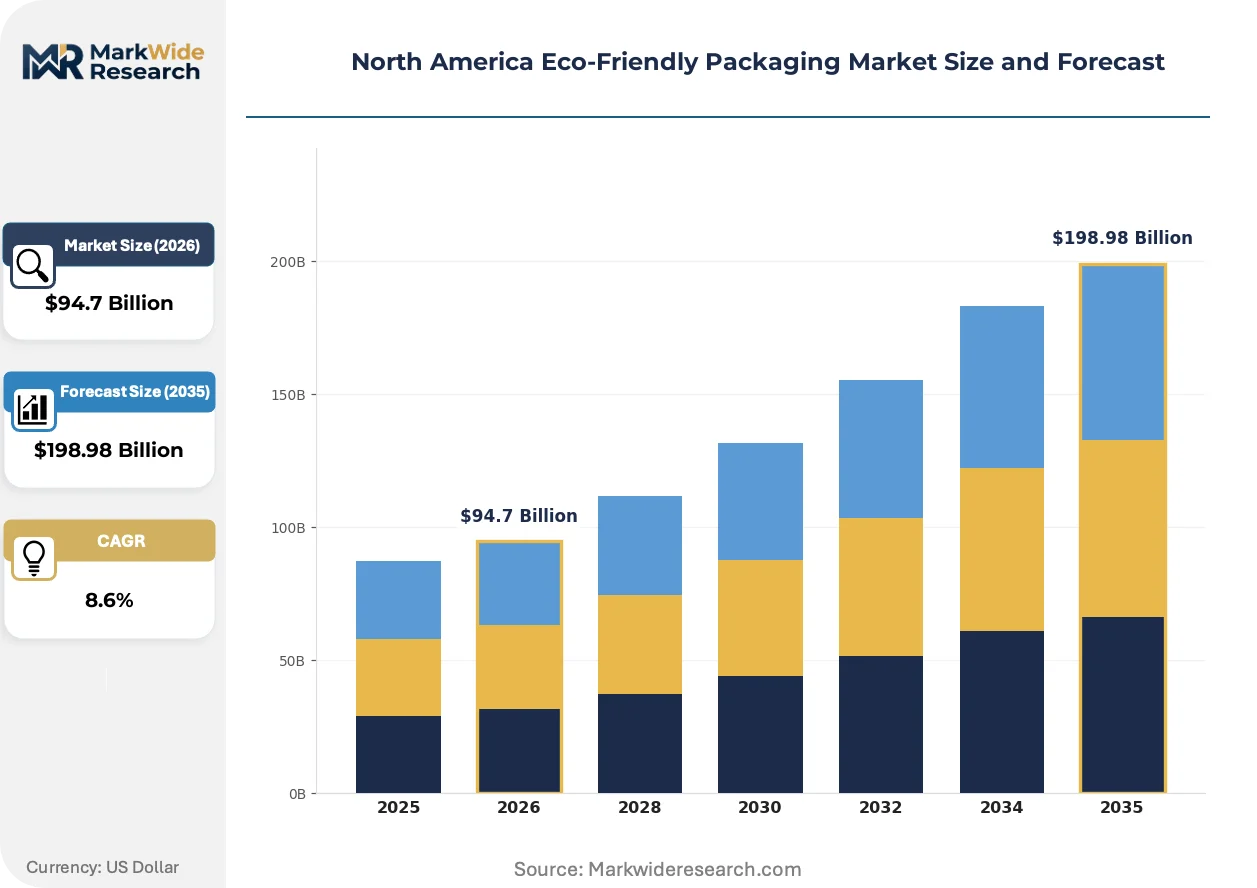
| Market Size in 2026 | $94.7 Billion |
| Market Size in 2035 | $198.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable Bags, Recycled Paper, Glass Containers, Plant-Based Plastics End User: Food & Beverage, Personal Care, Pharmaceuticals, Consumer Electronics Packaging Type: Boxes, Tapes, Labels, Wrappers Distribution Channel: Retail, E-commerce, Wholesale, Direct Sales |
| Companies Covered | Amcor plc, WestRock Company, Tetra Pak, Sealed Air, Sonoco Products Company, International Paper, Berry Global Inc., Smurfit Kappa, Evergreen Packaging LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Eco-Friendly Packaging Market Evolving Landscape
Material scientists and packaging engineers are converging on drop-in replacements that satisfy existing equipment constraints while eliminating fossil-derived inputs.
Barrier-coated molded fiber is displacing expanded polystyrene clamshells in fresh produce and prepared meal segments. Major grocery retailers specify this substrate for private-label ready-to-eat categories. The shift is compressing demand for petroleum-based thermal insulation across North American cold-chain logistics.
EPA recycled content guidelines for federal procurement are tightening eligibility standards for paperboard and plastic containers. Domestic mills must document chain-of-custody certification to qualify for government supply contracts. Foodservice distributors serving K-12 and institutional segments are reformulating specifications to meet these thresholds.
Direct supplier-brand partnerships are replacing spot-market resin purchasing for compostable packaging. Large CPGs negotiate multi-year offtake agreements with bio-refineries to secure volume and price stability. This restructuring is most visible in the prepared meal and snack categories where shelf-life requirements demand consistent material performance.
North America Eco-Friendly Packaging Market Segmentation
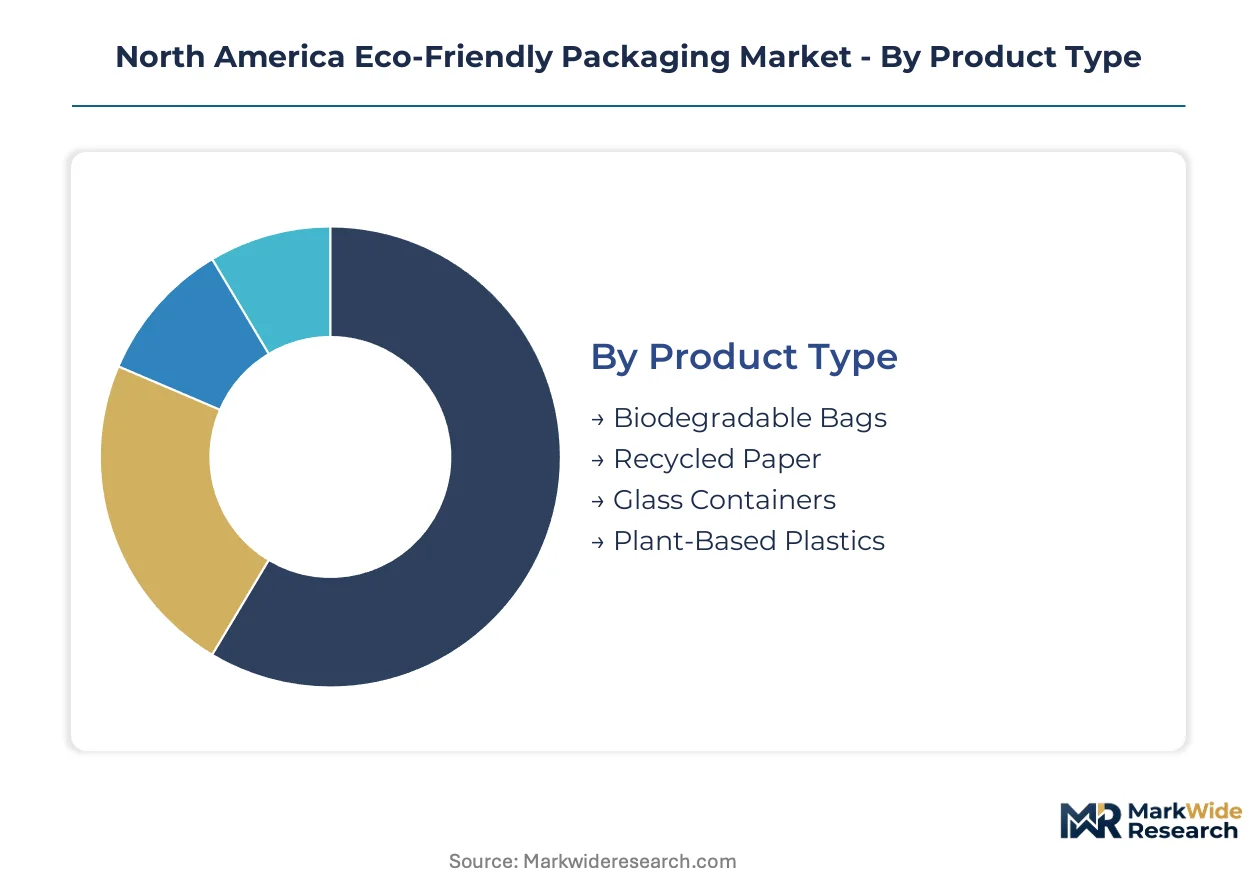
Segmentation in the North America eco-friendly packaging market reveals how regulatory thresholds and material certifications concentrate procurement decisions across distinct product categories and end-use verticals. Understanding these divisions exposes where compliance costs and supply chain reconfigurations create competitive advantage.
Product Type:
FDA food-contact notification requirements and California SB 54 recycled content mandates split procurement specifications across material categories, with converters requalifying resin streams to meet divergent compliance timelines.
- Biodegradable Bags:ASTM D6400-certified films derived from corn starch or sugarcane bagasse serve prepared meal and fresh produce segments requiring industrial composting infrastructure. Demand concentrates in the Pacific Northwest and Northeast where municipal composting facilities accept these substrates, though central states face landfill diversion bottlenecks.
- Recycled Paper:Post-consumer fiber content above 35 percent dominates volume flows through established municipal recovery infrastructure, with Great Lakes mills leveraging integrated production networks to serve K-12 and institutional foodservice distributors meeting EPA federal procurement guidelines.
- Glass Containers:Infinitely recyclable silica-based packaging retains premium positioning in personal care and pharmaceutical segments where chemical inertness outweighs weight penalties.
- Plant-Based Plastics:Bio-based polymers achieve price parity with virgin polyethylene in high-volume food service applications, capturing expanding share as performance gaps narrow against conventional polyethylene.
Recycled paper handles the majority of throughput; plant-based plastics is the fastest mover on share.
End User:
End-use verticals impose distinct barrier requirements and regulatory scrutiny that reshape material selection priorities and certification investments.
- Food & Beverage:Moisture-barrier coatings must meet FDA food-contact requirements without perfluorinated compounds, driving specification intensity in fresh produce and prepared meal segments across the Great Lakes manufacturing corridor.
- Personal Care:Brands face FTC Green Guides enforcement actions tightening substantiation standards for environmental marketing claims, forcing label revisions and third-party certifications.
- Pharmaceuticals:Cellulose-based insulated shippers with phase-change materials capture share from expanded polystyrene in temperature-sensitive biologics distribution.
- Consumer Electronics:Inflatable plant-based cushioning systems displace petroleum-derived void fill in e-commerce fulfillment networks.
Food & Beverage commands the largest procurement volumes; Pharmaceuticals is climbing the fastest on compliance-driven material substitution.
Packaging Type:
Format selection determines equipment retrofit requirements and heat-seal parameter recalibration needs across converting lines.
- Boxes:Barrier-coated molded fiber displaces expanded polystyrene clamshells in fresh produce and prepared meal segments, with major grocery retailers specifying this substrate for private-label ready-to-eat categories.
- Tapes:Pressure-sensitive adhesives formulated from bio-based tackifiers serve corrugated sealing applications in e-commerce fulfillment.
- Labels:Direct-print compostable substrates eliminate liner waste in produce and beverage applications.
- Wrappers:Flexible films engineered for home composting address snack and confectionery segments with shorter shelf-life requirements.
Boxes absorb the greatest material tonnage; Wrappers is gaining share fastest on single-use plastic reduction commitments.
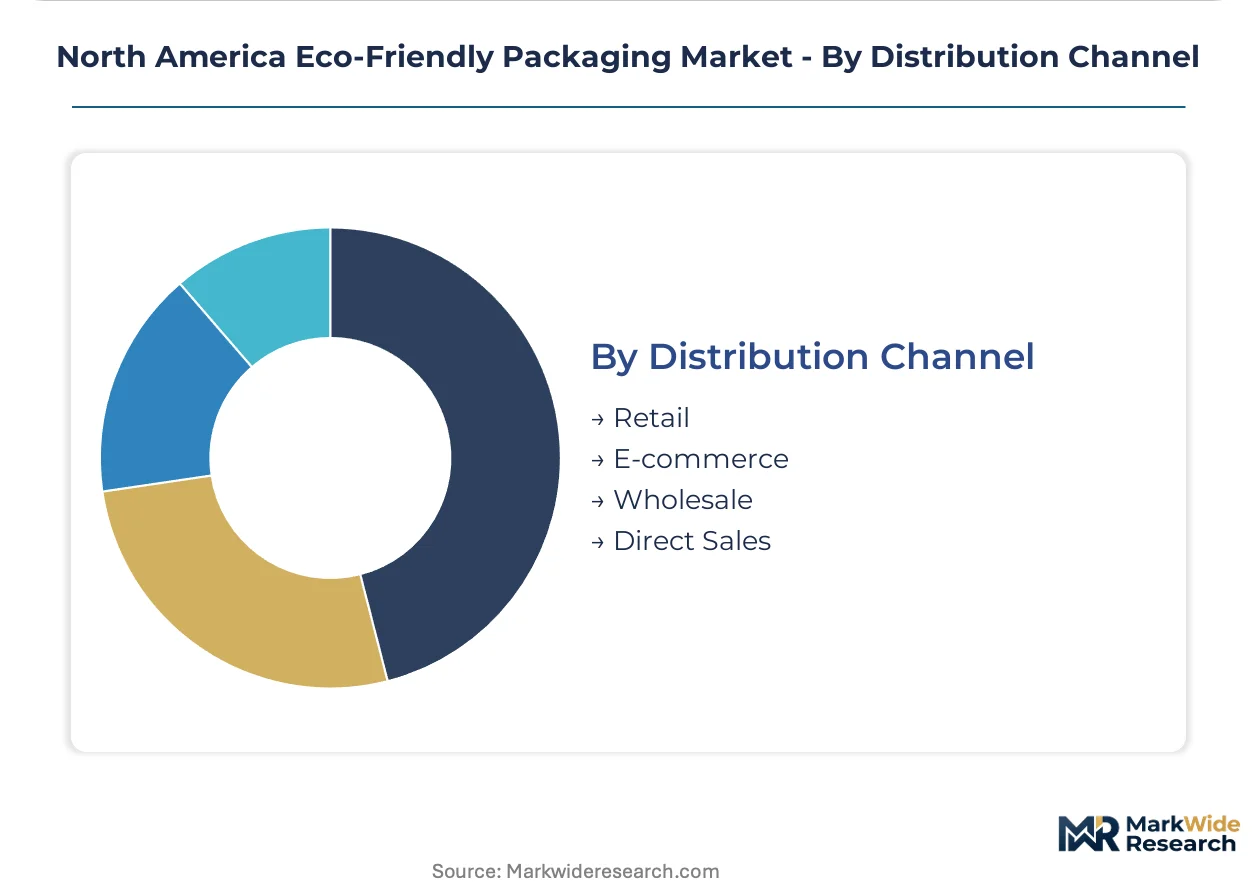
Distribution Channel:
Channel structure dictates lot size, customization depth, and sustainability documentation requirements that filter supplier eligibility.
- Retail:Private-label specifications from major grocery chains drive consolidated procurement of certified compostable packaging, with direct supplier-brand partnerships replacing spot-market resin purchasing.
- E-commerce:Void-fill and cushioning specifications prioritize dimensional weight reduction alongside material renewability, favoring inflatable plant-based systems.
- Wholesale:Foodservice distributors serving institutional segments reformulate specifications to meet EPA recycled content thresholds for government supply contracts.
- Direct Sales:Brand-owned channels enable premium positioning of bio-based packaging with full chain-of-custody documentation.
Retail channels move the highest packaging volumes; E-commerce is expanding most quickly on fulfillment network growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated paperboard mills and blow-molding facilities cluster along the Great Lakes corridor, shortening logistics loops for CPG brands. Michigan, Ohio, and Ontario host the densest concentration of converting capacity. EPA recycled content guidelines and California SB 54 extended producer responsibility mandates are redirecting capital toward domestic infrastructure.
United States
California SB 54 mandates 30 percent recycled content in plastic packaging by 2028, forcing converters to requalify resin streams and retool extrusion lines ahead of enforcement deadlines. The EPA's federal procurement guidelines tighten eligibility standards for paperboard and plastic containers. The Great Lakes manufacturing corridor spanning Michigan and Ohio anchors North American containerboard recovery through integrated mill systems.
Canada
Extended producer responsibility frameworks in Ontario and British Columbia assign end-of-life costs to brand owners, accelerating material transitions to certified compostable alternatives. Health Canada and PMRA coordinate food-contact safety standards with FDA alignment. The Prairie Provinces generate underutilized wheat straw fiber feedstocks for molded pulp packaging serving protein and dairy exporters.
Mexico
Nearshoring trends are pulling packaging specification decisions northward as US brands regionalize supply chains to reduce transit emissions. Mexican environmental regulators are drafting recycled content standards modeled on California's SB 54 framework. The Bajío Region and Northern Border States are attracting blow-molding and thermoforming investments to serve cross-border CPG distribution.
North America Eco-Friendly Packaging Market Competitive Landscape
Concentration sits with diversified packaging conglomerates that operate integrated mill networks and film manufacturing facilities. The vendor base spans three tiers: global integrated players with captive resin supply, regional converters with specialized equipment, and niche bio-material specialists focused on compostable certifications. Consolidation is accelerating through mill system acquisitions and multi-year offtake agreements with bio-refineries. Strategic partnerships between CPG brands and resin suppliers are replacing spot-market purchasing.
Among the integrated tier, Amcor plc, WestRock Company, and Sealed Air exemplify distinct archetypes. Amcor plc represents the film manufacturing specialist with global resin sourcing networks. WestRock Company anchors the containerboard recovery segment through mill system ownership. Sealed Air occupies the protective packaging vector with inflatable cushioning systems. These three entities collectively demonstrate how scale, vertical integration, and material science capabilities define competitive positioning in the North American market.
| Leading Market Players |
|---|
| Amcor plc |
| WestRock Company |
| Tetra Pak |
| Sealed Air |
| Sonoco Products Company |
| International Paper |
| Berry Global Inc. |
| Smurfit Kappa |
| Evergreen Packaging LLC |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between CPG brands and bio-refineries lock in resin supply visibility while stabilizing unit economics against volatile post-consumer recycled flake markets. California SB 54 compliance deadlines and FDA food-contact notification timelines compress procurement decisions into multi-year contracts that anchor price floors for certified compostable substrates.
Pricing Analysis
California SB 54 dictates the pricing tier structure across the North American eco-friendly packaging landscape. Three-tier pricing structure across premium, standard, and economy levels separates ASTM D6400-certified compostable films from post-consumer recycled paperboard and virgin bio-based alternatives. Cost compression in plant-based resins is intensifying because corn starch and sugarcane bagasse polymers achieve parity with virgin polyethylene in high-volume food service applications. Private-label retail buyers exhibit the highest price sensitivity, while pharmaceutical cold-chain distributors absorb premiums for cellulose-based insulated shippers.
Supply Chain Analysis
The United States and Canada anchor North American containerboard recovery through integrated mill systems in Michigan, Ohio, and Ontario. Raw material flows draw from wheat straw fiber feedstocks in the Prairie Provinces, post-consumer baled PET and HDPE from municipal collection infrastructure, and bio-refinery resin streams from agricultural processing clusters. Single-source vulnerability concentrates in industrial composting facilities accepting ASTM D6400-certified packaging, which remain concentrated in the Pacific Northwest and Northeast. Distribution runs through direct supplier-brand partnerships that displace spot-market resin purchasing for large CPG accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America eco-friendly packaging represents a high-growth disruption as California SB 54 and extended producer responsibility frameworks force material transitions ahead of enforcement deadlines. Plant-based resin cost compression and compostable certification standardization create inflection points for competitive repositioning.
For Market Incumbents: Compound backward integration into bio-refinery capacity to secure captive supply of corn starch and sugarcane bagasse-derived polymers. Accelerate mill system acquisitions in the Great Lakes corridor to consolidate containerboard recovery infrastructure against emerging molded pulp competitors. Lock in multi-year offtake agreements with protein and dairy exporters to preempt Prairie Province wheat straw fiber utilization by rival converters. For New Entrants and Emerging Players: Lead with pharmaceutical cold-chain applications where cellulose-based insulated shippers displace expanded polystyrene in temperature-sensitive biologics distribution. Target the Canadian Prairie Provinces for wheat straw fiber molded pulp packaging serving agricultural export clusters with underutilized feedstock access. Pursue direct sales channels enabling premium positioning with full chain-of-custody documentation rather than competing on price in consolidated retail procurement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among certification bodies and testing laboratories delivering FTC Green Guides compliance services. Five-to-ten-year viability favors converters with integrated film manufacturing networks and established retail collection partnerships over asset-light trading operations. Monitor FDA food-contact notification clearance timelines as the critical signal for bio-based barrier coating commercialization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Refinery Capacity | Captive resin supply from corn starch and sugarcane bagasse secures volume and price stability against volatile post-consumer flake markets. |
| Mill System Acquisition in Great Lakes Corridor | Integrated paperboard production in Michigan and Ontario shortens logistics loops for CPG brands meeting EPA federal procurement guidelines. |
| Multi-Year Offtake Agreement with Bio-Refinery | Direct supplier-brand partnerships replace spot-market purchasing and lock in consistent material performance for shelf-life-critical applications. |
| FTC Green Guides Compliance Certification | Third-party substantiation of environmental marketing claims creates recurring revenue streams as enforcement actions tighten substantiation standards. |
| Prairie Province Wheat Straw Fiber Utilization | Underutilized agricultural processing feedstocks in Alberta and Saskatchewan enable molded pulp packaging for protein and dairy exporters. |
Research Methodology
A standing panel of sustainability officers at CPG brands, procurement directors at foodservice distributors, mill operations managers, and regulatory compliance specialists provided ongoing calibration across the analysis window. Primary interviews with these stakeholders combined with secondary validation from EPA recycled content guidelines, California SB 54 regulatory filings, FDA food-contact notification databases, and municipal recovery infrastructure reports. Bottom-up volume modeling across biodegradable bags, recycled paper, and plant-based plastics categories triangulated against top-down market sizing from trade association data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type certification tier, end-use vertical barrier requirements, packaging format equipment compatibility, and distribution channel lot-size constraints. CAGRs derived from historical trajectory analysis and regulatory-driven substitution elasticity parameters incorporated plant-based resin cost compression curves and composting infrastructure expansion timelines as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained California SB 54 enforcement, FDA clearance timeline compression, or municipal composting facility expansion would require recalibration. Forecasts reflect documented assumptions regarding resin supply stability, brand owner capital allocation to compliance, and post-consumer collection rate trends. Recalibration cycles align with material shifts in extended producer responsibility legislation adoption across additional states.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
Compostable Tableware Market
Sustainable Packaging
Eco-Friendly Straw Market
Sustainable Packaging
Bio-Based Cutlery Market
Sustainable Packaging
Green Packaging Market
Sustainable Packaging
Sustainable Plastic Packaging Market
Sustainable Packaging
Eco Friendly Bottles Market
Sustainable Packaging
Middle East and Africa Eco-Friendly Packaging Market
Sustainable Packaging
Plant Based Packaging Market
Sustainable Packaging
GCC Green Packaging Market
Sustainable Packaging
Europe Green Packaging Market
Sustainable Packaging
Global Paper Straw Market
Sustainable Packaging
Global Disappearing Packaging Market
Sustainable Packaging
Compostable Food Trays Market
Sustainable Packaging
Bagasse Tableware Products Market
Sustainable Packaging
Areca Plates Market
Sustainable Packaging
Wheat Straw Cutlery Market