
 Eco Friendly Bottles Market | 2026-2036
Eco Friendly Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Eco Friendly Bottles Market Analysis
Corporate procurement teams are bifurcating away from individual consumers as the dominant buyer archetype in sustainable packaging. Ecologic Brands leverages molded fiber shell technology to anchor supply relationships with multinational beverage companies. Klean Kanteen competes through stainless steel durability positioning that extends product lifecycle claims for B2B clients. Hydro Flask controls premium placement in corporate wellness programs, differentiating through vacuum insulation specialization that commands higher contract values.
Eco friendly bottles are rigid containers engineered from renewable, recyclable, or biodegradable substrates—typically incorporating post-consumer recycled PET, polylactic acid biopolymers, borosilicate glass, or food-grade stainless steel—with wall thicknesses and seal tolerances designed to replace single-use packaging in liquid transport applications. Biodegradable plastic formulations currently lead material type segmentation due to compostability certifications that unlock municipal waste stream access, though stainless steel commands the deepest margin pools through durability premiums and replacement cycle compression. Online retail channels are expanding fastest among distribution channels as direct-to-consumer subscriptions reduce per-unit logistics costs for refillable formats.
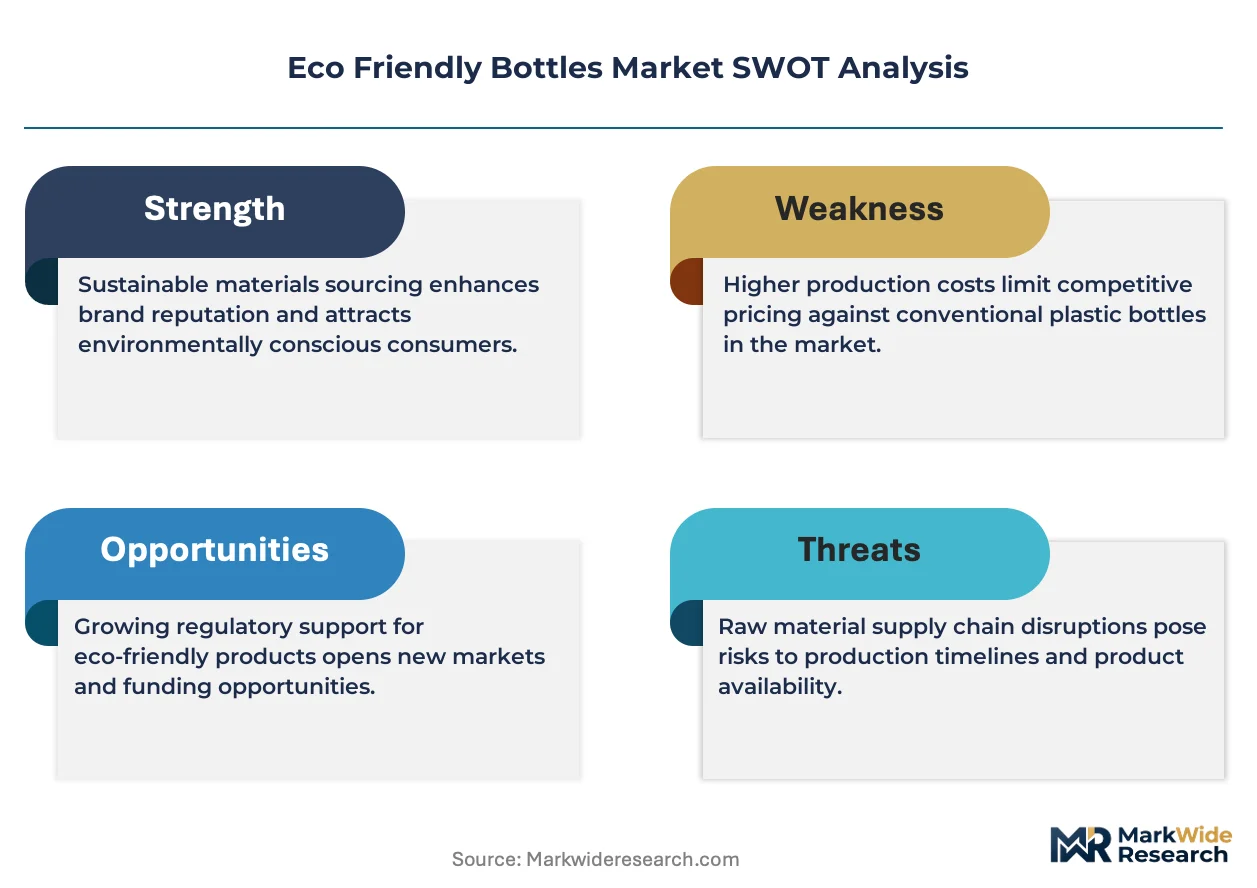
The EPA regulates recycled content claims under Green Guides enforcement, while the EU Green Deal's Packaging and Packaging Waste Regulation mandates minimum recycled thresholds that reshape product design specifications for export-bound manufacturers. India's BIS certification requirements for food-contact materials create additional compliance layers for bioplastic entrants targeting the country's urban retail chains. Stakeholders must monitor how fragmented national labeling standards for biodegradability will influence material selection decisions and cross-border formulation strategies.
Market Dynamics
Extended Producer Responsibility mandates across the European Union are compressing design-to-recycling timelines and forcing material substitution decisions upstream in beverage supply chains. Deposit-return systems in Germany and the Netherlands now capture over 90% of refillable bottle circulation, creating template compliance architectures that multinational brands must replicate across manufacturing footprints.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Minimum recycled content thresholds for PET containers trigger capital allocation toward post-consumer recycling infrastructure in export-oriented manufacturing hubs.
- Stainless steel durability premiums:Corporate wellness programs and B2B procurement contracts favor vacuum-insulated formats that compress replacement cycles and reduce total cost of ownership calculations.
- India:Urban retail chain expansion and BIS certification harmonization for food-contact biopolymers unlocks municipal waste stream access for compostable bottle formats in tier-one cities.
Market Restraints
- Post-consumer recycled PET supply concentration:Collection infrastructure gaps in Southern and Eastern Europe create feedstock bottlenecks that elevate input costs for rPET-dependent manufacturers.
- Biodegradation certification fragmentation:Competing municipal composting standards across France, Italy, and Spain force formulation customization that erodes production scale economies.
- Glass weight penalties:Borosilicate and soda-lime formats face logistics cost disadvantages against lighter substrates in e-commerce fulfillment networks.
Strategic Opportunities
- Direct-to-consumer subscription channels:Refillable bottle programs bypass retail margin extraction and build recurring revenue streams with predictable demand forecasting.
- Polylactic acid and polyhydroxyalkanoate convergence:Blended biopolymer formulations achieve heat resistance thresholds that open hot-fill beverage applications previously closed to plant-based substrates.
- US Green Guides enforcement:EPA recycled content claim verification creates first-mover advantage for brands with third-party certified supply chain documentation.
Industry Challenges
- Molded fiber shell engineering talent scarcity:Wet-forming process optimization for beverage-grade durability requires specialized material science expertise concentrated in limited geographic clusters.
- Multi-jurisdiction labeling compliance:Simultaneous satisfaction of EU Green Deal, US FTC Green Guides, and India BIS requirements extends product launch timelines and legal review costs.
- Legacy blow-molding equipment retrofitting:Transitioning PET lines to biopolymer-compatible processing temperatures demands capital expenditure with uncertain throughput recovery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eco Friendly Bottles Market |
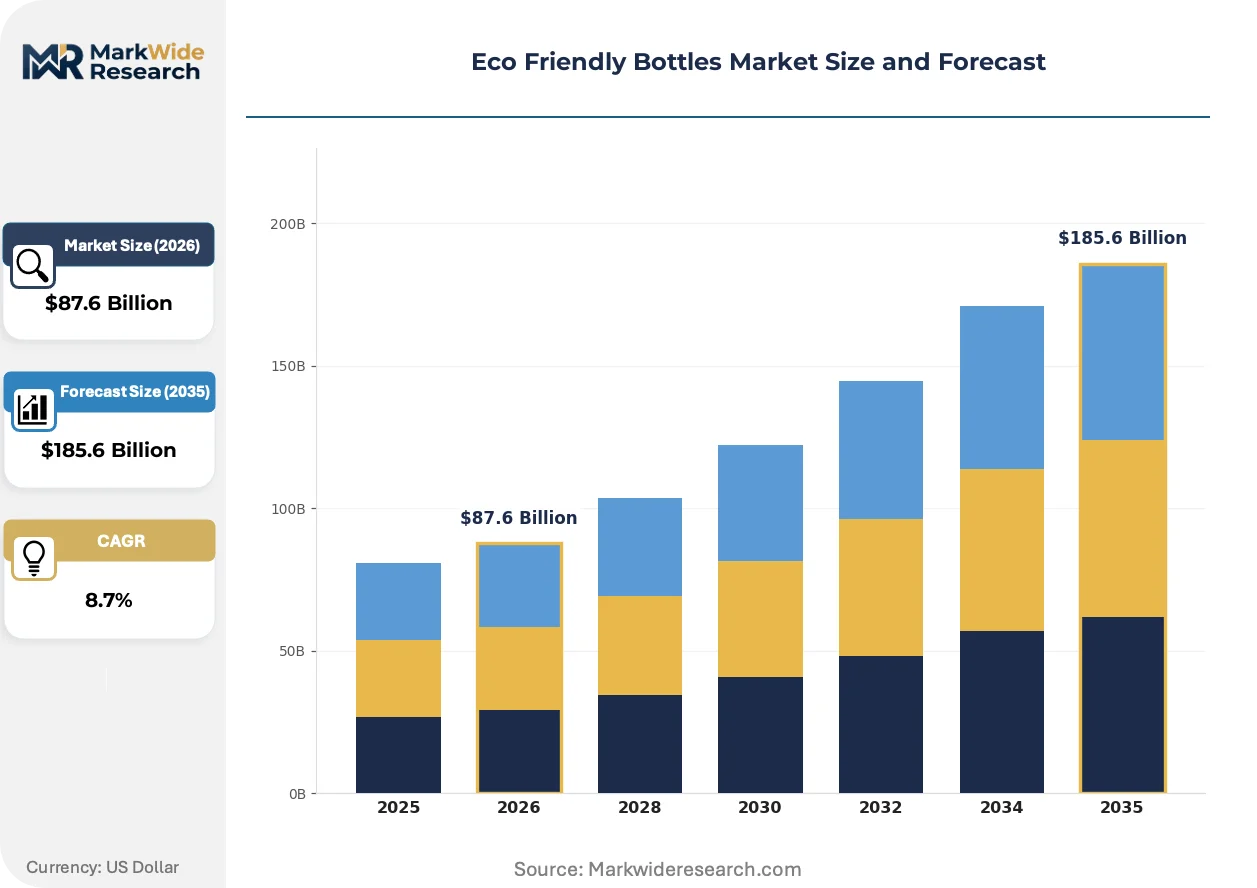
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $185.6 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Glass, Biodegradable Plastic, Recycled Plastic, Stainless Steel End User: Consumers, Corporations, Retail Chains, Event Organizers Design Style: Sporty, Minimalistic, Customized, Functional Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Ecologic Brands, One Green Bottle, Cascade Designs, SKS Bottle & Packaging, EarthLust, Pachamama, Hydro Flask, Klean Kanteen, CamelBak Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eco Friendly Bottles Market Emerging Trajectories
Material science breakthroughs and regulatory enforcement intensification are bifurcating competitive advantage between durability-positioned metal formats and disposability-positioned biopolymer alternatives. The innovation frontier now concentrates on hybrid substrates that satisfy multiple end-of-life pathways without sacrificing performance specifications.
Algae-derived and agricultural waste-based biopolymers are fragmenting the conventional PLA supply base by offering regionally sourced feedstock alternatives that reduce transportation emissions and qualify for national bioeconomy subsidies. Beverage brands with net-zero commitments are piloting these materials in limited regional releases to validate composting infrastructure compatibility before scaling. The resulting substrate diversification is fragmenting supplier consolidation patterns that previously favored petrochemical incumbents with integrated resin production.
REACH authorization requirements for intentional microplastics additives are forcing reformulation of conventional biodegradable plastics that relied on oxo-degradation accelerants. Manufacturers serving EU export markets must eliminate these additives or face market access restrictions under the restriction procedure. The regulatory pressure is compressing development timelines for enzymatic and marine-biodegradable alternatives that satisfy the stricter biodegradation testing protocols.
Bulk dispensing systems in corporate foodservice and hospitality are displacing individual bottle procurement through centralized refill infrastructure that transfers packaging ownership to facility operators. This operational model shift transfers compliance burden from beverage brands to institutional buyers while reducing per-serve material intensity. Germany and Scandinavia demonstrate the highest penetration of this model, driven by municipal procurement guidelines that prioritize packaging elimination over material substitution.
Eco Friendly Bottles Market Segmentation
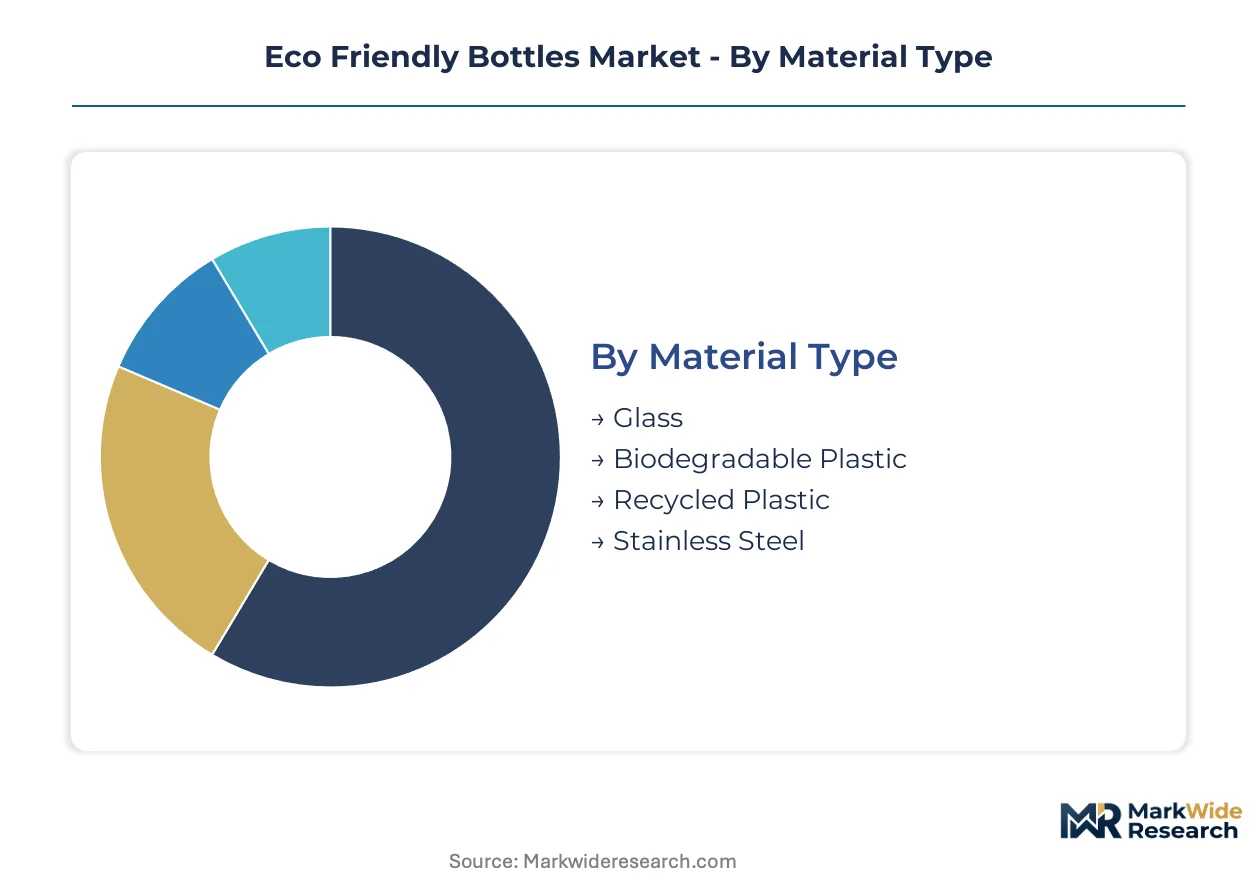
Material substrate selection and procurement channel configuration determine margin architecture and compliance exposure across the eco-friendly bottle value chain. Segment-specific demand patterns reveal divergent growth trajectories between durability-positioned metal formats and disposability-positioned biopolymer alternatives.
Material Type:
Domestic manufacturing clusters in Germany and the Netherlands anchor European supply for refillable formats, while export-oriented production concentrates in China and India for cost-sensitive biodegradable variants.
- Biodegradable Plastic:Formulations incorporating polylactic acid and polyhydroxyalkanoate achieve compostability certifications that unlock municipal waste stream access in France and Italy. Demand concentrates in urban retail chains across tier-one European cities where Extended Producer Responsibility mandates accelerate material substitution away from conventional plastics.
- Stainless Steel:Vacuum-insulated double-wall construction delivers durability premiums that compress replacement cycles in corporate wellness programs and B2B procurement contracts. German beverage brands and Scandinavian institutional buyers favor this substrate for total cost of ownership calculations in high-frequency use environments.
- Glass:Borosilicate and soda-lime formats serve premium positioning in specialty retail channels despite logistics weight penalties in e-commerce fulfillment networks.
- Recycled Plastic:Post-consumer rPET content satisfies EU Green Deal minimum thresholds for export-bound manufacturers while facing feedstock bottlenecks from collection infrastructure gaps in Southern and Eastern Europe.
Stainless steel commands the established base. The steepest expansion runs through biodegradable plastic.
End User:
Procurement authority is migrating from individual consumers toward institutional buyers with sustainability mandates and volume contracting power.
- Corporations:Bulk purchasing through centralized procurement functions prioritizes durability specifications and third-party certified supply chain documentation for ESG reporting compliance.
- Retail Chains:Private-label development and shelf-space allocation decisions favor substrates with clear disposal pathway labeling for consumer clarity in Germany and the Netherlands.
- Consumers:Direct-to-consumer subscription models reduce per-unit logistics costs for refillable formats in urban density corridors.
- Event Organizers:Temporary deployment scenarios favor compostable formats with rapid biodegradation certification for post-event waste stream integration.
Corporate procurement anchors volume concentration. Consumer subscriptions deliver the most rapid demand scaling.
Design Style:
Functional performance specifications dominate B2B selection criteria while aesthetic differentiation drives retail velocity in saturated consumer channels.
- Functional:Ergonomic grip geometry, leak-proof seal tolerances, and thermal retention specifications satisfy institutional procurement requirements for high-rotation use environments.
- Customized:Corporate branding integration and co-manufacturing partnerships enable beverage companies to transfer packaging compliance burden through private-label arrangements.
- Minimalistic:Reduced component count and modular disassembly support end-of-life recycling claims under EPA Green Guides enforcement.
- Sporty:Carabiner compatibility and single-hand operation features target athletic use cases with replacement cycle compression potential.
Functional design holds the procurement base. Customized formats are gaining share fastest in corporate channel expansion.
Distribution Channel:
Channel selection determines margin extraction architecture and compliance documentation requirements for recycled content claims.
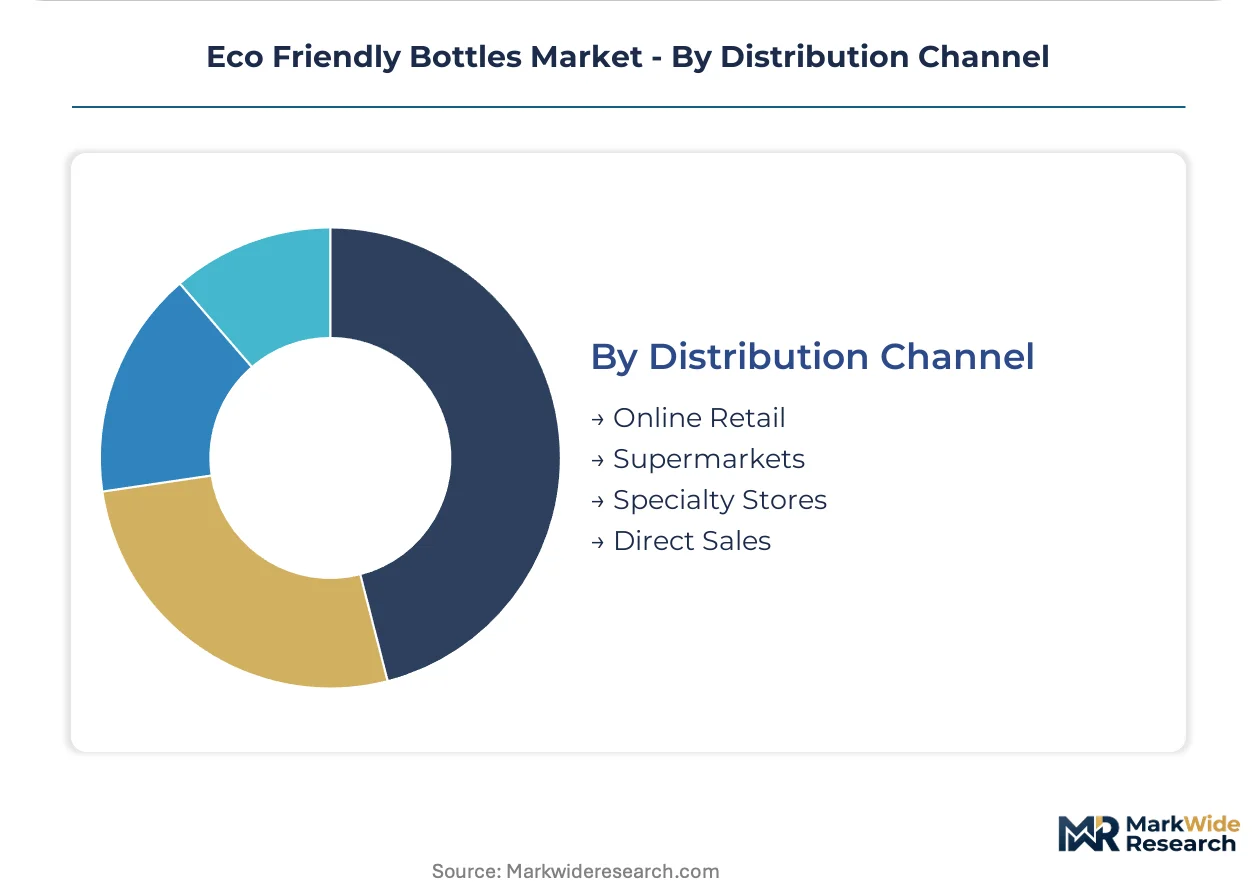
- Online Retail:Direct-to-consumer subscriptions bypass retail margin extraction and build recurring revenue streams with predictable demand forecasting for refillable formats.
- Direct Sales:B2B contract manufacturing relationships enable beverage brands to specify substrate composition and certification requirements upstream in supply chains.
- Supermarkets:Shelf-space negotiations prioritize SKUs with EU harmonized labeling for biodegradability to minimize consumer confusion at point of purchase.
- Specialty Stores:Premium positioning and educational staff interaction support higher price realization for vacuum-insulated metal formats with extended warranty positioning.
Supermarkets maintain the volume base. Online retail demonstrates the steepest trajectory in channel mix evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports biodegradable plastic bottle components to European beverage brands seeking EU Green Deal compliance, while German manufacturers supply vacuum-insulated stainless steel formats to corporate wellness programs across Scandinavia and North America.
Germany
Deposit-return systems capture over ninety percent of refillable bottle circulation, creating template compliance architectures for multinational replication. The EU Packaging and Packaging Waste Regulation mandates minimum recycled thresholds that reshape design specifications for export-bound producers. Manufacturing clusters in North Rhine-Westphalia concentrate molded fiber shell production for beverage-grade applications.
United States
Corporate procurement teams prioritize durability specifications and third-party certified supply chain documentation for ESG reporting compliance. EPA Green Guides enforcement regulates recycled content claims and creates first-mover advantage for brands with verified documentation. Production concentrates in Pacific Northwest states where aluminum and stainless steel fabrication heritage supports vacuum-insulated format manufacturing.
India
Urban retail chain expansion in tier-one cities drives compostable bottle format adoption for municipal waste stream access. BIS certification requirements for food-contact biopolymers create compliance layers for domestic and foreign entrants. Manufacturing gravity centers on Gujarat and Maharashtra where polymer processing infrastructure supports PLA and PHA formulation blending.
France
Extended Producer Responsibility mandates accelerate material substitution away from conventional plastics in urban retail channels. REACH authorization requirements for intentional microplastics additives force reformulation of oxo-degradation accelerants. Industrial activity clusters around Lyon and the Auvergne-Rhône-Alpes region where packaging innovation labs pilot algae-derived biopolymer alternatives.
Netherlands
Deposit-return system infrastructure achieves capture rates comparable to German benchmarks, driving refillable format circulation. Municipal procurement guidelines prioritize packaging elimination over material substitution in institutional foodservice. The Randstad metropolitan concentration hosts bulk dispensing system pilots that displace individual bottle procurement through centralized refill infrastructure.
Eco Friendly Bottles Market Vendor Landscape
Player mix skews toward material-specialist fabricators with substrate-specific process expertise rather than diversified packaging conglomerates. Market structure exhibits moderate fragmentation across four distinct competitive tiers: durability-positioned metal specialists, disposability-positioned biopolymer innovators, hybrid substrate developers, and private-label contract manufacturers. Strategic archetypes include vacuum-insulation technology leaders, molded fiber shell engineers, and compostable certification aggregators. Dominant competitive moves center on backward integration into post-consumer recycling feedstock and geographic expansion through B2B procurement contract anchoring.
Within the metal durability tier, Hydro Flask and Klean Kanteen exemplify vacuum-insulation specialization that commands premium contract values in corporate wellness programs. Ecologic Brands occupies a position within the molded fiber engineering cluster, representing wet-forming process capabilities for beverage-grade shell applications. These three anchors illustrate how competitive positioning bifurcates between lifecycle extension claims and end-of-life compostability credentials.
| Leading Market Players |
|---|
| Ecologic Brands |
| One Green Bottle |
| Cascade Designs |
| SKS Bottle & Packaging |
| EarthLust |
| Pachamama |
| Hydro Flask |
| Klean Kanteen |
| CamelBak Products |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between rPET converters and beverage brands lock in both post-consumer recycled feedstock access and price visibility against virgin PET volatility under EU Green Deal minimum content mandates. These arrangements compress margin uncertainty for manufacturers while transferring collection infrastructure risk upstream to municipal waste system operators in Germany and the Netherlands.
Pricing Analysis
The vacuum-insulation technology generation commands substantial premiums over single-wall stainless steel and biodegradable plastic alternatives, with pricing stratifying across premium, standard, and economy tiers based on certification grade and thermal retention performance. Corporate wellness programs demonstrate the lowest price sensitivity due to total cost of ownership calculations, while cost-conscious retail chains in Southern Europe exhibit acute sensitivity to rPET input cost fluctuations. Pricing pressure stems from biopolymer feedstock competition with food-grade applications, compressing margins for PLA-dependent formats.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for Chinese-manufactured biodegradable bottle components destined for EU beverage brands. Supply concentrates in China for cost-sensitive biopolymer formats, Germany for vacuum-insulated metal fabrication, and India for emerging PLA-PHA blending capacity. Raw material dependencies center on post-consumer PET flake, food-grade stainless steel coil, and corn-sugar feedstock for polylactic acid resin. Single-source vulnerability runs through rPET collection infrastructure gaps in Eastern Europe. Distribution runs through direct-to-consumer subscription channels and B2B contract manufacturing relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against centralized bulk dispensing systems that eliminate individual bottle procurement entirely. Incumbents must navigate the threat of institutional buyers transferring packaging ownership to facility operators through refill infrastructure.
For Market Incumbents: Fortify backward integration into post-consumer recycling feedstock through long-term municipal collection partnerships in Germany and the Netherlands. Secure vacuum-insulation engineering talent clusters in the Pacific Northwest through targeted acquisition of specialized fabrication shops. These moves defend against biopolymer innovators capturing corporate procurement contracts through compostability certification speed.
For New Entrants and Emerging Players: Lead with algae-derived biopolymer formulations in France and the Auvergne-Rhône-Alpes region to exploit national bioeconomy subsidies and regional composting infrastructure pilots. Target tier-one Indian urban retail chains where BIS certification harmonization creates temporary compliance windows for domestic entrants. Deploy direct-to-consumer subscription models to bypass established retail shelf-space barriers.
For Investors and Strategic Acquirers: Wet-forming process specialists with beverage-grade molded fiber shell capabilities represent the highest-conviction acquisition archetype given talent scarcity and multinational brand demand concentration. Long-term viability hinges on whether hybrid substrate developers can satisfy multiple end-of-life pathways without performance trade-offs. Watch REACH authorization enforcement intensity for intentional microplastics additives as the signal for enzymatic biodegradation technology inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Collection | Secures post-consumer feedstock access under EU Green Deal minimum content thresholds. |
| Direct-to-Consumer Subscription Launch | Bypasses retail margin extraction and builds predictable demand forecasting for refillable formats. |
| Algae-Derived Biopolymer Pilot Program | Qualifies for French national bioeconomy subsidies while validating composting infrastructure compatibility. |
| Vacuum-Insulation Engineering Acquisition | Captures scarce wet-forming talent concentrated in limited Pacific Northwest geographic clusters. |
| BIS Certification Harmonization Investment | Unlocks municipal waste stream access for compostable formats in tier-one Indian urban retail chains. |
Methodological Framework
The analysis maps biodegradable plastic, stainless steel, glass, and recycled plastic substrate segments, each validated through procurement directors at beverage brands, sustainability officers at corporate wellness programs, and category buyers at European retail chains. Primary interviews with supply chain managers at rPET converters and technical directors at biopolymer blenders combined with secondary validation from EU Packaging and Packaging Waste Regulation filings, EPA Green Guides enforcement records, and India BIS certification databases. Bottom-up volume triangulation against top-down value estimates ensured consistency across material type and distribution channel dimensions.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for bottle component imports and beverage industry procurement disclosures. The analytical framework models material substrate, end user archetype, design style, and distribution channel segmentation across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating EU EPR mandate compliance timelines and corporate wellness program adoption rates. Industry-specific forecast inputs include municipal composting infrastructure deployment schedules and REACH authorization restriction procedures.
Forecasts assume regulatory continuity in EU Green Deal implementation, EPA Green Guides enforcement, and India BIS food-contact requirements; material policy shifts would require re-modeling of compliance-driven material substitution timelines. Forecasts reflect assumptions regarding collection infrastructure buildout rates in Southern and Eastern Europe and biopolymer heat resistance threshold improvements. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
Bagasse Bowls Market
Sustainable Packaging
Global Paper Straw Market
Sustainable Packaging
Bio-Based Cutlery Market
Sustainable Packaging
Sustainable Foodservice Packaging Market
Sustainable Packaging
Compostable Food Trays Market
Sustainable Packaging
Green Packaging Market
Sustainable Packaging
Sustainable Packaging Market
Sustainable Packaging
Middle East and Africa Eco-Friendly Packaging Market
Sustainable Packaging
Europe Green Packaging Market
Sustainable Packaging
Asia-Pacific Eco-Friendly Packaging Market
Sustainable Packaging
Europe Sustainable Packaging Market
Sustainable Packaging
Japan Green Packaging Market
Sustainable Packaging
Bagasse Tableware Products Market
Sustainable Packaging
Plant Based Packaging Market
Sustainable Packaging
Wheat Straw Cutlery Market
Sustainable Packaging
Zero Waste Packaging Market