
 Asia-Pacific Sustainable Packaging Market | 2026-2036
Asia-Pacific Sustainable Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Sustainable Packaging Market Insights
Market Context
China's dual carbon goals is recalibrating the capital requirements for new entrants across the Asia-Pacific Sustainable Packaging Market. Amcor plc leverages its integrated film-to-pouch manufacturing footprint to secure long-term supply contracts with multinational food brands. Mondi plc anchors its competitive position through captive pulp supply and kraft paper specialization in Southeast Asian markets.
Technical Definition and Segment Structure
Asia-Pacific sustainable packaging encompasses materials and designs engineered to minimize environmental burden through biodegradation, recyclability, or reusability, typically incorporating post-consumer recycled content above 30 percent or certified compostable substrates meeting ASTM D6400 or EN 13432 protocols. Recyclable paper and biodegradable plant-based materials lead volume deployment, while compostable formats command premium pricing in food service channels across Japan and South Korea. The food and beverage application dominates absolute demand, though personal care segments in Australia and New Zealand exhibit faster growth as clean beauty brands mandate plastic-free secondary packaging.
Regulatory Frame and Outlook
Japan's METI enforces strict recycling targets for plastic packaging, while India's BIS develops compostability certification standards and Australia's APCO coordinates national packaging covenant obligations. These frameworks collectively elevate compliance costs for imports and privilege domestic converters with pre-certified substrate partnerships. Stakeholders must monitor enforcement variance between national regulators and preemptively align testing protocols with the most stringent jurisdiction in their supply chain.
Market Dynamics
China's MEE dual carbon goals are forcing coating and drying process decarbonization across the Asia-Pacific region, recalibrating capital requirements and supplier selection criteria for converters and brand owners alike.
Growth Catalysts
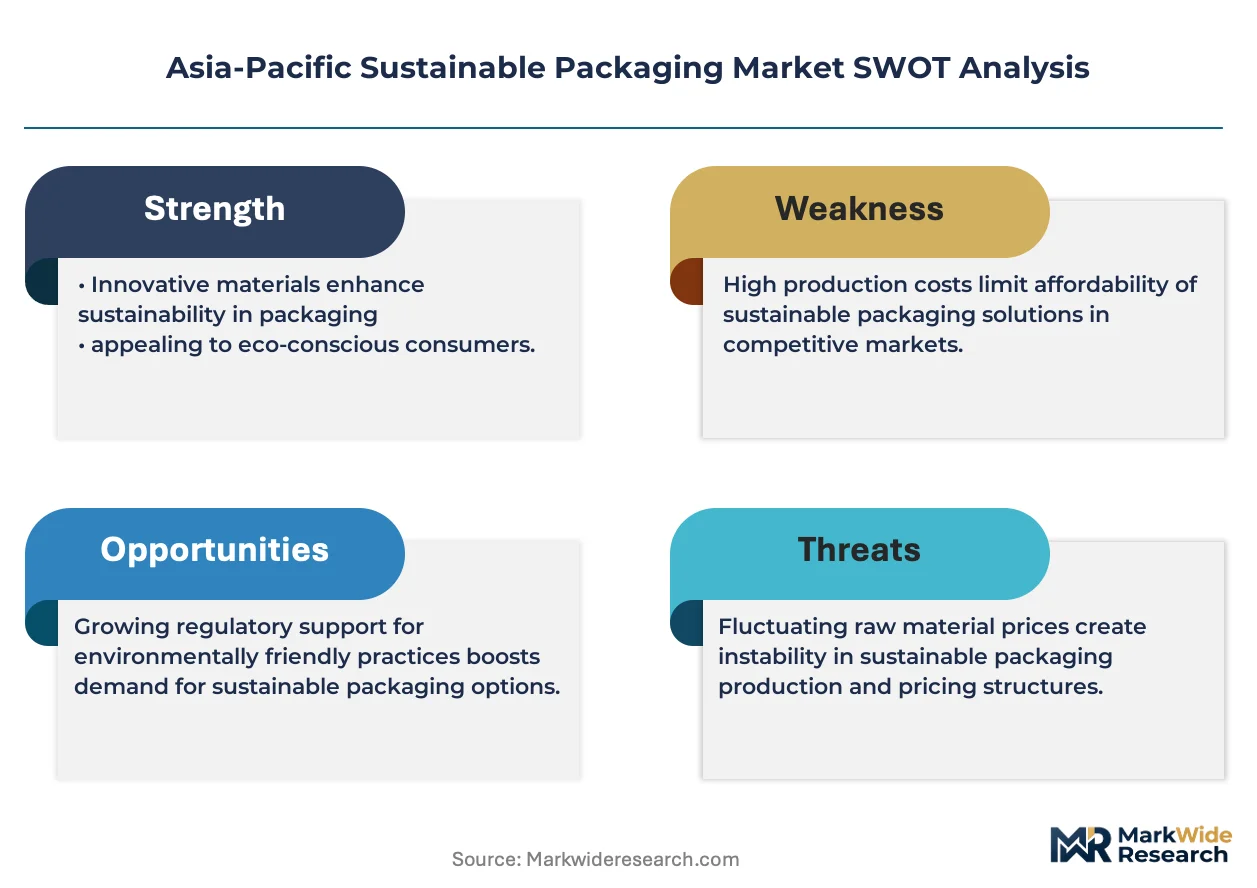
- India's BIS compostability standards:The Bureau of Indian Standards is finalizing certification protocols for compostable substrates, creating regulatory clarity that enables FMCG contract packagers in Maharashtra and Gujarat to scale certified pouch production.
- Fiber-based alternatives in Southeast Asia:Food and beverage brands across Indonesia, Thailand, and Vietnam are replacing conventional plastics with molded fiber and kraft-based formats, driven by retail sustainability mandates and export compliance requirements.
- Japan's METI recycling targets:The Ministry of Economy, Trade and Industry enforces strict plastic packaging recycling quotas, pushing converters toward mono-material designs and post-consumer recycled content above 30 percent.
Market Restraints
- Pulp input cost volatility:Captive pulp supply concentration in Indonesia and Malaysia exposes non-integrated converters to price swings that compress margin structures on kraft and molded fiber products.
- Technical limitation in barrier performance:Plant-based coatings still fail to match aluminum and multi-layer plastic oxygen barriers for shelf-stable dairy and retort applications, restricting adoption in high-performance food segments.
- Regulatory friction from Australia's APCO:The Australian Packaging Covenant Organisation's national obligations create compliance complexity for imports, privileging domestic converters with pre-certified substrate partnerships and raising entry barriers.
Strategic Opportunities
- Vietnam's underpenetrated food service channel:Quick-service restaurant chains and delivery platforms in Ho Chi Minh City and Hanoi lack certified compostable alternatives, creating first-mover space for regional substrate suppliers.
- Technology convergence of digital printing and water-based barriers:Inkjet and flexo systems combined with bio-based coatings enable short-run customization for clean beauty brands in Australia and New Zealand seeking plastic-free secondary packaging.
- South Korea's regulatory tailwind:Extended producer responsibility frameworks and single-use plastic bans in Seoul's food service sector accelerate demand for certified compostable formats meeting EN 13432 protocols.
Industry Challenges
- Certification timeline compression:ASTM D6400 and EN 13432 testing protocols require 180-day industrial composting validation, delaying product launches and locking working capital in qualification cycles.
- Barrier coating R&D skill scarcity:Formulation chemists with expertise in bio-based polymers and water-resistant cellulosic substrates command premium compensation, constraining mid-cap converter technical capacity.
- Legacy equipment retrofit capex:Converting lines designed for petroleum-based films require drying system upgrades and coating head modifications to handle viscous plant-based formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Sustainable Packaging Market |
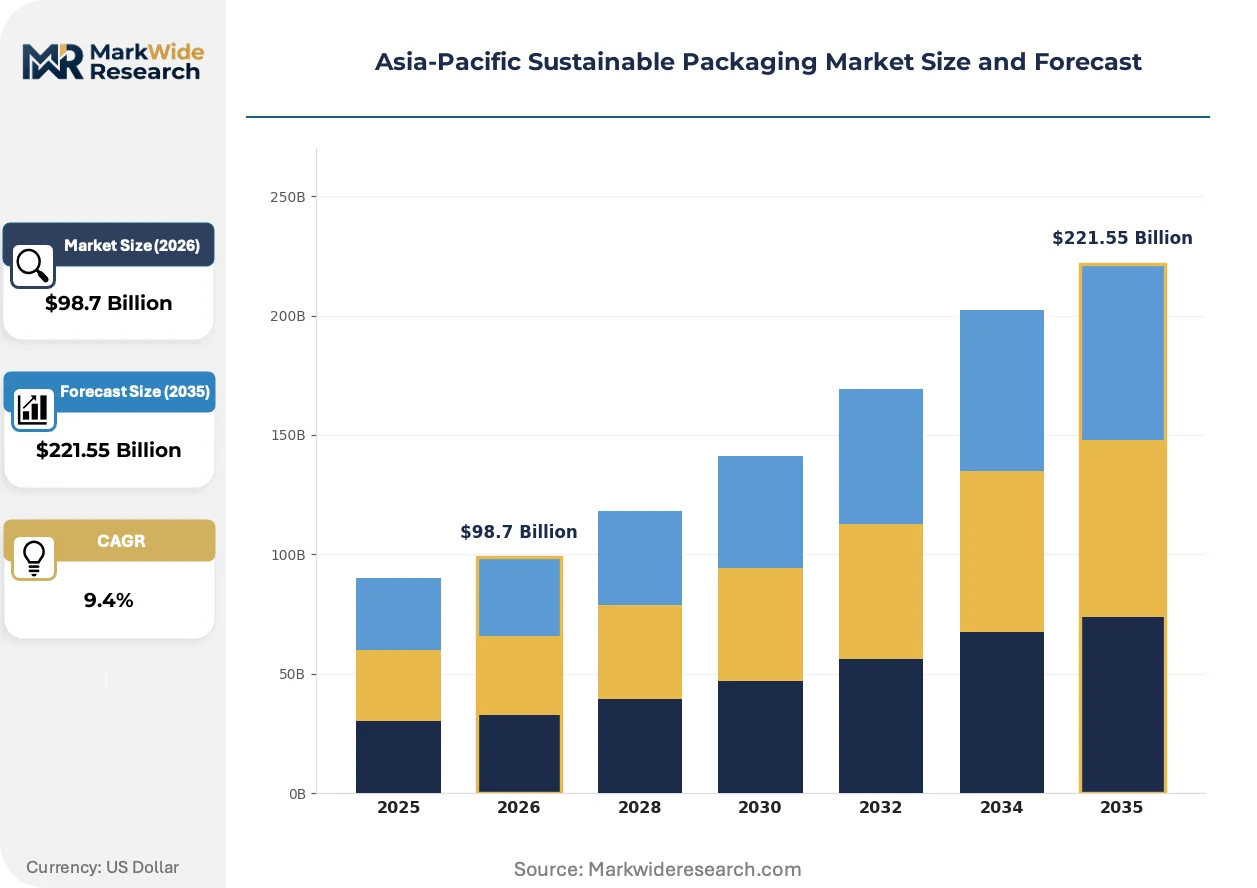
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $221.55 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable, Recyclable, Compostable, Reusable Material: Paper, Glass, Metal, Plant-Based Application: Food & Beverage, Personal Care, Electronics, Healthcare End User: Retail, Food Service, Online Retailers, Manufacturers |
| Companies Covered | Mondi plc, Sealed Air Corporation, Amcor plc, Uflex, Sonoco Products Company, Tetra Pak, Smurfit WestRock, ITC, Huhtamaki OYJ, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Sustainable Packaging Market Trends and Innovations
Digital manufacturing systems and bio-based material science are converging to compress development cycles and enable mass customization across the Asia-Pacific sustainable packaging value chain.
Robotic quality inspection and inline coating thickness measurement is automating defect detection and process control on high-speed kraft paper lines. Japanese and South Korean converters deploying these systems achieve yield improvements that offset premium bio-based raw material costs. The technology is automating manual inspection roles while compressing time-to-market for certified compostable formats.
Australia's APCO 2025 targets and South Korea's extended producer responsibility frameworks are mandating recycled content minimums and design-for-recyclability standards. These policies force brand owners to redesign multi-layer structures into mono-material alternatives or face compliance penalties. Food and beverage exporters across the region are responding by pre-qualifying substrates against the most stringent jurisdiction in their supply chain.
Clean beauty brands in Australia and New Zealand are unbundling secondary packaging from primary container procurement, creating direct relationships with specialty paperboard converters. This disintermediation bypasses traditional rigid packaging distributors and enables specification of plastic-free cartons with FSC certification and soy-based inks. The shift is most visible in Auckland and Sydney's indie cosmetic segments, where sustainability credentials drive premium positioning.
Asia-Pacific Sustainable Packaging Market Segmentation
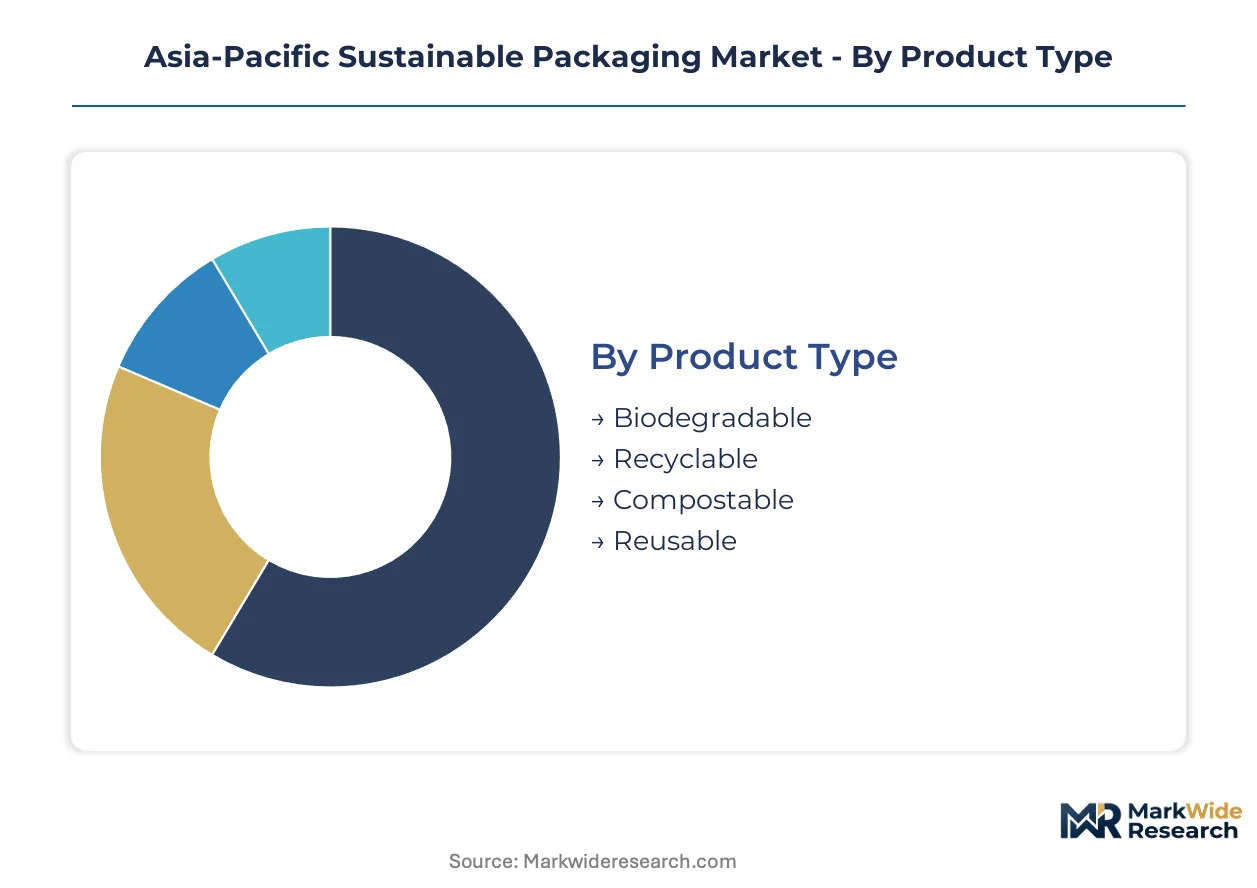
Segmentation reveals where capital deployment and technical capability concentrate across the Asia-Pacific sustainable packaging value chain. Understanding these divisions helps converters align substrate investments with regulatory enforcement patterns and end-use certification requirements.
Product Type:
Capital intensity varies sharply across product categories, with compostable formats demanding the heaviest upfront investment in certification infrastructure and industrial composting partnerships.
- Biodegradable:Materials engineered to decompose through microbial action without requiring industrial composting facilities, typically incorporating starch-based or PHA polymers. Demand clusters in India's western industrial corridor where FMCG contract packagers seek lower-cost alternatives to certified compostables amid BIS standard finalization.
- Recyclable:Mono-material or easily separable multi-layer structures compatible with existing municipal recycling streams, with post-consumer recycled content thresholds rising above 30 percent. Japan's METI recycling targets are pushing converters toward these formats, particularly for beverage bottles and secondary packaging in Tokyo-Osaka industrial zones.
- Compostable:Substrates meeting ASTM D6400 or EN 13432 protocols requiring 180-day industrial composting validation. Premium pricing in food service channels across Japan and South Korea offsets certification costs and working capital lockup in qualification cycles.
- Reusable:Durable formats designed for multiple use cycles through return logistics or deposit systems. Concentrated in South Korea's Seoul metropolitan area where extended producer responsibility frameworks incentivize circular packaging models for quick-service restaurant chains.
Recyclable formats absorb the bulk of installed capacity; compostable alternatives are expanding most quickly.
Material:
Raw material selection determines supply security and margin exposure to pulp price volatility across Southeast Asian production clusters.
- Paper:Kraft paper and molded fiber formats dominating volume deployment in food and beverage applications. Captive pulp supply in Indonesia and Malaysia privileges integrated converters while exposing non-integrated players to input cost swings.
- Glass:Inert barrier properties suit premium beverage and personal care segments, though weight and fragility limit adoption in e-commerce channels. Australia's APCO recycling targets support domestic glass recovery infrastructure.
- Metal:Aluminum and steel formats offering superior oxygen and light barriers for shelf-stable applications. China's MEE dual carbon goals are forcing coating process decarbonization that raises capital requirements for new metal packaging lines.
- Plant-Based:Emerging substrates including agricultural residue fibers and algae-derived polymers. Clean beauty brands in Australia and New Zealand are driving specification of these materials for plastic-free secondary packaging with FSC certification.
Paper commands the largest production base; plant-based alternatives are climbing the fastest as formulation chemistry advances.
Application:
Application segments diverge in performance requirements, with high-barrier food applications presenting the steepest technical barriers to sustainable substrate adoption.
- Food & Beverage:Dominates absolute demand across the region, spanning fresh produce, dairy, and processed goods. Technical limitations in plant-based oxygen barriers still restrict adoption in retort and shelf-stable dairy segments where aluminum and multi-layer plastic maintain performance advantages.
- Personal Care:Clean beauty brands in Australia and New Zealand are mandating plastic-free secondary packaging, creating direct procurement relationships with specialty paperboard converters bypassing traditional distribution channels.
- Electronics:Anti-static and moisture-barrier requirements favor molded fiber and corrugated formats with bio-based coatings. Demand concentrates in China's Pearl River Delta manufacturing clusters.
- Healthcare:Sterility and regulatory compliance requirements maintain plastic dominance, though recyclable mono-material alternatives are gaining traction in Japan's pharmaceutical distribution channels.
Food and beverage absorbs the bulk of installed capacity; personal care is gaining share fastest through sustainability-driven brand mandates.
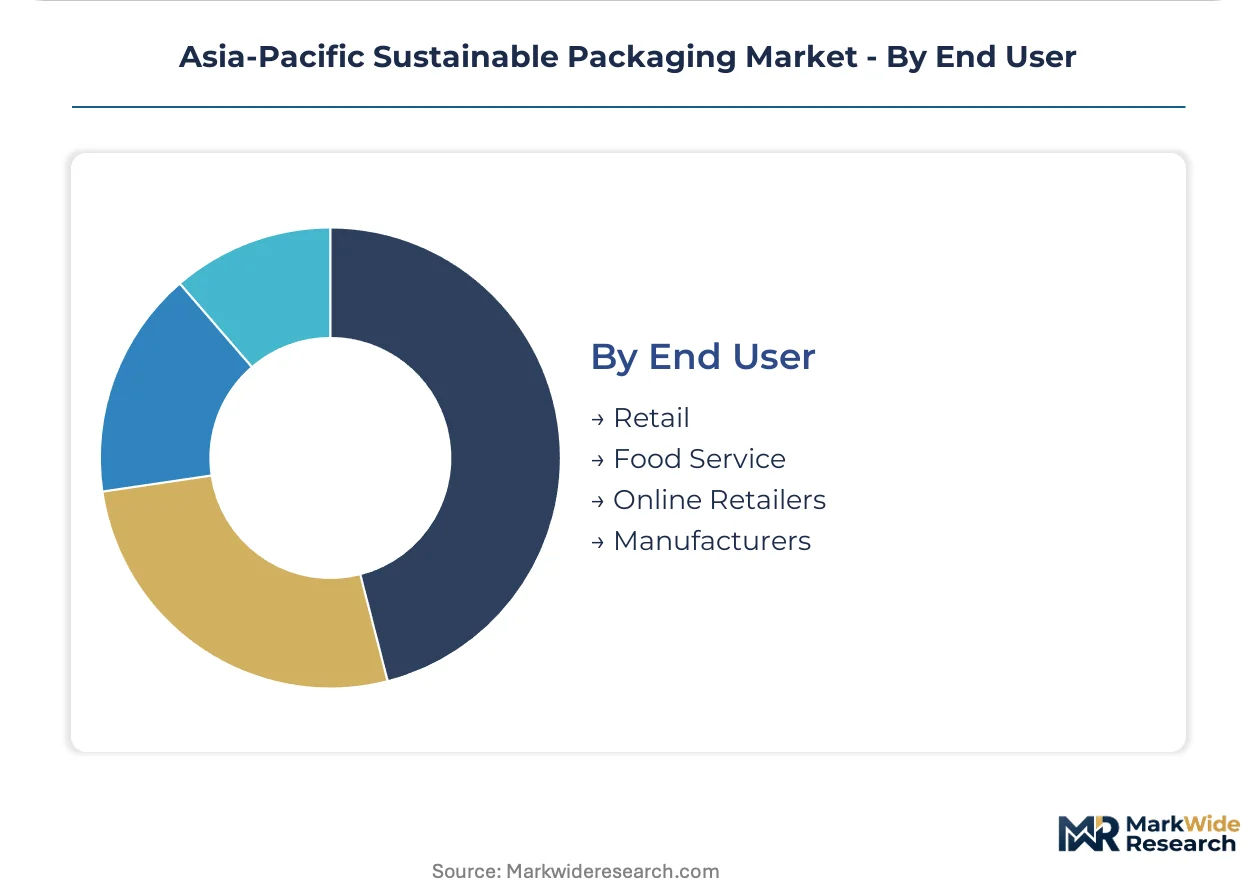
End User:
End-user categories structure procurement scale and specification authority, with retail and food service presenting divergent customization requirements.
- Retail:Large-format grocery and hypermarket chains driving standardization across private-label packaging. Volume concentration enables investment in certified substrate partnerships with pre-qualified domestic converters.
- Food Service:Quick-service restaurants and delivery platforms in Vietnam's Ho Chi Minh City and Hanoi markets lack certified compostable alternatives, creating first-mover space for regional suppliers. South Korea's single-use plastic bans in Seoul accelerate format transition.
- Online Retailers:E-commerce packaging prioritizes damage protection and dimensional efficiency over aesthetic sustainability credentials. China's cross-border export platforms are pre-qualifying substrates against multiple jurisdiction standards.
- Manufacturers:Brand-owning FMCG companies in Maharashtra and Gujarat are scaling compostable pouch production through contract packaging relationships, leveraging BIS regulatory clarity to secure long-term supply agreements.
Retail channels absorb the bulk of installed capacity; food service is expanding most quickly through regulatory tailwinds in South Korea and Vietnam.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates along industrial corridors where FMCG contract packagers scale compostable production and dual carbon regulations force process decarbonization. China's coating and drying upgrades, India's BIS certification clarity, and Southeast Asia's fiber substitution wave are recalibrating capital deployment across the region.
China
MEE dual carbon goals are forcing coating and drying process decarbonization across converter facilities. The Yangtze River Delta and Pearl River Delta industrial clusters face elevated capital requirements for new entrants seeking compliant substrate partnerships. Domestic converters with pre-certified supply chains capture multinational brand contracts.
India
FMCG contract packagers in Maharashtra and Gujarat are scaling compostable pouch lines following BIS regulatory clarity on certification protocols. The western industrial corridor from Mumbai to Ahmedabad concentrates demand as brand owners secure long-term supply agreements. Domestic substrate partnerships privilege converters with pre-qualified compostable formats.
Japan
METI enforces strict plastic packaging recycling quotas that push converters toward mono-material designs and post-consumer recycled content above 30 percent. The Tokyo-Osaka industrial zone dominates beverage bottle and secondary packaging conversion. Yield improvements from robotic quality inspection offset premium bio-based raw material costs.
South Korea
Extended producer responsibility frameworks and single-use plastic bans in Seoul accelerate demand for certified compostable formats meeting EN 13432 protocols. The Seoul Capital Area food service sector presents concentrated demand from quick-service restaurant chains. Regulatory tailwinds favor domestic converters with industrial composting partnerships.
Vietnam
Quick-service restaurant chains and delivery platforms in Ho Chi Minh City and Hanoi lack certified compostable alternatives, creating first-mover space for regional substrate suppliers. Retail sustainability mandates and export compliance requirements drive fiber-based substitution. Underpenetrated food service channels attract regional investment in molded fiber capacity.
Asia-Pacific Sustainable Packaging Market Competitive Landscape
Chinese producers anchor one tier; European and Australian specialists hold premium positions through certified substrate partnerships. The vendor base stratifies across integrated pulp-to-paper operators, film-to-pouch converters, and specialty coating formulators. Three archetypes dominate: captive pulp suppliers, integrated flexible packaging converters, and barrier coating technology licensors. Competitive moves concentrate on strategic partnerships for composting infrastructure and capacity expansion in Vietnam and Indonesia.
Within the integrated converter tier, Amcor plc and Mondi plc exemplify scale-driven positioning through film-to-pouch manufacturing footprints and captive pulp supply respectively. Among diversified packaging groups, Sealed Air Corporation and Sonoco Products Company occupy positions spanning protective formats and molded fiber applications. Tetra Pak represents the liquid food packaging specialist archetype with established aseptic carton technology. These anchors illustrate how substrate integration and certification pre-qualification separate premium-tier competitors from regional challengers.
| Leading Market Players |
|---|
| Mondi plc |
| Sealed Air Corporation |
| Amcor plc |
| Uflex |
| Sonoco Products Company |
| Tetra Pak |
| Smurfit WestRock |
| ITC |
| Huhtamaki OYJ |
| Others |
Pricing and Supply Chain Analysis
Pulp price indices in Indonesia and Malaysia cascade through kraft paper and molded fiber supply chains, stratifying converters into premium-certified, standard-compliant, and economy-grade tiers based on captive raw material access and BIS compostability certification status.
Pricing Analysis
Volume absorption concentrates in recyclable mono-material formats while compostable alternatives capture margin premiums. Pricing stratifies across ASTM D6400-certified, BIS-qualifying, and uncertified substrate tiers, with certification grade and captive pulp supply as primary differentiation drivers. Cost compression in standard-grade kraft is intensifying because non-integrated converters face input volatility. FMCG contract packagers in Maharashtra exhibit highest price sensitivity; Japanese food service channels show least.
Supply Chain Analysis
Certification gating through ASTM D6400 and EN 13432 protocols restricts qualified supplier pools and elongates procurement cycles. Pulp supply concentrates in Indonesia, Malaysia, and India; coating formulations draw from Chinese chemical producers and European specialty polymer licensors. Single-source vulnerability persists in industrial composting infrastructure partnerships. Distribution runs through domestic converter networks pre-qualified by multinational brand technical audits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial composting capacity scarcity props pricing premiums for certified compostable formats, constraining volume expansion until infrastructure buildout accelerates.
For Market Incumbents: Cement backward integration into captive pulp supply in Indonesia and Malaysia to defend margin structures against raw material volatility. Prioritize BIS pre-certification partnerships in Maharashtra and Gujarat before standard finalization locks in preferred supplier status.
For New Entrants and Emerging Players: Launch via direct substrate supply relationships with Vietnam's quick-service restaurant chains in Ho Chi Minh City and Hanoi, exploiting underpenetrated food service channels lacking EN 13432-certified alternatives. Target South Korean extended producer responsibility compliance deadlines as regulatory-forced switching catalyst.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap coating technology licensors with water-based barrier patent portfolios in China's Yangtze River Delta, where MEE dual carbon compliance costs strain undercapitalized converters. Watch for BIS enforcement variance between Maharashtra and Gujarat as geographic inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Pulp | Secures margin stability against Indonesian and Malaysian price swings for kraft-dependent converters. |
| Industrial Composting Partnership | Unlocks premium pricing in Japan and South Korea food service channels through ASTM D6400 validation. |
| Water-Based Barrier R&D Investment | Addresses technical limitation in oxygen barrier performance for shelf-stable dairy applications. |
| BIS Pre-Certification Alignment | Positions converters for Maharashtra-Gujarat FMCG contract packaging scale-up ahead of standard finalization. |
| Digital Printing Capability Addition | Enables short-run customization for Australia-New Zealand clean beauty plastic-free secondary packaging mandates. |
Research Methodology
Document review covered BIS draft standards, METI recycling target circulars, and APCO covenant obligations, complemented by interviews with converter operations directors, FMCG packaging procurement managers, and industrial composting facility operators. Secondary validation drew from MEE dual carbon policy filings, customs trade data for pulp and kraft paper flows, and SEC disclosures of listed packaging groups. Bottom-up substrate demand modeling and top-down regulatory enforcement timelines were triangulated against capacity announcements.
Segment-level outputs across material type, certification protocol, application, and regional regulatory cluster were generated through the analytical framework. CAGRs were derived from elasticity-adjusted volume projections incorporating pulp price scenarios and compliance cost pass-through assumptions. Forecast inputs included MEE enforcement intensity gradients and BIS standard adoption curves.
Regulatory enforcement variance, pulp price volatility spikes, and industrial composting infrastructure buildout delays are the dominant revision risks to modeled assumptions. A model refresh is warranted upon material change in BIS certification timeline or MEE inspection regime stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
GCC Green Packaging Market
Sustainable Packaging
Japan Green Packaging Market
Sustainable Packaging
Sustainable Packaging Market
Sustainable Packaging
Europe Green Packaging Market
Sustainable Packaging
Bio-Based Cutlery Market
Sustainable Packaging
Global Disappearing Packaging Market
Sustainable Packaging
Eco Friendly Bottles Market
Sustainable Packaging
Zero Waste Packaging Market
Sustainable Packaging
Sustainable Foodservice Packaging Market
Sustainable Packaging
Eco-Friendly Straw Market
Sustainable Packaging
Sustainable Plastic Packaging Market
Sustainable Packaging
Europe Sustainable Packaging Market
Sustainable Packaging
Areca Plates Market
Sustainable Packaging
Compostable Food Trays Market
Sustainable Packaging
Plant Based Packaging Market
Sustainable Packaging
Green Packaging Market