
 Europe Sustainable Packaging Market | 2026-2036
Europe Sustainable Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sustainable Packaging Market Insights
Single-source virgin plastic sourcing is decoupling from European converter procurement strategies as brands diversify supplier bases. Mondi Group anchors its position through integrated pulp-to-pack operations across Central Europe. DS Smith Plc competes via circular design services tied to retailer closed-loop commitments. Huhtamaki Oyj specializes in molded fiber applications for food service channels.
Sustainable packaging encompasses materials and designs engineered to minimize environmental burden across lifecycles, typically incorporating recycled content above 30 percent, bio-based feedstocks, or mono-material structures compatible with existing recycling streams. Its primary commercial purpose is to maintain product protection and shelf appeal while satisfying compliance and corporate sustainability targets. Recycled paper occupies the largest volume share among material types due to established collection infrastructure and consumer recognition. Flexible packaging formats within design categories are expanding fastest as barrier coating innovations replace multi-layer laminates. Food packaging applications command premium positioning because safety certification requirements create defensible margin pools for compliant suppliers.
EMA, ECHA, and the EU Green Deal collectively shape material approval pathways, extended producer responsibility fees, and carbon accounting disclosures across member states. REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of grease-resistant food contact materials before sunset dates take effect. Stakeholders must monitor how the Packaging and Packaging Waste Regulation's recycled content mandates will redistribute competitive advantage between mechanical recyclers and chemical recycling ventures.
Market Dynamics
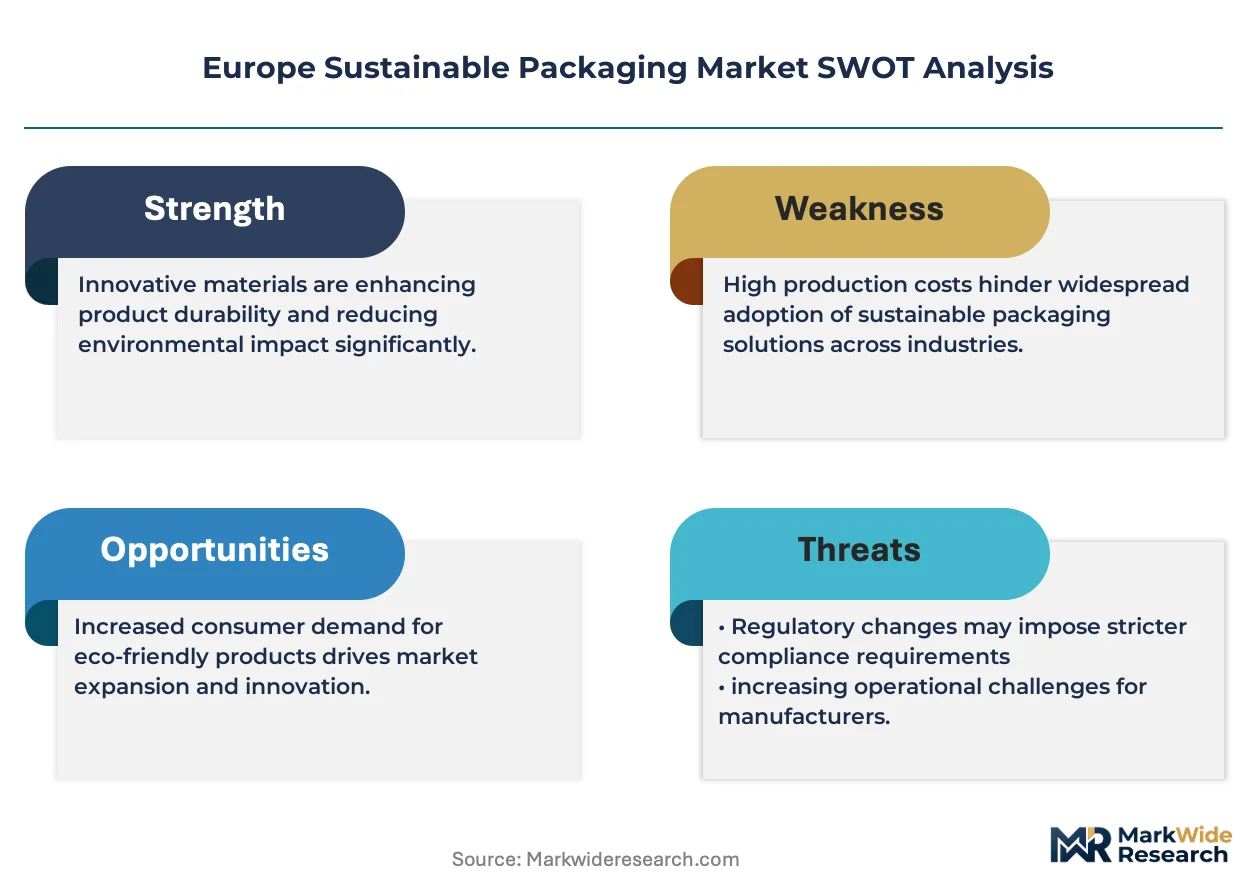
The EU Packaging and Packaging Waste Regulation is forcing converters to reconfigure material specifications and supplier relationships before mandatory recycled content thresholds activate, compressing decision timelines across the value chain.
Growth Catalysts
- EU Green Deal carbon accounting mandates:Food and beverage brands in Germany and France now require Scope 3 packaging emissions disclosures from tier-one suppliers, accelerating certified material procurement.
- Retailer closed-loop commitments:Carrefour and REWE Group sustainability scorecards favor mono-material fiber formats, directing converter R&D budgets toward recyclable barrier coatings.
- Italy's industrial packaging cluster:Converter networks around Bologna and Milan achieve 40% lower logistics costs through regional pulp-to-box integration, attracting brand co-location.
Market Restraints
- Pulp price volatility:Nordic softwood pulp contracts fluctuate with energy input costs, squeezing molded fiber margins for food service applications.
- Chemical recycling capacity gaps:Pyrolysis and depolymerization facilities remain concentrated in Netherlands and Belgium, creating supply bottlenecks for food-grade recycled polymer feedstocks.
- REACH substance restrictions:Per- and polyfluoroalkyl substance bans on grease-resistant coatings force reformulation of bakery and fast-food packaging before viable alternatives achieve commercial scale.
Strategic Opportunities
- Poland and Czech Republic converter expansion:Lower labor and energy costs attract German brand manufacturing relocations, building regional hub capacity for Central European distribution.
- Pharmaceutical secondary packaging:Cold-chain biologics growth creates demand for insulated fiber-based shippers with temperature-stable barrier properties, a segment with limited compliant suppliers.
- Digital watermarking integration:AI-powered sorting infrastructure deployment across France and Netherlands enables flexible packaging recovery, opening closed-loop service revenue streams for converters.
Industry Challenges
- Food contact safety certification timelines:EFSA novel food contact substance approvals average 18-24 months, delaying bio-based barrier coating commercialization for sensitive applications.
- Mechanical recycling feedstock quality variance:Post-consumer paper stream contamination rates in Southern Europe fluctuate, requiring converter investment in advanced sorting and de-inking capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sustainable Packaging Market |
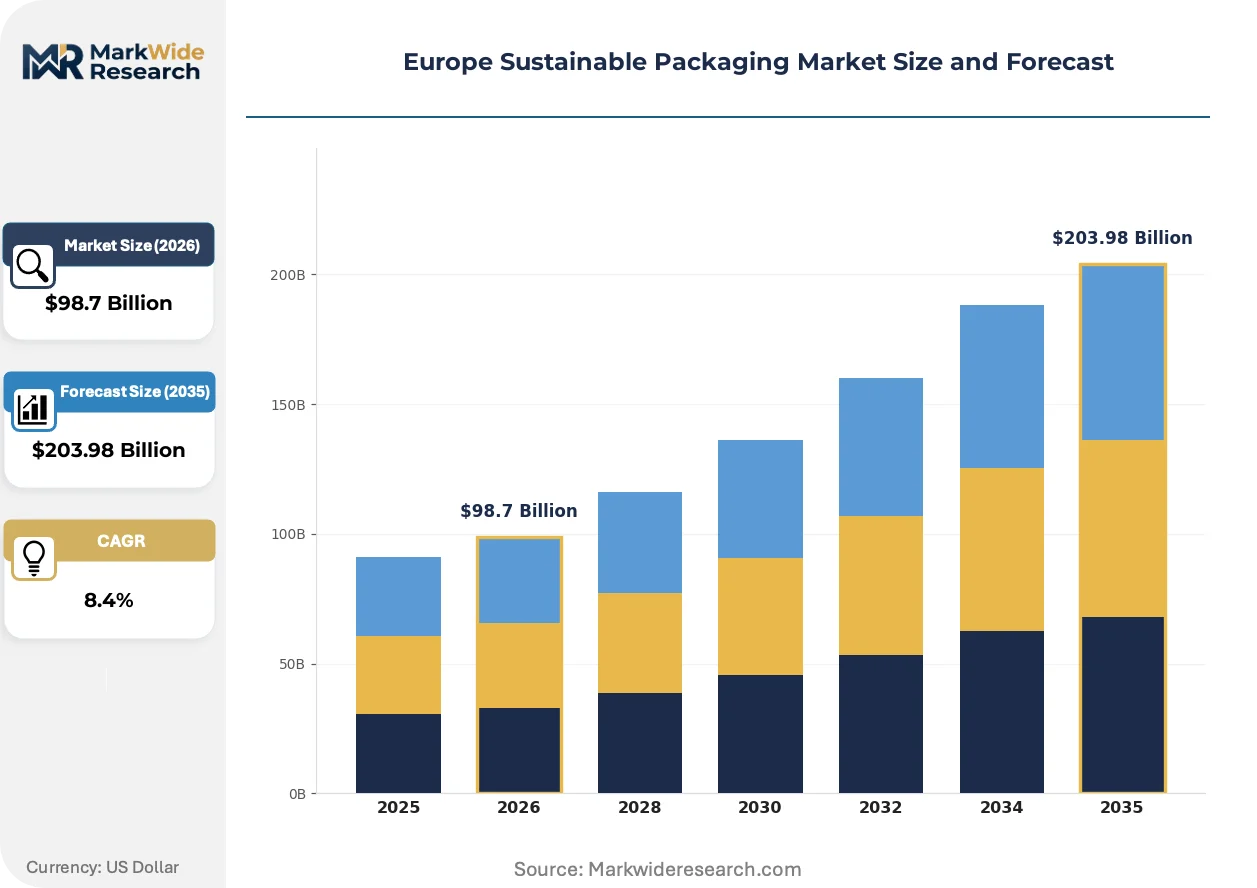
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $203.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Biodegradable Plastics, Recycled Paper, Glass, Metal Application: Consumer Goods, Food Packaging, Cosmetics, Electronics End User: Retail, Food & Beverage, Healthcare, Personal Care Design Type: Flexible Packaging, Rigid Packaging, Eco-Friendly Designs, Minimalist Packaging |
| Companies Covered | Amcor Plc, Mondi Group, Sealed Air Corporation, Tetra Pak International S.A., DS Smith Plc, Smurfit Kappa Group, Stora Enso Oyj, Berry Global, Inc., Huhtamaki Oyj, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sustainable Packaging Market Trends and Innovations
Barrier coating chemistry and sorting infrastructure are converging to unlock fiber-based alternatives for applications previously locked into multi-layer plastics, reshaping competitive capability requirements across converter tiers.
Water-based and bio-based barrier coatings are overtaking conventional polyethylene extrusion for fresh produce and dry food applications. German discount retailers Aldi and Lidl have mandated fiber-only produce trays by 2027, forcing their packaging suppliers to achieve commercial-scale coating throughput. This transition is compressing capital returns for extrusion equipment while rewarding integrated pulp-coating-converting operations.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant chemistry from food contact applications by 2026. The regulation forces reformulation of bakery, fast-food, and microwave packaging across all EU member states, with ECHA guidance documents determining acceptable replacement pathways. Food service channels in France and Italy face the steepest compliance cliffs due to high volumes of oil-resistant paperboard consumption.
Brand sustainability scorecards now weight packaging circularity metrics above unit cost in supplier selection protocols. Unilever and Nestlé procurement teams in the Netherlands and Switzerland have shifted to multi-year framework contracts tied to verified recycling rates, displacing spot-market purchasing for primary packaging categories. This behavioral shift concentrates volume with converters possessing certified closed-loop infrastructure, particularly visible in the Benelux retail supply base.
Europe Sustainable Packaging Market Segmentation
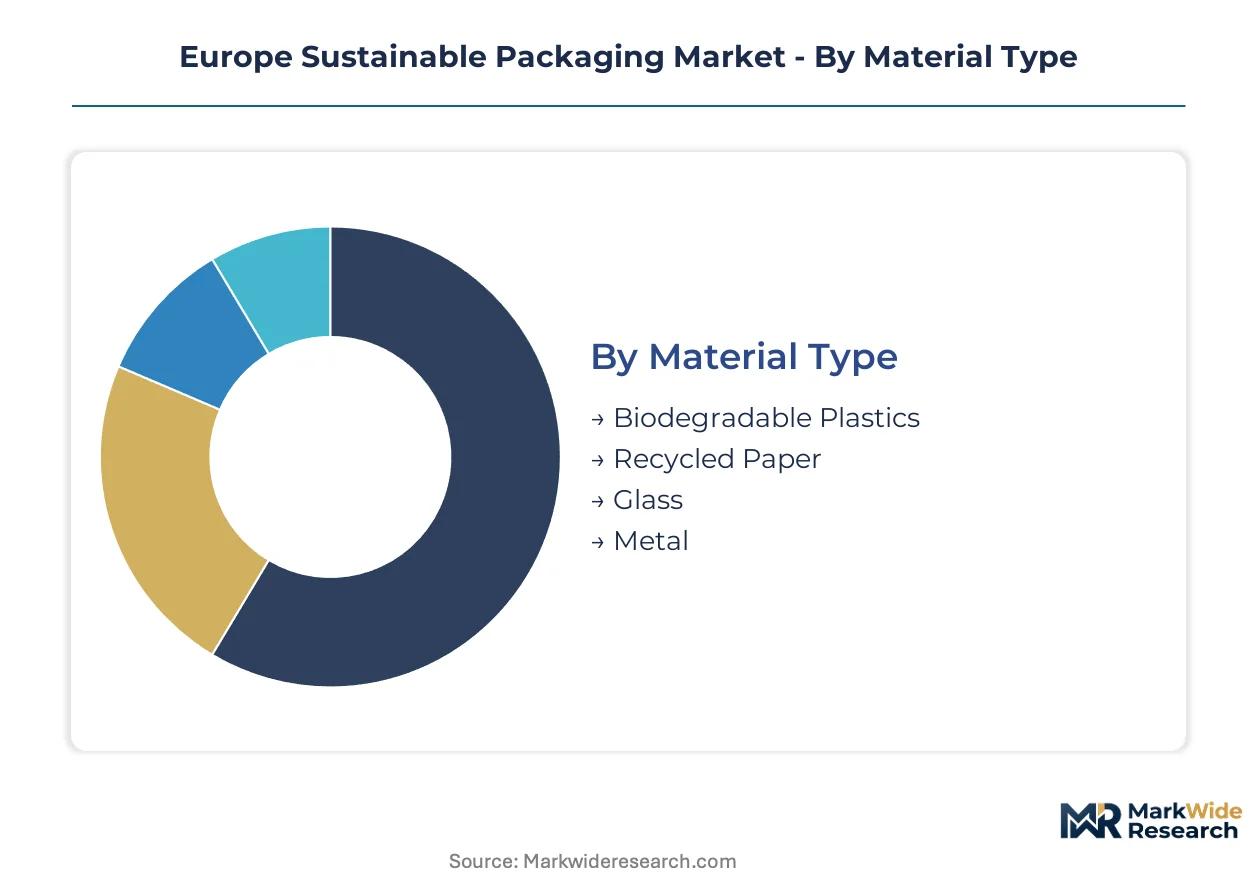
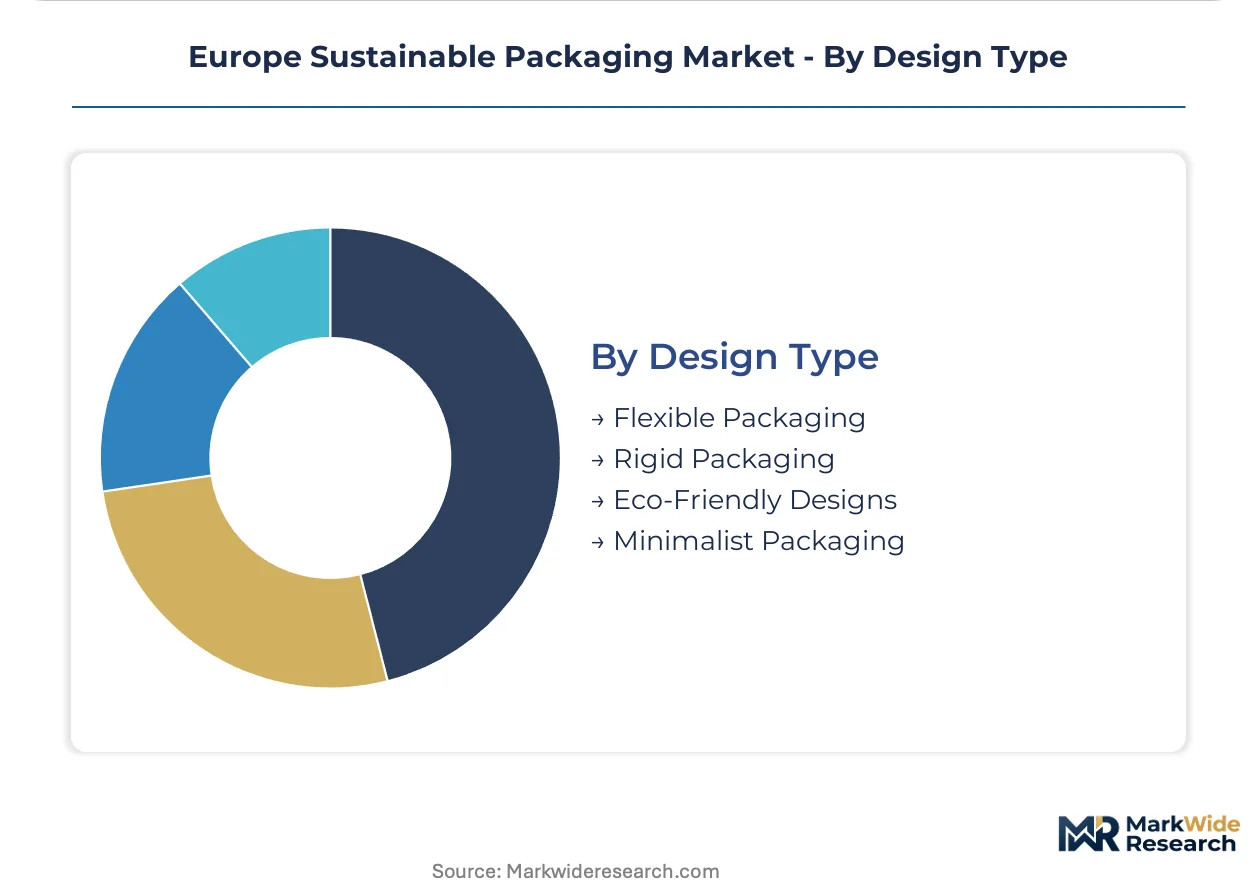
Converters and brand procurement teams navigate material specifications, application requirements, and design constraints simultaneously. Segmentation clarity reveals where compliance thresholds concentrate investment and where margin pools shift across the value chain.
Material Type:
Buyers prioritize recyclability certification and feedstock traceability when selecting base materials, with ECHA substance restrictions and EFSA food contact approvals governing viable options.
- Recycled Paper:Post-consumer fiber grades with de-inked pulp content above 80 percent dominate corrugated and folding carton applications. German discount retailers and French supermarket chains specify FSC-certified recycled content for private-label packaging, with Bologna-area converters achieving shortest lead times through regional pulp integration.
- Biodegradable Plastics:Polylactic acid and polyhydroxyalkanoate formulations serve food service disposables and agricultural film replacements. Industrial composting infrastructure gaps in Southern Europe limit addressable demand, though Netherlands and Belgium anaerobic digestion facilities create viable offtake corridors for certified products.
- Glass:Returnable bottle systems retain share in premium beverage categories across Germany and Switzerland, with refillable deposit schemes mandated by national packaging ordinances.
- Metal:Aluminum aerosols and steel cans leverage established magnetic and eddy-current sorting infrastructure, with Italian and Spanish recycling rates exceeding regional averages for these formats.
Volume sits with recycled paper; growth tilts toward biodegradable plastics.
Application:
End-use safety requirements and shelf-life demands determine material-process combinations, with food contact applications commanding the most stringent certification overhead.
- Food Packaging:Barrier-coated fiber trays and pouches replace multi-layer laminates for fresh produce and dry goods. Aldi and Lidl mandates for fiber-only produce packaging by 2027 redirect German supplier R&D toward water-based coating scale-up.
- Consumer Goods:E-commerce shipper formats emphasize dimensional optimization and return-stream recyclability, with Amazon and Zalando sustainability scorecards penalizing non-mono-material designs.
- Cosmetics:Refillable glass and aluminum formats gain share in prestige segments, though pump mechanisms and multi-component dispensers complicate closed-loop claims.
- Electronics:Molded pulp cushioning displaces expanded polystyrene for device protection, with Dutch and German consumer electronics brands specifying fiber-based alternatives for unboxing experience differentiation.
Food packaging commands the largest procurement volumes; electronics protective formats are expanding most quickly as OEM sustainability targets harden.
End User:
Procurement scale and specification authority vary sharply across buyer categories, with retail consolidation concentrating volume among fewer decision-makers.
- Food & Beverage:Nestlé and Unilever European procurement teams enforce multi-year framework contracts tied to verified recycling rates, displacing spot-market purchasing for primary packaging. Scope 3 emissions disclosure requirements now extend to tier-two converter suppliers.
- Retail:Carrefour and REWE Group sustainability scorecards weight circularity metrics above unit cost, directing mono-material fiber development across their private-label supply bases.
- Healthcare:Cold-chain biologics growth creates demand for insulated fiber-based shippers with temperature-stable barrier properties, a segment with limited EMA-compliant suppliers.
- Personal Care:Refill and concentrate formats reduce primary packaging intensity, with L'Oréal and Beiersdorf piloting aluminum and glass dispensing systems across German and French markets.
Food and beverage buyers absorb the greatest material tonnage; healthcare cold-chain applications offer the steepest margin premiums for qualified suppliers.
Design Type:
Format selection determines sorting infrastructure compatibility and extended producer responsibility fee calculations under evolving EU Packaging and Packaging Waste Regulation thresholds.
- Flexible Packaging:Mono-material polyethylene and polypropylene structures with digital watermarking enable AI-powered sortation across French and Dutch recycling facilities. Barrier coating innovations replace aluminum oxide layers for oxygen-sensitive applications.
- Rigid Packaging:Injection-molded and thermoformed containers maintain dimensional stability for stacking and display efficiency, with Italian converters specializing in thin-wall formats for dairy and prepared foods.
- Eco-Friendly Designs:Source-reduced geometries and elimination of non-functional decorative elements reduce material intensity, with German packaging ordinances mandating minimum empty space ratios for e-commerce shipments.
- Minimalist Packaging:Unprinted or single-color kraft formats serve brand authenticity positioning, particularly in organic food and natural cosmetics segments across Scandinavian markets.
Flexible formats gain share fastest as barrier chemistry matures; rigid containers retain dominance in temperature-sensitive and high-barrier applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nordic softwood pulp basins anchor European sustainable packaging feedstock security, with converter networks clustering around Baltic Sea ports and Central European industrial corridors to minimize logistics exposure.
Germany
Discount retailer mandates for fiber-only produce trays by 2027 are redirecting converter R&D budgets toward water-based barrier coating scale-up. The German Packaging Act enforces minimum recycled content thresholds and extended producer responsibility fees that penalize non-recyclable formats. Converter networks around Hamburg and the Rhine-Ruhr corridor achieve shortest lead times through integrated pulp-to-box operations serving Aldi and Lidl procurement teams.
France
Carrefour sustainability scorecards now weight circularity metrics above unit cost, concentrating volume with suppliers possessing certified closed-loop infrastructure. ECHA REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant chemistry from bakery and fast-food packaging by 2026. The Lyon-Turin logistics axis hosts specialized converters developing temperature-stable fiber shippers for cold-chain biologics distribution.
Italy
Food service channels face steep compliance cliffs due to high volumes of oil-resistant paperboard consumption in bakery and ready-meal segments. The EU Green Deal carbon accounting mandates require Scope 3 packaging emissions disclosures from tier-one suppliers, accelerating certified material procurement. Converter networks around Bologna and Milan achieve 40% lower logistics costs through regional pulp-to-box integration, attracting brand co-location investments.
Netherlands
Unilever and Nestlé procurement teams have shifted to multi-year framework contracts tied to verified recycling rates, displacing spot-market purchasing for primary packaging categories. AI-powered sorting infrastructure deployment enables flexible packaging recovery, opening closed-loop service revenue streams for converters with digital watermarking capabilities. The Rotterdam-Antwerp chemical cluster hosts pyrolysis and depolymerization facilities, though food-grade recycled polymer feedstock bottlenecks persist.
Poland
Lower labor and energy costs are attracting German brand manufacturing relocations, building regional hub capacity for Central European distribution. The Packaging and Packaging Waste Regulation's recycled content mandates are compressing decision timelines for converters reconfiguring material specifications. Warsaw-area industrial zones are emerging as secondary locations for molded fiber operations serving food service disposables demand.
Europe Sustainable Packaging Market Competitive Landscape
Capacity expansion dominates the current landscape as converters race to install water-based coating lines and certified recycling infrastructure ahead of regulatory deadlines. The vendor base separates into three tiers: integrated pulp-to-pack operators with captive fiber supply, specialized barrier coating innovators, and regional converters dependent on spot-market feedstock purchasing. Strategic archetypes include circular design service providers tied to retailer closed-loop commitments and molded fiber specialists targeting food service channels. M&A activity and backward integration into pulp assets represent the dominant competitive moves, with converters acquiring de-inking and sorting capabilities to secure feedstock quality.
Among Nordic-based integrated operators, Stora Enso Oyj and Mondi Group exemplify the pulp-captive archetype through controlled fiber supply chains. DS Smith Plc occupies a position within the circular design services tier, while Huhtamaki Oyj represents molded fiber specialization for food contact applications. These three anchors demonstrate how geographic proximity to softwood basins and retailer co-location strategies determine competitive positioning under tightening EU compliance frameworks.
| Leading Market Players |
|---|
| Amcor Plc |
| Mondi Group |
| Sealed Air Corporation |
| Tetra Pak International S.A. |
| DS Smith Plc |
| Smurfit Kappa Group |
| Stora Enso Oyj |
| Berry Global, Inc. |
| Huhtamaki Oyj |
| Others |
Pricing and Supply Chain Analysis
Barrier coating chemists and pulp process engineers cluster around the Baltic Sea industrial corridor, where labor-cost differentials between Nordic and Central European facilities widen pricing-tier spreads for certified fiber-based packaging by fifteen to twenty percent across premium and economy grades.
Pricing Analysis
Certified recycling-rate guarantees and closed-loop service bundling separate premium converter contracts from unbundled spot-market transactions. Three-tier pricing structure across premium, standard, and economy levels hinges on FSC chain-of-custody certification and EFSA food contact approval status. Cost compression in standard-tier molded fiber is intensifying because Nordic softwood pulp contracts fluctuate with energy input costs. Discount retailers and private-label buyers exhibit highest price sensitivity, while cold-chain biologics shippers accept premium positioning for EMA-compliant barrier performance.
Supply Chain Analysis
Regional distribution centers around Rotterdam, Hamburg, and Gdansk anchor hub-and-spoke patterns for pulp feedstock and finished packaging flows. Supply concentrates in Sweden, Finland, and Germany for softwood pulp; Italy and Poland for converter manufacturing. Raw material dependencies rest on Nordic bleached kraft pulp, post-consumer recovered paper streams, and bio-based barrier coating chemistries. Single-source vulnerability pervades food-grade recycled polymer feedstocks where pyrolysis capacity concentrates in Netherlands and Belgium. Distribution runs through retailer consolidation centers and co-located converter operations serving Aldi, Lidl, and Carrefour procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe sustainable packaging market sits in a technology-transition phase where water-based barrier coatings displace polyethylene extrusion for fresh produce applications, compressing capital returns for legacy equipment while rewarding integrated pulp-coating-converting operations.
For Market Incumbents: Anticipate REACH substance restriction enforcement by securing EFSA novel food contact substance approvals ahead of per- and polyfluoroalkyl substance sunset dates. Backward integration into de-inking and sorting capabilities defends feedstock quality against Southern European contamination variance. Capacity addition in Poland and Czech Republic industrial zones captures German brand manufacturing relocations.
For New Entrants and Emerging Players: Direct-to-converter digital procurement platforms bypass established distributor markups for mid-tier food service accounts. Pharmaceutical secondary packaging for cold-chain biologics offers the most penetrable white-space segment given limited EMA-compliant supplier bases. Co-development partnerships with Dutch and French AI-powered sorting infrastructure providers unlock closed-loop service revenue streams.
For Investors and Strategic Acquirers: The window for entry favors integrated pulp-to-pack operators with captive Baltic Sea fiber supply and certified recycling infrastructure. Long-term viability centers on converters achieving commercial-scale water-based coating throughput ahead of retailer mandate deadlines. Monitor ECHA guidance document releases on acceptable PFAS replacement pathways as the inflection indicator for barrier coating chemistry winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Assets | Captive Nordic softwood supply secures feedstock cost stability against energy-linked contract volatility. |
| Water-Based Barrier Coating Scale-Up | Aldi and Lidl fiber-only mandates by 2027 reward first-movers with locked-in retailer volume. |
| Digital Watermarking Deployment | AI-powered French and Dutch sorting infrastructure enables flexible packaging recovery service revenues. |
| EMA-Compliant Cold-Chain Development | Biologics distribution growth creates defensible margin pools for qualified fiber-based shipper suppliers. |
| Regional Hub Expansion in Poland | Lower labor and energy costs attract German brand co-location for Central European distribution coverage. |
Research Methodology
Document review covered EU Packaging and Packaging Waste Regulation impact assessments, ECHA REACH restriction guidance documents, and EFSA novel food contact substance approval databases, complemented by interviews with converter operations directors, retailer sustainability procurement leads, barrier coating R&D heads, and pulp trading specialists. Secondary validation drew from customs trade data for pulp and recovered paper flows, SEC filings of listed packaging groups, and industry association production statistics. Bottom-up volume modeling across material grades and top-down macroeconomic alignment ensured cross-verified outputs.
Segmented projections across material type, application, end user, and design category fed into analytical framework calculations over the projection horizon. Modeled dimensions included recycled content thresholds, food contact safety certification tiers, and regional logistics integration levels. CAGRs were derived from trend extrapolation moderated by regulatory compliance deadline phasing. Forecast inputs incorporated pulp price volatility indices and retailer mandate implementation schedules.
The model holds under stable EU Green Deal enforcement and REACH substance restriction timelines; deviation in ECHA guidance document releases or EFSA approval acceleration would shift competitive advantage between mechanical and chemical recycling pathways. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
Green Packaging Market
Sustainable Packaging
Bagasse Bowls Market
Sustainable Packaging
Japan Green Packaging Market
Sustainable Packaging
Compostable Tableware Market
Sustainable Packaging
Eco Friendly Bottles Market
Sustainable Packaging
Sustainable Packaging Market
Sustainable Packaging
Bagasse Tableware Products Market
Sustainable Packaging
Zero Waste Packaging Market
Sustainable Packaging
Global Disappearing Packaging Market
Sustainable Packaging
United States Green Packaging Market
Sustainable Packaging
Compostable Food Trays Market
Sustainable Packaging
Wheat Straw Cutlery Market
Sustainable Packaging
Europe Eco-Friendly Packaging Market
Sustainable Packaging
Eco-Friendly Straw Market
Sustainable Packaging
Plant Based Packaging Market
Sustainable Packaging
Sustainable Plastic Packaging Market