
 Global Disappearing Packaging Market | 2026-2036
Global Disappearing Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Disappearing Packaging Market Analysis
Food-grade specification upgrades are unwinding across the disappearing packaging value chain as safety thresholds tighten for direct-contact applications. Mitsubishi Chemical Holdings leverages its polymer science depth to sustain leadership in water-soluble resin formulations. Kuraray Co. Ltd. anchors its position through proprietary polyvinyl alcohol film technologies with controlled dissolution rates. Notpla Ltd. differentiates by specializing in seaweed-derived edible coatings that bypass conventional waste streams entirely.
Disappearing packaging encompasses materials engineered to dissolve, biodegrade, or become consumable after single use, typically employing polyvinyl alcohol matrices, alginate gels, or thermoplastic starch blends with dissolution temperatures calibrated between 20°C and 80°C. These systems serve industries seeking to eliminate post-consumer collection infrastructure while maintaining barrier performance during product shelf life. Water-soluble materials currently lead commercial deployment due to established extrusion infrastructure and predictable degradation kinetics, while edible films command premium positioning in food service and hospitality channels where consumption convenience outweighs unit cost. Plant-based fibers occupy a maturing niche in corrugated protective applications, though margin pools concentrate in pharmaceutical-grade soluble containers where purity certification requirements create supply scarcity.
The EPA regulates persistent pollutant thresholds for packaging entering US waterways, while ECHA enforces REACH compliance on base polymer chemistries used in European formulations. Japan's METI circular economy guidelines and GB standards in China are converging on dissolution-rate testing protocols that will reshape product certification requirements. Stakeholders must monitor which regulatory jurisdiction sets the most stringent dissolution-performance benchmark, as that standard will likely cascade into private-label procurement specifications across export markets.
Market Dynamics
EU Green Deal packaging waste directives are compressing compliance timelines for single-use formats, forcing brand owners to accelerate soluble film qualification ahead of 2030 elimination targets for persistent plastics.
Growth Catalysts
- EU Green Deal packaging mandates:The directive's 2030 reduction targets for plastic waste are compelling food and beverage manufacturers to qualify water-soluble formats for condiment and detergent pods.
- Japan METI circular economy guidelines:Dissolution-rate testing protocols are creating certification pathways that favor polyvinyl alcohol films in hospitality and institutional food service channels.
- Edible film technology maturation:Seaweed-derived alginate gels are achieving barrier performance parity with conventional films in short-shelf-life applications.
Market Restraints
- Polyvinyl alcohol feedstock concentration:Resin supply clusters in East Asian manufacturing basins expose formulators to shipping cost volatility and tariff exposure.
- Dissolution-rate calibration limits:Films engineered for cold-water dissolution sacrifice mechanical strength during high-humidity storage, constraining distribution geography.
- REACH chemical compliance friction:ECHA registration requirements for novel polymer additives extend formulation development cycles by 18-24 months.
Strategic Opportunities
- Pharmaceutical-grade soluble containers:Purity certification scarcity in oral-dose strip packaging creates margin pools for qualified suppliers.
- US EPA persistent pollutant thresholds:Waterway discharge regulations are opening procurement channels for marine-safe detergent pods in coastal municipalities.
- Direct-to-consumer subscription channels:Pre-portioned soluble formats align with refill-model economics in household cleaning and personal care verticals.
Industry Challenges
- Food-grade polymer chemistry expertise:Formulators with dual competency in barrier engineering and ingestion safety remain scarce across the value chain.
- Extrusion equipment reconfiguration:Legacy blown-film lines require substantial capital modification to handle hygroscopic water-soluble resins.
- Multi-jurisdiction certification sequencing:Divergent dissolution-rate testing protocols between Japan METI, EPA, and ECHA force redundant validation expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Disappearing Packaging Market |
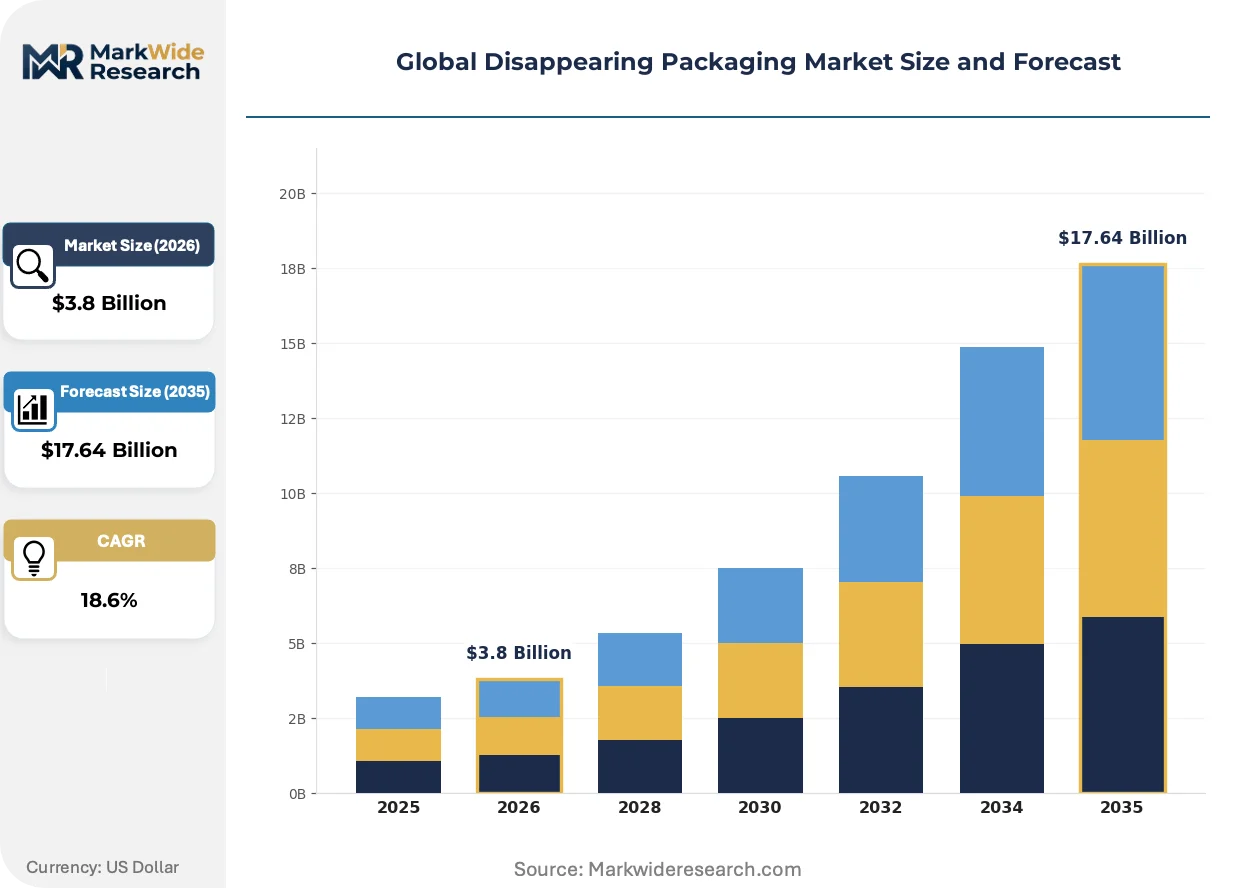
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Biodegradable Plastics, Edible Films, Water-Soluble Materials, Plant-Based Fibers End User: Food & Beverage, Cosmetics, Pharmaceuticals, E-commerce Application: Single-Use Containers, Wrapping Films, Labels, Food Packaging Distribution Channel: Online Retail, Supermarkets, Direct Sales, Specialty Stores |
| Companies Covered | Aicello Corporation, Notpla Ltd, Mondi Group, Cortec Corporation, Mitsubishi Chemical Holdings, Kuraray Co. Ltd., Lactips, Lithey Inc., Aquapak Polymer Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Disappearing Packaging Market Emerging Trajectories
Thermoplastic starch blends are achieving commercial scale in protective corrugated applications, while controlled-dissolution polyvinyl alcohol films penetrate pharmaceutical and food service channels with precision-tuned degradation kinetics.
Seaweed-derived edible coatings are displacing petroleum-based barrier films in single-serve condiment and beverage applications. Quick-service restaurant chains in Northern Europe are piloting alginate-based sachets for sauce portions. This displacement is compressing demand for conventional portion-control plastics in food service procurement.
REACH chemical framework amendments are tightening monomer purity thresholds for polyvinyl alcohol resins entering European formulations. ECHA enforcement actions against residual acetyl group content are forcing resin suppliers to upgrade distillation capabilities. Pharmaceutical-grade film manufacturers are absorbing certification costs fastest due to existing quality management infrastructure.
Brand-owner sustainability scorecards are elevating dissolution-verified packaging in supplier selection criteria. Food and beverage procurement teams in Germany and the United States are embedding dissolution-rate documentation requirements into private-label specifications. This behavioral shift is most visible in detergent pod and dishwasher tablet segments where water-soluble film constitutes the primary consumer touchpoint.
Global Disappearing Packaging Market Segmentation
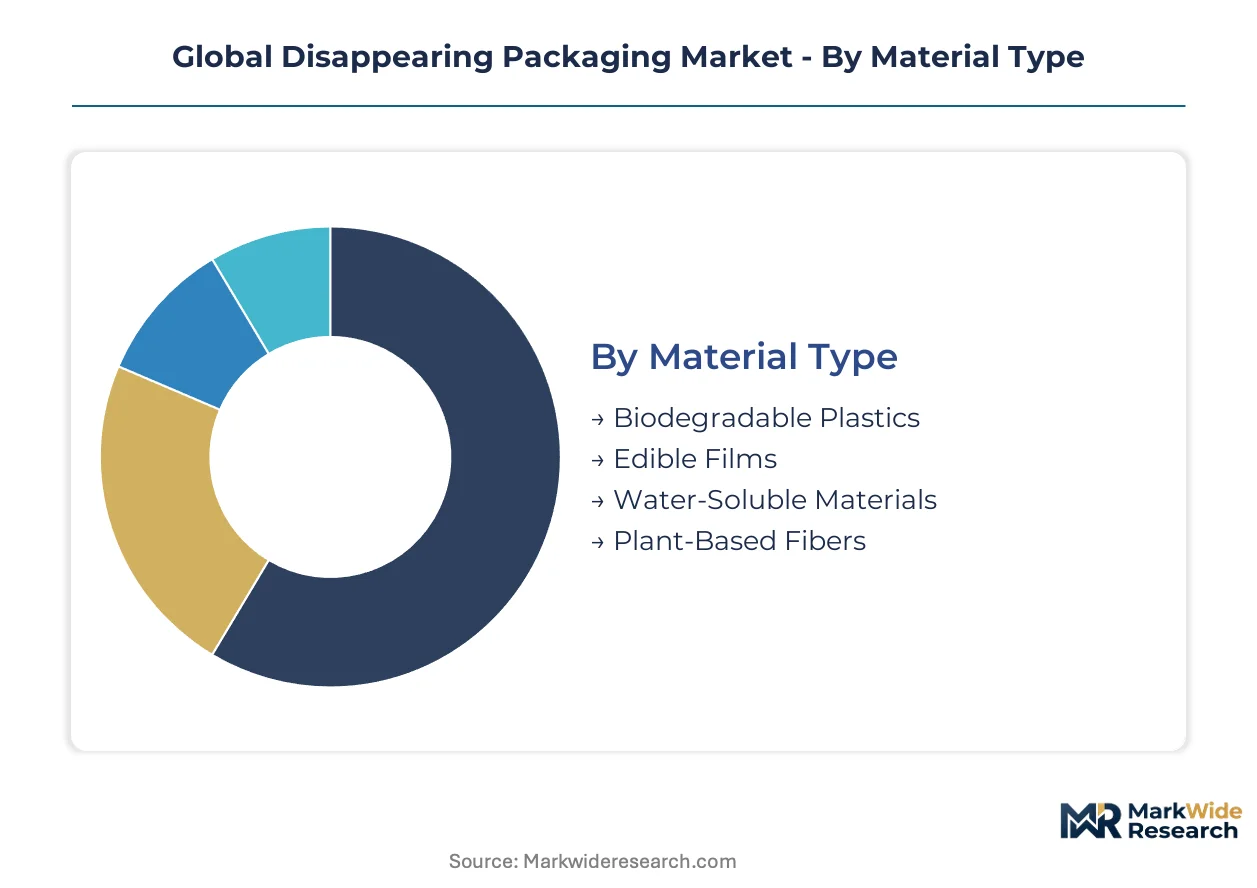
Material chemistry and dissolution kinetics determine regulatory pathways and end-use eligibility across disappearing packaging categories. Segmentation clarity enables suppliers to align formulation investments with jurisdiction-specific compliance thresholds and customer performance requirements.
Material Type:
REACH chemical framework amendments and FDA food-contact notifications create divergent qualification burdens depending on base polymer chemistry and dissolution mechanism.
- Water-Soluble Materials:Polyvinyl alcohol matrices dominate commercial deployment through established extrusion infrastructure and predictable degradation kinetics calibrated between 20°C and 80°C. Germany and Japan concentrate procurement for detergent pods and dishwasher tablets where dissolution-rate documentation satisfies METI guidelines and EU Green Deal packaging directives.
- Edible Films:Seaweed-derived alginate gels and thermoplastic starch blends achieve barrier performance parity with conventional films in short-shelf-life applications. Quick-service restaurant chains in Northern Europe pilot alginate-based sachets for sauce portions, bypassing conventional waste streams entirely.
- Biodegradable Plastics:Polylactic acid and polyhydroxyalkanoate formulations face ECHA registration requirements for novel polymer additives that extend development cycles.
- Plant-Based Fibers:Corrugated protective applications occupy a maturing niche with margin pressure from commodity pulp alternatives.
Water-soluble materials handle the majority of throughput; edible films are expanding most quickly on share as food-service procurement shifts toward consumption-convenience formats.
End User:
Customer procurement sophistication varies sharply across sectors, with pharmaceutical and food-grade specifications demanding dual competency in barrier engineering and ingestion safety.
- Food & Beverage:Brand-owner sustainability scorecards in Germany and the United States embed dissolution-rate documentation into private-label specifications for condiment pods and beverage capsules. FDA food-contact notifications and EFSA safety assessments govern direct-contact applications.
- Pharmaceuticals:Purity certification scarcity in oral-dose strip packaging creates margin pools for qualified suppliers meeting USP and EP monograph requirements. Mitsubishi Chemical Holdings and Kuraray Co. Ltd. anchor supply positions through polymer science depth.
- Cosmetics:Single-serve serum pods and bath oil capsules drive water-soluble film demand in premium personal care channels.
- E-commerce:Protective corrugated applications from plant-based fibers compete with conventional bubble wrap in direct-to-consumer fulfillment.
Food and beverage commands the largest procurement volume; pharmaceuticals posts the steepest expansion trajectory on certification-scarcity pricing power.
Application:
Functional requirements for barrier performance, mechanical strength, and dissolution speed dictate material selection and equipment reconfiguration needs.
- Wrapping Films:Controlled-dissolution polyvinyl alcohol films penetrate pharmaceutical and food service channels with precision-tuned degradation kinetics. Extrusion equipment reconfiguration for hygroscopic resins requires substantial capital modification of legacy blown-film lines.
- Single-Use Containers:Pharmaceutical-grade soluble containers for oral-dose delivery command premium positioning where purity certification requirements create supply scarcity.
- Food Packaging:Edible coatings displace petroleum-based barrier films in single-serve condiment applications across Northern European quick-service restaurant pilots.
- Labels:Water-soluble adhesive systems face dissolution-rate calibration limits where cold-water engineering sacrifices mechanical strength during high-humidity storage.
Wrapping films carry the dominant share of material throughput; single-use containers are climbing the fastest on pharmaceutical certification premiums.
Distribution Channel:
Channel economics align with packaging format scale and customer technical support requirements.
- Direct Sales:Pharmaceutical and food-grade manufacturers procure through technical-specification relationships requiring dissolution-rate validation and regulatory documentation. ECHA, FDA, and METI compliance sequencing drives redundant validation expenditures.
- Online Retail:Pre-portioned soluble formats in household cleaning and personal care verticals align with refill-model economics and subscription channel growth.
- Supermarkets:Detergent pods and dishwasher tablets reach mass-market penetration through retail shelf placement.
- Specialty Stores:Premium edible films and cosmetic pods target conscious-consumer segments with sustainability-verified packaging.
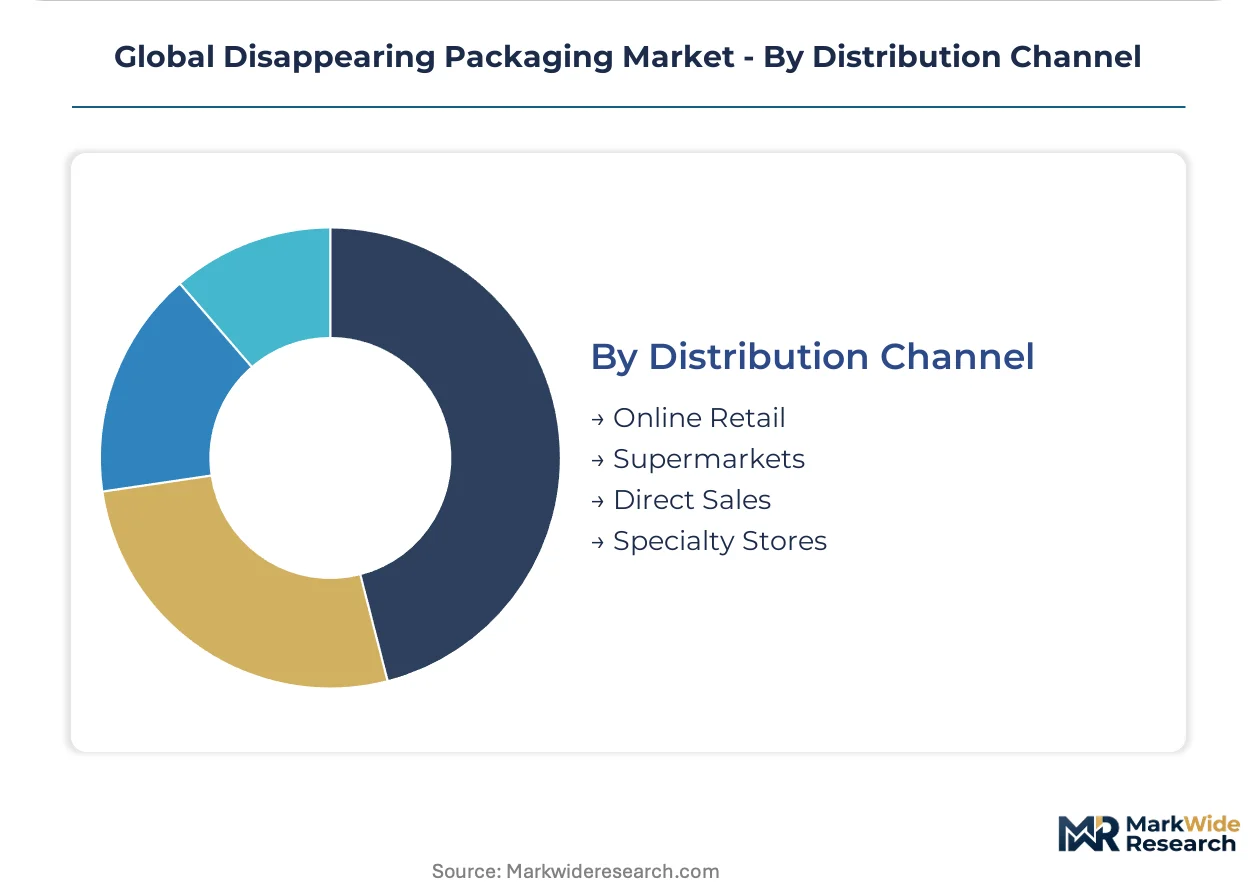
Direct sales manages the highest-value transactions; online retail is gaining share fastest on subscription-format alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate the lowest price elasticity as regulatory compliance costs dominate procurement decisions, while fast-moving consumer goods channels in the United States prioritize unit economics over dissolution-performance premiums.
United States
Coastal municipalities in California and New York are driving marine-safe detergent pod procurement as EPA persistent pollutant thresholds tighten waterway discharge standards. FDA food-contact notification pathways for edible films remain lengthier than water-soluble alternatives, delaying hospitality adoption. The Pacific Northwest hosts pilot-scale alginate processing facilities serving quick-service restaurant chains.
Germany
Brand-owner sustainability scorecards from BASF and Henkel procurement teams embed dissolution-rate documentation into private-label specifications for condiment pods. EU Green Deal packaging waste directives compress compliance timelines ahead of 2030 plastic elimination targets. The Rhine-Ruhr industrial corridor concentrates polyvinyl alcohol resin compounding capacity for pharmaceutical-grade applications.
Japan
METI circular economy guidelines create certification pathways that favor polyvinyl alcohol films in institutional food service and hospitality channels. Dissolution-rate testing protocols from the agency are reshaping export specifications across Asian markets. The Kanto region around Tokyo anchors formulation R&D clusters serving domestic pharmaceutical and cosmetic manufacturers.
United Kingdom
Quick-service restaurant chains in London and Manchester are piloting seaweed-derived edible sachets for sauce portions under pressure from municipal plastic reduction mandates. EFSA safety assessments for direct-contact alginate applications proceed in parallel with REACH compliance for base polymer chemistries. The Midlands manufacturing belt hosts thermoplastic starch blending operations for e-commerce protective applications.
China
GB standards on dissolution-rate testing are converging with Japan METI protocols, reshaping certification requirements for export-oriented formulators. Domestic demand concentrates in pharmaceutical-grade soluble containers where USP and EP monograph compliance creates supply scarcity. The Yangtze River Delta clusters polyvinyl alcohol resin production serving both domestic and international water-soluble film manufacturers.
Global Disappearing Packaging Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the disappearing packaging value chain. The market structure fragments across specialty chemical conglomerates with polymer science depth, venture-backed material innovators, and regional film extrusion specialists. Two strategic archetypes dominate: integrated resin-to-film manufacturers controlling dissolution kinetics, and application-specific formulators partnering with brand owners on custom certification. Competitive moves concentrate on strategic partnerships for regulatory co-certification and capacity expansion in pharmaceutical-grade production lines.
Within the integrated chemical conglomerate tier, Mitsubishi Chemical Holdings and Kuraray Co. Ltd. exemplify players with captive polymer science capabilities spanning resin synthesis through film extrusion. Notpla Ltd. occupies a distinct position among venture-backed specialists focused on seaweed-derived edible formats that bypass conventional waste infrastructure entirely. Aicello Corporation represents the mid-scale Japanese specialist archetype with regional strength in dissolution-controlled applications. These three anchors illustrate how competitive positioning diverges between scale-driven resin integration and niche-format innovation.
| Leading Market Players |
|---|
| Aicello Corporation |
| Notpla Ltd |
| Mondi Group |
| Cortec Corporation |
| Mitsubishi Chemical Holdings |
| Kuraray Co. Ltd. |
| Lactips |
| Lithey Inc. |
| Aquapak Polymer Ltd |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for polyvinyl alcohol resin lock in both supply access and price visibility for water-soluble film manufacturers serving pharmaceutical and food-grade channels. These arrangements insulate qualified formulators from East Asian feedstock volatility while embedding REACH and FDA certification costs into multi-year pricing schedules.
Pricing Analysis
EU Green Deal packaging directives dictate the pricing tier structure across the disappearing packaging value chain. Three-tier pricing structure across pharmaceutical-grade, food-contact, and industrial-grade certification levels segments buyers by compliance burden. Price differentiation rests on dissolution-rate documentation and ECHA registration status. Cost compression in industrial-grade films is intensifying because commodity pulp alternatives erode plant-based fiber margins. Fast-moving consumer goods channels in the United States demonstrate highest price sensitivity, while German pharmaceutical procurement shows lowest elasticity.
Supply Chain Analysis
East Asian resin manufacturing clusters anchor supply concentration for water-soluble film production. China, Japan, and South Korea host polyvinyl alcohol synthesis capacity that feeds global extrusion operations. Raw material dependencies center on acetylene and ethylene feedstocks for resin polymerization, plus alginate harvests from North Atlantic seaweed operations. Single-source vulnerability runs through Yangtze River Delta resin plants exposed to shipping cost volatility. Distribution runs through direct technical-sales relationships for pharmaceutical-grade volumes, with spot-market procurement serving industrial protective applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disappearing packaging functions as a service-attach opportunity where dissolution-rate certification and regulatory documentation generate recurring revenue streams expanding faster than base resin sales. After-sales compliance support now commands premium positioning in procurement negotiations.
For Market Incumbents: Shield formulation expertise through captive polymer science capabilities spanning resin synthesis to film extrusion. Acquire alginate processing facilities in Northern Europe to secure seaweed-derived edible film feedstocks against Notpla Ltd. expansion. Invest in multi-jurisdiction certification infrastructure to compress ECHA, FDA, and METI validation cycles. For New Entrants and Emerging Players: Differentiate on pharmaceutical-grade purity certification where USP and EP monograph compliance creates supply scarcity. Target oral-dose strip packaging and single-serve condiment sachets as white-space segments with lowest incumbent saturation. Pursue direct-to-consumer subscription channels for household cleaning pods where refill-model economics favor soluble formats. For Investors and Strategic Acquirers: Specialty resin-to-film integrators with dissolution-kinetic control represent the highest-conviction acquisition archetype for sustained margin capture. Long-term viability hinges on regulatory co-certification capabilities rather than commodity scale. Watch for ECHA enforcement actions on residual acetyl group content as inflection signals for upstream distillation upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive polyvinyl alcohol production secures dissolution-rate control against East Asian supply volatility. |
| Pharmaceutical-Grade Certification Investment | USP and EP monograph compliance opens margin pools in oral-dose strip packaging. |
| Seaweed Processing Capacity Expansion | Alginate gel production in Northern Europe bypasses conventional petrochemical feedstock dependencies. |
| Multi-Jurisdiction Regulatory Co-Certification | Parallel ECHA, FDA, and METI validation reduces redundant expenditure for global brand owners. |
| Direct-to-Consumer Subscription Launch | Pre-portioned soluble formats align with refill-model economics in household cleaning verticals. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of ECHA registration databases, FDA food-contact notifications, and Japan METI dissolution-rate protocols. Primary interviews engaged polymer scientists at resin manufacturers, procurement leads at detergent and pharmaceutical brand owners, extrusion equipment engineers, and regulatory affairs specialists at film formulators. Secondary validation drew from customs trade data, SEC filings of specialty chemical conglomerates, and EU Green Deal implementation tracking. Bottom-up demand modeling triangulated against top-down market sizing across material chemistry segments.
Segmentation dimensions modeled include material type, end-use industry, dissolution temperature range, and regional regulatory cluster. Volume and value outputs across the projection horizon reflect adoption curve analysis by application maturity and certification pathway complexity. CAGRs were derived from regression against historical qualification timelines and forward-looking procurement commitments. Forecast inputs incorporated EU Green Deal compliance deadline proximity and METI protocol convergence with Chinese GB standards.
Material uncertainties — regulatory acceleration or delay, feedstock price shocks, and novel edible film barrier breakthroughs — sit outside the modeled envelope. Forecasts reflect documented assumptions on dissolution-rate testing protocol harmonization. Practitioners should keep alternative scenarios live as ECHA enforcement intensity and seaweed harvest yield variability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
Areca Plates Market
Sustainable Packaging
Asia-Pacific Eco-Friendly Packaging Market
Sustainable Packaging
Eco-Friendly Straw Market
Sustainable Packaging
Sustainable Plastic Packaging Market
Sustainable Packaging
Compostable Tableware Market
Sustainable Packaging
Europe Green Packaging Market
Sustainable Packaging
Global Paper Straw Market
Sustainable Packaging
Middle East and Africa Eco-Friendly Packaging Market
Sustainable Packaging
Japan Green Packaging Market
Sustainable Packaging
United States Green Packaging Market
Sustainable Packaging
Europe Sustainable Packaging Market
Sustainable Packaging
North America Eco-Friendly Packaging Market
Sustainable Packaging
Sustainable Packaging Market
Sustainable Packaging
GCC Green Packaging Market
Sustainable Packaging
Bagasse Tableware Products Market
Sustainable Packaging
Sustainable Foodservice Packaging Market